
 Outbound Medical Tourism Services Market | 2026-2036
Outbound Medical Tourism Services Market Size, Share, and Industry Trends Forecast 2026-2036
Outbound Medical Tourism Services Market Outlook
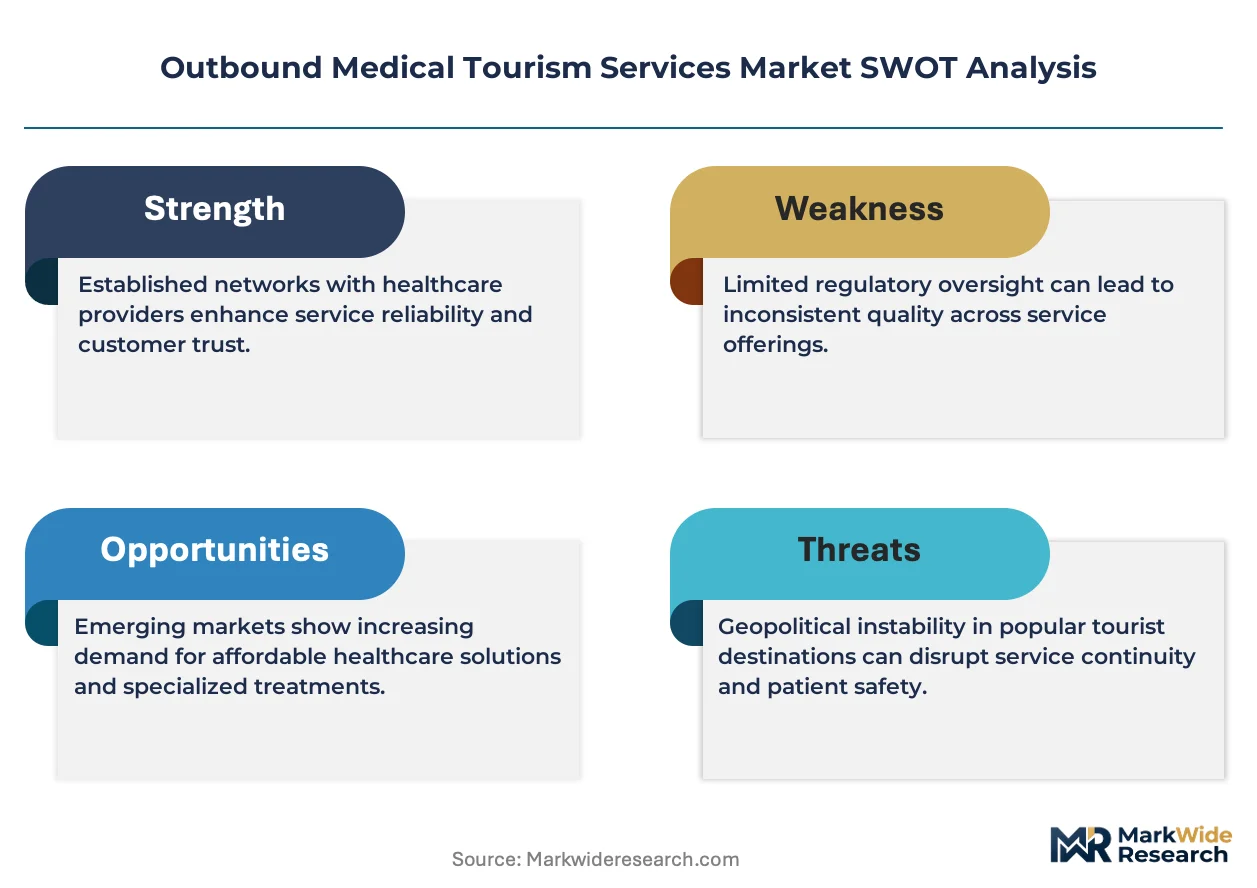
Medical aggregator platforms is repositioning how patients discover, compare, and book cross-border care packages. Apollo Hospitals leverages its integrated hospital network across South Asia to sustain destination loyalty for complex cardiac interventions. Bumrungrad International Hospital anchors premium service tiers through Joint Commission International accreditation and dedicated international patient coordination centers. Fortis Healthcare Ltd competes on cost-transparent bundled pricing for oncology and transplant services directed at Middle Eastern and African referral channels.
Outbound medical tourism services encompass the organized provision of diagnostic, surgical, and therapeutic healthcare delivered outside a patient's home country, typically coordinated through specialized intermediaries that manage travel logistics, provider matching, and post-operative follow-up protocols. The primary commercial purpose centers on accessing cost differentials, reduced wait times, or unavailable specialist procedures through accredited foreign facilities. Cosmetic surgery and dental procedures command the largest patient volume segments, while cardiovascular surgery and fertility treatments capture disproportionate margin pools due to higher per-case values and extended recovery stays. Thailand and India dominate destination flows, though Turkey gains traction for hair transplantation and ophthalmology where EU-aligned clinical standards reduce perceived risk.
Joint Commission International standards, Turkey's Ministry of Health foreign patient regulations, and India's National Accreditation Board for Hospitals & Healthcare Providers framework collectively determine which facilities qualify for insurance reimbursement and government employee schemes in origin markets. These accreditation requirements shape demand by filtering provider eligibility and establishing baseline quality signals that reduce patient search friction. Stakeholders must monitor evolving bilateral health agreements and telemedicine licensing rules that could either streamline pre-operative consultations or create new compliance barriers for cross-border care coordinators.
Market Dynamics
Medical aggregator platforms are compressing patient discovery timelines and eroding traditional referral channel margins by enabling direct price comparison across accredited facilities in multiple jurisdictions simultaneously.
Growth Catalysts
- Joint Commission International accreditation:Turkish and Thai hospitals leverage this standard to qualify for reimbursement under US employer self-funded health plans, expanding addressable patient pools beyond cash-paying segments.
- India's cardiac bypass concentration:Apollo Hospitals and Fortis Healthcare anchor destination loyalty through bundled pricing for uninsured American patients facing prohibitive domestic surgical costs.
- Telemedicine licensing harmonization:Pre-operative consultation protocols increasingly satisfy origin-country malpractice insurers, reducing legal friction for cross-border surgical bookings.
Market Restraints
- Malpractice liability asymmetry:US-origin patients face limited legal recourse for surgical complications in Mexican facilities due to jurisdictional enforcement gaps and capped damage awards.
- Currency volatility exposure:Turkish lira depreciation compresses real margins for Istanbul hair transplantation clinics despite volume growth from European patients.
- Supply concentration in Bangkok:Bumrungrad International Hospital and competing Thai flagship facilities control premium-tier accreditation slots, creating bottleneck risk for new market entrants.
Strategic Opportunities
- Vietnam's underdeveloped accreditation infrastructure:Early movers establishing Joint Commission International-certified facilities in Ho Chi Minh City capture spillover demand from Thailand's saturated premium tier.
- EU AI Act diagnostic compliance:Automated pre-screening algorithms for orthopedic candidacy assessment create regulatory-mandated upgrade cycles for Mexican hospital IT systems.
- Subscription-based recovery housing:Extended-stay platforms integrating post-operative nursing with tourism infrastructure displace traditional hotel bookings in Malaysian medical travel corridors.
Industry Challenges
- Cross-border nursing credential recognition:Post-operative care coordinators require dual-licensing in origin and destination jurisdictions, constraining staffing scalability for high-volume Mexican facilities.
- Electronic health record interoperability:Legacy HL7 standards in Indian hospitals create data fragmentation that complicates continuity-of-care handoffs to US primary care networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outbound Medical Tourism Services Market |
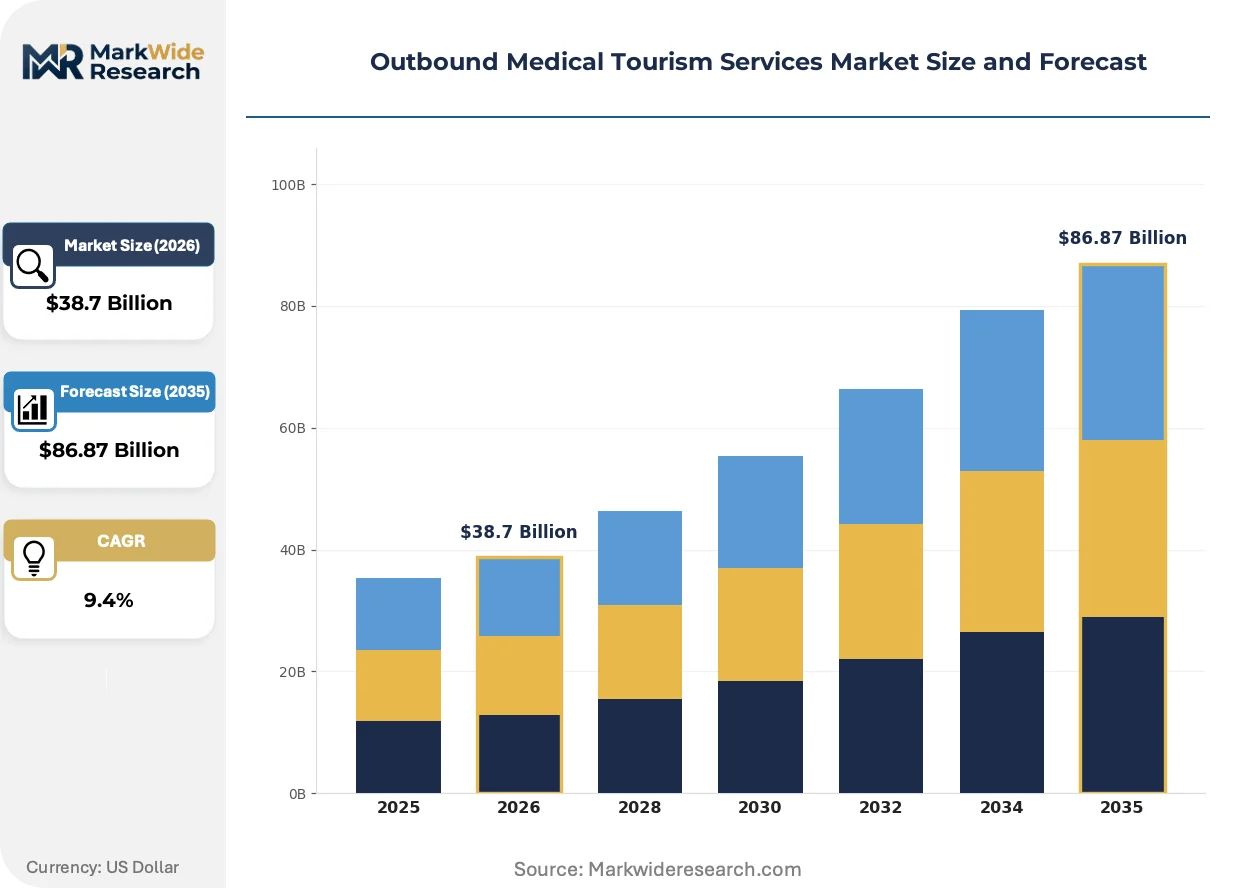
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cosmetic Surgery, Dental Procedures, Fertility Treatments, Cardiovascular Surgery Destination: Thailand, India, Mexico, Turkey Patient Demographics: Age Group, Gender, Income Level, Health Status Travel Arrangement: Package Tours, Individual Arrangements, Group Tours, Medical Aggregators |
| Companies Covered | Apollo Hospitals, Bumrungrad International Hospital, Christus Muguerza Hospital, KPJ Healthcare Berhad, Bangkok Dusit Medical Services, Fortis Healthcare Ltd, Prince Court Medical Center, Asklepios Kliniken GmbH, WorldMed Assist, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outbound Medical Tourism Services Market Strategic Shifts
Digital health infrastructure is reconfiguring how patients verify quality signals, compare bundled pricing, and coordinate multi-leg travel itineraries around surgical schedules. Three developments are compressing transaction friction and expanding addressable segments.
Remote patient monitoring wearables are integrating pre-operative risk stratification with real-time post-surgical recovery tracking. Thai and Turkish hospitals deploy these devices to reduce readmission liability and satisfy US employer plan requirements for remote follow-up protocols. The technology is integrating clinical data streams directly into malpractice insurance underwriting models, compressing premium spreads between accredited and non-accredited facilities.
REACH chemical safety documentation requirements now extend to implantable device coatings used in EU-destined orthopedic procedures. Turkish manufacturers serving German and Dutch patients must demonstrate compliance with substance-of-very-high-concern screening protocols. Cardiac stent and joint replacement suppliers are responding by shifting procurement toward EU-notified-body-certified component vendors, raising input costs for Ankara and Istanbul facilities.
Employer direct contracting with accredited foreign hospitals is displacing traditional insurer-mediated referrals for elective procedures. Self-funded US corporations in manufacturing and logistics sectors negotiate fixed-price bundles for joint replacements and spinal fusions. Texas and Arizona-based employers with high-deductible plan structures represent the most visible adoption geography, driven by proximity to Mexican border facilities and state-level regulatory accommodation of cross-border care in self-insured arrangements.
Outbound Medical Tourism Services Market Segmentation
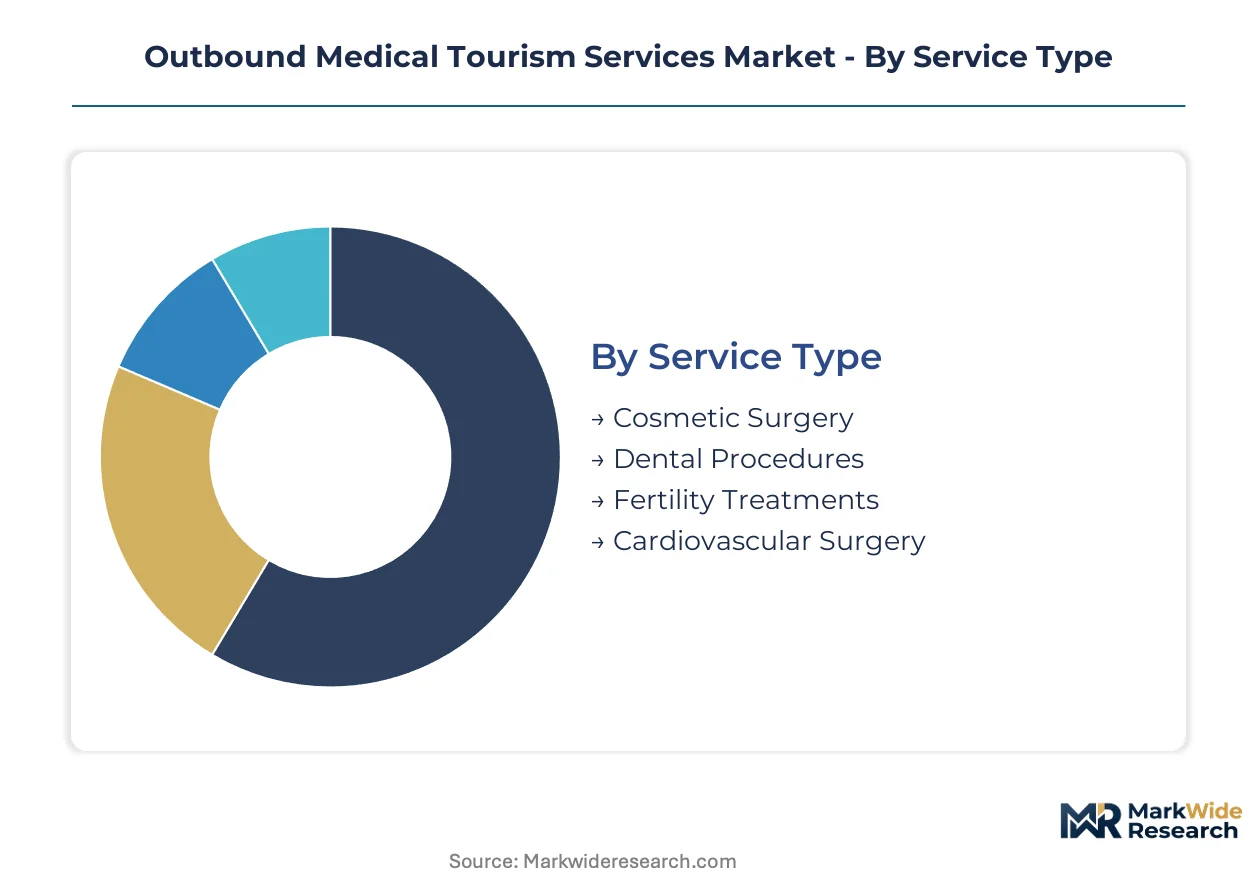
Outbound medical tourism services fragment across four distinct dimensions that determine pricing power, patient acquisition costs, and operational complexity. Service type and destination geography capture the bulk of revenue concentration, while patient demographics and travel arrangement models shape margin structures and platform economics.
Service Type:
Volume-driven segments dominate patient flows, yet premium surgical categories extract disproportionate value per case through extended recovery stays and complication management protocols.
- Cosmetic Surgery:Procedures span minimally invasive injectables to complex reconstructive interventions. Thai and Mexican facilities anchor demand from North American patients seeking price differentials on rhinoplasty, liposuction, and breast augmentation. Joint Commission International accreditation filters provider eligibility for US employer reimbursement schemes.
- Cardiovascular Surgery:Complex open-heart procedures including coronary artery bypass grafting and valve replacement command the highest per-case values. Apollo Hospitals in India and Turkish cardiac centers concentrate demand from uninsured Americans facing domestic surgical costs exceeding available savings.
- Dental Procedures:Implants, crowns, and full-mouth reconstructions drive cross-border volume from US retirees. Mexican border clinics in Tijuana and Los Algodones capture geographic proximity advantages for same-day and multi-day treatment protocols.
- Fertility Treatments:IVF cycles and egg freezing services attract patients from jurisdictions with restrictive regulations or long public wait lists. Spanish-speaking patients concentrate in Mexican facilities, while Middle Eastern demand flows toward Turkey and Cyprus.
Mature deployment sits with cosmetic surgery. Newer deployment is concentrated in cardiovascular surgery.
Destination:
Accreditation density and bilateral health agreements determine which destinations qualify for insurance reimbursement versus cash-only patient segments.
- Thailand:Bumrungrad International Hospital and competing Bangkok flagship facilities anchor premium-tier medical tourism through Joint Commission International certification. German and Dutch patients drive European volume for orthopedic and ophthalmology procedures.
- Turkey:Istanbul and Ankara facilities concentrate hair transplantation and ophthalmology demand where EU-aligned clinical standards reduce perceived risk. Ministry of Health foreign patient regulations reshape entry requirements and facility licensing.
- India:Apollo Hospitals and Fortis Healthcare sustain destination loyalty for cardiac bypass and joint replacement through bundled pricing transparency. Uninsured American patients and Middle Eastern referral channels represent core demand segments.
- Mexico:Border facilities in Tijuana, Los Algodones, and Monterrey capture elective orthopedic and dental volume from Texas and Arizona-based employers with self-funded health plans. Proximity enables multi-visit treatment protocols without extended accommodation costs.
Established accreditation infrastructure dominates in Thailand. Steepest expansion trajectory is occurring in Turkey.
Patient Demographics:
Price sensitivity and insurance status fragment demand across distinct behavioral clusters with divergent service expectations and risk tolerances.
- Age Group:Retirees aged 55-75 drive orthopedic and cardiac procedure volume. Younger cohorts concentrate in cosmetic and fertility segments with higher discretionary spending flexibility.
- Income Level:High-deductible plan holders and uninsured middle-income households represent core price-sensitive demand. Wealth segments seek premium concierge coordination and extended recovery amenities.
- Gender:Female patients dominate cosmetic surgery and fertility treatment flows. Male patients concentrate in hair transplantation, dental reconstruction, and cardiac interventions.
- Health Status:Elective procedure candidates with controlled comorbidities qualify for streamlined scheduling. Complex cases requiring pre-operative optimization face extended coordination timelines and higher cancellation risk.
Volume concentration aligns with middle-income uninsured segments. Premium service tiers target high-net-worth individuals seeking privacy and concierge logistics.
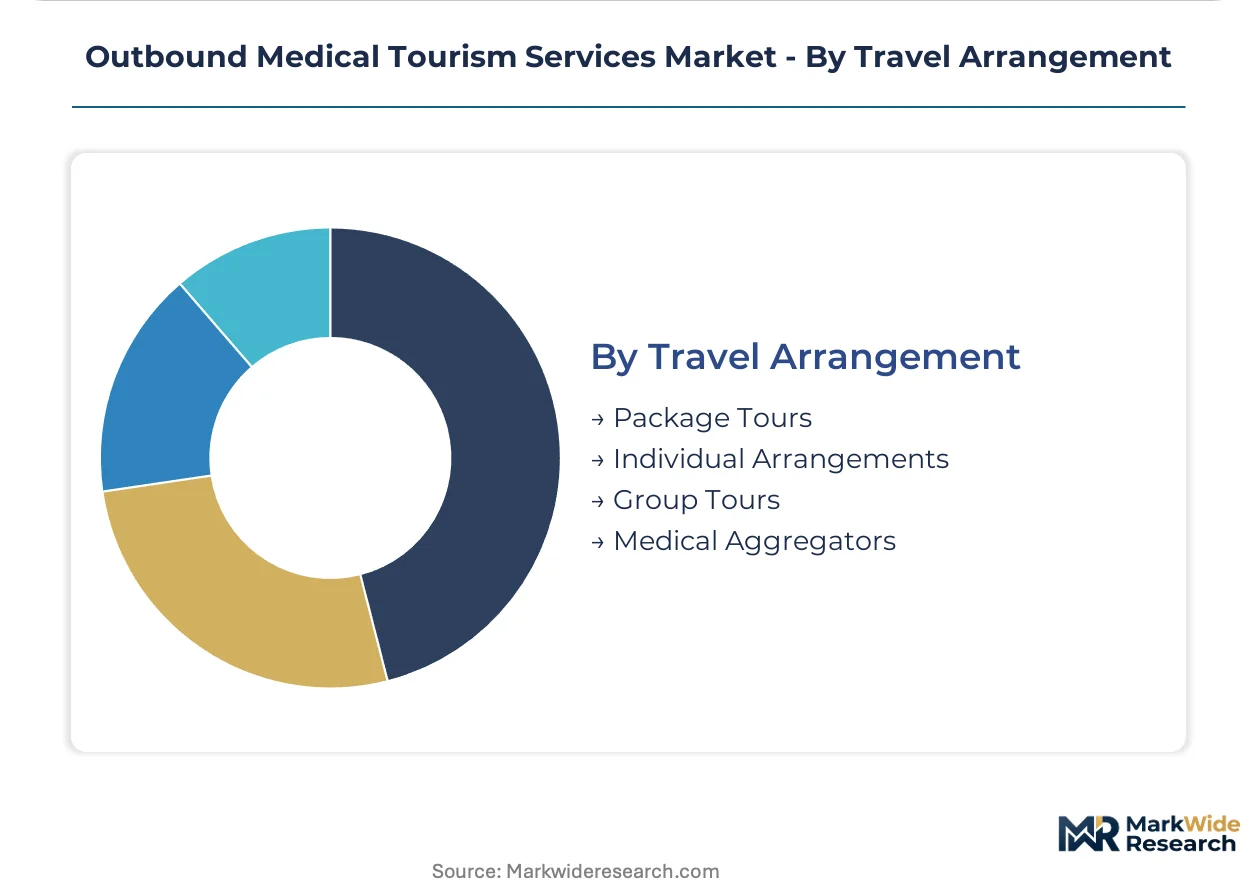
Travel Arrangement:
Intermediation models determine patient discovery costs, price transparency, and post-operative liability allocation between platforms and provider facilities.
- Medical Aggregators:Digital platforms enable direct price comparison across accredited facilities in multiple jurisdictions simultaneously. These intermediaries compress patient discovery timelines and erode traditional referral channel margins through bundled package transparency.
- Package Tours:Integrated offerings combine surgical procedures with accommodation, ground transport, and tourism activities. Thai and Malaysian facilities leverage these arrangements to extend length-of-stay and capture ancillary spending.
- Individual Arrangements:Self-directed patients negotiate directly with foreign hospitals, typically through existing diaspora networks or prior medical referrals. This segment carries higher coordination burden and malpractice liability exposure.
- Group Tours:Employer-sponsored or association-organized cohort travel reduces per-patient logistics costs for standardized procedures. US manufacturing sector self-funded plans represent visible adoption geography for joint replacement group arrangements.
Platform-mediated booking is gaining share fastest. Traditional package tour operators face margin compression from aggregator price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient outflows concentrate in origin markets with high domestic healthcare costs and limited public coverage, while destination countries compete through accreditation density and proximity advantages. The United States generates the largest outbound volume of uninsured and high-deductible plan holders seeking cardiac and orthopedic procedures abroad.
United States
Texas and Arizona-based employers with self-funded health plans drive cross-border surgical volume to Mexican facilities. HIPAA portability rules complicate electronic health record transfers for post-operative continuity. Tijuana and Los Algodones clusters specialize in same-day dental implants and multi-visit orthopedic protocols.
Mexico
Border state facilities capture elective procedure demand from American retirees aged 55-75 seeking cost differentials on joint replacements. The country's national health ministry regulates foreign patient licensing through facility certification programs. Monterrey's medical corridor anchors premium-tier orthopedic and bariatric surgery capacity.
Thailand
Bangkok flagship hospitals sustain destination loyalty through Joint Commission International accreditation and dedicated international patient coordination centers. Thai medical tourism promotion policies incentivize private hospital infrastructure investment. Bumrungrad International Hospital controls premium-tier capacity in the capital's central business district.
Turkey
Istanbul hair transplantation and ophthalmology clinics attract European patients through EU-aligned clinical standards and price competitiveness. Ministry of Health foreign patient regulations reshape entry requirements and facility licensing thresholds. Ankara facilities concentrate government-subsidized cardiac intervention capacity.
India
Apollo Hospitals and Fortis Healthcare anchor destination loyalty for cardiac bypass and joint replacement through bundled pricing transparency. The National Accreditation Board for Hospitals & Healthcare Providers framework determines insurance reimbursement eligibility. Mumbai and Delhi clusters concentrate high-volume oncology and transplant service lines.
Outbound Medical Tourism Services Market Competitive Environment
Top-tier vendors anchor destination hospital networks with international accreditation, while mid-tier regional chains compete on proximity and price transparency. The market structure concentrates around hospital groups with dedicated international patient divisions and established referral channel relationships. Three archetypes dominate: integrated multi-hospital networks, single-site flagship facilities, and medical aggregator platforms coordinating cross-border logistics. Dominant competitive moves include accreditation acquisition for insurance reimbursement eligibility and direct employer contracting bypassing traditional insurer intermediation.
Within the integrated network tier, Apollo Hospitals and Fortis Healthcare Ltd represent the South Asian hospital group model with multi-city presence and bundled service packaging. Bumrungrad International Hospital occupies a position exemplifying the single-site flagship archetype through concentrated premium-tier capacity in Bangkok. These three entities collectively illustrate how accreditation density and international patient infrastructure determine competitive positioning in destination markets.
| Leading Market Players |
|---|
| Apollo Hospitals |
| Bumrungrad International Hospital |
| Christus Muguerza Hospital |
| KPJ Healthcare Berhad |
| Bangkok Dusit Medical Services |
| Fortis Healthcare Ltd |
| Prince Court Medical Center |
| Asklepios Kliniken GmbH |
| WorldMed Assist |
| Others |
Value Chain & Pricing Dynamics
US employer self-funded health plans demanding bundled price transparency for cross-border joint replacements force Mexican and Indian hospitals to restructure service packaging and compress intermediary margins, tightening cost discipline across destination facilities.
Pricing Analysis
Margin tightening in standard-tier cardiac and orthopedic packages reflects employer direct contracting bypassing traditional insurer intermediation. Pricing stratifies across Joint Commission International-accredited premium facilities, nationally certified standard hospitals, and non-accredited economy clinics serving cash-paying retirees. Cost compression accelerates in Mexican border markets as Texas and Arizona employers consolidate surgical volumes for negotiating leverage. Uninsured middle-income American households exhibit highest price sensitivity, while high-net-worth individuals purchasing concierge coordination show lowest elasticity.
Supply Chain Analysis
Turkey's Ministry of Health domestic-content mandates for foreign patient facilities reshape sourcing toward EU-notified-body-certified implant vendors. Medical device procurement draws from Germany, Switzerland, and domestic Turkish manufacturers for cardiac stents and orthopedic implants. Supply chain risk centers on REACH chemical safety documentation requirements for implantable device coatings serving European patients. Distribution runs through hospital-integrated international patient coordination centers rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital health infrastructure is displacing legacy referral channel economics, with remote patient monitoring wearables and telemedicine pre-consultation protocols restructuring how patients verify quality signals and coordinate surgical bookings.
For Market Incumbents: Acquire telemedicine licensing capabilities and remote patient monitoring device fleets to defend against aggregator platform disintermediation. Apollo Hospitals and Bumrungrad International Hospital should deepen backward integration into post-operative recovery housing in Bangkok and Chennai. Joint Commission International accreditation renewal cycles represent critical defensive investment levers for insurance reimbursement eligibility.
For New Entrants and Emerging Players: Capture Vietnam's underdeveloped accreditation infrastructure in Ho Chi Minh City before Joint Commission International certification slots saturate. Target employer-sponsored group tour arrangements for standardized orthopedic procedures as the most penetrable segment. Launch direct-to-employer sales teams in Texas and Arizona manufacturing corridors to bypass aggregator commission structures.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier hospital groups achieving first-mover Joint Commission International certification in secondary destinations given employer direct contracting adoption curves. Long-term viability favors platforms integrating digital discovery with captive recovery infrastructure. Watch bilateral health agreement negotiations between US states and Mexican federal authorities as inflection signals for reimbursement expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Licensing Harmonization | Pre-operative consultation protocols satisfy US malpractice insurers, reducing legal friction for cross-border surgical bookings. |
| Joint Commission International Certification | Turkish and Thai hospitals qualify for reimbursement under US employer self-funded health plans, expanding addressable patient pools. |
| Remote Patient Monitoring Integration | Wearable devices reduce readmission liability and satisfy US employer plan requirements for post-surgical follow-up protocols. |
| Employer Direct Contracting | Self-funded corporations in Texas and Arizona negotiate fixed-price bundles, displacing traditional insurer-mediated referrals. |
| Post-Operative Recovery Housing | Extended-stay platforms integrating nursing with tourism infrastructure displace traditional hotel bookings in Malaysian corridors. |
Study Parameters
Multi-period observation of accreditation acquisition timelines, employer direct contracting announcements, and telemedicine regulatory filings anchored the trend analysis, supplemented by interviews with hospital international patient directors, medical aggregator platform executives, employer benefits managers, and cross-border care coordinators. Secondary validation drew from Joint Commission International certification databases, US Department of Labor self-funded plan disclosures, Turkish Ministry of Health foreign patient licensing records, and Indian National Accreditation Board for Hospitals & Healthcare Providers audit reports. Bottom-up patient flow modeling triangulated against top-down destination revenue estimates.
Segment-weighting applied service type, destination geography, patient demographic, and travel arrangement dimensions across the projection horizon. Cardiovascular surgery and cosmetic procedure volumes were modeled separately given divergent margin structures and recovery stay requirements. CAGRs derived from facility capacity expansion pipelines, bilateral health agreement negotiation calendars, and employer adoption curve assumptions for direct contracting arrangements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to telemedicine licensing rule changes, currency volatility in Turkish and Indian markets, and US state-level regulatory accommodation of cross-border care in self-insured arrangements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
Malaysia Medical Tourism Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
North America Health Tourism Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
South Korea Medical Tourism Market
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market