
 Europe Medical Tourism Market | 2026-2036
Europe Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Tourism Market Insights
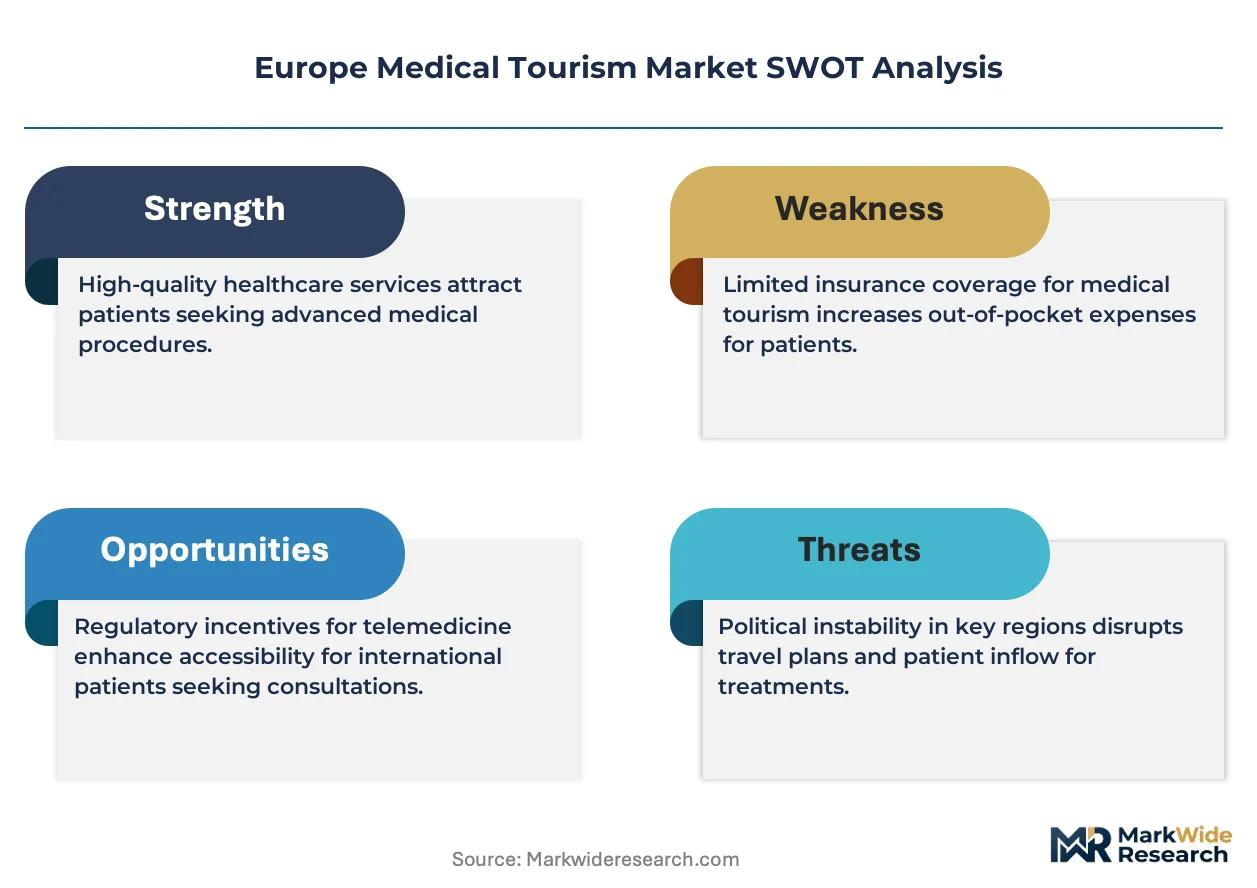
The split between premium concierge medical travel and price-driven commodity treatment packages is realigning competitive strategy across European hospital networks. Helios Hospitals leverages its integrated clinic network across Germany, Poland, and Bulgaria to capture volume in both tiers. The Royal Marsden sustains premium positioning through oncology specialization that attracts Middle Eastern and Asian private payers. Cromwell Hospital anchors London's high-end segment with direct billing relationships to international insurers.
Europe medical tourism encompasses the organized movement of patients across national borders to access planned healthcare, spanning diagnostic workups, surgical interventions, post-acute rehabilitation, and wellness services delivered through accredited clinical facilities. Patient flows depend on comparative cost structures, waiting list differentials, and specialized clinical capabilities unavailable in home jurisdictions. Surgical procedures and cosmetic treatments command the largest revenue pools, while telemedicine infrastructure is displacing traditional referral channels by enabling pre-operative consultations and remote follow-up. Rehabilitation services represent the fastest-expanding segment as ageing populations in Northern Europe seek extended post-surgical recovery in Mediterranean climate settings.
EMA coordination on cross-border healthcare directives, EU Green Deal sustainability requirements for clinical facilities, and national accreditation standards enforced by France's ANSM and Germany's KBA-aligned hospital certification bodies collectively shape market access conditions. GDPR compliance for patient data transfer and the EU AI Act governance of diagnostic algorithms now determine which providers can accept digitally-originated international referrals. Stakeholders must monitor how forthcoming revisions to the Cross-Border Healthcare Directive affect reimbursement portability and whether national quality registries will harmonize sufficiently to support transparent provider selection.
Market Dynamics
Telemedicine infrastructure is compressing patient acquisition timelines and enabling pre-operative consultations across borders, fundamentally altering how European clinics source international patients and manage care continuity.
Growth Catalysts
- EU Cross-Border Healthcare Directive:Reimbursement portability provisions under the directive accelerate patient mobility from high-waitlist jurisdictions toward Central European surgical centers.
- Orthopaedic surgical robotics:Adoption of computer-assisted navigation systems in Hungarian and Polish clinics narrows quality perception gaps with Western European alternatives.
- Mediterranean climate rehabilitation:Ageing Northern European populations drive post-acute recovery demand toward Spanish and Portuguese coastal facilities.
Market Restraints
- GDPR compliance costs:Patient data transfer protocols impose infrastructure investments that disadvantage smaller clinic operators in Bulgaria and Romania.
- EU MDR certification timelines:Extended conformity assessment periods for implantable devices delay service line expansions at mid-tier hospitals.
- Domestic healthcare substitution:Telehealth follow-up platforms reduce the necessity of physical presence for routine post-operative monitoring.
Strategic Opportunities
- EU AI Act diagnostic pathways:Algorithm-governed pre-screening tools create compliant channels for automated patient triage and referral matching.
- Bariatric surgery corridors:Underpenetrated Czech and Slovak markets offer volume expansion potential given proximity to German-speaking patient populations.
- Integrated wellness-rehabilitation hybrids:Convergence of clinical recovery with thermal spa infrastructure differentiates Hungarian offerings.
Industry Challenges
- Multilingual care coordination:Patient navigator shortages constrain scale at clinics targeting Arabic and Asian language markets.
- Legacy EHR interoperability:Fragmented electronic health record standards between origin and destination jurisdictions complicate care handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Tourism Market |
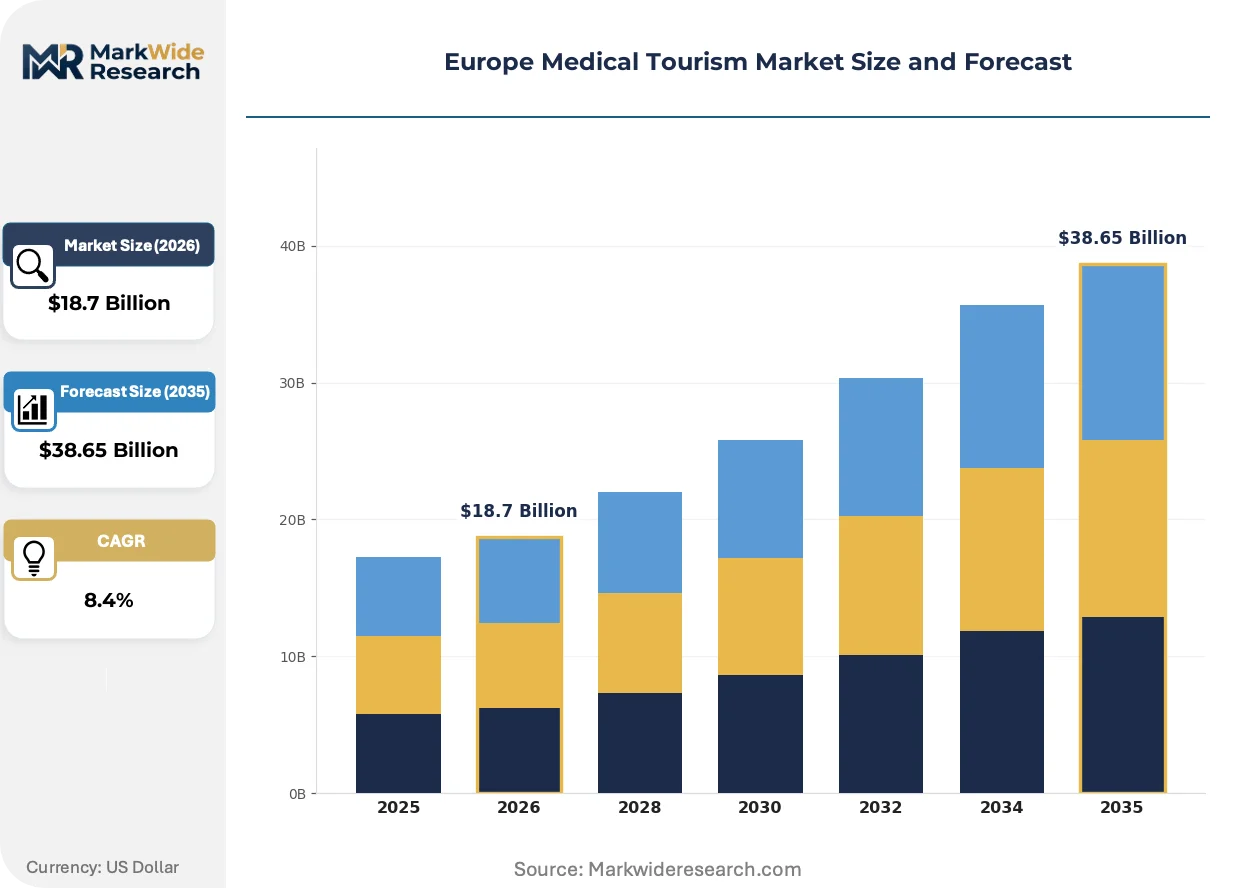
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Surgical Procedures, Cosmetic Treatments, Rehabilitation, Dental Care End User: Individuals, Corporations, Health Insurers, Government Agencies Technology: Telemedicine, Electronic Health Records, Mobile Health Apps, Wearable Devices Pricing Model: Package Pricing, Insurance Funding, Out-of-Pocket, Subscription Services |
| Companies Covered | Helios Hospitals, The Royal Marsden, Cromwell Hospital, Institut de la Hernie Paris, Charité University Hospital, Fresenius Medical Care, Bupa Global, UZ Leuven, AMTA Health, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Tourism Market Trends and Innovations
Digital patient journey orchestration is compressing decision cycles from initial inquiry to surgical booking, while regulatory harmonization pressures force consolidation among subscale accreditation bodies.
Remote patient monitoring platforms are electrifying post-operative care models by enabling continuous biometric surveillance across borders. German cardiac rehabilitation centers deploy wearable-integrated dashboards to track recovery metrics for returning Scandinavian patients. This capability compresses length-of-stay requirements and expands addressable catchment zones beyond traditional geographic limits.
EMA coordination on the EU Medical Device Regulation tightens quality benchmarks for implantable devices used in cross-border procedures. French ANSM and German KBA-aligned certification bodies now require enhanced clinical evidence packages for high-risk device categories. Central European surgical centers respond by consolidating procurement relationships with notified bodies holding broader EU scope.
Direct-to-patient digital marketing is displacing traditional medical travel intermediaries as the dominant patient acquisition channel. Baltic and Polish clinics now allocate majority marketing spend toward search-optimized platforms and physician-facing teleconsultation interfaces. This shift is most visible in the cosmetic surgery segment, where Turkish competitors have demonstrated the scalability of algorithmically-targeted patient funnels.
Europe Medical Tourism Market Segmentation
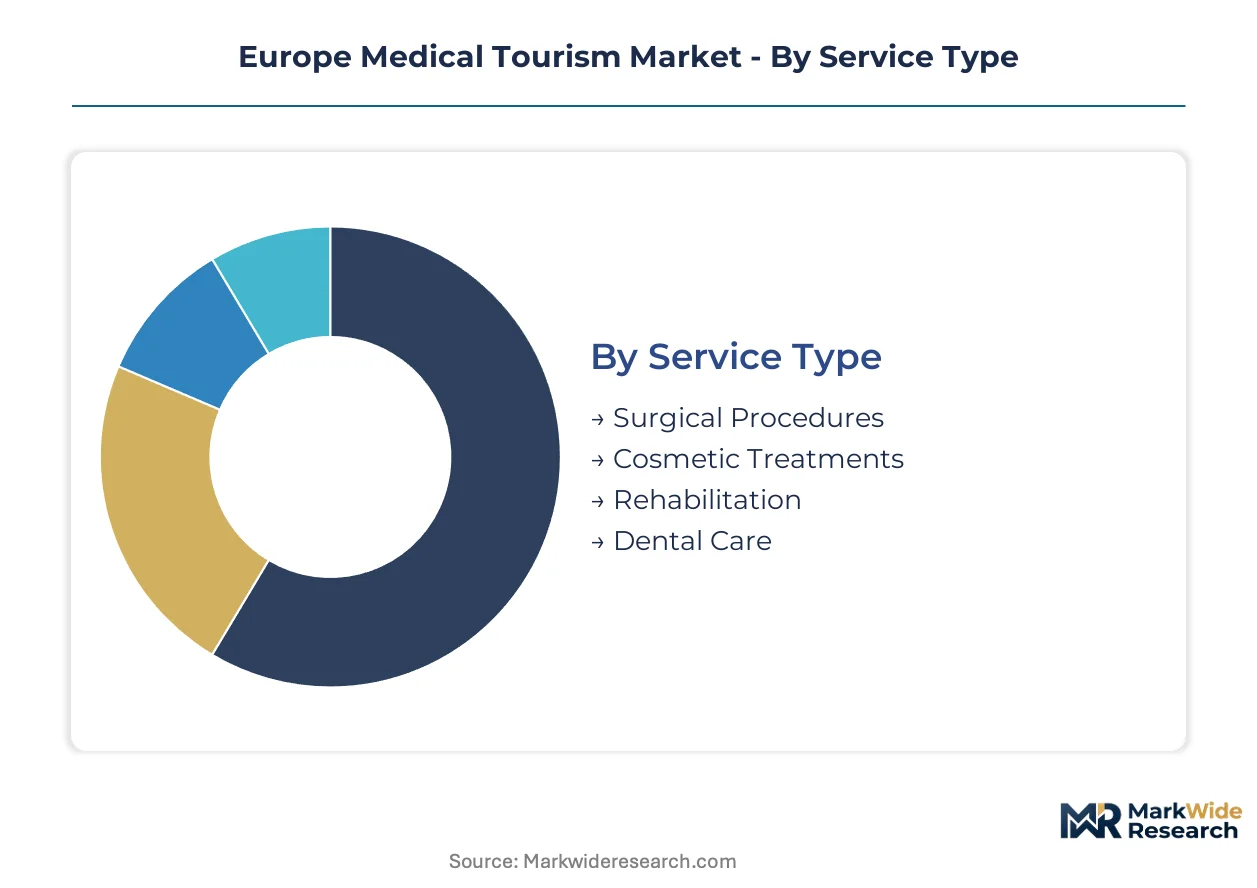
Segmentation reveals how certification burdens and reimbursement pathways split patient flows across European medical tourism corridors. Providers must align service configurations with specific regulatory requirements governing each segment's cross-border delivery.
Service Type:
EU MDR conformity assessment intensity varies sharply across service categories, with implantable device procedures requiring notified body oversight that smaller clinics struggle to maintain.
- Surgical Procedures:Cardiac, orthopaedic, and bariatric interventions utilizing implantable devices face the steepest EMA regulatory compliance costs. Demand concentrates in Hungarian and Polish surgical centers serving German and Austrian patients seeking shorter wait times for hip replacements and cardiac valve procedures.
- Rehabilitation:Post-acute recovery programs combine clinical protocols with thermal spa infrastructure, particularly in Hungarian lake-region facilities. Northern European retirees drive volume toward Spanish and Portuguese coastal clinics offering climate-advantaged physiotherapy programs.
- Cosmetic Treatments:Aesthetic surgery and dermatology procedures operate under lighter device regulations but require strict GDPR compliance for photographic documentation transfer.
- Dental Care:Implantology and prosthodontics in Bulgarian and Romanian clinics attract price-sensitive patients from Western Europe with same-day CAD/CAM restoration capabilities.
Leading the category by volume: Surgical Procedures. Expanding most quickly: Rehabilitation.
End User:
Cost tier stratification separates premium concierge segments from price-driven bulk purchasers, with reimbursement portability determining addressable patient pools.
- Individuals:Private payers span high-net-worth patients seeking oncology specialization at London's Royal Marsden to budget-conscious retirees pursuing dental implants in Sofia. Self-funded travelers respond to direct-to-patient digital marketing and telemedicine pre-screening.
- Health Insurers:International carriers with direct billing relationships to Cromwell Hospital and Helios network facilities steer covered lives toward accredited centers. Prior authorization requirements and bundled payment contracts shape referral patterns.
- Corporations:Self-insured employers and expatriate benefit managers negotiate volume contracts for executive health screening and elective procedures, favoring English-language capacity and single-point care coordination.
- Government Agencies:NHS partnership agreements and Scandinavian regional health authorities purchase block capacity for waitlist reduction, particularly in orthopaedic and cataract surgery.
Dominant by revenue contribution: Individuals. Fastest channel expansion: Health Insurers.
Technology:
Digital infrastructure maturity determines which providers can accept EU-wide referrals under GDPR and EU AI Act governance requirements.
- Telemedicine:Pre-operative consultation platforms and remote follow-up systems enable Baltic and Polish clinics to capture patients without physical presence requirements. GDPR-compliant video infrastructure and encrypted record transfer separate compliant operators from excluded competitors.
- Electronic Health Records:Interoperability gaps between origin and destination jurisdictions complicate care handoffs, with German KBA-aligned certification standards creating de facto barriers for non-compliant systems.
- Mobile Health Apps:Patient journey orchestration tools compress decision cycles from inquiry to booking, particularly in cosmetic surgery funnels.
- Wearable Devices:Biometric surveillance dashboards deployed by German cardiac rehabilitation centers enable remote monitoring of returning Scandinavian patients, compressing length-of-stay requirements.
Highest deployment concentration: Telemedicine. Steepest adoption trajectory: Wearable Devices.
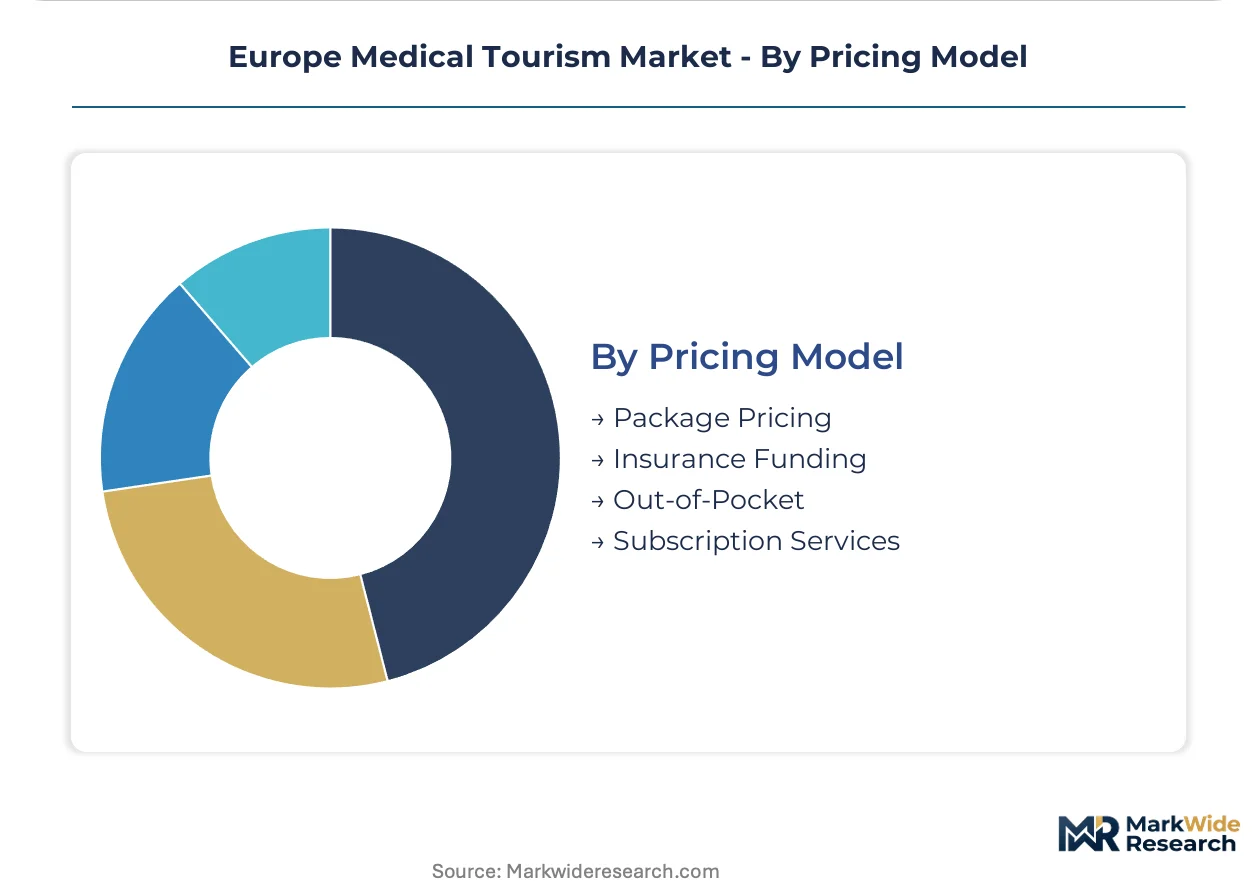
Pricing Model:
Margin structure and working capital intensity diverge significantly across payment mechanisms, with package pricing requiring upfront cost transparency that conflicts with variable clinical pathways.
- Package Pricing:All-inclusive bundles covering procedure, accommodation, and transfer dominate Central European clinic offerings, with price points typically 40-60% below Western European alternatives. Fixed-cost structures demand accurate surgical volume forecasting.
- Out-of-Pocket:Direct payment by uninsured or underinsured patients sustains Bulgarian and Romanian dental and cosmetic surgery volumes, with transparent pricing published on search-optimized platforms.
- Insurance Funding:Reimbursement portability under EU Cross-Border Healthcare Directive enables patients to claim back costs from home jurisdictions, though administrative friction limits utilization.
- Subscription Services:Annual membership models for preventive screening and concierge access remain nascent, concentrated in London and Swiss premium clinic networks.
Largest transaction volume: Package Pricing. Gaining share fastest: Insurance Funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Budapest anchors Central Europe's medical tourism corridor, drawing German and Austrian patients toward orthopaedic and cardiac surgical centers clustered along the Danube basin.
Germany
German patients generate outbound volume toward Hungarian and Polish clinics seeking shorter wait times for hip replacements and cardiac valve procedures. KBA-aligned hospital certification standards create de facto quality barriers that Central European providers must match. Berlin and Munich hospital networks maintain premium positioning through oncology specialization and integrated rehabilitation protocols.
United Kingdom
NHS waitlist pressures drive British patients toward European surgical centers offering package-priced orthopaedic and cataract procedures. GDPR compliance requirements for patient data transfer shape provider selection criteria. London's Harley Street medical district and Cromwell Hospital sustain high-end positioning through direct billing relationships with international insurers and Middle Eastern private payers.
Hungary
Thermal spa infrastructure in the Lake Balaton region converges with clinical rehabilitation protocols to attract Northern European retirees seeking post-acute recovery. EU Cross-Border Healthcare Directive reimbursement portability accelerates patient inflows from Austria and Germany. Budapest surgical centers leverage computer-assisted navigation systems to narrow quality perception gaps with Western European alternatives.
Poland
Polish clinics capture volume from German-speaking patients through cost-advantaged dental implantology and cosmetic surgery offerings. Extended EU MDR conformity assessment timelines for implantable devices strain smaller operators' certification maintenance. Krakow and Warsaw surgical centers deploy telemedicine pre-screening platforms to compress patient acquisition timelines from initial inquiry to booking.
Spain
Spanish coastal facilities in Costa del Sol and the Balearic Islands attract ageing Northern European populations seeking climate-advantaged physiotherapy programs. ANSM-equivalent national accreditation frameworks under Health Ministry oversight govern quality benchmarks for cross-border rehabilitation services. Barcelona and Madrid hospital networks integrate wellness-hospitality hybrids to extend length-of-stay revenue capture.
Europe Medical Tourism Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and care coordination sophistication. The vendor base organizes into three tiers: integrated hospital networks spanning multiple jurisdictions, single-site specialty centers with deep clinical focus, and price-driven clinic operators competing on transparent package pricing. Tiered margin structures reflect divergent investments in multilingual patient navigation, GDPR-compliant data infrastructure, and EU MDR device certification maintenance. Consolidation pressures favor scale operators capable of absorbing regulatory compliance costs while smaller Bulgarian and Romanian clinics face displacement.
Within the integrated network tier, Helios Hospitals exemplifies cross-border scale through clinic presence across Germany, Poland, and Bulgaria. The Royal Marsden occupies premium positioning through oncology specialization attracting Middle Eastern and Asian private payers. Cromwell Hospital anchors London's high-end segment with established direct billing infrastructure. These three entities represent contrasting archetypes: geographic diversification, clinical depth, and payer relationship intensity respectively.
| Leading Market Players |
|---|
| Helios Hospitals |
| The Royal Marsden |
| Cromwell Hospital |
| Institut de la Hernie Paris |
| Charité University Hospital |
| Fresenius Medical Care |
| Bupa Global |
| UZ Leuven |
| AMTA Health |
| Others |
Pricing and Supply Chain Analysis
Multilingual patient navigator concentration in Budapest and Krakow clinics feeds directly into pricing-tier spreads across the European medical tourism corridor. Labor-cost differentials between Central European surgical centers and Western European alternatives enable package pricing at 40-60% discounts while maintaining margin structures through lower coordination overhead.
Pricing Analysis
Outcome-based pricing anchors premium-tier positioning at oncology-specialized London facilities where survival metrics and recurrence rates justify elevated reimbursement rates. Three-tier pricing structure across premium, standard, and economy levels separates concierge-managed international patient programs from self-directed package purchasers and uninsured cash-pay segments. Cost compression in the economy tier is intensifying because Bulgarian and Romanian clinics compete on transparent published rates for dental and cosmetic procedures. Government agency purchasers under NHS partnership agreements exhibit highest price sensitivity, while Middle Eastern private payers at Royal Marsden demonstrate lowest elasticity.
Supply Chain Analysis
Direct-to-patient digital channels now handle the majority of international patient acquisition, displacing traditional medical travel intermediaries across Baltic and Polish clinic networks. Implantable device supply concentrates in Germany, Switzerland, and the Netherlands under EU MDR notified body oversight, with Central European surgical centers consolidating procurement through fewer certified suppliers to maintain conformity. Raw material dependencies span titanium alloys for orthopaedic hardware, biocompatible polymers for cardiac valves, and pharmaceutical-grade silicones for cosmetic applications. Single-source vulnerability around German KBA-aligned certification standards creates de facto exclusion for non-compliant clinic operators. Distribution runs through telemedicine-enabled pre-screening platforms that compress patient acquisition timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European medical tourism market sits in a technology-transition phase where telemedicine infrastructure is systematically replacing traditional referral channel intermediaries as the dominant patient sourcing mechanism.
For Market Incumbents: Lock in GDPR-compliant data infrastructure and EU MDR device certification maintenance as defensive moats against smaller clinic displacement. Consolidate multilingual patient navigator teams in Budapest and Warsaw to defend coordination capabilities against emerging Polish competitors. Absorb compliance cost burdens through scale advantages while subscale Bulgarian operators face regulatory exclusion. For New Entrants and Emerging Players: The 40-60% price-point gap between premium London oncology centers and economy-tier Sofia dental clinics creates white-space targeting opportunity. Czech and Slovak bariatric surgery corridors offer the most penetrable geography given underpenetrated status and proximity to German-speaking populations. Deploy algorithm-governed pre-screening tools under EU AI Act compliance as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with integrated hospital networks possessing cross-border clinic presence given reimbursement portability acceleration under EU Cross-Border Healthcare Directive revisions. Long-term viability favors operators with demonstrated GDPR infrastructure and direct billing relationships to international insurers. Monitor harmonization progress between national quality registries as the inflection indicator for transparent provider selection platforms.| Strategic Initiative | Industry Significance |
|---|---|
| GDPR Infrastructure Investment | Encrypted patient data transfer capability separates compliant operators from excluded competitors under EU privacy law. |
| EU MDR Certification Maintenance | Notified body relationships for implantable devices determine service line expansion eligibility at cardiac centers. |
| Telemedicine Pre-Screening Deployment | Video consultation platforms compress Hungarian and Polish patient acquisition timelines from inquiry to surgical booking. |
| Direct Billing Infrastructure | International insurer relationships at Cromwell Hospital and Helios network facilities secure premium patient flows. |
| Rehabilitation-Wellness Hybrid Development | Thermal spa integration in Lake Balaton region extends length-of-stay revenue capture for Northern European retirees. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this European medical tourism market analysis. Primary interviews with hospital international patient directors, biomedical equipment procurement managers, GPO contracts specialists, and Health Ministry accreditation officers combined with secondary validation from EMA device registration databases, ANSM inspection reports, and national quality registry publications. Bottom-up surgical volume estimates from Hungarian and Polish clinic networks triangulated against top-down reimbursement portability statistics under EU Cross-Border Healthcare Directive frameworks.
Data-stream reconciliation across patient flow tracking, device procurement records, and telemedicine platform analytics informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include service type, end user category, technology deployment maturity, and pricing mechanism, with additional granularity on national accreditation tier and language capability. CAGRs were derived through regression analysis of historical patient mobility patterns against regulatory event timing. Forecast inputs incorporated EU AI Act implementation timelines and GDPR enforcement precedent from CNIL rulings.
Inputs from hospital procurement databases and GPO contract disclosures were available through the study window; gaps in real-time patient outcome tracking across borders introduce uncertainty bands around rehabilitation segment projections. Forecasts reflect assumptions on reimbursement portability administrative friction reduction and quality registry harmonization progress. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Medical Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
North America Health Tourism Market
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
South Korea Medical Tourism Market
Medical Tourism
Outbound Medical Tourism Services Market