
 Asia-Pacific Medical Tourism Market | 2026-2036
Asia-Pacific Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Tourism Market Analysis
Thailand's Medical Council accreditation standards is repositioning the cost-of-entry calculus for new hospital operators across Southeast Asia. Bumrungrad International Hospital leverages its Joint Commission International certification to anchor premium patient flows from the Middle East and Africa. Apollo Hospitals Enterprise Limited dominates South Asian medical tourism through its proton therapy center in Chennai and dedicated international patient services division. Bangkok Dusit Medical Services extends its network across provincial Thailand to capture secondary-city demand.
Asia-Pacific medical tourism encompasses cross-border travel for elective, diagnostic, and therapeutic healthcare services delivered through accredited private facilities, typically involving pre-arranged treatment packages with bundled accommodation and recovery protocols. The primary commercial purpose centers on arbitraging cost differentials for complex procedures while maintaining clinical outcomes comparable to Western benchmarks. Cosmetic surgery and cardiac surgery command the largest revenue pools within service type segmentation, though fertility treatments represent the fastest-expanding category driven by regulatory liberalization in select jurisdictions. Thailand, India, Singapore, and Malaysia as destination categories reveal a bifurcated structure where Thailand and India compete on volume and cost, while Singapore occupies the ultra-premium segment.
India's CDSCO facility licensing requirements, Malaysia's Ministry of Health quality certification framework, and Singapore's MOH private hospital accreditation system collectively shape market access and patient trust dynamics across the region. These regulatory architectures determine which facilities qualify for government-backed medical tourism promotion and international insurance panel inclusion. Stakeholders must monitor evolving accreditation reciprocity agreements between source-country insurers and destination regulators to anticipate patient flow redistribution.
Market Dynamics
Thailand's Medical Council accreditation tightening is compressing facility supply across Southeast Asia, forcing patient flows toward certified operators while raising capital barriers for new entrants. This regulatory recalibration is redistributing volume toward established hospital networks with existing international certifications.
Growth Catalysts
- Cardiac surgery arbitrage:Cost differentials of 60-80% versus Western markets pull patients from the Middle East and Africa to accredited Thai and Indian facilities.
- Malaysia's Ministry of Health quality certification:Government-backed promotion through MM2H visa integration streamlines patient entry and extends average stay duration.
- Fertility treatment liberalization:Regulatory easing in Thailand and Cambodia permits procedures restricted in source markets, expanding addressable patient base.
Market Restraints
- Medical malpractice liability fragmentation:Cross-border jurisdiction disputes complicate patient recourse and elevate insurance costs for receiving hospitals.
- Specialist surgeon concentration:Cardiac and oncology expertise clusters in Bangkok, Chennai, and Singapore, creating bottleneck capacity constraints.
- Source-market reimbursement exclusion:Most OECD public health systems deny coverage for elective overseas procedures, limiting addressable demand to self-pay and private insurance segments.
Strategic Opportunities
- Vietnam's underdeveloped private hospital sector:Da Nang and Ho Chi Minh City lack internationally accredited competitors, creating first-mover positioning for JCI-certified entrants.
- Telemedicine pre-consultation convergence:Remote diagnostics and AI-assisted imaging enable pre-arrival treatment planning, compressing required on-site stay duration.
- Japan's inbound medical visa expansion:METI-designated Global Healthcare Zones in Tokyo and Fukuoka offer regulatory fast-tracking for international patient services.
Industry Challenges
- JCI certification timeline compression:Accreditation cycles extend 18-24 months, delaying revenue recognition for new facility investments.
- Multilingual patient coordinator scarcity:Arabic, Russian, and Mandarin-speaking case managers command premium wages, inflating fixed operating costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Tourism Market |
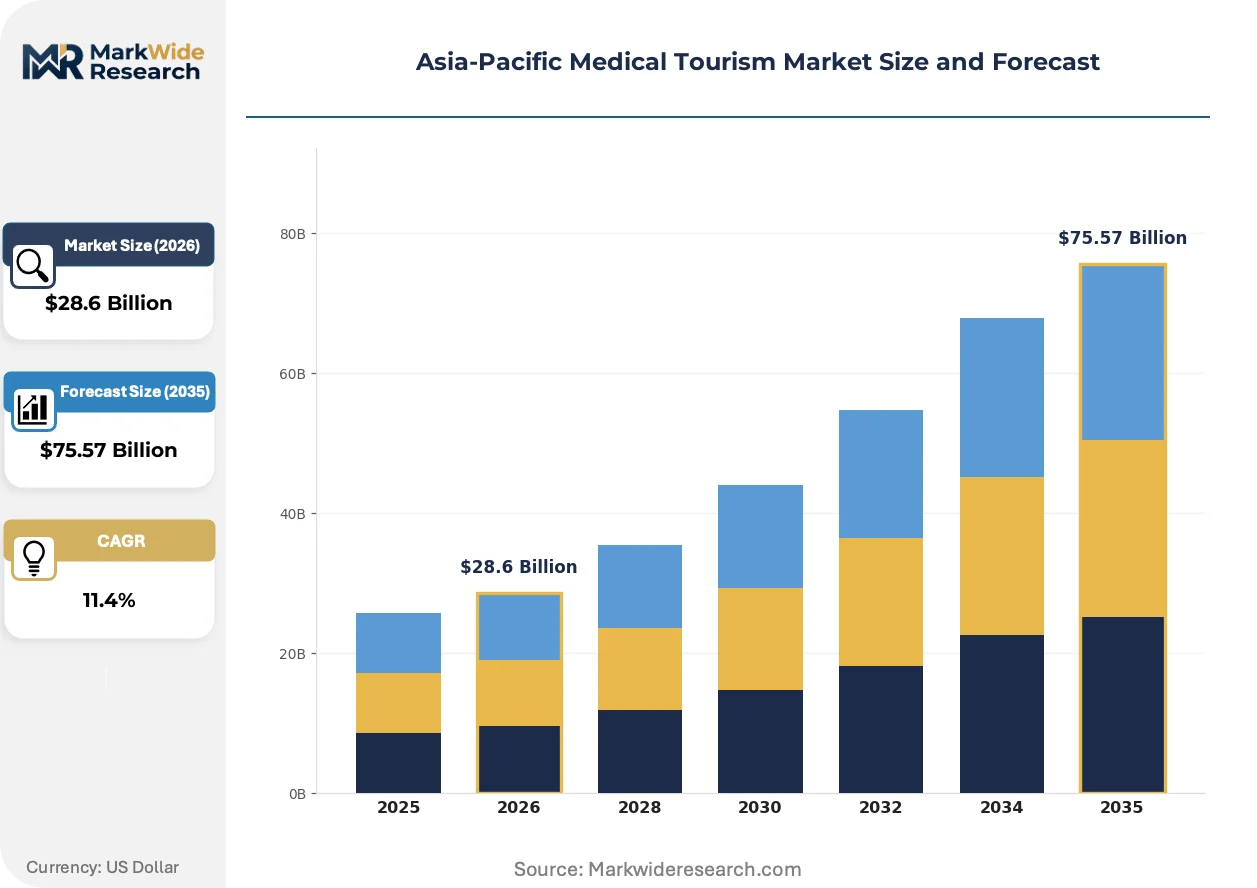
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cosmetic Surgery, Dental Treatment, Cardiac Surgery, Orthopedic Procedures Patient Type: International Tourists, Local Residents, Medical Tourists, Expatriates Destination: Thailand, India, Singapore, Malaysia Treatment Type: Specialized Surgeries, Wellness Therapies, Rehabilitation, Fertility Treatments |
| Companies Covered | IHH Healthcare, Mount Elizabeth Hospital, Bumrungrad International Hospital, KPJ Healthcare Berhad, Fortis Healthcare Limited, Apollo Hospitals Enterprise Limited, Raffles Medical Group, Gleneagles Hospital, Bangkok Dusit Medical Services, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Tourism Market Emerging Trajectories
Digital health infrastructure is collapsing geographic friction in pre-treatment patient engagement, while regulatory reciprocity agreements are rewiring insurance panel access across the region.
Telemedicine platforms integrated with AI-assisted diagnostic imaging are decentralizing specialist consultation access. Patients in the Middle East and Central Asia now complete pre-operative assessments remotely, reducing required on-site stay from 14 days to 5-7 days. This compression is expanding feasible travel radius and enabling secondary-city hospital participation.
Singapore's MOH private hospital accreditation system is mandating real-time outcome reporting to maintain license status. Facilities must submit surgical complication rates and patient satisfaction scores quarterly, with non-compliance triggering promotional restrictions. Thai and Malaysian regulators are observing this framework for potential adoption, pressuring cross-border standardization.
Patient acquisition is fragmenting from medical travel agencies toward direct-to-consumer digital channels. Hospital-owned platforms now capture 35-40% of international bookings in leading Thai facilities, displacing commission-based intermediaries. This channel shift is most advanced in Bangkok's private hospital corridor, where Bumrungrad and Bangkok Hospital operate dedicated Arabic and Russian-language booking portals.
Asia-Pacific Medical Tourism Market Segmentation
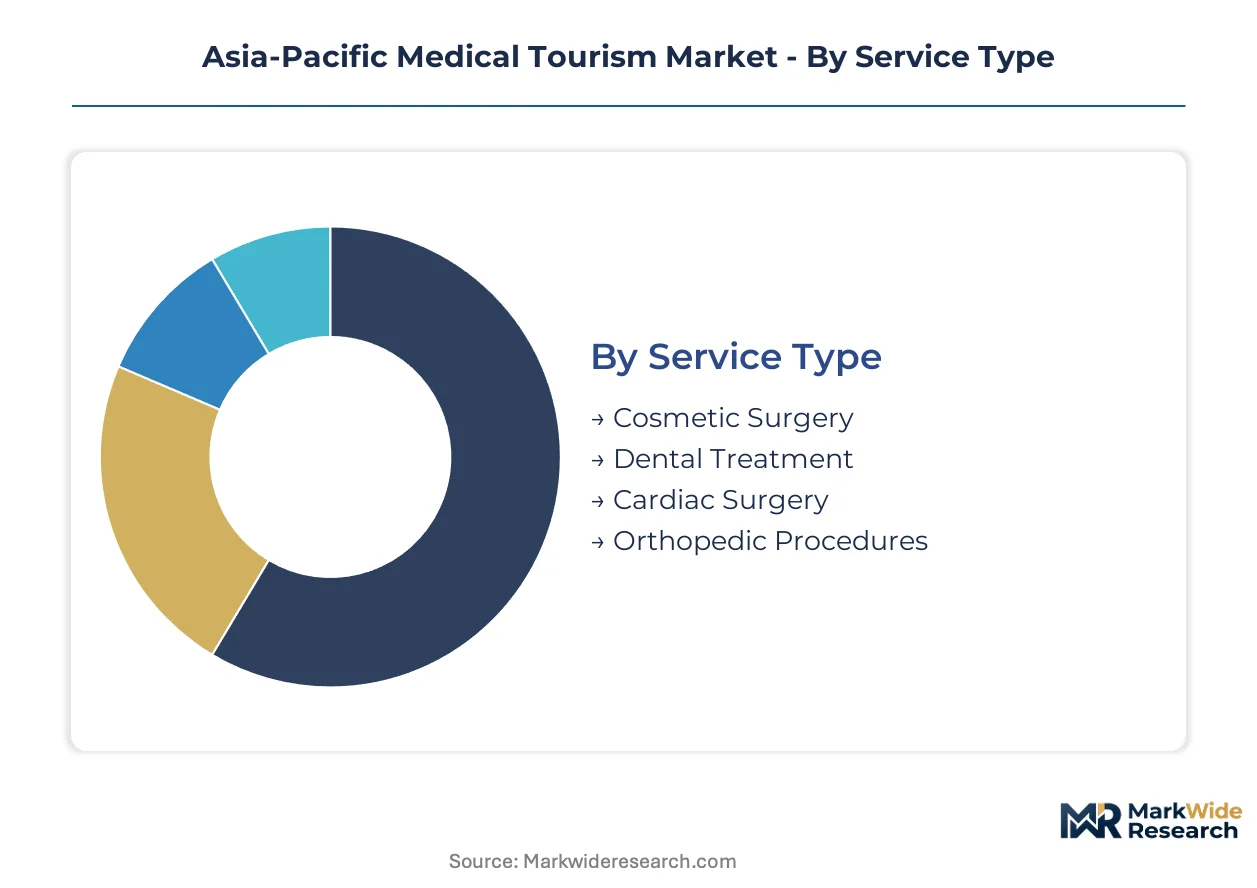
Asia-Pacific medical tourism segmentation reveals how patient decisions cascade through service selection, destination choice, and treatment modality. Understanding these intersecting categories enables facilities to align accreditation investments with addressable demand pools.
Service Type:
Cost arbitrage magnitude drives initial service selection, with procedure complexity and recovery duration shaping total trip economics.
- Cosmetic Surgery:Procedures range from rhinoplasty to full-body contouring, typically requiring 7-14 day recovery windows. Bangkok's private hospital corridor captures Middle Eastern demand for discrete, package-priced aesthetic work.
- Cardiac Surgery:Coronary artery bypass grafting and valve replacement demand ICU infrastructure and perfusionist teams. Indian facilities in Chennai and Hyderabad attract African patients through 60-80% cost differentials versus Western benchmarks.
- Dental Treatment:Implantology and full-mouth reconstruction dominate, with Phuket and Kuala Lumpur competing on same-day CAD/CAM crown fabrication.
- Orthopedic Procedures:Joint replacement and spinal fusion require physiotherapy continuity, favoring destinations with established post-operative care networks.
Volume sits with cosmetic surgery; growth tilts toward cardiac surgery.
Patient Type:
Payment source and visa status fragment the addressable market into distinct acquisition channels with diverging margin profiles.
- Medical Tourists:Patients traveling explicitly for scheduled procedures, typically self-pay or private-insured. Thailand's Medical Council accreditation standards filter this segment toward certified operators.
- International Tourists:Leisure travelers extending stays for elective procedures, particularly dental and cosmetic work. Malaysia's MM2H visa integration targets this hybrid demand.
- Expatriates:Long-term foreign residents accessing routine and semi-urgent care, concentrated in Singapore and Bangkok. This segment demands English-language clinical documentation for employer reimbursement.
- Local Residents:Domestic patients in private facilities, often cross-subsidizing international service infrastructure. Indian tertiary hospitals balance this base with foreign patient prioritization.
Revenue concentrates with medical tourists; expansion tilts toward expatriate retention.
Destination:
Regulatory architecture and certification density determine which facilities qualify for government-backed promotion and insurance panel inclusion.
- Thailand:Bangkok's private hospital corridor anchors volume leadership through Joint Commission International certification density and dedicated Arabic-language patient services.
- India:CDSCO facility licensing requirements shape market access, with Chennai and Hyderabad proton therapy centers commanding oncology premium positioning.
- Singapore:MOH private hospital accreditation mandates real-time outcome reporting, maintaining ultra-premium positioning for complex oncology and organ transplantation.
- Malaysia:Ministry of Health quality certification framework enables government-backed medical tourism promotion, with Iskandar Malaysia targeting Indonesian cross-border demand.
Patient volume clusters in Thailand; value per case climbs fastest in Singapore.
Treatment Type:
Clinical intensity and regulatory permissiveness segment treatment demand across facility capability tiers.
- Specialized Surgeries:Cardiac, neurological, and oncological procedures requiring ICU infrastructure and subspecialist teams. Singapore and Indian metro hospitals dominate this tier.
- Fertility Treatments:IVF and surrogacy services benefit from regulatory liberalization in Thailand and Cambodia, expanding addressable patient base from restrictive source markets.
- Wellness Therapies:Preventive and alternative medicine packages, concentrated in Thai resort destinations with spa-integrated recovery protocols.
- Rehabilitation:Post-surgical physiotherapy and addiction recovery, requiring extended-stay accommodation integration.
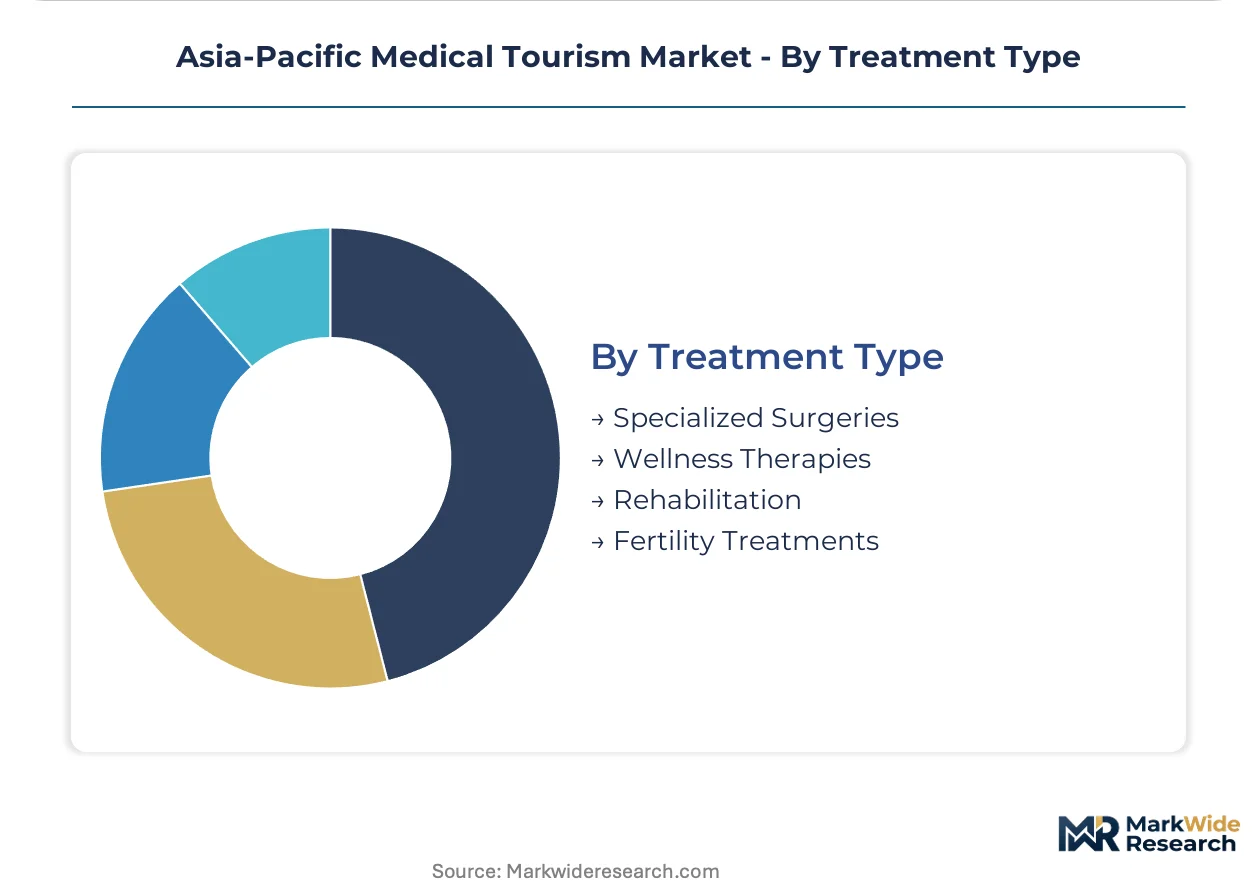
Revenue weight rests with specialized surgeries; fertility treatments gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Eastern Economic Corridor tax incentives and visa facilitation programs concentrate foreign patient processing infrastructure in Bangkok's private hospital corridor, redistributing volume toward certified operators with existing international accreditation.
Thailand
Cardiac surgery cost arbitrage and cosmetic procedure packages draw Middle Eastern and African patients to Bangkok's Joint Commission International-certified facilities. Thailand's Medical Council accreditation tightening compresses facility supply, raising capital barriers for new entrants. Bangkok Dusit Medical Services extends its network across provincial Thailand to capture secondary-city demand.
India
Proton therapy centers in Chennai and Hyderabad command oncology premium positioning for African and Middle Eastern patients. CDSCO facility licensing requirements shape market access and patient trust dynamics. Apollo Hospitals Enterprise Limited dominates South Asian medical tourism through its dedicated international patient services division.
Singapore
Ultra-premium positioning for complex oncology and organ transplantation attracts high-net-worth patients from Southeast Asia and China. MOH private hospital accreditation mandates real-time outcome reporting to maintain license status. Raffles Medical Group and Mount Elizabeth Hospital anchor the city-state's premium-tier medical services cluster.
Malaysia
Ministry of Health quality certification enables government-backed medical tourism promotion through MM2H visa integration. KPJ Healthcare Berhad leverages this framework to streamline patient entry and extend average stay duration. Iskandar Malaysia specifically targets Indonesian cross-border demand with dedicated international patient facilities.
Japan
METI-designated Global Healthcare Zones in Tokyo and Fukuoka offer regulatory fast-tracking for international patient services. Japan's inbound medical visa expansion targets affluent Chinese and Southeast Asian patients seeking advanced diagnostic and therapeutic care. Gleneagles Hospital and IHH Healthcare occupy positions within this emerging premium-tier segment.
Asia-Pacific Medical Tourism Market Vendor Landscape
Thai and Indian hospital networks anchor the volume-driven tier; Singaporean and Malaysian specialists hold ultra-premium positioning. The vendor base clusters around three strategic archetypes: diversified hospital conglomerates with multi-city networks, single-city premium facilities with JCI certification density, and government-linked healthcare groups with visa-integration advantages. Competitive moves concentrate on accreditation reciprocity negotiations with source-country insurers and telemedicine platform integration for pre-arrival patient engagement.
Within the diversified conglomerate tier, IHH Healthcare and Apollo Hospitals Enterprise Limited exemplify scale-driven expansion across multiple jurisdictions. Bangkok Dusit Medical Services represents the network-extension archetype, while Bumrungrad International Hospital occupies a position as the single-city premium facility with dedicated Arabic and Russian-language patient services. These three anchors demonstrate how certification density and visa facilitation programs determine patient flow capture in the Asia-Pacific medical tourism market.
| Leading Market Players |
|---|
| IHH Healthcare |
| Mount Elizabeth Hospital |
| Bumrungrad International Hospital |
| KPJ Healthcare Berhad |
| Fortis Healthcare Limited |
| Apollo Hospitals Enterprise Limited |
| Raffles Medical Group |
| Gleneagles Hospital |
| Bangkok Dusit Medical Services |
| Others |
Supply Flow & Price Mechanics
Perfusionist team salaries in Bangkok's private hospital corridor cascade through cardiac surgery package pricing, compressing margins at Indian facilities competing on 60-80% cost differentials while elevating premium positioning for Singapore's MOH-accredited operators with outcome-reporting mandates.
Pricing Analysis
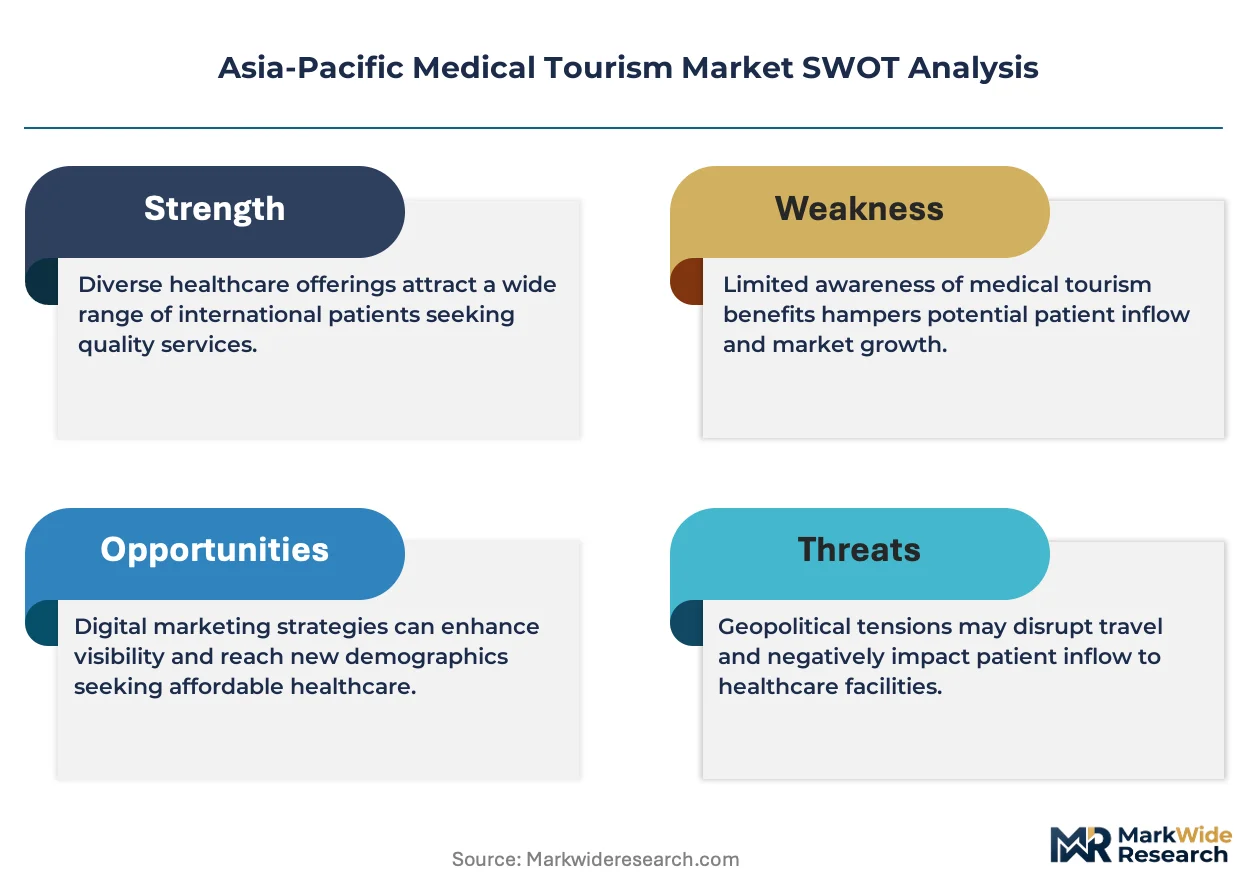
Short lead-time premiums for cardiac surgery slots at Joint Commission International-certified Bangkok facilities command 15-25% markups over standard booking windows, while spot availability in Chennai's proton therapy centers discounts 10-15% for flexible scheduling. Three-tier pricing structure across premium, standard, and economy levels segments by accreditation density and after-surgical care bundling. Price differentiation hinges on JCI certification tier and Arabic-language patient coordinator availability. Pricing pressure intensifies in cosmetic surgery as direct-to-consumer digital channels displace commission-based medical travel agencies. Self-pay African cardiac patients exhibit highest price sensitivity; Middle Eastern high-net-worth oncology seekers show lowest.
Supply Chain Analysis
Direct-to-hospital digital channels now capture 35-40% of international bookings in leading Thai facilities, displacing traditional medical travel agency intermediaries. Geographic supply concentration clusters cardiac perfusionist expertise in Bangkok, Chennai, and Singapore, with fertility treatment capacity expanding across Bangkok, Phnom Penh, and Ho Chi Minh City. Critical dependencies include imported stent inventories from USA and EU manufacturers, radioisotope supplies for proton therapy centers, and Arabic-speaking nursing staff recruitment from Middle Eastern source markets. Single-source vulnerability in JCI accreditation consultant services creates 18-24 month bottlenecks for new facility licensing. Distribution runs through hospital-owned multilingual booking portals, GPO contracts with international insurers, and government-backed MM2H visa-integrated packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemedicine pre-consultation platforms are displacing legacy medical travel agency intermediaries, collapsing geographic friction in patient acquisition and compressing required on-site stay duration from 14 days to 5-7 days.
For Market Incumbents: Extend JCI certification reciprocity negotiations with Middle Eastern and African insurers to lock in panel access before regulatory harmonization spreads. Anchor premium positioning through real-time outcome reporting infrastructure as Thai and Malaysian regulators observe Singapore's MOH framework for potential adoption. Backward integration into telemedicine pre-consultation platforms defends against digital-native entrants capturing direct patient relationships. For New Entrants and Emerging Players: Russian-speaking cardiac patients from Central Asia represent an underserved buyer archetype with limited Arabic-competitor saturation and high procedure complexity. Target Da Nang and Ho Chi Minh City's absence of internationally accredited competitors for first-mover JCI certification. Launch dedicated Russian-language patient coordinator teams and telemedicine pre-arrival assessment platforms as primary go-to-market angle. For Investors and Strategic Acquirers: Thai Medical Council accreditation tightening is the leading indicator that facility supply compression will redistribute volume toward certified operators with existing international certifications. Five-to-ten year viability favors diversified hospital conglomerates with multi-city networks and established visa-facilitation relationships. Watch for CDSCO facility licensing requirement harmonization with Middle Eastern insurance panels as inflection signal for Indian market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| JCI Certification Expansion | Thai Medical Council tightening raises capital barriers for uncertified competitors. |
| Telemedicine Platform Integration | Remote diagnostics enable 5-7 day on-site stays versus legacy 14-day protocols. |
| Arabic-Language Patient Services | Bumrungrad and Bangkok Hospital anchor Middle East and Africa demand capture. |
| MM2H Visa Integration | Malaysian government-backed promotion extends average patient stay duration. |
| Proton Therapy Center Investment | Chennai and Hyderabad facilities command oncology premium positioning. |
Methodological Framework
Independent corroboration across hospital international patient services directors, medical travel agency operators, and health ministry regulatory officials underwrites the qualitative findings in this study. Primary interviews with JCI accreditation consultants, Arabic-speaking patient coordinators, and Middle Eastern insurance panel managers combined with secondary validation from hospital procurement databases, GPO contracts, and CDSCO facility licensing records. Bottom-up patient flow estimates from leading Thai and Indian facilities triangulate against top-down market sizing from government medical tourism promotion agencies.
Comparable-period anchoring to pre-pandemic patient volume baselines and post-recovery acceleration patterns structured the forecast window across the analysis window. Segmentation dimensions modeled include service type complexity tiers, destination regulatory clusters, patient payment source categories, and treatment modality intensity levels. CAGRs derived from procedure volume growth trajectories, average revenue per case expansion, and certification density saturation curves. Industry-specific inputs encompass JCI certification timeline distributions and MM2H visa approval rate fluctuations.
Revisions become necessary when Thai Medical Council accreditation standards tighten beyond modeled timelines, when Middle Eastern insurer panel exclusions expand, or when telemedicine regulatory frameworks fragment across source markets. Forecasts reflect documented assumptions regarding certification reciprocity negotiation progress and visa facilitation program continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Outbound Medical Tourism Services Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
North America Health Tourism Market
Medical Tourism
Malaysia Medical Tourism Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
South Korea Medical Tourism Market