
 France Medical Tourism Market | 2026-2036
France Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
France Medical Tourism Market Foresight
The Haute Autorité de Santé certification cycle is unwinding competitive access, as only facilities meeting its rigorous clinical standards qualify for international patient programs. Institut Gustave Roussy anchors France's oncology tourism appeal through its research-driven treatment protocols. The American Hospital of Paris leverages its dual French-American accreditation to capture North American tourists seeking familiar care standards. Medical Concierge France specializes in end-to-end logistics, controlling the patient journey from arrival through post-operative recovery.
France medical tourism encompasses the organized provision of elective and specialized healthcare services to foreign nationals, typically combining surgical intervention with structured recovery periods in accredited facilities; the sector relies on ISO 15189-compliant laboratory networks and JCI-accredited hospital infrastructure to ensure interoperable quality benchmarks across patient origin markets. Cosmetic surgery and orthopedic surgery command the largest procedure volumes among medical service types, with fertility treatments representing the fastest-growing segment as cross-border reproductive care restrictions tighten elsewhere in Europe. Private clinics capture disproportionate margins compared to public hospital counterparts, while concierge services within travel arrangement types extract premium pricing through personalized care coordination.
ANSM oversees pharmaceutical and medical device standards governing implantable materials used in inbound procedures, while CNIL enforces GDPR-aligned patient data protections that shape how foreign client records traverse French health information systems. The EU Cross-Border Healthcare Directive establishes reimbursement frameworks that partially offset out-of-pocket costs for European patients, directly stimulating Western Europe visitor flows. Stakeholders must monitor evolving HTA assessments by HAS and their downstream impact on which procedures qualify for international marketing.
Market Dynamics
The EU Cross-Border Healthcare Directive is compressing reimbursement timelines for European patients, channeling demand toward Paris-Ile-de-France facilities with HAS-certified international programs. This regulatory alignment is accelerating competitive consolidation among clinics that lack dual accreditation pathways.
Growth Catalysts
- HAS Certification Cycle:The Haute Autorité de Santé's rigorous accreditation framework filters substandard providers, concentrating patient flows into elite facilities that qualify for state-backed international marketing programs.
- Orthopedic Procedure Demand:European patients seeking elective joint replacements are migrating to French private clinics offering shorter wait times than their domestic systems.
- GDPR-Aligned Data Infrastructure:CNIL-enforced patient data protections reassure cross-border clients that medical records traverse French health information systems with EU-standard privacy safeguards.
Market Restraints
- Input Cost Concentration:ANSM-regulated implantable materials face supply concentration among specialized European manufacturers, creating procurement vulnerability for high-volume orthopedic centers.
- Technical Limitation:Language barriers in post-operative care protocols limit expansion into non-French-speaking patient segments without costly multilingual staffing.
- Regulatory Friction:HTA assessments by HAS create uncertainty about which procedures qualify for international marketing, freezing investment in emerging service lines.
Strategic Opportunities
- Fertility Treatment Segment:Restrictions on cross-border reproductive care elsewhere in Europe are redirecting demand toward French clinics with liberal regulatory frameworks.
- Concierge Service Integration:End-to-end logistics providers are capturing premium pricing by controlling patient journeys from arrival through recovery, displacing fragmented booking models.
- North American Channel:Dual French-American accreditation pathways offer untapped penetration potential among US tourists seeking familiar care standards during European travel.
Industry Challenges
- Multilingual Care Coordination:Post-operative nursing staff with certified medical English proficiency command wage premiums that compress margins at mid-tier facilities.
- Accreditation Timeline Compression:JCI hospital accreditation cycles require 18-24 month capital commitments before international patient revenue materializes.
- Legacy System Integration:Electronic health record interoperability between French hospital information systems and foreign insurer platforms demands expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Medical Tourism Market |
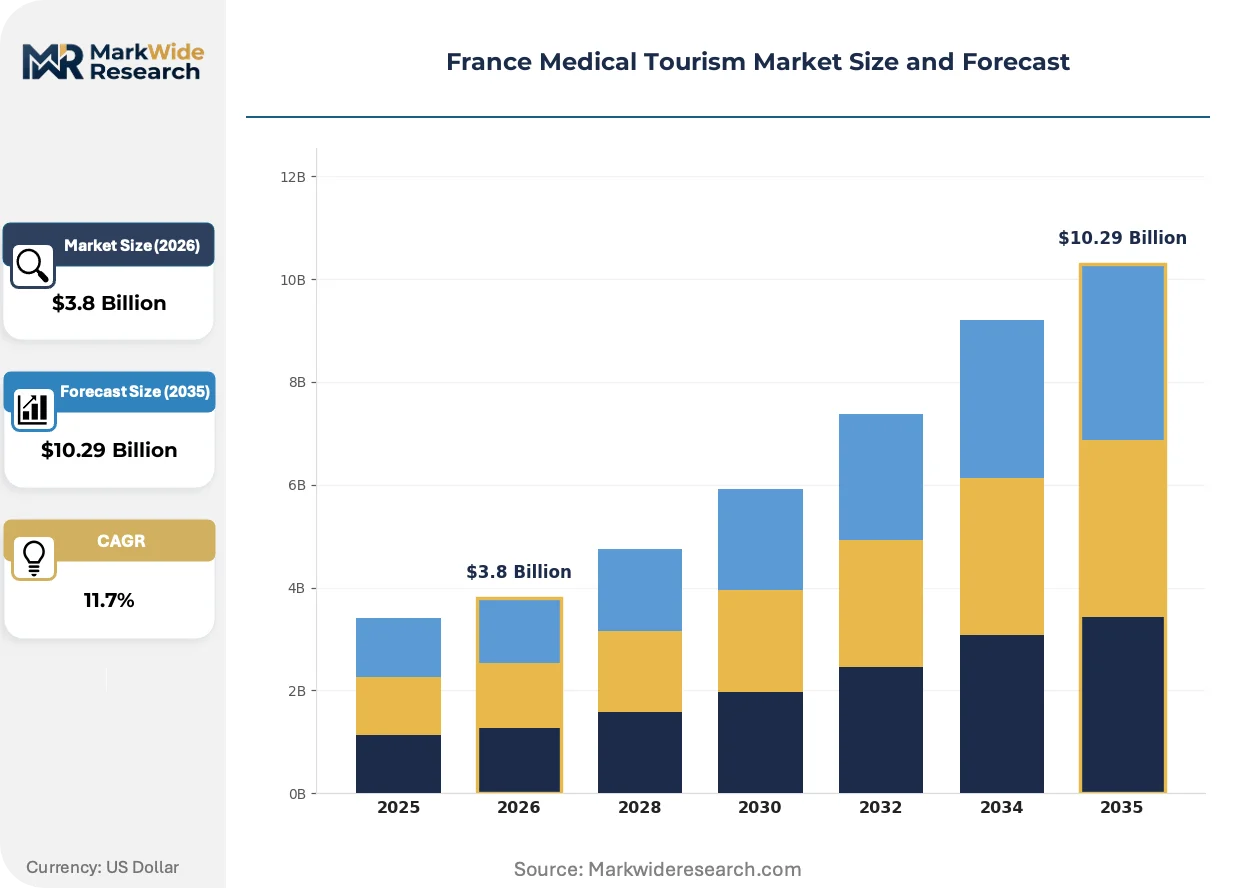
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medical Service Type: Cosmetic Surgery, Dental Care, Orthopedic Surgery, Fertility Treatments, Cardiovascular Procedures Patient Origin: Western Europe Visitors, Middle East Residents, African Clients, North American Tourists, Asian Patients Healthcare Facility Type: Private Clinics, Specialized Hospitals, Wellness Centers, Rehabilitation Facilities, Diagnostic Centers Travel Arrangement Type: Package Tours, Individual Travel, Concierge Services, Insurance-Covered Trips, Corporate Partnerships |
| Companies Covered | The Hernia Institute Paris, Medifrance Solution, France Medical Access, FAME Santé, France Surgery, Medical Concierge France, American Hospital of Paris, Institut Gustave Roussy, Clinique Bizet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Medical Tourism Market Shifts & Advancements
Telemedicine pre-consultation workflows are compressing patient acquisition costs while remote monitoring technologies reshape post-operative care economics. These shifts are redistributing value capture between clinical providers and technology-enabled concierge platforms.
AI-powered diagnostic imaging is displacing traditional radiologist review for pre-operative orthopedic assessments. Private clinics in the Paris cluster are adopting these tools to accelerate patient onboarding. The technology is compressing specialist consultation timelines from weeks to days.
GDPR enforcement by CNIL is tightening data localization requirements for patient records. Foreign nationals now expect explicit consent protocols for cross-border information transfers. North American patients are driving demand for HIPAA-aligned documentation standards alongside EU compliance.
Direct-to-patient digital platforms are fragmenting traditional referral networks. European health insurers are bypassing general practitioners to contract directly with HAS-certified facilities. This channel shift is most visible among German and Belgian patient segments seeking elective procedures.
France Medical Tourism Market Segmentation
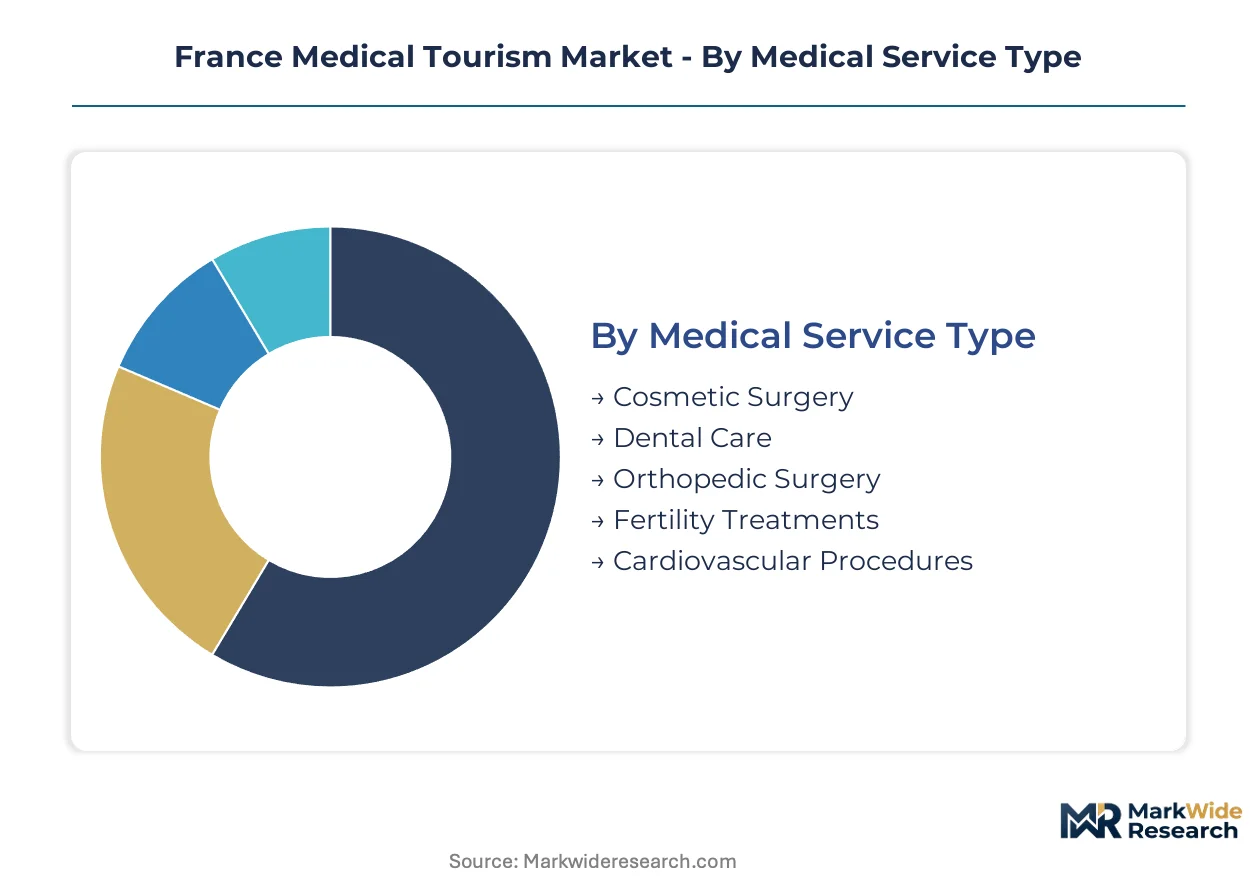
France medical tourism segmentation reveals how HAS certification filters concentrate demand into specific facility tiers while travel arrangement innovations reshape patient acquisition economics. Understanding these divides exposes where pricing power accumulates and which service lines face displacement from telemedicine alternatives.
Medical Service Type:
Cosmetic surgery faces intensifying substitution pressure from non-invasive aesthetic procedures and at-home devices, forcing French clinics to differentiate through surgeon reputation and recovery environment quality rather than procedure alone.
- Cosmetic Surgery:Rhinoplasty, breast augmentation, and body contouring procedures dominate inbound volumes. Paris-Ile-de-France private clinics capture premium positioning through HAS-certified plastic surgery units serving Western Europe visitors seeking discretion and shorter wait times than domestic systems allow.
- Orthopedic Surgery:Elective joint replacements and spinal procedures concentrate demand among Belgian, German, and Swiss patients escaping domestic queue systems. Instituts mutualistes in Lyon and Marseille compete with Paris facilities on cost while maintaining identical implant quality standards under ANSM oversight.
- Fertility Treatments:IVF and cryopreservation services attract cross-border demand from jurisdictions with restrictive reproductive laws. French bioethics framework permits procedures prohibited elsewhere in Europe.
- Cardiovascular Procedures:Interventional cardiology and valve replacements draw African and Middle East clients to French university hospital networks.
- Dental Care:Implantology and aesthetic dentistry serve price-sensitive segments from the UK and Ireland seeking cost arbitrage against domestic private rates.
Orthopedic surgery retains volume leadership; fertility treatments hold the steepest expansion curve as regulatory divergence across Europe widens.
Patient Origin:
Western Europe visitors concentrate disproportionate revenue per case through insurance reimbursement pathways under the EU Cross-Border Healthcare Directive, while African and Middle East clients drive cash-pay premium segments.
- Western Europe Visitors:Belgian, German, Swiss, and British patients dominate elective procedure volumes. GDPR-aligned data protections and familiar regulatory standards reduce friction in care coordination.
- North American Tourists:US and Canadian visitors combine European travel with scheduled procedures, prioritizing English-speaking staff and JCI-accredited facilities. The American Hospital of Paris anchors this segment.
- Middle East Residents:Gulf state nationals seek oncology and complex surgical interventions at French university hospitals. Medical Concierge France controls end-to-end logistics for this high-value cohort.
- African Clients:Francophone West and Central African elites access specialized care unavailable domestically. Payment guarantees and embassy coordination shape facility selection.
- Asian Patients:Smaller but growing segment seeking fertility and wellness services, concentrated in Paris luxury clinic networks.
Western Europe visitors anchor current revenue; Middle East residents are climbing the fastest as concierge services penetrate Gulf markets.
Healthcare Facility Type:
Private clinics command margin premiums through controlled patient journeys and faster procedure scheduling, while public hospital international departments struggle with legacy administrative systems.
- Private Clinics:HAS-certified établissements de santé privés d'intérêt collectif dominate cosmetic and orthopedic segments. Chirurgie ambulatoire models compress length-of-stay costs while maintaining clinical outcomes.
- Specialized Hospitals:Cancer centers and cardiovascular institutes attract complex case referrals. Institut Gustave Roussy anchors oncology tourism through research protocol access.
- Wellness Centers:Post-operative recovery and preventive medicine services extend patient stays. Thermal spa integration in regions like Auvergne-Rhône-Alpes differentiates from clinical-only competitors.
- Rehabilitation Facilities:Physical therapy and post-surgical recovery centers serve orthopedic and neurological patients requiring extended stays.
- Diagnostic Centers:Imaging and laboratory services support pre-operative workups, increasingly adopting AI-powered radiology to accelerate patient onboarding.
Private clinics capture the highest margins per bed; specialized hospitals are gaining share fastest through research-driven treatment protocols.
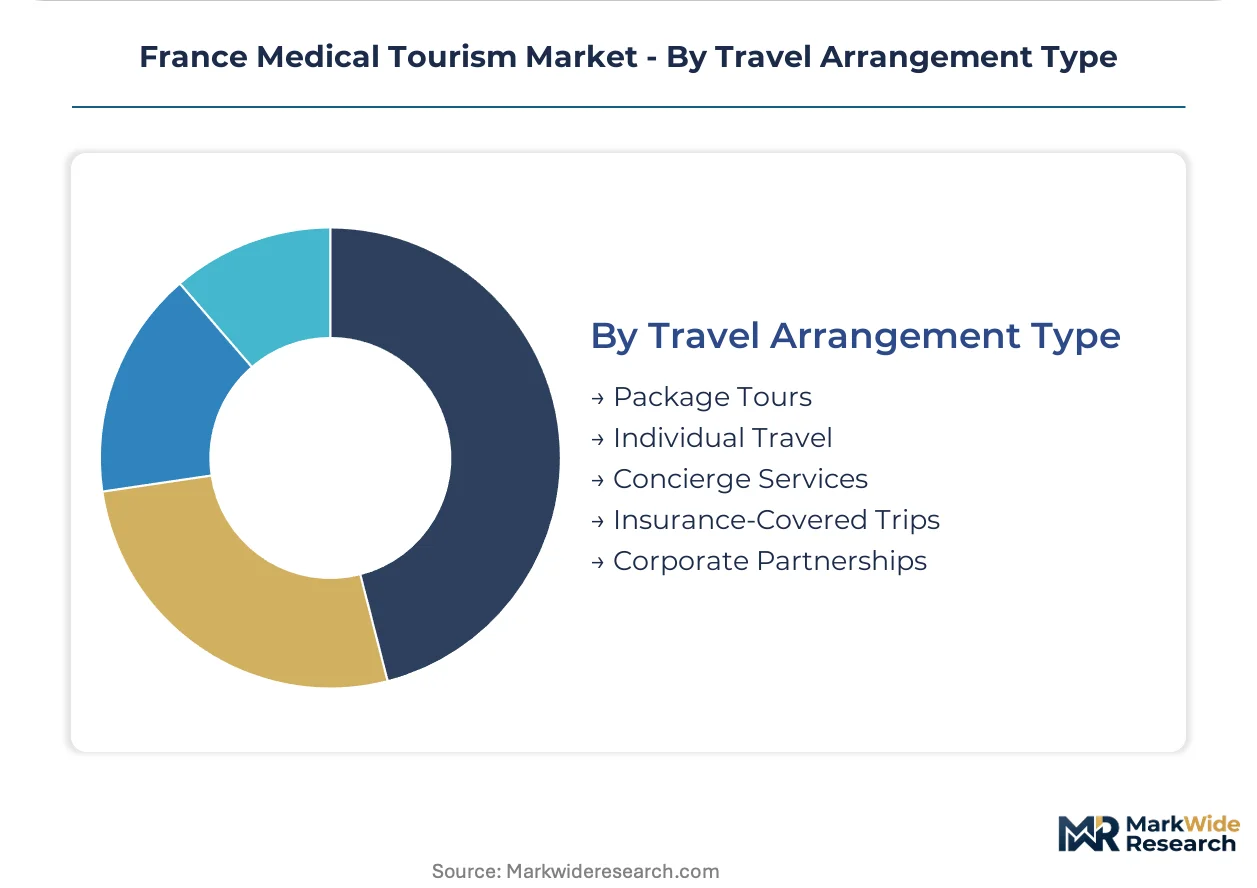
Travel Arrangement Type:
Concierge services are displacing fragmented booking models by controlling the full patient journey, extracting premium pricing through personalized coordination that traditional travel agencies cannot replicate.
- Concierge Services:End-to-end logistics providers manage arrival, accommodation, procedure scheduling, and post-operative recovery. Medical Concierge France and similar operators capture 15-25% service fees on total package value.
- Insurance-Covered Trips:EU Cross-Border Healthcare Directive reimbursements channel Western European patients toward HAS-certified facilities with pre-negotiated insurer contracts.
- Package Tours:Traditional medical travel aggregators bundle procedures with tourism components. Market share is compressing as direct-to-facility booking platforms fragment referral networks.
- Individual Travel:Self-directed patients arrange procedures independently, concentrated among French-speaking African clients with existing Paris networks.
- Corporate Partnerships:Employer-sponsored medical travel programs serve expatriate workforces and executive health screening, particularly in energy and finance sectors.
Concierge services dominate premium segment economics; insurance-covered trips are expanding most quickly as EU reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Cross-Border Healthcare Directive is channeling reimbursement flows toward French facilities with HAS-certified international programs, concentrating patient acquisition in specific metropolitan clusters with established concierge infrastructure.
Île-de-France
Paris anchors inbound volume through the American Hospital of Paris and Institut Gustave Roussy, which capture North American oncology tourists and Middle East residents seeking complex interventions. HAS certification requirements filter demand into elite facilities with state-backed international marketing privileges. The Paris-Ile-de-France cluster commands premium positioning across cosmetic and orthopedic segments.
Auvergne-Rhône-Alpes
Lyon's instituts mutualistes compete with Paris on cost while maintaining ANSM-mandated implant quality standards for Belgian and Swiss orthopedic patients. Thermal spa integration in this region differentiates post-operative recovery offerings from clinical-only competitors. The Lyon cluster specializes in shorter-stay ambulatory surgery models.
Provence-Alpes-Côte d'Azur
Nice and Marseille facilities attract Mediterranean-crossing patients from Italy and North Africa seeking fertility treatments unavailable under restrictive domestic frameworks. French bioethics regulations permit procedures prohibited elsewhere in Southern Europe. The coastal cluster leverages wellness tourism infrastructure for extended recovery stays.
Hauts-de-France
Lille's proximity to Belgian and British markets positions it for dental and elective procedure arbitrage seekers escaping domestic private rates. GDPR-aligned data protections reduce friction for UK patients post-Brexit. The border-adjacent cluster specializes in same-day surgical workflows.
France Medical Tourism Market Competitive Landscape
Listed hospital networks compete with private clinic specialists across accreditation tier and patient journey control. Market structure concentrates margin capture in dual-accredited facilities with concierge service integration, while mid-tier public hospital international departments struggle with legacy administrative systems. Three archetypes dominate: research-driven oncology centers, dual French-American accredited hospitals, and end-to-end logistics coordinators. Competitive moves center on JCI accreditation acquisition and telemedicine pre-consultation platform deployment.
Within the concierge-coordination tier, Medical Concierge France exemplifies patient journey control from arrival through recovery. The American Hospital of Paris occupies a position among dual-accredited facilities serving North American tourists. Institut Gustave Roussy represents the research-driven oncology anchor attracting complex case referrals from Gulf state nationals.
| Leading Market Players |
|---|
| The Hernia Institute Paris |
| Medifrance Solution |
| France Medical Access |
| FAME Santé |
| France Surgery |
| Medical Concierge France |
| American Hospital of Paris |
| Institut Gustave Roussy |
| Clinique Bizet |
| Others |
Supply & Pricing Matrix
Scale economies at HAS-certified facilities in the Paris-Ile-de-France cluster compress per-procedure costs while erecting price floors that marginalize uncertified competitors. This concentration dynamic concentrates procurement leverage among elite clinics and reshapes margin distribution across the French medical tourism value chain.
Pricing Analysis
Certification level under HAS and JCI frameworks creates the primary spread between premium and standard service tiers. HAS-certified private clinics command three-tier pricing structure across premium, standard, and economy levels based on accreditation grade and surgeon reputation. Pricing pressure stems from telemedicine pre-consultation platforms compressing patient acquisition costs at mid-tier facilities. North American tourists exhibit lowest price sensitivity, prioritizing dual-accredited facilities with English-speaking staff; dental care seekers from the UK and Ireland show highest sensitivity, driving cost arbitrage demand.
Supply Chain Analysis
Germany and Switzerland anchor European manufacturing of orthopedic implants and cardiovascular devices under ANSM oversight. French clinics draw from specialized European suppliers for implantable materials, with procurement concentrated among CE-marked device manufacturers. Single-source vulnerability runs through concentrated German orthopedic implant suppliers facing input material constraints. Distribution runs through hospital procurement consortiums and direct-to-clinic agreements with HAS-certified facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemedicine-enabled pre-consultation platforms threaten traditional patient acquisition economics, forcing incumbents to defend substitution pressure from technology-enabled concierge models that fragment referral networks.
For Market Incumbents: Consolidate control over end-to-end patient journeys through concierge service integration rather than fragmented booking partnerships. HAS certification investment anchors defensive positioning against uncertified competitors while JCI dual-accreditation captures North American tourist segments. Vertical integration into post-operative recovery facilities in Auvergne-Rhône-Alpes thermal spa regions locks in extended-stay revenue streams. For New Entrants and Emerging Players: Anchor in fertility treatment segments where regulatory divergence across Europe redirects demand toward French clinics with liberal bioethics frameworks. The Provence-Alpes-Côte d'Azur cluster offers white-space penetration among Mediterranean-crossing Italian patients seeking procedures unavailable domestically. Direct-to-patient digital platforms bypass traditional GP referral networks for fastest go-to-market velocity. For Investors and Strategic Acquirers: Dual-accredited mid-tier clinic networks with underdeveloped concierge capabilities represent the most attractive acquisition archetype for platform roll-up strategies. Long-term viability hinges on regulatory alignment between EU Cross-Border Healthcare Directive reimbursement frameworks and HTA assessment stability. The signal to monitor is HAS certification timeline compression and its downstream impact on facility valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| JCI Dual-Accreditation Pathway | Unlocks North American tourist segments seeking familiar care standards at Paris facilities. |
| Concierge Service Integration | Captures 15-25% service fees by controlling full patient journeys from arrival through recovery. |
| Telemedicine Pre-Consultation Deployment | Compresses specialist consultation timelines from weeks to days for orthopedic assessments. |
| Thermal Spa Partnership Network | Extends patient stays in Auvergne-Rhône-Alpes through post-operative wellness integration. |
| Direct-to-Patient Digital Platform | Fragments traditional GP referral networks for German and Belgian elective procedure seekers. |
Research Methodology
Operator-level perspectives from clinic operations directors, HAS certification auditors, medical concierge service founders, and hospital procurement managers anchored the qualitative base. Primary interview data combined with secondary validation from ANSM device registration databases, EU Cross-Border Healthcare Directive reimbursement filings, and hospital accreditation records. Bottom-up procedure volume estimates triangulated against top-down market sizing across medical service type and patient origin segments.
Sensitivity analysis tested forecast outputs against variable assumptions for EU reimbursement policy continuity and telemedicine adoption velocity across the analysis window. Segmentation modeling incorporated medical service type, patient origin geography, healthcare facility tier, and travel arrangement channel. CAGRs derived from procedure volume trajectories and average revenue per case trends, with fertility treatment and concierge service segments receiving distinct growth curve assumptions.
Decision-makers should treat outputs as directional under assumptions of stable HAS certification standards and continued EU Cross-Border Healthcare Directive enforcement; material deviation in HTA assessment criteria or reimbursement timeline compression would warrant model refresh. Specific risks include regulatory friction from evolving bioethics frameworks and supply concentration in German implant manufacturers. Recalibration cycles align with material shifts in EU healthcare policy and telemedicine platform penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
Malaysia Medical Tourism Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
Europe Medical Tourism Market