
 Thailand Medical Tourism Market | 2026-2036
Thailand Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Medical Tourism Market Outlook
Joint Commission International (JCI) accreditation is bifurcating the competitive landscape into accredited multi-specialty chains and non-accredited local operators. Bumrungrad International Hospital leverages its JCI gold seal to anchor premium medical tourist flows from the Middle East and Southeast Asia. Bangkok Hospital Group (BDMS) sustains network scale across fourteen facilities, while Yanhee International Hospital specializes in cosmetic surgery volume.
Thailand medical tourism encompasses cross-border travel for elective procedures, diagnostic services, and complex surgeries performed in private tertiary facilities with English-speaking staff and dedicated international patient centers. Cosmetic surgery and dental care segments dominate current revenue, while robotic surgery and telemedicine integration represent the fastest-expanding technology tiers. Package pricing models capture prepaid tourist flows, whereas pay-per-procedure structures serve spontaneous demand from regional visitors.
Thailand's Medical Hub of Asia policy, administered by the Ministry of Public Health, shapes market access through streamlined non-immigrant MT visas and tax incentives for hospital infrastructure investment. The Medical Council of Thailand enforces physician licensing standards that foreign patients use as quality signals when selecting facilities. Stakeholders must monitor how telemedicine regulations evolve to determine whether pre-arrival consultations become a regulated revenue stream or a competitive cost center.
Market Dynamics
Thailand's Medical Hub of Asia policy is concentrating demand flows toward Bangkok's private hospital cluster while compressing competitive differentiation around JCI accreditation tiers and package pricing models.
Growth Catalysts
- Non-immigrant MT visas:Thailand's streamlined visa framework reduces administrative friction for Middle Eastern and Southeast Asian patients seeking elective procedures.
- Cosmetic surgery specialization:Dedicated international patient centers within Bangkok's tertiary facilities capture prepaid tourist flows through bundled accommodation-procedure packages.
- Robotic surgery adoption:Da Vinci surgical systems and similar platforms are expanding addressable procedure complexity beyond traditional cosmetic and dental segments.
Market Restraints
- Physician licensing bottlenecks:Medical Council of Thailand enforcement creates credentialing delays for foreign-trained specialists seeking practice rights.
- Bangkok demand concentration:Over 70% of medical tourist volume flows through a single metropolitan cluster, creating capacity constraints and price inflation pressure.
- Regional competition from Singapore and Malaysia:Alternative ASEAN destinations with comparable JCI accreditation are fragmenting patient sourcing from Gulf Cooperation Council states.
Strategic Opportunities
- Chiang Mai and Phuket secondary hubs:Northern and southern provinces offer untapped capacity for wellness-integrated medical tourism outside Bangkok's saturated corridor.
- Telemedicine pre-arrival consultations:Remote diagnostic triage and surgical planning could extend patient capture radius to African and Latin American source markets.
- Tax incentive infrastructure expansion:Thailand's Board of Investment privileges for hospital construction are accelerating greenfield tertiary facility development in secondary cities.
Industry Challenges
- English-Thai medical interpreter scarcity:Bilingual nursing and patient coordination staff command wage premiums that compress margin structures at non-accredited facilities.
- JCI accreditation timelines:The 12-18 month certification process delays market entry for new hospital groups seeking premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Medical Tourism Market |
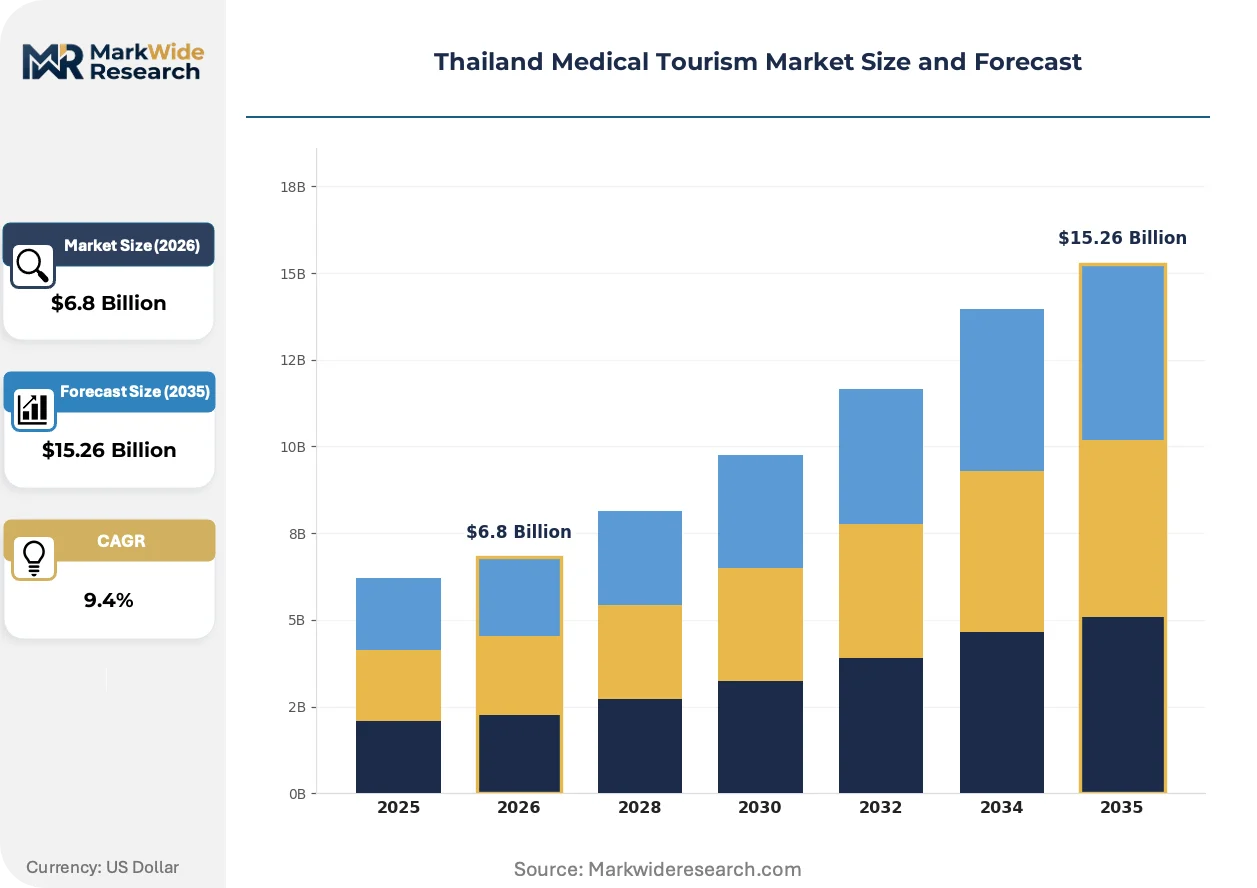
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cosmetic Surgery, Dental Care, Fertility Treatment, Cardiovascular Surgery End User: International Patients, Local Residents, Health Insurance Beneficiaries, Medical Tourists Technology: Telemedicine, Minimally Invasive Surgery, Robotic Surgery, Electronic Health Records Pricing Model: Package Pricing, Pay-Per-Procedure, Insurance Coverage, Membership Plans |
| Companies Covered | Phyathai Hospital Group, Yanhee International Hospital, Bumrungrad International Hospital, Kasemrad International Rattanathibet Hospital, MedPark Hospital, Bangkok Hospital Group (BDMS), BNH Hospital, Mission Hospital, Samitivej Hospital Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Medical Tourism Market Strategic Shifts
Digital health infrastructure and regulatory modernization are compressing patient acquisition cycles while elevating pre-arrival care coordination as a competitive battleground.
Telemedicine platforms are supplanting traditional travel-agent intermediaries as the primary patient acquisition channel. Middle Eastern medical tourists now complete initial consultations through encrypted video platforms before booking flights. This channel shift is compressing the traditional 90-day decision window to under 14 days and eliminating commission layers that previously captured 15-20% of package value.
Thailand's Medical Hub of Asia policy framework is mandating electronic health record interoperability across private hospital networks. The Ministry of Public Health's data-sharing requirements are forcing consolidation among fragmented clinic operators unable to afford HIPAA-compliant infrastructure. International patient centers at Bumrungrad and BDMS facilities are responding by integrating pre-arrival diagnostic uploads into surgical planning workflows.
Package pricing transparency is displacing opaque pay-per-procedure billing as the dominant patient preference signal. Regional visitors from Vietnam and Cambodia now demand all-inclusive quotes covering complications and revision surgeries. This behavioral shift is most visible in cosmetic surgery segments, where Bangkok Hospital Group has introduced fixed-price guarantees for rhinoplasty and breast augmentation procedures.
Thailand Medical Tourism Market Segmentation
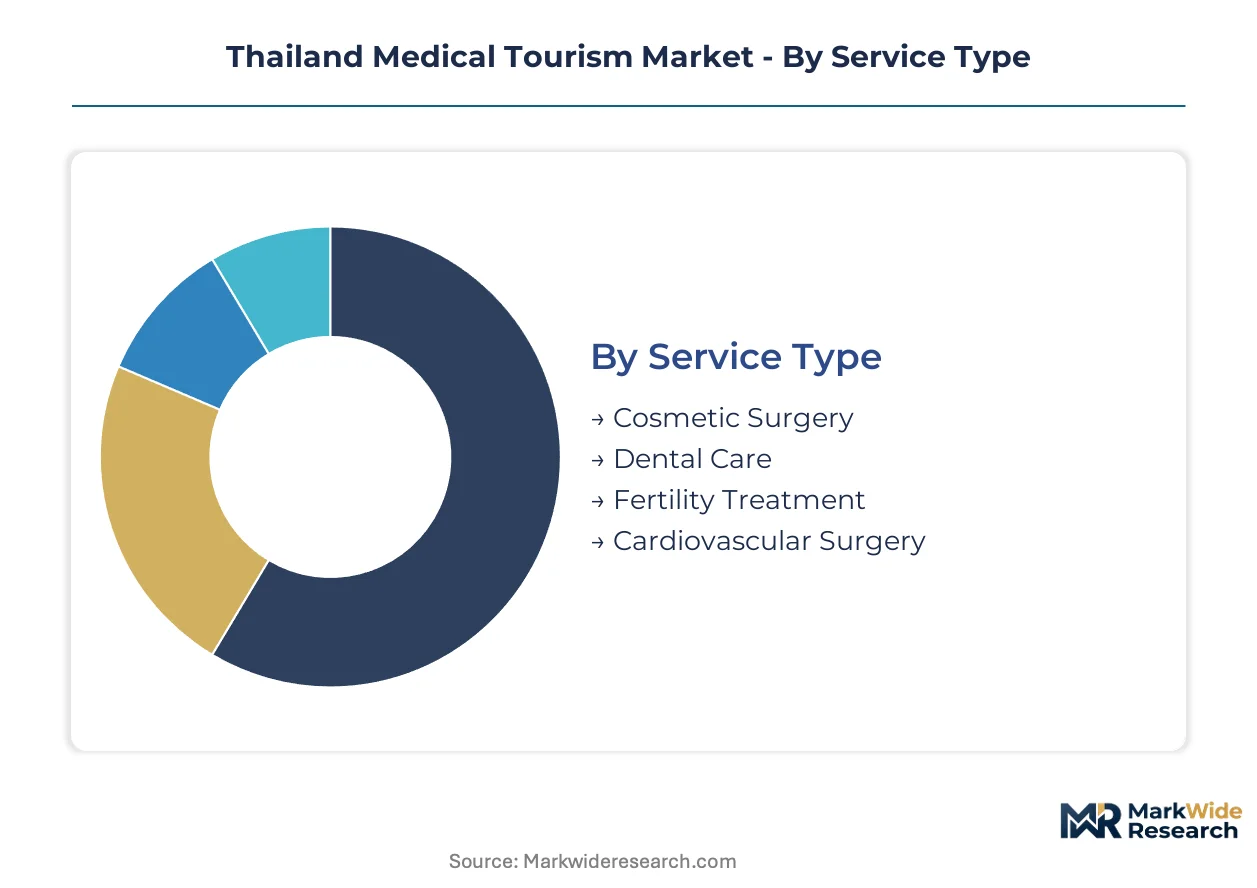
Service type segmentation reveals where Thailand's private hospitals capture premium margin versus where substitute destinations threaten volume. End user and technology dimensions expose acquisition-channel dependencies that reshape pricing power across Bangkok's hospital clusters.
Service Type:
Cosmetic surgery faces intensifying substitution pressure from Turkish and South Korean clinics offering comparable JCI accreditation at lower package prices.
- Cosmetic Surgery:Procedures encompass rhinoplasty, breast augmentation, and body contouring performed in dedicated aesthetic centers with English-speaking coordinators. Demand concentrates in Bangkok's Sukhumvit corridor where Bumrungrad and Yanhee bundle accommodation-procedure packages for Middle Eastern sourcing markets facing currency volatility.
- Dental Care:Crowns, implants, and full-mouth reconstructions leverage Thailand's laboratory cost advantages and same-day CAD/CAM milling capabilities. Bangkok Hospital Group channels ASEAN regional patients through border-clinic partnerships in Nong Khai and Udon Thani.
- Fertility Treatment:IVF and egg-freezing services exploit Thailand's permissive regulatory framework for donor gametes.
- Cardiovascular Surgery:Complex valve replacements and coronary bypass procedures require Da Vinci robotic systems available only at BDMS flagship facilities.
Cosmetic surgery retains volume leadership; cardiovascular surgery holds the steepest expansion curve as robotic platforms extend treatable case complexity.
End User:
Customer-type segmentation tracks how payment-source fragmentation alters pre-arrival consultation investments and package-design priorities.
- International Patients:Self-pay travelers from Gulf Cooperation Council states and Southeast Asia drive prepaid package demand with 14-day booking windows compressed by telemedicine triage. Bangkok's international patient centers assign dedicated Arabic and Mandarin coordinators to secure repeat referral flows.
- Medical Tourists:Visitors explicitly traveling for treatment distinct from incidental care during leisure travel. Phuket's beachfront recovery facilities capture this segment through wellness-integrated positioning unavailable in Bangkok's clinical environment.
- Local Residents:Thai nationals accessing private facilities for queue-jumping on elective procedures.
- Health Insurance Beneficiaries:Policyholders from countries with outbound reimbursement schemes.
International patients retain volume leadership; medical tourists hold the steepest expansion curve as secondary hubs build recovery-resort capacity.
Technology:
Technology adoption separates capital-intensive tertiary operators from clinic networks unable to fund interoperability mandates.
- Robotic Surgery:Da Vinci and competing platforms enable prostatectomy, cardiac valve repair, and gynecologic oncology with reduced recovery windows. BDMS and Bumrungrad anchor competitive positioning through exclusive regional distribution agreements with Intuitive Surgical.
- Telemedicine:Encrypted pre-arrival consultation platforms now displace travel-agent intermediaries for initial patient capture. Middle Eastern sourcing markets complete diagnostic triage through hospital-branded apps before visa application.
- Minimally Invasive Surgery:Laparoscopic and endoscopic techniques reduce length-of-stay metrics for insurance reimbursement calculations.
- Electronic Health Records:Ministry-mandated interoperability standards force consolidation among fragmented clinic operators.
Telemedicine retains volume leadership; robotic surgery holds the steepest expansion curve as procedure complexity thresholds rise.
Pricing Model:
Payment-structure segmentation exposes where transparency mandates compress margin versus where opacity still permits surcharge capture.
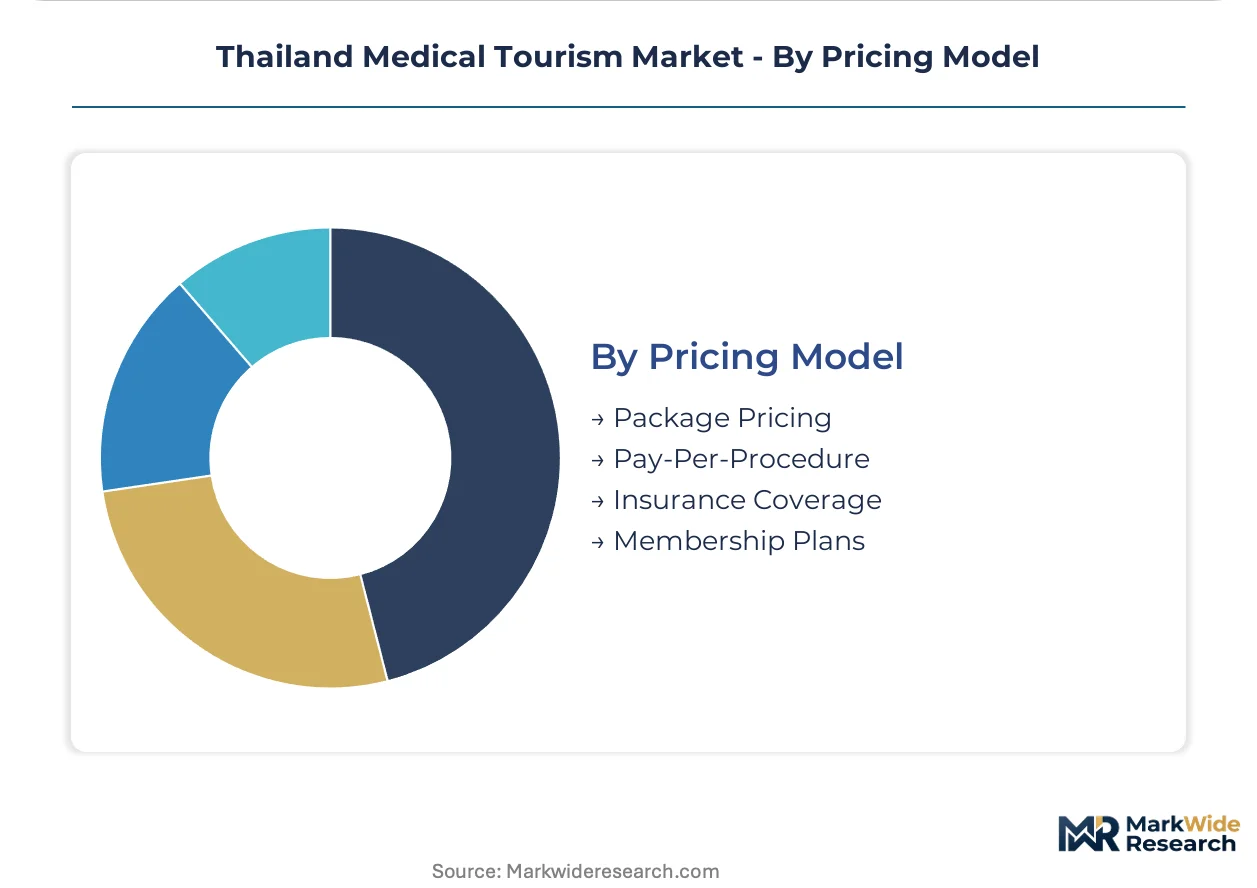
- Package Pricing:All-inclusive quotes covering procedure, accommodation, complications, and revision surgery. Bangkok Hospital Group introduced fixed-price guarantees for cosmetic segments after Vietnamese and Cambodian patients demanded quote certainty.
- Pay-Per-Procedure:Itemized billing for spontaneous demand from regional visitors crossing land borders. Non-accredited clinics in border provinces retain this model for price-sensitive Cambodian and Lao patients.
- Insurance Coverage:Direct settlement arrangements with Gulf and European insurers requiring JCI accreditation as network entry condition.
- Membership Plans:Annual subscription models for repeat cosmetic maintenance and wellness screening.
Package pricing retains volume leadership; membership plans hold the steepest expansion curve as patient lifetime value calculations penetrate CRM systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical tourists from Gulf Cooperation Council states, Southeast Asia, and East Asia dominate Thailand's patient inflows, with Bangkok's private hospital cluster capturing over seventy percent of total volume. Visa-streamlined corridors from Saudi Arabia, the UAE, and Kuwait concentrate elective cosmetic and cardiac demand in the capital's Sukhumvit corridor.
Bangkok Metropolitan Region
Cosmetic surgery and cardiovascular procedures drive patient flows from Middle Eastern markets. Thailand's Ministry of Public Health administers the Medical Hub of Asia policy, issuing non-immigrant MT visas that reduce administrative friction for extended treatment stays. Bumrungrad International Hospital and Bangkok Hospital Group anchor the Sukhumvit corridor cluster, where JCI-accredited facilities bundle accommodation-procedure packages.
Chiang Mai Province
Wellness-integrated medical tourism attracts European and North American retirees seeking post-surgical recovery in cooler highland climates. Thailand's Board of Investment extends tax incentives for hospital infrastructure development outside Bangkok. Chiang Mai Ram Hospital and private clinic networks are expanding orthopedic and rehabilitation capacity to capture secondary-hub demand.
Phuket Province
Beachfront recovery facilities capture medical tourists explicitly combining elective procedures with leisure travel. The Ministry of Public Health coordinates with provincial authorities to license international patient centers in tourism zones. Bangkok Hospital Group's Phuket facility and specialized cosmetic clinics in Patong serve Australian and Russian sourcing markets.
Songkhla Province
Border-proximate dental and ophthalmology clinics serve spontaneous demand from Malaysian patients crossing the Sadao checkpoint. Thailand's Medical Council of Thailand enforces physician licensing standards that Malaysian patients interpret as quality signals. Hat Yai's private hospital cluster competes on package pricing against Singaporean and domestic Malaysian alternatives.
Rayong Province
Industrial estate proximity attracts corporate wellness contracts from Japanese and Korean manufacturing affiliates. Thailand's Board of Investment privileges accelerate greenfield tertiary facility development in Eastern Economic Corridor zones. Private hospital operators are positioning diagnostic and executive health screening services for expatriate management populations.
Thailand Medical Tourism Market Competitive Environment
Player mix skews toward JCI-accredited multi-specialty hospital chains with integrated international patient centers. Consolidation pressure from Ministry-mandated electronic health record interoperability is compressing margins for non-accredited clinic operators. Three archetypes dominate: flagship tertiary hospitals with robotic surgery platforms, cosmetic surgery volume specialists, and network-scale hospital groups with geographic coverage. Competitive moves concentrate on capacity expansion in secondary provinces and telemedicine platform development for pre-arrival patient capture.
Within the flagship tertiary tier, Bumrungrad International Hospital and Bangkok Hospital Group exemplify JCI gold-seal positioning that anchors premium patient flows from Gulf Cooperation Council states. Yanhee International Hospital occupies a specialist position concentrated in cosmetic surgery volume. Phyathai Hospital Group and Samitivej Hospital Group represent network-scale operators expanding across Bangkok's metropolitan catchment. Kasemrad International Rattanathibet Hospital, MedPark Hospital, BNH Hospital, and Mission Hospital sit within the mid-tier accredited segment competing on package pricing transparency.
| Leading Market Players |
|---|
| Phyathai Hospital Group |
| Yanhee International Hospital |
| Bumrungrad International Hospital |
| Kasemrad International Rattanathibet Hospital |
| MedPark Hospital |
| Bangkok Hospital Group (BDMS) |
| BNH Hospital |
| Mission Hospital |
| Samitivej Hospital Group |
| Others |
Value Chain & Pricing Dynamics
Bangkok's 70% patient-volume concentration creates scale economies that compress unit costs for JCI-accredited tertiary facilities while elevating price floors for non-accredited provincial operators. This geographic clustering shapes both procurement leverage for imported surgical equipment and the premium capture available through bundled accommodation-procedure packages.
Pricing Analysis
Cost-plus contracts with medical device distributors typically index to Thai Baht-USD exchange rates and JCI certification tiers. Pricing stratifies across premium, standard, and economy tiers, with JCI gold-seal facilities commanding 40-60% premiums over non-accredited competitors. Cost compression in the standard tier is intensifying because Turkish and South Korean clinics now offer comparable cosmetic surgery accreditation. Regional visitors from Vietnam and Cambodia exhibit highest price sensitivity, while Gulf Cooperation Council patients demonstrate lowest sensitivity due to currency advantages and bundled luxury accommodation expectations.
Supply Chain Analysis
Suvarnabhumi Airport customs clearance and cold-chain logistics chokepoints govern inbound flows of Da Vinci surgical systems and temperature-sensitive biologics. Thailand draws from Germany, Japan, and the USA for precision surgical equipment, while pharmaceutical inputs feed from India and Switzerland. Single-source vulnerability concentrates in robotic surgery platform maintenance contracts held by Intuitive Surgical. Distribution runs through hospital-group procurement consortia that aggregate demand across BDMS and Bumrungrad networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Middle Eastern sourcing markets as telemedicine platforms consolidate patient acquisition channels and eliminate traditional travel-agent intermediaries. This concentration among digitally-enabled patient segments rewards early movers in encrypted consultation infrastructure.
For Market Incumbents: Consolidate through exclusive robotic surgery distribution agreements that lock out regional competitors from Intuitive Surgical's Da Vinci platforms. Defend margin structures by backward integration into wellness-integrated recovery resorts in Chiang Mai and Phuket, offsetting Bangkok's capacity constraints and price inflation pressure.
For New Entrants and Emerging Players: Lead with telemedicine-enabled pre-arrival consultation platforms targeting African and Latin American sourcing markets currently underserved by Bangkok's Arabic and Mandarin-focused patient coordinators. Capture spontaneous demand from Malaysian border-crossers through Hat Yai facilities emphasizing Dental Council of Malaysia reciprocal recognition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hospital groups with deployed robotic surgery platforms and Ministry-mandated electronic health record interoperability. Long-term viability hinges on secondary hub capacity in tax-incentivized provinces. Watch telemedicine regulation evolution as the inflection signal determining whether pre-arrival consultations become regulated revenue streams or competitive cost centers.
| Strategic Initiative | Industry Significance |
|---|---|
| JCI Accreditation Investment | Medical Council of Thailand licensing standards signal quality to Gulf Cooperation Council patients. |
| Robotic Surgery Platform Deployment | Da Vinci systems at BDMS flagship facilities extend treatable cardiovascular case complexity. |
| Telemedicine Infrastructure Buildout | Encrypted pre-arrival platforms displace travel-agent intermediaries for Middle Eastern sourcing markets. |
| Secondary Hub Capacity Expansion | Board of Investment tax incentives accelerate greenfield development in Chiang Mai and Phuket. |
| Package Pricing Transparency | Fixed-price guarantees for cosmetic procedures respond to Vietnamese and Cambodian quote-certainty demands. |
Study Parameters
Operator-level perspectives from international patient center directors, Ministry of Public Health regulatory officials, robotic surgery platform distributors, and Gulf Cooperation Council medical travel coordinators anchored the qualitative base. Secondary validation drew from Medical Council of Thailand licensing records, Joint Commission International accreditation databases, Board of Investment incentive disclosures, and private hospital financial filings. Bottom-up procedure-volume estimates triangulated against top-down Ministry of Public Health medical tourist arrival statistics.
Sensitivity analysis tested forecast robustness across visa-policy scenarios, exchange-rate volatility bands, and regional competitor response intensities. The analytical framework segmented by service type, end-user payment source, technology tier, and pricing model across the projection horizon. CAGRs derived from logistic diffusion curves for robotic surgery adoption and elasticity-adjusted demand functions for cosmetic and dental segments. Procedure complexity thresholds and telemedicine regulatory evolution served as key forecast inputs.
Underlying assumptions cover sustained Medical Hub of Asia policy continuity and JCI accreditation demand stability, with deviation risk concentrated in physician licensing bottleneck resolution and ASEAN competitor pricing aggression. Practitioners should keep alternative scenarios live as telemedicine regulations and Gulf currency pegs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
South Korea Medical Tourism Market
Medical Tourism
Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
Malaysia Medical Tourism Market