
 Canada Animal Protein Market | 2026-2036
Canada Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Animal Protein Market Outlook
Asset-light contract processing and third-party logistics leasing is reconfiguring capital deployment across the Canada animal protein sector. Saputo Inc. leverages its Quebec dairy network to sustain fluid milk and cheese dominance in Central Canada. Cooke Inc. anchors Atlantic Canada through vertically integrated aquaculture operations spanning hatcheries to distribution. Kerry Group PLC differentiates via specialized protein ingredient systems supplied to domestic food manufacturers.
Canada animal protein encompasses muscle tissue, collagen, and derived isolates from livestock and aquaculture species, processed to minimum protein thresholds for human nutrition and industrial formulation. Poultry leads volume due to shorter production cycles and lower feed conversion ratios, while beef commands premium positioning in retail and foodservice channels. Seafood from Cooke Inc. and allied processors occupies a fast-growing niche driven by export demand and domestic per-capita consumption shifts toward whitefish and shellfish.
Health Canada enforces the Safe Food for Canadians Regulations mandating preventive controls and lot traceability, while the Canadian Food Inspection Agency administers grading standards that shape processor compliance costs and market access. The Canadian Agricultural Partnership funds facility modernization, indirectly steering consolidation toward larger federally inspected plants. Stakeholders must monitor evolving CFIA enforcement priorities and provincial environmental permitting for intensive livestock operations.
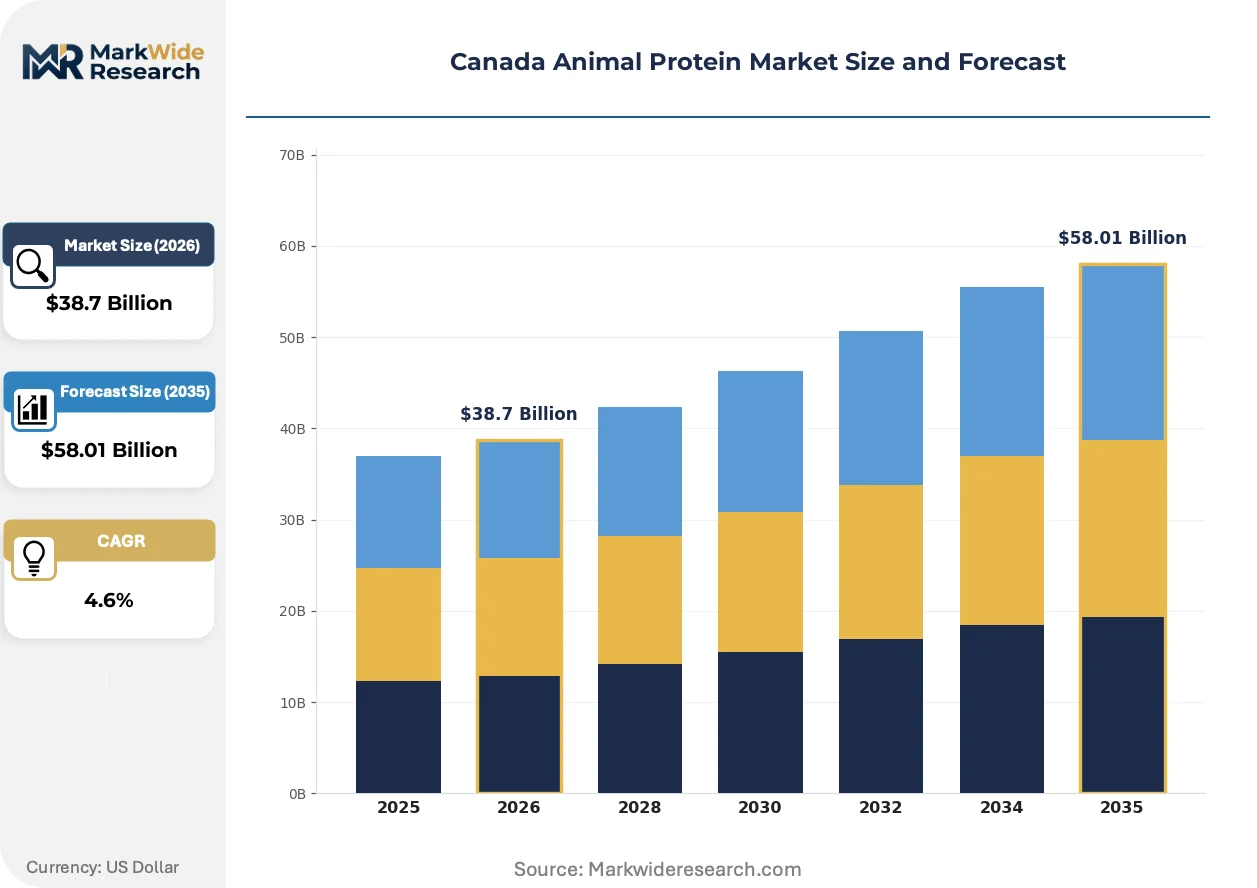
Market Dynamics
Health Canada's Safe Food for Canadians Regulations are compressing processing timelines while forcing capital redeployment toward federally inspected facilities, reshaping competitive advantage around traceability infrastructure rather than scale alone.
Growth Catalysts
- Canadian Agricultural Partnership funding:Facility modernization grants accelerate consolidation into larger plants, steering investment toward Alberta's integrated cattle corridor and Quebec's dairy processing networks.
- Premium beef positioning:Retail and foodservice channels reward grade-verified product, pulling investment toward grading infrastructure and cold-chain integrity.
- Cell-cultured protein R&D:Alternative protein technologies are attracting federal innovation credits, creating parallel capacity development alongside conventional livestock systems.
Market Restraints
- Feed grain price volatility:Prairie drought cycles and international corn markets transmit directly into Alberta feedlot margins, compressing processor procurement flexibility.
- CFIA inspection capacity constraints:Federally inspected plant certification backlogs limit expansion timelines for mid-scale Ontario and Quebec processors seeking export eligibility.
- Plant-based substitution:Pea and soy protein isolates are capturing foodservice formulation share, pressuring commodity poultry and pork volume growth.
Strategic Opportunities
- Atlantic Canada aquaculture expansion:Cooke Inc.'s vertically integrated model demonstrates scalable whitefish and shellfish production for export-oriented growth.
- Value-added processed meats:Ontario and Quebec processors are capturing margin expansion through ready-to-cook and ethnic product lines for domestic retail.
- Carbon credit monetization:Alberta's cattle feeding operations are accessing provincial offset protocols, converting methane reduction into revenue streams.
Industry Challenges
- Veterinary epidemiology expertise scarcity:African swine fever preparedness and avian influenza response protocols demand specialized talent that federal and provincial agencies compete to retain.
- Legacy traceability system integration:Small-scale British Columbia and Prairie processors face capex burdens to retrofit lot-tracking software compliant with Safe Food for Canadians Regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Animal Protein Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry, Beef, Pork, Seafood End User: Restaurants, Retailers, Food Processors, Households Distribution Channel: Direct Sales, e-Commerce, Wholesalers, Supermarkets Packaging Type: Bulk Packaging, Vacuum Packaging, Tray Packaging, Canned |
| Companies Covered | Agropur Dairy Cooperative, Saputo Inc., Glanbia PLC, Arla Foods amba, Fonterra Co-operative Group Limited, Kerry Group PLC, Groupe Lactalis, Ajinomoto Co. Inc., Cooke Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Animal Protein Market Strategic Shifts
Digital infrastructure and alternative protein technologies are compressing traditional production cycles while regulatory enforcement tightens around preventive controls, forcing simultaneous investment in compliance and innovation.
Blockchain-enabled supply chain verification is virtualizing lot-tracking documentation across federally inspected beef and poultry plants. Major retailers are mandating immutable origin records for private-label protein lines. This technology is virtualizing audit costs while compressing recall response timelines from days to hours.
Health Canada's updated Safe Food for Canadians Regulations mandate preventive control plans with documented hazard analysis for all licensed facilities. Compliance costs are diverting capital from production expansion toward quality management infrastructure. Smaller provincially inspected plants in Manitoba and Saskatchewan are exiting rather than absorbing federal upgrade requirements.
Foodservice procurement teams are consolidating supplier relationships around vertically integrated partners capable of delivering specification-grade product with embedded traceability. Broadline distributors are de-listing fragmented commodity suppliers lacking lot-level documentation. Ontario's institutional feeding sector exhibits the most aggressive consolidation, with hospital and university systems reducing approved vendor lists by half.
Canada Animal Protein Market Segmentation
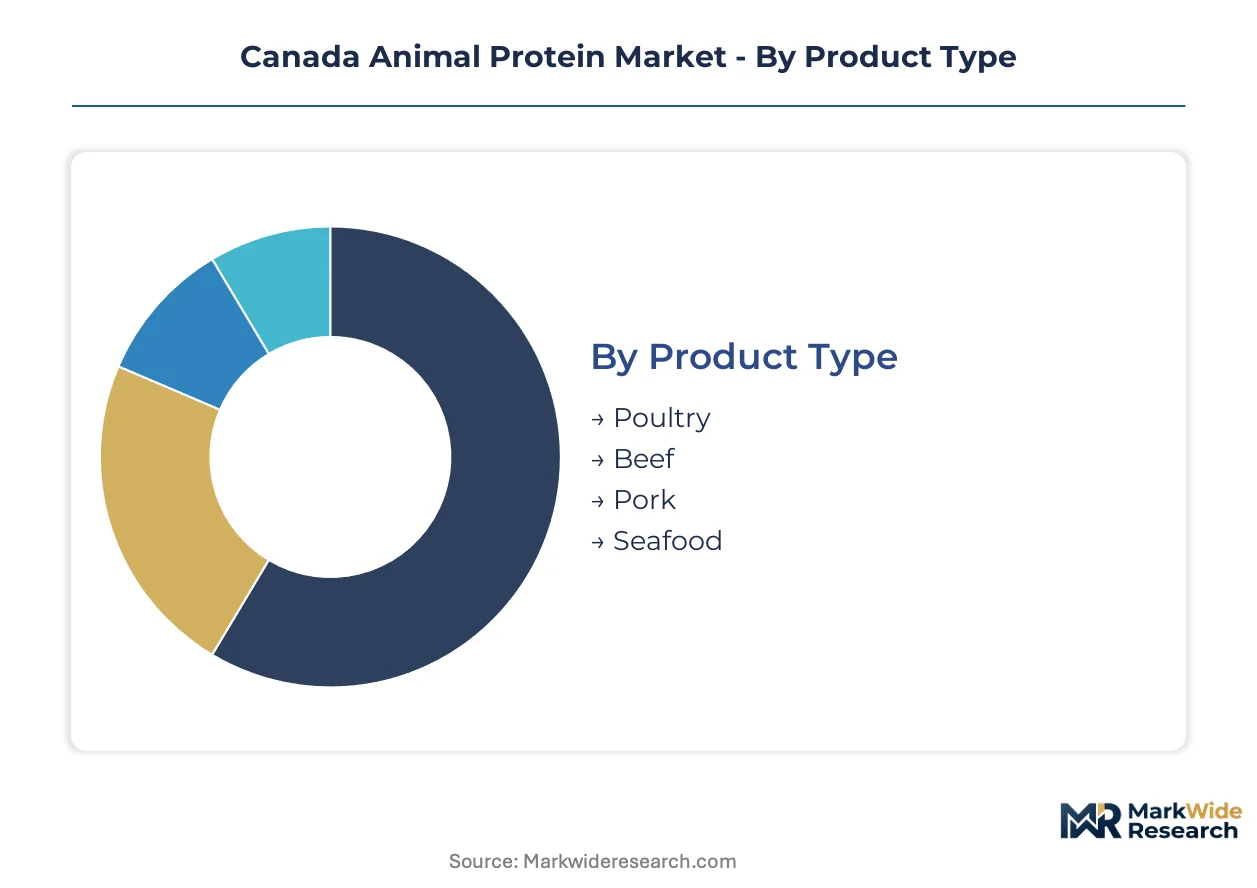
Segmentation reveals how protein flows diverge across Canadian supply chains. Product type determines regulatory pathway and margin structure, while end-user concentration shapes regional processing investments and cold-chain infrastructure deployment.
Product Type:
After-sales service intensity varies sharply across protein categories, with beef requiring grading arbitration and cold-chain remediation while poultry demands rapid shelf-life intervention.
- Poultry:Short production cycles and superior feed conversion ratios make this the volume anchor. Demand clusters in Ontario and Quebec processing corridors where Health Canada's preventive control mandates compress margins but lock in retail access.
- Beef:Premium grade-verified product commands sustained retail and foodservice loyalty. Alberta's integrated feeding and processing corridor concentrates investment, with CFIA grading infrastructure determining market eligibility.
- Pork:Mid-tier positioning between poultry efficiency and beef premiums. Prairie production faces feed cost volatility and African swine fever preparedness costs.
- Seafood:Atlantic Canada's vertically integrated aquaculture operations supply export-oriented whitefish and shellfish. Cooke Inc.'s hatchery-to-distribution model demonstrates scalable traceability compliance.
By volume, poultry leads. By growth pace, seafood is ahead.
End User:
Cost tier stratification separates commodity procurement from specification-grade relationships, with foodservice operators paying premiums for embedded traceability.
- Restaurants:Broadline distributors consolidate supplier lists around vertically integrated partners. Ontario's institutional feeding sector—hospitals and universities—exhibits the most aggressive vendor reduction.
- Retailers:Private-label protein lines now mandate blockchain-enabled origin documentation. Major chains are de-listing fragmented commodity suppliers lacking lot-level records.
- Food Processors:Value-added meat expansion concentrates in Ontario and Quebec, with processors capturing margin through ready-to-cook and ethnic product lines.
- Households:Direct and e-commerce channels accelerated post-pandemic, though supermarkets retain dominant share for fresh protein.
By transaction volume, retailers dominate. By margin expansion, food processors are climbing the fastest.
Distribution Channel:
Geographic reach determines channel viability, with remote households and Atlantic seafood exports requiring differentiated logistics models.
- Direct Sales:Alberta cattle feeders and Atlantic aquaculture operations use direct contracts to secure grade premiums and export eligibility. Bypassing intermediaries demands internal traceability infrastructure.
- e-Commerce:Frozen and value-added products suit last-mile delivery, though fresh protein remains limited by cold-chain cost and CFIA inspection timing.
- Wholesalers:Traditional broadline distribution faces consolidation pressure as retailers and foodservice operators reduce approved vendor lists.
- Supermarkets:Central Canada chains leverage Quebec dairy networks and Ontario poultry processing for private-label dominance.
By revenue concentration, supermarkets lead. By channel transformation speed, e-commerce is gaining share fastest.
Packaging Type:
Margin structure separates shelf-life extension technologies from commodity bulk formats, with vacuum and modified-atmosphere systems commanding equipment investment.
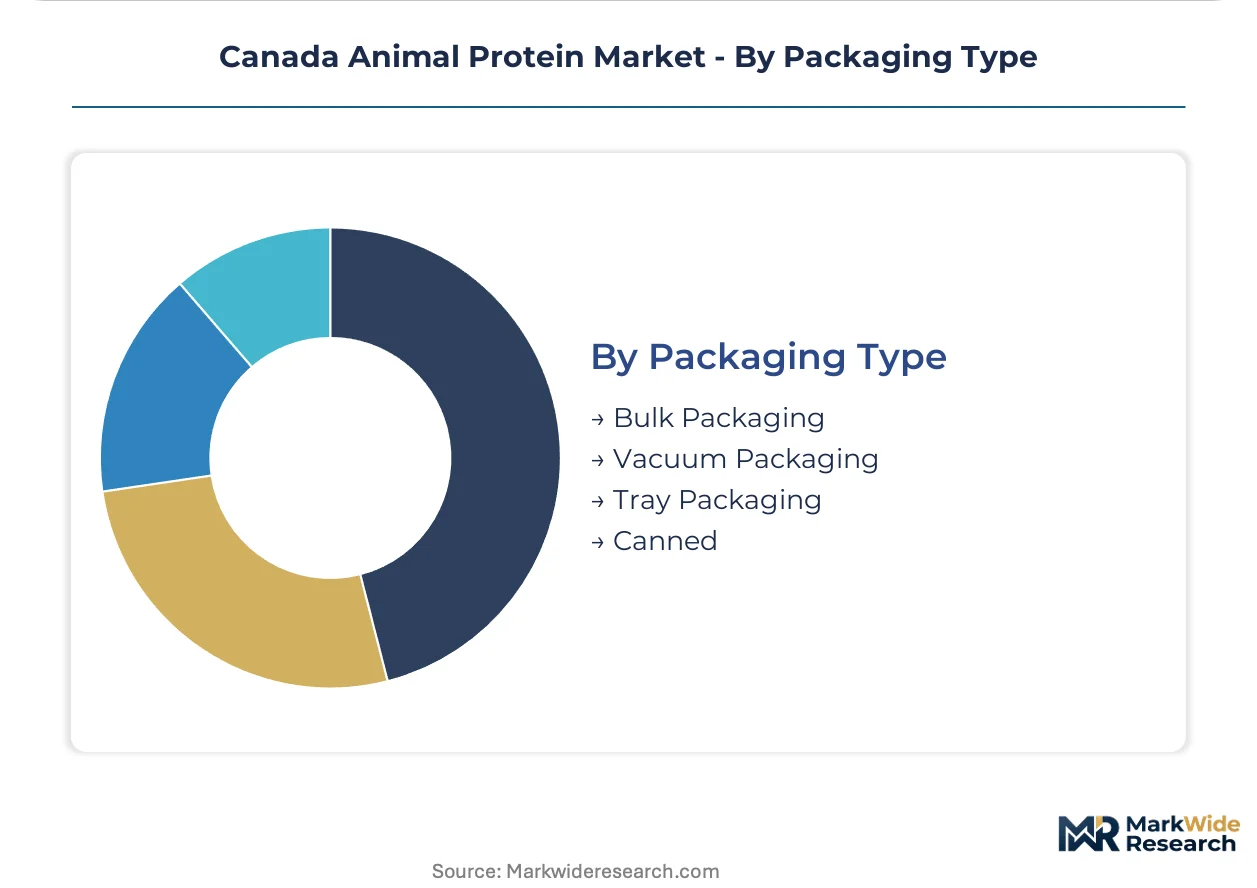
- Bulk Packaging:Food processors and institutional buyers favor this format for cost efficiency. Alberta feedlot direct sales and Quebec dairy ingredient shipments rely on bulk logistics.
- Vacuum Packaging:Retail-ready premium cuts and export-oriented seafood use this technology to extend shelf life and satisfy CFIA lot-traceability requirements.
- Tray Packaging:Standard for fresh retail display, with modified-atmosphere variants capturing premium positioning in Ontario and Quebec urban markets.
- Canned:Niche preservation for seafood and specialty meats, with limited growth relative to fresh and frozen alternatives.
By unit volume, tray packaging leads. By technology upgrade intensity, vacuum packaging shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice procurement teams and retail buyers concentrate demand in three provinces, while export-oriented aquaculture operations anchor Atlantic capacity. Health Canada regulations and provincial environmental permitting shape facility investment across sub-regional corridors.
Ontario
Institutional feeding systems and urban retail chains drive poultry and value-added meat procurement. Health Canada's Safe Food for Canadians Regulations compress processing timelines for Toronto-area plants. The Golden Horseshoe corridor hosts federally inspected facilities expanding ready-to-cook production lines.
Quebec
Dairy processing networks and ethnic food manufacturers sustain fluid milk and cheese demand. The Canadian Agricultural Partnership funds facility modernization grants steering consolidation toward larger plants. Montreal and surrounding regions concentrate dairy protein extraction and ingredient manufacturing capacity.
Alberta
Integrated cattle feeding operations and beef grading infrastructure command premium positioning in retail and foodservice channels. Provincial carbon offset protocols enable methane reduction monetization for feedlot operators. The Calgary-Edmonton corridor anchors federally inspected beef processing and cold-chain distribution.
British Columbia
Seafood processing and niche livestock operations serve Pacific export markets and domestic specialty retail. Provincial environmental permitting for intensive livestock operations limits expansion timelines. Vancouver and coastal regions concentrate aquaculture technology development and alternative protein R&D facilities.
Atlantic Canada
Vertically integrated aquaculture operations supply export-oriented whitefish and shellfish to international markets. Cooke Inc.'s hatchery-to-distribution model demonstrates scalable traceability compliance. New Brunswick and Nova Scotia host marine protein processing clusters serving European and Asian buyers.
Canada Animal Protein Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement tiers, creating a bifurcated structure where scale-driven consolidators face agile regional processors. The vendor base organizes around three archetypes: dairy-dominant cooperatives with captive milk supply, vertically integrated aquaculture operators controlling hatchery-to-retail chains, and ingredient-system suppliers embedding traceability into food processor formulations. Dominant competitive moves include backward integration into feed and genetics operations, plus strategic partnerships with retailers mandating blockchain-enabled origin documentation.
Among Canada-based dairy and protein processors, Saputo Inc., Agropur Dairy Cooperative, and Cooke Inc. occupy distinct archetype positions. Saputo represents the scale-driven consolidator leveraging Quebec network density for fluid milk and cheese dominance. Agropur exemplifies the cooperative structure with farmer-owned supply integration. Cooke anchors the vertically integrated aquaculture archetype spanning Atlantic Canada operations. Kerry Group PLC and Glanbia PLC sit within the ingredient-system supplier tier, serving domestic food manufacturers with specialized protein isolates and nutritional formulations. These five entities collectively illustrate the competitive spectrum from raw material control through value-added formulation.
| Leading Market Players |
|---|
| Agropur Dairy Cooperative |
| Saputo Inc. |
| Glanbia PLC |
| Arla Foods amba |
| Fonterra Co-operative Group Limited |
| Kerry Group PLC |
| Groupe Lactalis |
| Ajinomoto Co. Inc. |
| Cooke Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Alberta's federally inspected beef plants is compressing processor margins while amplifying pricing power for integrated cattle feeders with captive cold-chain infrastructure. This utilization squeeze feeds directly into procurement strategies across Ontario and Quebec foodservice channels.
Pricing Analysis
Certification level under Safe Food for Canadians Regulations creates the primary spread between commodity and specification-grade product. Three-tier pricing structure across premium, standard, and economy levels dominates, with CFIA grading verification and embedded traceability as the key differentiation drivers. Cost compression in mid-tier pork and poultry is intensifying because pea and soy protein isolates capture formulation share in foodservice channels. Institutional buyers exhibit highest price sensitivity, while retailers with private-label programs absorb premiums for blockchain-enabled origin documentation.
Supply Chain Analysis
Prairie feed grain sourcing and Atlantic hatchery operations anchor upstream supply for Alberta cattle feeders and Cooke Inc.'s aquaculture network. The supply chain draws from domestic barley and corn production, imported soybean meal, and marine feed formulations for Atlantic operations. Single-source vulnerability concentrates in CFIA-inspected plant capacity, where certification backlogs limit processor expansion. Distribution runs through vertically integrated cold-chain networks controlled by major retailers and broadline foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary epidemiology expertise and preventive control plan implementation capacity are scarce assets that determine facility licensing velocity and margin capture across the Canadian animal protein sector.
For Market Incumbents: Insulate grade-verified beef positioning through backward integration into Alberta feeding operations and genetics programs. Lock in retail access by embedding blockchain traceability ahead of CFIA mandate expansion. Channel consolidation by broadline distributors threatens commodity poultry suppliers lacking lot-level documentation infrastructure. For New Entrants and Emerging Players: Build out value-added processed meat capacity in Ontario's Golden Horseshoe corridor, where ethnic product lines and ready-to-cook formats face limited specialized competition. Direct-to-institutional channels for specification-grade seafood offer the most penetrable entry point. Lead with embedded traceability compliance as the go-to-market differentiator against legacy provincially inspected plants. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated aquaculture operators with hatchery-to-distribution control and long-term export contracts. Five-to-ten-year viability favors asset-light contract processors with multi-species flexibility and leased cold-chain access. Monitor CFIA inspection capacity expansion announcements as the inflection signal for mid-scale processor valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Control Plan Investment | CFIA compliance infrastructure secures retail access and export eligibility for federally inspected plants. |
| Blockchain Traceability Deployment | Immutable lot-tracking satisfies major retailer private-label mandates and compresses recall response timelines. |
| Backward Integration into Feed Operations | Captive grain sourcing insulates Alberta cattle feeders from Prairie drought cycle volatility. |
| Value-Added Product Line Expansion | Ready-to-cook and ethnic formats capture margin expansion in Ontario and Quebec retail channels. |
| Atlantic Aquaculture Capacity Buildout | Vertically integrated whitefish and shellfish production serves European and Asian export demand growth. |
Study Parameters
A spread of perspectives from beef processing executives, CFIA regulatory affairs leads, foodservice procurement directors, and Prairie feedlot operators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through Canadian Food Inspection Agency enforcement bulletins, Health Canada regulatory filings, Canadian Agricultural Partnership disbursement records, and provincial environmental permit databases. Bottom-up facility capacity assessments and top-down protein flow estimates were triangulated against trade data and retail scanner information.
Demand-supply balance modeling across the projection horizon incorporated segmentation by protein species, end-user channel, and provincial regulatory cluster. CAGRs were derived from volume trajectory analysis and value-per-unit expansion assumptions. Forecast inputs included feed grain price correlation models, CFIA inspection capacity buildout schedules, and alternative protein substitution elasticities in foodservice formulation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cell-cultured protein ventures or accelerated plant-based substitution would shift outcomes. Cross-checking against Canadian cattle on-feed statistics and Atlantic aquaculture landing reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Compound Horse Feedstuff Market
Agriculture and Agri Products
Asia-Pacific Artificial Humus Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
Organic Farming Market
Agriculture and Agri Products
North America Aloe Vera Market
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Corn Co-Products Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
Netherlands Commercial Greenhouse Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
United States Alfalfa Market