
 Boswellia Market | 2026-2036
Boswellia Market Size, Share, and Industry Trends Forecast 2026-2036
Boswellia Market Outlook
Curcumin is expanding its displacement of synthetic NSAIDs in joint-health formulations, compressing pricing power for competing botanicals and forcing boswellia suppliers to emphasize unique anti-inflammatory mechanisms. Sabinsa Corporation leverages its integrated supply chain from Indian raw material to US finished extracts. PLT Health Solutions sustains clinical validation programs that differentiate its branded ingredients in practitioner channels. Arjuna Natural anchors South Indian production with solvent-free extraction infrastructure.
Boswellia comprises the oleo-gum-resin of Boswellia serrata and related species, yielding 30-60% boswellic acids including the pharmacologically active AKBA (acetyl-11-keto-β-boswellic acid) fraction through hydroalcoholic or supercritical CO₂ extraction for anti-inflammatory, anti-arthritic, and immunomodulatory applications. Resin extract dominates value generation due to standardization requirements for pharmaceutical and nutraceutical clients, while essential oil captures aromatherapy premiums through terpene-rich fractions. Capsule formulations represent the fastest-growing finished-delivery format as direct-to-consumer brands bypass traditional practitioner channels.
India's CDSCO mandates quality standards for herbal APIs under the Drugs and Cosmetics Act, while the US FDA exercises enforcement discretion over dietary supplement claims through Warning Letters targeting anti-inflammatory disease claims. The European Medicines Agency's herbal monograph for Boswellia serrata establishes pharmacopeial benchmarks that determine EU market access for concentrated extracts. Stakeholders must monitor evolving pharmacovigilance requirements in Germany and France where boswellia-containing products face reclassification pressures between food supplement and traditional herbal medicine frameworks.
Market Dynamics
India's PLI scheme for herbal products is redirecting capital toward domestic extraction capacity, compressing margins for traders dependent on fragmented raw material sourcing while rewarding vertically integrated processors with standardized boswellic acid output.
Growth Catalysts
- CDSCO herbal API standards:India's Drugs and Cosmetics Act mandates quality benchmarks that legitimize boswellia extracts for pharmaceutical formulators, accelerating substitution of synthetic NSAIDs in anti-inflammatory therapeutics.
- Solvent-free supercritical CO₂ extraction:This technology preserves terpene integrity and AKBA potency, enabling premium positioning in practitioner-grade nutraceutical channels that demand pharmacopeial-grade standardization.
- Gujarat-Rajasthan processing clusters:Geographic concentration of resin tapping and primary processing infrastructure creates captive supply security for extractors serving European and North American finished-product manufacturers.
Market Restraints
- Wild-harvested resin supply volatility:Boswellia serrata trees in Gujarat and Rajasthan face cyclical yield fluctuations from monsoon dependency, forcing extractors to maintain 8-12 month raw material inventories.
- EMA herbal monograph compliance costs:European pharmacopeial benchmarks require HPLC-standardized AKBA content above 30%, disqualifying unstandardized gum-resin traders from EU pharmaceutical supply chains.
- Curcumin displacement pressure:Turmeric-derived anti-inflammatory formulations capture shelf space in joint-health categories, forcing boswellia suppliers to differentiate through unique 5-LOX inhibition mechanisms.
Strategic Opportunities
- US direct-to-consumer capsule channels:E-commerce subscription models bypass traditional practitioner networks, enabling branded ingredient suppliers to capture margin previously allocated to clinical gatekeepers.
- Essential oil aromatherapy premiumization:Terpene-rich fractions from hydrodistillation capture wellness segment pricing power distinct from pharmaceutical-grade boswellic acid markets.
- FSSAI functional food integration:India's food safety regulator permits boswellia in specified health beverages, opening formulation partnerships with domestic beverage manufacturers targeting inflammation-conscious consumers.
Industry Challenges
- Phytochemical standardization expertise gap:Analytical chemists capable of validating AKBA, KBA, and total boswellic acid profiles command premium salaries, constraining mid-scale extractor capacity expansion.
- Batch-to-batch resin quality variance:Wild harvesting practices across Gujarat and Rajasthan produce inconsistent gum-resin composition, requiring preprocessing investments that erode processor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boswellia Market |
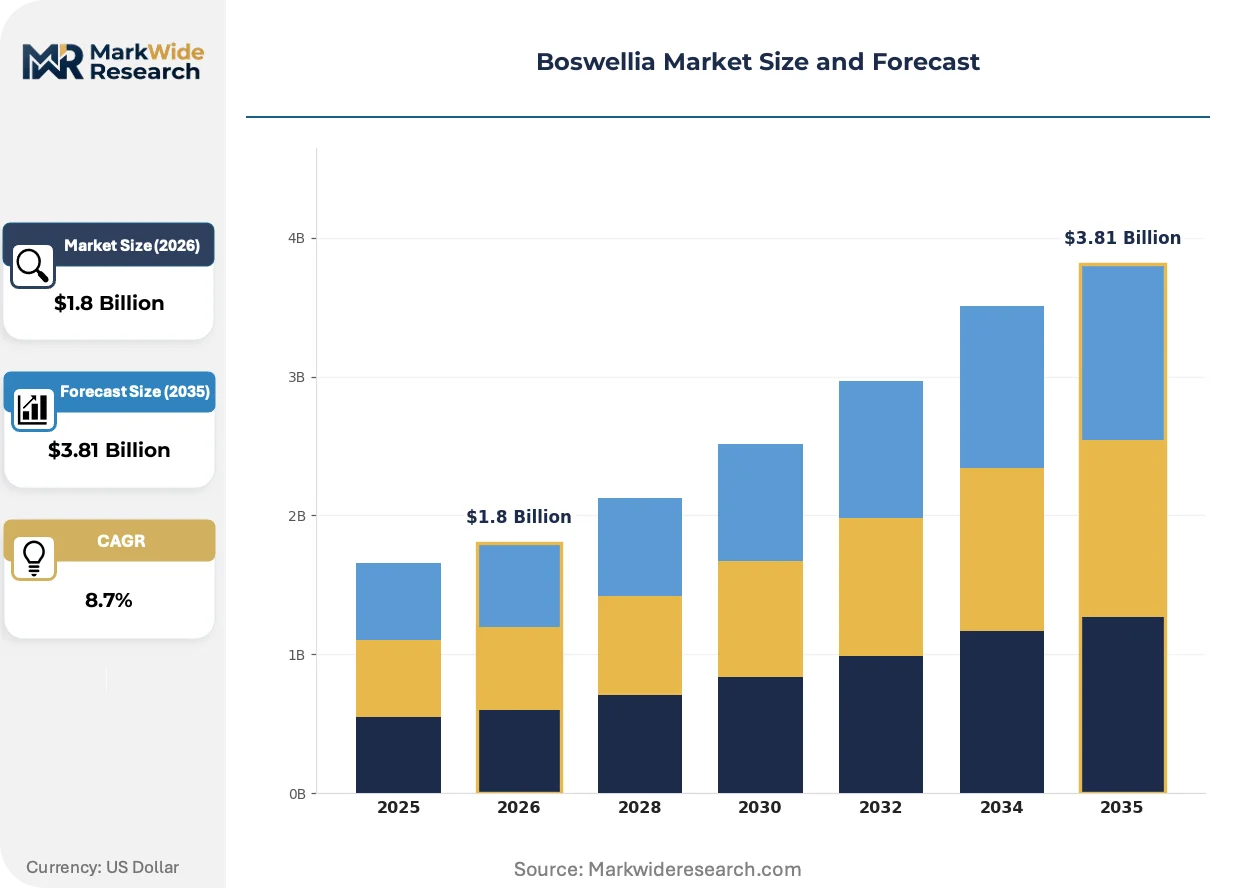
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin Extract, Essential Oil, Powder, Capsules Application: Nutraceuticals, Pharmaceuticals, Cosmetics, Aromatherapy End User: Healthcare Providers, Retail Consumers, Manufacturers, Researchers Distribution Channel: Online Retail, Pharmacies, Health Stores, Supermarkets |
| Companies Covered | Sabinsa Corporation, PLT Health Solutions, Arjuna Natural Pvt Ltd, Alchem International Pvt Ltd, Verdure Sciences, Nutra Green Biotechnology Co., Ltd., Gurjar Phytochem Pvt. Ltd., S.A. Herbal Bioactives LLP, NOW Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boswellia Market Strategic Shifts
Extraction technology maturation and regulatory pharmacopeial convergence are compressing the competitive window for unstandardized traders while rewarding integrated processors with clinical validation capabilities.
Supercritical CO₂ extraction is converging with hydroalcoholic fractionation to produce dual-standardized outputs that simultaneously meet EMA monograph specifications for boswellic acids and terpene profiles demanded by aromatherapy formulators. European botanical extractors are adopting these hybrid systems at pilot scale, enabling single-facility production of both pharmaceutical-grade AKBA concentrates and wellness-oriented essential oil fractions. This technical fusion is collapsing the historical separation between medicinal and cosmetic supply chains, forcing traditional gum-resin traders to upgrade analytical capabilities or exit premium segments.
REACH registration requirements for imported herbal substances are tightening documentary evidence for boswellia resin entering EU cosmetic and pharmaceutical value chains. The European Chemicals Agency's evolving substance evaluation protocols now demand full supply chain traceability from Indian tapping cooperatives through to finished extract, disqualifying multi-layered trading networks. German and French formulators are responding by contracting directly with Rajasthan-based processors holding solvent-free extraction certifications, bypassing Mumbai trading houses that previously intermediated European supply.
Practitioner channel consolidation is compressing the traditional clinical gatekeeper model that historically distributed standardized extracts. North American integrative medicine clinics are consolidating purchasing through group purchasing organizations, extracting volume discounts from branded ingredient suppliers that previously commanded premium pricing through individual practitioner relationships. This concentration is most visible in California and New York metropolitan markets, where clinic networks now specify AKBA standardization thresholds in collective procurement contracts that smaller extractors cannot meet.
Boswellia Market Segmentation
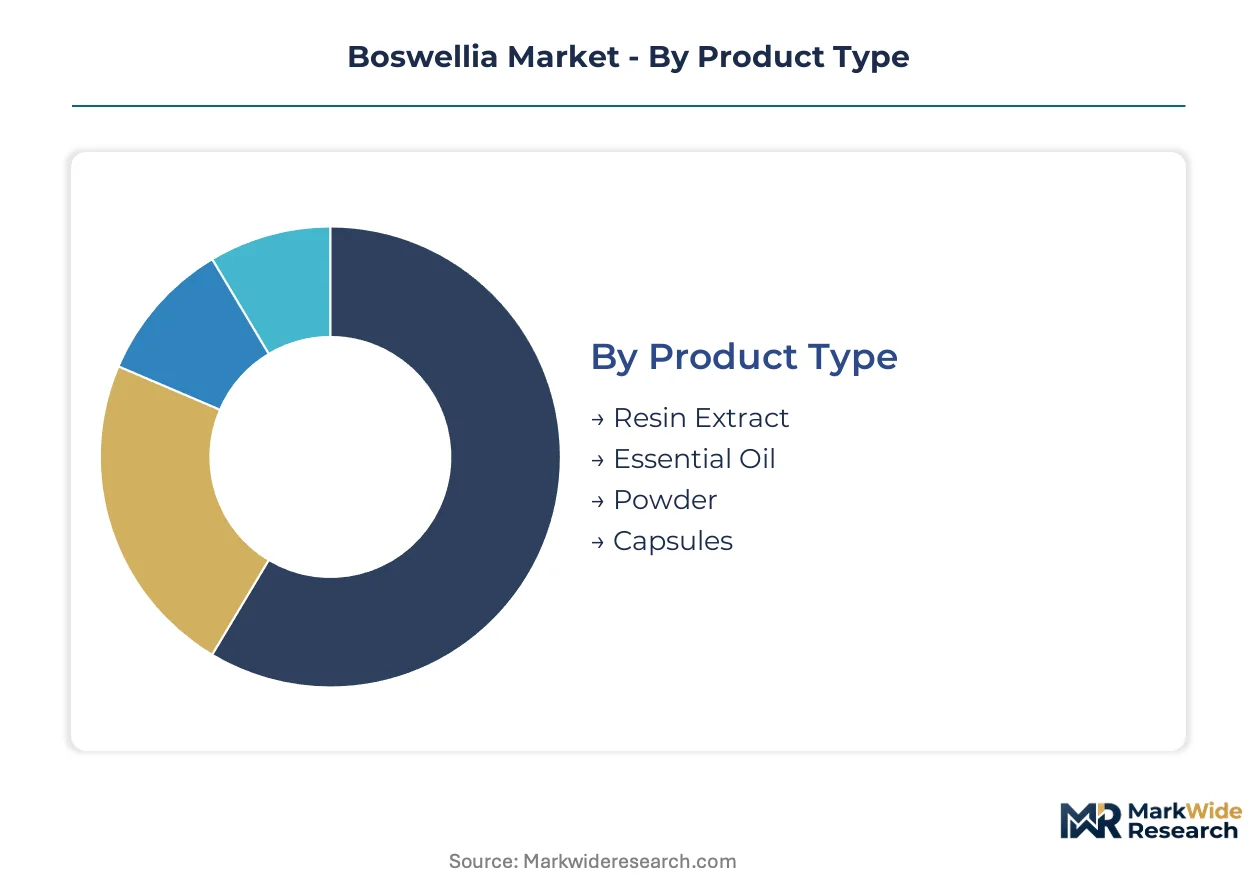
Segmentation in the boswellia market reveals how regulatory complexity and extraction technology create divergent margin structures across product formats. Each category demands distinct certification pathways that determine market access and pricing power.
Product Type:
EMA herbal monograph compliance separates pharmaceutical-grade segments from wellness-oriented formats, with CDSCO API standards further stratifying Indian domestic supply.
- Resin Extract:Hydroalcoholic or supercritical CO₂ extraction yields standardized boswellic acid concentrates between 30-60% AKBA content. Pharmaceutical formulators in Germany and France specify EMA-compliant resin extracts for anti-inflammatory therapeutics, with batch-to-batch HPLC validation mandatory for EU market access.
- Essential Oil:Hydrodistillation captures terpene-rich fractions including α-pinene, limonene, and myrcene for aromatherapy applications. French and German wellness brands command premium positioning through organic certification and GC-MS phytochemical profiling that traces to Rajasthan tapping cooperatives.
- Powder:Raw gum-resin milling produces unstandardized material for traditional Ayurvedic practitioners and bulk ingredient traders.
- Capsules:Direct-to-consumer brands in the US bypass practitioner channels through e-commerce subscription models with specified AKBA standardization.
Resin extract sits at the top of the volume ranking, with capsules climbing the fastest.
Application:
End-use concentration determines whether segments compete on clinical validation or wellness positioning, with pharmaceutical applications demanding the steepest regulatory investment.
- Nutraceuticals:Dietary supplement formulations require FDA enforcement discretion compliance for structure-function claims, with Warning Letter risk elevating legal review costs for anti-inflammatory positioning. US direct-to-consumer brands drive formulation innovation through capsule and soft-gel delivery systems.
- Pharmaceuticals:CDSCO-registered herbal APIs under India's Drugs and Cosmetics Act enable prescription-grade boswellic acid formulations for osteoarthritis and inflammatory bowel disease. German and Italian formulators source EMA-monograph-compliant extracts for traditional herbal medicine registrations.
- Cosmetics:REACH-registered boswellia resin enters EU cosmetic value chains through German and French formulators demanding full supply chain traceability from Indian tapping cooperatives.
- Aromatherapy:Terpene-profile standardization through GC-MS analysis supports wellness segment pricing distinct from pharmaceutical boswellic acid markets.
Pharmaceuticals capture the highest margin per kilogram, though nutraceuticals are expanding most quickly.
End User:
Procurement concentration among consolidated buyers is compressing traditional margin structures for smaller extractors unable to meet collective contract specifications.
- Healthcare Providers:North American integrative medicine clinics in California and New York metropolitan markets consolidate purchasing through group purchasing organizations specifying AKBA thresholds above 30%.
- Retail Consumers:E-commerce subscription models enable branded ingredient suppliers to capture margin previously allocated to clinical gatekeepers through direct capsule and soft-gel sales.
- Manufacturers:European finished-product manufacturers contract directly with Rajasthan-based processors holding solvent-free extraction certifications, bypassing Mumbai trading houses.
- Researchers:Academic and clinical trial sponsors demand certified reference materials with validated AKBA, KBA, and total boswellic acid profiles for pharmacokinetic studies.
Manufacturers dominate procurement volume, with retail consumers gaining share fastest.
Distribution Channel:
Channel selection determines whether suppliers capture practitioner-grade premiums or compete on convenience and subscription retention metrics.
- Online Retail:Amazon and direct-to-consumer brand sites bypass traditional practitioner networks, enabling AKBA-standardized capsule subscriptions with automated replenishment.
- Pharmacies:German and French pharmacy chains stock EMA-registered traditional herbal medicines requiring pharmacist consultation, preserving premium pricing through professional gatekeeping.
- Health Stores:US specialty retailers like Whole Foods and Sprouts emphasize organic and non-GMO certifications for wellness-positioned boswellia powders and capsules.
- Supermarkets:India's FSSAI-permitted functional food integrations place boswellia in specified health beverages through domestic beverage manufacturer partnerships.
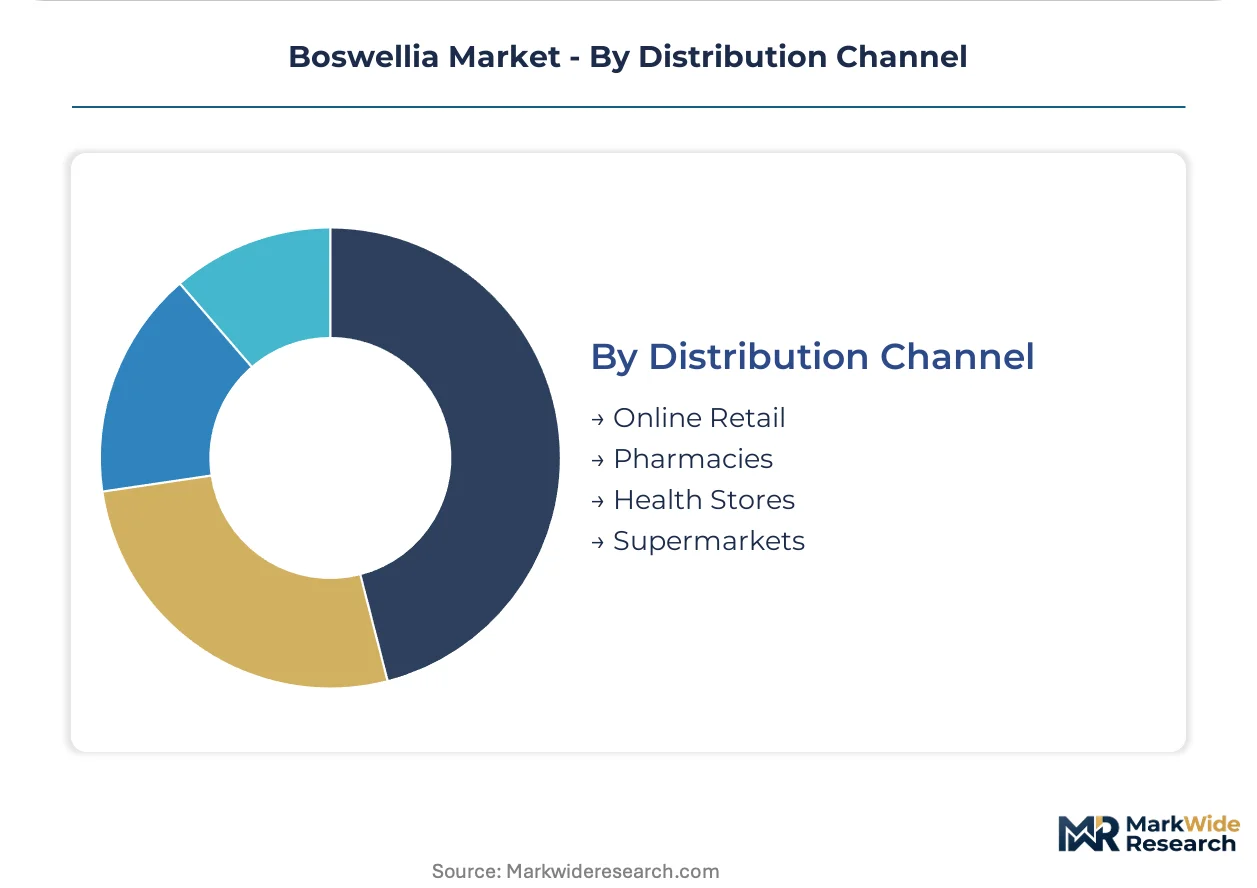
Pharmacies maintain the highest margin per transaction, while online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat and Rajasthan processing clusters supply the majority of global raw material, with India's PLI scheme redirecting investment toward domestic extraction capacity. European and North American markets depend on standardized extracts from these Indian supply bases.
India
Domestic pharmaceutical formulators drive demand for CDSCO-registered herbal APIs under the Drugs and Cosmetics Act. The PLI scheme for herbal products and active pharmaceutical ingredients channels capital toward captive extraction infrastructure. Gujarat and Rajasthan clusters concentrate resin tapping and primary processing, with solvent-free supercritical CO₂ extraction facilities expanding in Ahmedabad and Jodhpur.
Germany
Traditional herbal medicine manufacturers source EMA-monograph-compliant boswellia extracts for osteoarthritis formulations. REACH registration requirements tighten documentary evidence for imported resin, forcing direct contracting with Rajasthan processors. Bavaria-based formulators lead EU pharmacopeial-grade procurement, bypassing Mumbai trading houses that previously intermediated supply.
United States
Direct-to-consumer brands bypass practitioner networks through e-commerce subscription models for AKBA-standardized capsules. FDA enforcement discretion over dietary supplement claims elevates legal review costs for anti-inflammatory positioning. California and New York metropolitan integrative medicine clinics consolidate purchasing through group purchasing organizations.
France
Pharmacy chains stock EMA-registered traditional herbal medicines requiring pharmacist consultation. ANSM pharmacovigilance requirements create reclassification pressures between food supplement and traditional herbal medicine frameworks. Provence-Alpes-Côte d'Azur wellness brands command premium positioning through organic certification and GC-MS phytochemical profiling.
China
Traditional medicine practitioners incorporate boswellia into anti-arthritic formulations alongside domestic botanicals. NMPA herbal medicine standards influence import specifications for Indian resin extracts. Yangtze River Delta processing hubs evaluate supercritical CO₂ extraction technology for terpene preservation.
Boswellia Market Competitive Environment
Global majors compete with regional champions across extraction technology and regulatory certification dimensions. The vendor base stratifies between vertically integrated processors with captive Indian supply and trading-dependent formulators vulnerable to raw material volatility. Three archetypes dominate: integrated extractors with Rajasthan-Gujarat infrastructure, clinical validation specialists serving practitioner channels, and direct-to-consumer branded ingredient suppliers. Competitive moves concentrate on solvent-free extraction certifications and EMA monograph compliance investments.
Among India-based integrated processors, Sabinsa Corporation, Arjuna Natural Pvt Ltd, and Alchem International Pvt Ltd occupy positions spanning raw material control through finished extract output. These entities exemplify the vertically integrated archetype, with geographic naming conventions indicating subcontinental operational bases. US-headquartered PLT Health Solutions and Verdure Sciences represent the clinical validation specialist tier, while Nutra Green Biotechnology Co., Ltd. anchors Chinese sourcing capabilities. Gurjar Phytochem Pvt. Ltd. and S.A. Herbal Bioactives LLP sit within the mid-scale Rajasthan-Gujarat processing segment.
| Leading Market Players |
|---|
| Sabinsa Corporation |
| PLT Health Solutions |
| Arjuna Natural Pvt Ltd |
| Alchem International Pvt Ltd |
| Verdure Sciences |
| Nutra Green Biotechnology Co., Ltd. |
| Gurjar Phytochem Pvt. Ltd. |
| S.A. Herbal Bioactives LLP |
| NOW Foods |
| Others |
Value Chain & Pricing Dynamics
EMA-monograph-compliant procurement specifications from German and French pharmaceutical formulators force extractors to invest in HPLC-standardized AKBA validation, compressing margins for unstandardized traders while rewarding integrated processors with pricing power tied to certification tier.
Pricing Analysis
Raw resin inventory costs pass through directly to extract pricing, with wild-harvested supply volatility in Gujarat and Rajasthan driving 8-12 month stockholding requirements that elevate working capital burdens. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and bulk gum-resin levels reflects AKBA concentration and EMA compliance status. Cost compression in mid-tier nutraceutical segments intensifies because curcumin displacement pressure forces boswellia suppliers to compete on mechanism differentiation. Contract manufacturers demonstrate highest price sensitivity due to thin formulation margins, while practitioner-channel brands maintain lowest sensitivity through clinical validation premiums.
Supply Chain Analysis
REACH registration and EMA herbal monograph compliance gate EU market access, disqualifying multi-layered trading networks lacking documentary traceability from Indian tapping cooperatives through finished extract. Supply concentrates in India, with Germany and the United States as primary demand anchors. The value chain draws from wild-harvested Boswellia serrata resin, supercritical CO₂ extraction equipment, and certified reference materials for analytical validation. Single-source vulnerability runs through Rajasthan-Gujarat processing clusters exposed to monsoon-dependent yield fluctuations. Distribution runs through direct contracting between European finished-product manufacturers and solvent-free-certified Indian processors, bypassing traditional Mumbai trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The boswellia market functions as a stable compounder anchored by irreversible substitution of synthetic NSAIDs with standardized botanical anti-inflammatories in European and North American therapeutic protocols.
For Market Incumbents: Extend AKBA standardization capabilities beyond 30% thresholds to capture practitioner-channel consolidation in California and New York metropolitan markets. Deepen backward integration into Rajasthan tapping cooperatives through exclusive supply agreements that lock in raw material security against cyclical yield volatility. Invest in dual-standardized extraction infrastructure producing simultaneous pharmaceutical-grade boswellic acid concentrates and terpene-rich aromatherapy fractions to collapse the historical separation between medicinal and cosmetic supply chains. For New Entrants and Emerging Players: Launch via US direct-to-consumer e-commerce subscription models that bypass established practitioner gatekeepers and capture margin previously allocated to clinical networks. Target FSSAI-permitted functional food integration partnerships with Indian beverage manufacturers, the most penetrable white-space segment given regulatory clearance for specified health applications. Emphasize solvent-free supercritical CO₂ extraction certifications as the primary go-to-market angle to differentiate against hydroalcoholic competitors in premium wellness channels. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale Rajasthan-Gujarat processors holding captive raw material relationships and pending EMA monograph compliance investments rather than pure trading entities. Long-term viability over a 5-10 year horizon rests on irreversible regulatory pharmacopeial convergence that entrenches standardized extract demand. The signal to watch is CDSCO herbal API registration acceleration under India's PLI scheme, indicating domestic pharmaceutical formulator demand inflection that would validate captive extraction infrastructure investments.| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Extraction Certification | EMA and REACH compliance enables premium EU pharmaceutical supply chain access for Rajasthan-Gujarat processors. |
| Direct-to-Consumer Channel Launch | Subscription capsule models bypass practitioner gatekeepers and capture margin in US e-commerce wellness segments. |
| Backward Integration into Tapping Cooperatives | Exclusive raw material agreements mitigate monsoon-dependent yield volatility for integrated extractors. |
| Dual-Standardized Production Infrastructure | Hybrid supercritical CO₂ and hydroalcoholic systems collapse separation between pharmaceutical and aromatherapy supply chains. |
| FSSAI Functional Food Partnership | Health beverage formulation alliances open India's domestic inflammation-conscious consumer segment to standardized extract suppliers. |
Study Parameters
Direct dialogue with extraction plant managers, pharmaceutical formulator procurement leads, EMA regulatory affairs specialists, and Indian PLI scheme administrators grounded qualitative insights in operational reality. Secondary validation drew from CDSCO herbal API filings, EMA herbal monograph documentation, REACH registration databases, and US FDA Warning Letter archives. Bottom-up resin volume estimates from Gujarat-Rajasthan processing clusters triangulated against top-down pharmaceutical and nutraceutical demand projections.
Segmented outputs across resin extract, essential oil, powder, and capsule product types combined with nutraceutical, pharmaceutical, cosmetic, and aromatherapy application channels. CAGRs derived from regression analysis of historical standardization premium trends and regulatory compliance cost trajectories. Forecast inputs incorporated PLI scheme capital flow patterns and practitioner-channel consolidation velocity in North American integrative medicine markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EMA monograph revision or sustained curcumin displacement acceleration in joint-health categories. A model refresh is warranted upon material change in CDSCO herbal API registration thresholds or FSSAI functional food specification expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Saudi Arabia Poultry Meat Market
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
India Agriculture Market
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
Taro Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
Asia-Pacific Artificial Humus Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Alfalfa Protein Concentrate Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
African Swine Feed Market
Agriculture and Agri Products
Chaga Mushroom Market