
 Greenhouse Horticulture Market | 2026-2036
Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
Greenhouse Horticulture Market Intelligence
The Netherlands is tilting toward high-tech glasshouse expansion for year-round tomato and pepper cultivation. Van der Hoeven leverages decades of integrated greenhouse engineering to dominate turnkey project delivery across Western Europe. Certhon competes through advanced climate-computing systems that optimize energy use per kilogram of yield. Priva Holding anchors its position in precision irrigation and environmental control software for large-scale commercial operators.
Greenhouse horticulture denotes the cultivation of plants within controlled-environment structures using engineered climate, lighting, and substrate systems, typically employing steel-framed glass or polyethylene enclosures with automated ventilation, heating, and fertigation equipment. The practice enables precise management of temperature, humidity, CO2 concentration, and photoperiod to maximize photosynthetic efficiency and crop uniformity for commercial output. Vegetables command the largest volume share among product types, driven by supermarket chain procurement of locally sourced, pesticide-reduced produce. Hydroponics leads technology adoption in water-scarce regions where soil-based cultivation faces regulatory restrictions on groundwater extraction. Commercial growers represent the deepest end-user margin pool, though research institutions are expanding controlled-environment agriculture trials for cultivar development.
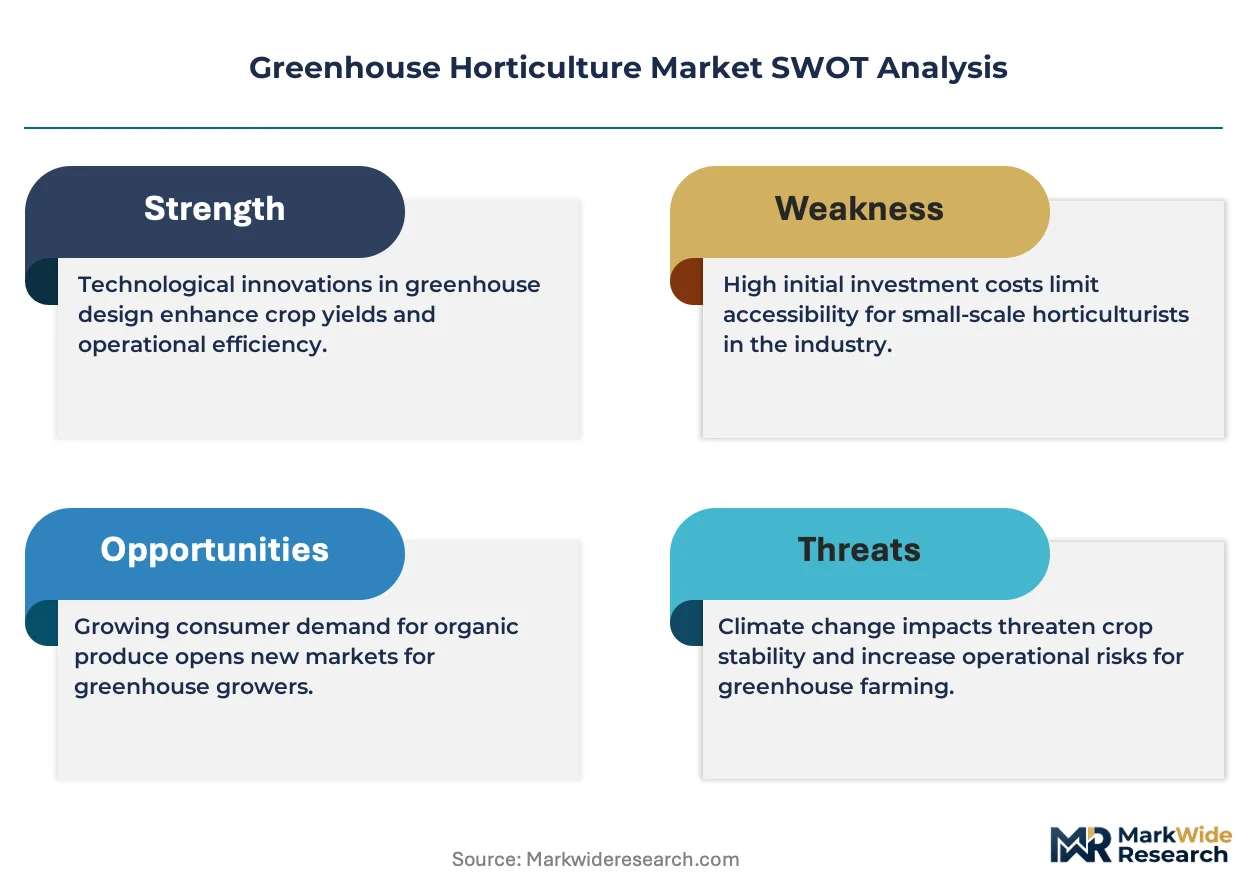
The EPA enforces Clean Water Act provisions that constrain agricultural runoff from open-field operations, indirectly steering vegetable producers toward contained hydroponic systems with closed-loop nutrient recycling. REACH and the EU Green Deal mandate progressive reduction of chemical pesticide application, compelling Dutch and Spanish greenhouse operators to adopt biological pest management and pollinator-friendly protocols. The F-Gas Regulation phases down hydrofluorocarbon use in refrigeration and heat-pump systems, pushing Certhon and Van der Hoeven toward CO2-based heat recovery and geothermal integration in new designs. Stakeholders must weigh capital intensity against regulatory compliance timelines when selecting technology platforms for multi-decade facility investments.
Market Dynamics
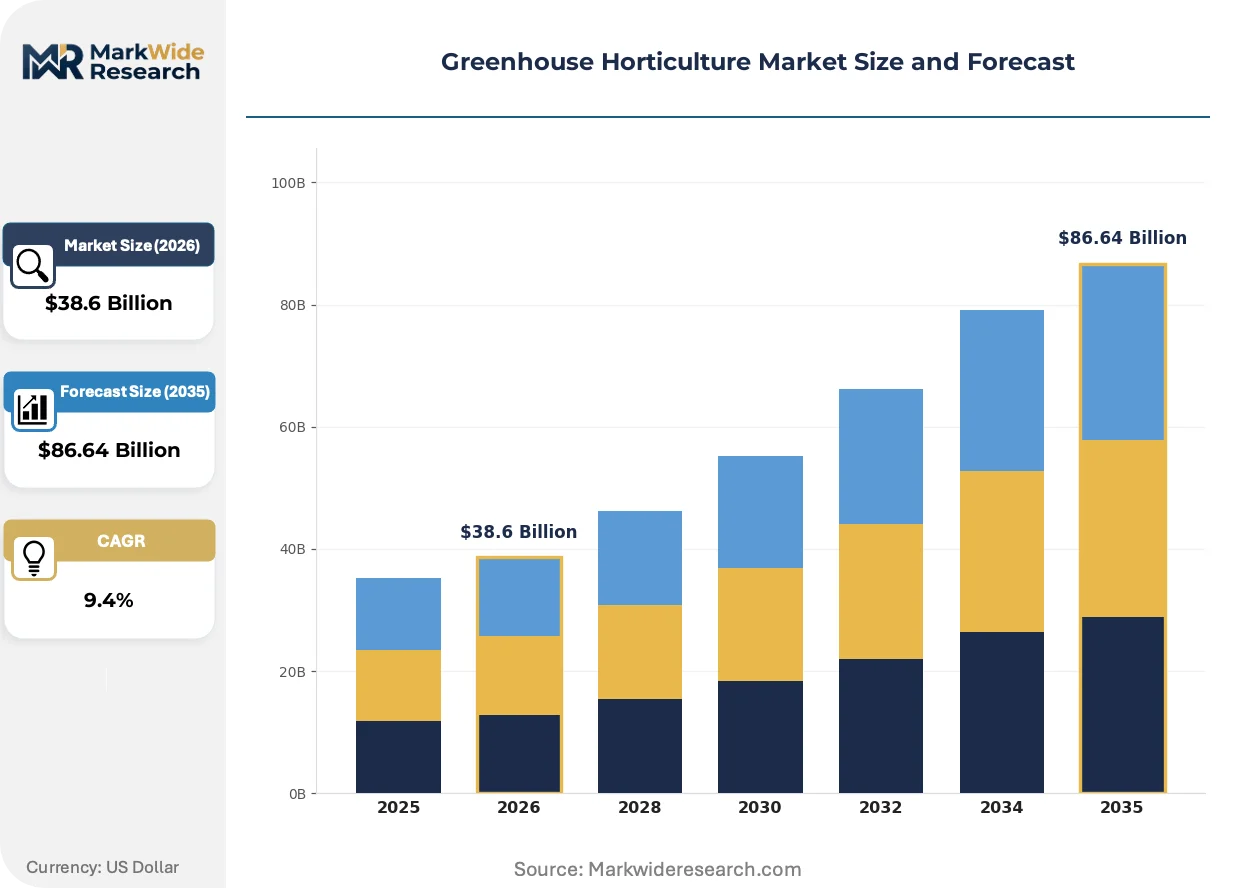
Water-use restrictions across drought-prone agricultural regions are forcing vegetable producers toward closed-loop hydroponic systems that eliminate soil-based runoff entirely. This structural pivot toward contained cultivation is reshaping capital allocation decisions for multi-decade facility investments.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants accelerates adoption of CO2-based heat recovery systems in Dutch and Spanish glasshouse expansions.
- Supermarket chain procurement:Centralized purchasing of pesticide-reduced, locally sourced produce drives contract consolidation toward large-scale commercial greenhouse operators.
- Hydroponics technology:Closed-loop nutrient recycling enables cultivation in water-scarce regions where groundwater extraction faces statutory limits.
Market Restraints
- Energy input volatility:Natural gas and electricity price swings compress operating margins for heated glasshouse operations in Northern Europe.
- Steel and aluminum supply concentration:Structural framing material sourcing clusters in Chinese manufacturing, exposing project timelines to trade policy friction.
- Technical skill scarcity:Climate-computing system operation requires agronomy-software hybrid expertise that vocational pipelines have not scaled to match.
Strategic Opportunities
- China's MIIT smart-agriculture standards:Domestic food security mandates create demand for turnkey greenhouse engineering with integrated environmental controls.
- Geothermal integration:Shallow geothermal loops paired with CO2 heat pumps open year-round cultivation in previously marginal Northern climates.
- Biological pest management:REACH-mandated pesticide reduction creates service revenue streams for pollinator-friendly protocol implementation.
Industry Challenges
- Capex intensity of climate-computing infrastructure:Sensor networks and automated fertigation systems require upfront investment that strains grower balance sheets.
- Certification timeline compression:EU Green Deal compliance deadlines outpace biological control product registration cycles, creating operational gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greenhouse Horticulture Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Flowers, Fruits, Herbs Technology: Hydroponics, Aeroponics, Soil-based, Bioponics End User: Commercial Growers, Home Gardeners, Research Institutions, Landscaping Services Application: Food Production, Ornamental Gardening, Seed Production, Research Activities |
| Companies Covered | Prospiant, Van der Hoeven, Dalsem, GGS Structures Inc., Hoogendoorn, Certhon, Richel Group, Agra Tech, Inc., Priva Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greenhouse Horticulture Market Strategic Shifts & Innovations
Climate-computing platforms are converging with biological cultivation protocols to transform greenhouse operations from energy-intensive structures into precision manufacturing environments for plant biomass.
Environmental sensor arrays coupled with machine-learning inference engines are digitizing greenhouse management at the row level. Large-scale commercial operators in the Netherlands deploy these systems to modulate irrigation, lighting, and CO2 dosing in real-time. The technology is digitizing yield forecasting from seasonal approximation to weekly prediction, compressing procurement contract negotiation cycles.
REACH authorization requirements for remaining chemical crop protection agents are accelerating biological control agent adoption. Dutch and Spanish operators now integrate banker-plant systems and beneficial insect release protocols into standard operating procedures. Vegetable cultivation segments face the steepest compliance cost escalation, driving consolidation toward operators with in-house entomology expertise.
Direct contracting between supermarket chains and greenhouse consortia is displacing traditional produce auction mechanisms. German and British retail buyers now specify cultivar, harvest window, and packaging format through multi-year offtake agreements. This pattern concentrates volume with integrated operators capable of certifying pesticide residue levels below regulatory minimums.
Greenhouse Horticulture Market Segmentation
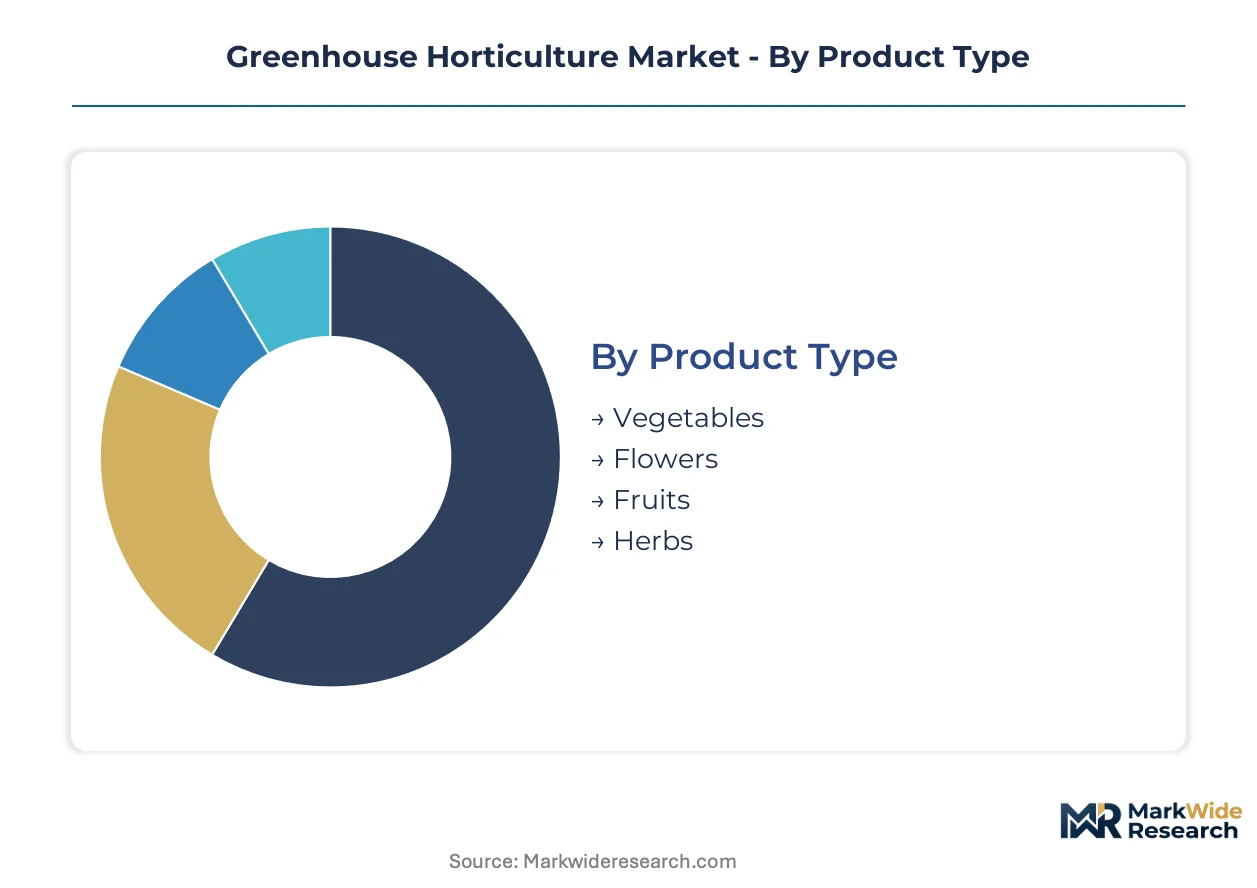
Segmentation in greenhouse horticulture reveals distinct capital allocation patterns across cultivation systems and buyer categories. Technology choice determines energy intensity and regulatory exposure, while end-user type shapes facility scale and automation depth.
Product Type:
Mature supermarket procurement contracts anchor vegetable cultivation, while emerging premium segments reshape margin structures across floral and specialty crops.
- Vegetables:Tomato, pepper, and cucumber operations dominate glasshouse acreage under multi-year retail offtake agreements. Dutch and Spanish commercial clusters supply year-round production to German and British supermarket chains seeking pesticide-reduced sourcing.
- Flowers:Ornamental cultivation concentrates in Kenya, Ethiopia, and Ecuador for European export markets. Rose and chrysanthemum operations compete on stem length uniformity and cold-chain logistics rather than energy-efficient climate control.
- Fruits:Strawberry and raspberry protected cultivation expands in water-scarce regions of California and Morocco.
- Herbs:Basil, mint, and cilantro operations serve fresh-cut retail and foodservice channels with rapid harvest cycles.
Vegetables retain volume leadership; herbs hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive closed-loop systems from accessible soil-based entry points, with regulatory pressure driving migration up the technology ladder.
- Hydroponics:Nutrient film technique and deep-water culture systems eliminate soil media entirely, enabling water recycling rates exceeding 90% in drought-affected jurisdictions. California's Sustainable Groundwater Management Act and Spain's national hydrological plans restrict open-field extraction, funneling vegetable investment toward contained hydroponic infrastructure.
- Aeroponics:Mist-based root delivery achieves highest water-use efficiency for leafy green and herb production. NASA and ESA research programs validate the technology for closed-environment life support, though commercial deployment remains limited to high-value pharmaceutical and nutraceutical feedstock cultivation.
- Soil-based:Traditional substrate cultivation persists in regions with permissive groundwater regulations and lower energy costs.
- Bioponics:Organic-compliant recirculating systems integrate aquaculture effluent for nutrient delivery, serving certified organic market segments.
Hydroponics commands the largest installed base; aeroponics climbs the fastest despite capital barriers.
End User:
Customer type determines automation depth, with commercial operators absorbing full climate-computing suites while research and consumer segments prioritize accessibility over precision.
- Commercial Growers:Large-scale operators deploy integrated environmental control systems across multi-hectare facilities. These buyers negotiate directly with supermarket procurement teams and absorb the full cost of REACH compliance, biological pest management protocols, and F-Gas Regulation-aligned heat pump installations.
- Home Gardeners:Hobby-scale greenhouse kits and countertop hydroponic systems serve urban consumers seeking pesticide transparency. Retail channels through Amazon and specialty garden centers dominate, with price points sensitive to energy cost inflation.
- Research Institutions:Universities and agricultural extension services operate controlled-environment agriculture trials for cultivar development and climate adaptation studies.
- Landscaping Services:Commercial horticulture contractors maintain seasonal bedding plant production for municipal and corporate clients.
Commercial growers absorb the deepest technology investment; research institutions expand facility count most rapidly.
Application:
Volume concentration in food production contrasts with margin premium available in specialized seed and research applications requiring phytosanitary certification.
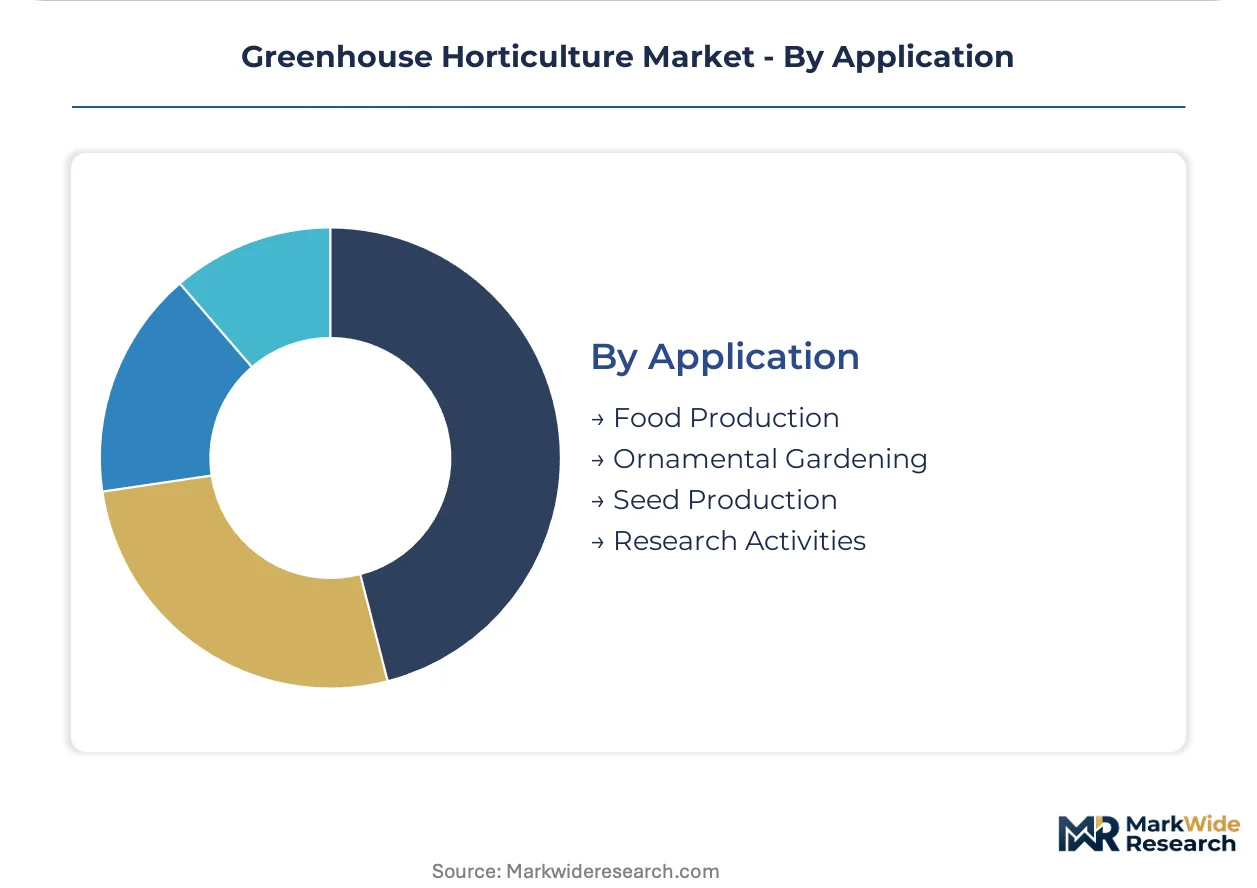
- Food Production:Fresh vegetable and herb cultivation for retail and foodservice channels represents the dominant revenue pool. EFSA residue monitoring programs and supermarket private-label standards enforce traceability requirements that favor integrated operators with in-house laboratory testing.
- Ornamental Gardening:Bedding plants, potted flowers, and landscape nursery stock serve seasonal consumer demand and commercial landscaping contracts.
- Seed Production:Hybrid vegetable seed and rootstock propagation requires isolated greenhouse zones with stringent pest exclusion protocols.
- Research Activities:Controlled-environment trials for crop physiology, pathology, and breeding programs operate at smaller scale with specialized lighting and atmosphere control.
Food production retains volume leadership; seed production captures the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and the EU Green Deal anchor regulatory momentum in Western Europe, while China's MIIT standards and California's groundwater restrictions reshape investment geography across the analysis window.
Netherlands
Supermarket procurement contracts for pesticide-reduced vegetables drive glasshouse expansion around Westland and Aalsmeer. The F-Gas Regulation accelerates CO2-based heat recovery adoption in new facilities. Dutch engineering clusters dominate turnkey project delivery across Western Europe.
China
Domestic food security mandates under MIIT smart-agriculture standards concentrate investment in Shandong and Jiangsu provinces. The country's dual carbon goals constrain energy-intensive heating designs. Beijing-Tianjin-Hebei corridor operators pilot integrated environmental control systems for year-round vegetable supply.
United States
California's Sustainable Groundwater Management Act funnels vegetable investment toward closed-loop hydroponic infrastructure in Salinas Valley and Imperial County. EPA Clean Water Act enforcement constrains open-field agricultural runoff. Southwestern operators absorb capital intensity through multi-year retail offtake structures.
Spain
National hydrological plans restrict groundwater extraction in Almería and Murcia, compelling migration to contained cultivation systems. EU Green Deal pesticide reduction timelines compress biological control product registration cycles. Andalusian greenhouse clusters integrate banker-plant protocols for compliant tomato and pepper production.
Canada
Leamington, Ontario anchors North American greenhouse vegetable supply to US Midwest retail chains. Provincial energy cost volatility compresses operating margins for heated glasshouse operations. British Columbia operators experiment with shallow geothermal loops paired with CO2 heat pumps for margin defense.
Greenhouse Horticulture Market Key Industry Players
Capability concentration sits with integrated engineering specialists; scale advantage sits with modular structure fabricators. The vendor base stratifies across three tiers: turnkey project deliverers, climate-computing software providers, and structural component suppliers. Dominant competitive moves include strategic partnerships with supermarket procurement teams and backward integration into environmental control hardware.
Among Dutch integrated engineering specialists, Van der Hoeven and Certhon exemplify the capability-driven tier, while Priva Holding occupies a position within precision irrigation and environmental control software. These entities represent divergent strategic archetypes: Van der Hoeven anchors turnkey delivery, Certhon exemplifies advanced climate-computing integration, and Priva Holding anchors software-layer specialization for large-scale commercial operators.
| Leading Market Players |
|---|
| Prospiant |
| Van der Hoeven |
| Dalsem |
| GGS Structures Inc. |
| Hoogendoorn |
| Certhon |
| Richel Group |
| Agra Tech, Inc. |
| Priva Holding |
| Others |
Cost & Logistics Intelligence
Glasshouse overcapacity in Almería and Murcia compresses turnkey project margins while concentrating pricing power with engineering specialists capable of integrating F-Gas-compliant heat recovery systems. This utilization asymmetry forces modular structure fabricators toward commodity positioning while climate-computing platforms capture premium tiers.
Pricing Analysis
Geographic price spreads between Dutch high-tech glasshouse expansions and Spanish polyethylene-clad installations exceed 40 percent on a per-square-meter basis. Project-based contracting dominates, with pricing stratifying across premium climate-computing integration, standard environmental controls, and economy structural-only tiers. Cost compression in the economy tier intensifies because Chinese steel framing imports face escalating tariff exposure. Research institutions exhibit highest price sensitivity due to grant-funded capital constraints; supermarket-linked commercial growers absorb premium pricing for compliance-ready turnkey delivery.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates structural framing procurement risk for Western European project developers. Steel and aluminum supply concentrates in Chinese manufacturing, with secondary sourcing from Turkish and Indian mills. Component dependencies span climate sensors from Dutch engineering clusters, irrigation membranes from Israeli suppliers, and CO2 heat pumps from Japanese manufacturers. Single-source vulnerability concentrates in advanced climate-computing software layers. Distribution runs through direct contracting between engineering specialists and commercial grower consortia, bypassing traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greenhouse horticulture is approaching a platform-economics inflection as climate-computing systems converge with biological cultivation protocols, creating interoperability standards that will determine which environmental control architectures dominate multi-decade facility investments.
For Market Incumbents: Harden defensive positioning through backward integration into sensor hardware manufacturing and captive supply of CO2 heat pump systems. Prioritize certification investment for REACH-compliant biological pest management protocols to lock in supermarket procurement contracts. Anchor capacity expansion in geothermal-rich jurisdictions like British Columbia to offset energy input volatility threatening Dutch and Canadian margin structures.
For New Entrants and Emerging Players: Build out service revenue streams around pollinator-friendly protocol implementation and banker-plant system management, white-space targets created by EU Green Deal pesticide reduction timelines. Target research institution facility expansion in China under MIIT smart-agriculture standards, the most penetrable geography for turnkey environmental control integration. Pursue direct partnerships with provincial agricultural extension services rather than competing head-to-head with established engineering specialists.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across climate-computing infrastructure as sensor networks and automated fertigation systems claim larger shares of total project cost. Long-term viability favors acquisition targets with in-house entomology expertise and biological control agent registration capabilities. Monitor biological pest management product approval velocity at ECHA as the critical signal for operational gap duration and compliance cost trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal Integration Partnership | Shallow geothermal loops paired with CO2 heat pumps open year-round cultivation in marginal Northern climates. |
| Biological Control Agent Registration | ECHA authorization timelines determine competitive positioning for Dutch and Spanish operators facing EU Green Deal deadlines. |
| Supermarket Direct Contracting | German and British retail buyers now specify cultivar and harvest window through multi-year offtake agreements. |
| Climate-Computing Platform Launch | Machine-learning inference engines digitize yield forecasting from seasonal approximation to weekly prediction. |
| Backward Integration into Sensor Hardware | In-house production of environmental sensor arrays reduces dependency on discrete component suppliers. |
Research Approach
Cross-validation between primary interviews with greenhouse engineering executives and secondary analysis of ECHA regulatory filings anchors the qualitative findings. The research program incorporated structured conversations with commercial grower procurement leads, climate-computing software developers, and supermarket category buyers, triangulated against EU F-Gas Regulation implementation reports, MIIT smart-agriculture standard documents, and EPA Clean Water Act enforcement patterns. Bottom-up facility investment tracking and top-down market sizing were reconciled across the analysis window.
Calibration against historical capacity deployment in the Netherlands, Spain, and Canada validated the projection framework. Segmentation modeling spanned cultivation system technology, product type, end-user category, and regional regulatory cluster. CAGRs were derived from trend extrapolation of investment flows and penetration curve analysis for hydroponic and aeroponic systems. Forecast inputs incorporated groundwater restriction stringency indices and supermarket procurement contract velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by modular structure fabricators toward climate-computing integration would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Elaeis Guineensis Kernel Oil Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
Alfalfa Protein Concentrate Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
Asia-Pacific Artificial Humus Market
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Feed Protein Market