
 North America Probiotic Drinks Market | 2026-2036
North America Probiotic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Probiotic Drinks Market Analytics
Precision fermentation and next-generation strain engineering is reshaping how probiotic beverages achieve viability counts and shelf stability without cold-chain dependence. Danone S.A. leverages its refrigerated distribution network to dominate conventional retail placement. Lifeway Foods, Inc. anchors its position through kefir specialization and heritage brand recognition in ethnic and health-food channels. Nestlé S.A. competes via R&D intensity in synbiotic formulations that combine probiotics with targeted prebiotic fibers.
Probiotic drinks are non-alcoholic beverages containing live beneficial microorganisms, typically Lactobacillus or Bifidobacterium strains at minimum counts of 10^6 to 10^9 colony-forming units per serving, manufactured through controlled fermentation or post-fermentation inoculation to support digestive and immune health. Dairy-based drinks occupy the largest volume share due to established consumer familiarity and protein-carrying matrices that protect culture viability, while fermented beverages represent the fastest-expanding margin pool as kombucha and water kefir attract experimental younger demographics. Online retail channels are capturing disproportionate growth as direct-to-consumer subscriptions enable temperature-controlled shipping and personalized strain combinations for health-conscious individuals.
The FDA exercises oversight through its Generally Recognized as Safe notification pathway and evolving guidance on structure-function claims, while Health Canada's Natural and Non-prescription Health Products Directorate imposes stricter labeling requirements that influence cross-border product standardization. The USDA's National Organic Program certification creates premium tier access for dairy and grain-based formulations meeting pasture and feed standards. Stakeholders must monitor emerging state-level sugar taxation proposals and municipal packaging ordinances that could reshape formulation priorities and material choices across California, New York, and Canadian provincial markets.
Market Dynamics
Precision fermentation and next-generation strain engineering are compressing the cold-chain dependency that once dictated probiotic beverage distribution economics across North America.
Growth Catalysts
- California innovation clusters:San Francisco Bay Area and Los Angeles biotech corridors concentrate venture funding for synbiotic startups developing shelf-stable formulations.
- FDA's evolving GRAS pathway:Streamlined Generally Recognized as Safe notifications for novel microbial strains accelerate product development timelines for fermented beverage innovators.
- Health-conscious millennial routines:Daily functional beverage consumption habits in urban centers drive recurring purchase velocity for kombucha and water kefir categories.
Market Restraints
- Dairy input cost volatility:Organic milk and kefir grain supply fluctuations squeeze margin structures for traditional dairy-based probiotic drink manufacturers.
- Live culture technical limitation:Viability decay above refrigerated temperatures restricts ambient retail channel penetration and complicates last-mile logistics.
- State-level sugar taxation proposals:California and New York municipal ordinances threaten formulation reformulation costs for sweetened fermented beverages.
Strategic Opportunities
- Canadian provincial expansion:Health Canada's Natural and Non-prescription Health Products Directorate creates premium tier access for certified organic formulations in Ontario and British Columbia.
- Direct-to-consumer subscription channels:Temperature-controlled shipping enables personalized strain combinations bypassing conventional retail slotting constraints.
- Shelf-stable technology convergence:Microencapsulation meets precision fermentation to unlock ambient distribution in convenience and mass retail channels.
Industry Challenges
- Microbiology talent scarcity:Strain engineering and fermentation science expertise concentrates in limited geographic pockets, constraining R&D scaling.
- Organic certification timeline compression:USDA National Organic Program pasture and feed standards extend supply chain onboarding for new dairy suppliers.
- Cross-border labeling harmonization:Divergent FDA and Health Canada structure-function claim requirements complicate unified North American product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Probiotic Drinks Market |
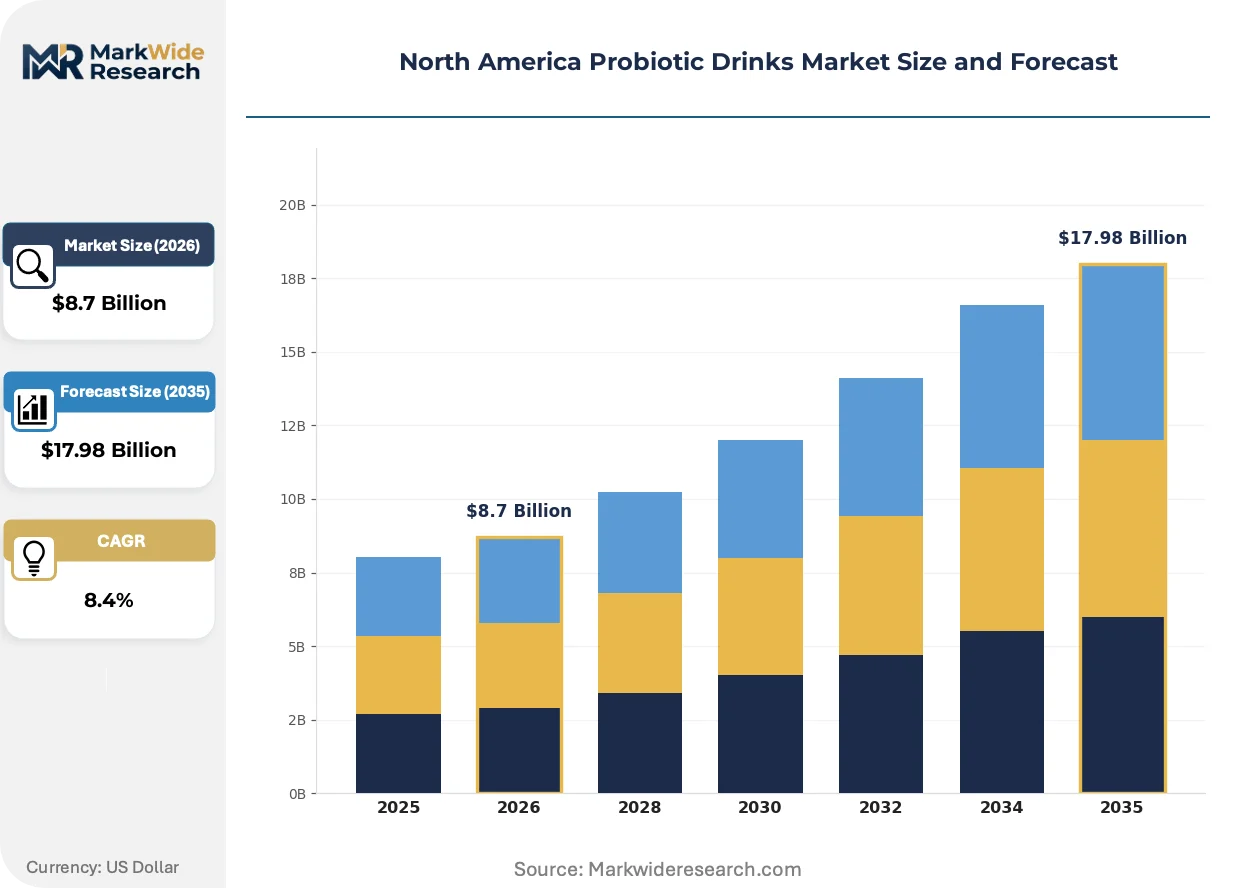
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermented Beverages, Carbonated Drinks, Juice-based Drinks, Dairy-based Drinks Ingredient Type: Fruits, Herbs, Grains, Dairy Consumer Type: Health-conscious Individuals, Athletes, Older Adults, Families Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores |
| Companies Covered | Nestlé S.A., Grupo LALA SAB de CV, Yakult Honsha Co., Ltd., Kerry Group PLC, General Mills, Inc., Danone S.A., Lifeway Foods, Inc., Fonterra Co-operative Group Limited, PepsiCo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Probiotic Drinks Market Evolving Landscape
Bioprocessing advances and regulatory recalibration are simultaneously expanding viable distribution channels and compressing traditional competitive moats in probiotic beverages.
Microencapsulation technology is digitizing strain viability monitoring through embedded biosensors that track colony-forming unit counts in real time throughout shelf life. Beverage manufacturers deploying these systems gain predictive quality control capabilities that reduce spoilage rates. The technology is digitizing supply chain transparency expectations, forcing legacy cold-chain operators to adopt comparable visibility tools or cede premium positioning.
FDA guidance on structure-function claims is tightening evidentiary standards for digestive health assertions on probiotic labels. Manufacturers must now substantiate live culture efficacy through clinical documentation rather than generic fermentation heritage. Fermented beverage startups in California and the Northeast are responding by building in-house clinical trial capabilities or partnering with academic research institutions.
Subscription-based replenishment models are displacing conventional grocery channel dependence for core consumer segments. Direct-to-consumer platforms enable strain personalization and temperature-controlled logistics that ambient retail cannot replicate. This behavioral pivot is most visible among millennial and Gen Z households in metropolitan areas where delivery infrastructure density supports reliable cold-chain fulfillment.
North America Probiotic Drinks Market Segmentation
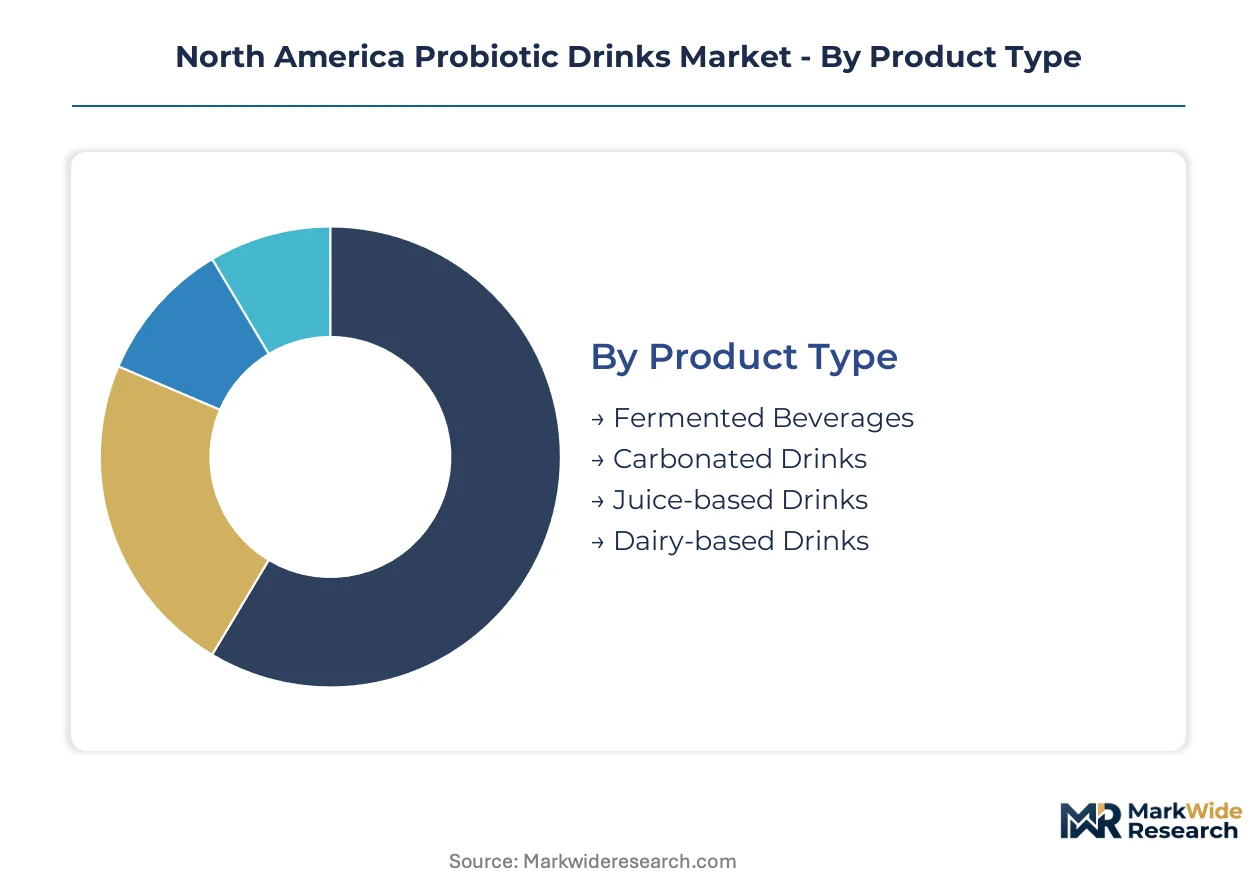
Probiotic drink segmentation reveals how formulation matrices, ingredient sourcing, and channel economics create distinct margin pools across North America. Each dimension carries unique regulatory exposure and cold-chain requirements that reshape competitive positioning.
Product Type:
Mature shelf-stable formats anchor volume while emerging fermentation technologies unlock ambient distribution economics.
- Dairy-based Drinks:Protein-carrying matrices of kefir and drinkable yogurt protect Lactobacillus and Bifidobacterium viability through refrigerated distribution. California's organic dairy corridors supply protein concentrates to manufacturers serving health-food retail networks.
- Fermented Beverages:Kombucha and water kefir rely on SCOBY or tibicos cultures in controlled anaerobic fermentation, delivering organic acids and live cultures without dairy allergens. Brooklyn and Portland fermentation clusters attract venture funding for synbiotic innovation targeting experimental millennials.
- Carbonated Drinks:Pressurized CO2 environments challenge culture survival, requiring microencapsulation or post-fermentation inoculation.
- Juice-based Drinks:Low-pH fruit matrices naturally inhibit pathogen growth but demand careful strain selection for acid tolerance.
Dairy-based drinks handle the majority of throughput; fermented beverages are climbing the fastest on share.
Ingredient Type:
Cost tiers separate commodity feedstocks from certified organic inputs that command shelf placement premiums.
- Dairy:Organic milk and kefir grains carry USDA National Organic Program certification requirements for pasture access and non-GMO feed, extending supplier onboarding timelines. Midwest dairy cooperatives dominate conventional supply while California's Central Valley anchors organic production.
- Fruits:Berry, citrus, and tropical purees provide flavor masking and prebiotic fiber substrates. Pacific Northwest berry processors and Florida citrus concentrate suppliers feed formulation pipelines for juice-based and kombucha manufacturers.
- Grains:Oat, rice, and buckwheat bases enable dairy-free positioning for allergen-sensitive consumers.
- Herbs:Adaptogenic and botanical inclusions require GRAS self-determination or FDA notification for novel ingredients.
Dairy commands the highest input cost tier; fruits are expanding most quickly as kombucha formulations diversify.
Consumer Type:
Application intensity varies from daily functional routines to episodic athletic recovery protocols.
- Health-conscious Individuals:Urban millennials and Gen Z consumers in metropolitan corridors integrate probiotic beverages into morning wellness routines, driving subscription replenishment velocity. Direct-to-consumer platforms target this segment with personalized strain combinations and temperature-controlled shipping.
- Athletes:Protein-fortified kefir and recovery-focused synbiotics target post-exercise gut permeability management. Colorado and California fitness culture clusters concentrate demand for performance-positioned formulations.
- Families:Multi-serve formats and kid-friendly flavor profiles emphasize convenience and palatability over strain diversity.
- Older Adults:Digestive regularity and immune support claims align with age-related microbiome concerns, requiring substantiation through Health Canada or FDA structure-function frameworks.
Health-conscious individuals generate the highest purchase frequency; athletes are gaining share fastest on per-unit value.
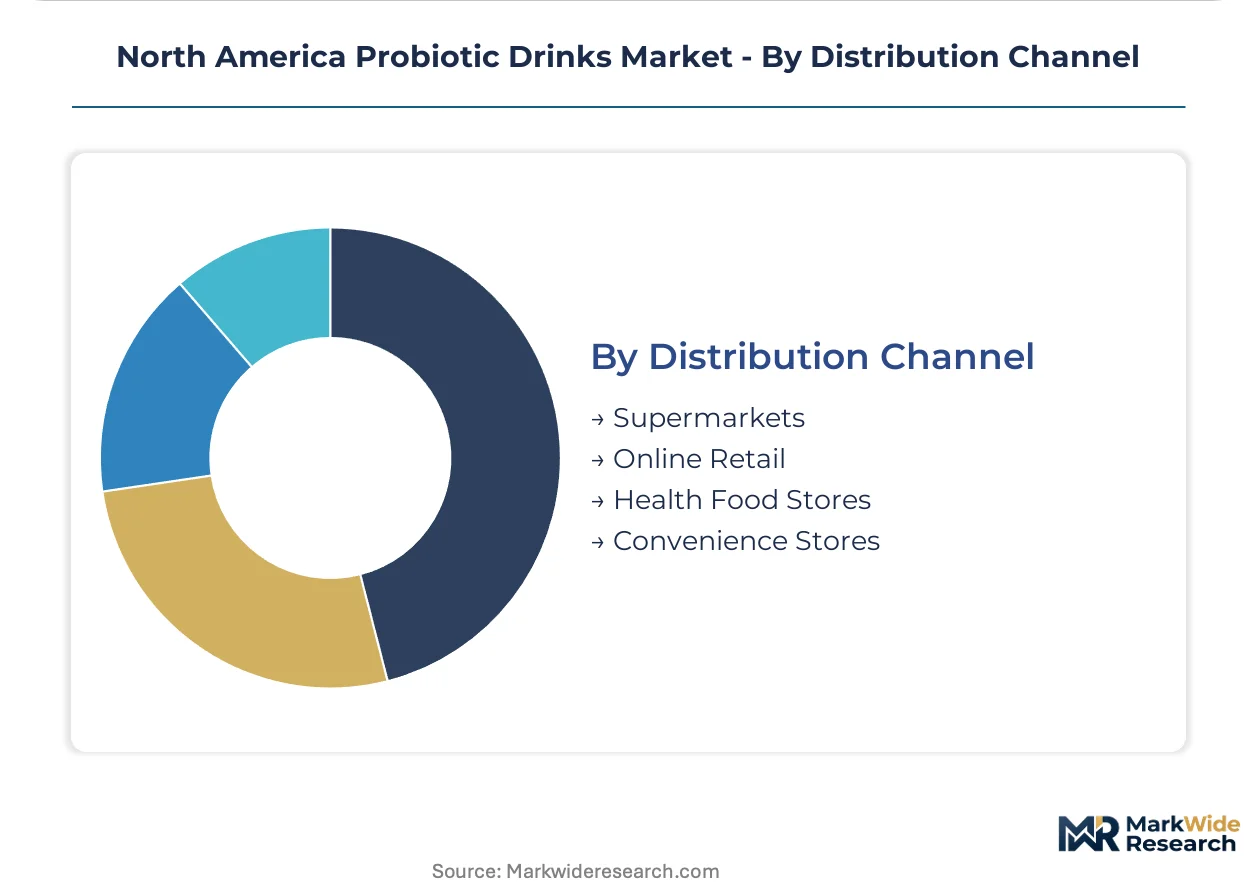
Distribution Channel:
Channel selection dictates cold-chain infrastructure investment and margin retention economics.
- Online Retail:Direct-to-consumer subscriptions enable strain personalization and temperature-controlled logistics bypassing conventional slotting fees. Brooklyn and Austin fulfillment hubs specialize in cold-chain parcel density for recurring delivery models.
- Supermarkets:Refrigerated case placement demands distributor relationships and trade spend for eye-level positioning. Northeast and West Coast grocery chains lead probiotic beverage SKU expansion.
- Health Food Stores:Independent retailers and regional chains like Whole Foods Market emphasize certified organic and local sourcing credentials.
- Convenience Stores:Ambient shelf-stable formulations remain underpenetrated due to live culture viability constraints.
Supermarkets handle the majority of volume throughput; online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious millennials and Gen Z consumers concentrate in coastal metropolitan corridors, driving recurring purchase velocity for functional beverage routines across the region.
United States
California's innovation clusters in San Francisco Bay Area and Los Angeles attract venture funding for synbiotic startups developing shelf-stable formulations. The FDA's evolving Generally Recognized as Safe notification pathway accelerates product development timelines for novel microbial strains. Brooklyn and Portland fermentation hubs concentrate kombucha and water kefir experimentation targeting experimental younger demographics.
Canada
Ontario and British Columbia health food corridors anchor demand for certified organic probiotic formulations among urban wellness consumers. Health Canada's Natural and Non-prescription Health Products Directorate imposes stricter labeling requirements that influence cross-border product standardization efforts. Toronto and Vancouver distribution networks specialize in temperature-controlled logistics for direct-to-consumer subscription models.
Mexico
Mexico City Metro and Nuevo León industrial zones concentrate dairy processing infrastructure for kefir and drinkable yogurt production serving domestic consumption. The country's national food safety regulator oversees live microbial ingredient standards through established dairy hygiene protocols. Guadalajara's Central Mexico corridor attracts regional headquarters for multinational beverage manufacturers targeting Latin American expansion.
North America Probiotic Drinks Market Competitive Landscape
Channel-controlling players compete with product-specialist players across refrigerated and ambient distribution networks. The market structure tiers between multinational conglomerates with integrated cold-chain infrastructure and focused fermentation specialists with heritage positioning. Three strategic archetypes dominate: dairy-based kefir specialists leveraging ethnic channel recognition, synbiotic innovators combining precision fermentation with microencapsulation, and beverage conglomerates extending portfolio reach through acquisition. Competitive moves concentrate on refrigerated distribution network expansion and direct-to-consumer platform development.
Among Switzerland-based multinationals, Nestlé S.A. exemplifies the R&D-intensive archetype in synbiotic formulations. Danone S.A. and Lifeway Foods, Inc. occupy positions across the dairy-based specialization spectrum, with the former representing scale-driven refrigerated distribution control and the latter anchoring heritage kefir positioning in ethnic and health-food channels.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Grupo LALA SAB de CV |
| Yakult Honsha Co., Ltd. |
| Kerry Group PLC |
| General Mills, Inc. |
| Danone S.A. |
| Lifeway Foods, Inc. |
| Fonterra Co-operative Group Limited |
| PepsiCo Inc. |
| Others |
Value Network & Pricing Analysis
California's Central Valley organic dairy corridors concentrate kefir grain and protein concentrate capacity, translating upstream fermentation feedstock scarcity into downstream margin compression for refrigerated probiotic beverage manufacturers serving premium retail tiers.
Pricing Analysis
Cost-plus contracts indexed to USDA dairy commodity benchmarks dominate ingredient procurement for kefir and drinkable yogurt manufacturers. Three-tier pricing structure across premium certified-organic, standard conventional-dairy, and economy private-label tiers separates shelf-stable from cold-chain-dependent formulations. Pricing pressure stems from organic milk input volatility as pasture and feed standards extend supplier onboarding timelines. Mass-market supermarket buyers exhibit highest price sensitivity, while direct-to-consumer subscription segments absorb premium positioning for personalized strain combinations.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Midwest dairy cooperatives and Pacific Northwest berry processors ease working capital constraints for kombucha and water kefir startups. Raw material sourcing draws from California organic dairy, Florida citrus concentrate suppliers, and Canadian kefir grain distributors. Single-source vulnerability concentrates in live culture strain banks maintained by limited microbiology laboratories. Distribution runs through refrigerated trucking networks anchored in Brooklyn and Austin fulfillment hubs for direct-to-consumer channels, with conventional retail depending on distributor-controlled cold-chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based fermented beverages and functional sodas with microbiome claims represent credible substitution threats that dairy-based probiotic incumbents must neutralize through formulation diversification and channel control.
For Market Incumbents: Insulate refrigerated distribution advantages by securing exclusive slotting agreements with Northeast and West Coast grocery chains while accelerating shelf-stable microencapsulation R&D to offset ambient-channel competition from plant-based entrants. Backward integration into California organic dairy supply secures kefir grain and protein concentrate access against input cost volatility. For New Entrants and Emerging Players: Canadian provincial markets in Ontario and British Columbia offer the most penetrable entry point given Health Canada's premium-tier certification pathways and underdeveloped direct-to-consumer cold-chain density. Ambient-stable synbiotic formulations targeting convenience retail gaps bypass incumbent refrigerated network dominance. For Investors and Strategic Acquirers: Long-term, this sits as a platform-consolidation play because precision fermentation capabilities and strain-engineering IP will determine category economics as cold-chain dependence erodes. Acquisition targets should display microbiology talent depth and GRAS notification experience. The signal to watch is FDA guidance finalization on structure-function claim substantiation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Shelf-Stable Technology Licensing | Microencapsulation partnerships unlock ambient distribution in convenience and mass retail channels previously inaccessible. |
| Direct-to-Consumer Platform Launch | Subscription models bypass conventional slotting fees while enabling temperature-controlled logistics and strain personalization. |
| Certified Organic Supply Integration | USDA National Organic Program compliance secures premium-tier placement in Whole Foods Market and regional health-food chains. |
| Synbiotic R&D Partnership | Precision fermentation collaborations with California biotech clusters accelerate next-generation strain engineering timelines. |
| Cross-Border Labeling Harmonization | Unified FDA-Health Canada structure-function claim portfolios reduce compliance duplication across North American markets. |
Research Methodology
A standing panel of fermentation science directors, refrigerated distribution logistics managers, health-food retail category buyers, and FDA regulatory affairs specialists provided ongoing calibration throughout the research cycle. Primary fieldwork combined structured interviews with secondary validation through FDA GRAS notification filings, USDA National Organic Program certification databases, Health Canada Natural and Non-prescription Health Products Directorate records, and Nielsen retail audit data. Bottom-up strain-level demand modeling and top-down category value triangulation anchored volume estimates.
Scenario-bracketing around FDA guidance finalization timelines, organic dairy input cost trajectories, and shelf-stable technology adoption curves bounded the projection horizon. Segmentation dimensions modeled include product matrix type, ingredient certification tier, distribution channel infrastructure, and consumer application intensity. CAGRs derived from historical velocity patterns adjusted for structural shifts in cold-chain economics and regulatory claim substantiation requirements. Industry-specific inputs incorporated live culture viability decay curves and temperature-controlled shipping cost elasticity.
Practitioners should monitor FDA structure-function claim enforcement actions, California sugar taxation legislative movement, and Health Canada organic certification backlog durations for early signals of forecast deviation. Macro-economic conditions affecting discretionary functional beverage expenditure, breakthroughs in ambient-stable strain engineering, or cross-border trade friction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market
Functional Food and Beverage
Functional Tea Market
Functional Food and Beverage
Fermented Protein Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market
Functional Food and Beverage
South America Functional Beverages Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Low Fat Protein Market
Functional Food and Beverage
Japan Functional Drinks Market
Functional Food and Beverage
Middle East and Africa Protein Bar Market
Functional Food and Beverage
Functional Powdered Lipids Market