
 North America Fermented Ingredient Market | 2026-2036
North America Fermented Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fermented Ingredient Market Analytics
Subscription-based technical service contracts for fermentation process optimization is restructuring how ingredient suppliers monetize expertise beyond physical product sales. Novonesis leverages its enzymatic technology leadership to anchor long-term service agreements with North American dairy processors. DSM-Firmenich sustains competitive positioning through integrated strain development capabilities that extend from lab to commercial scale. Cargill, Incorporated dominates bulk fermentation output by controlling extensive Midwest corn syrup feedstock networks.
Fermented ingredients comprise microbially transformed organic substrates including yeast extracts, bacterial cultures, and enzyme preparations typically standardized to specific activity units or protein content. These inputs serve as flavor modulators, texture enhancers, probiotic carriers, and biocatalysts across food and pharmaceutical manufacturing. Yeast-derived extracts occupy the largest revenue pool in North American fermented ingredient supply, reflecting entrenched demand from savory flavor applications. Enzyme segments register the fastest structural expansion, driven by precision fermentation advances that reduce unit production costs for pharmaceutical-grade biocatalysts.
FDA GRAS notification requirements and Health Canada Novel Food Regulations govern strain safety validation and label claims for fermented bioactives sold across the United States and Canada. USDA organic certification standards and EPA biopesticide rules further constrain which fermentation substrates and processing aids qualify for premium-positioned product lines. Stakeholders must monitor evolving EPA effluent guidelines for fermentation facilities and emerging state-level clean-label statutes that could disqualify certain synthetic processing aids from shelf-stable formulations.
Market Dynamics
Precision fermentation scale-up economics and FDA GRAS notification tightening are restructuring how ingredient suppliers deploy capital and validate strains across the United States and Canada.
Growth Catalysts
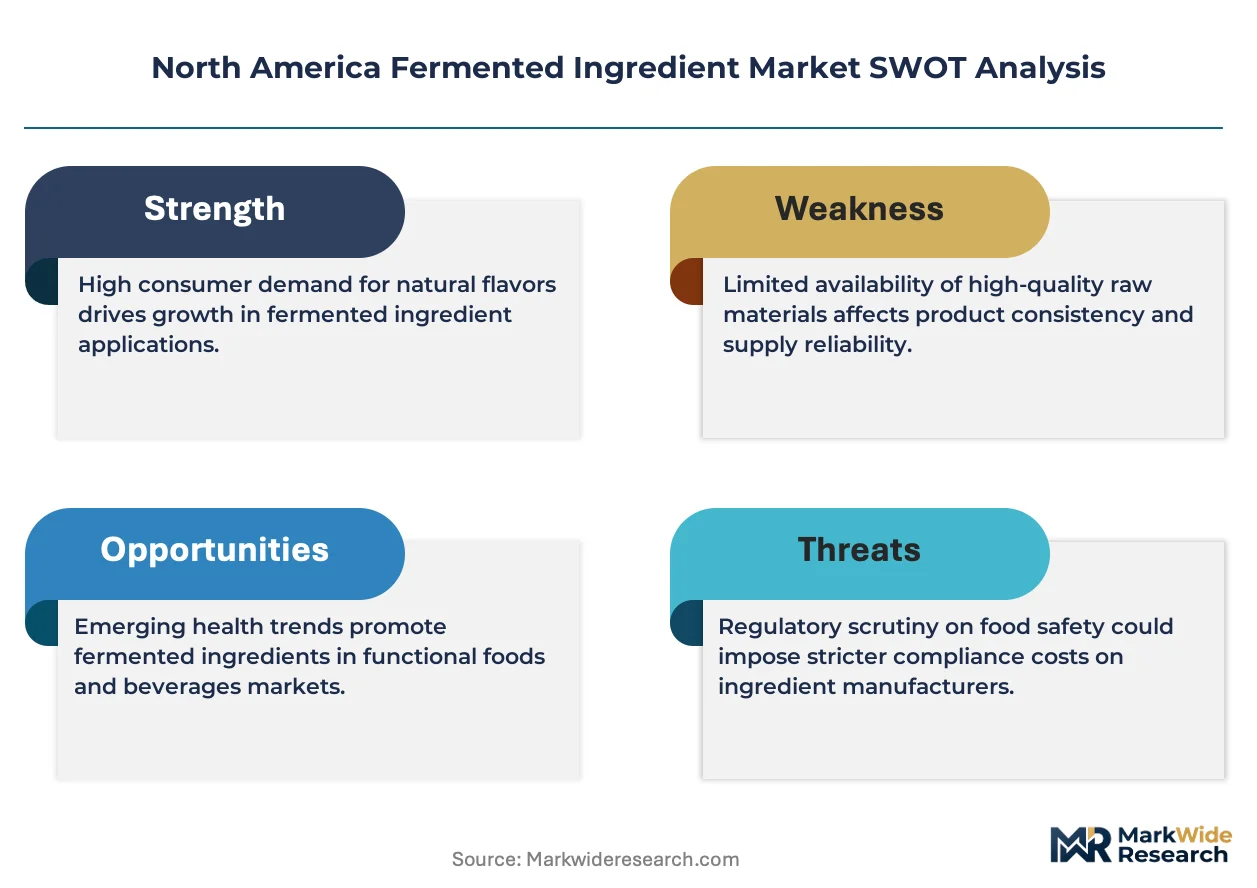
- Clean-label statutes:California and New York state-level clean-label requirements are accelerating substitution of synthetic processing aids with fermentation-derived alternatives in shelf-stable formulations.
- Enzyme cost compression:Precision fermentation advances are reducing unit production costs for pharmaceutical-grade biocatalysts, expanding addressable demand from generic drug manufacturers.
- Great Lakes dairy corridor:Concentrated dairy processing capacity across Wisconsin and Michigan is generating sustained pull for fermentation-derived enzymes and flavor modulators.
Market Restraints
- Midwest feedstock concentration:Corn syrup supply networks controlled by a limited set of agribusiness operators create input cost volatility and bargaining asymmetry for fermentation facilities.
- EPA effluent compliance:Emerging EPA guidelines for fermentation facility wastewater are imposing capital-intensive treatment upgrades that disadvantage smaller production sites.
- Strain validation timelines:FDA GRAS notification requirements and Health Canada Novel Food Regulations extend strain safety validation to 18-24 months, compressing effective patent windows.
Strategic Opportunities
- Mexico functional beverage expansion:Underpenetrated demand from Mexican clean-label beverage formulators offers first-mover positioning for fermentation-derived protein suppliers.
- Subscription service contracts:Technical service agreements for fermentation process optimization are creating recurring revenue streams beyond physical product sales.
- USDA organic certification:Premium-positioned product lines qualifying under USDA organic standards command 15-30% price premiums in California's functional food innovation cluster.
Industry Challenges
- Strain development talent scarcity:Competition for microbial geneticists and fermentation engineers between food, pharmaceutical, and biotech sectors is compressing hiring cycles and inflating compensation.
- Legacy system integration:California and Great Lakes dairy processors face technical friction integrating precision fermentation inputs with established pasteurization and homogenization equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fermented Ingredient Market |
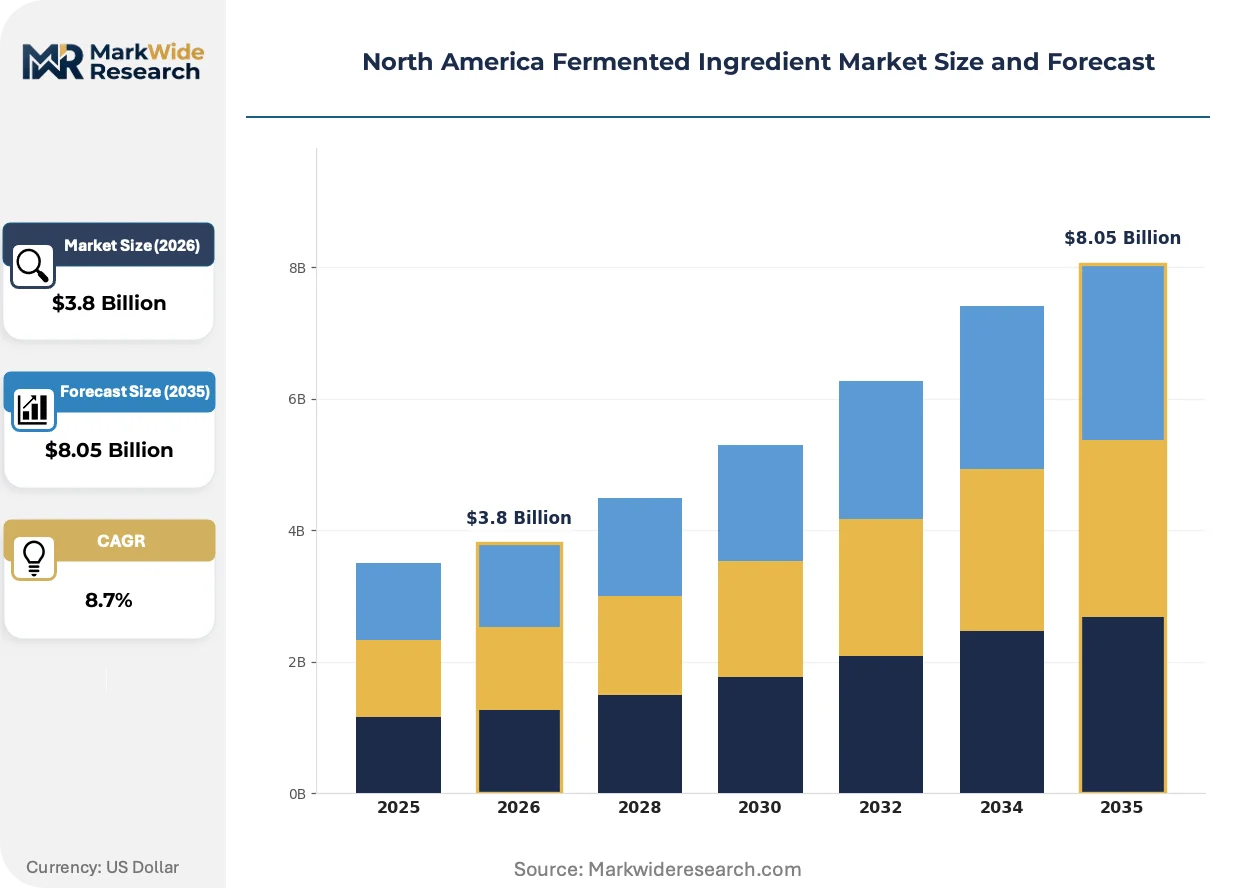
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast, Bacteria, Enzymes, Proteins Application: Beverages, Dairy Products, Nutraceuticals, Snacks End User: Food Industry, Pharmaceutical Companies, Cosmetic Sector, Animal Feed Form: Powder, Liquid, Capsules, Granules |
| Companies Covered | BASF SE, DSM-Firmenich, DuPont, Cargill, Incorporated, Novonesis, Chr. Hansen Holding A/S, Lallemand Inc., Ajinomoto Co., Inc., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fermented Ingredient Market Evolving Landscape
Active fermentation process control systems and regulatory data transparency requirements are compressing batch-to-batch variability and reshaping supplier-buyer technical relationships.
Continuous fermentation monitoring is unifying real-time metabolite sensing with automated nutrient feed control. Pharmaceutical-grade enzyme manufacturers in the United States are adopting these systems fastest, with pilot installations operational across the Great Lakes corridor. The technology is unifying quality assurance with process economics, collapsing the traditional separation between R&D strain development and commercial production optimization.
Health Canada Novel Food Regulations now mandate whole-genome sequencing documentation for all novel microbial strains introduced after 2023. This policy shift forces ingredient suppliers to maintain dedicated bioinformatics capabilities or outsource to certified sequencing providers. Enzyme segments face the steepest compliance burden, with several U.S.-based suppliers establishing Vancouver satellite labs to accelerate Health Canada pre-submission consultations.
Buyer concentration among U.S. dairy processors is consolidating procurement authority into centralized technical sourcing functions. Three of the five largest Great Lakes dairy cooperatives now mandate fermentation ingredient suppliers provide dedicated on-site process engineers as a contract condition. This pattern is most visible in Wisconsin, where multi-year service agreements now accompany 60% of bulk enzyme purchases.
North America Fermented Ingredient Market Segmentation
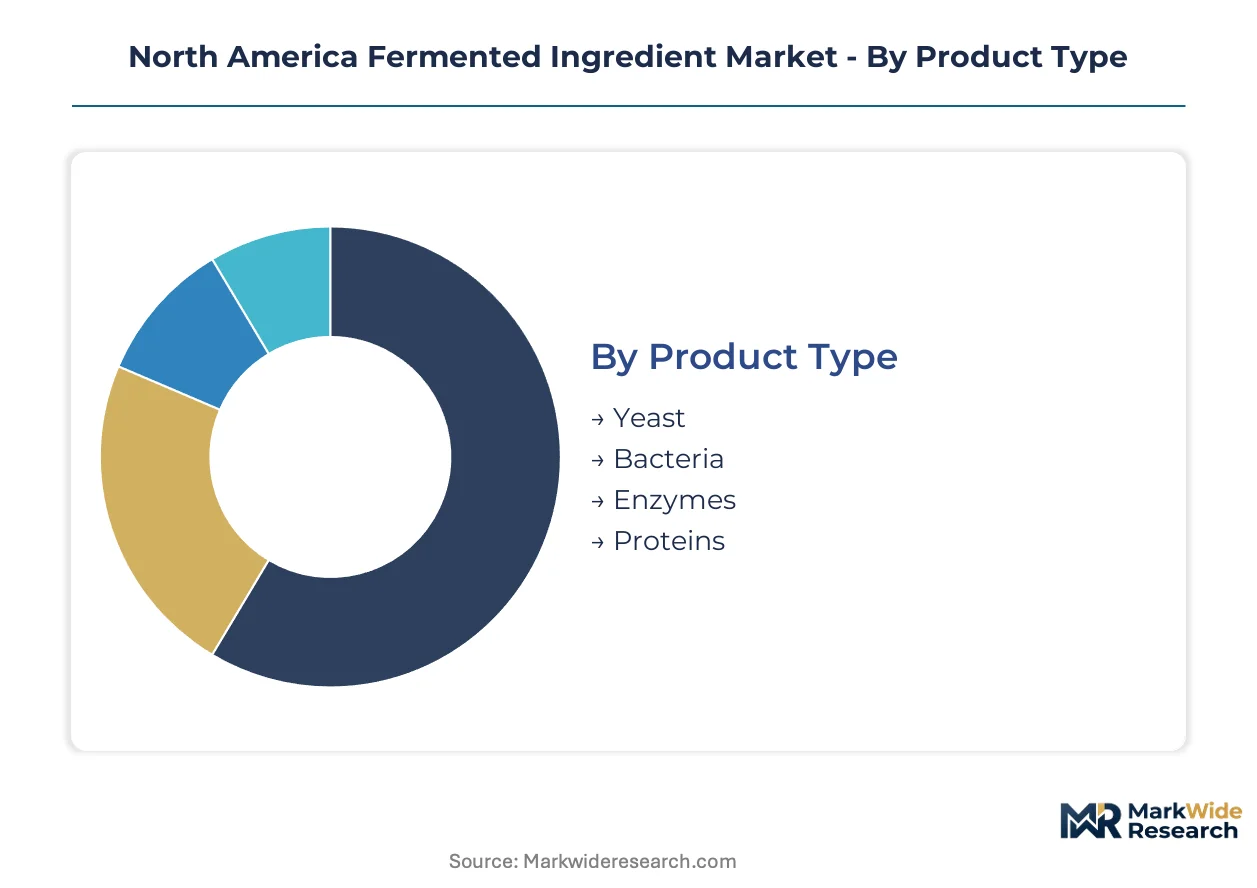
Segmentation in the North America fermented ingredient market reveals how regulatory pathways and certification requirements fragment supplier economics. FDA GRAS notifications and Health Canada Novel Food Regulations impose divergent validation burdens across product categories, reshaping which segments attract capital deployment.
Product Type:
Yeast extracts and bacterial cultures carry lighter FDA notification requirements than precision fermentation proteins, which face whole-genome sequencing mandates from Health Canada.
- Yeast:Autolyzed and hydrolyzed yeast extracts standardized to ribonucleotide content serve as savory flavor modulators. Demand concentrates in Wisconsin dairy processing facilities seeking clean-label alternatives to synthetic flavor enhancers, though California's functional food cluster is driving specification tightening for organic-certified variants.
- Enzymes:Standardized biocatalyst preparations including proteases, lipases, and carbohydrases produced via submerged fermentation. Pharmaceutical-grade enzyme demand from Great Lakes generic drug manufacturers is accelerating precision fermentation scale-up, with unit cost compression expanding addressable markets.
- Bacteria:Live and heat-treated cultures for fermentation starter applications and probiotic delivery.
- Proteins:Fermentation-derived functional proteins and protein isolates for alternative food formulations.
Leading the category by volume: Yeast. Growing fastest: Enzymes.
Application:
Application segments diverge sharply by margin structure, with nutraceuticals commanding premium pricing tied to clinical validation requirements while beverage applications prioritize cost-per-dose efficiency.
- Dairy Products:Fermentation-derived enzymes and flavor systems for cheese manufacturing, yogurt production, and dairy protein modification. Wisconsin and Michigan processing corridors generate concentrated demand, with cooperatives mandating on-site technical service as a contract condition.
- Nutraceuticals:Probiotic formulations, postbiotic preparations, and fermentation-derived bioactives for dietary supplements. California's functional food innovation cluster drives specification innovation, with USDA organic certification commanding substantial price premiums.
- Beverages:Fermentation inputs for clean-label soft drinks, functional waters, and alcoholic beverage production.
- Snacks:Yeast extracts and flavor modulators for savory snack seasoning applications.
Highest margin capture: Nutraceuticals. Steepest volume expansion: Dairy Products.
End User:
End user concentration determines contract structure, with pharmaceutical companies demanding batch documentation and food processors prioritizing supply security.
- Food Industry:Dairy processors, beverage formulators, and savory food manufacturers purchasing fermentation inputs for texture, flavor, and shelf-life modification. Great Lakes dairy cooperatives now consolidate procurement through centralized technical sourcing functions.
- Pharmaceutical Companies:Generic drug manufacturers and active pharmaceutical ingredient producers sourcing pharmaceutical-grade enzymes and biocatalysts. FDA GRAS notification requirements and extended strain validation timelines compress effective patent windows.
- Cosmetic Sector:Fermentation-derived bioactives for skincare and personal care formulations.
- Animal Feed:Probiotic and enzyme supplements for livestock nutrition and feed efficiency.
Dominant procurement volume: Food Industry. Fastest contract sophistication: Pharmaceutical Companies.
Form:
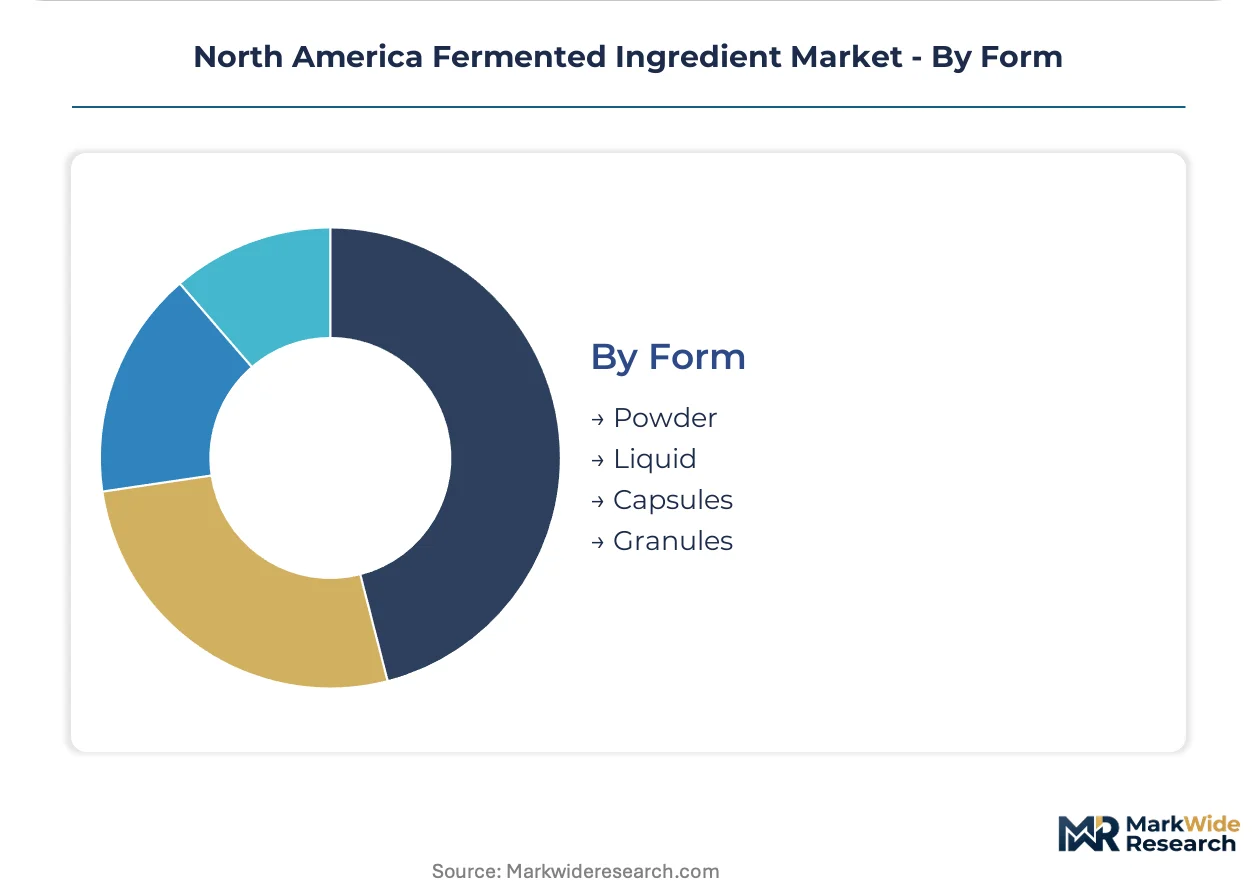
Form selection constrains logistics economics and stability requirements, with powder formats dominating bulk shipment while liquid forms enable just-in-time delivery.
- Powder:Spray-dried and drum-dried preparations with defined moisture specifications for extended shelf stability. Midwest corn syrup feedstock networks support bulk powder production, though EPA effluent guidelines are imposing capital-intensive treatment upgrades on manufacturing sites.
- Liquid:Aqueous suspensions and concentrates requiring cold chain or preservative systems. California beverage formulators prefer liquid enzymes for direct dosing integration, creating regional demand concentration.
- Capsules:Encapsulated probiotic and enzyme preparations for nutraceutical and pharmaceutical delivery.
- Granules:Agglomerated powder forms for controlled dissolution in food processing applications.
Primary shipment format: Powder. Regional preference divergence: Liquid in California versus Powder in Great Lakes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the United States and Canada, while Mexican demand growth outpaces domestic supply development. This geographic asymmetry creates cross-border trade dependencies and regulatory coordination challenges across the three markets.
United States
The Great Lakes dairy processing corridor spanning Wisconsin and Michigan generates concentrated demand for fermentation-derived enzymes and flavor modulators. FDA GRAS notification requirements govern strain safety validation for bioactive ingredients entering interstate commerce. California's functional food innovation cluster in the San Francisco Bay Area drives specification tightening for organic-certified yeast extracts and precision fermentation proteins.
Canada
Health Canada Novel Food Regulations mandate whole-genome sequencing documentation for novel microbial strains introduced after 2023. Several U.S.-based suppliers have established Vancouver satellite labs to accelerate pre-submission consultations with regulators. The Prairie Provinces support bulk fermentation feedstock production through extensive grain processing infrastructure serving North American markets.
Mexico
Clean-label beverage formulators in Mexico City and Guadalajara are expanding purchases of fermentation-derived proteins, creating underpenetrated demand for specialized ingredient suppliers. Mexican federal food safety regulations under COFEPRIS align with FDA frameworks while maintaining distinct import documentation requirements. The Bajío Region's growing food manufacturing base is attracting technical service investments from North American fermentation specialists.
North America Fermented Ingredient Market Competitive Landscape
Top-tier vendors anchor integrated strain-to-product platforms, while mid-tier specialists compete on technical service depth and regional feedstock access. The vendor base stratifies across three layers: multinational conglomerates controlling corn syrup networks and commercial-scale capacity; enzymatic technology leaders monetizing process optimization expertise; and regional culture suppliers serving dairy cooperative procurement functions. Dominant competitive moves include backward integration into proprietary strain development and multi-year service agreements embedding on-site process engineers.
Among European-headquartered conglomerates, BASF SE and DSM-Firmenich exemplify the integrated platform archetype spanning feedstock through finished bioactives. Novonesis occupies a distinct position anchoring enzymatic technology leadership through long-term technical service contracts. Cargill, Incorporated represents the feedstock-integrated scale operator controlling Midwest corn syrup networks that supply bulk fermentation output across the region.
| Leading Market Players |
|---|
| BASF SE |
| DSM-Firmenich |
| DuPont |
| Cargill, Incorporated |
| Novonesis |
| Chr. Hansen Holding A/S |
| Lallemand Inc. |
| Ajinomoto Co., Inc. |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Corn syrup futures volatility cascades through Midwest fermentation economics, compressing margins for bulk enzyme producers while amplifying pricing power for vertically integrated operators controlling captive feedstock supply.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade enzymes accelerates because precision fermentation scale-up is collapsing unit economics. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic-certified extracts from conventional grades and commodity spot offerings. Price differentiation rests on Health Canada whole-genome sequencing compliance and FDA GRAS notification status. Generic drug manufacturers exhibit acute price sensitivity, while California nutraceutical formulators absorb premiums for organic certification.
Supply Chain Analysis
USDA organic feedstock sourcing mandates are reshaping procurement patterns for premium-positioned product lines. Supply concentrates in the United States, Canada, and Mexico, with Midwest corn syrup networks anchoring bulk production capacity. Raw material dependencies center on dextrose feedstock, nitrogen sources, and pharmaceutical-grade filtration media. Single-source vulnerability pervades the Great Lakes corridor, where three agribusiness operators control regional dextrose supply. Distribution runs through technical service agreements embedding on-site process engineers at dairy cooperative facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strain development talent scarcity constrains capacity expansion across the United States and Canada, sustaining pricing power for incumbents with established microbial geneticist teams.
For Market Incumbents: Cement long-term technical service contracts with Great Lakes dairy cooperatives to lock out precision fermentation specialists seeking anchor accounts. Expand backward integration into proprietary strain development capabilities to offset FDA GRAS notification timeline compression. Prioritize Vancouver satellite lab investments to accelerate Health Canada pre-submission consultations before novel food sequencing mandates tighten further. For New Entrants and Emerging Players: Begin with underpenetrated Mexican beverage formulators in Mexico City and Guadalajara, where clean-label protein demand outpaces specialized supplier presence. Target first-mover positioning through fermentation-derived protein offerings tailored to COFEPRIS import documentation requirements. Pursue technical service partnerships with Bajío Region food manufacturers as a beachhead for regional expansion. For Investors and Strategic Acquirers: The window for entry favors enzymatic technology specialists with Health Canada regulatory navigation capabilities and established Vancouver consultation infrastructure. Five-to-ten-year viability hinges on consolidation of mid-tier culture suppliers serving dairy cooperative procurement functions. Monitor EPA effluent guideline implementation timelines as an inflection indicator for capital-intensive treatment upgrade burdens that will disadvantage smaller production sites.| Strategic Initiative | Industry Significance |
|---|---|
| Technical Service Contract Expansion | Embedding on-site process engineers at Wisconsin dairy cooperatives locks in multi-year revenue streams beyond commodity enzyme sales. |
| Vancouver Satellite Lab Establishment | Proximity to Health Canada accelerates whole-genome sequencing pre-submissions for novel microbial strains. |
| USDA Organic Feedstock Integration | Captive supply of certified organic dextrose secures 15-30% price premiums in California functional food channels. |
| Precision Fermentation Scale-Up | Unit cost compression for pharmaceutical-grade biocatalysts expands addressable demand from generic drug manufacturers. |
| Mexico Market Entry Partnership | Technical service investments in the Bajío Region establish regulatory navigation capabilities for COFEPRIS compliance. |
Research Methodology
Multi-period observation of FDA GRAS notification timelines, Health Canada Novel Food Regulation submission volumes, and EPA effluent guideline implementation progress anchored the trend analysis, supplemented by interviews with microbial geneticists, fermentation process engineers, dairy cooperative procurement directors, and pharmaceutical enzyme sourcing managers. Secondary validation drew from FDA GRAS notification databases, Health Canada Novel Food submissions, USDA organic certification records, and SEC 10-K disclosures from publicly traded ingredient suppliers. Bottom-up capacity modeling triangulated against top-down demand estimates from dairy processing corridor output data.
Segment-weighting approaches applied differential growth assumptions across yeast extracts, enzymes, bacterial cultures, and precision fermentation proteins, with additional weighting for organic certification status and pharmaceutical-grade versus food-grade specifications. CAGRs derived from installed capacity expansion schedules, strain validation pipeline visibility, and substitution elasticity estimates for synthetic processing aids. Forecast inputs incorporated EPA effluent treatment capital expenditure cycles and Mexican beverage formulation trend trajectories.
Underlying measurement precision varies by segment; enzyme and precision fermentation protein forecasts carry tighter precision than bacterial culture estimates due to more visible capacity expansion pipelines. Forecasts reflect assumptions regarding regulatory timeline stability, feedstock price volatility, and talent availability for strain development roles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Cetyl Palmitate Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Banana Powder Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
Resistant Dextrin Market
Food Additives and Ingredients
Africa Food Additives Market
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
South Africa Anti Caking Agents Market