
 Global Spray Polyurethanes Foam Market | 2026-2036
Global Spray Polyurethanes Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spray Polyurethanes Foam Market Foresight
Market Context
Modular insulation kits bundling spray foam with vapor barriers and sealants is hardening as the default procurement format for commercial contractors. BASF SE leverages its upstream isocyanate capacity to control input costs across regional blending operations. Dow Chemical Company anchors North American distribution through dedicated applicator networks. Huntsman Corporation differentiates via specialty catalyst formulations that shorten cure times in cold-weather installations.
Technical Definition and Segment Structure
Spray polyurethane foam is a thermoset cellular plastic formed by reacting polymeric methylene diphenyl diisocyanate with polyols, blowing agents, and surfactants at the point of application, typically achieving R-values of 6.0 to 7.0 per inch in closed-cell configurations. Its primary purpose is to create monolithic air barriers and thermal envelopes that eliminate convection losses in building assemblies. Closed cell foam commands the dominant margin pool due to its structural rigidity and moisture resistance in below-grade applications, while water-blown technology is gaining fastest as HFC phasedowns compress conventional blowing agent supply. Residential buildings represent the most mature end-user channel, with cold storage facilities emerging as the highest-growth vertical due to escalating cold chain infrastructure investment.
Regulatory Frame and Outlook
The EPA SNAP program and EU F-Gas Regulation are restricting hydrofluorocarbon blowing agents, compelling reformulation toward hydrofluoroolefins and water-blown systems across multinational supply chains. OSHA respiratory protection standards and REACH chemical registration requirements are elevating compliance costs for applicator certification and raw material documentation. Stakeholders must monitor evolving national building codes and carbon border mechanisms to anticipate which formulation platforms will retain market access across key jurisdictions.
Market Dynamics
The EPA SNAP program and EU F-Gas Regulation are forcing simultaneous reformulation of blowing agent chemistry across multinational supply chains, compressing legacy HFC-based product lines while elevating water-blown and hydrofluoroolefin platforms to commercial scale.
Growth Catalysts
- Cold chain infrastructure buildout:Food logistics operators in China and Germany are specifying closed-cell spray foam for new refrigerated warehouse construction, driven by pharmaceutical distribution requirements and perishable e-commerce volume.
- EU F-Gas Regulation phasedown:The progressive HFC quota reduction is compelling European applicators to retrain on low-GWP formulations, creating replacement demand for equipment and certified installation services.
- Retrofit mandates in existing building stock:Energy efficiency ordinances in New York City and San Francisco are triggering deep energy retrofits where spray foam air sealing satisfies blower door test requirements for compliance.
Market Restraints
- Isocyanate supply concentration:MDI production clusters in the US Gulf Coast and Rotterdam-Antwerp corridor create vulnerability to hurricane disruptions and European energy price spikes.
- OSHA respiratory protection enforcement:Heightened workplace exposure monitoring is extending project timelines and elevating contractor insurance costs for interior applications.
- Mineral wool substitution in fire-rated assemblies:Building code officials in California and Ontario are specifying non-combustible cavity insulation where thermal barriers cannot achieve required fire ratings.
Strategic Opportunities
- Data center thermal management:Hyperscale facility operators in Virginia and Frankfurt are trialing spray foam for precision air barrier control in mission-critical server halls.
- Indian cold storage deficit:The country's national cold chain infrastructure gap of approximately 25 million metric tons represents unmet demand for insulated envelope systems.
- Water-blown technology convergence with bio-based polyols:Formulators combining soy-derived polyol streams with water blowing are accessing green building certification premiums in Nordic markets.
Industry Challenges
- Certified applicator scarcity:The specialized equipment handling and chemical safety training required for SPF installation is constraining crew availability during peak construction seasons in Texas and Florida.
- Legacy building stock compatibility:Moisture management conflicts with historic masonry assemblies in Boston and Philadelphia are generating callbacks and warranty disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spray Polyurethanes Foam Market |
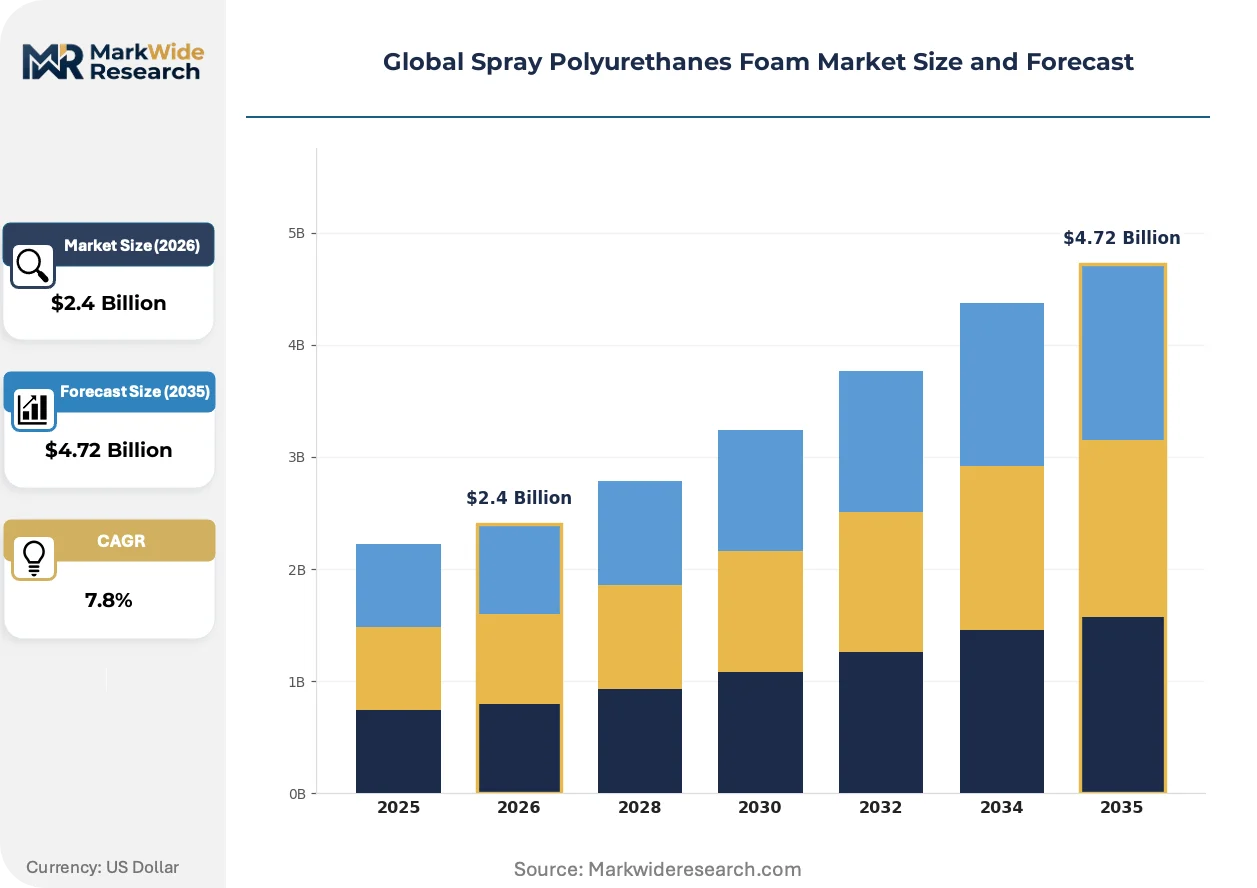
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Cell, Closed Cell, Hybrid, High Resilience Technology: Low Pressure, High Pressure, Catalyzed Systems, Water Blown, Solvent Blown Application: Construction Insulation, Refrigeration Panels, Acoustic Insulation, HVAC Systems, Packaging End User: Residential Buildings, Commercial Complexes, Cold Storage Facilities, Industrial Plants |
| Companies Covered | BASF SE, Dow Chemical Company, Huntsman Corporation, Covestro AG, Carlisle Companies Inc., Lapolla Industries, Bayer AG, NCFI Polyurethanes, Demilec USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spray Polyurethanes Foam Market Shifts & Advancements
Reformulation chemistry and installation methodology are evolving in parallel as regulatory deadlines compress product development cycles and contractor retraining windows.
Hydrofluoroolefin blowing agents are integrating into next-generation closed-cell formulations to achieve sub-10 GWP ratings while preserving R-value performance. Commercial roofing contractors in the United States are adopting these systems for compliance with state-level HFC prohibitions. The transition is integrating specialty chemical suppliers into direct technical service relationships with regional applicator networks, bypassing traditional distribution intermediaries.
The EU F-Gas Regulation's 2024 quota stepdown is accelerating product registration timelines for low-GWP alternatives across ECHA's REACH framework. Manufacturers are submitting expanded toxicological dossiers for HFO variants and water-blown catalyst systems. Cold storage engineering firms in Germany and the Netherlands are specifying only GWP-compliant foam in new tender documents, rejecting conventional HFC-based bids regardless of price.
Integrated insulation procurement is consolidating vapor barrier, air sealing, and thermal envelope specifications into single-source contractor agreements. National homebuilders in the United States are moving away from fragmented subcontractor models toward turnkey envelope packages. This pattern is most pronounced in the Sun Belt metro corridors where production volume and code stringency create procurement scale economies for bundled solutions.
Global Spray Polyurethanes Foam Market Segmentation
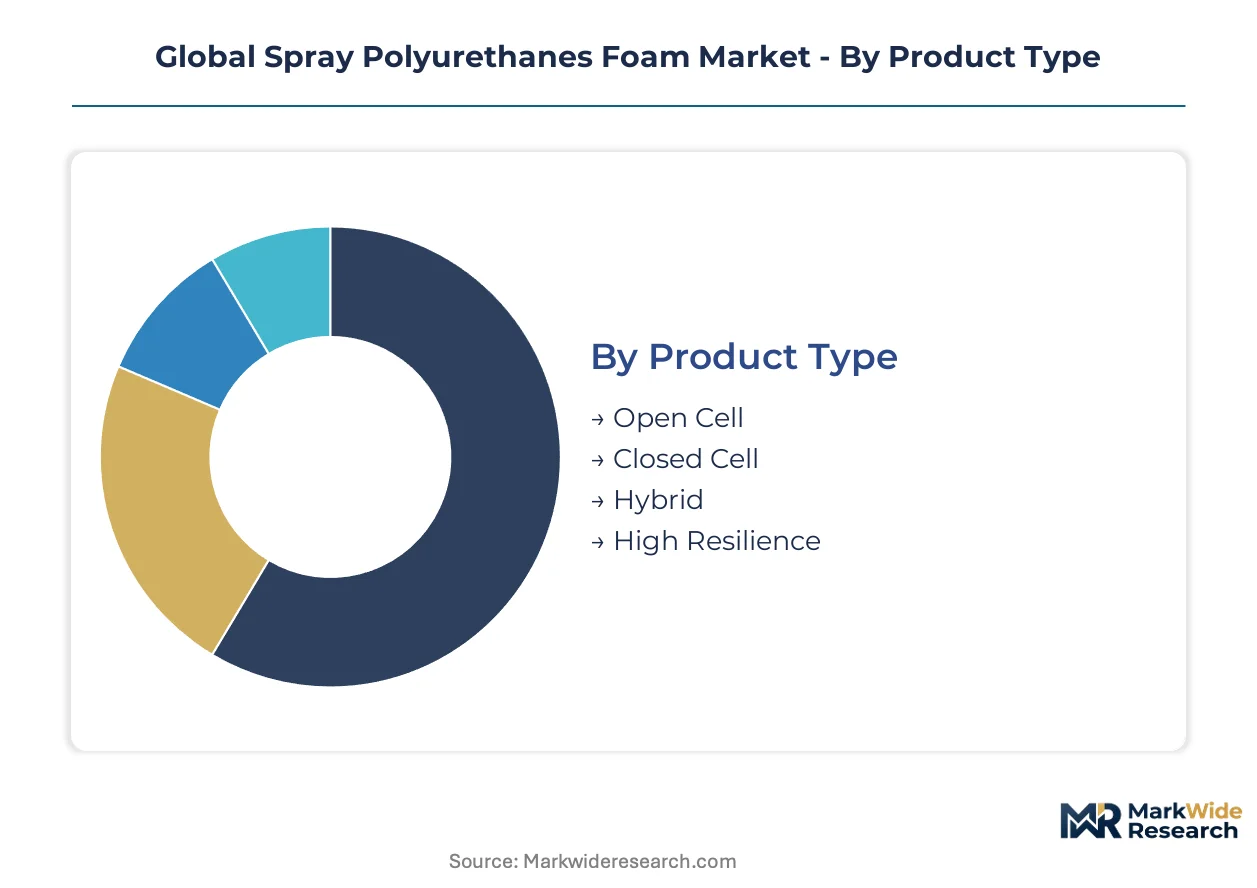
Spray polyurethane foam markets fragment across formulation chemistry, installation technology, and end-use thermal requirements. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning across multinational supply chains.
Product Type:
Supply concentration in isocyanate feedstocks funnels through distinct cellular architectures that determine thermal performance and structural load-bearing capacity.
- Closed Cell:Rigid thermoset structure with trapped gas cells delivers R-values of 6.0 to 7.0 per inch and vapor impermeability. Demand concentrates in below-grade commercial foundations across Germany and the US Gulf Coast, driven by moisture resistance mandates in ASHRAE 90.1 compliance paths.
- Open Cell:Lower density formulation with interconnected cells provides acoustic dampening and cost-effective air sealing at R-3.5 to R-4.0 per inch. Residential attic retrofits in Texas and Florida absorb volume, constrained by climate zone limitations on condensation risk.
- Hybrid:Dual-density systems combining open-cell base layers with closed-cell protective skins target complex envelope geometries in multi-family construction.
- High Resilience:Flexible cellular structures engineered for dynamic load applications in industrial cushioning and specialized packaging.
Closed Cell absorbs the bulk of installed capacity; Hybrid formulations are expanding most quickly in multi-family envelope specifications.
Technology:
Equipment capital requirements and formulation chemistry differentiate installation platforms by project scale and applicator certification tiers.
- High Pressure:Two-component metering systems delivering 1000+ psi reaction pressures achieve rapid cure times and superior cell structure. Commercial roofing contractors in the United States specify these systems for large-area applications, pressured by state-level HFC prohibitions requiring equipment compatibility with low-GWP formulations.
- Water Blown:Eliminates synthetic blowing agents entirely through carbon dioxide generation from isocyanate-water reactions. Nordic green building projects and EU F-Gas Regulation compliance pathways drive specification, despite 10-15% R-value penalty versus HFC benchmarks.
- Low Pressure:Portable dispensing equipment for residential retrofit and detail sealing work.
- Catalyzed Systems:Accelerated cure chemistry for cold-weather installation windows in northern climates.
- Solvent Blown:Legacy formulations declining under VOC emission restrictions.
High Pressure retains dominant equipment installed base; Water Blown technology is climbing the fastest as regulatory deadlines compress reformulation timelines.
Application:
Building code stringency and thermal performance specifications segment demand across envelope assemblies and industrial equipment.
- Construction Insulation:Monolithic air barrier and thermal envelope applications in walls, roofs, and foundations. Deep energy retrofits in New York City and San Francisco trigger volume, where blower door test requirements for Local Law 97 compliance specify spray foam air sealing.
- Refrigeration Panels:Insulated envelope systems for cold storage warehouses and refrigerated transport. Pharmaceutical distribution requirements and perishable e-commerce volume in China and Germany concentrate demand for closed-cell specifications with sub-0.05 perm vapor transmission.
- Acoustic Insulation:Open-cell applications in interior partition assemblies for sound transmission control.
- HVAC Systems:Duct sealing and equipment insulation in commercial mechanical spaces.
- Packaging:Protective foam-in-place systems for industrial and consumer goods shipping.
Construction Insulation commands the largest revenue pool; Refrigeration Panels demonstrate the steepest expansion trajectory from cold chain infrastructure investment.
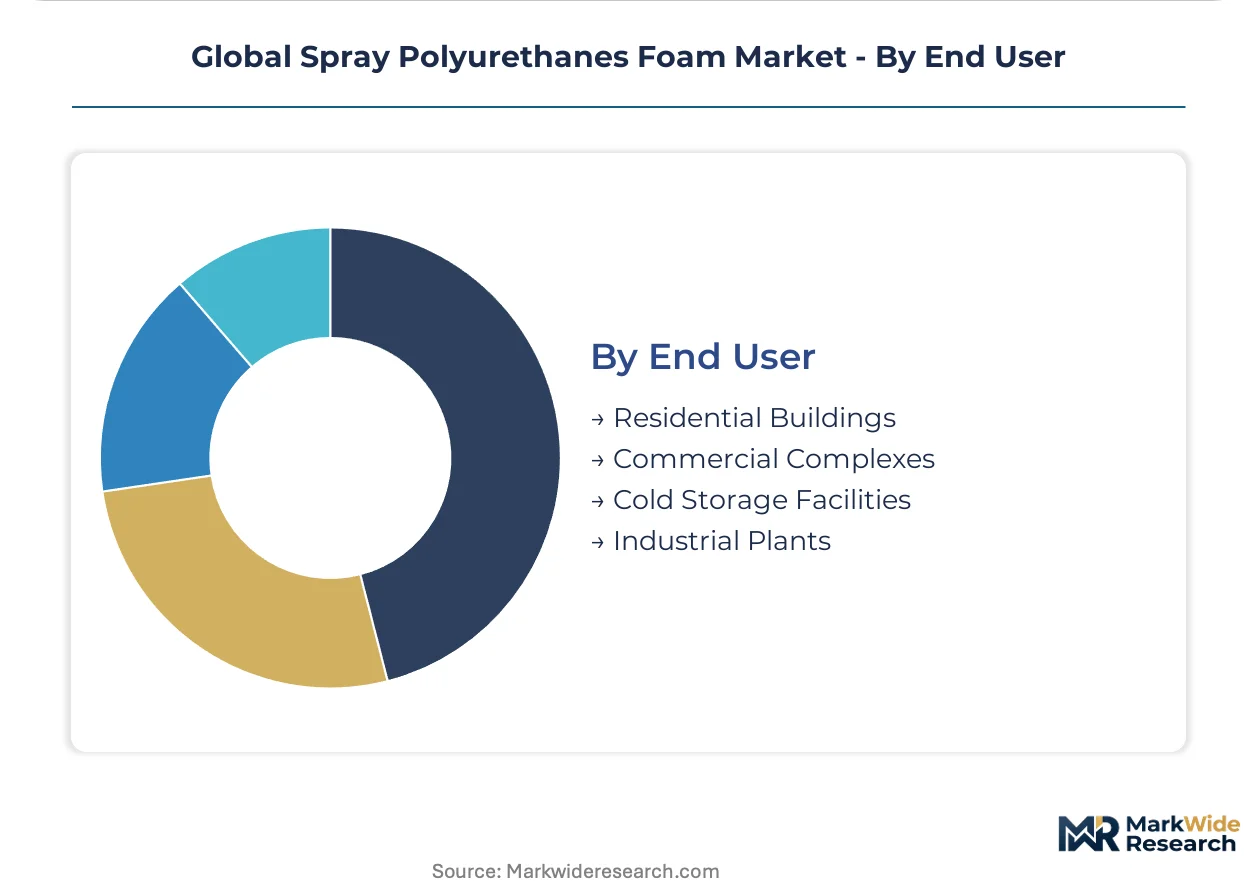
End User:
Procurement scale and specification authority concentrate across building ownership types with divergent risk tolerances and compliance obligations.
- Cold Storage Facilities:Refrigerated warehouses and distribution centers requiring continuous thermal envelope integrity. Engineering firms in Germany and the Netherlands reject HFC-based bids in tender documents regardless of price, compelled by EU F-Gas Regulation quota stepdowns and corporate carbon accounting.
- Commercial Complexes:Office, retail, and institutional buildings with professional facility management and capital planning cycles. National homebuilders in the US Sun Belt consolidate procurement through turnkey envelope packages, displacing fragmented subcontractor models.
- Residential Buildings:Single-family and multi-family housing with owner-driven or production builder procurement.
- Industrial Plants:Manufacturing facilities with process temperature control and equipment insulation requirements.
Cold Storage Facilities capture the fastest volume growth; Commercial Complexes retain the largest specification influence over national distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and Germany's Rhine-Ruhr corridor concentrate spray polyurethane foam manufacturing capacity through tax incentives and streamlined chemical permitting.
United States
Deep energy retrofits in New York City and San Francisco drive specification volume for Local Law 97 compliance. The EPA SNAP program restricts HFC blowing agents in commercial roofing applications. Gulf Coast MDI production clusters near Houston face hurricane disruption risks that compress regional supply availability.
Germany
Refrigerated warehouse construction for pharmaceutical distribution absorbs premium closed-cell formulations. The EU F-Gas Regulation's 2024 quota stepdown compels applicator retraining on hydrofluoroolefin systems. Engineering firms in the Netherlands and western Germany reject HFC-based bids in tender documents regardless of price.
China
Cold chain infrastructure gaps of approximately 25 million metric tons spur insulated envelope investment for perishable e-commerce. National dual carbon goals accelerate water-blown technology adoption in green building projects. Yangtze River Delta manufacturing zones concentrate polyol blending operations near Shanghai port facilities.
India
Post-harvest food loss reduction programs trigger cold storage construction across agricultural belts. The country's national building code adoption varies by state, creating fragmented specification standards. Gujarat and Maharashtra industrial corridors attract polyurethane system house investments for regional distribution.
Global Spray Polyurethanes Foam Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and installation service tiers. The market structure reflects moderate consolidation among isocyanate producers upstream and fragmentation among regional applicator networks downstream. Three strategic archetypes dominate: multinational chemical majors with captive feedstock supply, specialty system houses with formulation expertise, and turnkey envelope contractors with installation scale. Capacity expansion and geographic licensing agreements represent the dominant competitive moves as regulatory deadlines compress reformulation timelines.
Within the multinational chemical tier, BASF SE and Dow Chemical Company exemplify upstream-integrated positioning through isocyanate production control. Covestro AG occupies a specialty materials position reflecting its polyurethane-focused corporate structure. These three entities anchor competitive dynamics through raw material access and regional blending network coverage.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| Huntsman Corporation |
| Covestro AG |
| Carlisle Companies Inc. |
| Lapolla Industries |
| Bayer AG |
| NCFI Polyurethanes |
| Demilec USA Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between HFO-compliant and legacy HFC formulations splits procurement economics across the Global Spray Polyurethanes Foam Market, with premium pricing for low-GWP systems tied to Rotterdam-Antwerp MDI sourcing and compressed margins on conventional lines facing regulatory obsolescence.
Pricing Analysis
Expedited lead-time premiums attach to HFO-blown closed-cell formulations from certified European system houses, while spot-market discounts emerge for legacy HFC inventory in unconstrained jurisdictions. Project-based contracting dominates commercial roofing specifications, with price differentiation anchored in REACH registration tier and applicator certification level. Pricing pressure intensifies on water-blown systems as Nordic green building quotas expand, squeezing margins for undifferentiated commodity blenders. Cold storage engineering firms exhibit lowest price sensitivity, prioritizing GWP compliance over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from German refrigerated warehouse operators compel qualification across at least two MDI suppliers, typically drawing from US Gulf Coast and Rotterdam-Antwerp production clusters. Raw material dependencies center on polymeric methylene diphenyl diisocyanate, specialty polyols, and hydrofluoroolefin blowing agents. Hurricane disruption risk concentrates in Texas-Louisiana isocyanate capacity. Distribution runs through dedicated applicator networks anchored by multinational chemical majors with captive blending operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Spray Polyurethanes Foam Market consolidates around regulatory compliance capabilities, with EU F-Gas quota stepdowns and EPA SNAP enforcement eliminating undercapitalized regional blenders lacking reformulation infrastructure.
For Market Incumbents: Anchor market position through backward integration into HFO catalyst supply and captive MDI storage at Rotterdam-Antwerp hubs. Invest in applicator certification academies to constrain crew availability for competitors. Defend against mineral wool substitution in California fire-rated assemblies by accelerating intumescent coating compatibility programs.
For New Entrants and Emerging Players: Launch via water-blown technology partnerships targeting India's 25 million metric ton cold storage deficit. Penetrate Gujarat and Maharashtra industrial corridors where state-level building code adoption lags national standards. Pursue turnkey envelope procurement contracts with perishable e-commerce logistics operators seeking bundled insulation-vapor barrier solutions.
For Investors and Strategic Acquirers: Re-rating potential sits with specialty system houses possessing ECHA-registered HFO formulations given the EU F-Gas Regulation's progressive quota compression. Long-term viability favors assets with demonstrated low-GWP commercial scale and established technical service relationships with cold storage engineering firms. Monitor tender document language in Germany and the Netherlands for inflection signals on HFC bid rejection rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New blending facilities in Yangtze River Delta zones reduce lead times for Chinese cold chain projects. |
| Backward Integration | Captive MDI storage at Houston and Rotterdam hubs buffers hurricane and energy price disruption exposure. |
| Green Manufacturing Transition | Water-blown systems with bio-based polyols access Nordic green building certification premiums. |
| Long-term Supply Agreement | Fixed-price HFO blowing agent contracts lock in formulation costs ahead of regulatory quota stepdowns. |
| Joint Venture | Regional licensing partnerships accelerate applicator network coverage in underpenetrated Indian agricultural belts. |
Research Methodology
Document review covered ECHA REACH registration databases, EPA SNAP rulemaking dockets, and EU F-Gas Regulation quota allocation records, complemented by interviews with polyurethane system house technical directors, commercial roofing contractor procurement leads, cold storage facility engineering consultants, and German refrigeration panel OEMs. Secondary validation drew from Cefic chemical production statistics, USITC trade flow data, and SEC 10-K disclosures from listed chemical majors. Bottom-up volume modeling triangulated against top-down macroeconomic elasticity estimates across the analysis window.
Historical volume trajectories were cross-referenced against expert panel inputs from regional applicator networks. The analytical framework modeled demand across formulation chemistry, installation technology, and end-use thermal requirements, with additional segmentation by regulatory compliance tier. CAGRs were derived from elasticity-adjusted projection algorithms incorporating cold chain infrastructure investment pipelines and building code stringency indices. Industry-specific inputs included HFC phasedown timelines and certified applicator training capacity constraints.
The model assumes a particular technology adoption path for hydrofluoroolefin and water-blown systems; alternative pathways involving accelerated electrochemical blowing agent innovation would alter the outlook. Forecasts reflect assumptions on regulatory enforcement consistency and MDI supply continuity. Deviation in EU F-Gas quota allocation severity or Gulf Coast hurricane frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Specialty Plasticizer Market
Specialty Chemicals
Copovidone Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
Global Tetrakis (Hydroxymethyl) Phosphonium Sulfate Market
Specialty Chemicals
Sodium Hyaluronate Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Organometallics Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Rosin Market