
 Low-Calorie Savoury Snacks Market | 2026-2036
Low-Calorie Savoury Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Savoury Snacks Market Analytics
Plant-based protein isolates from pea and fava beans is recalibrating cost structures across extruded snack lines. PepsiCo leverages its North American salty-snack infrastructure to control ingredient sourcing at scale. Nestle anchors its portfolio reformulation through proprietary air-popping technologies that cut oil content without texture loss. Mondelez International competes in the premium cracker segment through European bakery expertise adapted to reduced-fat recipes.
Low-calorie savoury snacks are formulated products containing fewer than 150 kilocalories per standard serving, typically achieved through reduced oil absorption, alternative base materials such as dehydrated vegetables or pulse flours, and controlled moisture content below 4 percent to preserve shelf stability without preservative loading. Their primary commercial purpose is to deliver satiety and flavor satisfaction within self-imposed dietary constraints. Chips dominate volume through established manufacturing amortization, though veggie sticks represent the fastest-expanding margin pool as refrigerated produce supply chains integrate with snack packaging lines. Single-serve packs command premium shelf placement in convenience channels, while resealable bags capture repeat-purchase households seeking portion discipline.
The FDA enforces serving-size alignment with actual consumption patterns, compelling label transparency that redirects R&D spending toward verifiable calorie reduction. EFSA evaluates novel food ingredient petitions for pulse-derived bases, creating a two-track approval environment that advantages established multinationals with dedicated regulatory affairs capacity. The EU Green Deal packaging waste directives pressure migration from multi-layer films to mono-material or paper-based alternatives, altering barrier-property requirements for shelf-stable low-fat formulations. Stakeholders must monitor how front-of-pack scoring systems in France and the United Kingdom recalibrate consumer willingness-to-pay across flavor and format combinations.
Market Dynamics
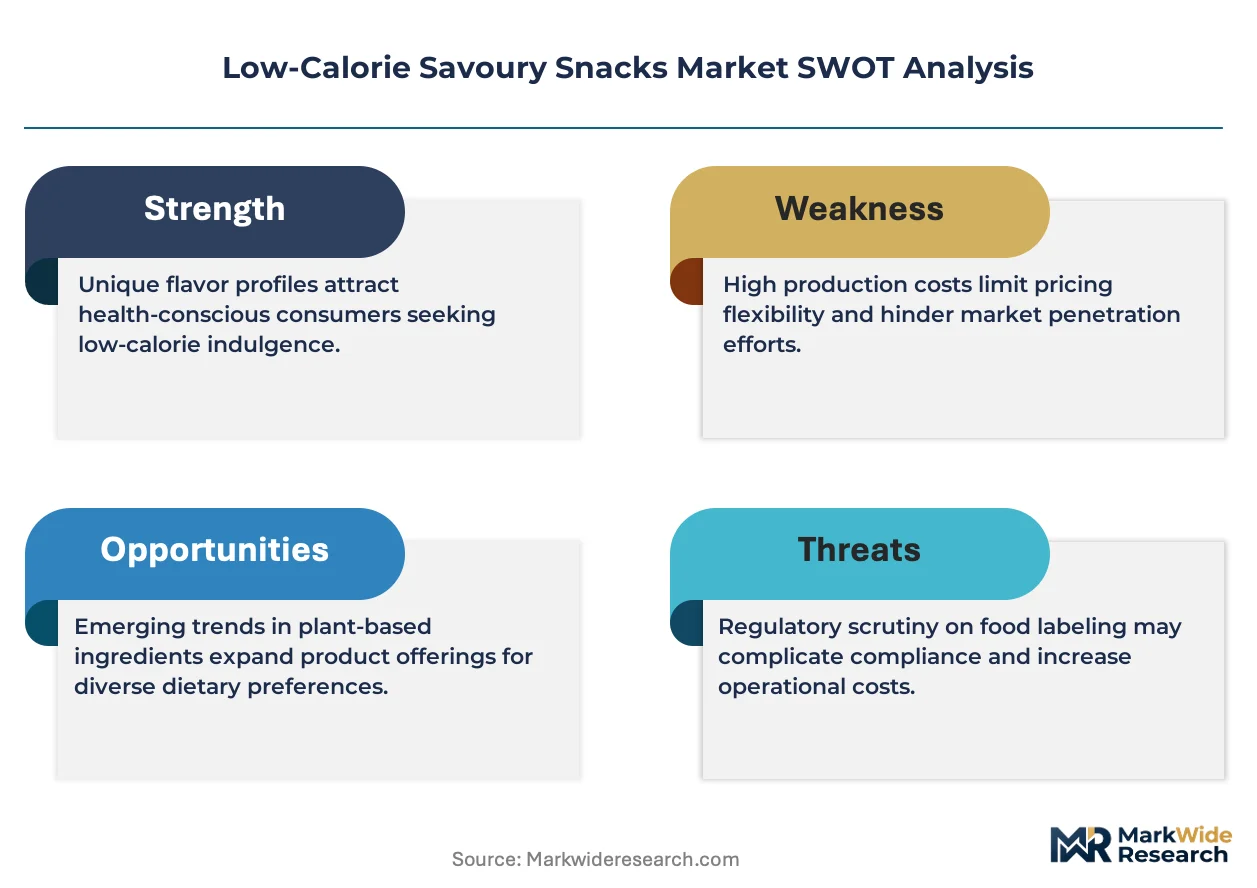
Front-of-pack labeling mandates across multiple jurisdictions are forcing simultaneous reformulation of sodium, fat, and calorie profiles while maintaining palatability thresholds that drive repeat purchase.
Growth Catalysts
- EU Green Deal packaging directives:Mono-material and paper-based barrier innovations open shelf-stable formats previously reserved for multi-layer plastics, expanding addressable retail channels for low-fat extruded products.
- Pulse flour extrusion:Pea and fava bean protein isolates enable clean-label protein fortification without allergen warnings that constrain soy-based alternatives in school and workplace channels.
- Urban millennial workforce clusters:Dense office districts in the United States sustain subscription-box economics for portion-controlled single-serve packs that bypass traditional convenience-store markup structures.
Market Restraints
- Edible oil price volatility:Sunflower and rapeseed oil input costs fluctuate with Black Sea supply disruptions, compressing margins on air-popped lines that still require light oil coating for flavor adherence.
- Refrigerated produce supply chain concentration:Fresh vegetable stick processing depends on California and Arizona growing belts, creating climate-driven volume risk for the fastest-expanding margin segment.
- Moisture barrier technical ceiling:Sub-4% moisture targets for shelf stability without preservatives conflict with consumer texture preferences for "baked-not-fried" positioning in premium tiers.
Strategic Opportunities
- Direct-to-consumer cold chain integration:Refrigerated last-mile networks originally built for meal-kit delivery now accommodate fresh-cut vegetable snacks with 14-day shelf windows, unlocking household penetration beyond convenience retail.
- FDA serving-size alignment rules:Updated consumption-pattern baselines create first-mover advantage for brands that reformulate to verifiable sub-150 kcal thresholds before enforcement deadlines tighten.
- Air-popping and infrared drying convergence:Hybrid thermal processing cuts oil absorption below 8% by weight while preserving Maillard reaction depth previously achievable only through deep frying.
Industry Challenges
- Clean-label R&D talent scarcity:Formulation chemists capable of balancing sensory thresholds with reduced sodium and fat targets command premium compensation in competitive food science labor markets.
- EFSA novel food petition timelines:Pulse-derived ingredient approvals average 18-24 months, advantaging multinationals with dedicated regulatory affairs capacity over mid-tier competitors.
- Legacy extrusion equipment retrofit costs:Transitioning from fried to air-popped lines requires capital-intensive die and airflow system replacements that strain balance sheets below $50 million revenue scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Savoury Snacks Market |
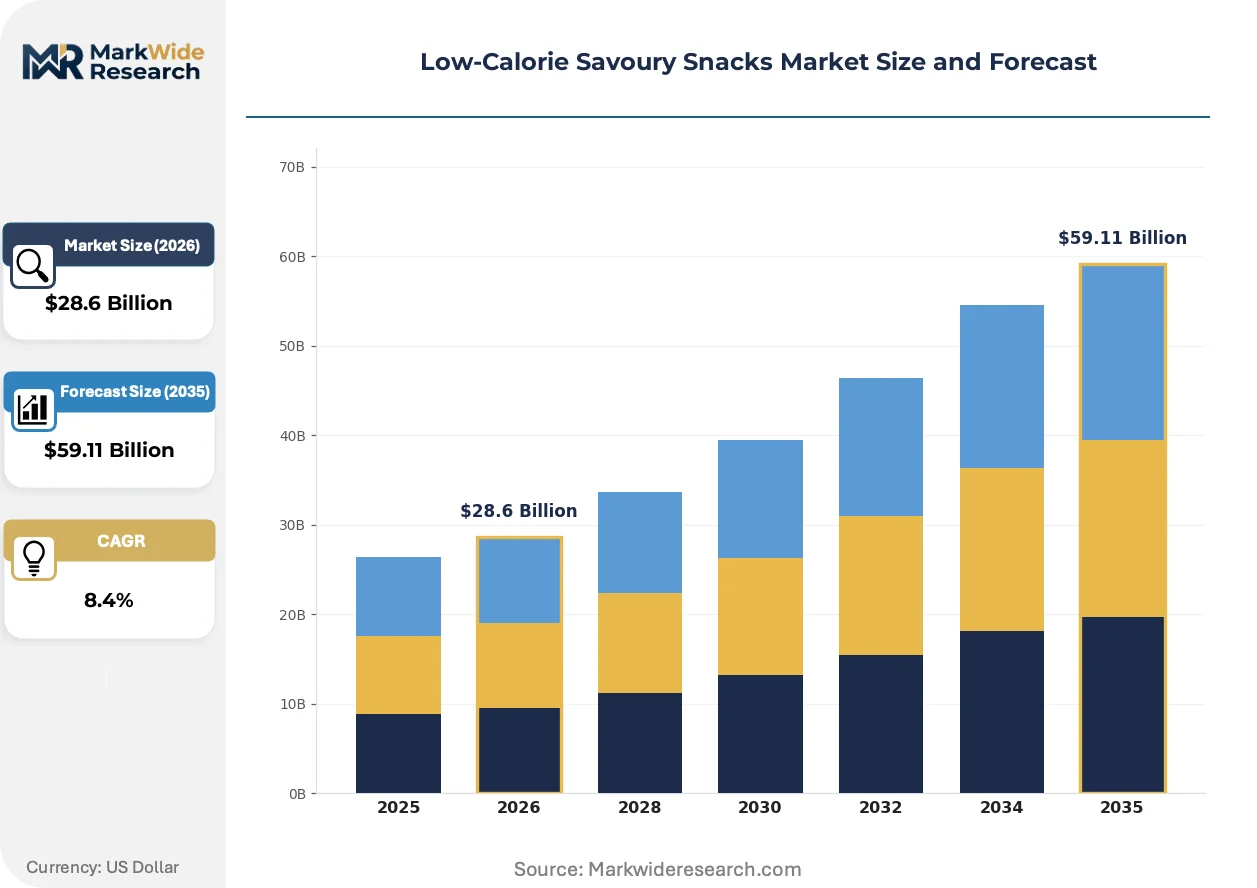
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Crackers, Pretzels, Veggie Sticks Flavor Profile: Spicy, Savory, Cheesy, Barbecue Packaging Type: Single-Serve Packs, Family Packs, Bulk Bags, Resealable Bags Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Health Food Stores |
| Companies Covered | PepsiCo, The Kraft Heinz Company, Nestle, General Mills, Mondelez International, Conagra Brands, Danone, Kellogg's, Calbee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Savoury Snacks Market Evolving Landscape
Active reformulation is compressing traditional category boundaries between shelf-stable chips, refrigerated produce, and protein-fortified alternatives. Three converging forces are redrawing competitive terrain.
Infrared-assisted air-popping is rewriting cost structures for oil-free texture delivery. Equipment manufacturers in Germany and Italy are shipping hybrid thermal systems that combine radiant heat with forced convection to achieve surface browning without lipid contact. Mid-tier North American contract manufacturers are adopting these lines to serve private-label retailers demanding clean-label credentials. The technology is compressing the premium gap between extruded puffs and traditional fried chips.
Front-of-pack traffic-light schemes in France and the United Kingdom are recalibrating R&D prioritization. Nutri-Score and equivalent labeling systems penalize sodium and saturated fat more aggressively than absolute calorie content, redirecting formulation resources toward salt replacers and oil substitution rather than simple portion reduction. European bakery-adjacent snack lines face particular pressure given their historical reliance on butter and cheese powders for flavor delivery.
Workplace micro-market vending is displacing traditional convenience-store distribution for better-for-you positioning. Employers in United States tech and finance clusters install refrigerated self-service units that bypass the 40-50% retail markup endemic to C-store channels. Fresh vegetable stick suppliers capture household penetration through corporate wellness subsidies that offset per-unit premiums. This channel rotation is most visible in Austin, Seattle, and Boston metropolitan corridors where employer density supports route economics.
Low-Calorie Savoury Snacks Market Segmentation
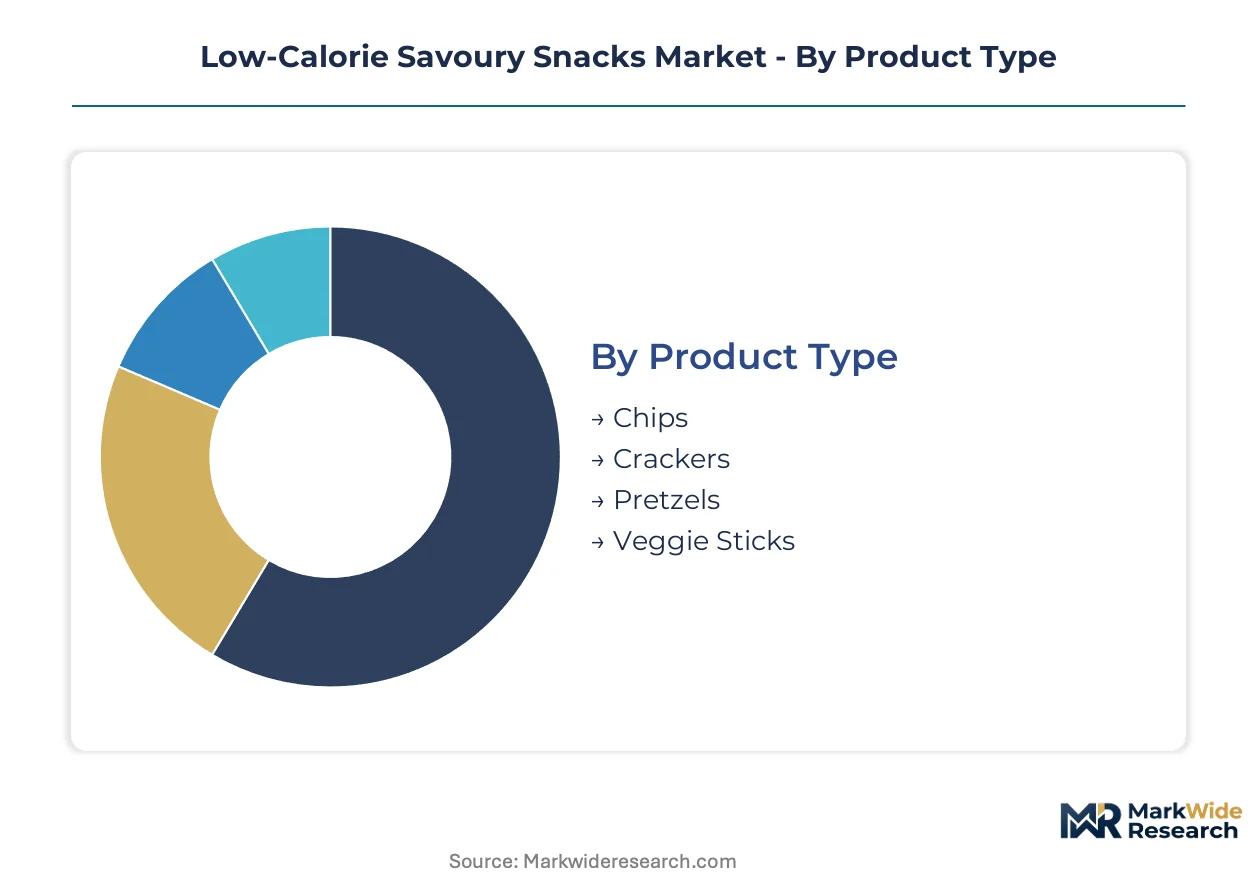
Segmentation in low-calorie savoury snacks reveals how capital deployment, regulatory exposure, and channel economics fragment competitive returns. Manufacturers must align extrusion technology, barrier packaging investments, and cold-chain capabilities against distinct margin pools.
Product Type:
Capital intensity varies sharply across extrusion methods, with frying-to-air-popping retrofits demanding the heaviest balance-sheet commitments.
- Chips:Extruded or thin-sliced potato and pulse bases dominate volume through amortized frying and air-popping lines. United States convenience-store penetration sustains single-serve economics, though oil-input volatility compresses margins on legacy fried formats.
- Veggie Sticks:Fresh-cut and dehydrated vegetable formats require refrigerated supply chain integration or sub-4% moisture targets for shelf stability. California and Arizona growing belt concentration creates climate-driven volume risk for this fastest-expanding margin pool.
- Crackers:European bakery-adjacent expertise anchors reduced-fat recipes through controlled lamination and infrared finishing.
- Pretzels:Alkaline-cooked wheat bases occupy mid-tier positioning with lower protein-fortification potential than pulse alternatives.
Most installed capacity flows through Chips. Expansion is steepest in Veggie Sticks.
Flavor Profile:
Reformulation costs concentrate in sodium reduction and clean-label seasoning systems, with spicy profiles facing fewer technical barriers than cheese analogues.
- Spicy:Capsicum and pepper-based heat delivery achieves clean-label positioning without sodium-heavy flavor enhancers. United States millennial clusters in Austin and Seattle metropolitan corridors drive workplace micro-market adoption through employer wellness subsidies.
- Cheesy:Nutritional yeast and fermented dairy powders face Nutri-Score penalties in France and the United Kingdom, redirecting R&D toward enzymatic flavor precursors and lipid-coated release systems.
- Savory:Herb and umami blends from mushroom and seaweed extracts align with EFSA novel food petition pathways for emerging ingredient suppliers.
- Barbecue:Molasses and smoke flavoring systems carry higher sugar loading that conflicts with front-of-pack traffic-light scoring in EU jurisdictions.
Reformulation investment concentrates in Cheesy. Clean-label migration is advancing most quickly in Spicy.
Packaging Type:
Barrier-property requirements under EU Green Deal directives are forcing capital redeployment from multi-layer films toward mono-material alternatives.
- Single-Serve Packs:Portion-controlled formats command premium shelf placement in convenience channels and sustain subscription-box economics for United States urban office clusters. Individual unit economics depend on high-speed form-fill-seal lines with nitrogen-flush capabilities.
- Resealable Bags:Zipper and adhesive closure systems capture repeat-purchase households seeking portion discipline, with mono-material zipper integration posing technical hurdles for legacy equipment.
- Family Packs:Mid-size formats balance per-ounce value positioning against warehouse club distribution requirements.
- Bulk Bags:Foodservice and institutional channels demand extended shelf stability without retail-grade barrier investments.
Equipment utilization peaks on Single-Serve Packs. Regulatory pressure is intensifying fastest on Resealable Bags.
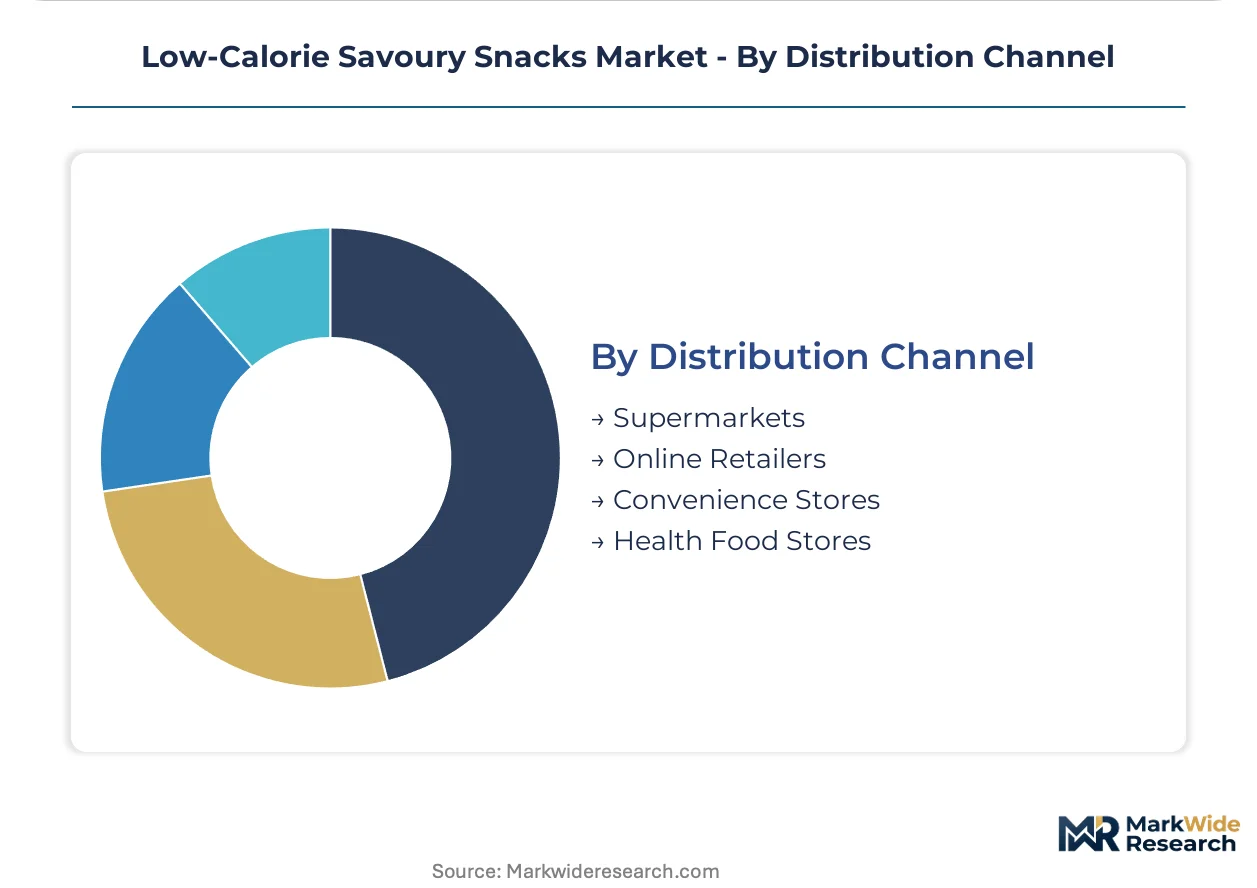
Distribution Channel:
Route economics and margin capture diverge sharply between refrigerated last-mile networks and ambient shelf-stable logistics.
- Convenience Stores:Impulse-driven velocity sustains 40-50% retail markups that compress manufacturer margins, with premium placement fees for better-for-you positioning. United States C-store penetration remains the reference channel for single-serve trial conversion.
- Online Retailers:Direct-to-consumer subscription models bypass traditional markup structures, leveraging refrigerated last-mile networks originally built for meal-kit delivery to reach household penetration beyond convenience retail.
- Supermarkets:Planogram negotiations and slotting fees favor multinationals with trade promotion budgets and front-of-pack label optimization for Nutri-Score and equivalent systems.
- Health Food Stores:Curated assortment and educated consumer base support premium pricing for clean-label and organic certified lines with limited scale.
Volume concentration sits with Supermarkets. Margin expansion is climbing the fastest in Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston metropolitan corridor anchors workplace micro-market penetration for fresh vegetable stick distribution, with employer wellness subsidies accelerating refrigerated snack adoption in dense office clusters across the United States, Germany, and the United Kingdom.
United States
Austin and Seattle tech corridors sustain subscription-box economics for portion-controlled single-serve packs that bypass traditional convenience-store markup structures. FDA serving-size alignment rules compel label transparency that redirects R&D spending toward verifiable sub-150 kcal thresholds. California and Arizona growing belts concentrate fresh vegetable processing capacity, creating climate-driven volume exposure for the fastest-expanding margin segment.
Germany
Equipment manufacturers in Bavaria and Baden-Württemberg ship hybrid thermal air-popping systems that combine radiant heat with forced convection to achieve surface browning without lipid contact. EU Green Deal packaging waste directives pressure migration from multi-layer films to mono-material alternatives, altering barrier-property requirements for shelf-stable low-fat formulations. Frankfurt and Munich workplace clusters drive corporate wellness program adoption of refrigerated vending formats.
United Kingdom
Front-of-pack Nutri-Score equivalent schemes penalize sodium and saturated fat more aggressively than absolute calorie content, redirecting formulation resources toward salt replacers and oil substitution. London metropolitan employers install refrigerated self-service units that bypass 40-50% retail markups endemic to convenience channels. Birmingham and Manchester logistics hubs integrate cold-chain networks originally built for meal-kit delivery to accommodate fresh-cut vegetable snacks with 14-day shelf windows.
France
Paris and Lyon metropolitan corridors sustain premium cracker demand through European bakery expertise adapted to reduced-fat recipes. ANSM evaluates novel food ingredient petitions for pulse-derived bases, creating regulatory timelines that advantage established multinationals with dedicated regulatory affairs capacity. Île-de-France workplace micro-markets displace traditional convenience-store distribution for better-for-you positioning through employer wellness subsidies.
Japan
Tokyo and Osaka urban density supports convenience-store penetration for single-serve low-calorie savoury formats with established manufacturing amortization. METI standards for processed food labeling create transparency requirements that align with clean-label migration trends. Kanto region extrusion technology specialists develop infrared-assisted drying systems that cut oil absorption below 8% by weight while preserving Maillard reaction depth.
Low-Calorie Savoury Snacks Market Competitive Landscape
Global majors compete with regional champions across reformulation technology and cold-chain integration, with the vendor base stratifying between scale-driven multinationals and mid-tier specialists. The market exhibits tiered concentration: dominant players control North American salty-snack infrastructure and European bakery expertise, while contract manufacturers serve private-label demand. Two strategic archetypes predominate: integrated multinationals with captive regulatory affairs capacity, and agile mid-caps exploiting refrigerated last-mile networks. Competitive moves center on portfolio diversification into pulse-based protein fortification and backward integration into ingredient sourcing.
Within the integrated multinational tier, PepsiCo, Nestle, and Mondelez International exemplify divergent strategic positioning. PepsiCo occupies a position anchored in North American distribution infrastructure at scale. Nestle represents European-led reformulation capabilities through proprietary processing technologies. Mondelez International sits within the premium bakery-adjacent segment leveraging continental European expertise. These three entities collectively illustrate how regulatory capacity, manufacturing technology, and geographic footprint determine competitive returns in front-of-pack labeling environments.
| Leading Market Players |
|---|
| PepsiCo |
| The Kraft Heinz Company |
| Nestle |
| General Mills |
| Mondelez International |
| Conagra Brands |
| Danone |
| Kellogg's |
| Calbee |
| Others |
Value Network & Pricing Analysis
Formulation chemists capable of balancing sensory thresholds with reduced sodium and fat targets cluster in the United States Midwest and Bavaria, with labor-cost differentials between these hubs widening the spread between premium clean-label tiers and economy fried formats. This geographic concentration of technical talent feeds directly into pricing-tier stratification, as manufacturers in higher-cost jurisdictions capture margin through proprietary air-popping and infrared-drying patents while contract manufacturers in lower-cost regions compete on volume throughput.
Pricing Analysis
Input-cost pass-through from sunflower and rapeseed oil volatility compresses margins on legacy fried lines, while air-popped and extruded alternatives absorb less commodity exposure. Pricing stratifies across premium, standard, and economy tiers, with clean-label certification and proprietary thermal processing commanding the widest spreads. Price erosion runs through the standard tier as private-label retailers consolidate procurement. Foodservice buyers exhibit highest price sensitivity, while direct-to-consumer subscribers accept per-unit premiums for portion-controlled formats.
Supply Chain Analysis
EU Green Deal domestic-content mandates for mono-material packaging are reshaping sourcing toward European barrier-film suppliers and away from Asian multi-layer producers. Raw material supply concentrates in the United States for pulse flours, Germany for hybrid thermal processing equipment, and the Netherlands for modified-atmosphere packaging films. Sunflower oil sourcing draws from Black Sea origins, creating tariff-exposure risk for coating-dependent lines. Distribution runs through refrigerated last-mile networks originally built for meal-kit delivery, now repurposed for fresh vegetable sticks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between the United States, where FDA serving-size alignment rules create first-mover advantages for sub-150 kcal reformulation, and the European Union, where EFSA novel-food petition timelines advantage established multinationals with captive regulatory capacity.
For Market Incumbents: Hedge against edible oil price volatility through backward integration into pulse-flour milling and long-term offtake agreements with Bavarian equipment suppliers. Defend margin position by accelerating proprietary air-popping patent filings before hybrid thermal systems commoditize. Prioritize regulatory affairs capacity expansion in Brussels to compress EFSA petition timelines for pea and fava bean protein isolates. For New Entrants and Emerging Players: FDA serving-size alignment rules in the United States open a window for mid-tier brands that achieve verifiable sub-150 kcal thresholds before enforcement deadlines tighten. Target workplace micro-market vending in Austin and Seattle metropolitan corridors, where employer wellness subsidies offset per-unit premiums. Pursue direct-to-consumer cold-chain integration leveraging refrigerated last-mile networks originally built for meal-kit delivery. For Investors and Strategic Acquirers: Contract manufacturers with hybrid thermal air-popping lines are the most active acquirer targets in this space, as private-label retailers consolidate supply bases. Long-term viability hinges on exposure to the refrigerated produce segment, where climate-driven volume risk creates cyclical entry points. Watch EFSA novel-food approval velocity as the inflection indicator for pulse-protein ingredient economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulse-Flour Milling | Captive supply of pea and fava bean isolates insulates margins from Black Sea oil volatility. |
| Hybrid Thermal Processing Patent Filings | Infrared-assisted air-popping differentiation compresses before equipment manufacturers commoditize. |
| Direct-to-Consumer Cold-Chain Launch | Refrigerated last-mile networks unlock household penetration beyond convenience-store markups. |
| EFSA Regulatory Affairs Capacity Expansion | Dedicated Brussels presence compresses 18-24 month novel-food timelines versus mid-tier competitors. |
| Workplace Micro-Market Route Buildout | Corporate wellness subsidies in Austin and Seattle offset per-unit premiums for fresh vegetable sticks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulation chemists, regulatory affairs directors at multinationals, category buyers at United States convenience-store chains, and cold-chain logistics operators with secondary validation against FDA enforcement guidance documents, EFSA novel-food petition databases, EU Green Deal packaging directive drafts, and Nielsen retail audit data. Bottom-up segment sizing and top-down macro constraint checks triangulated volume and value estimates.
Historical reference periods anchored the projection horizon to pre-pandemic baseline consumption patterns and post-reformulation adoption curves across the analysis window. The analytical framework modeled product type, flavor profile, packaging format, distribution channel, and thermal processing technology as core segmentation dimensions. CAGRs derived from fitted adoption curves for air-popping and infrared-drying equipment penetration, cross-referenced with pulse-flour supply expansion timelines and workplace micro-market installation rates.
Revisions become necessary when EFSA accelerates or delays novel-food approvals, when California-Arizona growing belt conditions disrupt fresh vegetable supply, or when EU Green Deal packaging enforcement timelines shift. Forecasts reflect documented assumptions about clean-label R&D talent availability and edible oil price trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Spicy Sticks (Chinese Snack) Market
Snacks
Crackers Market
Snacks
Middle East and Africa Snack Pellets Market
Snacks
Super Low Calorie Snacks Market
Snacks
Dairy Protein Crisps Market
Snacks
Fried Potato Chips Market
Snacks
Snack Subscription Market
Snacks
Organic Snack Food Market
Snacks
South America Snack Bar Market
Snacks
Southeast Asia Savory Snacks Market
Snacks
Crispy Fruit Chips Market
Snacks
High Fiber Snack Foods Market
Snacks
High Carb Low Fat Snack Market
Snacks
Germany Snack Bar Market
Snacks
Mediterranean Lentil Crisps and Inclusion Bases Market
Snacks
Pretzels (Savory Snacks) Market