
 RTE Popcorn Market | 2026-2036
RTE Popcorn Market Size, Share, and Industry Trends Forecast 2026-2036
RTE Popcorn Market Outlook
Multi-source ingredient procurement is realigning how RTE popcorn manufacturers secure corn supply and flavor inputs. Conagra Brands Inc. leverages its frozen-foods distribution backbone to place RTE popcorn in mainstream retail freezers and ambient aisles simultaneously. PepsiCo Inc. anchors its snack portfolio through Frito-Lay's convenience-store dominance, while Quinn Foods LLC differentiates via non-GMO and organic ingredient credentials that command premium placement in natural-channel grocers.
Ready-to-eat popcorn consists of pre-popped corn kernels processed through hot-air expansion or oil-popped methods, then seasoned and packaged in moisture-barrier materials to maintain crunch over shelf lives of six to twelve months. The product serves as a portable, portion-controlled snack alternative to chips and crackers in both impulse and planned-purchase occasions. Caramel and cheese variants within the flavor profile capture the highest margin pools due to ingredient complexity and consumer willingness to pay for indulgent positioning. Pouch packaging formats are gaining velocity over rigid tubs in online and convenience channels where shipping economics and shelf-space efficiency favor flexible materials.
FDA nutrition-labeling rules and EPA emissions standards for food-manufacturing facilities shape operational compliance costs and reformulation timelines across U.S. production sites. State-level extended producer responsibility frameworks in California and New York are pressuring brands to redesign multilayer packaging into recyclable mono-material structures. Stakeholders must monitor how regulatory timelines for packaging recyclability intersect with consumer price sensitivity in private-label versus branded purchasing decisions.
Market Dynamics
Extended producer responsibility frameworks in California and New York are forcing RTE popcorn manufacturers to abandon multilayer flexible packaging in favor of recyclable mono-material structures before 2030 deadlines.
Growth Catalysts
- Streaming-service household expansion:Cineplex operators and at-home entertainment consumers are building permanent snack pantries, creating recurring purchase rhythms for pre-popped formats in ambient and freezer aisles.
- FDA whole-grain labeling pathways:Reformulated products qualifying for whole-grain health claims capture premium shelf positioning and reimbursement-adjacent placement in workplace and institutional channels.
- Hot-air expansion technology:Oil-free popping methods reduce saturated fat content while extending shelf stability, enabling clean-label positioning in natural-channel grocers.
Market Restraints
- Midwest corn supply concentration:Drought vulnerability across Iowa and Illinois growing regions creates input cost volatility and quality inconsistency for non-GMO and organic contract requirements.
- Multilayer packaging technical lock-in:Existing moisture-barrier films combining polyethylene and metallized layers resist mechanical recycling under current municipal infrastructure.
- Cheese powder import dependency:Specialty dairy flavor inputs concentrate in Wisconsin and California processing facilities, exposing margin compression from regional labor shortages.
Strategic Opportunities
- California EPR compliance lead:First-mover brands redesigning pouch structures for curbside recyclability secure preferential placement in Kroger and Albertsons chains ahead of 2027 enforcement.
- Convenience-store cooler expansion:Refrigerated RTE popcorn formats targeting fresh-perception positioning capture impulse traffic in 7-Eleven and Circle K locations.
- Dual carbon goals alignment:China SAMR low-carbon manufacturing incentives create export pathways for U.S. producers with verified Scope 3 reductions in agricultural inputs.
Industry Challenges
- Packaging engineer scarcity:Limited talent pools for mono-material barrier design delay reformulation timelines and raise R&D wage pressure.
- Legacy equipment retooling capex:Vertical form-fill-seal machines require seven-figure replacement investments to handle new film structures without speed degradation.
- Organic certification audit backlog:USDA accredited body capacity constraints extend supply chain verification timelines for non-GMO ingredient claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RTE Popcorn Market |
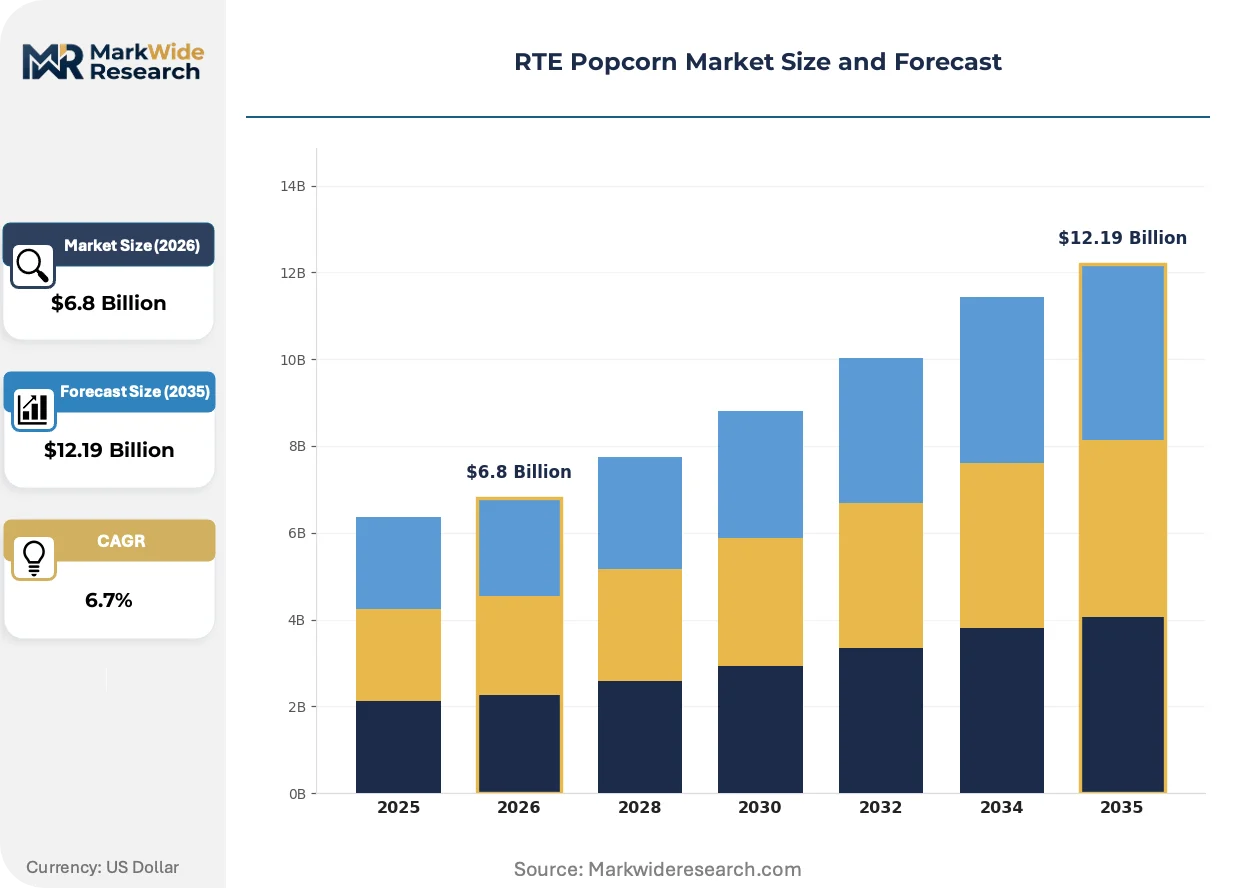
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Cheese, Caramel, Kettle Corn Packaging Type: Bags, Boxes, Tubs, Pouches Flavor Profile: Sweet, Savory, Spicy, Classic Sales Channel: Online, Supermarkets, Convenience Stores, Specialty Shops |
| Companies Covered | American Pop Corn Co., The Hershey Co., Conagra Brands Inc., Quinn Foods LLC, General Mills Inc., PepsiCo Inc., Weaver Popcorn Manufacturing Inc., PROPER Snacks, Campbell Soup Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RTE Popcorn Market Strategic Shifts
Active packaging technologies and regulatory compliance architectures are compressing product development cycles while reshaping how RTE popcorn manufacturers balance shelf-life performance against circular economy mandates.
High-barrier mono-material films incorporating ethylene vinyl alcohol copolymers are modularizing traditional multilayer structures into single-stream recyclable formats. Natural-channel grocers and club stores are adopting these pouches at accelerated rates to preempt California and New York EPR enforcement. The technology is modularizing supply chain relationships between converters and resin suppliers, forcing long-term contract renegotiations.
EPA emissions standards for food-manufacturing facilities are tightening thermal oxidizer requirements for oil-popping operations. Hot-air expansion lines face lower compliance burdens, tilting capital allocation toward air-popped capacity expansions in Midwest production clusters. California facilities bear the highest retrofit costs, accelerating consolidation toward states with less stringent state-level overlay requirements.
Subscription pantry loading by streaming-service households is displacing single-bag impulse purchases with multi-unit case formats. Amazon Subscribe & Save and direct-to-brand replenishment programs capture recurring revenue at lower per-unit shipping economics. This pattern concentrates in suburban Texas and Florida markets where pantry square footage exceeds national averages.
RTE Popcorn Market Segmentation
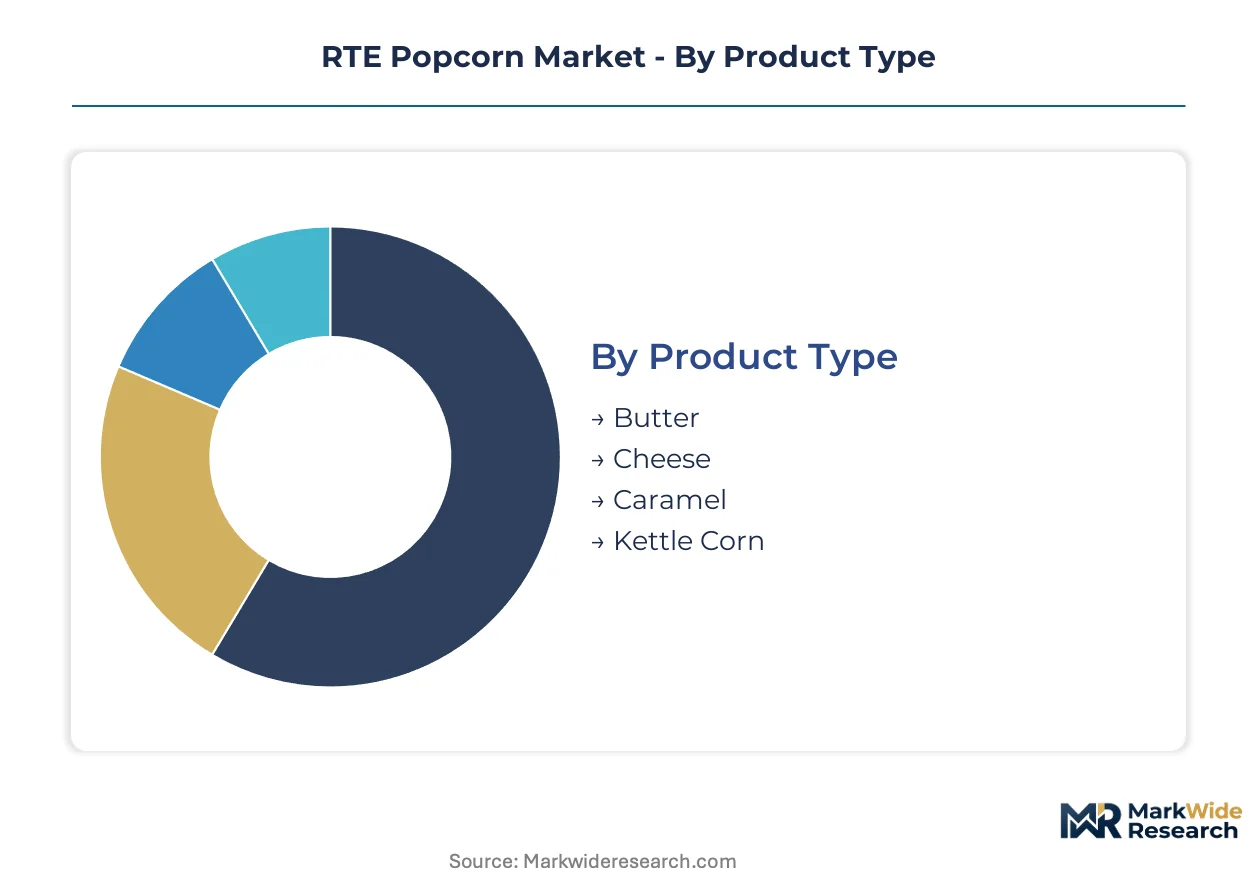
RTE popcorn manufacturers calibrate formulation complexity, barrier packaging specifications, and channel economics against distinct consumer usage occasions. Segmentation reveals how caramel and cheese variants command premium positioning while pouch formats reshape shipping economics.
Product Type:
Flavor complexity separates impulse purchasers from pantry-stockers and determines ingredient cost structures across production runs.
- Butter:Oil-popped kernels coated with butter-flavored seasoning dominate mainstream retail velocity. Walmart and Kroger ambient aisles in Texas and Florida move the highest case volumes through multi-pack configurations.
- Cheese:Cheddar and white cheddar powders require specialized dairy processing inputs from Wisconsin facilities. Natural-channel grocers position these SKUs adjacent to cracker sets for entertaining occasions.
- Caramel:Sugar-based coating applied post-popping creates indulgent positioning with extended production cycles.
- Kettle Corn:Dual sweet-savory profile targets state fair nostalgia and seasonal limited editions.
Butter leads volumes today; caramel is gaining share fastest.
Packaging Type:
Material selection hinges on shelf-life requirements, shipping damage rates, and recyclability mandates under California EPR frameworks.
- Bags:Vertical form-fill-seal polypropylene structures dominate club store and supermarket ambient placement. Amazon Subscribe & Save programs favor these formats for dimensional weight efficiency in fulfillment centers.
- Pouches:Stand-up flexible structures with resealable zippers capture natural-channel and online velocity. Mono-material redesigns for curbside recyclability are accelerating Kroger and Albertsons adoption ahead of enforcement deadlines.
- Boxes:Corrugated secondary packaging enables pallet optimization for wholesale club formats.
- Tubs:Rigid polypropylene containers maintain crunch integrity for convenience store cooler placement.
Bags anchor current volume; pouches are expanding most quickly.
Flavor Profile:
Palate positioning determines price elasticity and cross-merchandising adjacencies across retail formats.
- Savory:Cheese and herb blends align with beer and wine occasions in adult-targeted placements. 7-Eleven and Circle K refrigerated sets are testing fresh-perception savory SKUs for impulse capture.
- Sweet:Caramel and kettle profiles dominate seasonal gifting and movie-night pantry loading. Suburban streaming-service households in Florida build recurring purchase rhythms around these variants.
- Spicy:Chili-lime and sriracha coatings target younger demographics in convenience and specialty channels.
- Classic:Lightly salted air-popped formats qualify for FDA whole-grain health claims in institutional channels.
Savory holds volume leadership; sweet profiles climb the fastest.
Sales Channel:
Channel selection dictates case pack configurations, promotional cadence, and margin structures through the value chain.
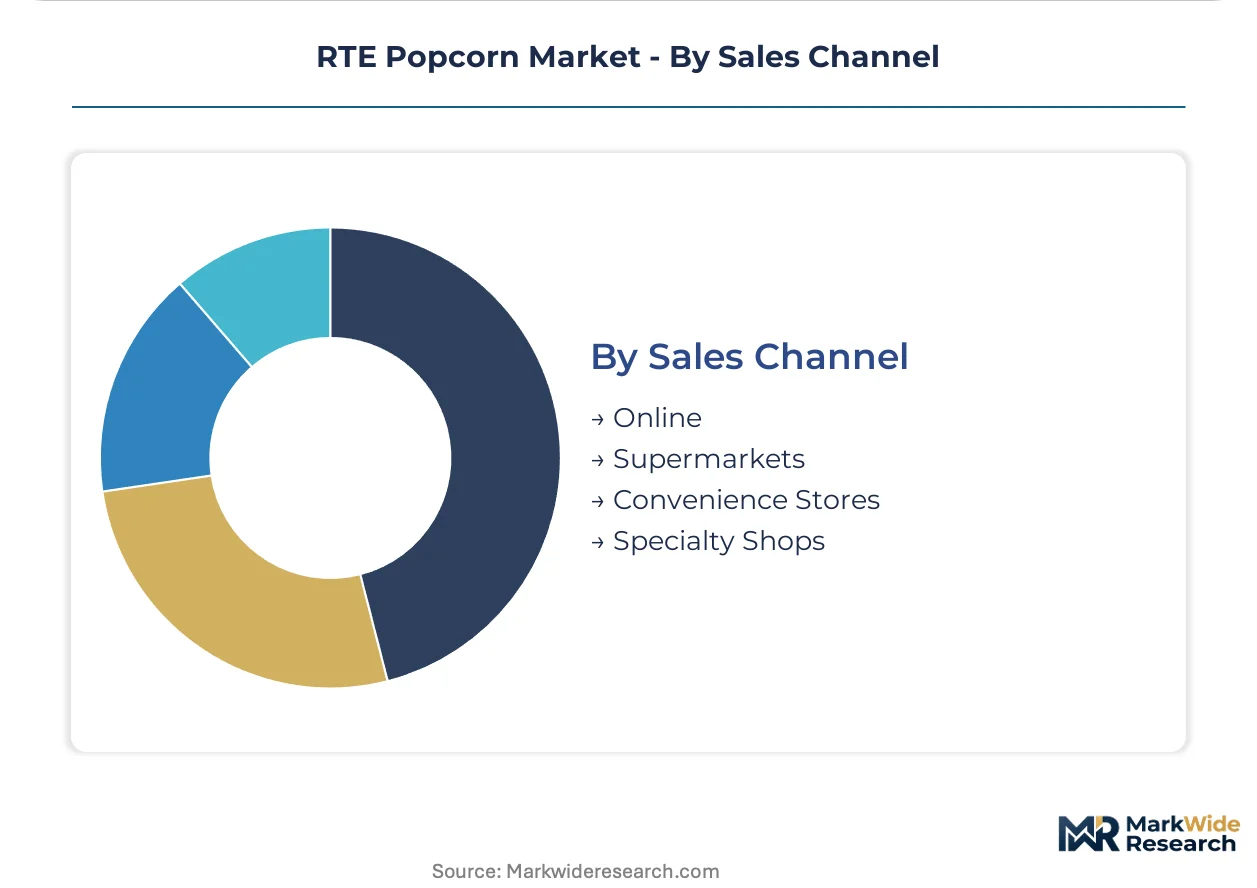
- Supermarkets:Ambient and freezer aisle placement drives planned-purchase volume through feature ad programming. Albertsons and Kroger chains are prioritizing recyclable pouch SKUs for shelf reset timelines.
- Online:Amazon Subscribe & Save and direct-to-brand replenishment programs concentrate in suburban Texas and Florida markets. Multi-unit case formats displace single-bag economics with lower per-unit shipping costs.
- Convenience Stores:Impulse velocity depends on checkout adjacency and cooler placement for fresh-perception positioning.
- Specialty Shops:Natural-channel grocers command premium placement for non-GMO and organic credentialed SKUs.
Supermarkets dominate current volume; online channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest corn processing clusters anchor North American RTE popcorn production, with Iowa and Illinois growing regions supplying contract specifications for both commodity and specialty grain requirements. Demand dispersion across streaming-service households and cineplex operators creates distinct regional consumption patterns that reshape distribution network investments.
United States
Texas and Florida suburban markets drive pantry-loading velocity through Amazon Subscribe & Save programs. FDA whole-grain labeling pathways and trans-fat disclosure requirements tighten formulation standards for products targeting institutional channels. California facilities face the highest EPA emissions retrofit costs, accelerating production consolidation toward Midwest and Southeast states with lighter regulatory overlays.
Canada
Cross-border ingredient sourcing from U.S. Midwest corn suppliers supports Ontario and Quebec processing facilities. Health Canada nutrition labeling regulations align with FDA frameworks while maintaining distinct bilingual packaging requirements. Greater Toronto Area distribution hubs serve as consolidation points for club store formats moving into western provinces.
Germany
Natural-channel grocers in Bavaria and North Rhine-Westphalia prioritize organic and non-GMO credentialed imports. EU Green Deal packaging recyclability mandates and ECHA chemical registration requirements shape barrier film specifications. Berlin-Brandenburg logistics clusters handle inbound specialty flavor inputs from Benelux chemical processors.
United Kingdom
London and Southeast England convenience store chains test refrigerated RTE popcorn formats for fresh-perception positioning. Extended producer responsibility frameworks pressuring multilayer packaging redesign mirror California and New York timelines. Midlands manufacturing sites concentrate hot-air expansion capacity for clean-label export production.
China
SAMR low-carbon manufacturing incentives create export pathways for U.S. producers with verified agricultural input reductions. Yangtze River Delta and Pearl River Delta urban clusters concentrate demand from cinema chain expansion and middle-class snack pantry formation. GB standards for food contact materials differ from FDA specifications, requiring separate production runs for compliant export SKUs.
RTE Popcorn Market Competitive Environment
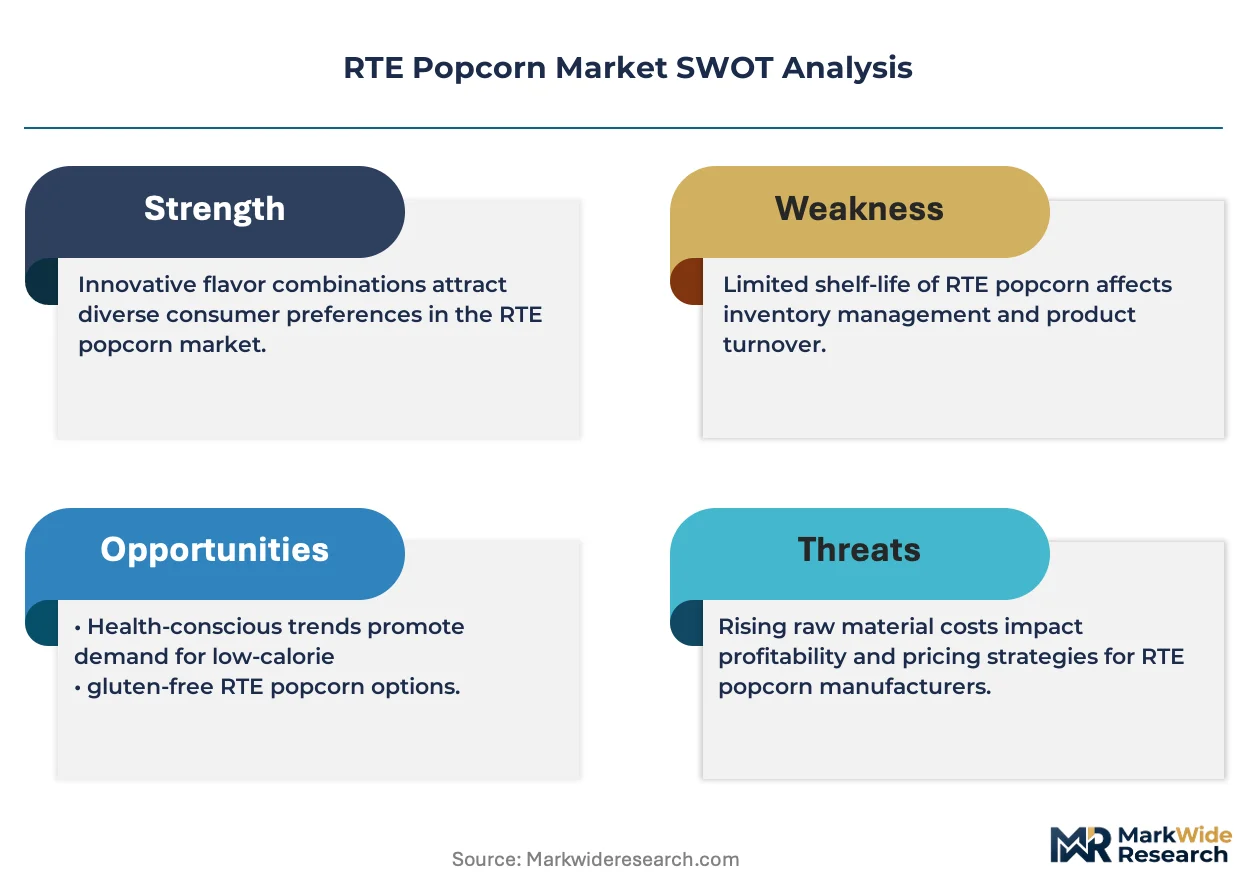
Established producers occupy the standard tier; emerging entrants pursue clean-label and organic positioning to capture premium placement in natural-channel grocers. The vendor base stratifies across three maturity tiers: multinational snack conglomerates with frozen-foods distribution backbones, mid-cap specialists leveraging non-GMO credentials, and regional contract manufacturers serving private-label programs. Two dominant competitive moves define current dynamics: packaging redesign for California and New York EPR compliance ahead of 2027 enforcement, and hot-air expansion capacity expansion to reduce EPA emissions compliance burdens.
Among U.S.-based diversified snack manufacturers, Conagra Brands Inc., PepsiCo Inc., and Quinn Foods LLC exemplify distinct strategic archetypes. Conagra Brands Inc. leverages frozen-foods infrastructure for dual-temperature distribution. PepsiCo Inc. anchors convenience-store dominance through Frito-Lay's retail relationships. Quinn Foods LLC occupies the premium-tier position through organic and non-GMO ingredient credentials. Each represents a different pathway to shelf-space allocation: scale economies, channel control, or certification-based differentiation.
| Leading Market Players |
|---|
| American Pop Corn Co. |
| The Hershey Co. |
| Conagra Brands Inc. |
| Quinn Foods LLC |
| General Mills Inc. |
| PepsiCo Inc. |
| Weaver Popcorn Manufacturing Inc. |
| PROPER Snacks |
| Campbell Soup Co. |
| Others |
Value Chain & Pricing Dynamics
California EPR mandates for mono-material recyclability gate both qualified packaging supply and premium-tier pricing access for RTE popcorn manufacturers, forcing brands to absorb converter retooling costs or forfeit placement in Kroger and Albertsons chains ahead of enforcement deadlines. This regulatory filter concentrates pricing power among converters with barrier-film engineering capabilities while compressing margins for brands locked into legacy multilayer structures.
Pricing Analysis
Input-cost pass-through from corn and dairy powder volatility shapes tiered pricing across the RTE popcorn category. Three-tier pricing structure across premium, standard, and economy levels separates organic-credentialed SKUs in natural-channel grocers from mainstream butter variants in Walmart ambient aisles and private-label economy packs. Cost compression in the standard tier is intensifying because Midwest drought cycles and Wisconsin labor shortages squeeze ingredient margins. Private-label buyers at Aldi and Lidl exhibit highest price sensitivity, while streaming-service households purchasing through Amazon Subscribe & Save show lowest elasticity for recurring pantry loads.
Supply Chain Analysis
Freight cost differentials between Midwest corn processing clusters and coastal distribution hubs anchor supply chain configuration for RTE popcorn manufacturers. Iowa and Illinois growing regions supply contract specifications for both commodity and specialty grain requirements, while Wisconsin facilities concentrate specialty dairy flavor inputs. The supply chain draws from polyethylene resin suppliers in Texas and Louisiana, metallized film converters in Ohio, and pouch finishing operations in California. Single-source vulnerability concentrates in organic corn contract farming, where USDA accredited body audit backlogs extend verification timelines. Distribution runs through frozen-foods infrastructure for dual-temperature placement and ambient trucking networks for mainstream retail velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between California facilities facing EPA emissions retrofit burdens and Midwest production clusters with lighter regulatory overlays and proximate corn supply.
For Market Incumbents: Lock in mono-material packaging supply agreements with converters ahead of California EPR enforcement timelines to secure preferential placement in Kroger and Albertsons chains. Prioritize hot-air expansion capacity additions in Iowa and Illinois to reduce EPA compliance costs while maintaining clean-label positioning for natural-channel grocers. Channel control through frozen-foods distribution infrastructure defends against private-label encroachment in ambient and freezer aisles.
For New Entrants and Emerging Players: Enter via refrigerated RTE popcorn formats targeting fresh-perception positioning in 7-Eleven and Circle K cooler expansions, where incumbent presence remains thin. Target suburban Texas and Florida streaming-service households through direct-to-brand subscription models, bypassing slotting fee barriers in mainstream retail. White space concentrates in spicy flavor profiles for younger demographics and organic certification for premium natural-channel placement.
For Investors and Strategic Acquirers: Roll-up economics work for regional contract manufacturers with USDA organic certification and established private-label relationships because brand consolidation pressures create distressed asset opportunities. Mid-cap specialists with backward integration into corn processing and captive flavor formulation capabilities offer strongest 5-10 year viability. Monitor California EPR compliance timelines as inflection indicator for packaging converter distress and brand margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Packaging Redesign | California EPR compliance secures Kroger and Albertsons shelf placement ahead of enforcement deadlines. |
| Hot-Air Expansion Capacity Addition | Midwest installations reduce EPA emissions compliance burdens versus California facility retrofits. |
| Direct-to-Consumer Subscription Launch | Amazon Subscribe & Save and brand-owned replenishment capture recurring revenue in Texas and Florida suburbs. |
| Refrigerated Format Introduction | 7-Eleven and Circle K cooler placement targets fresh-perception impulse traffic with limited incumbent competition. |
| Organic Certification Investment | USDA credentialed SKUs command premium placement in Whole Foods and Sprouts natural-channel sets. |
Study Parameters
Direct dialogue with RTE popcorn brand managers, category buyers at Kroger and Albertsons, packaging converters, and USDA accredited organic certification bodies grounded qualitative findings in operational realities. Secondary validation drew from FDA labeling guidance documents, EPA emissions standards filings, California and New York EPR framework texts, and Nielsen retail audit data for snack category velocity. Bottom-up volume modeling from production facility capacities and top-down demand estimation from streaming-service household penetration rates were triangulated against trade flow data from U.S. corn and dairy processing regions.
Bottom-up demand estimation by flavor profile, packaging format, and sales channel structured analytical framework across the projection horizon. Segmentation dimensions modeled include product type complexity, barrier packaging specifications, and channel economics. CAGRs were derived from trend extrapolation of pantry-loading velocity in suburban markets and capping assumptions for EPR compliance cost absorption. Forecast inputs incorporated hot-air expansion technology adoption curves and mono-material film performance validation timelines.
Inputs from FDA guidance releases and state-level EPR rulemaking were available through the study window; gaps in real-time converter capacity utilization and organic corn contract pricing introduce uncertainty bands around packaging cost assumptions. Forecasts reflect documented assumptions about enforcement timelines and technology adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Specialty Snacks Market
Snacks
Sweet Potato Chips Market
Snacks
Dried Fruit Snacks Market
Snacks
Brazil Snack Bar Market
Snacks
South Korea Snack Bar Market
Snacks
Edible Flakes Market
Snacks
South America Protein Bar Market
Snacks
Meat Protein Chips Market
Snacks
United Kingdom Energy Bar Market
Snacks
Europe Extruded Snack Food Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Mushroom Based Jerky Market
Snacks
Corn Chips Market
Snacks
Qatar Potato Chips Market
Snacks
United States Energy Bar Market
Snacks
France Energy Bar Market