
 North America Premium Chocolate Market | 2026-2036
North America Premium Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Premium Chocolate Market Analytics
Specialty retail and direct-to-consumer channels are expanding their share of premium chocolate distribution. Mondelez International leverages its continental logistics network to sustain shelf presence across mainstream and upscale retail tiers. Lindt anchors its North American position through flagship boutique stores in major metropolitan corridors. Theo competes on certified organic and fair-trade sourcing credentials that resonate with coastal consumer bases.
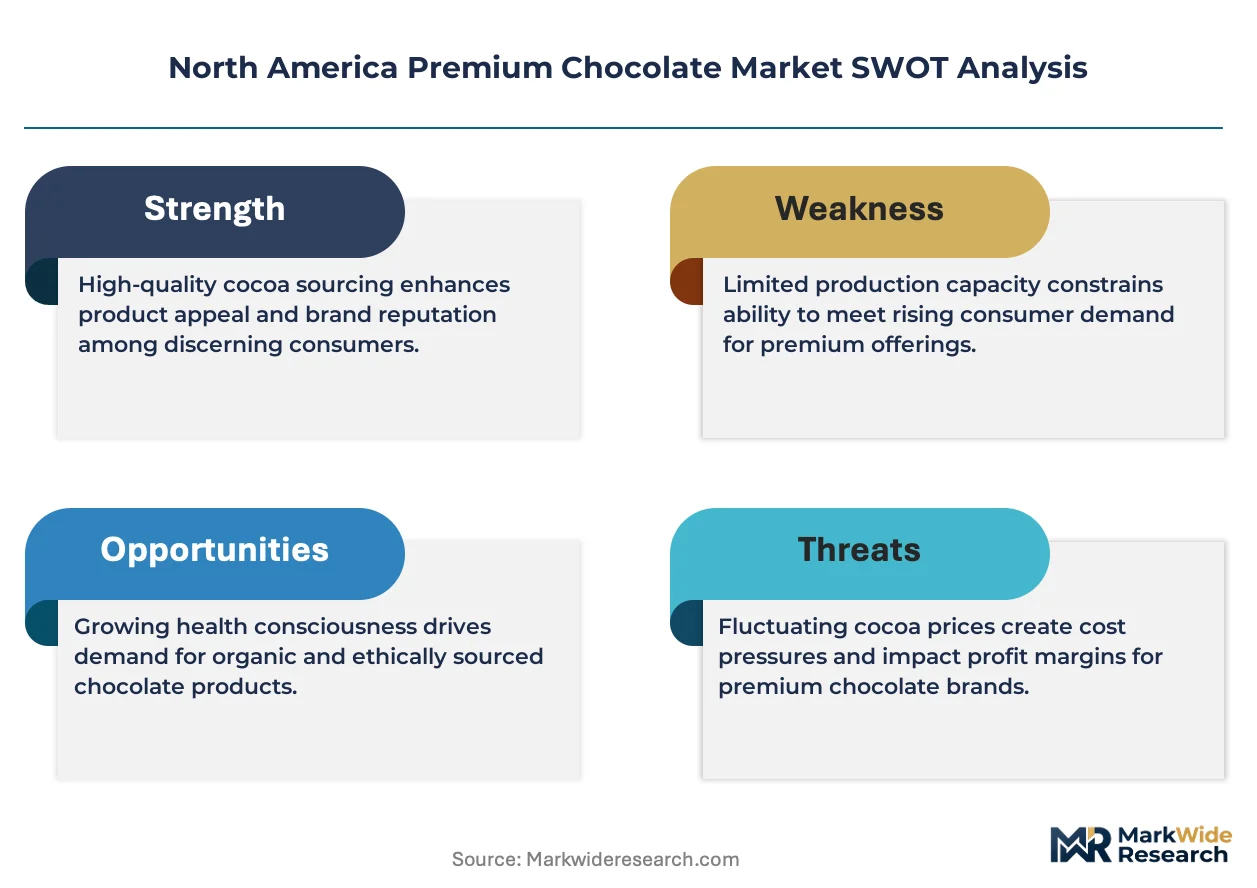
Premium chocolate denotes confectionery products manufactured with superior-grade cacao beans, typically exceeding 60% cacao content in dark varieties, utilizing minimal processing and artisan or small-batch production methods. These products serve discerning consumers seeking sensory complexity, provenance transparency, and ethical supply chain verification. Dark chocolate commands the deepest margin pools due to its alignment with health-conscious positioning and clean-label preferences. Gift Pack packaging captures elevated per-unit economics during seasonal peaks, while Specialty Stores distribution channels concentrate the highest brand-loyal customer lifetime value.
The FDA governs ingredient disclosure and allergen labeling requirements that directly shape product formulation and packaging investment. USDA organic certification and state-level California Proposition 65 chemical warning standards impose additional compliance layers for premium positioning. Stakeholders must monitor evolving cacao sustainability regulations and traceability mandates that will determine supplier qualification and consumer trust architecture.
Market Dynamics
Bean-to-bar traceability technology is compressing supply chain opacity and forcing reformulation transparency across North American premium chocolate manufacturing. FDA labeling updates and California Proposition 65 chemical warning standards are accelerating compliance investment timelines.
Growth Catalysts
- Ethical sourcing mandates:Consumer preference for fair-trade cacao verification is pulling inventory decisions toward certified supply chains. Retailers now require third-party ethical credentials as table stakes for shelf placement.
- Clean-label positioning:Dark chocolate varieties exceeding 70% cacao content align with health-conscious dietary patterns. This formulation category commands premium positioning in specialty food retail.
- California's artisan corridor:Concentrated craft chocolate production in the San Francisco Bay Area and Los Angeles basin generates regional innovation spillover. Local ingredient sourcing networks strengthen product differentiation claims.
Market Restraints
- Cacao price volatility:West African supply concentration exposes margins to weather-driven harvest disruptions. Input cost swings compress working capital flexibility for small-batch producers.
- Organic certification timelines:USDA organic conversion periods delay new product launches by 36 months minimum. This friction limits rapid response to emerging flavor trends.
- Plant-based confectionery substitution:Oat milk and coconut-based alternatives capture trial among lactose-intolerant and vegan consumer segments. Premium chocolate loses occasion share to these emerging categories.
Strategic Opportunities
- Pacific Northwest craft food ecosystem:Seattle and Portland specialty retail density supports direct-to-consumer subscription models. Regional consumer willingness-to-pay for provenance transparency exceeds national averages.
- Blockchain traceability convergence:Distributed ledger technology integration with QR-enabled packaging creates immutable origin documentation. Early adopters capture price premiums from verification-seeking buyers.
- IRA clean energy incentives:Renewable energy tax credits reduce facility operating costs for domestic manufacturing expansion. Processing equipment electrification aligns with ESG investor screening criteria.
Industry Challenges
- Confectionery science talent scarcity:Specialized expertise in cacao fermentation chemistry and tempering automation commands premium compensation. Smaller producers struggle to attract qualified R&D personnel against multinational salary benchmarks.
- Legacy ERP integration friction:Batch-level traceability requirements conflict with decades-old inventory management systems. Custom middleware development consumes capital that could deploy toward production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Premium Chocolate Market |
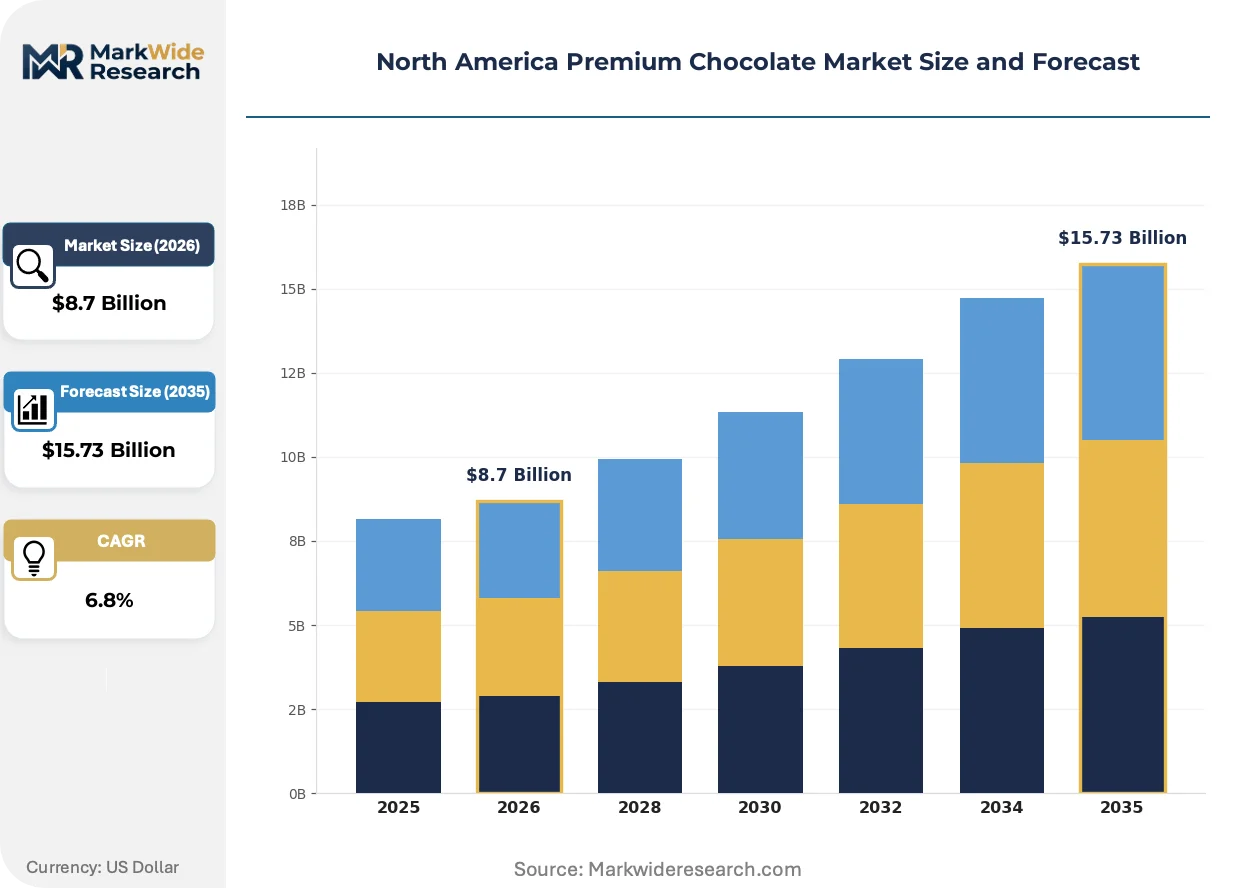
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Packaging Type: Box, Bar, Bag, Gift Pack Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Customer Type: Individual Consumers, Corporations, Event Planners, Gift Buyers |
| Companies Covered | Mondelez International Inc., Nestlé SA, Lindt, Ghirardelli, Godiva, Mars Incorporated, Ferrero International SA, Theo, The Hershey Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Premium Chocolate Market Evolving Landscape
Technology-enabled transparency is collapsing the information asymmetry between cacao origin and retail shelf. Regulatory pressure on chemical disclosure and supply chain documentation is accelerating digital infrastructure investment across the value chain.
Blockchain-based provenance platforms are unifying farm-level data with consumer-facing verification interfaces. Artisan producers in California and the Pacific Northwest are piloting these systems to differentiate against commodity chocolate imports. This transparency infrastructure is compressing the trust-building timeline from years to individual purchase occasions.
FDA updated food labeling requirements now mandate clearer added sugar disclosure and allergen cross-contamination warnings. Premium chocolate manufacturers must reformulate or redesign packaging to maintain shelf eligibility. Dark chocolate segments with minimal ingredient lists face lower compliance burden than inclusion-heavy milk chocolate varieties.
Direct-to-consumer subscription models are displacing traditional wholesale dependency for emerging brands. Specialty food retailers in metropolitan corridors now compete with monthly chocolate clubs for high-lifetime-value customers. This channel rotation is most visible in California's urban markets where delivery logistics density supports economical last-mile fulfillment.
North America Premium Chocolate Market Segmentation
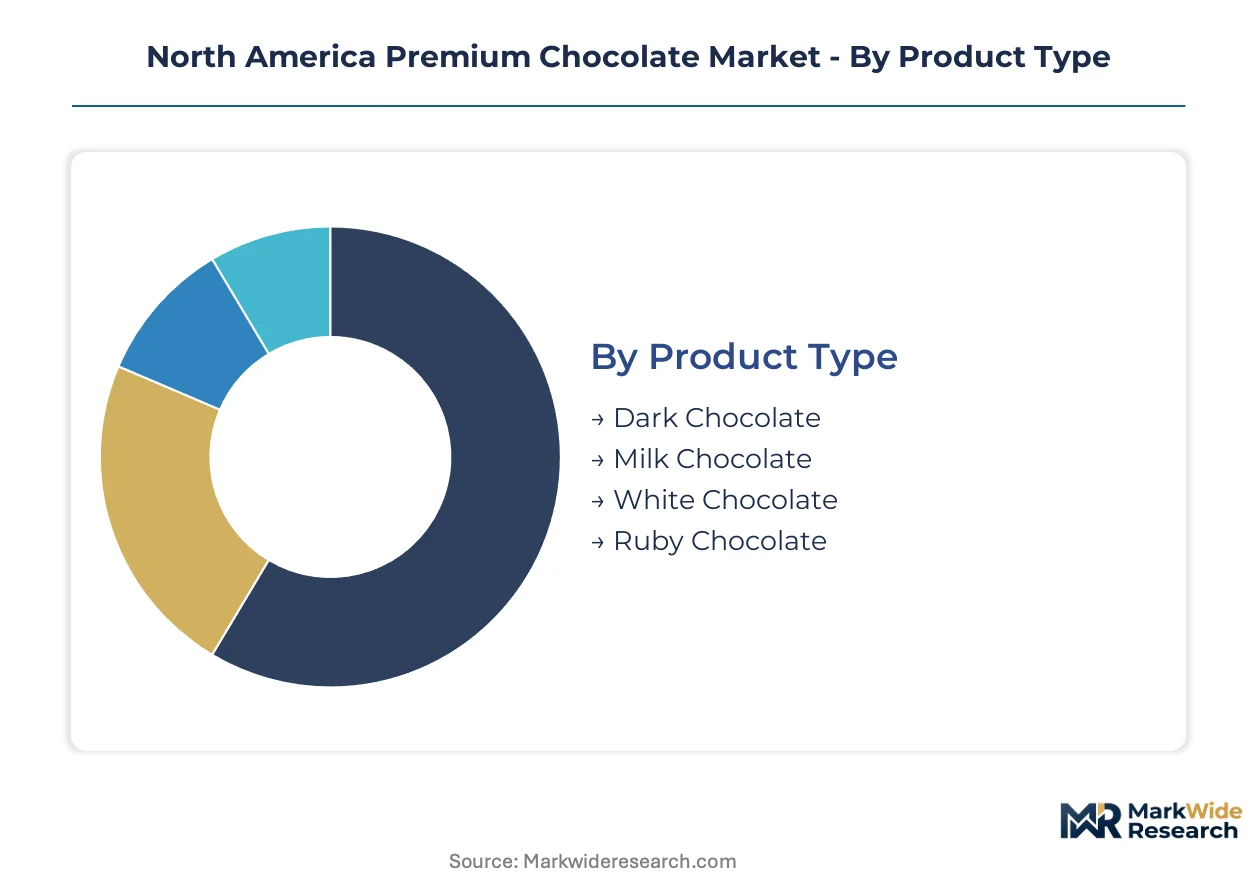
Premium chocolate segmentation reveals distinct margin architectures across product formulations, packaging formats, and channel strategies. Each dimension carries specific compliance burdens and consumer trust requirements that reshape competitive positioning.
Product Type:
Standalone consumption segments dominate direct retail, while embedded applications concentrate in foodservice and ingredient supply.
- Dark Chocolate:Formulations exceeding 60% cacao content deliver the deepest sensory complexity and align with FDA clean-label positioning. California's artisan corridor generates the highest per-unit pricing for single-origin dark varieties, constrained by cacao price volatility from West African supply concentration.
- Milk Chocolate:Lower cacao percentages require more intensive allergen labeling under FDA updated requirements. Demand concentrates in gift packaging occasions where creamy texture preferences override health positioning.
- White Chocolate:Cocoa butter-based formulations without cocoa solids face distinct USDA organic certification timelines.
- Ruby Chocolate:Pink-hued cacao variety commands novelty premiums in Pacific Northwest specialty retail.
Volume placements concentrate in Dark Chocolate; the faster expansion belongs to Ruby Chocolate.
Packaging Type:
Cost tiers separate impulse purchases from planned gifting occasions, with per-unit economics scaling nonlinearly across formats.
- Box:Rigid packaging supports premium unboxing experiences and protects temper-sensitive formulations during temperature fluctuations. Corporate procurement in metropolitan corridors drives volume, constrained by seasonal demand compression outside holiday windows.
- Bar:Standard format dominates everyday consumption with minimal packaging compliance burden. Individual Consumers in California and Pacific Northwest urban markets generate the highest repeat purchase frequency.
- Bag:Flexible format captures trial and sharing occasions with lower per-unit price points.
- Gift Pack:Curated assortments command elevated economics through occasion-based pricing power.
Volume placements concentrate in Bar format; Gift Pack claims the steepest expansion trajectory during seasonal peaks.
Distribution Channel:
Customer acquisition costs vary dramatically between discovery-oriented physical retail and replenishment-focused digital channels.
- Supermarkets:Mass retail placement requires slotting fee investments and FDA-compliant packaging at scale. Shelf space competition from plant-based alternatives constrains premium chocolate facings in conventional grocery.
- Online Retail:Direct-to-consumer subscriptions bypass wholesale margin compression and capture lifetime value through recurring revenue. Pacific Northwest logistics density supports economical cold-chain fulfillment for temperature-sensitive products.
- Specialty Stores:Curated assortment environment enables provenance storytelling and bean-to-bar traceability demonstration.
- Convenience Stores:Impulse-oriented channel captures immediate consumption with limited premium positioning.
Volume placements concentrate in Supermarkets; Specialty Stores deliver the highest customer lifetime value concentration.
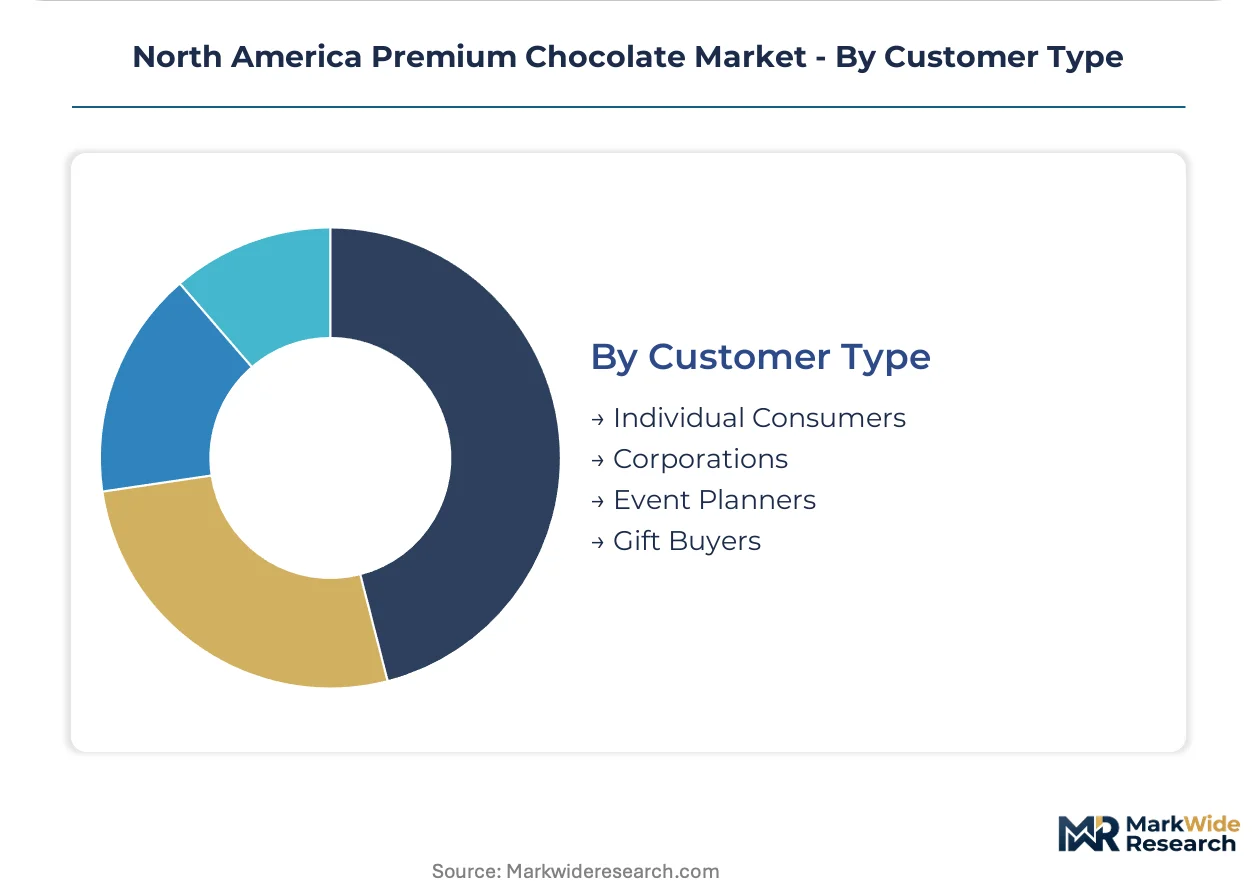
Customer Type:
Procurement patterns separate emotional, occasion-driven purchasing from systematic, contract-based volume acquisition.
- Individual Consumers:Personal consumption and small-scale gifting drive recurring demand with strong brand loyalty potential. California's urban markets show elevated willingness-to-pay for ethical sourcing verification.
- Corporations:Bulk procurement for employee recognition and client gifting requires consistent supply reliability and customizable branding. Seasonal concentration creates working capital pressure for manufacturers.
- Event Planners:Wedding and corporate event coordination demands scalable fulfillment with precise timing.
- Gift Buyers:Occasion-specific purchasing concentrates in holiday windows with premium packaging requirements.
Volume placements concentrate in Individual Consumers; Corporations represent the most stable contract-based demand foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's artisan chocolate corridor concentrates production through state-level clean energy incentives and specialty food infrastructure. The Pacific Northwest craft food ecosystem leverages Seattle and Portland retail density for direct-to-consumer subscription scaling.
United States
California's Bay Area and Los Angeles basin generate the highest per-unit pricing for single-origin dark varieties. FDA updated food labeling requirements mandate clearer added sugar disclosure and allergen cross-contamination warnings. The San Francisco artisan corridor anchors bean-to-bar traceability pilot programs with blockchain-enabled packaging.
Canada
Urban centers in Ontario and British Columbia show elevated willingness-to-pay for ethical sourcing verification. Health Canada maintains strict allergen labeling standards that parallel FDA requirements for cross-border product consistency. Vancouver specialty retail density supports Pacific Northwest craft food ecosystem spillover.
Mexico
Domestic cacao cultivation in Tabasco and Chiapas supplies raw material to premium chocolate manufacturers. Mexican organic certification aligns with USDA timelines but offers faster conversion for nearshoring producers. Mexico City Metro specialty food retail concentrates demand for provenance-transparent imports.
North America Premium Chocolate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational confectionery conglomerates anchoring mainstream retail placement while artisan producers capture specialty channel premiums. The vendor base organizes into three tiers: mass-market heritage brands, mid-tier premium specialists, and micro-batch craft producers. Strategic moves concentrate on direct-to-consumer subscription expansion and bean-to-bar traceability technology deployment.
Within the mass-market heritage tier, Mondelez International Inc. and The Hershey Company occupy positions sustained by continental logistics networks and shelf presence across retail tiers. Among premium specialists, Lindt exemplifies flagship boutique store strategies in major metropolitan corridors, while Theo represents certified organic and fair-trade sourcing credentials that resonate with coastal consumer bases.
| Leading Market Players |
|---|
| Mondelez International Inc. |
| Nestlé SA |
| Lindt |
| Ghirardelli |
| Godiva |
| Mars Incorporated |
| Ferrero International SA |
| Theo |
| The Hershey Company |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between USDA organic and conventional cacao splits the North American premium chocolate market into parallel pricing architectures with distinct sourcing protocols. Bean-to-bar producers command 40-60% premiums over commodity processors, yet face compressed margins when West African harvest disruptions spike raw material costs. FDA labeling compliance and California Proposition 65 chemical disclosure requirements layer fixed regulatory costs that small-batch producers amortize across lower volumes.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning while spot inventory liquidates at distressed levels. Subscription-based direct-to-consumer models anchor recurring revenue with 15-20% price premiums over wholesale channels. Price differentiation rests on ethical certification tier and single-origin provenance documentation, with Fair Trade and Rainforest Alliance credentials commanding measurable buyer premiums. Pricing pressure stems from oat milk and coconut-based confectionery alternatives capturing trial among vegan segments. Individual consumers in California's urban corridors show lowest price sensitivity; corporate gift buyers exhibit highest elasticity during economic softness.
Supply Chain Analysis
Domestic-content mandates under USDA organic certification reshape sourcing toward Mexican Tabasco and Chiapas cultivation regions with faster conversion timelines. West African supply concentration in Côte d'Ivoire and Ghana exposes margins to weather-driven harvest volatility. Raw material dependencies center on fermented cacao beans, cocoa butter, and cane sugar with limited substitution flexibility. Single-source vulnerability concentrates in West African port logistics and Atlantic shipping lanes. Distribution runs through temperature-controlled specialty retail networks in California's artisan corridor and Pacific Northwest craft food ecosystems, with direct-to-consumer subscription channels displacing traditional wholesale dependency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around traceability technology investments that weaker players cannot fund, accelerating exits among undercapitalized artisan producers. Cacao price volatility and certification compliance burdens squeeze marginal operators toward acquisition or closure.
For Market Incumbents: Anticipate blockchain traceability convergence as a defensive necessity rather than differentiation luxury. Mondelez International and Lindt should deepen upstream control over Mexican cacao cultivation to hedge West African supply concentration. FDA labeling updates and organic certification timelines favor scaled compliance infrastructure that micro-batch competitors cannot replicate. Channel control through flagship boutique expansion in metropolitan corridors protects margin architecture against direct-to-consumer erosion. For New Entrants and Emerging Players: Direct-to-consumer subscription routes offer the most penetrable entry vector with bypassed slotting fees and captured lifetime value. Pacific Northwest craft food ecosystems present white-space opportunity given regional willingness-to-pay premiums for provenance transparency. Ruby chocolate novelty positioning in specialty retail captures trial before multinational scale-up. Corporate gifting segments remain underpenetrated by certified organic specialists, offering contract-based demand foundation with lower customer acquisition costs than individual consumer markets. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier premium specialists holding established organic certification and Pacific Northwest distribution density given ESG investor screening convergence. Long-term viability over a five-to-ten year window favors producers with backward integration into Mexican cacao cultivation and renewable energy processing infrastructure. Acquisition target archetype: certified organic specialists with $5-15 million revenue scale and direct-to-consumer subscription traction. The signal to watch is blockchain traceability adoption rates among specialty retailers as shelf-placement gatekeeping mechanism.| Strategic Initiative | Industry Significance |
|---|---|
| Bean-to-Bar Traceability Deployment | Blockchain-enabled packaging satisfies retailer ethical credential requirements and captures verification-seeking buyer premiums. |
| Direct-to-Consumer Subscription Scaling | Monthly chocolate clubs bypass wholesale margin compression and build recurring revenue in California urban markets. |
| USDA Organic Certification Investment | Thirty-six month conversion timelines create defensive moats against rapid competitive response to flavor trends. |
| Mexican Cacao Cultivation Integration | Nearshoring into Tabasco and Chiapas reduces Atlantic logistics exposure and accelerates organic conversion timelines. |
| Renewable Energy Processing Transition | IRA clean energy tax credits align facility operations with ESG investor screening criteria and reduce operating costs. |
Research Methodology
Document review covered FDA labeling guidance, USDA organic certification protocols, and California Proposition 65 chemical disclosure standards, complemented by interviews with specialty food retail buyers, artisan chocolate production managers, and cacao import logistics coordinators. Secondary validation drew from customs trade data, Nielsen retail audit figures, and SEC filings of publicly traded confectionery conglomerates. Bottom-up demand modeling across individual consumer, corporate, and gift buyer segments triangulated against top-down market sizing from production capacity and import volume analysis.
Segmented outputs across product type, packaging format, distribution channel, and customer archetype fed into growth projection modeling across the analysis window. CAGRs were derived from historical volume trajectory analysis adjusted for regulatory catalysts and substitution threat parameters. Forecast inputs incorporated cacao futures price volatility patterns, organic certification pipeline conversion rates, and specialty retail square footage expansion in identified urban corridors.
The model holds under stable regulatory enforcement of FDA labeling and organic certification standards; deviation in cacao supply disruption severity or plant-based substitution acceleration would shift volume and value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Confectionery Fats Market
Confectionery
Chocolate Couverture Market
Confectionery
Diet Candy Market
Confectionery
Italy Chocolate Market
Confectionery
India Industrial Chocolate Market
Confectionery
Carob Chocolate Market
Confectionery
Global Candy Market
Confectionery
Premium Chocolate Market
Confectionery
Liquorice Shellac Market
Confectionery
North America Chocolate Market
Confectionery
Global Compound Chocolate Market
Confectionery
South Korea Chocolate Market
Confectionery
Europe Dark Chocolate Market
Confectionery
Low Calorie Sweets Market
Confectionery
Bangladesh Candy Market
Confectionery
Cookie Dough Market