
 Europe Premium Chocolate Market | 2026-2036
Europe Premium Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Premium Chocolate Market Intelligence
Bean-to-bar traceability technology is fragmenting traditional supply chain hierarchies across European premium chocolate production. Chocoladefabriken Lindt & Sprüngli AG anchors its position through vertical integration from Ecuadorian sourcing to Swiss retail. Ferrero International SA differentiates via hazelnut supply control and limited-edition seasonal positioning. Neuhaus NV specializes in Belgian praline heritage and controlled boutique distribution.
Premium chocolate denotes confectionery containing elevated cocoa mass percentages, single-origin bean sourcing, and artisanal processing methods such as conching durations exceeding seventy-two hours. Dark Chocolate leads product type value pools due to health-positioning and EFSA-permitted flavanol claims, while Ruby Chocolate represents the fastest-growing segment driven by color differentiation and younger consumer trial. Specialty Stores capture margin concentration through experiential retail and staff-guided tasting, whereas Online Retail expands fastest in Germany and the Netherlands via subscription gifting models.
EFSA governs health and nutrition claims on cocoa flavanol content, while EU Green Deal agricultural standards shape sustainable sourcing mandates for deforestation-free supply chains. REACH compliance affects food-contact packaging materials and migration limits for premium wrapping foils. Stakeholders must monitor evolving EUDR traceability requirements and decide between compliance investment premiums or contracted supplier consolidation.
Market Dynamics
EFSA traceability mandates and EU Green Deal deforestation regulations are compressing supply chain tiers, forcing processors to consolidate sourcing relationships or absorb compliance premiums directly.
Growth Catalysts
- EU Green Deal agricultural standards:Mandatory sustainable sourcing certifications are locking premium producers into deforestation-free supply chains, creating competitive moats against uncertified imports.
- Bean-to-bar processing technology:Small-batch conching and tempering equipment is democratizing artisanal production, enabling regional craft brands to challenge established processors.
- Belgium:Concentrated praline heritage clusters in Brussels and Bruges are attracting culinary tourism and export demand for certified-origin products.
Market Restraints
- Cocoa butter price volatility:Weather-driven supply interruptions in West African origins are compressing margins for processors locked into fixed-price retail contracts.
- EFSA health claim substantiation:Rigorous flavanol quantification requirements are extending product development timelines and raising analytical testing costs.
- Single-origin supply concentration:Dependence on Ecuadorian and Venezuelan fine-flavor bean stocks exposes processors to origin-specific political and climatic disruptions.
Strategic Opportunities
- Subscription gifting models:German and Dutch e-commerce platforms are building recurring revenue streams through curated monthly chocolate deliveries.
- EUDR traceability infrastructure:Early investment in blockchain-based farm-to-wrapper tracking systems will secure preferential retailer access when full enforcement begins.
- Ruby chocolate applications:Pink-hued couverture is penetrating bakery and ice cream channels, extending beyond confectionery into ingredient supply.
Industry Challenges
- Confectionery technician scarcity:Master chocolatier apprenticeship pipelines in Switzerland and Belgium are failing to replace retiring craft specialists.
- REACH food-contact compliance:Migration limit testing for decorative metallic foils and printed wrappers is extending packaging qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Premium Chocolate Market |
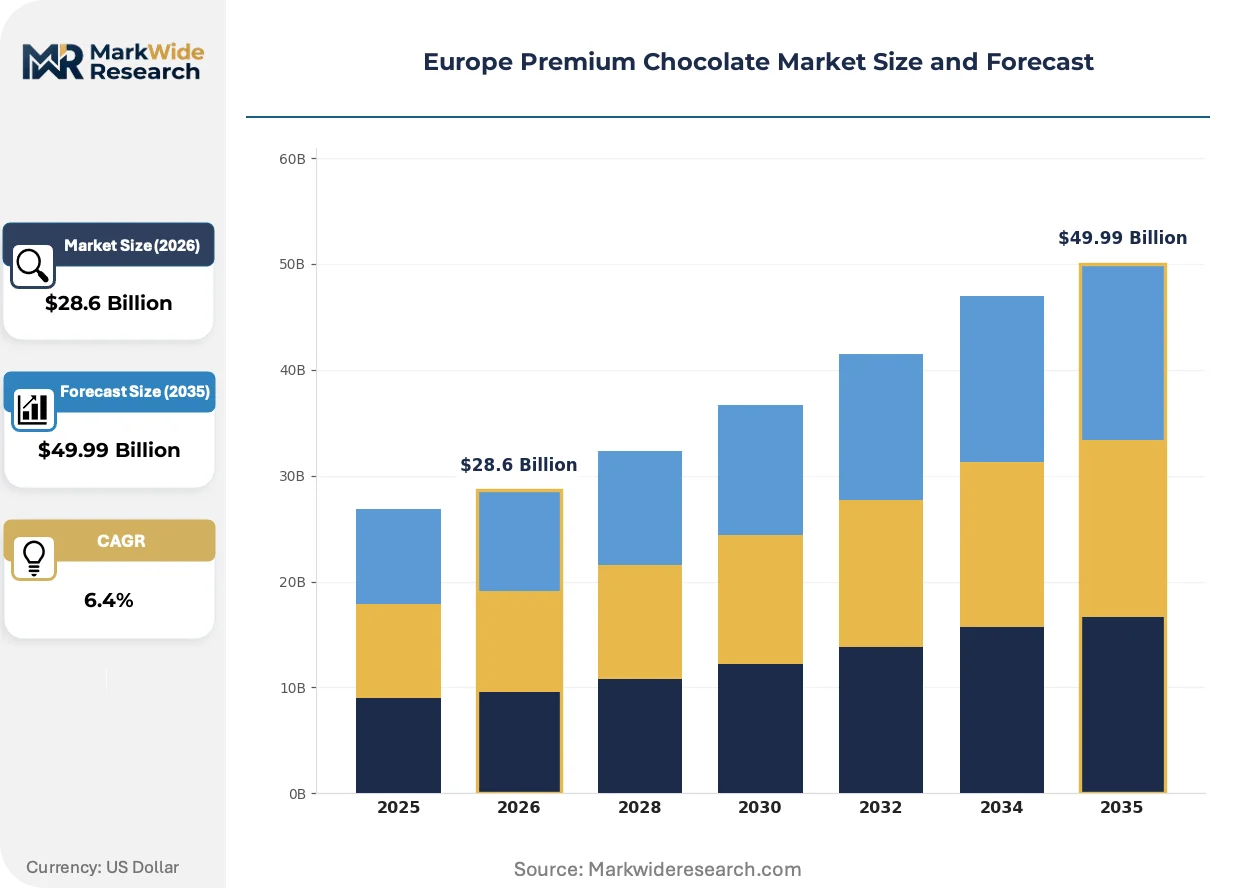
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Convenience Stores End User: Individuals, Gift Givers, Corporates, Food Service Price Tier: Premium, Super Premium, Affordable Luxury, Mass Market |
| Companies Covered | Nestlé SA, Neuhaus NV, Chocoladefabriken Lindt & Sprüngli AG, Yıldız Holding, Pierre Marcolini Group, Ferrero International SA, Mars Incorporated, Cemoi Group, Mondelez International Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Premium Chocolate Market Strategic Shifts & Innovations
Digital provenance systems and regulatory disclosure requirements are rewriting how European premium chocolate commands price premiums and defends shelf positioning against mass-market alternatives.
Blockchain-based farm-to-bar tracking is virtualizing traditional paper-based certification chains. Belgian and Swiss processors are deploying distributed ledger systems to document fermentation times, drying protocols, and cooperative payments. This technology is virtualizing the role of conventional third-party auditors, compressing verification costs while accelerating retailer onboarding.
EFSA nutrition and health claims regulation is tightening flavanol content thresholds for cardiovascular benefit assertions. Dark chocolate products must now meet specified (-)-epicatechin concentrations to retain label permissions. High-cocoa-mass segments are reformulating recipes and investing in standardized analytical protocols to maintain compliance.
Specialty store experiential retail is displacing conventional supermarket impulse purchasing. French and German consumers are prioritizing guided tastings, origin storytelling, and limited-batch exclusivity over price-driven selection. This channel rotation concentrates margin capture in urban flagship locations while eroding volume-based distributor relationships.
Europe Premium Chocolate Market Segmentation
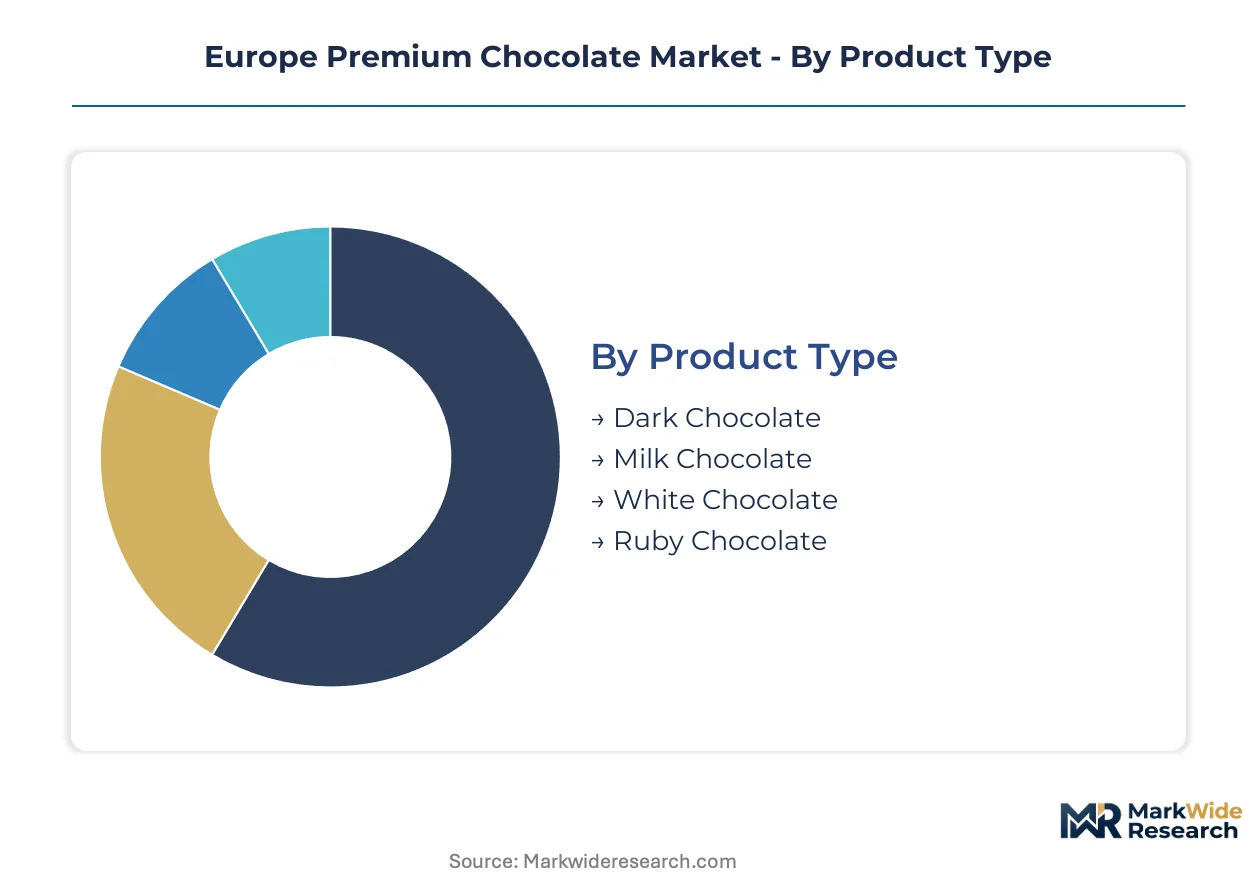
Premium chocolate segmentation in Europe reflects divergent consumer missions across health-conscious self-purchase, ceremonial gifting, and corporate hospitality. Channel and price tier fragmentation forces manufacturers to maintain parallel portfolio architectures rather than unified product lines.
Product Type:
Mature segments anchor volume while emerging formats reshape trial dynamics and color-based differentiation.
- Dark Chocolate:Cocoa mass percentages exceeding seventy percent dominate Belgian and Swiss production. EFSA-permitted flavanol cardiovascular claims concentrate demand among German health-positioned consumers and French pharmacy retail channels.
- Ruby Chocolate:Pink-hued couverture derived from unfermented Ruby cocoa beans offers color differentiation without artificial additives. Younger demographics in the Netherlands and UK drive trial through bakery and ice cream ingredient applications.
- Milk Chocolate:Elevated cocoa butter ratios distinguish premium Swiss and Belgian recipes from mass-market alternatives.
- White Chocolate:High cocoa butter content without cocoa solids serves confectionery and patisserie ingredient channels.
Dark Chocolate handles the majority of throughput; Ruby Chocolate is expanding most quickly on share.
Distribution Channel:
Margin concentration follows experiential retail investment while digital infrastructure captures recurring revenue.
- Specialty Stores:Staff-guided tastings and origin storytelling command price premiums in Brussels, Bruges, and Zurich flagship locations. Belgian praline heritage clusters leverage controlled boutique distribution to defend exclusivity.
- Online Retail:Subscription gifting models build recurring revenue through German and Dutch e-commerce platforms. Curated monthly deliveries penetrate corporate gifting segments with minimal physical footprint.
- Supermarkets:Impulse fixture placement competes on packaging differentiation and seasonal limited editions.
- Convenience Stores:Grab-and-go premium single-serve formats target urban commuter corridors.
Specialty Stores capture the dominant margin pool; Online Retail is climbing the fastest on volume contribution.
End User:
Usage occasion fragmentation requires distinct packaging formats and messaging architectures.
- Gift Givers:Seasonal assortments and limited-edition packaging drive Swiss premium gifting corridor demand. Heritage branding and origin certification justify price premiums for ceremonial exchange.
- Corporates:Branded hospitality chocolates and event favors concentrate in Frankfurt and London financial district procurement.
- Individuals:Health-motivated self-purchase favors high-cocoa-mass dark chocolate with EFSA-compliant labeling.
- Food Service:Couverture supply for restaurant dessert programs and patisserie wholesale channels.
Gift Givers sustain the largest revenue base; Corporates are gaining share fastest through hospitality procurement expansion.
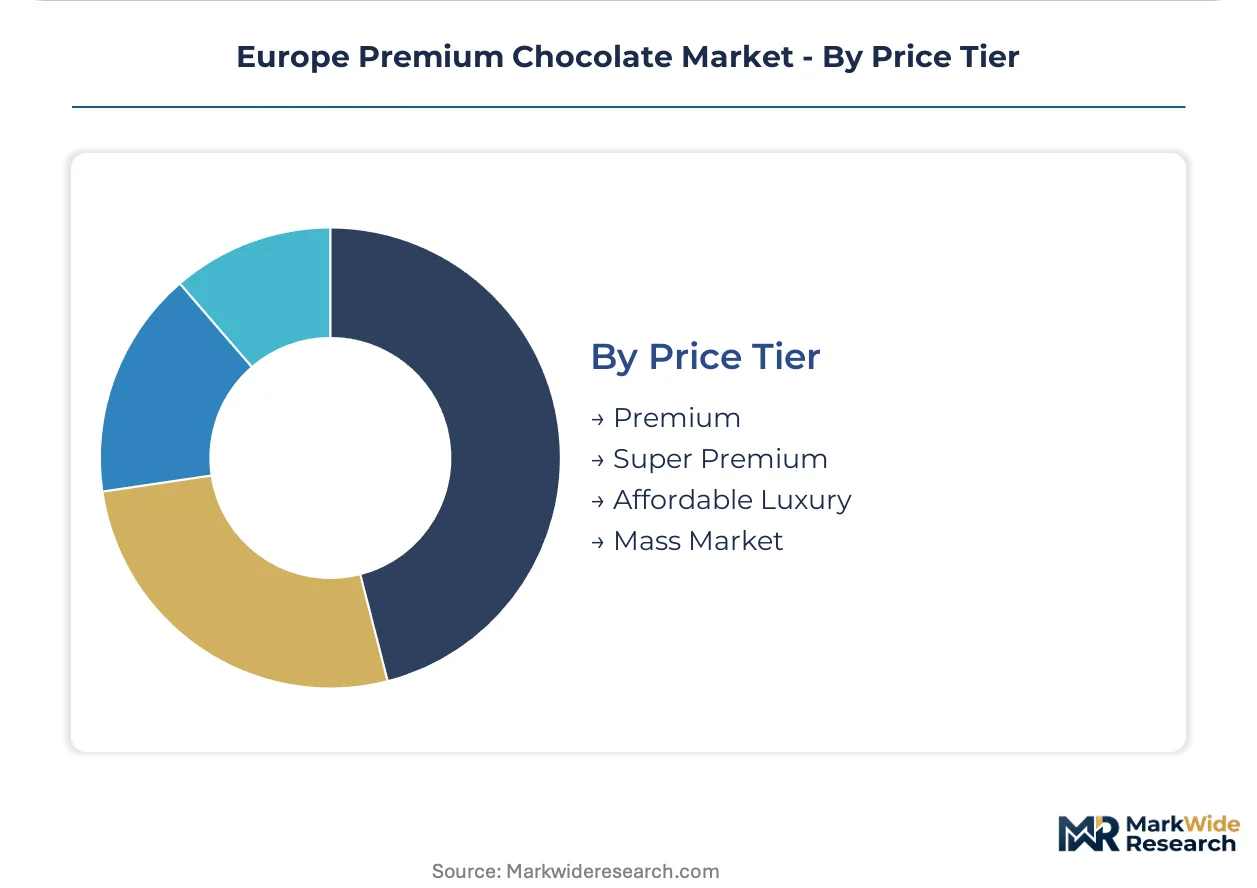
Price Tier:
Certification grade and provenance documentation stratify accessible luxury from ultra-premium positioning.
- Super Premium:Single-origin bean-to-bar products with blockchain traceability and cooperative payment documentation. Ecuadorian and Venezuelan fine-flavor stocks support Belgian craft segment pricing.
- Premium:Mass artisanal brands with controlled origin blending and extended conching protocols.
- Affordable Luxury:Accessible gifting formats with heritage packaging and mid-tier cocoa percentages.
- Mass Market:Price-competitive formulations with premium branding cues but standard ingredient sourcing.
Super Premium commands the steepest expansion trajectory; Premium handles the majority of unit throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian bean-to-bar exports flow primarily into German retail corridors and Swiss hospitality procurement channels, establishing a north-south trade spine that concentrates value capture in heritage processing clusters.
Belgium
Brussels and Bruges praline heritage clusters anchor European craft chocolate tourism and certified-origin export demand. EFSA labeling requirements for cocoa content substantiation shape product development protocols for bean-to-bar specialists. The Flanders region concentrates small-batch conching facilities serving boutique distribution networks across the Benelux.
Switzerland
Zurich and Geneva premium gifting corridors sustain ceremonial chocolate exchange traditions among corporate and affluent consumer segments. Swissmedic food-contact regulations govern decorative packaging materials for luxury assortments. The Lake Geneva basin hosts vertically integrated processors controlling Ecuadorian sourcing through captive supply relationships.
Germany
Cologne and Berlin e-commerce platforms drive subscription gifting model expansion with curated monthly deliveries penetrating corporate procurement. EU Green Deal deforestation-free sourcing mandates lock premium producers into certified supply chains. The Rhine-Ruhr metropolitan corridor concentrates specialty store flagship locations commanding experiential retail premiums.
France
Parisian pharmacy retail channels concentrate health-positioned dark chocolate demand among flavanol-conscious consumers. ANSM and EFSA joint oversight tightens cardiovascular benefit claim substantiation requirements. The Île-de-France region anchors staff-guided tasting boutiques displacing supermarket impulse purchasing.
Netherlands
Amsterdam and Rotterdam digital infrastructure supports fastest-growing online retail penetration for subscription and direct-to-consumer models. REACH compliance affects food-contact packaging migration limits for premium wrapping materials. The Randstad cluster integrates bean-to-bar traceability technology with blockchain-based farm-to-wrapper documentation systems.
Europe Premium Chocolate Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tiering that separates heritage Belgian praline houses from Swiss-scale processors and emerging craft brands. The vendor base stratifies around three archetypes: vertically integrated origin controllers, boutique heritage specialists, and agile craft challengers deploying small-batch technology. Dominant competitive moves include strategic partnerships for EUDR traceability infrastructure and portfolio diversification into Ruby chocolate ingredient supply.
Within the heritage specialist tier, Neuhaus NV and Pierre Marcolini Group occupy positions exemplifying controlled boutique distribution and Belgian praline craftsmanship. Chocoladefabriken Lindt & Sprüngli AG anchors the scale-driven integrated processor archetype with Swiss-registered vertical control from sourcing through retail. These three entities represent distinct competitive positioning vectors: heritage exclusivity, artisanal provenance storytelling, and captive supply chain mastery.
| Leading Market Players |
|---|
| Nestlé SA |
| Neuhaus NV |
| Chocoladefabriken Lindt & Sprüngli AG |
| Yıldız Holding |
| Pierre Marcolini Group |
| Ferrero International SA |
| Mars Incorporated |
| Cemoi Group |
| Mondelez International Inc |
| Others |
Cost & Logistics Intelligence
The Flanders region's small-batch conching capacity concentration shapes downstream pricing power for Belgian bean-to-bar processors serving German specialty retail corridors. EUDR traceability compliance premiums and cocoa butter input volatility are compressing margins for processors locked into fixed-price retail contracts.
Pricing Analysis
Processing-technology pricing gaps separate legacy conching equipment from next-generation precision tempering systems and emerging blockchain-verified origin documentation tiers. Three-tier pricing structure across super-premium, premium, and affordable luxury levels stratifies by certification grade and provenance documentation depth. Price differentiation rests on EFSA-compliant flavanol quantification and single-origin cooperative payment transparency. Cost compression in the affordable luxury tier is intensifying because mass-market brands are mimicking heritage packaging cues. Corporate gifting segments show lowest price sensitivity; individual health-motivated self-purchase segments demand value transparency.
Supply Chain Analysis
Fine-flavor cocoa bean stocks from Ecuador, Venezuela, and Madagascar anchor upstream feedstock dependencies for European premium chocolate production. Processing draws from West African bulk cocoa butter, Swiss packaging material suppliers, and Dutch logistics hubs. Single-origin supply concentration creates tariff exposure and climate-driven harvest volatility risks. Distribution runs through Belgian heritage boutique networks, German e-commerce subscription platforms, and Swiss hospitality procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
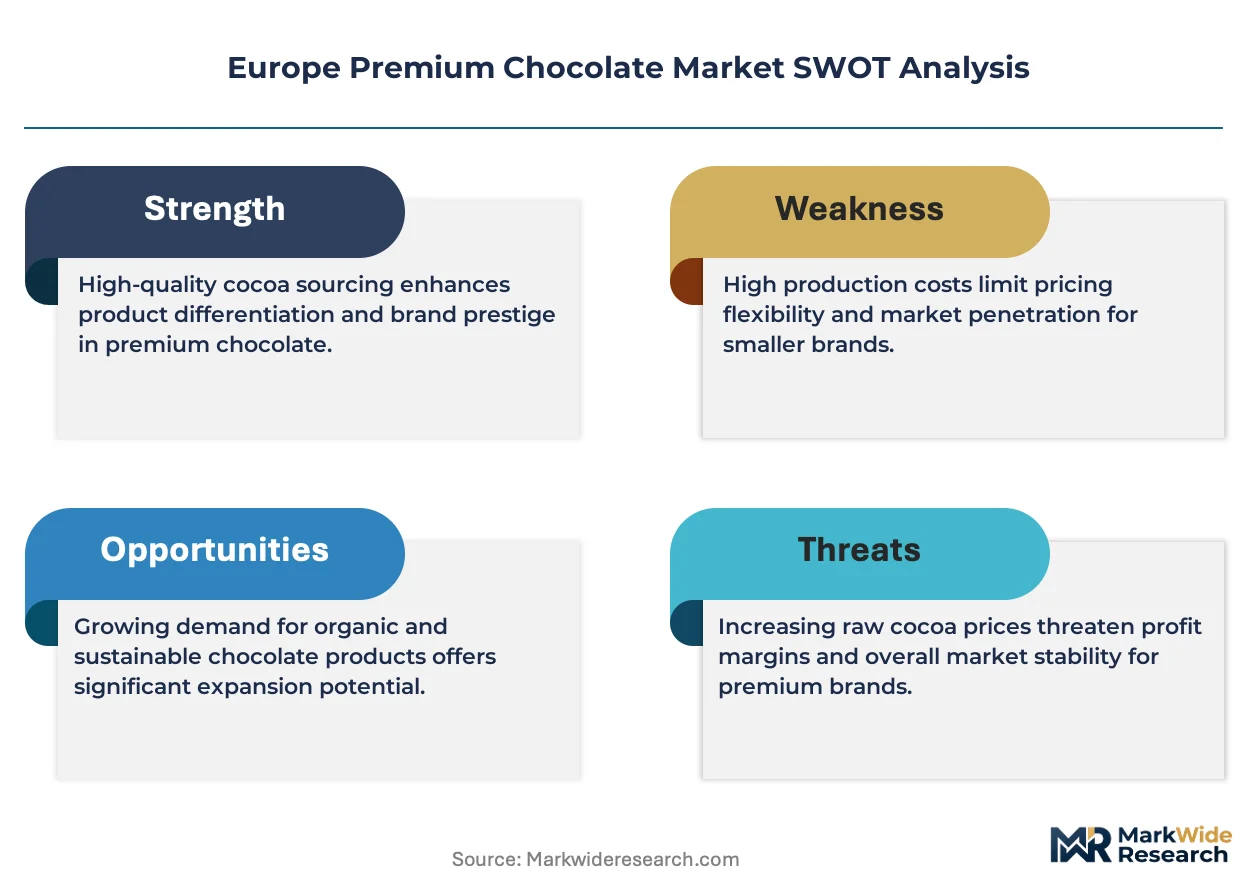
Premium chocolate incumbents must defend against plant-based confectionery substitutes and functional snack alternatives that are capturing health-positioned trial occasions. Substitution threats from adaptogenic and protein-enriched snacking categories require portfolio repositioning.
For Market Incumbents: Pre-empt craft brand encroachment by securing captive Ecuadorian fine-flavor supply through cooperative equity stakes. Consolidate EUDR traceability infrastructure investment before full enforcement locks in preferential retailer access. Channel control through flagship specialty store expansion in Paris and Zurich corridors defends margin capture against digital-native entrants.
For New Entrants and Emerging Players: French pharmacy retail channels represent underpenetrated white-space for EFSA-compliant flavanol-positioned dark chocolate. Corporate gifting subscription models in Frankfurt and Amsterdam offer recurring revenue with minimal physical footprint requirements. Bean-to-bar transparency storytelling provides the most penetrable go-to-market angle against heritage brand opacity.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-moat play because EUDR compliance infrastructure and EFSA health claim permissions create irreproducable regulatory assets. Acquisition targets should display vertically integrated origin relationships and blockchain traceability deployment. The signal to watch is EUDR enforcement acceleration triggering distressed supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Traceability Infrastructure Investment | Blockchain farm-to-wrapper documentation secures preferential access to EDEKA and Carrefour shelf resets. |
| Ruby Chocolate Ingredient Supply Expansion | Pink-hued couverture penetration into bakery and ice cream channels extends addressable market beyond confectionery. |
| Specialty Store Flagship Expansion | Staff-guided tasting boutiques in Brussels and Zurich command price premiums unavailable through supermarket distribution. |
| Subscription Gifting Model Launch | Curated monthly deliveries through German e-commerce platforms build recurring revenue with minimal working capital intensity. |
| EFSA Health Claim Compliance Investment | Standardized (-)-epicatechin analytical protocols preserve cardiovascular benefit labeling permissions for dark chocolate portfolios. |
Research Approach
Initial hypotheses were tested against primary input from master chocolatiers, specialty store buyers, cocoa cooperative managers, and EFSA regulatory consultants and refined through secondary validation. Primary stakeholder interviews combined with customs trade data, EFSA guidance document archives, Nielsen retail audit records, and EU Green Deal implementation tracking supplied triangulation anchors. Bottom-up volume modeling across production facilities and top-down expenditure analysis across consumer segments converged on demand estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end-user occasion, and price tier stratification. CAGRs were derived from regression analysis of historical premium chocolate expenditure patterns and elasticity-adjusted volume projections. Forecast inputs incorporated cocoa futures curve movements and EUDR implementation phase transitions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Swiss processors or well-capitalized private-label entrants would shift outcomes. Cocoa butter price spikes beyond historical volatility bands or accelerated EUDR enforcement timelines represent specific revision triggers. Cross-checking against Euromonitor International's chocolate confectionery expenditure series is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Germany Chocolate Market
Confectionery
Caramel Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
Global Candy Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
Gummy Candy Market
Confectionery
Edible Glitter Market
Confectionery
Confectionery Fats Market
Confectionery
Sugar-Free Chocolate Market
Confectionery
Italy Chocolate Market
Confectionery
North America Marshmallow Market
Confectionery
Sugarless Chocolate Market
Confectionery
Sugar-Free Sweets Market
Confectionery
Middle East Chocolate Market
Confectionery
Japan Chocolate Market
Confectionery
Confectionery Coating Market