
 Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market | 2026-2036
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market Intelligence
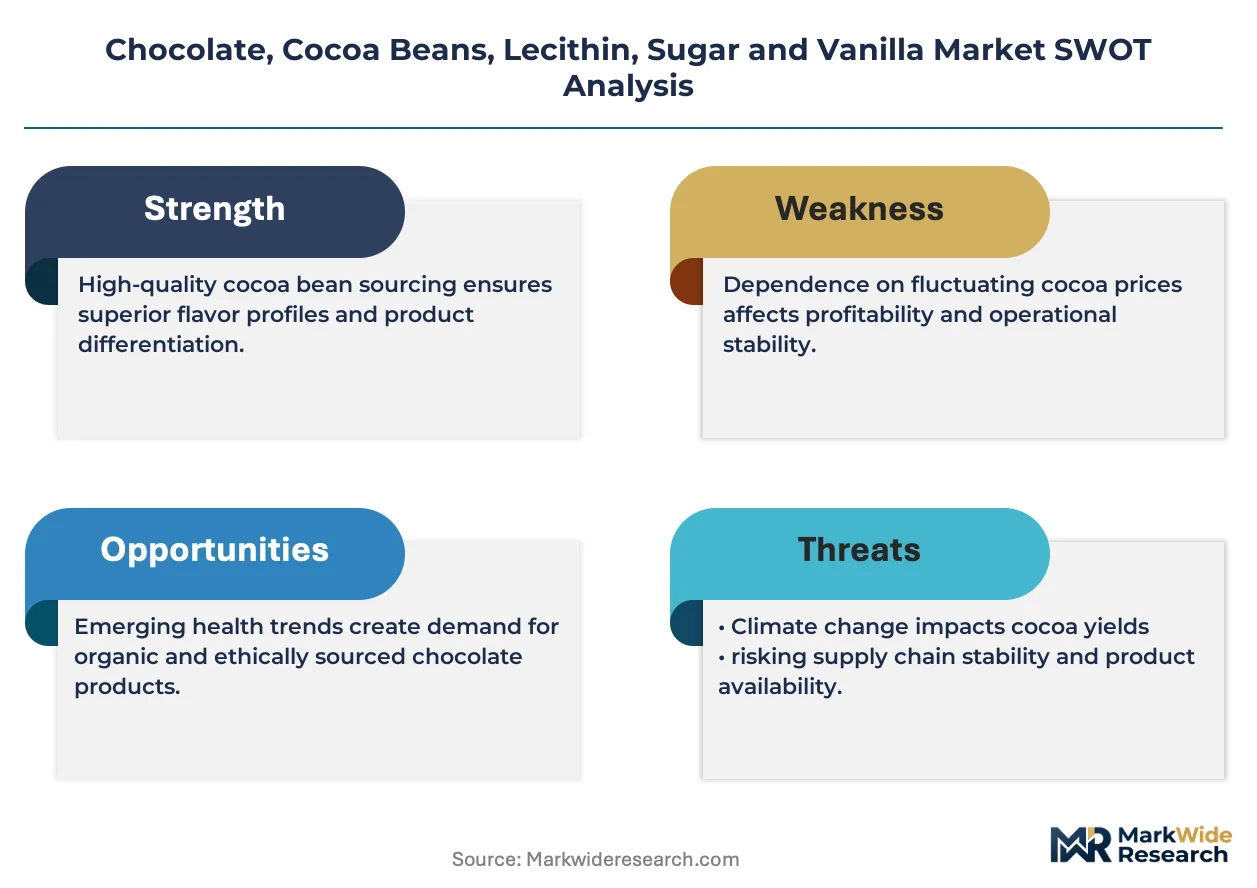
The gap between artisanal bean-to-bar chocolate and mass-market compound coatings is recalibrating procurement strategies across the value chain. Barry Callebaut AG leverages its integrated cocoa processing network to secure long-term bean supply from West African cooperatives. Cargill Inc. competes through its sustainability certification programs that lock in premium pricing for traceable cocoa. The Hershey Company anchors North American confectionery demand with backward integration into sugar refining and chocolate liquor production.
Chocolate, cocoa beans, lecithin, sugar and vanilla constitute the foundational inputs for confectionery, bakery and beverage formulations, with cocoa butter requiring precise tempering curves between 31°C and 32°C to achieve stable polymorphic crystal structures. Dark chocolate and milk chocolate segments dominate value capture in retail channels, while cocoa powder and liquid lecithin concentrate in industrial food service applications where emulsification and fat-reduction properties command formulation premiums. White chocolate occupies a narrower niche among premium bakeries despite its absence of cocoa solids.
FDA food additive regulations and the EU Deforestation Regulation shape import compliance costs for cocoa and vanilla, while ISO 22000 and HACCP protocols govern lecithin processing standards across European and North American facilities. Brazil's ANVISA and India's FSSAI enforce progressively stricter contaminant thresholds for imported chocolate ingredients, tightening market access for unverified suppliers. Stakeholders must monitor evolving traceability mandates and bean-to-bar certification requirements as procurement decisions increasingly hinge on documented origin rather than commodity pricing alone.
Market Dynamics
The EU Deforestation Regulation is forcing confectionery manufacturers to rebuild traceability infrastructure for cocoa and vanilla supply chains, compressing procurement timelines and elevating compliance costs across European processing facilities.
Growth Catalysts
- Clean-label confectionery demand:Retailers in Germany and France are expanding shelf space for single-origin dark chocolate and natural vanilla formulations, pulling procurement toward certified bean-to-bar suppliers.
- REACH-compliant lecithin processing:European refiners are investing in solvent-free extraction technologies to meet ECHA contaminant thresholds, opening premium formulation contracts for emulsifier-grade outputs.
- Côte d'Ivoire-Ghana cocoa concentration:Cooperative consolidation in West African growing regions is enabling long-term offtake agreements that stabilize input costs for industrial chocolate liquor buyers.
Market Restraints
- Cocoa butter price volatility:Weather-driven yield fluctuations in Ecuador and Indonesia are amplifying cost unpredictability for tempering-dependent chocolate manufacturers.
- Madagascar vanilla supply concentration:Cyclone exposure and political instability in the Sava region create single-point-of-failure risk for natural vanilla extract procurement.
- EU Deforestation Regulation compliance friction:Satellite-based traceability mandates and due diligence documentation requirements are extending lead times for cocoa bean imports into Rotterdam and Hamburg.
Strategic Opportunities
- Underpenetrated Brazilian sugar-ethanol integration:Northeastern mills are diverting cane crush toward crystalline sugar for confectionery, creating alternative supply corridors independent of Indian export quotas.
- Regenerative agriculture certification tailwinds:USDA Organic and EU Organic standards are creating price premiums for cocoa cooperatives adopting agroforestry systems in Cameroon and Nigeria.
- Direct-to-bakery liquid lecithin channels:Artisanal bread and pastry producers are bypassing distributor markups through tanker-truck delivery contracts with North American soy processing facilities.
Industry Challenges
- Bean-to-bar tempering technician scarcity:Precision control of cocoa butter polymorphic crystallization requires specialized operators, creating recruitment bottlenecks for mid-scale chocolate manufacturers.
- ISO 22000 certification timeline compression:Lecithin refiners face accelerated audit cycles as European buyers demand concurrent HACCP and FSSC 22000 documentation for supplier qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market |
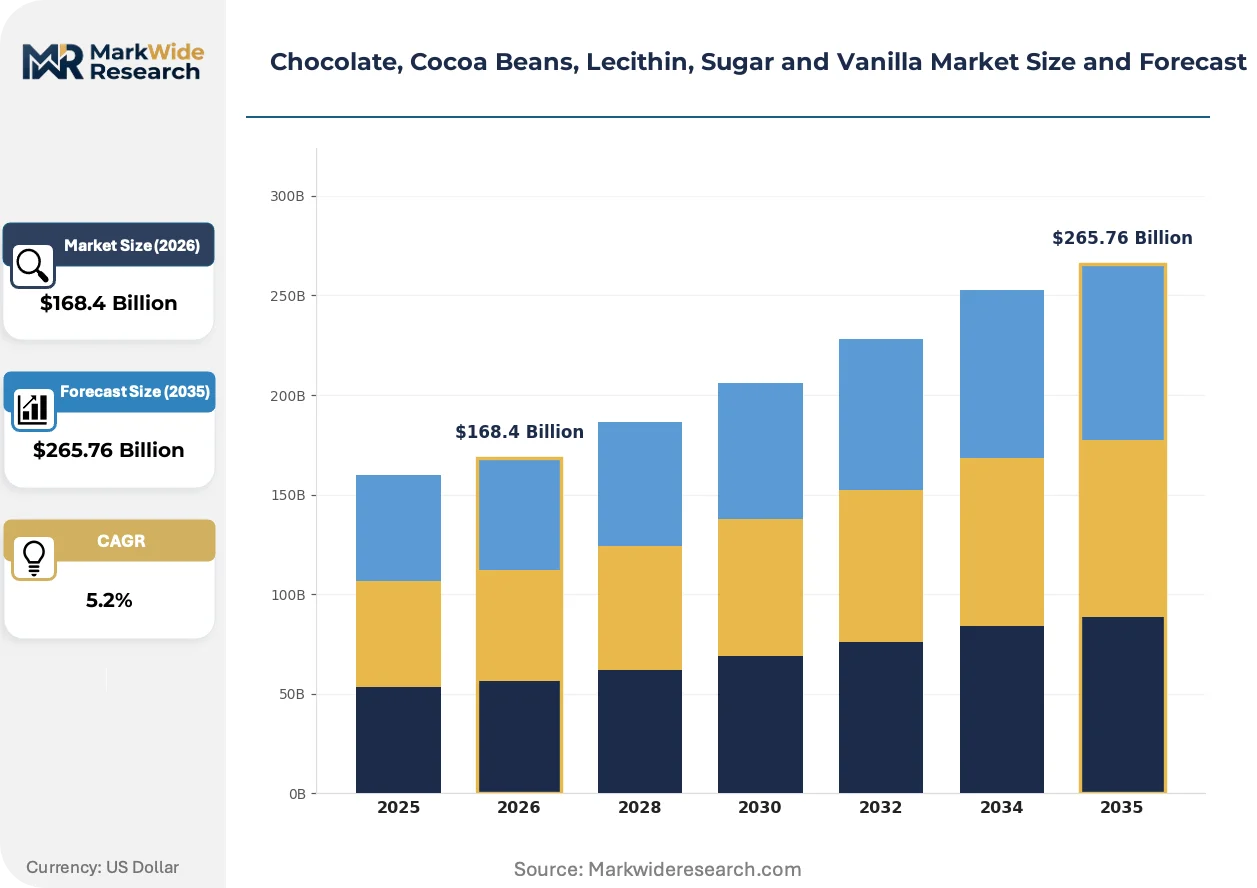
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $265.76 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Cocoa Powder Ingredient Type: Cocoa Beans, Lecithin, Sugar, Vanilla Extract End User: Confectionery Manufacturers, Bakeries, Food Service, Retail Form: Blocks, Chips, Liquids, Powders |
| Companies Covered | FUJI OIL CO., LTD., United Cocoa Processor, Inc., Barry Callebaut AG, Puratos Group, Touton S.A., Cargill Inc., Guan Chong Berhad, Tradin Organic Agriculture B.V., The Hershey Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market Strategic Shifts & Innovations
Blockchain-enabled provenance tracking is compressing the distance between cocoa cooperatives and finished chocolate brands, while novel extraction methods are expanding the functional applications of lecithin beyond traditional emulsification.
Blockchain-based farm-to-fork traceability platforms are decentralizing supply chain verification for cocoa and vanilla. Mid-tier confectionery brands in the Netherlands and Belgium are adopting these systems fastest, pressured by retailer ESG mandates. This technology is decentralizing audit authority away from third-party certifiers toward immutable ledger records that buyers can query directly.
The EU Deforestation Regulation's due diligence requirements are reshaping import documentation for cocoa beans and vanilla pods entering European customs territories. Processors must now submit geolocation coordinates for every production plot in their supply base. Dark chocolate and single-origin product lines face the steepest compliance burden, with several German manufacturers accelerating supplier requalification programs to meet December enforcement deadlines.
Buyer consolidation among industrial bakery and confectionery groups is compressing ingredient sourcing cycles for lecithin and cocoa butter. Large-scale manufacturers are consolidating purchase orders through preferred supplier frameworks, displacing spot-market transactions. This concentration is most visible in North American food service channels, where national bakery chains are negotiating multi-year liquid lecithin contracts with captive pricing clauses.
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market Segmentation
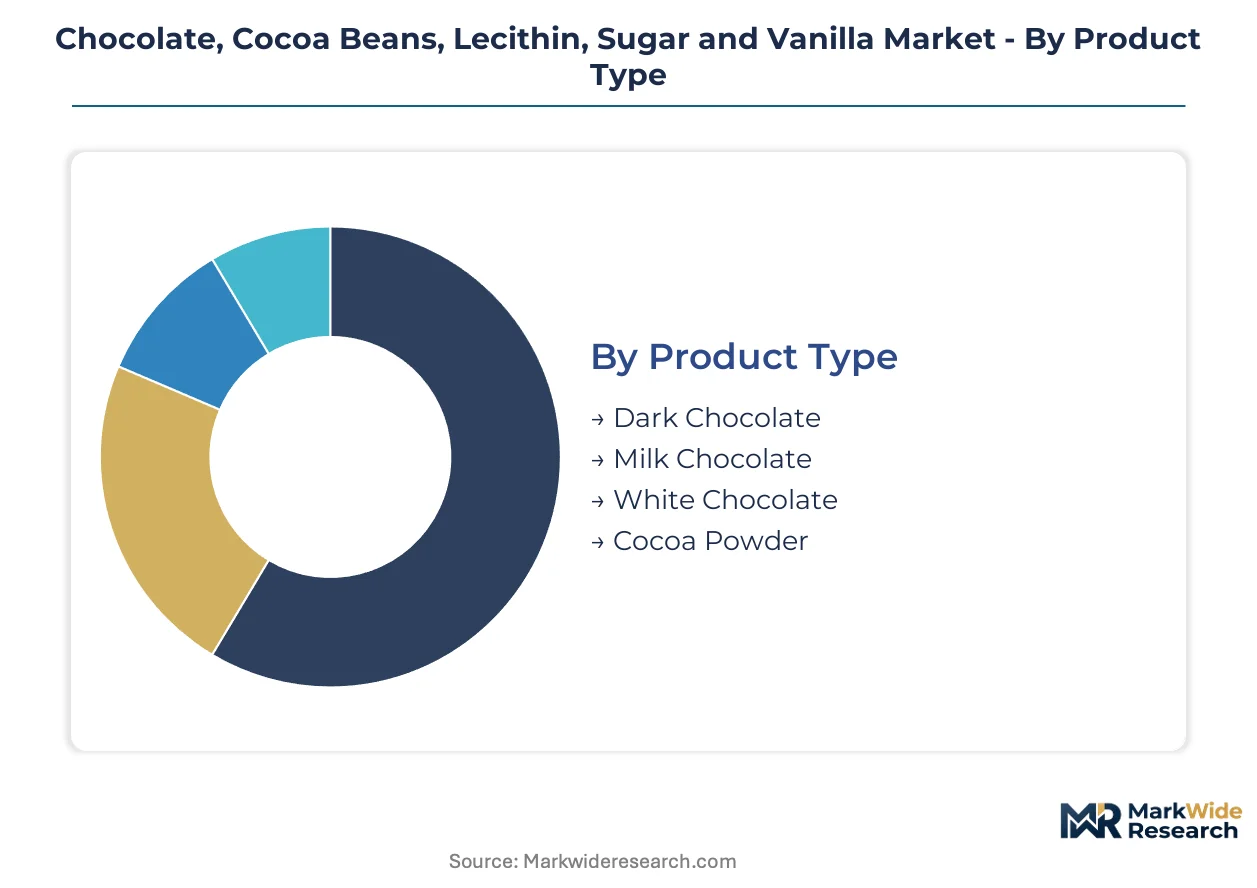
Segmentation in the Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market reveals divergent value capture strategies across artisanal bean-to-bar producers and industrial compound manufacturers. Procurement patterns, tempering requirements, and regulatory compliance burdens vary sharply by product form and end-user channel.
Product Type:
The customization-standardization spectrum spans from artisanal single-origin dark chocolate with precise tempering protocols to mass-market milk chocolate optimized for high-speed enrobing lines.
- Dark Chocolate:Cocoa butter content exceeds 35% with minimal dairy solids, demanding polymorphic crystal control between 31°C and 32°C during tempering. Bean-to-bar manufacturers in Belgium and Switzerland concentrate procurement here, drawn by premium shelf positioning and EU Deforestation Regulation traceability premiums.
- Milk Chocolate:Formulated with 10-12% milk solids and lower cocoa mass, engineered for snap and melt profiles suitable for high-volume molding operations. North American confectionery manufacturers anchor volume demand, leveraging backward integration into sugar refining to compress input costs.
- White Chocolate:Cocoa butter base without cocoa solids, occupying narrow premium bakery niches in France and Japan where fat content regulations constrain formulation flexibility.
- Cocoa Powder:Press cake-derived alkalized or natural powder, concentrating in industrial beverage and bakery applications where fat reduction and color standardization command formulation premiums.
Most installed capacity flows through Milk Chocolate. Expansion is steepest in Dark Chocolate.
Ingredient Type:
Cost tier stratification separates commodity-grade inputs from certified-origin materials commanding documentation premiums.
- Cocoa Beans:Forastero, Criollo, and Trinitario varietals with fermentation and drying protocols determining flavor precursor development. West African cooperative supply dominates industrial channels, while Ecuadorian and Venezuelan fine-flavor beans concentrate in premium chocolate liquor production.
- Lecithin:Soy and sunflower-derived phospholipid emulsifiers, with solvent-free extraction methods gaining share in European REACH-compliant formulations.
- Sugar:Crystalline sucrose from Brazilian cane mills or European beet processors, with Northeastern Brazilian supply corridors expanding as alternatives to Indian export quota dependence.
- Vanilla Extract:Bourbon and Tahitian vanilla species, with Madagascar Sava region supply concentration creating cyclone exposure risk for natural extract procurement.
Volume concentration sits with Cocoa Beans. Value expansion is climbing fastest in Vanilla Extract.
End User:
Application-driven specification divergence separates artisanal tempering requirements from industrial emulsification tolerances.
- Confectionery Manufacturers:Integrated chocolate liquor production with precise viscosity and temper curve specifications for enrobing and molding lines.
- Bakeries:Compound coatings and cocoa powder concentrates where fat bloom resistance and moisture tolerance override snap quality.
- Food Service:Liquid lecithin and cocoa butter applications in sauce and dessert formulations requiring stable emulsion performance.
- Retail:Packaged chocolate blocks and chips with clean-label certification and single-origin provenance documentation for shelf differentiation.
Procurement volume concentrates in Confectionery Manufacturers. Specification complexity is expanding most quickly in Retail.
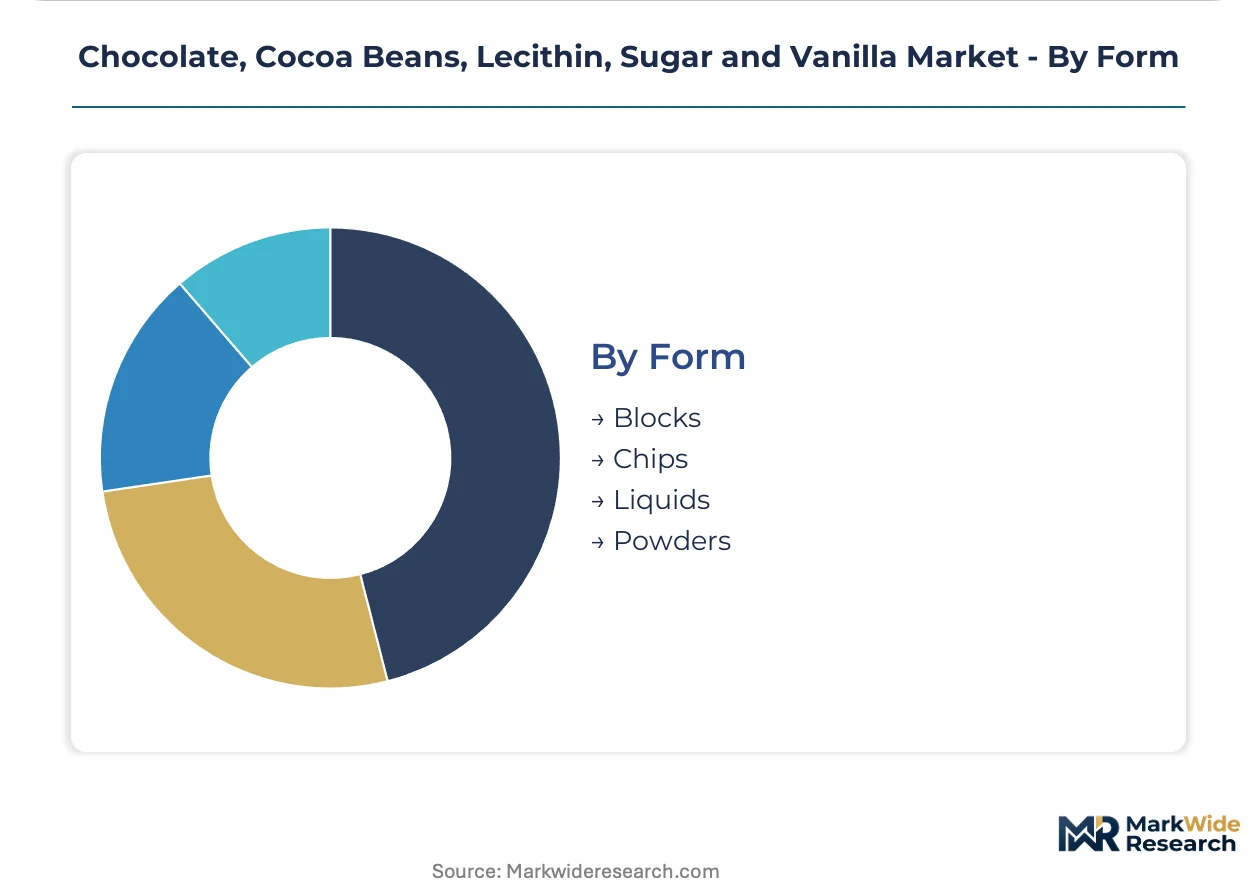
Form:
Supply chain configuration separates bulk liquid and powder logistics from solid tempering-dependent distribution.
- Blocks:Tempered solid chocolate requiring controlled temperature storage through 18-20°C ranges to prevent fat bloom and polymorphic destabilization.
- Chips:Count-controlled drops optimized for industrial bakery dispersion and melting point standardization.
- Liquids:Tanker-truck delivered chocolate liquor and lecithin for high-volume confectionery and food service channels.
- Powders:Cocoa powder and spray-dried vanilla concentrates for beverage and dry mix applications.
Distribution infrastructure concentrates in Liquids. Investment in controlled-temperature capacity is expanding most quickly in Blocks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss and Belgian chocolate technicians anchor European artisanal production networks, while West African agronomists and Brazilian cane engineers concentrate upstream supply. These talent pools shape procurement corridors across four distinct national markets.
Germany
Confectionery manufacturers in Cologne and Hamburg drive demand for traceable cocoa liquor and lecithin emulsifiers. The EU Deforestation Regulation forces processors to submit geolocation coordinates for every West African plot in their supply base. The Hamburg-Rotterdam processing corridor now hosts accelerated supplier requalification programs ahead of December enforcement deadlines.
United States
Pennsylvania and Illinois chocolate manufacturers anchor North American demand for milk chocolate and compound coatings. FDA food additive regulations govern cocoa butter tempering standards and lecithin contaminant thresholds. The Hershey-Philadelphia corridor maintains backward integration into sugar refining and chocolate liquor production to compress input costs.
Brazil
Northeastern cane mills in Pernambuco and Alagoas divert crush toward crystalline sugar for confectionery applications. ANVISA enforces progressively stricter contaminant thresholds for imported chocolate ingredients, tightening market access for unverified suppliers. The São Paulo-Ribeirão Preto corridor hosts expanding liquid lecithin processing capacity for South American bakery chains.
Switzerland
Bean-to-bar specialists in Zurich and Vevey concentrate procurement of Ecuadorian and Venezuelan fine-flavor cocoa beans. Swissmedic oversees food contact material regulations for chocolate packaging and processing equipment. The Lake Geneva corridor maintains precision tempering facilities where polymorphic crystal control between 31°C and 32°C commands technical premiums.
Belgium
Artisanal chocolatiers in Brussels and Antwerp expand shelf space for single-origin dark chocolate with documented provenance. ECHA REACH compliance drives investment in solvent-free lecithin extraction technologies. The Port of Antwerp corridor processes increasing volumes of certified cocoa beans under blockchain-enabled traceability platforms.
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market Key Industry Players
Capital-heavy cocoa processors compete with asset-light ingredient traders across tiered market positions. The structure concentrates around integrated grinders with West African cooperative networks and specialty lecithin refiners with REACH-compliant extraction capacity. Three archetypes dominate: vertically integrated chocolate liquor producers, certified-origin bean traders, and emulsifier specialists with food-service tanker-truck delivery capabilities. Competitive moves center on long-term offtake agreements with West African cooperatives and multi-year liquid lecithin contracts with captive pricing clauses.
Within the integrated processing tier, Barry Callebaut AG and Cargill Inc. exemplify capital-heavy archetypes with West African sourcing infrastructure. Among North American confectionery manufacturers, The Hershey Company occupies a position representing backward integration into sugar refining and chocolate liquor production. These three entities anchor competitive dynamics across procurement, processing, and retail channel access.
| Leading Market Players |
|---|
| FUJI OIL CO., LTD. |
| United Cocoa Processor, Inc. |
| Barry Callebaut AG |
| Puratos Group |
| Touton S.A. |
| Cargill Inc. |
| Guan Chong Berhad |
| Tradin Organic Agriculture B.V. |
| The Hershey Company |
| Others |
Cost & Logistics Intelligence
The EU Deforestation Regulation gates qualified supply and premium-tier pricing access for cocoa and vanilla procurement, forcing processors to absorb traceability infrastructure costs or forfeit European market entry. Buyers now pay documentation premiums for geolocation-verified beans, while unverified suppliers face exclusion from Rotterdam and Hamburg processing corridors.
Pricing Analysis
Ingredient-plus-certification bundling separates spot-market commodity cocoa from long-term offtake agreements with cooperative traceability guarantees. Price differentiation rests on EU Deforestation Regulation compliance status and organic certification tier, with compliant suppliers capturing premium positioning. Pricing pressure stems from Madagascar vanilla cyclone exposure and West African cocoa butter volatility. Industrial confectionery manufacturers exhibit highest price sensitivity, while artisanal bean-to-bar producers absorb premiums for documented provenance.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Antwerp consolidate cocoa bean intake before forwarding to chocolate liquor processing facilities across Belgium and Switzerland. Supply concentrates in Côte d'Ivoire, Ghana, and Madagascar for cocoa and vanilla, with Brazilian cane mills feeding crystalline sugar demand. Raw material dependencies include fermented cocoa beans, solvent-extracted lecithin, and Bourbon vanilla pods. Single-source vulnerability in the Sava region threatens natural extract continuity. Distribution runs through tanker-truck liquid channels for industrial buyers and temperature-controlled block storage for artisanal tempering operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on backward integration into sugar refining and chocolate liquor production, compressing input costs for scale manufacturers while premium-tier positioning rewards traceability investment.
For Market Incumbents: Anchor procurement advantage through long-term cooperative offtake agreements in West African growing regions, locking bean supply ahead of EU Deforestation Regulation enforcement. Expand solvent-free lecithin extraction capacity to capture REACH-compliant formulation contracts. Defend against emerging blockchain-native traceability platforms by accelerating supplier requalification programs.
For New Entrants and Emerging Players: Artisanal bakery chains represent an underserved buyer archetype seeking direct-to-producer liquid lecithin contracts bypassing distributor markups. Target Northeastern Brazilian sugar corridors as alternative supply sources independent of Indian export quotas. Pursue regenerative agriculture certification pathways in Cameroon and Nigeria to capture USDA Organic and EU Organic price premiums.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale cocoa processors with established West African cooperative networks because compliance infrastructure amortizes across combined volumes. The five-to-ten year viability window favors platforms consolidating traceable bean supply. Acquisition targets should demonstrate satellite-based geolocation documentation and HACCP certification. Watch for EU Deforestation Regulation enforcement acceleration as inflection indicator for premium-tier pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Cooperative Offtake Agreements | Barry Callebaut and Cargill lock West African bean supply ahead of regulatory deadlines. |
| Solvent-free Lecithin Extraction Investment | European refiners meet ECHA REACH thresholds to secure emulsifier-grade formulation contracts. |
| Blockchain-enabled Traceability Platform Adoption | Dutch and Belgian mid-tier brands satisfy retailer ESG mandates through immutable ledger verification. |
| Backward Integration into Sugar Refining | The Hershey Company compresses input costs through captive Pennsylvania sugar processing capacity. |
| Regenerative Agriculture Certification Programs | Cameroon and Nigerian cooperatives capture organic price premiums through agroforestry system adoption. |
Research Approach
Direct dialogue with cocoa cooperative managers, chocolate liquor procurement directors, lecithin refinery technical leads, and European confectionery regulatory affairs officers grounded qualitative findings. Secondary validation drew from EU Deforestation Regulation implementation guidance, FDA food additive filings, ECHA REACH substance registrations, and West African customs trade data. Bottom-up volume modeling across cooperative supply tiers triangulated against top-down value estimates from processing facility capacity disclosures.
Bottom-up segment analysis modeled product type splits across dark, milk, and white chocolate alongside ingredient-grade stratification and end-user channel configuration. CAGRs were derived from weighted average growth contributions across these segmentation dimensions. Forecast inputs incorporated tempering-dependent manufacturing capacity constraints, EU Deforestation Regulation compliance timeline assumptions, and Madagascar vanilla cyclone frequency patterns.
Inputs from cooperative export records and European processing facility utilization reports were available through the study window; gaps in real-time satellite verification coverage introduce uncertainty bands around traceability compliance projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
US Dark Chocolate Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
Asia-Pacific Sugar Free Mints Market
Confectionery
Carob Chocolate Market
Confectionery
Sugar Free Lollipops Market
Confectionery
Global Candy Market
Confectionery
Chocolate Flavors Market
Confectionery
Caramel Market
Confectionery
Global Industrial Chocolate Market
Confectionery
China Chocolate Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Boiled-Cooked Icing Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
India Chocolate Market
Confectionery
Europe Confectionery Market