
 MENA Artificial Intelligence Market | 2026-2036
MENA Artificial Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
MENA Artificial Intelligence Market Analytics
Buyer concentration among Gulf government entities is repositioning procurement dynamics across the MENA AI landscape. G42 leverages sovereign cloud infrastructure to anchor UAE federal contracts. Presight AI competes on analytics specialization for public safety and urban intelligence. Humain sustains R&D intensity through partnerships with Saudi research institutions.
Artificial intelligence in the MENA region encompasses machine learning algorithms, natural language processing systems, and computer vision architectures deployed for predictive analytics, automation, and decision augmentation across commercial and government operations. Solutions dominate current revenue as governments prioritize turnkey systems over custom development, while cloud-based deployment expands fastest where telecom infrastructure supports edge-to-core latency requirements. Machine learning occupies the deepest margin pools due to scarcity of Arabic-language training data and localized model expertise.
SAMA, the UAE's National Artificial Intelligence Office, and Saudi Data and Artificial Intelligence Authority shape demand through data sovereignty mandates, algorithmic procurement standards, and sector-specific licensing for financial and healthcare applications. Compliance with these frameworks determines market access for foreign platform providers and creates preference for locally hosted inference infrastructure. Stakeholders must monitor evolving certification requirements for high-risk AI deployments in government and regulated sectors.
Market Dynamics
Sovereign AI procurement mandates across Saudi Arabia and the UAE are consolidating public sector demand around locally hosted inference infrastructure, compressing vendor selection pools and elevating data residency compliance above technical performance in contract awards.
Growth Catalysts
- Saudi Vision 2030:National transformation targets allocate concentrated capital toward smart city infrastructure and sovereign AI capabilities, creating anchor demand for predictive analytics platforms in Riyadh.
- Arabic NLP scarcity:Limited training data availability for Arabic-language models creates premium pricing power for localized machine learning expertise and proprietary dataset development.
- Dubai fintech licensing:Regulatory frameworks for digital banking and insurtech generate specialized demand for algorithmic decision systems in credit scoring and fraud detection.
Market Restraints
- NVIDIA GPU supply concentration:Inference hardware dependency on single-source advanced semiconductor suppliers exposes deployment timelines to export control volatility and allocation rationing.
- Data center power constraints:Gulf cooling requirements and grid capacity limitations restrict training cluster scale in Dubai and Riyadh, forcing workload distribution across fragmented facilities.
- SAMA algorithmic certification:Saudi banking regulator's mandatory model validation protocols extend procurement cycles by 8-14 months for financial sector deployments.
Strategic Opportunities
- Egyptian public sector digitization:Cairo government modernization programs remain undersupplied with Arabic-language automation tools, creating first-mover positioning for compliant solution providers.
- Edge-to-core convergence:5G infrastructure rollout in UAE and Saudi Arabia enables distributed inference architectures that reduce latency for real-time computer vision in logistics and security.
- Healthcare AI carve-outs:MOHAP's specialized licensing pathway for diagnostic algorithms creates regulated entry points for radiology and pathology automation in Abu Dhabi health systems.
Industry Challenges
- Arabic data engineering talent:Scarce pipeline of bilingual machine learning engineers with regional domain expertise forces reliance on expensive expatriate hiring or offshore development partnerships.
- Legacy system integration:Government and banking core infrastructure built on decades-old architectures requires costly middleware development to enable API connectivity with modern AI stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA Artificial Intelligence Market |
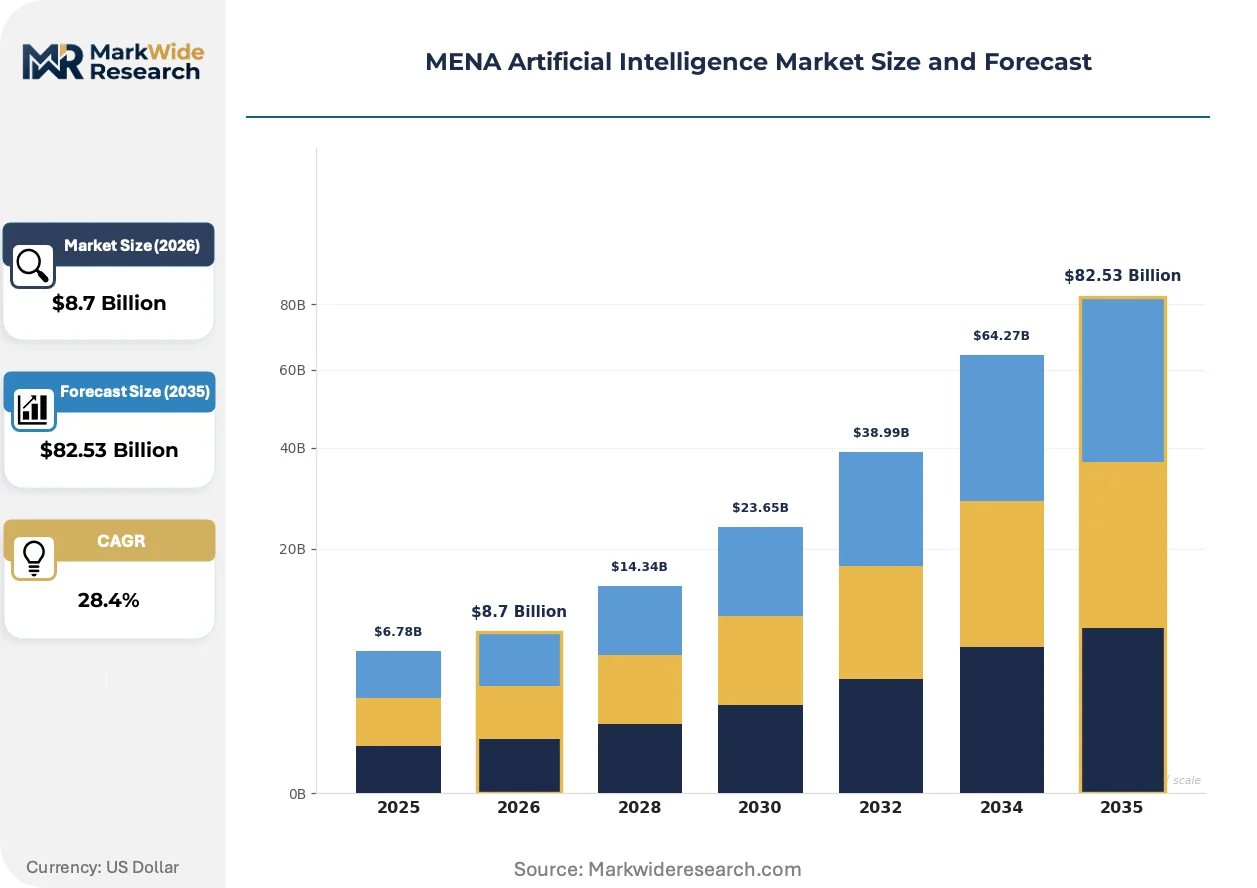
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solutions, Services, Platforms, Tools End User: Healthcare, Retail, Finance, Government Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Lumitech FZCO, Humain, G42, OctoXLabs, SoluLab, Presight AI, Singula, Ai, Intelmatix, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA Artificial Intelligence Market Evolving Landscape
Foundation model architectures are absorbing specialized vertical applications across MENA government and enterprise deployments, compressing the traditional segmentation between general-purpose platforms and industry-specific solutions.
Large language model fine-tuning for Arabic dialects is absorbing scarce GPU resources previously allocated to computer vision projects, redirecting R&D budgets toward linguistic capabilities. Saudi research institutions and UAE federal agencies are prioritizing conversational AI procurement over predictive maintenance systems. This resource reallocation is compressing margin pools for established analytics vendors while elevating specialized NLP providers in Riyadh and Dubai contract competitions.
SAMA's Model Risk Management Guidelines and the UAE National Artificial Intelligence Office's algorithmic impact assessment mandates are formalizing documentation requirements for high-stakes financial and government deployments. These frameworks extend procurement timelines but create compliance-based differentiation for vendors with pre-certified infrastructure. Banking and public safety sectors are responding by embedding regulatory specialists within technical sales teams to accelerate validation cycles.
Buyer concentration among Gulf sovereign wealth vehicles and federal ministries is consolidating procurement authority under centralized technology funds, displacing departmental-level software purchasing. System integrators and global cloud providers are restructuring MENA go-to-market around single-window government relationships rather than distributed enterprise sales. This pattern is most visible in Saudi Arabia, where SDAIA's unified contracting framework aggregates demand across previously siloed ministry budgets.
MENA Artificial Intelligence Market Segmentation
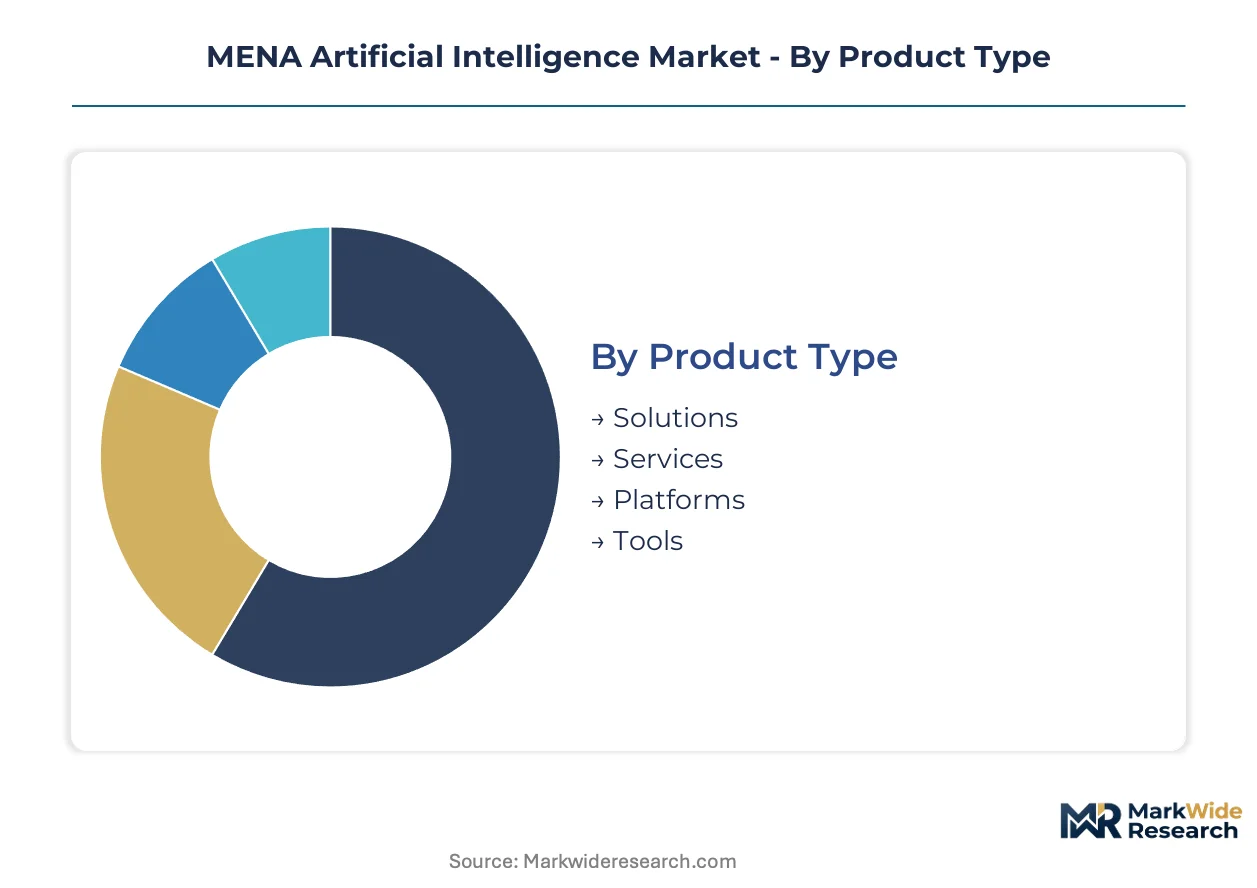
MENA AI procurement patterns fragment across four structural dimensions, each carrying distinct compliance burdens and infrastructure requirements. Certification mandates from SAMA, SDAIA, and UAE's National Artificial Intelligence Office create asymmetric barriers that reshape competitive positioning within each segment cluster.
Product Type:
SAMA's algorithmic certification protocols and UAE federal procurement standards impose divergent documentation requirements across product categories, with sovereign cloud hosting mandates favoring certain delivery models.
- Solutions:Turnkey systems integrating pre-trained models with localized inference infrastructure dominate government contracts. Riyadh's smart city deployments and Dubai's federal AI procurement concentrate demand here, driven by compressed deployment timelines and SDAIA's unified contracting preferences.
- Services:Custom model development, Arabic dataset engineering, and regulatory compliance consulting command premium pricing. Scarce bilingual machine learning talent in the Gulf forces reliance on specialized service providers with pre-certified infrastructure.
- Platforms:End-to-end development environments with embedded sovereignty controls attract enterprise adopters seeking in-house Arabic NLP capabilities.
- Tools:Specialized utilities for data annotation, model monitoring, and bias detection serve mid-market adopters with limited IT resources.
Solutions sits at the top of the volume ranking, with Services climbing the fastest.
End User:
Customer-type concentration determines pricing power, with sovereign wealth-funded entities consolidating procurement authority and compressing vendor margins through volume commitments.
- Healthcare:Diagnostic algorithms and clinical decision support systems face MOHAP's specialized licensing pathway in Abu Dhabi. Radiology and pathology automation attract concentrated investment from UAE health systems seeking compliance-first deployment.
- Government:Federal ministries and smart city authorities aggregate demand through centralized technology funds. Saudi Arabia's SDAIA framework and UAE's federal AI office displace departmental purchasing with sovereign-scale contracts.
- Finance:Credit scoring and fraud detection systems navigate SAMA's 8-14 month model validation cycles. Algorithmic decision systems for digital banking concentrate in Dubai's licensed fintech ecosystem.
- Retail:Demand personalization and inventory optimization systems lag sovereign sector adoption due to thinner compliance mandates and dispersed customer bases.
Government procurement anchors absolute spending, while Healthcare gains share fastest on regulatory carve-out specialization.
Technology:
GPU allocation patterns across MENA research institutions reveal technology prioritization, with Arabic linguistic capabilities absorbing resources previously directed toward computer vision.
- Machine Learning:Predictive analytics platforms with Arabic-language training data scarcity command steepest margin premiums. Saudi research partnerships and proprietary dataset development sustain competitive moats for localized providers.
- Natural Language Processing:Large language model fine-tuning for Arabic dialects redirects R&D budgets from other technology verticals. Conversational AI procurement now outranks predictive maintenance in federal agency priorities.
- Computer Vision:Real-time inference for logistics and security applications leverages UAE and Saudi 5G infrastructure rollout.
- Robotics:Physical automation systems face integration complexity with legacy Gulf industrial infrastructure.
Machine Learning retains the deepest margin pools, with Natural Language Processing expanding most quickly on sovereign linguistic priority.
Deployment:
Infrastructure maturity and data sovereignty mandates create sharp segmentation in deployment preferences across the Gulf's fragmented data center landscape.
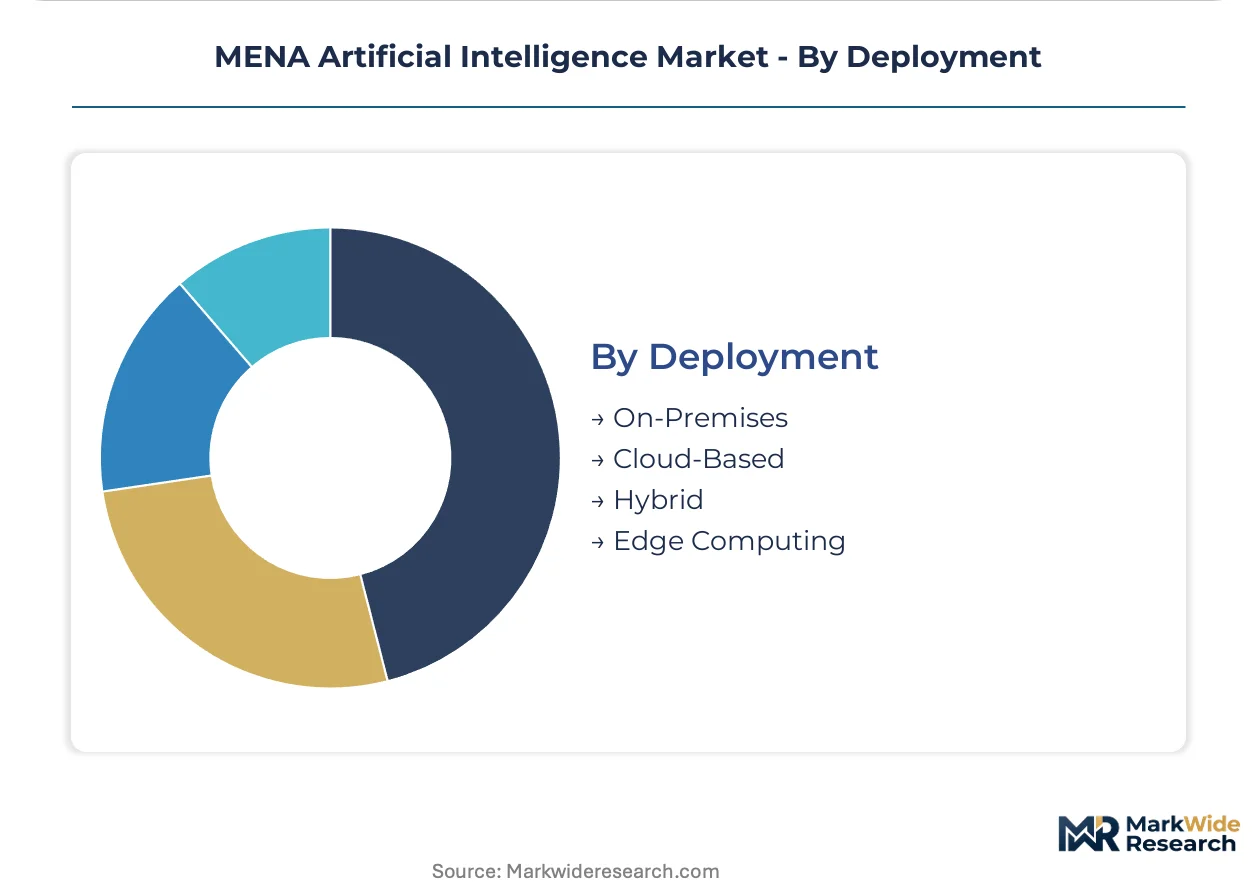
- Cloud-Based:Expansion accelerates where telecom infrastructure supports edge-to-core latency requirements. G42's sovereign cloud anchors UAE federal contracts with pre-certified compliance architecture.
- On-Premises:Air-gapped inference for classified government and financial workloads persists despite higher capital intensity. SAMA data residency mandates sustain preference for locally hosted infrastructure in Saudi banking.
- Hybrid:Split architectures balancing sensitive data on-premises with scalable compute in sovereign cloud environments attract mid-market enterprises.
- Edge Computing:Distributed inference for real-time computer vision depends on 5G density in Riyadh and Dubai logistics corridors.
Cloud-Based deployment leads current implementation scale, with Edge Computing gaining fastest on infrastructure convergence timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE command divergent procurement strategies despite shared sovereign AI ambitions, with Riyadh consolidating authority under SDAIA while Dubai maintains federal-local flexibility. Egypt and Qatar represent emerging demand centers where regulatory frameworks remain less codified.
Saudi Arabia
SDAIA's unified contracting framework aggregates previously siloed ministry budgets into sovereign-scale technology funds. SAMA's Model Risk Management Guidelines impose 8-14 month validation cycles on financial sector AI deployments. Riyadh anchors absolute regional spending through NEOM smart city infrastructure and concentrated capital allocation under Vision 2030 transformation targets.
United Arab Emirates
Dubai's fintech licensing regime generates specialized demand for algorithmic credit scoring and fraud detection systems. The National Artificial Intelligence Office mandates algorithmic impact assessments for high-stakes government deployments. Abu Dhabi's MOHAP diagnostic algorithm pathway creates regulated entry points for healthcare automation in federal health systems.
Egypt
Cairo government modernization programs remain undersupplied with Arabic-language automation tools relative to Gulf peers. The country's national AI strategy directs public sector digitization budgets toward sovereign capability development. Alexandria and Cairo tech corridors attract first-mover positioning from compliant solution providers seeking expansion beyond saturated Gulf markets.
Qatar
Qatar Foundation research partnerships sustain R&D investment in Arabic NLP capabilities despite smaller absolute procurement volumes. The country's national digitization office coordinates smart city investments around Doha's infrastructure modernization. Education City and Lusail development zones concentrate pilot deployments for computer vision and predictive analytics applications.
Israel
Tel Aviv's cybersecurity ecosystem generates adjacent demand for AI-enabled threat detection and anomaly recognition systems. The Israel Innovation Authority directs grant funding toward dual-use technology development with civilian applications. Haifa and Jerusalem research institutions maintain specialized expertise in computer vision and signal processing architectures.
MENA Artificial Intelligence Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the MENA AI landscape, with sovereign wealth-backed entities leveraging infrastructure scale against boutique analytics vendors. Market structure tilts toward consolidation as government procurement centralization compresses vendor selection pools. Three archetypes dominate: sovereign cloud operators with pre-certified compliance architecture, Arabic NLP specialists with proprietary dataset moats, and system integrators restructuring around single-window government relationships. Competitive dynamics center on regulatory pre-certification investments and strategic partnerships with Saudi research institutions.
Within the sovereign infrastructure tier, G42 anchors UAE federal contracting through compliant cloud hosting capabilities. Presight AI occupies a position exemplifying analytics specialization for public safety and urban intelligence deployments. Humain represents the R&D-intensive archetype, sustaining technical differentiation through institutional partnerships with Saudi data science programs.
| Leading Market Players |
|---|
| Lumitech FZCO |
| Humain |
| G42 |
| OctoXLabs |
| SoluLab |
| Presight AI |
| Singula |
| Ai |
| Intelmatix |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between SDAIA-prequalified sovereign cloud providers and uncertified commodity inference vendors manifests in both pricing power and supply chain sourcing strategies. Premium-tier contracts for Arabic NLP deployment in Riyadh and Dubai command substantial markups through bundled compliance architecture, while budget-tier procurement from Egyptian government digitization programs sources through fragmented reseller networks with minimal localization investment.
Pricing Analysis
Capacity additions in UAE sovereign cloud infrastructure are reshaping price floors for government AI procurement, compressing margins for mid-tier service providers lacking pre-certified hosting capabilities. Three-tier pricing structure across premium, standard, and economy levels separates G42-grade sovereign hosting from hybrid deployments and offshore development partnerships. Pricing pressure stems from SAMA's extended validation cycles, which force vendors to absorb compliance costs upfront. Government ministries show lowest price sensitivity due to consolidated technology funds, while Egyptian mid-market enterprises exhibit highest sensitivity to per-inference compute costs.
Supply Chain Analysis
Regional distribution centers in Dubai Internet City and Riyadh's King Abdulaziz City for Science and Technology form hub-and-spoke patterns for NVIDIA GPU allocation across Gulf deployment sites. Supply concentration in Taiwan, USA, and South Korea for advanced semiconductors creates single-source vulnerability for inference hardware procurement. Raw material dependencies span HBM memory modules, advanced packaging substrates, and liquid cooling systems. Distribution runs through sovereign wealth-backed technology funds rather than open market channels, with SDAIA and UAE's National Artificial Intelligence Office controlling allocation priority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MENA AI market functions as a stable compounder anchored by irreversible sovereign digitization commitments under Saudi Vision 2030 and UAE federal transformation programs.
For Market Incumbents: Lock in regulatory pre-certification investments before SDAIA and SAMA tighten algorithmic procurement standards further. Deepen backward integration into Arabic dataset development to defend margin pools against emerging NLP specialists. Anchor capacity in Riyadh's expanding data center corridor to secure proximity to NEOM and smart city demand clusters. For New Entrants and Emerging Players: Cloud-native delivery routes through sovereign cloud marketplaces offer the fastest path to compliant government contracting without capital-intensive infrastructure buildout. Egyptian public sector digitization remains the most penetrable geography, with Cairo and Alexandria tech corridors undersupplied relative to Gulf saturation. Target healthcare AI carve-outs under MOHAP's diagnostic licensing pathway as a regulated entry point with compressed competitive intensity. For Investors and Strategic Acquirers: Consolidation pressure builds where procurement centralization under SDAIA's unified contracting framework displaces fragmented ministry-level purchasing. Long-term viability favors vertically integrated platforms with sovereign cloud hosting, Arabic NLP capabilities, and pre-certified compliance architecture. Watch GPU allocation rationing from NVIDIA as the critical inflection signal for vendor margin compression and forced market exit.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | SDAIA prequalification unlocks access to consolidated Saudi government technology funds. |
| Arabic Dataset Acquisition | Proprietary dialect training data creates defensible moats in NLP contract competitions. |
| Regulatory Specialist Embedding | SAMA validation expertise accelerates banking sector procurement cycles by months. |
| Edge Infrastructure Partnership | 5G carrier alliances enable real-time computer vision deployment in logistics corridors. |
| Research Institution Alliance | Humain-style Saudi university partnerships sustain R&D intensity without captive capital. |
Research Methodology
Coverage spans Saudi Arabia, UAE, Egypt, Qatar, and Israel, with primary inputs from each market's distinct regulatory and procurement environment. Primary interviews incorporated AI procurement officers at Saudi federal ministries, UAE National Artificial Intelligence Office policy leads, Egyptian government digitization directors, and CTOs at Dubai-licensed fintech operators. Secondary validation drew from SDAIA procurement disclosures, SAMA Model Risk Management Guidelines, UAE federal AI strategy documents, hyperscaler capex filings, and Gulf data center development permits. Bottom-up deployment tracking triangulated against top-down sovereign budget allocation analysis.
Granularity-level modeling distinguished product type, end user sector, core technology, and deployment architecture dimensions across the projection horizon. Machine learning and natural language processing segments incorporated Arabic-language training data scarcity premiums and GPU allocation constraints. Government, healthcare, and finance end-use verticals reflected divergent compliance timeline impacts. CAGRs derived from weighted scenario analysis across infrastructure buildout, regulatory enforcement, and sovereign funding commitment trajectories.
The model assumes a particular technology adoption path; alternative pathways for edge-to-core distributed inference architectures would alter the outlook if 5G rollout timelines accelerate or stall. Forecasts reflect documented assumptions around SAMA certification cycle durations, NVIDIA supply allocation continuity, and sovereign cloud capacity expansion schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
Global Artificial Intelligence SAAS Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Global Citizen Services AI Market
Artificial Intelligence (AI)
Smart Virtual Personal Assistants Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Oil and Gas Market
Artificial Intelligence (AI)
Enterprise AI Governance and Compliance Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
Conversational AI Market