
 AI in Food & Beverages Market | 2026-2036
AI in Food & Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Food & Beverages Market Insights
Machine learning engineer scarcity is redrawing competitive boundaries across food automation. NVIDIA Corporation leverages its GPU architecture to dominate training workloads for computer vision inspection systems. ABB Ltd anchors its position through deep integration of robotics with real-time quality analytics on processing lines. Honeywell International Inc. competes by extending its industrial software stack into predictive maintenance for beverage packaging equipment.
AI in Food & Beverages encompasses algorithmic systems that ingest sensor data, visual inputs, and operational parameters to automate decision-making across production, distribution, and service environments. These systems typically process inputs at sub-second latency thresholds to enable real-time sorting, predictive spoilage detection, and dynamic supply chain rebalancing. Machine Learning applications command the deepest deployment pools, particularly in demand forecasting where historical consumption patterns train neural networks against weather and event variables. Computer Vision segments are expanding fastest, driven by hyperspectral imaging advances that detect contaminants at conveyor speeds exceeding human visual cognition limits. Quality Control deployments retain the densest margin pools, since defect interception downstream of packaging incurs exponentially higher recall costs.
FDA oversight of AI-enabled food safety diagnostics is tightening validation requirements for algorithmic hazard detection systems. The EU AI Act classifies certain food inspection automation as high-risk, mandating conformity assessments before CE marking deployment. USDA grading protocols are beginning to accommodate computer vision outputs for standardized quality assessment of produce and meat products. Stakeholders must weigh regulatory compliance investment against first-mover advantages in automated safety certification.
Market Dynamics
Machine learning inference latency requirements are compressing hardware procurement cycles as food processors demand sub-100-millisecond decision thresholds for real-time contamination detection on high-speed production lines.
Growth Catalysts
- EU AI Act high-risk classification:Automated food inspection systems now face mandatory conformity assessments, creating certified vendor pools that reward early compliance investments and lock out unqualified competitors.
- Hyperspectral imaging maturation:Conveyor-mounted sensors detecting chemical signatures invisible to RGB cameras are expanding defect catch rates in nut sorting and foreign material detection applications.
- United States demand concentration:Major protein processors and beverage manufacturers are deploying computer vision at scale, pulling GPU and edge computing infrastructure investment toward North American deployment centers.
Market Restraints
- Silicon supply concentration:NVIDIA GPU dependency for training workloads creates single-source vulnerability for vision system developers seeking to customize defect detection models.
- FDA validation friction:Algorithmic hazard detection systems face lengthening pre-market approval timelines as the agency tightens evidentiary standards for AI-enabled food safety diagnostics.
- Technical latency floors:Edge inference on battery-powered inspection drones remains constrained by thermal dissipation limits, capping deployment flexibility in remote agricultural monitoring.
Strategic Opportunities
- India FSSAI digitization:The regulator's push for automated compliance documentation in cold chain monitoring creates entry paths for predictive spoilage detection vendors.
- Robotics-analytics convergence:Integration of collaborative robot arms with real-time quality scoring enables closed-loop sorting that adapts grip parameters to product condition.
- Direct-to-processor software licensing:Bypassing traditional systems integrators, AI model providers are contracting directly with plant engineering teams for per-line deployment fees.
Industry Challenges
- Machine learning engineer scarcity:Food sector compensation benchmarks lag technology industry standards, constraining in-house model development capacity at mid-sized processors.
- Legacy MES integration complexity:Brownfield facilities running 1990s-era manufacturing execution systems require costly protocol translation layers to ingest AI-generated quality signals.
- CE marking timeline compression:EU AI Act conformity assessment backlogs are extending deployment schedules for automated inspection equipment destined for European packaging lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Food & Beverages Market |
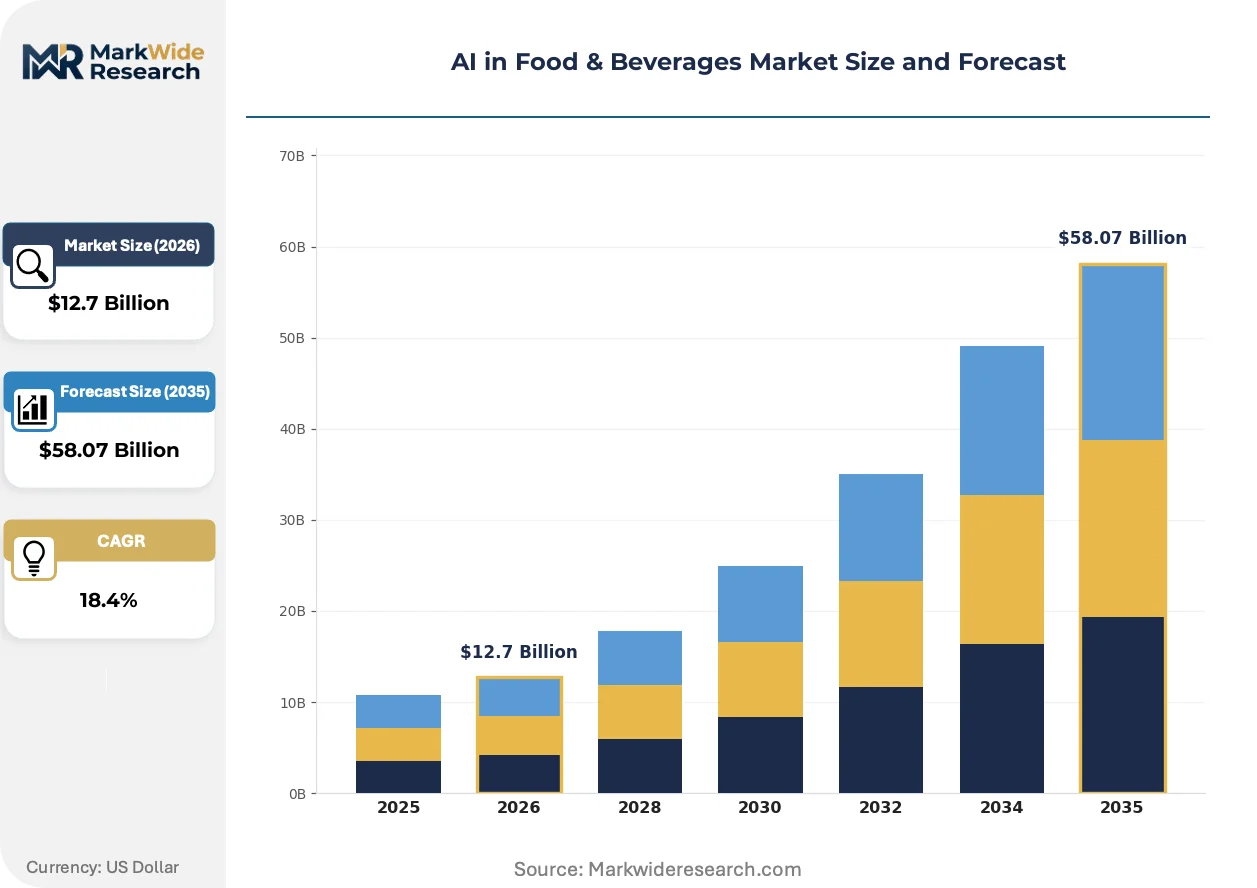
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.07 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Supply Chain Optimization, Predictive Maintenance, Quality Control, Customer Insights Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics End User: Restaurants, Food Manufacturers, Retailers, Beverage Companies Service Type: Consulting, Integration, Managed Services, Support |
| Companies Covered | TOMRA Sorting Solutions AS, Rockwell Automation Inc., ABB Ltd, Honeywell International Inc., Key Technology Inc., Sesotec GmbH, NVIDIA Corporation, Siemens AG, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Food & Beverages Market Trends and Innovations
Hyperspectral imaging hardware is commoditizing faster than anticipated, compressing the window for premium pricing on vision-based quality systems and forcing differentiation toward software-defined detection logic.
Hyperspectral sensors capturing 100-plus wavelength bands are supplanting traditional RGB-line scan cameras in high-value sorting applications. Nut processors and frozen vegetable packers are retrofitting existing conveyors with chemical-composition mapping capabilities. This hardware shift is compressing margins on legacy vision equipment while expanding addressable markets for software-centric defect classification vendors.
The EU AI Act's high-risk system designation for automated food safety inspection is mandating human-in-the-loop architectures for certain deployment categories. Equipment manufacturers must now engineer override interfaces and audit logging that satisfy notified body review. European dairy and meat inspection lines are responding by segmenting AI-assisted pre-screening from final human certification stages.
Food manufacturers are unbundling after-sales service contracts from capital equipment purchases, preferring per-inspection pricing models that align vendor compensation with detection accuracy outcomes. This procurement pattern is disrupting traditional machinery OEM revenue streams concentrated in maintenance retainers. Protein processors in the United States are piloting outcome-based arrangements where vision system providers bear cost of missed defects.
AI in Food & Beverages Market Segmentation
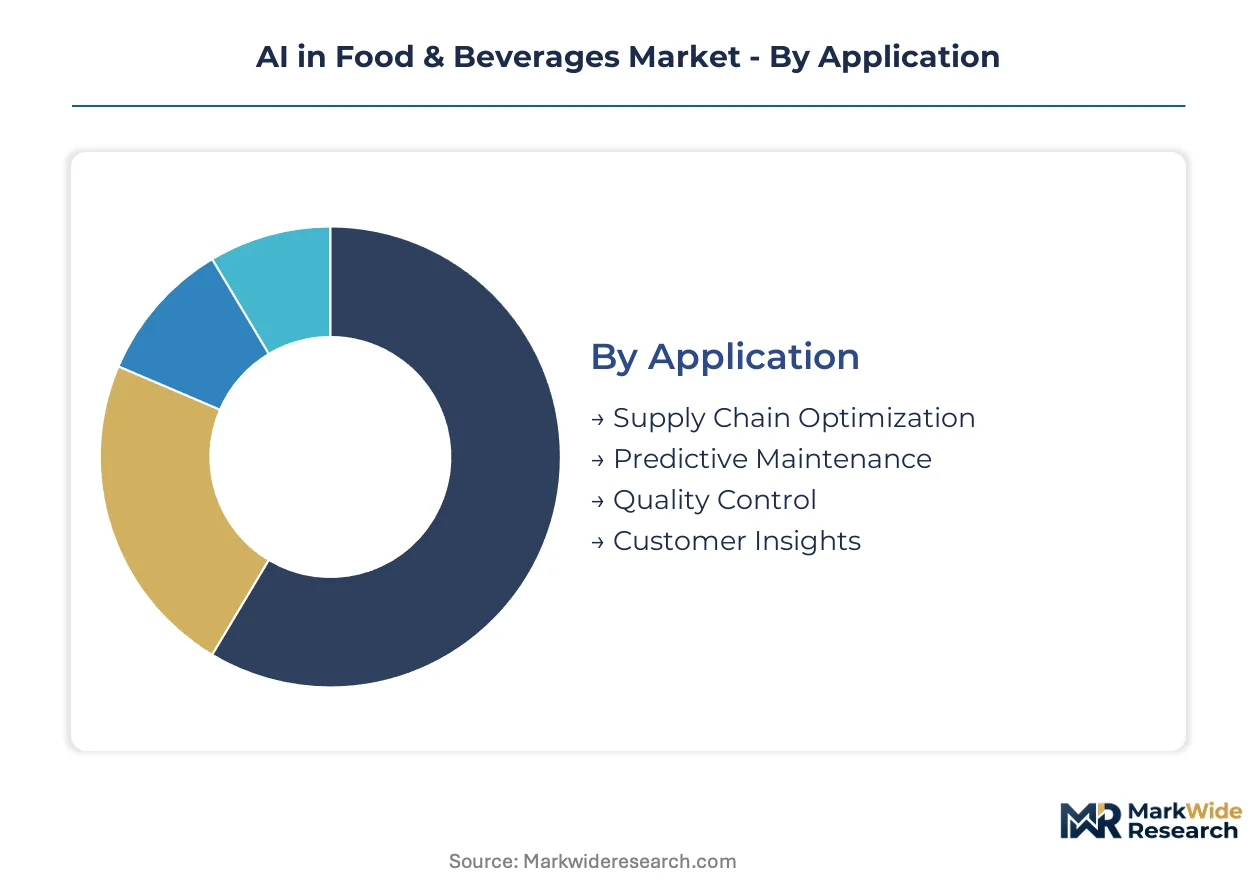
Segmentation in AI for Food & Beverages separates deployment architectures by regulatory exposure and operational criticality. Different applications face distinct validation requirements from FDA, EU AI Act, and national food safety authorities. Technology choices and service models align with these compliance burdens and the latency demands of live production environments.
Application:
EU AI Act high-risk classification and FDA pre-market approval timelines differentiate commercial viability across use cases. Quality Control and Predictive Maintenance carry the heaviest conformity burdens.
- Quality Control:Hyperspectral imaging and computer vision systems detect contaminants at conveyor speeds exceeding human cognition. Protein processors in the United States deploy these systems under USDA grading protocol accommodations, balancing detection accuracy against recall cost exposure.
- Predictive Maintenance:Sensor fusion and anomaly detection algorithms forecast equipment failure in beverage packaging lines. Honeywell extends industrial software stacks into this segment, capturing margin pools tied to unplanned downtime avoidance.
- Supply Chain Optimization:Demand forecasting neural networks trained on weather and event variables reduce waste for restaurant chains expanding AI-driven operations.
- Customer Insights:Natural language processing extracts preference patterns from digital ordering channels and feedback systems.
Established volume favors Quality Control; emerging adoption favors Predictive Maintenance.
Technology:
Cost tier separates training-intensive platforms from edge-deployable inference engines. GPU dependency for Machine Learning creates silicon supply vulnerability distinct from lighter-weight Robotics integration.
- Machine Learning:Neural network training for demand forecasting and spoilage prediction commands the deepest deployment pools. NVIDIA GPU architectures dominate these workloads, though single-source concentration constrains customization for mid-sized processors.
- Computer Vision:Hyperspectral imaging advances expand defect catch rates in nut sorting and foreign material detection. The segment climbs the fastest as hardware commoditization compresses margins on legacy RGB-line scan equipment.
- Robotics:Collaborative robot arms integrate with real-time quality scoring for closed-loop sorting. ABB anchors position through deep integration with processing line analytics.
- Natural Language Processing:Voice-enabled ordering systems and compliance documentation automation serve restaurant and cold chain monitoring applications.
Training cost intensity concentrates in Machine Learning; deployment flexibility concentrates in Computer Vision.
End User:
Customer type determines procurement sophistication and outcome-based contracting appetite. Direct-to-processor software licensing disrupts traditional systems integrator channels for plant engineering teams.
- Food Manufacturers:Brownfield facilities with 1990s-era MES systems require costly protocol translation layers. Major protein processors pilot outcome-based arrangements where vision providers bear cost of missed defects.
- Beverage Companies:High-speed packaging lines demand sub-100-millisecond inference latency for real-time contamination detection. Predictive maintenance deployments concentrate here due to continuous operation economics.
- Restaurants:Demand forecasting and automated ordering systems reduce waste for expanding chains. Procurement patterns favor per-inspection pricing over capital equipment purchases.
- Retailers:Cold chain monitoring and automated compliance documentation respond to India FSSAI digitization pushes for predictive spoilage detection.
Capital intensity favors Food Manufacturers; pricing model innovation favors Restaurants.
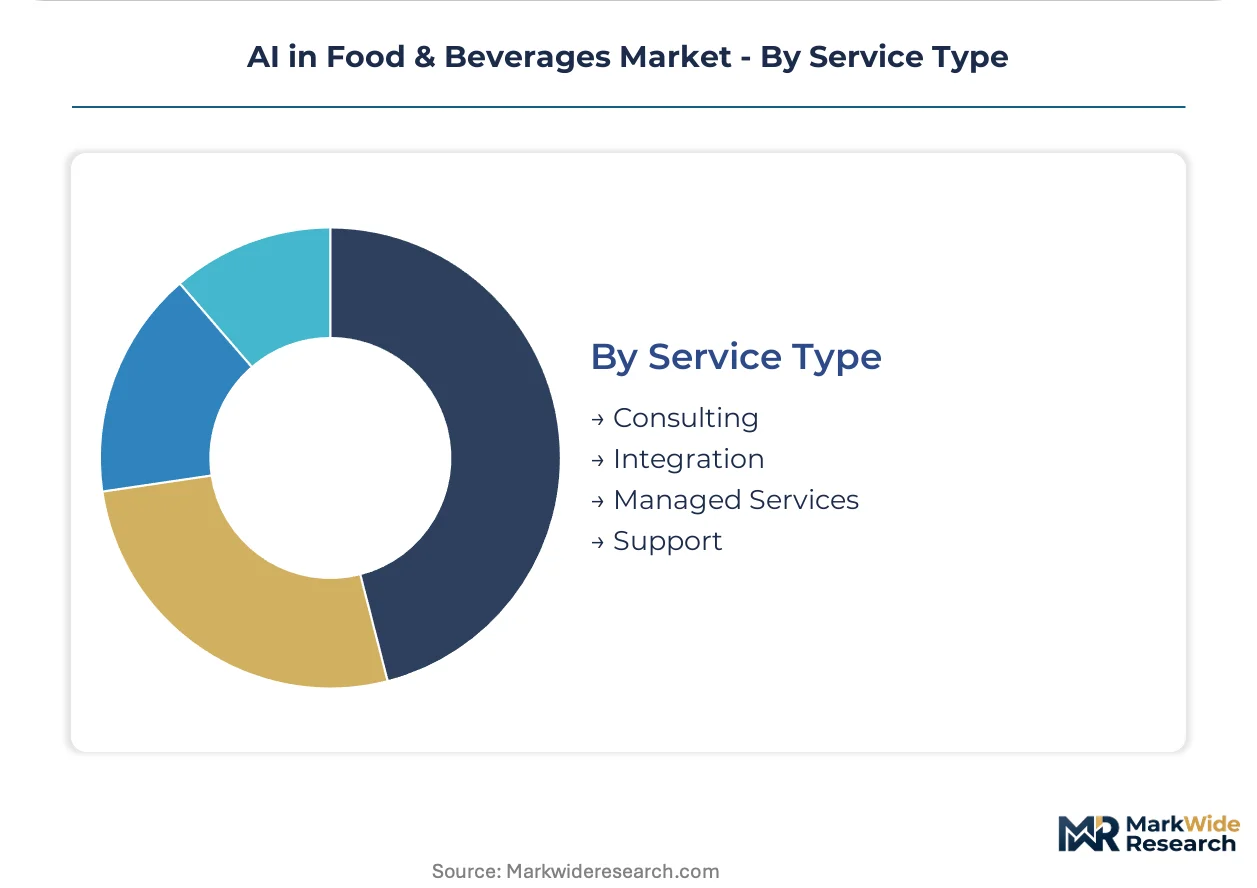
Service Type:
Maturity separates established maintenance retainers from emerging outcome-aligned structures. Unbundling of after-sales contracts disrupts traditional machinery OEM revenue concentration.
- Integration:Legacy MES protocol translation and edge computing infrastructure deployment for brownfield facilities. CE marking timeline compression under EU AI Act extends schedules for European packaging line equipment.
- Managed Services:Per-line deployment fees and detection accuracy-based compensation align vendor incentives with operational outcomes. Protein processors in the United States lead this procurement shift.
- Consulting:Compliance pathway navigation for FDA validation and EU AI Act conformity assessment preparation.
- Support:Human-in-the-loop override interfaces and audit logging for high-risk system classifications.
Revenue stability favors Integration; margin expansion favors Managed Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA validation requirements for AI-enabled food safety diagnostics anchor the United States as the dominant geography, while the EU AI Act's high-risk classification system reshapes vendor qualification pools across automated inspection equipment markets.
United States
Major protein processors and beverage manufacturers deploy computer vision at scale for quality control and contamination detection. FDA oversight tightens evidentiary standards for algorithmic hazard detection systems, extending pre-market approval timelines. Chicago and Omaha industrial corridors concentrate GPU infrastructure investment for training workloads, pulling edge computing deployment toward North American processing centers.
Germany
Automated dairy and meat inspection lines segment AI-assisted pre-screening from final human certification stages under high-risk system mandates. CE marking conformity assessment backlogs extend deployment schedules for European packaging equipment. Bavaria's machinery manufacturing clusters engineer override interfaces and audit logging for notified body review compliance.
China
Domestic food manufacturers retrofit brownfield facilities with protocol translation layers for legacy MES integration. SAMR and GB standards accommodate computer vision outputs for standardized produce grading. Yangtze River Delta processing hubs pilot hyperspectral imaging for nut sorting and foreign material detection at conveyor speeds.
India
FSSAI digitization pushes for automated compliance documentation in cold chain monitoring, creating entry paths for predictive spoilage detection vendors. Maharashtra and Gujarat food processing corridors demand sub-100-millisecond inference latency for real-time quality analytics on high-speed lines.
Japan
Premium beverage packaging equipment operators adopt predictive maintenance deployments under continuous operation economics. METI guidelines shape validation frameworks for robotics-analytics convergence in collaborative sorting applications. Osaka-Kobe industrial zones integrate real-time quality scoring with adaptive grip parameters for closed-loop processing.
AI in Food & Beverages Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with GPU-dependent training specialists commanding premium positioning while industrial automation incumbents leverage installed base relationships. The market structure tiers around silicon suppliers, robotics integrators, and software-defined detection vendors. Three strategic archetypes dominate: hyperspectral hardware commoditizers, edge inference optimizers, and outcome-based service model innovators. Competitive moves concentrate on direct-to-processor software licensing bypassing traditional systems integrators, and per-inspection pricing arrangements that transfer defect cost liability to equipment providers.
Within the industrial automation tier, ABB Ltd and Honeywell International Inc. exemplify archetypes anchored in processing line integration and predictive maintenance extension respectively. NVIDIA Corporation occupies a position representing the silicon concentration vulnerability that constrains customization capacity for mid-sized vision system developers. Rockwell Automation Inc. and Siemens AG sit within the control systems incumbent category, facing unbundling pressure as food manufacturers prefer per-line deployment fees over capital equipment purchases.
| Leading Market Players |
|---|
| TOMRA Sorting Solutions AS |
| Rockwell Automation Inc. |
| ABB Ltd |
| Honeywell International Inc. |
| Key Technology Inc. |
| Sesotec GmbH |
| NVIDIA Corporation |
| Siemens AG |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
Per-inspection pricing arrangements lock in both supply access and price visibility for food processors seeking to transfer defect cost liability to AI vision providers. This contract-structure pattern concentrates margin pressure on equipment vendors while insulating buyers from algorithmic failure risk.
Pricing Analysis
United States protein processors pay premium rates for outcome-based contracts where vision system providers bear missed defect costs, while European buyers face CE marking timeline compression that inflates total cost of ownership. Pricing stratifies across FDA-validated premium tiers, EU AI Act conformity-assessed standard tiers, and unvalidated economy tiers for non-regulated applications. Cost compression in the standard tier intensifies as hyperspectral hardware commoditization erodes equipment margins. Mid-sized food manufacturers exhibit highest price sensitivity due to constrained capital budgets, whereas major beverage companies prioritize detection accuracy over unit economics.
Supply Chain Analysis
The United States and Taiwan anchor GPU fabrication for training workloads, while China and South Korea dominate edge inference chip packaging and memory supply. NVIDIA GPU architectures draw from TSMC foundry capacity, HBM3 memory stacks, and specialized cooling subsystems. Single-source vulnerability in advanced node silicon creates structural risk for vision system developers seeking customized defect detection models. Distribution runs through direct-to-processor software licensing channels that bypass traditional systems integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
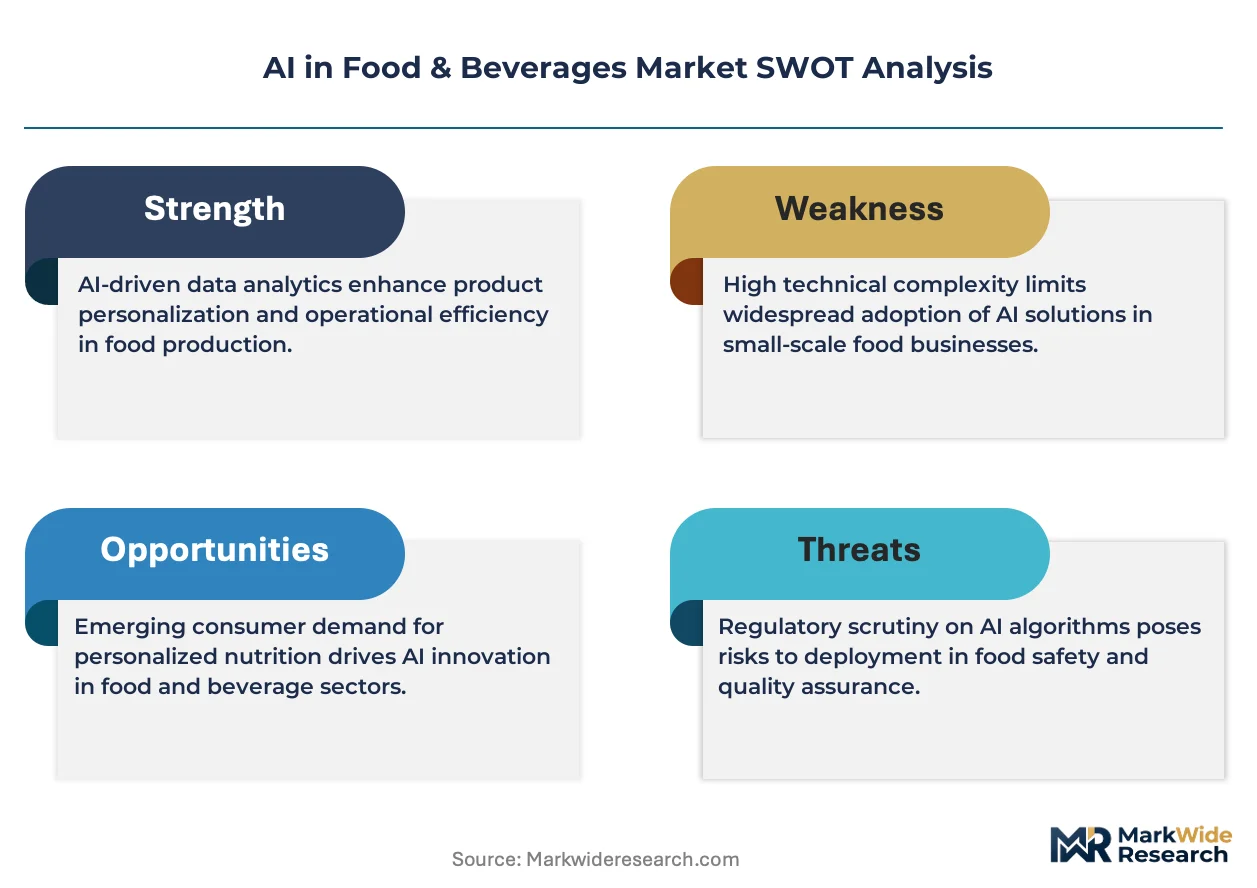
EU AI Act high-risk classification creates a regulatory inflection that separates certified vendors from locked-out competitors across automated food inspection markets.
For Market Incumbents: Compound installed base advantages by embedding predictive maintenance modules into existing MES integrations at brownfield facilities. Deepen backward integration into hyperspectral sensor calibration to defend against hardware commoditization. Prioritize FDA validation pathway investments to maintain premium positioning as evidentiary standards tighten for algorithmic hazard detection systems. For New Entrants and Emerging Players: Differentiate on per-inspection outcome pricing that aligns vendor compensation with detection accuracy metrics. Target India FSSAI digitization mandates for cold chain monitoring as the most penetrable geography. Deploy direct-to-plant-engineering sales channels that circumvent established systems integrator relationships. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined detection vendors with EU AI Act conformity assessment completion and established per-line deployment fee revenue streams. Long-term viability favors vendors capable of bridging regulatory compliance with outcome-based contracting structures. Watch hyperspectral hardware margin compression as the inflection signal for software-centric differentiation value.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment Completion | Creates certified vendor pool entry barriers that lock out unqualified competitors from European dairy and meat inspection lines. |
| Direct-to-Processor Software Licensing | Bypasses traditional systems integrator channels and captures per-line deployment fees from plant engineering teams. |
| Hyperspectral Hardware Backward Integration | Secures sensor calibration control as commodity pricing erodes margins on legacy RGB-line scan equipment. |
| FDA Validation Pathway Investment | Positions vendors for tightened pre-market approval timelines as evidentiary standards intensify for AI-enabled food safety diagnostics. |
| Outcome-Based Service Model Innovation | Transfers defect cost liability to providers and aligns compensation with detection accuracy metrics for protein processors. |
Research Methodology
Initial hypotheses were tested against primary input from food safety compliance officers, plant engineering directors, vision system procurement managers, and AI model development leads and refined through secondary validation against FDA 510(k) filings, EU AI Act notified body guidance documents, USDA grading protocol amendments, and hyperspectral imaging patent filings. Bottom-up deployment estimates triangulated against top-down market sizing from GPU infrastructure investment disclosures and edge computing procurement data.
Variance decomposition across the projection horizon isolates volume drivers from price drivers within each segmentation dimension. The analytical framework models deployment architecture, application criticality, regulatory exposure tier, and end-user procurement sophistication. CAGRs were derived from installed base expansion curves and replacement cycle acceleration patterns. Hyperspectral imaging hardware commoditization velocity and EU AI Act conformity assessment backlog duration served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside FDA validation timeline stability or NVIDIA GPU supply continuity would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement intensity and silicon foundry capacity allocation. Recalibration cycles align with material shifts in EU AI Act implementation guidance and hyperspectral sensor cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence Platform Market
Artificial Intelligence (AI)
AI Demand Forecasting Software Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market
Artificial Intelligence (AI)
AI Text Generator Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
United States Conversational AI Market
Artificial Intelligence (AI)
No-Code AI Platform Market
Artificial Intelligence (AI)
Deep Learning Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market