
 Global AI Governance Market | 2026-2036
Global AI Governance Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI Governance Market Foresight
Asset-light subscription financing is narrowing the competitive field for AI governance software. Microsoft Corporation leverages its Azure cloud infrastructure to bundle governance tools with existing enterprise contracts. IBM Corporation anchors its position through Watson OpenScale and specialized consulting services for regulated industries. SAS Institute differentiates via deep statistical lineage tracking that appeals to risk-averse financial clients.
AI governance encompasses the frameworks, technical tools, and organizational processes that ensure artificial intelligence systems operate within defined ethical boundaries, legal constraints, and performance thresholds, incorporating automated bias detection algorithms and model explainability protocols to maintain audit trails across machine learning pipelines. The primary commercial purpose centers on reducing regulatory liability while sustaining algorithmic performance in high-stakes decision environments. Compliance Monitoring solutions currently command the strongest margin pools as banks and insurers face intensifying scrutiny from national regulators. Cloud-Based deployment is accelerating fastest among mid-sized technology vendors seeking scalable oversight without capital-intensive infrastructure buildouts.
The EU AI Act, GDPR, and ISO/IEC 42001 standards collectively establish the compliance architecture that vendors must embed to access European commercial opportunities. The US Federal Trade Commission and the National Institute of Standards and Technology shape parallel requirements through enforcement actions and voluntary risk management frameworks that increasingly influence procurement specifications. Stakeholders must monitor how divergent regulatory timelines between Brussels and Washington create compliance fragmentation that favors modular, jurisdiction-agnostic platform architectures.
Market Dynamics
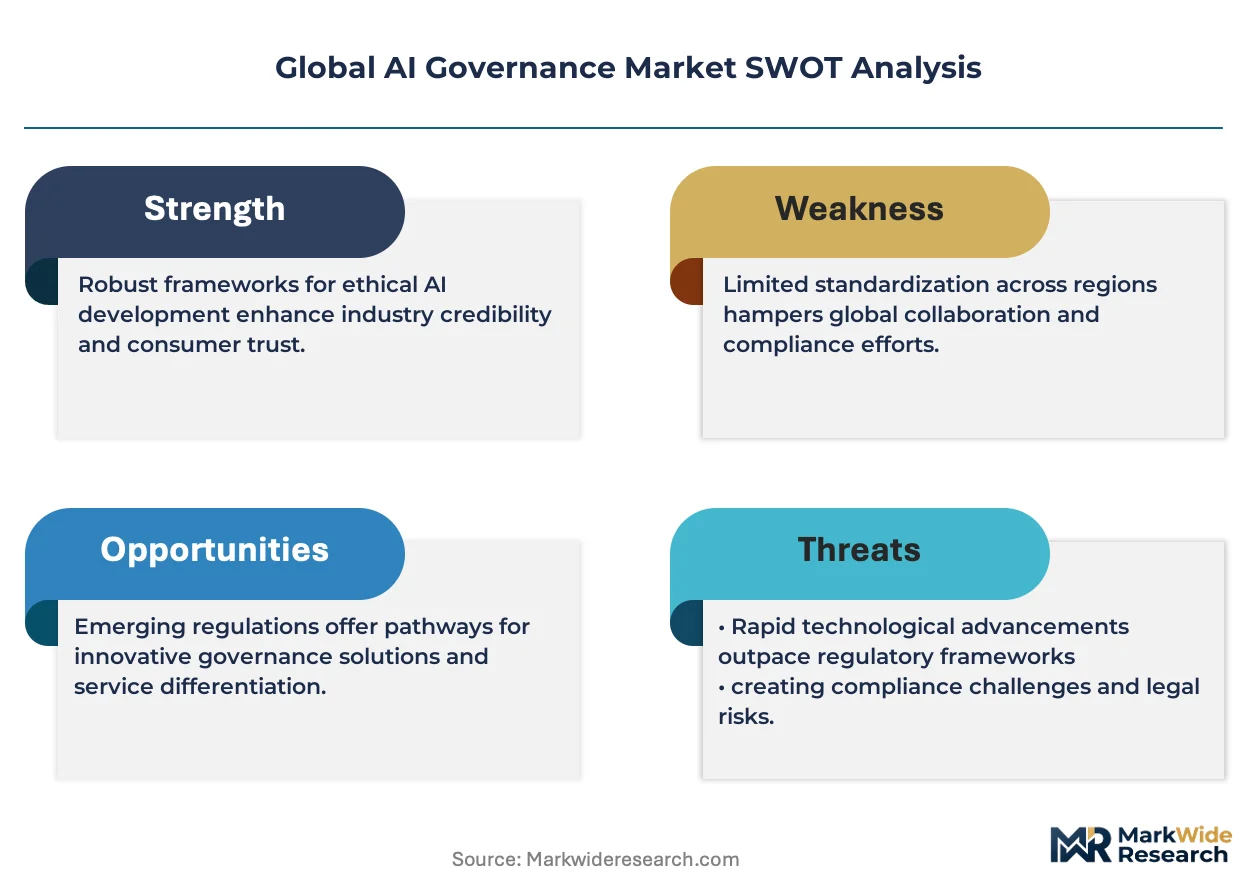
Binding conformity requirements under the EU AI Act are forcing financial institutions and industrial manufacturers into accelerated procurement cycles, compressing vendor evaluation timelines from eighteen months to under six months as liability risks mount.
Growth Catalysts
- EU AI Act Conformity Mandates:Financial institutions in Germany face binding algorithmic audit requirements that necessitate automated governance platforms for high-risk credit scoring and insurance underwriting systems.
- ISO/IEC 42001 Certification Urgency:Enterprises pursuing standardized AI management systems are driving demand for integrated compliance tooling that unifies risk documentation across machine learning operations.
- Cloud Infrastructure Maturation:Mid-sized technology vendors are abandoning on-premise deployments in favor of scalable oversight architectures that reduce capital expenditure barriers to entry.
Market Restraints
- Specialized Talent Scarcity:Shortages of professionals fluent in both machine learning engineering and regulatory interpretation are inflating implementation costs and extending deployment timelines.
- Fragmented Jurisdictional Standards:Divergent compliance timelines between Brussels and Washington are forcing vendors to maintain parallel platform architectures, raising development overhead.
- Legacy System Integration Friction:Established banks and insurers encounter technical debt when embedding governance protocols into decades-old core banking infrastructure.
Strategic Opportunities
- Underpenetrated Industrial Manufacturing:German automotive and chemical producers represent untapped demand for operational AI governance as they deploy predictive maintenance and quality control algorithms.
- Convergence of Explainability and Lineage Tracking:Platforms combining automated bias detection with statistical provenance mapping can capture risk-averse financial clients seeking unified audit trails.
- Subscription Model Expansion:Asset-light financing structures are opening mid-market access previously blocked by enterprise-grade licensing minimums.
Industry Challenges
- Cross-Functional Skill Deficits:Organizations struggle to staff teams combining data science expertise with legal compliance knowledge necessary for effective platform utilization.
- Certification Timeline Compression:Vendors must accelerate ISO/IEC 42001 and EU AI Act conformity assessments to match procurement windows shortened by regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI Governance Market |
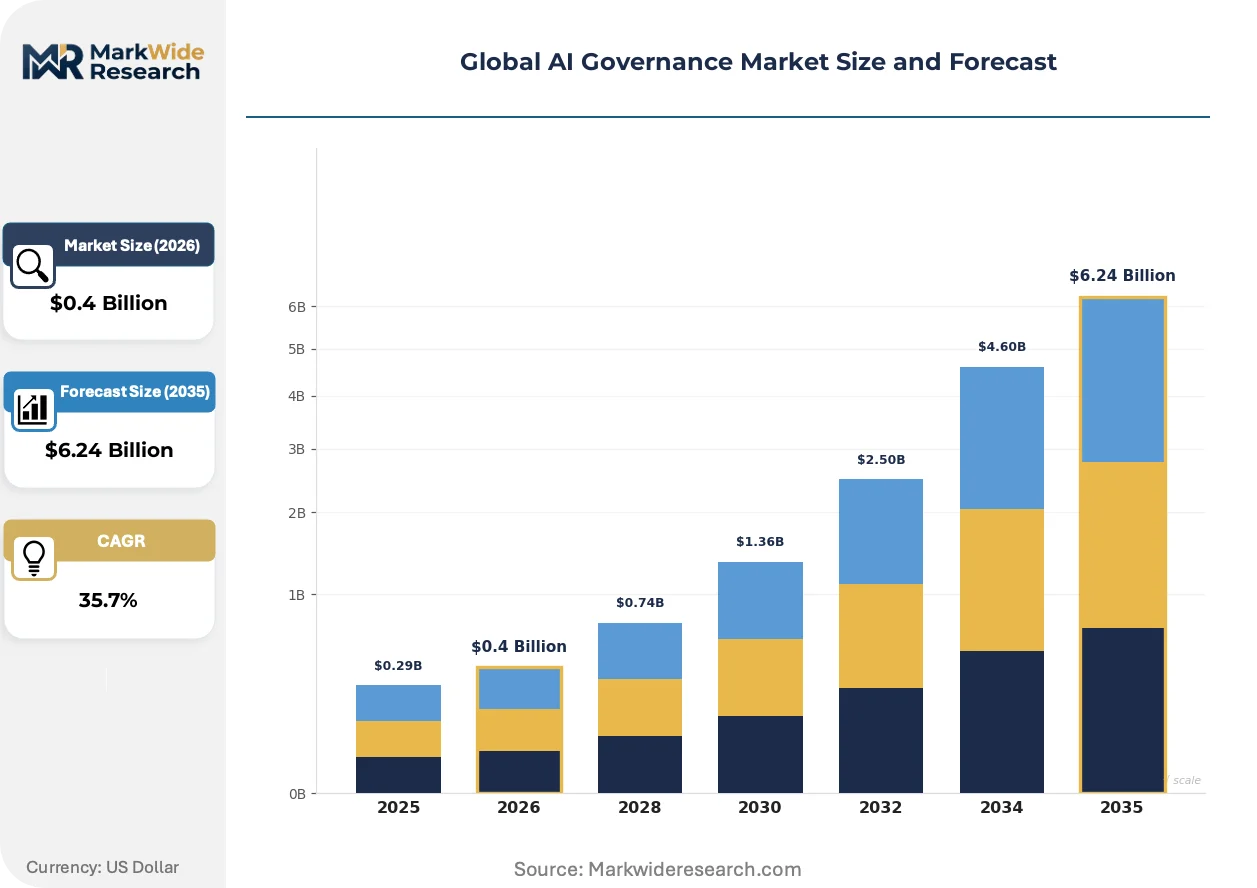
| Market Size in 2026 | $0.4 Billion |
| Market Size in 2035 | $6.24 Billion |
| CAGR (2026 – 2036) | 35.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Policy Management, Compliance Monitoring, Risk Assessment, Data Privacy, Ethics Advisory Deployment Mode: Cloud-Based, On-Premises, Hybrid, Edge Computing Application Sector: Financial Institutions, Government Agencies, Education Providers, Telecommunications, Energy Firms End User Type: Regulatory Bodies, Technology Vendors, Consulting Firms, Research Organizations |
| Companies Covered | Microsoft Corporation, IBM Corporation, Google LLC, SAP SE, Amazon Web Services, SAS Institute, FICO, Accenture, DataRobot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI Governance Market Shifts & Advancements
Automated model explainability protocols are transforming how enterprises demonstrate algorithmic accountability to regulators and internal risk committees alike.
Real-time bias detection algorithms embedded within machine learning pipelines are rendering obsolete retrospective audit approaches that identified discriminatory patterns only after deployment damage occurred. Banks and insurers in Germany are adopting these integrated monitoring systems within twelve-month implementation cycles. The shift is compressing competitive differentiation around speed of incident response rather than breadth of retrospective analysis.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-risk AI applications before market entry, creating a pre-certification bottleneck for credit scoring and recruitment algorithms. Industrial manufacturers in the automotive sector are restructuring procurement specifications to prioritize vendors with established EU notified body relationships. This regulatory architecture is favoring modular platform designs that can accommodate evolving technical documentation requirements.
Enterprise buyers are unbundling governance software from bundled cloud service contracts, creating direct procurement channels that bypass infrastructure vendor intermediation. Mid-sized financial services firms in Frankfurt and Munich are establishing dedicated AI risk committees with independent vendor evaluation authority. This behavioral shift is most pronounced in Germany, where supervisory expectations from BaFin are elevating governance tooling to board-level oversight agendas.
Global AI Governance Market Segmentation
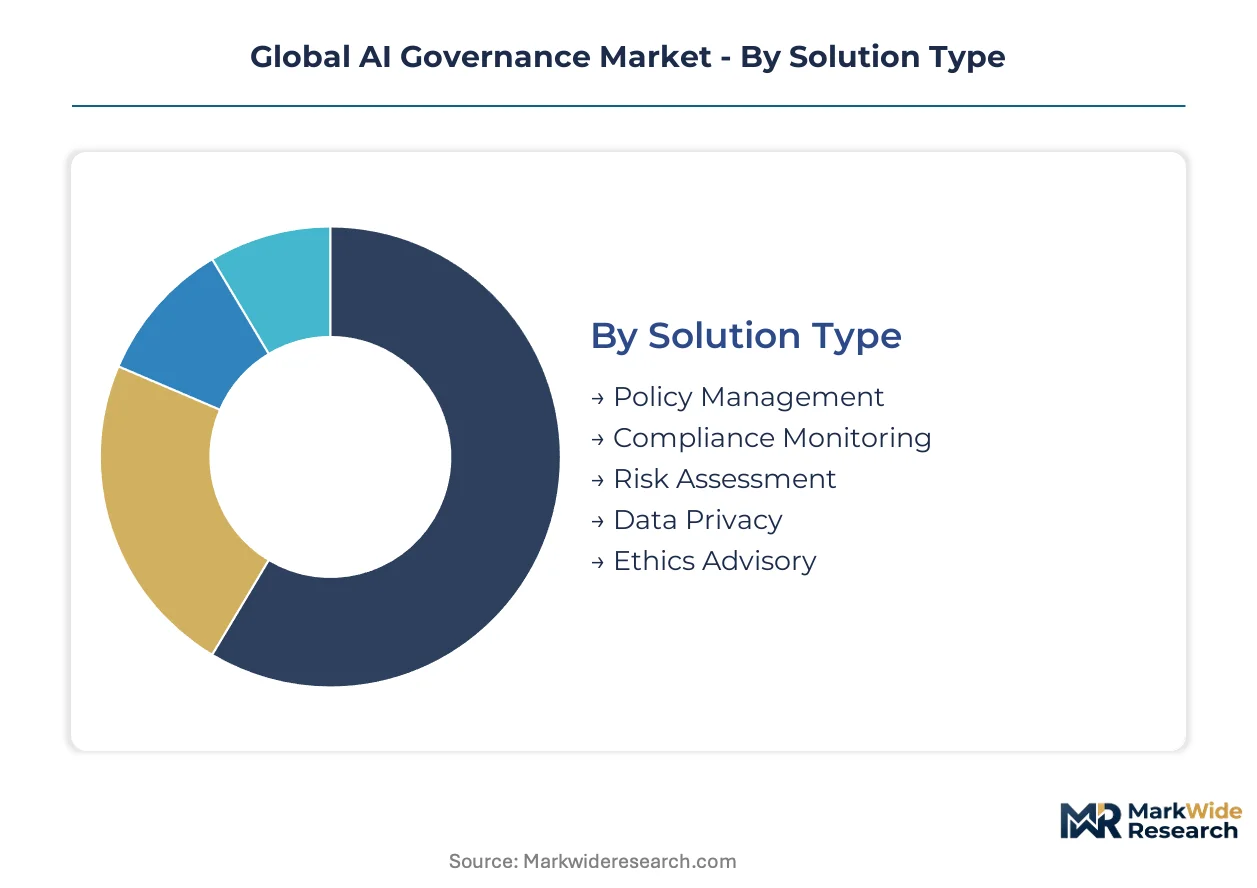
Segmentation in AI governance markets reveals how compliance architecture varies by technical deployment, regulatory intensity, and buyer sophistication. Procurement patterns diverge sharply between financial institutions facing binding audit mandates and government agencies operating under voluntary frameworks.
Solution Type:
After-sales service intensity varies dramatically across solution categories, with Compliance Monitoring platforms requiring continuous regulatory update feeds and dedicated support desks.
- Compliance Monitoring:Automated real-time surveillance of algorithmic decision pipelines against evolving regulatory benchmarks. German banks under BaFin supervision drive concentrated procurement for credit scoring audit trails. The EU AI Act's binding conformity deadlines compress implementation windows to under six months.
- Policy Management:Centralized repositories for governance documentation, version control, and cross-jurisdictional policy harmonization. Technology vendors in the United States and European Union deploy these systems to manage divergent FTC and EU AI Act requirements simultaneously. Procurement prioritizes modular architectures accommodating regulatory fragmentation.
- Risk Assessment:Quantitative scoring frameworks for algorithmic harm probability and impact severity.
- Data Privacy:Technical controls ensuring GDPR, state-level privacy laws, and sector-specific data protection mandates.
- Ethics Advisory:Human-in-the-loop consultation protocols for ambiguous algorithmic decisions.
By volume, Compliance Monitoring leads. By growth pace, Ethics Advisory is ahead.
Deployment Mode:
Cost tier stratification separates enterprise-grade on-premise installations from mid-market cloud subscriptions.
- Cloud-Based:Scalable governance oversight delivered via multi-tenant SaaS architectures with API-first integration. Mid-sized technology vendors in Frankfurt and Munich abandon capital-intensive infrastructure for operational expenditure models. The maturation of containerized security controls reduces data residency objections.
- Hybrid:Split architectures placing sensitive model training on-premise while leveraging cloud analytics for non-critical monitoring. Financial institutions in Germany deploy hybrid configurations to satisfy BaFin data localization expectations while accessing scalable compute. Procurement specifications increasingly mandate seamless workload portability.
- On-Premises:Fully captive infrastructure for classified or critical national infrastructure applications.
- Edge Computing:Distributed governance enforcement at device or sensor level for latency-constrained industrial AI.
By revenue concentration, Cloud-Based dominates. By expansion trajectory, Hybrid configurations are climbing the fastest.
Application Sector:
Customer type segmentation reveals divergent procurement authority structures across institutional buyers.
- Financial Institutions:Banks, insurers, and asset managers deploying algorithmic credit scoring, fraud detection, and underwriting systems. German financial institutions under intensifying ECB and BaFin scrutiny represent the most concentrated demand pool. The EU AI Act's high-risk classification triggers mandatory pre-deployment conformity assessments.
- Government Agencies:Public sector bodies implementing AI for benefits administration, law enforcement, and regulatory enforcement. Procurement cycles extend eighteen to thirty-six months but carry substantial contract values. Budget authorization processes prioritize vendors with established public sector certification.
- Education Providers:Universities and vocational institutions governing research AI and administrative algorithms.
- Telecommunications:Network operators managing customer churn prediction and automated service routing.
- Energy Firms:Utilities deploying predictive maintenance and grid optimization algorithms.
By contract value, Financial Institutions lead. By procurement velocity, Telecommunications is gaining share fastest.
End User Type:
Supply concentration among platform developers shapes how governance tools reach ultimate implementers.
- Technology Vendors:Enterprise software and cloud infrastructure providers embedding governance capabilities into broader platform offerings. Microsoft and IBM bundle governance modules with existing enterprise contracts, narrowing competitive access for standalone specialists. Procurement committees increasingly demand unbundled evaluation authority.
- Consulting Firms:Advisory practices configuring and deploying governance platforms for client-specific compliance environments. German automotive and chemical producers engage these intermediaries for ISO/IEC 42001 certification preparation. Fee structures are shifting from time-and-materials to outcome-based implementation guarantees.
- Regulatory Bodies:Government supervisors procuring oversight tools for market surveillance and enforcement.
- Research Organizations:Academic and non-profit institutions developing experimental governance methodologies.
By platform deployment scale, Technology Vendors lead. By engagement growth, Consulting Firms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net governance platform exports flow from the United States and Germany toward Asia-Pacific financial centers, while regulatory complexity drives localized procurement in Frankfurt and New York. Import dependency concentrates in emerging digital economies seeking EU-conformant tooling. Cross-border data residency requirements fragment cloud deployment architectures.
United States
The FTC's algorithmic enforcement actions and NIST risk management frameworks compel financial services procurement in New York and San Francisco. Federal procurement specifications increasingly embed governance requirements into enterprise software contracts. Washington's policy uncertainty around AI legislation creates interim demand for jurisdiction-agnostic platforms.
Germany
BaFin supervisory expectations and EU AI Act conformity deadlines compress procurement cycles for Frankfurt banks and Munich insurers. Industrial manufacturers in Stuttgart and Wolfsburg deploy operational governance for predictive maintenance algorithms. The country's notified body infrastructure accelerates certification timelines relative to neighboring jurisdictions.
United Kingdom
The Information Commissioner's Office guidance on automated decision-making shapes procurement specifications for London financial institutions. Post-Brexit regulatory divergence from Brussels creates demand for dual-compliant platform architectures. Edinburgh and Manchester technology clusters show concentrated mid-market adoption of cloud-based governance subscriptions.
Japan
METI's AI governance guidelines and financial sector self-regulatory codes drive adoption among Tokyo-based insurers and asset managers. Manufacturing conglomerates in Osaka and Nagoya embed governance protocols into quality control AI systems. Language-localized explainability interfaces represent a distinct procurement requirement.
Singapore
The Monetary Authority of Singapore's Veritas framework and Project Guardian initiatives position the city-state as a governance platform export hub for Southeast Asian financial institutions. Regional headquarters procurement in Marina Bay concentrates demand for multi-jurisdiction compliance tooling. Data sovereignty requirements favor hybrid deployment architectures.
Global AI Governance Market Competitive Landscape
On the supply side, the industry is consolidating around cloud infrastructure bundling and specialized compliance consulting. Three strategic archetypes dominate: hyperscale platform bundlers, statistical lineage specialists, and advisory-led systems integrators. Competitive moves concentrate on unbundling resistance through dedicated risk committee relationships and accelerated ISO/IEC 42001 certification pathways.
Within the hyperscale tier, Microsoft Corporation exemplifies infrastructure-anchored governance bundling, while IBM Corporation occupies a position spanning software tooling and implementation services. SAS Institute represents the statistical lineage specialist archetype with deep risk-averse financial client penetration.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Google LLC |
| SAP SE |
| Amazon Web Services |
| SAS Institute |
| FICO |
| Accenture |
| DataRobot |
| Others |
Supply & Pricing Matrix
Frankfurt's concentration of BaFin-supervised financial institutions generates asymmetric pricing power for governance platform vendors serving high-risk algorithmic audit requirements. Cloud infrastructure maturation in this cluster compresses capital expenditure barriers, feeding subscription model expansion across mid-sized technology vendors seeking scalable oversight without proprietary data center builds.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle ISO/IEC 42001 certification support with dedicated regulatory update feeds, while standard offerings target automated compliance monitoring without advisory services. Price differentiation rests on certification level and after-sales service intensity. Cost compression in economy tiers is intensifying because mid-sized vendors abandon on-premise minimums for asset-light SaaS delivery. Government agencies show least price sensitivity due to eighteen-to-thirty-six month procurement cycles and substantial contract values.
Supply Chain Analysis
Upstream cloud compute capacity draws from United States, Germany, and Singapore data center clusters. Software development talent concentrates in India and Eastern Europe for cost-engineered components. Supply chain risk centers on single-source vulnerability for specialized machine learning explainability libraries. Distribution runs through direct enterprise sales teams and consulting firm intermediaries, with German automotive producers increasingly engaging advisory-led procurement channels for ISO/IEC 42001 preparation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between Brussels and Washington creates structural white space for modular, jurisdiction-agnostic platform architectures. Unbundling of governance software from hyperscale cloud contracts generates direct procurement channels that favor specialized vendors with accelerated certification pathways.
For Market Incumbents: Insulate recurring revenue streams through backward integration into regulatory consulting services and captive ISO/IEC 42001 certification preparation. Deepen vertical integration of automated bias detection algorithms with statistical lineage tracking to defend against emerging statistical specialists. Prioritize notified body relationships in Germany to compress conformity assessment timelines below competitor benchmarks. For New Entrants and Emerging Players: Pursue underpenetrated industrial manufacturing segments in Stuttgart and Wolfsburg, where predictive maintenance AI deployment lacks operational governance tooling. Target mid-sized financial services firms in Frankfurt establishing independent AI risk committees with unbundled vendor evaluation authority. Lead with subscription financing structures that bypass enterprise-grade licensing minimums previously blocking market access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors advisory-led systems integrators with outcome-based implementation guarantees rather than pure software plays. Long-term viability rests on convergence of explainability and lineage tracking capabilities within unified audit trail platforms. The signal to monitor is acceleration of EU AI Act enforcement actions creating pre-certification bottlenecks that favor vendors with established regulatory relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure bundling governance tools with existing enterprise contracts narrows competitive field for standalone specialists. |
| Acquisition of Specialist Firm | IBM Watson OpenScale expansion through targeted statistical lineage capabilities captures risk-averse financial client segments. |
| Strategic Partnership | SAS Institute alliances with German notified bodies accelerate EU AI Act conformity timelines relative to regional competitors. |
| Geographic Expansion | Singapore Veritas framework positioning creates export hub opportunity for Southeast Asian multi-jurisdiction compliance tooling. |
| Product Launch | Real-time bias detection algorithms embedded within ML pipelines displace retrospective audit approaches in German banking procurement. |
Research Methodology
The analysis maps compliance monitoring, policy management, risk assessment, data privacy, and ethics advisory solution categories, each validated through primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists. Secondary sources include SEC filings, hyperscaler capex disclosures, EU AI Act implementation guidance, and ISO/IEC 42001 certification databases. Bottom-up segment sizing triangulates against top-down regulatory deadline impact modeling across the analysis window.
Fixed assumptions include EU AI Act binding conformity timelines and ISO/IEC 42001 certification urgency; varied parameters span cloud infrastructure maturation rates and cross-jurisdictional regulatory divergence. Segmentation dimensions modeled cover deployment mode, organization size, vertical application, integration complexity, and regional adoption pattern. CAGRs derive from algorithmic audit procurement velocity and mid-market subscription financing penetration. Industry-specific inputs incorporate BaFin supervisory expectation intensity and notified body certification capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in central bank interest rate trajectories or enterprise software budget freezes would shift the trajectory. Forecasts reflect documented assumptions around regulatory enforcement consistency and cloud infrastructure cost curves. Cross-checking against EU AI Act implementation timelines and hyperscaler earnings disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Europe Generative AI Market
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
AI in Life Sciences Market
Artificial Intelligence (AI)
Reinforcement Learning Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
Permission-Aware AI Repository Gateway Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market