
 Global Artificial Intelligence (AI) in Drug Discovery Market | 2026-2036
Global Artificial Intelligence (AI) in Drug Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence (AI) in Drug Discovery Market Foresight
GPU cluster expansion across North American cloud regions is realigning how discovery platforms access computational capacity. NVIDIA Corporation leverages its specialized silicon architecture to anchor training workloads for molecular simulation pipelines. Insilico Medicine sustains autonomous drug design operations spanning generative chemistry and clinical prediction. Schrödinger dominates physics-based modeling software licensing across large pharmaceutical accounts.
Artificial Intelligence in Drug Discovery denotes computational systems that learn patterns from biological, chemical, and clinical datasets to predict molecular behavior, optimize compound selection, and simulate therapeutic outcomes, typically operating across neural architectures with parameter counts exceeding one billion and training corpora spanning millions of annotated bioassay results. Its primary commercial purpose is to reduce attrition rates in pharmaceutical pipelines by prioritizing candidates with higher probability of safety and efficacy before laboratory synthesis. Machine learning and natural language processing together constitute the dominant component layer, with NLP specifically capturing regulatory document mining and biomedical literature extraction that accelerates target hypothesis generation. Lead optimization and clinical trial simulation represent the fastest-expanding application segments, as sponsors seek algorithmic replacement for traditional dose-ranging studies and adaptive protocol designs.
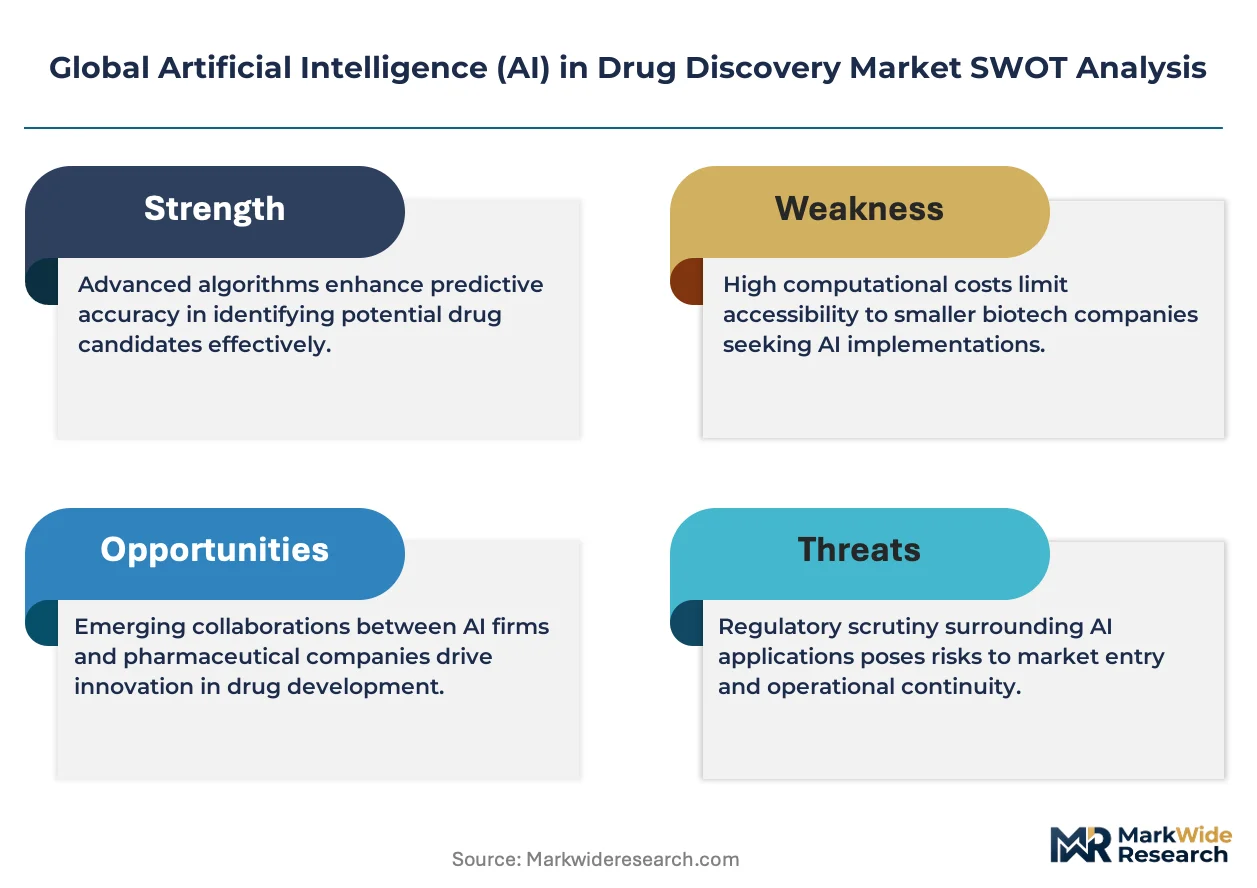
The FDA, EMA, and WHO have each issued framework documents addressing validation standards for AI-generated evidence in regulatory submissions, with the FDA's emerging guidance on model-informed drug development directly conditioning how sponsors structure algorithmic training datasets for agency review. The EU AI Act introduces risk-classification requirements for clinical decision-support systems that will reshape market access conditions for European-deployed platforms. Stakeholders must monitor divergence between FDA algorithmic transparency expectations and EU conformity assessment pathways to avoid fragmented development costs.
Market Dynamics
GPU cluster expansion across North American cloud regions is compressing preclinical timelines by enabling parallel molecular simulation workloads that previously required months of sequential computation. This infrastructure shift is forcing pharmaceutical sponsors to restructure their computational biology vendor relationships around elastic capacity rather than fixed licensing.
Growth Catalysts
- FDA Model-Informed Drug Development Guidance:The framework validates algorithmic training datasets for regulatory review, reducing submission risk for sponsors deploying predictive biomarker platforms.
- Generative Chemistry Pipelines:Autonomous compound design systems compress lead optimization from years to months by iterating molecular structures against polypharmacology constraints.
- Boston-Cambridge Computational Biology Cluster:Federal research funding concentration and venture capital deployment density exceed other national markets, anchoring talent migration and platform development.
Market Restraints
- NVIDIA Silicon Dependency:Specialized GPU architecture concentration creates supply bottleneck risk for training workloads, with foundry capacity constraints extending procurement lead times.
- EU AI Act Risk Classification:Clinical decision-support systems face conformity assessment pathways that fragment development costs across Atlantic deployment strategies.
- Annotated Bioassay Data Scarcity:High-quality training corpora remain concentrated within proprietary pharmaceutical archives, limiting algorithmic generalization for emerging target classes.
Strategic Opportunities
- Japan's PMDA Digital Transformation:Regulatory sandbox programs for AI-enabled drug development tools create first-mover positioning for platforms demonstrating Sakigake designation eligibility.
- Adaptive Protocol Design Convergence:Real-world evidence integration with synthetic control arm generation is converging with decentralized trial infrastructure to compress Phase II recruitment.
- India's CDSCO Computational Pathway:Emerging regulatory clarity on algorithmic evidence standards creates white space for cost-effective discovery outsourcing from Western sponsors.
Industry Challenges
- Cross-Functional Talent Integration:Computational chemists, machine learning engineers, and regulatory strategists operate with misaligned incentive structures and publication constraints.
- Algorithmic Validation Standardization:Absence of harmonized benchmarking protocols across FDA, EMA, and WHO frameworks forces redundant qualification studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence (AI) in Drug Discovery Market |
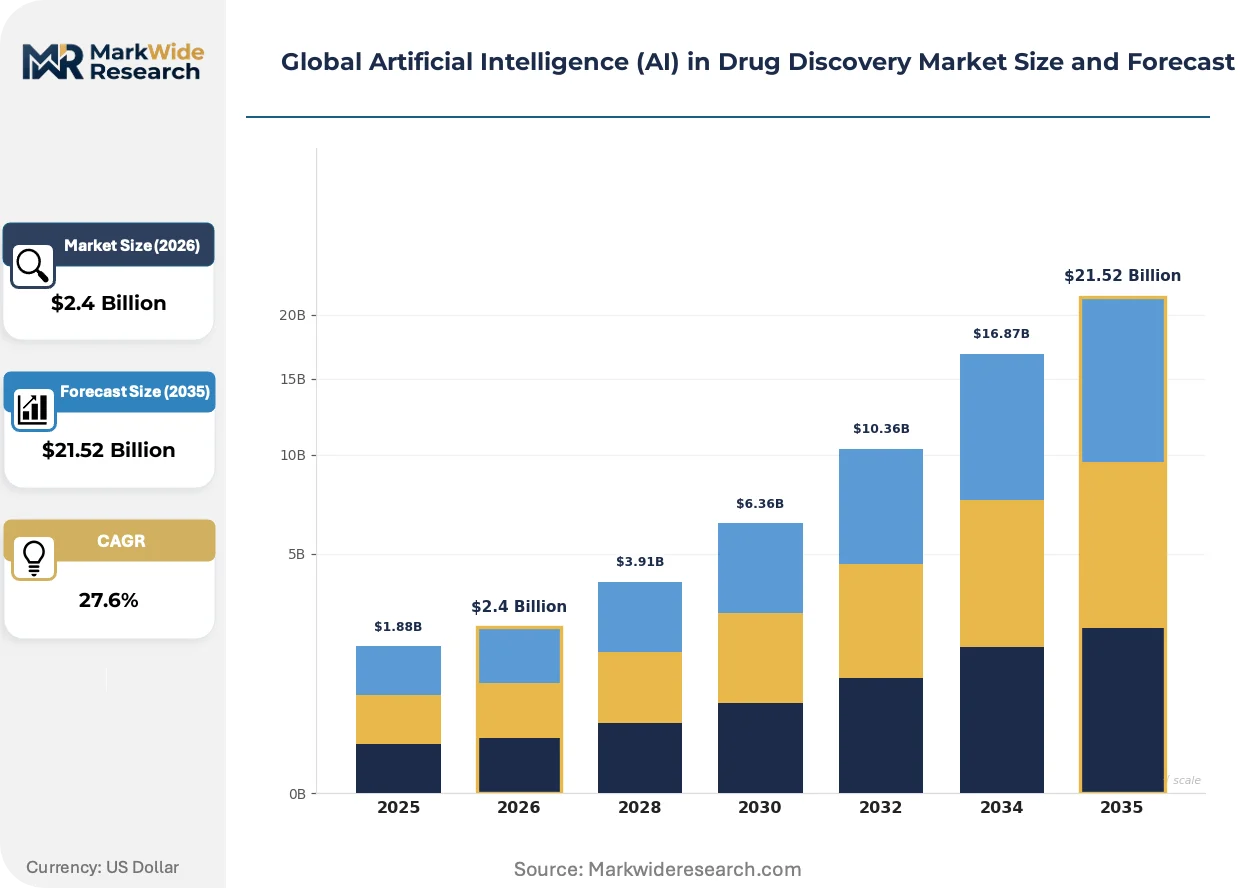
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $21.52 Billion |
| CAGR (2026 – 2036) | 27.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Machine Learning, Natural Language Processing, Computer Vision, Robotics, Expert Systems Application: Target Identification, Lead Optimization, Clinical Trial Simulation, Biomarker Discovery, Toxicity Prediction End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Contract Research Organizations, Academic Labs Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing |
| Companies Covered | Isomorphic Labs (Alphabet Inc.), NVIDIA Corporation, Recursion Pharmaceuticals, Schrödinger, Insilico Medicine, Exscientia, BenevolentAI, IBM, Atomwise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence (AI) in Drug Discovery Market Shifts & Advancements
Foundation models trained on molecular representations are displacing task-specific architectures across target identification and lead optimization workflows. This architectural shift is compressing model development cycles and enabling transfer learning across therapeutic areas.
Transformer-based protein structure prediction is converging with generative diffusion models for de novo ligand design. Large pharmaceutical sponsors are deploying these integrated pipelines for G-protein coupled receptor targets previously considered intractable. The structural consequence is collapsing the iteration cycle between structural biology insight and chemical matter synthesis.
The EU AI Act introduces mandatory conformity assessment for clinical decision-support systems exceeding defined risk thresholds. European-deployed platforms must demonstrate algorithmic transparency and bias mitigation to maintain market access. Sponsors with EU development strategies are restructuring quality management systems around ISO/IEC 42001 alignment.
Biopharma procurement teams are unbundling computational platform licensing from professional services engagements. Sponsors now demand API-accessible model inference with consumption-based pricing rather than perpetual software licenses. This shift is most visible among mid-cap biotechnology companies in the United States seeking to preserve capital efficiency while accessing frontier capabilities.
Global Artificial Intelligence (AI) in Drug Discovery Market Segmentation
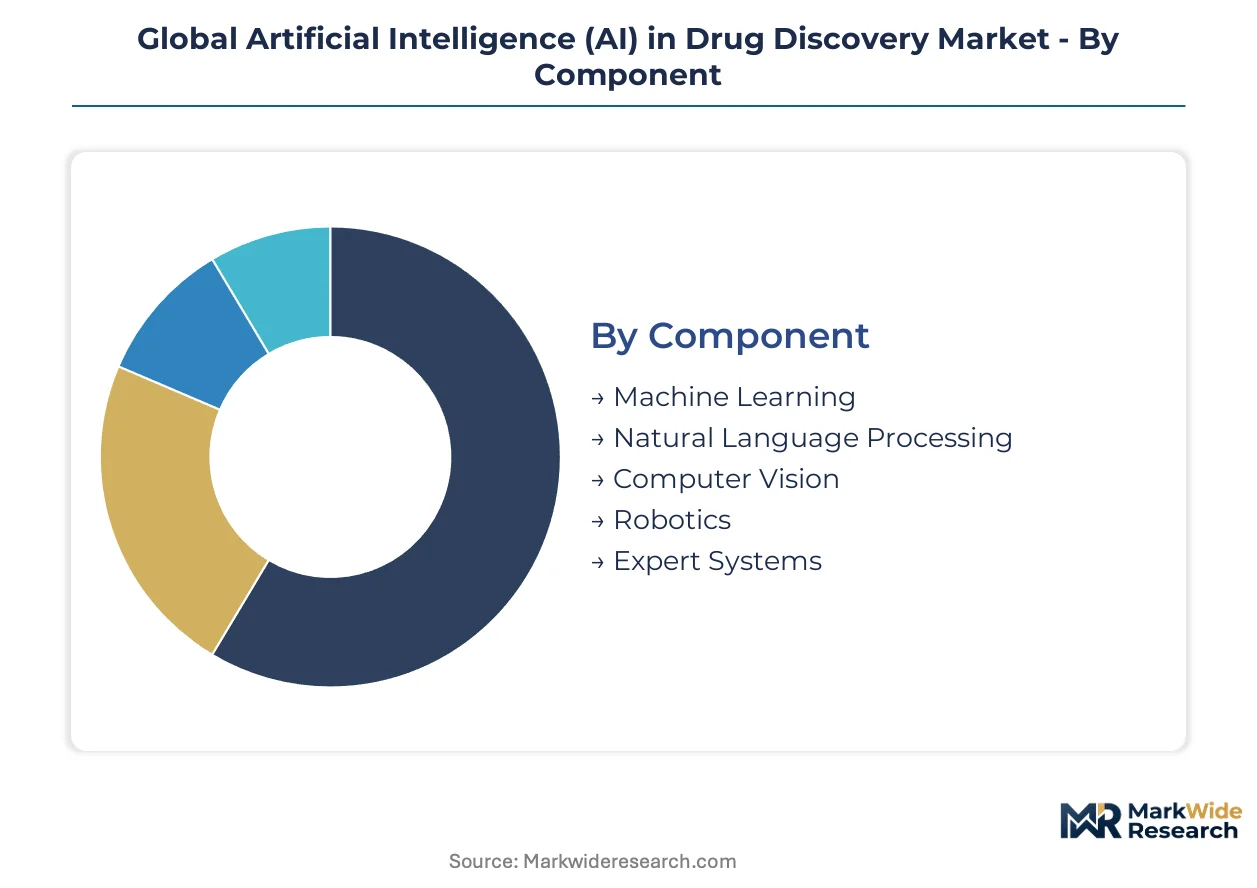
Segmentation in AI-driven drug discovery reveals how computational architectures align with distinct value creation stages. Component selection determines model training capacity, while application focus shapes regulatory pathway design and partnership structures.
Component:
Neural architecture specialization defines competitive differentiation across discovery pipelines, with parameter scale and training corpus composition determining functional boundaries.
- Machine Learning:Supervised and unsupervised algorithms process molecular fingerprints, binding affinity data, and ADMET properties to predict compound behavior. Demand concentrates among large pharmaceutical sponsors in the United States seeking to compress lead optimization cycles against FDA validation requirements. Constraint: annotated bioassay data scarcity limits generalization for novel target classes.
- Natural Language Processing:Transformer architectures extract target hypotheses from biomedical literature, patent filings, and regulatory documents. Research institutes in Boston-Cambridge deploy NLP pipelines to accelerate mechanistic understanding ahead of laboratory validation. Driver: FDA model-informed drug development guidance rewards literature-mined biomarker rationales.
- Computer Vision:Convolutional networks classify cellular imaging and histopathology outputs from high-content screening assays.
- Robotics:Automated laboratory execution systems integrate with predictive models to close the design-make-test-analyze loop.
- Expert Systems:Rule-based inference engines encode medicinal chemistry heuristics for interpretable decision support in regulatory submissions.
Machine Learning leads on scale; Natural Language Processing leads on momentum.
Application:
Functional deployment stage determines computational intensity requirements and regulatory exposure, with downstream applications demanding higher validation rigor.
- Target Identification:Foundation models trained on multi-omics data predict disease-relevant protein targets and druggable binding sites. Biotechnology firms in the United States prioritize this segment to secure intellectual property positioning ahead of competitor programs. Driver: generative chemistry pipelines require validated targets to constrain molecular design spaces.
- Lead Optimization:Generative models iterate molecular structures against polypharmacology, synthesizability, and patentability constraints. Pharmaceutical companies deploy GPU clusters across North American cloud regions to enable parallel exploration of chemical space previously inaccessible to traditional methods. Constraint: NVIDIA silicon dependency creates procurement bottlenecks for training infrastructure.
- Clinical Trial Simulation:Mechanistic models and virtual patient cohorts predict dosing regimens and safety profiles.
- Biomarker Discovery:Multi-modal learning integrates genomic, proteomic, and imaging data to stratify patient populations.
- Toxicity Prediction:Deep learning classifiers flag hepatotoxicity, cardiotoxicity, and genotoxicity liabilities from structural features.
Lead Optimization captures the steepest expansion trajectory as sponsors replace traditional dose-ranging studies with algorithmic protocols.
End User:
Organizational scale and capital structure determine platform access models, with procurement patterns diverging between integrated sponsors and outsourced service providers.
- Pharmaceutical Companies:Integrated discovery organizations deploy end-to-end AI pipelines across target identification through clinical candidate nomination. Sponsors in the United States restructure vendor relationships around API-accessible inference with consumption-based pricing rather than perpetual licenses. Driver: capital efficiency mandates favor elastic computational capacity over fixed infrastructure.
- Biotechnology Firms:Mid-cap developers unbundle platform licensing from professional services to preserve runway while accessing frontier capabilities. Venture-backed sponsors in Boston-Cambridge concentrate demand for generative chemistry and clinical prediction modules. Constraint: cross-functional talent integration challenges slow deployment timelines.
- Research Institutes:Academic and government laboratories focus on foundational model development and open dataset curation.
- Contract Research Organizations:Service providers build computational biology offerings to capture outsourced discovery demand from capital-constrained sponsors.
- Academic Labs:University-based groups train domain-specific architectures with limited commercial validation requirements.
Pharmaceutical Companies anchor volume demand; Biotechnology Firms are gaining share fastest as platform accessibility improves.
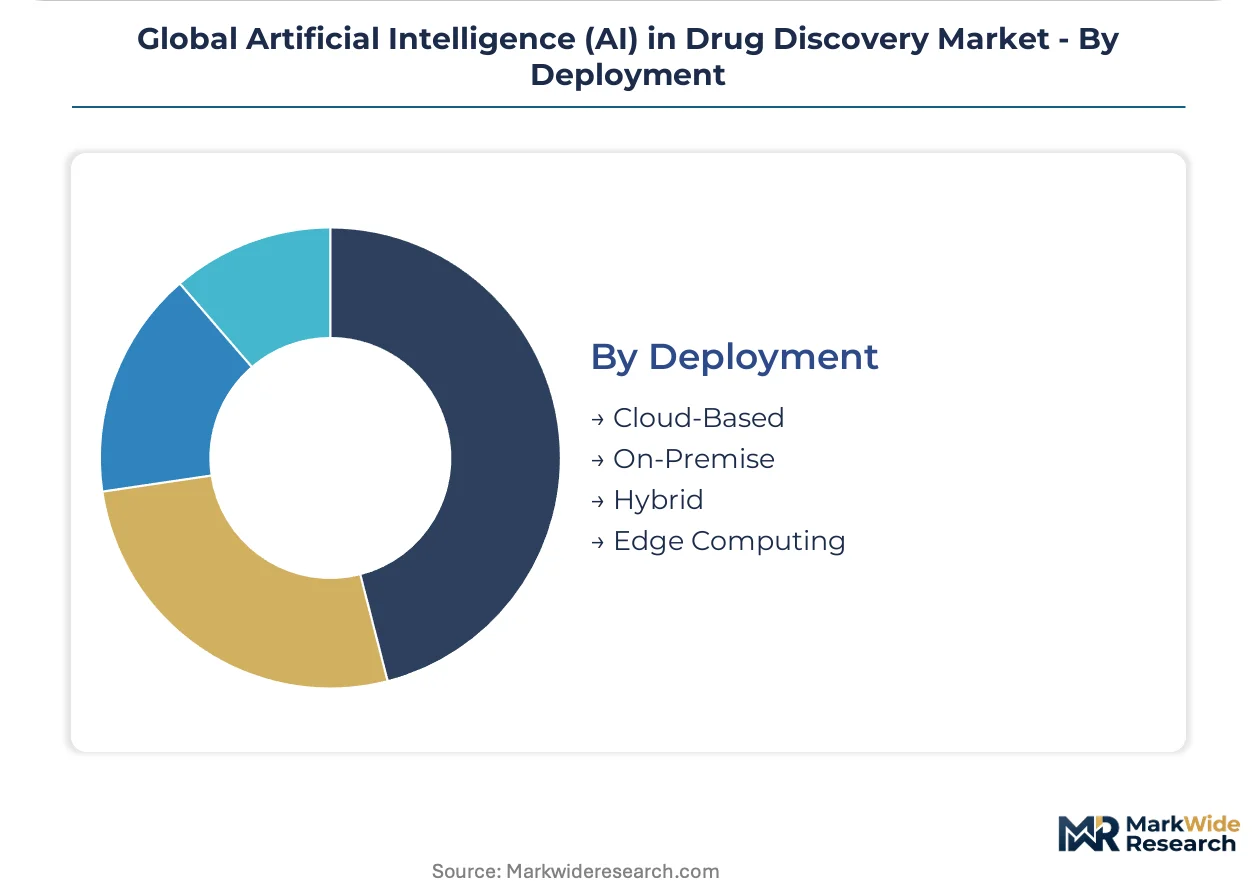
Deployment:
Infrastructure configuration determines data sovereignty, latency constraints, and regulatory compliance scope across jurisdictional boundaries.
- Cloud-Based:Elastic GPU cluster access enables variable workload scaling without capital commitment. European-deployed platforms face EU AI Act conformity assessment requirements for clinical decision-support systems exceeding defined risk thresholds. Driver: ISO/IEC 42001 alignment becomes mandatory for market access.
- On-Premise:Captive infrastructure preserves proprietary dataset control and satisfies pharmaceutical sponsor security requirements.
- Hybrid:Partitioned architectures route sensitive training data to on-premise systems while offloading inference to cloud regions.
- Edge Computing:Distributed processing at laboratory instrumentation reduces latency for real-time experimental feedback loops.
Cloud-Based deployment dominates current procurement; Hybrid architectures are climbing the fastest as data sovereignty requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between FDA validation pathways and EU AI Act conformity assessments is redirecting platform development investment toward jurisdictions with lower compliance friction. Sponsors now route training infrastructure and clinical validation studies to markets where algorithmic evidence standards remain unsettled.
United States
Federal research funding concentration and venture capital deployment density in computational biology exceed all other national markets. FDA model-informed drug development guidance validates algorithmic training datasets for regulatory review, reducing submission risk for predictive biomarker platforms. The Boston-Cambridge cluster anchors talent migration and platform development, with pharmaceutical sponsors restructuring vendor relationships around API-accessible inference.
United Kingdom
BenevolentAI and Exscientia anchor generative chemistry operations serving European and North American sponsors simultaneously. MHRA divergence from EMA algorithmic evidence standards creates regulatory sandbox opportunities for AI-enabled drug development tools. London-Oxford-Cambridge corridor concentrates natural language processing pipelines extracting target hypotheses from biomedical literature.
Germany
Physics-based modeling software licensing concentrates across large pharmaceutical accounts headquartered in Frankfurt and Munich regions. EMA framework documents on AI-generated evidence reshape validation requirements for sponsors seeking centralized marketing authorization. Heidelberg and Munich clusters integrate mechanistic modeling with automated laboratory execution systems.
China
NMPA regulatory clarity on algorithmic evidence standards remains in draft consultation, creating white space for domestic platform development ahead of Western market entry. Shenzhen and Shanghai clusters expand GPU cluster capacity for molecular simulation workloads previously routed to North American cloud regions. Insilico Medicine maintains autonomous drug design operations spanning generative chemistry and clinical prediction from Shanghai facilities.
Japan
PMDA digital transformation programs and Sakigake designation eligibility create first-mover positioning for platforms demonstrating accelerated review pathways. METI funding for computational biology infrastructure concentrates demand in Tokyo-Osaka corridor. Domestic pharmaceutical sponsors deploy foundation models trained on molecular representations for target identification ahead of global expansion.
Global Artificial Intelligence (AI) in Drug Discovery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized therapeutic area dominance through foundation model architectures. NVIDIA Corporation anchors specialized silicon supply for training workloads, while Schrödinger dominates physics-based modeling software licensing. The market structures around three archetypes: infrastructure providers controlling computational capacity, platform developers integrating end-to-end pipelines, and application specialists targeting single discovery stages. Competitive moves concentrate on strategic partnerships restructuring vendor relationships and portfolio diversification into adjacent therapeutic modalities.
Within the infrastructure-provider tier, NVIDIA Corporation occupies a position controlling specialized GPU architecture supply for molecular simulation pipelines. Among platform-integrated developers, Insilico Medicine exemplifies autonomous drug design operations spanning generative chemistry and clinical prediction, while Schrödinger represents physics-based modeling software licensing concentration across large pharmaceutical accounts. These three entities anchor distinct competitive vectors: silicon dependency, end-to-end pipeline integration, and established software licensing relationships.
| Leading Market Players |
|---|
| Isomorphic Labs (Alphabet Inc.) |
| NVIDIA Corporation |
| Recursion Pharmaceuticals |
| Schrödinger |
| Insilico Medicine |
| Exscientia |
| BenevolentAI |
| IBM |
| Atomwise |
| Others |
Supply & Pricing Matrix
GPU cluster spot pricing indices across North American cloud regions cascade through AI drug discovery platform economics, compressing margins for training-intensive workloads while concentrating pricing power with silicon-constrained infrastructure providers. This cost structure forces pharmaceutical sponsors to unbundle perpetual software licenses from professional services engagements and restructure procurement around consumption-based API access.
Pricing Analysis
Direct-to-OEM channel discounts anchor enterprise pharmaceutical account pricing, with consumption-based SaaS tiers displacing perpetual licensing across mid-cap biotechnology sponsors. Three-tier pricing structure across premium, standard, and economy levels differentiates by GPU cluster allocation, model parameter scale, and regulatory validation depth. Pricing pressure stems from NVIDIA silicon procurement bottlenecks extending lead times for training infrastructure. Mid-cap biotechnology firms exhibit highest price sensitivity, prioritizing capital efficiency over frontier capability access.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical demand for captive GPU clusters, while API-accessible inference routes through cloud service provider marketplaces. Supply concentrates in Taiwan for advanced semiconductor foundry capacity, the United States for specialized AI accelerator design, and China for domestic platform development serving NMPA regulatory pathways. Raw material dependencies span high-bandwidth memory modules, specialized photolithography equipment, and rare earth elements for magnetic components. Single-source vulnerability at the foundry tier exposes procurement timelines to geopolitical disruption. Distribution runs through hyperscaler marketplaces and direct enterprise licensing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI drug discovery functions as a stable compounder, with FDA model-informed drug development guidance providing regulatory validation continuity that insulates platform revenue from cyclical pharmaceutical R&D budget volatility.
For Market Incumbents: Cement platform stickiness through backward integration into proprietary bioassay data generation, capturing training corpus assets that emerging entrants cannot replicate. Expand GPU cluster capacity in the Boston-Cambridge corridor to anchor talent migration and reduce NVIDIA silicon dependency exposure. Lock in multi-year enterprise subscriptions before EU AI Act conformity assessment costs fragment European pricing structures. For New Entrants and Emerging Players: Transformer-based protein structure prediction offers a technology-first wedge into G-protein coupled receptor target programs previously considered intractable for large pharmaceutical sponsors. India's CDSCO computational pathway presents the most penetrable regulatory geography, with algorithmic evidence standards still in formative consultation. Pursue white-space positioning through API-first deployment models targeting mid-cap biotechnology firms seeking elastic capacity without perpetual license commitments. For Investors and Strategic Acquirers: Asymmetric upside sits with platform developers integrating end-to-end pipelines from target identification through clinical prediction, capturing value chain compression that point-solution vendors cannot match. Foundation model architectures trained on molecular representations demonstrate superior long-term viability across therapeutic area expansion. Monitor FDA guidance divergence from EMA algorithmic transparency requirements as the critical inflection signal for Atlantic deployment strategy fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Foundation Model Architecture Investment | Parameter scale exceeding one billion enables transfer learning across therapeutic areas, compressing development cycles for novel target classes. |
| GPU Cluster Capacity Expansion | Captive infrastructure in Boston-Cambridge reduces NVIDIA silicon dependency and anchors computational biology talent migration. |
| EU AI Act Conformity Assessment Preparation | ISO/IEC 42001 alignment becomes mandatory for clinical decision-support system market access in European jurisdictions. |
| Proprietary Bioassay Data Generation | In-house training corpus development creates defensible moats against algorithmic generalization constraints facing data-scarce competitors. |
| API-First Platform Commercialization | Consumption-based pricing models capture mid-cap biotechnology demand seeking capital-efficient access to frontier capabilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, computational biology platform engineers, and pharmaceutical procurement directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and venture capital deployment databases. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates across component, application, end user, and deployment dimensions.
Historical reference periods anchored the projection horizon through documented GPU cluster expansion trajectories, regulatory framework evolution timelines, and pharmaceutical R&D budget allocation shifts. Segmentation dimensions modeled include neural architecture type, functional deployment stage, organizational scale and capital structure, and infrastructure configuration. CAGRs derived from fitted growth curves incorporating training corpus scaling laws, algorithmic validation standardization progress, and therapeutic area expansion patterns. Industry-specific forecast inputs encompassed federal research funding disbursement rates and cloud region capacity buildout schedules.
The model holds under stable regulatory validation pathways and continued cloud infrastructure investment; deviation in FDA-EMA guidance divergence or foundry capacity constraints would shift growth trajectories. Forecasts reflect base-case assumptions regarding algorithmic transparency standardization and bioassay data sharing coalition formation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence in Logistics Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Automotive Market
Artificial Intelligence (AI)
Voice Assistance Application Market
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
Enterprise AI Governance and Compliance Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Stadium Market
Artificial Intelligence (AI)
Artificial Intelligence in Workspace Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market