
 Global Natural Language Generation (NLG) Market | 2026-2036
Global Natural Language Generation (NLG) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Natural Language Generation (NLG) Market Foresight
Transformer-based architectures are recalibrating cost structures across the NLG stack by displacing recurrent neural networks in production environments. Alphabet Inc. leverages its proprietary tensor processing infrastructure to sustain inference cost advantages at scale. Microsoft Corporation anchors enterprise demand through deep integration with productivity suites and Azure cloud services. International Business Machines Corporation competes in regulated verticals where explainable output requirements dominate procurement criteria.
Natural Language Generation encompasses computational systems that transform structured data into coherent human language through template-driven, statistical, or neural methods, typically operating with latency thresholds under 500 milliseconds for real-time applications. The technology serves commercial purposes ranging from automated financial narrative production to personalized customer communication at scale. Cloud-based deployment leads current infrastructure choices while edge computing configurations represent the fastest-growing configuration as latency-sensitive use cases expand. API integration solutions capture the largest margin pool by embedding NLG capabilities into existing enterprise workflows rather than requiring standalone platform adoption.
The EU AI Act imposes transparency obligations on automated content systems that reshape product development priorities for vendors seeking European market access. FDA guidance on software as a medical device intersects with clinical NLG applications, while GDPR data processing rules constrain training data sourcing strategies across the industry. Stakeholders must monitor evolving liability frameworks for machine-generated content as jurisdictions diverge in assigning responsibility for erroneous automated outputs.
Market Dynamics
Transformer-based architectures are compressing inference latency thresholds below 100 milliseconds for real-time financial narrative generation, forcing incumbent vendors to restructure their neural stack economics or cede enterprise procurement cycles to cloud-native competitors.
Growth Catalysts
- EU AI Act transparency mandates:Automated content disclosure requirements in European markets are accelerating procurement of auditable NLG pipelines among multinational banks preparing compliance infrastructure.
- Edge computing latency requirements:Manufacturing floors in Germany and Japan are deploying on-premise NLG modules to generate equipment diagnostic narratives without cloud round-trip delays.
- Real-time regulatory reporting:SEC and FERC filing automation is pulling structured data transformation capabilities into compliance technology budgets at North American energy trading desks.
Market Restraints
- GPU cluster supply concentration:Inference cost volatility tracks NVIDIA data center shipment allocations, with enterprise buyers facing 6-9 month procurement queues for dedicated tensor processing infrastructure.
- Training data licensing friction:GDPR Article 5 constraints on web-scraped corpora are forcing vendors toward expensive synthetic data generation or premium licensed content pools.
- Template-based system substitution:Rule-driven NLG retains cost advantages below 10,000 document volumes annually, limiting neural system penetration in mid-market insurance underwriting workflows.
Strategic Opportunities
- Clinical trial narrative automation:FDA software-as-medical-device guidance is creating first-mover advantages for NLG vendors building structured adverse event report generation into electronic data capture platforms.
- API-first distribution models:Embedding generation capabilities through REST endpoints captures margin pools in existing Salesforce and ServiceNow workflows without standalone platform adoption friction.
- India's BFSI digitization:RBI-mandated financial inclusion reporting is driving demand for vernacular language generation across regional bank branches in Maharashtra and Karnataka.
Industry Challenges
- Prompt engineering talent scarcity:Production-grade transformer tuning requires specialized reinforcement learning expertise that concentrates in San Francisco, London, and Bangalore hiring markets.
- Legacy system integration complexity:Mainframe-hosted core banking databases in Japanese and German institutions resist standard API connectivity, extending implementation timelines for real-time narrative injection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Natural Language Generation (NLG) Market |
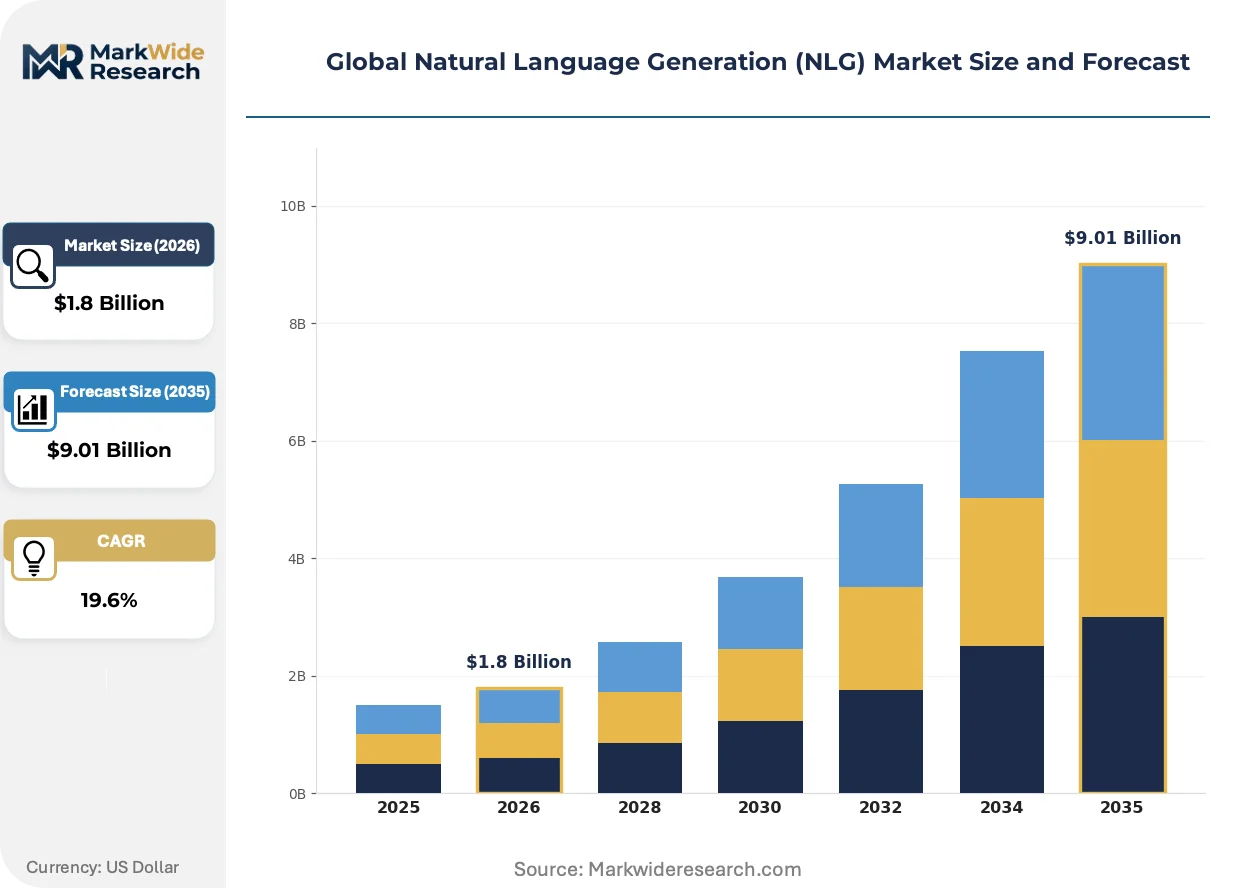
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $9.01 Billion |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution/Offering: API Integration, Standalone Software, Managed Services, Custom Solutions Use Case: Content Creation, Customer Support Automation, Financial Reporting, Personalized Marketing, Data Summarization End User: Financial Institutions, Media Agencies, E-Commerce Firms, Telecom Operators, Academic Entities |
| Companies Covered | Alphabet Inc., Microsoft Corporation, International Business Machines Corporation, Amazon Web Services, Salesforce, Inc., ARRIA NLG Limited, Yseop, Narrative Science, Automated Insights, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Natural Language Generation (NLG) Market Shifts & Advancements
Multimodal foundation models are collapsing the boundary between structured data ingestion and narrative output, enabling single-pass generation from tabular, visual, and textual inputs without intermediate pipeline stages.
Retrieval-augmented generation architectures are converging with vector database infrastructure to ground enterprise NLG outputs in proprietary document corpora. Pharmaceutical medical affairs teams at firms subject to FDA promotional review are adopting these systems to ensure claim substantiation. The structural consequence is compression of legal review cycles from weeks to hours for externally facing scientific content.
The EU AI Act's risk-tier classification system is forcing vendors to reengineer product architectures for high-stakes application categories. Systems generating creditworthiness explanations or clinical diagnostic narratives now require human oversight interfaces and output logging capabilities. German automotive manufacturers and French health technology firms are front-loading compliance engineering to secure CE marking pathways before the 2025 enforcement deadline.
Enterprise buyers are unbundling NLG capabilities from monolithic AI platforms and procuring through specialized API marketplaces. Procurement teams at US-based asset managers and UK insurers now evaluate generation quality through standardized benchmark suites rather than vendor demonstrations. This shift is most visible in financial services, where model cards and evaluation leaderboards have displaced traditional RFP processes for short-listing vendors.
Global Natural Language Generation (NLG) Market Segmentation
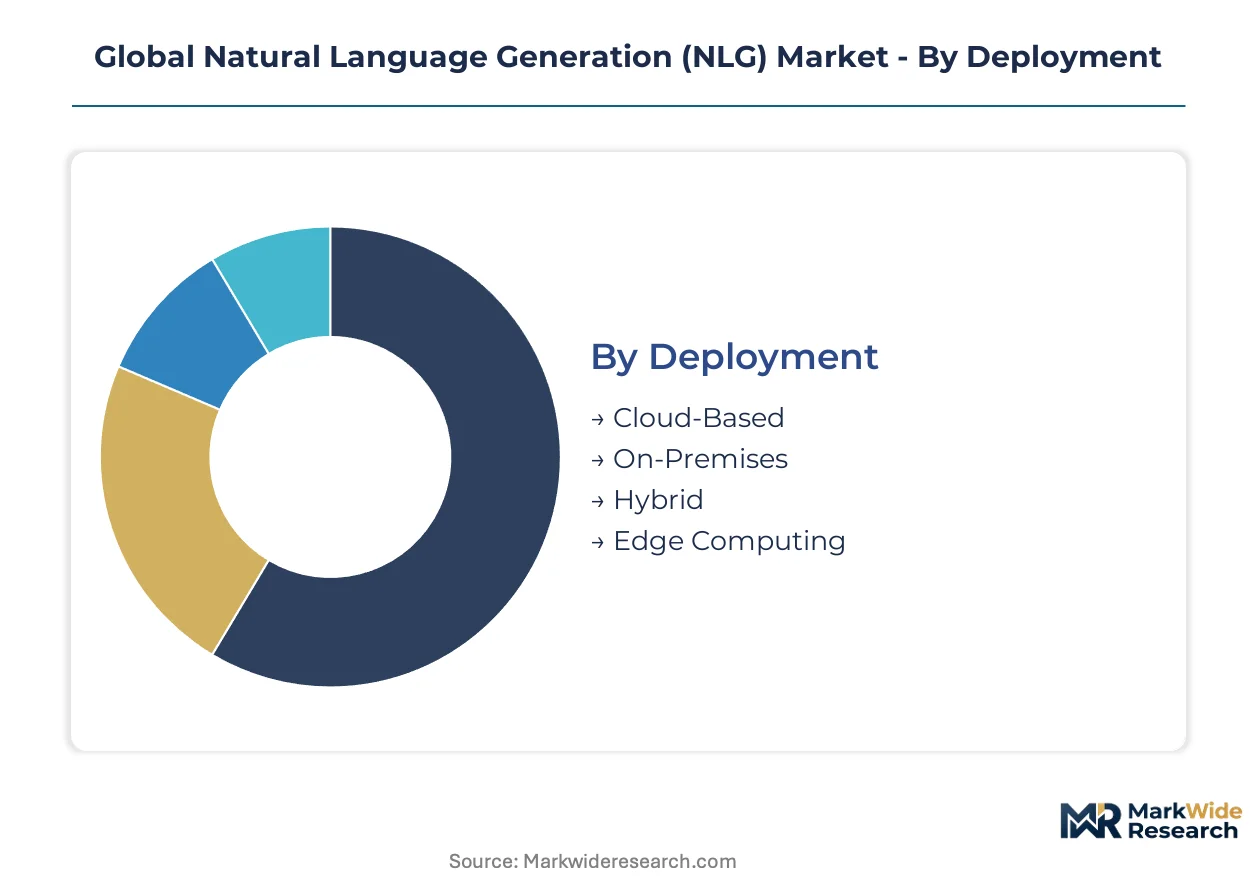
NLG procurement patterns diverge sharply across deployment topologies and integration models, with compliance architecture dictating viable configuration choices. Financial institutions filter vendor shortlists through regulatory audit requirements that vary by jurisdiction and use case risk tier.
Deployment:
Cloud-based configurations face EU AI Act transparency obligations and FDA software-as-medical-device guidance, while edge and on-premise alternatives navigate data residency mandates from national regulators.
- Cloud-Based:Multi-tenant infrastructure delivers sub-100-millisecond inference latency through hyperscaler tensor processing clusters. Demand concentrates at North American asset managers and UK insurers migrating core banking functions to Azure and AWS environments, though GDPR Article 44 cross-border transfer rules constrain European deployment architectures.
- On-Premises:Dedicated hardware installations in German automotive manufacturing floors and Japanese pharmaceutical facilities satisfy operational technology isolation requirements. These configurations absorb higher capital intensity to avoid cloud round-trip delays in equipment diagnostic narrative generation.
- Hybrid:Split processing architectures route sensitive training data through local infrastructure while pushing inference workloads to distributed cloud nodes.
- Edge Computing:Embedded modules on factory devices in Bavaria and Karnataka generate real-time maintenance logs without network dependency.
Cloud-based deployment sits at the top of the volume ranking, with edge computing climbing the fastest as manufacturing latency requirements harden.
Solution/Offering:
Margin capture varies dramatically by integration depth, with API embedding commanding premium pricing against standalone platform alternatives that require workflow disruption.
- API Integration:REST endpoint architectures embed generation capabilities directly into existing Salesforce and ServiceNow instances without standalone platform adoption friction. Financial services procurement teams at US asset managers and UK insurers now evaluate quality through standardized benchmark suites rather than vendor demonstrations.
- Standalone Software:Full-platform deployments persist in regulated verticals requiring comprehensive audit trails and human oversight interfaces for EU AI Act high-risk system compliance.
- Managed Services:Vendor-operated infrastructure transfers operational burden to specialized providers with dedicated reinforcement learning expertise.
- Custom Solutions:Bespoke development for clinical trial narrative automation at FDA-regulated pharmaceutical firms addresses adverse event report generation in electronic data capture platforms.
API integration leads current revenue concentration, though custom solutions are expanding most quickly in life sciences verticals facing promotional review requirements.
Use Case:
Risk-tier classification under the EU AI Act reshapes product development priorities, with creditworthiness explanations and clinical diagnostic narratives triggering enhanced human oversight mandates.
- Content Creation:Automated journalism and product description generation at media agencies and e-commerce firms operates in lower-risk regulatory tiers with reduced compliance engineering overhead.
- Customer Support Automation:Conversational agents in telecom operator call centers balance response latency against escalation pathway design for unresolved queries.
- Financial Reporting:SEC and FERC filing automation pulls structured data transformation capabilities into compliance technology budgets at North American energy trading desks, with real-time narrative generation compressing disclosure timelines.
- Personalized Marketing:Dynamic email and notification content at e-commerce firms leverages behavioral data pipelines with GDPR consent management constraints.
- Data Summarization:Executive briefing generation from enterprise document corpora converges with retrieval-augmented generation architectures and vector database infrastructure.
Financial reporting dominates current procurement volume, while data summarization gains share fastest as enterprise buyers unbundle NLG from monolithic AI platforms.
End User:
Vertical-specific procurement criteria fragment the addressable market, with explainable output requirements dominating regulated industries and latency thresholds driving manufacturing adoption.
- Financial Institutions:Multinational banks front-load compliance engineering for EU AI Act transparency mandates, accelerating procurement of auditable NLG pipelines for automated regulatory reporting.
- Media Agencies:High-volume content production workflows prioritize generation throughput and multi-language capability over interpretability features.
- E-Commerce Firms:Personalization engines at scale demand real-time product description variation with inventory system integration.
- Telecom Operators:Customer interaction volume drives API-first distribution model preference for embedded workflow integration.
- Academic Entities:Research data narrative generation and grant reporting automation operate with constrained procurement budgets favoring open-source foundation model fine-tuning.
Financial institutions anchor current demand concentration, with academic entities showing the steepest expansion trajectory as research data management requirements mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco Bay Area technology clusters anchor enterprise NLG procurement through hyperscaler tensor processing infrastructure and concentrated venture deployment. Cloud-native vendors leverage proximity to reinforcement learning talent pools while serving financial services buyers migrating from legacy data centers. Regulatory divergence across jurisdictions fragments deployment architectures as compliance engineering absorbs product development resources.
United States
Asset managers in Manhattan and Chicago drive real-time SEC filing automation demand through Azure and AWS cloud migrations. FERC disclosure requirements at North American energy trading desks compress narrative generation timelines into sub-100-millisecond latency thresholds. Boston-based pharmaceutical firms integrate NLG modules into electronic data capture platforms for FDA-regulated adverse event reporting.
Germany
Automotive manufacturers in Bavaria deploy on-premise NLG modules for equipment diagnostic narratives without cloud dependency. EU AI Act transparency mandates force reengineering of high-risk system architectures before the 2025 enforcement deadline. Stuttgart industrial floors absorb higher capital intensity to satisfy operational technology isolation requirements from national cybersecurity regulators.
United Kingdom
London insurers evaluate generation quality through standardized benchmark suites rather than vendor demonstrations. GDPR Article 44 cross-border transfer rules constrain European deployment architectures for multinational banks. Edinburgh fintech clusters front-load compliance engineering for automated creditworthiness explanation systems.
India
RBI-mandated financial inclusion reporting drives vernacular language generation demand across Maharashtra and Karnataka regional bank branches. Bangalore technology campuses concentrate prompt engineering talent scarce in Western hiring markets. Mumbai-based asset managers adopt API-first distribution models embedding generation capabilities into existing Salesforce workflows.
Japan
Tokyo pharmaceutical facilities satisfy PMDA software-as-medical-device guidance through structured adverse event report automation. Mainframe-hosted core banking databases resist standard API connectivity, extending implementation timelines for real-time narrative injection. Osaka manufacturing floors deploy edge computing modules generating maintenance logs without network round-trip delays.
Global Natural Language Generation (NLG) Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and specialized compliance verticals. The vendor base stratifies into three tiers: hyperscalers operating tensor processing clusters at continental scale, enterprise software incumbents with productivity suite integration advantages, and niche specialists serving regulated industries with explainable output requirements. Dominant competitive moves include API-first distribution partnerships embedding generation capabilities into existing enterprise workflows, and compliance engineering investments securing CE marking pathways before EU AI Act enforcement deadlines.
Within the hyperscaler tier, Alphabet Inc. and Microsoft Corporation exemplify cloud-native architectures leveraging proprietary infrastructure for inference cost advantages at scale. IBM Corporation occupies a position among regulated vertical specialists where auditable pipelines and human oversight interfaces dominate procurement criteria. Salesforce, Inc. anchors the enterprise application integration vector through workflow embedding rather than standalone platform displacement. These three archetypes—hyperscaler infrastructure, compliance-specialized systems, and embedded application layers—capture distinct margin pools without direct feature competition.
| Leading Market Players |
|---|
| Alphabet Inc. |
| Microsoft Corporation |
| International Business Machines Corporation |
| Amazon Web Services |
| Salesforce, Inc. |
| ARRIA NLG Limited |
| Yseop |
| Narrative Science |
| Automated Insights |
| Others |
Supply & Pricing Matrix
API-first versus standalone platform divergence separates margin capture in the NLG stack, with REST endpoint embedding commanding premium pricing against workflow-disruptive full-platform alternatives while hyperscaler tensor processing clusters in the United States and Ireland anchor supply-side concentration for cloud-native inference.
Pricing Analysis
GPU cluster procurement queues and synthetic data generation costs pass through to enterprise buyers as subscription tier adjustments. Three-tier pricing structure across premium, standard, and economy levels tracks API call volume thresholds and compliance certification grade. Pricing pressure stems from template-based system substitution below 10,000 annual document volumes in mid-market insurance underwriting. Mid-market procurement teams show highest price sensitivity, while FDA-regulated pharmaceutical firms absorb premium tiers for audit trail completeness.
Supply Chain Analysis
Direct-to-enterprise channels handle multinational bank demand, while API marketplaces serve embedded workflow integration at asset managers and insurers. Hyperscaler infrastructure concentrates in the United States, Ireland, and Singapore, with NVIDIA data center shipments feeding tensor processing cluster deployment. Training data licensing draws from premium content pools and synthetic generation pipelines given GDPR Article 5 constraints on web-scraped corpora. Single-source vulnerability runs through NVIDIA inference chip allocation, with distribution running through hyperscaler marketplaces and specialized API exchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in NLG rests on API embedding depth and compliance engineering premiums, with transformer inference cost compression enabling tier repricing toward high-volume enterprise contracts.
For Market Incumbents: Deepen API marketplace presence to capture unbundling demand from monolithic AI platform displacement. Fortify compliance engineering investments for EU AI Act high-risk system certification ahead of enforcement deadlines. Extend backward integration into proprietary tensor processing infrastructure to defend inference cost position against cloud-native challengers. For New Entrants and Emerging Players: Capture clinical trial narrative automation white space in FDA-regulated electronic data capture platforms where first-mover advantages persist. Target vernacular language generation demand at India's regional bank branches facing RBI-mandated financial inclusion reporting. Lead with managed service offerings that transfer operational burden from talent-scarce reinforcement learning markets. For Investors and Strategic Acquirers: Consolidation pressure builds where prompt engineering talent scarcity concentrates vendor viability in San Francisco, London, and Bangalore hiring markets. Long-term viability favors specialized compliance verticals over horizontal platform plays given regulatory divergence. Watch for API marketplace liquidity thresholds as inflection signals for embedded workflow integration dominance.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Launch | REST endpoint architectures capture margin pools in existing Salesforce and ServiceNow workflows without displacement friction. |
| EU AI Act Compliance Engineering | Human oversight interfaces and output logging capabilities secure CE marking pathways for high-risk creditworthiness explanation systems. |
| Edge Computing Module Deployment | Embedded factory-floor installations in Bavaria and Karnataka satisfy operational technology isolation from national cybersecurity regulators. |
| Retrieval-Augmented Generation Integration | Vector database convergence grounds pharmaceutical medical affairs outputs in proprietary document corpora for FDA promotional review. |
| Vernacular Language Capability Expansion | Maharashtra and Karnataka regional bank demand addresses RBI-mandated financial inclusion reporting automation requirements. |
Research Methodology
Multiple input streams — structured interviews with NLG procurement officers at North American asset managers, technical discussions with platform engineers at hyperscaler AI divisions, and validation sessions with regulatory affairs leads at FDA-regulated pharmaceutical firms — were reconciled against secondary sources including SEC 10-K filings, hyperscaler capex disclosures, and EU AI Act implementation guidance. Bottom-up deployment volume estimates and top-down enterprise software spending analysis were triangulated to anchor market sizing.
Historical adoption curves from cloud migration cycles were cross-referenced against panel input from CTOs and IT procurement officers to model penetration trajectories across the analysis window. Segmentation dimensions included deployment topology, integration model, use case risk tier, and end-user vertical. CAGRs were derived from weighted average of technology diffusion rates and compliance-driven replacement cycles, with transformer architecture displacement timelines and edge computing latency requirement hardening as specific forecast inputs.
Regulatory enforcement timing, GPU cluster supply allocation volatility, and template-based system substitution elasticity are the dominant revision risks to projection assumptions. Forecasts reflect documented assumptions regarding enterprise cloud migration pace and EU AI Act implementation uniformity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Manufacturing Market
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Emotion AI Software Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market
Artificial Intelligence (AI)
Brain-Computer Interface System Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Asia-Pacific AI Orchestration Market
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
Global AI Training Dataset Market