
 Online Insurance Market | 2026-2036
Online Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Online Insurance Market Analysis
Direct-to-consumer digital distribution is narrowing as incumbent carriers and insurtech startups converge on the same mobile-first customer base. Allianz leverages its proprietary risk-engineering platforms to sustain pricing power in commercial lines. Lemonade competes through AI-driven claims automation that reduces loss-adjustment expenses. Progressive anchors its market position with usage-based telematics data that personalizes auto premiums.
Online insurance denotes policies sold, underwritten, and serviced through internet-connected platforms without mandatory agent intermediation, relying on algorithmic risk scoring and API-based data verification for real-time quoting. Its primary commercial purpose is reducing customer acquisition costs while expanding addressable populations beyond traditional agent-served segments. Health insurance and auto insurance command the largest premium volumes, though life insurance trails due to complex medical underwriting requirements. Direct online platforms capture the fastest growth trajectory as mobile-native consumers bypass broker intermediaries entirely.
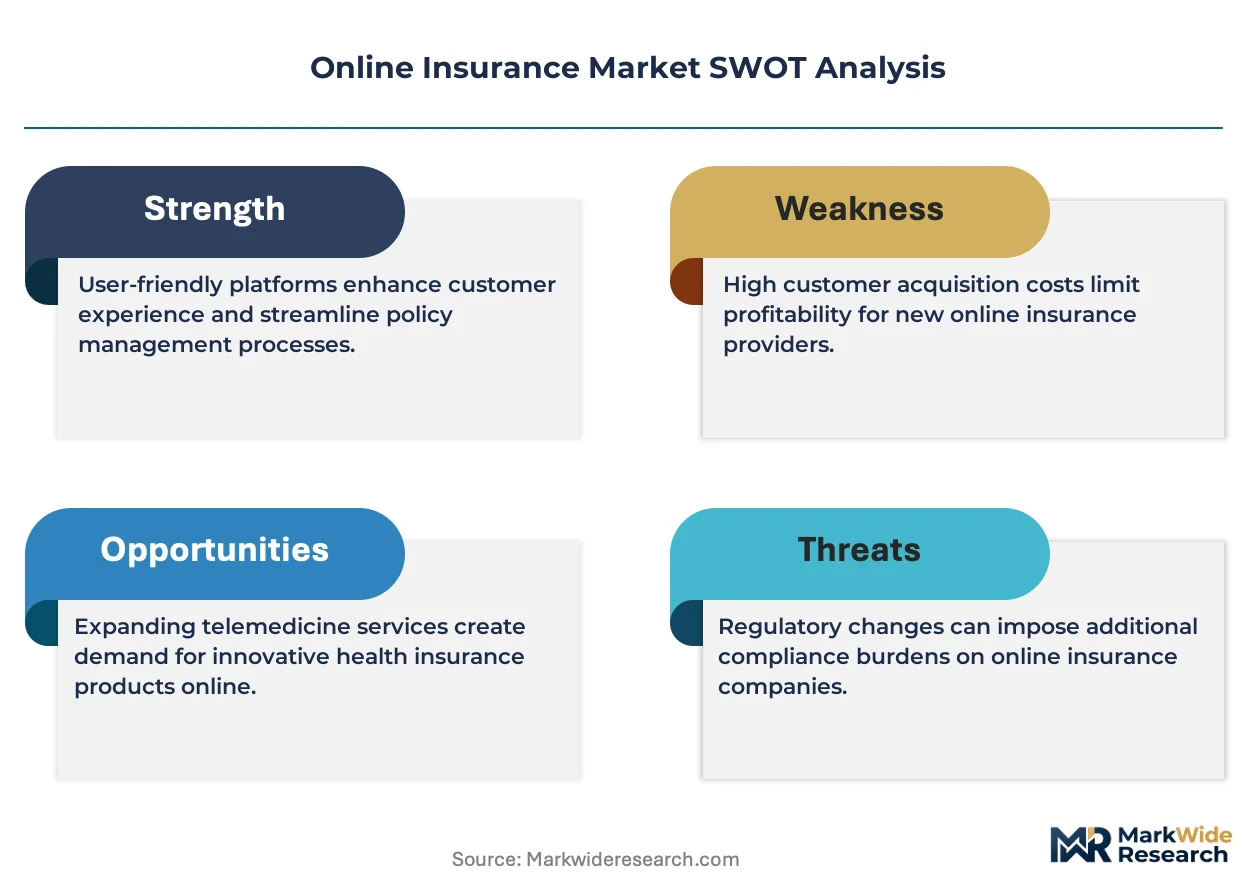
FDA oversight of wellness-linked life insurance products, GDPR constraints on behavioral data usage in the European Union, and state insurance commissioner rate approvals in the United States collectively shape product design and market access boundaries. Regulators in India through IRDAI and in Germany through BaFin are tightening digital sales disclosure standards to protect consumers from algorithmic bias. Stakeholders must monitor evolving AI governance frameworks that could restrict predictive underwriting models before committing long-term technology roadmaps.
Market Dynamics
Algorithmic underwriting platforms are compressing policy issuance cycles from days to minutes, forcing incumbents to rebuild core systems around API-first architectures or cede direct distribution to insurtech challengers.
Growth Catalysts
- Telematics Integration:Usage-based auto insurance leveraging real-time vehicle data expands addressable risk pools beyond traditional actuarial categories. Progressive and European carriers deploy OBD-II devices and smartphone sensors to price mileage and behavior.
- GDPR-Compliant Data Frameworks:Standardized consent management tools enable cross-border policy sales within the European Union. BaFin disclosure guidelines provide regulatory clarity for algorithmic sales channels in Germany.
- Small Business Digital Adoption:Micro-enterprises in the United States bypass agent networks for commercial property and liability coverage. Embedded insurance APIs at point-of-sale platforms capture this segment.
Market Restraints
- Legacy Core System Debt:Mainframe-based policy administration at established carriers limits real-time quoting capabilities. Migration costs consume 18-24 month IT roadmaps.
- Behavioral Data Restrictions:GDPR Article 22 constraints on automated decision-making limit predictive pricing models in EU member states. Insurers must maintain human review loops for contested claims.
- Medical Underwriting Complexity:Life insurance products require paramedical examinations that resist full digitization. Simplified issue products carry adverse selection risk.
Strategic Opportunities
- Embedded Distribution Channels:E-commerce platforms and fintech apps host insurance at transaction points. Travel booking sites in India cross-sell trip cancellation through IRDAI-approved APIs.
- Climate Risk Parametric Products:Satellite-triggered policies bypass traditional loss adjustment for flood and drought coverage. Farmers in drought-prone Indian states access payout certainty.
- AI Claims Automation:Computer vision and NLP compress property damage assessment from weeks to hours. Lemonade's AI-driven workflows reduce loss-adjustment expense ratios.
Industry Challenges
- Actuarial-Data Science Integration:Traditional pricing teams and machine-learning engineers operate on incompatible validation standards. Talent scarcity in hybrid roles slows model deployment.
- Multi-State Compliance Fragmentation:US carriers face 50 separate insurance commissioner rate filing requirements. Rate adequacy disputes in California and Florida delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Insurance Market |
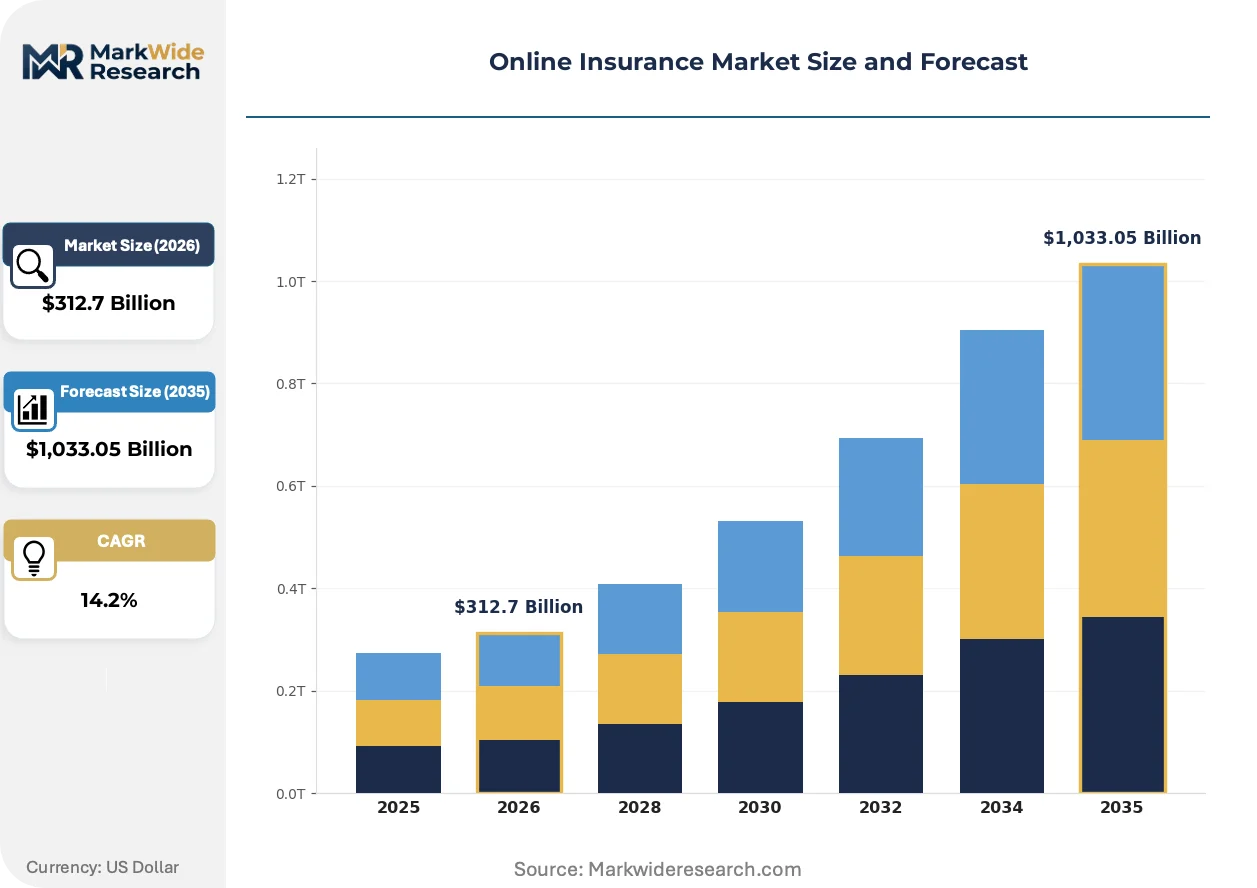
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $1,033.05 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Insurance, Life Insurance, Auto Insurance, Property Insurance Customer Type: Individuals, Families, Small Businesses, Corporations Distribution Channel: Direct Online Platforms, Insurance Brokers, Comparison Websites, Mobile Applications Premium Range: Low Premium, Medium Premium, High Premium, Luxury Premium |
| Companies Covered | Allianz, AXA, State Farm, Progressive, Lemonade, Next Insurance, Root Insurance, Oscar Health, Policygenius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Insurance Market Emerging Trajectories
Real-time data streams and embedded distribution are collapsing the traditional insurance value chain, compressing acquisition costs while raising the bar for instant underwriting precision.
Telematics hardware and smartphone-based driving analytics is migrating from niche usage-based programs to standard auto policy pricing. Mid-market carriers in the United States and Germany now collect acceleration, braking, and mileage data as default underwriting inputs. This compression of risk assessment into continuous monitoring enables dynamic premium adjustments that static demographic models cannot match.
The EU AI Act's risk classification framework imposes documentation and human oversight requirements on automated underwriting systems. High-risk insurance algorithms must maintain audit trails and explainability standards. German and French carriers are rebuilding pricing engines to satisfy BaFin and CNIL interpretability mandates before the 2025 enforcement window.
Mobile-native consumers now initiate policy research through aggregator comparison tools rather than captive agent relationships. Direct online platforms in the United States, Germany, and India capture this behavioral shift with instant quote engines. Agent-served distribution retains dominance only in complex commercial lines and high-net-worth personal lines where customization demands human advisory.
Online Insurance Market Segmentation
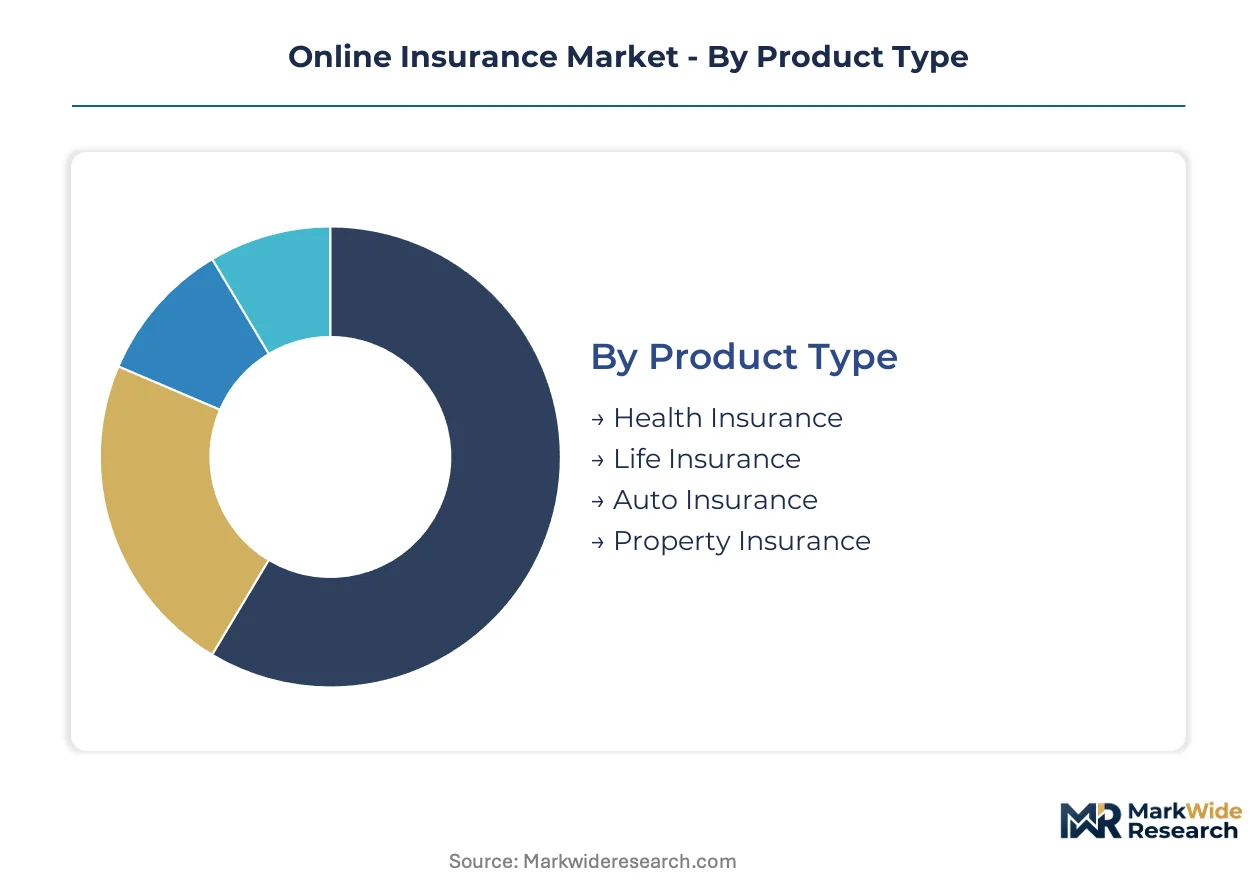
Online insurance segmentation reveals divergent service intensity requirements across product lines. Health and auto policies demand continuous digital engagement through claims portals and telematics apps, while life insurance requires intermittent but high-touch medical underwriting support. Distribution channel selection directly determines post-sale servicing architecture and customer retention economics.
Product Type:
After-sales-service intensity varies dramatically across product categories, with health and auto insurance requiring ongoing digital touchpoints versus life insurance's episodic but complex servicing demands.
- Health Insurance:Real-time claims adjudication through API-connected provider networks demands persistent platform uptime and chatbot support. United States and Indian insurers invest heavily in mobile symptom checkers and digital prior authorization workflows to reduce call center dependency. Telemedicine integrations now serve as standard retention tools.
- Auto Insurance:Continuous telematics data streams require 24/7 infrastructure for dynamic pricing adjustments and instant accident response. Progressive and European carriers deploy smartphone sensors and OBD-II devices that feed real-time driving behavior into monthly premium recalculations, creating persistent customer engagement.
- Life Insurance:Paramedical examination coordination and beneficiary management need scheduled human intervention despite digitization efforts. Simplified issue products in India bypass full underwriting but carry adverse selection risk that demands post-issue monitoring.
- Property Insurance:Catastrophe response and contractor network dispatch require surge-capable service infrastructure. Climate parametric products in drought-prone Indian states automate payouts through satellite triggers, reducing loss adjustment overhead.
Auto insurance holds the largest share; momentum sits with health insurance as telemedicine integrations deepen policyholder stickiness.
Customer Type:
Cost tier segmentation separates price-sensitive individual purchasers from corporations demanding bespoke coverage architectures and dedicated account servicing.
- Individuals:Single-policyholders purchasing through direct online platforms prioritize instant quote comparison and self-service claims. Mobile-native consumers in Germany and the United States bypass agent relationships entirely, compressing acquisition costs for carriers.
- Families:Multi-life health and bundled property-auto combinations require dependent management tools and consolidated billing. Family plans in India through IRDAI-regulated platforms increasingly embed wellness incentives that drive renewal behavior.
- Small Businesses:Micro-enterprises purchasing commercial property and liability coverage through embedded APIs at point-of-sale platforms represent the fastest-expanding segment. United States fintech partnerships capture this demand with instant certificate generation.
- Corporations:Enterprise clients demand customized risk engineering and captive cell structures that resist full digitization. Allianz retains these relationships through proprietary risk-assessment platforms and dedicated underwriting teams.
Individuals dominate transaction volume; small businesses are climbing the fastest as embedded distribution captures previously unserved micro-enterprises.
Distribution Channel:
Application-based segmentation distinguishes algorithmic direct platforms from human-intermediated channels with divergent data requirements and compliance obligations.
- Direct Online Platforms:Captive insurer websites and mobile apps with instant quoting engines and API-based verification now serve as the primary growth vector. Lemonade and similar insurtechs deploy AI-driven claims automation that compresses settlement cycles from weeks to hours.
- Insurance Brokers:Independent intermediaries retain dominance in complex commercial lines and high-net-worth personal lines where customization demands human advisory. GDPR Article 22 constraints on automated decision-making reinforce broker relevance in EU member states.
- Comparison Websites:Aggregator platforms in Germany and the United States drive price transparency but commoditize carrier differentiation. These channels capture mobile-native consumers initiating policy research outside captive agent relationships.
- Mobile Applications:Smartphone-native distribution with embedded insurance at transaction points—travel booking sites in India, ride-hailing platforms—expands addressable populations beyond traditional insurance purchasers.
Direct online platforms command the steepest expansion trajectory; brokers defend share in segments where algorithmic pricing faces regulatory or complexity constraints.
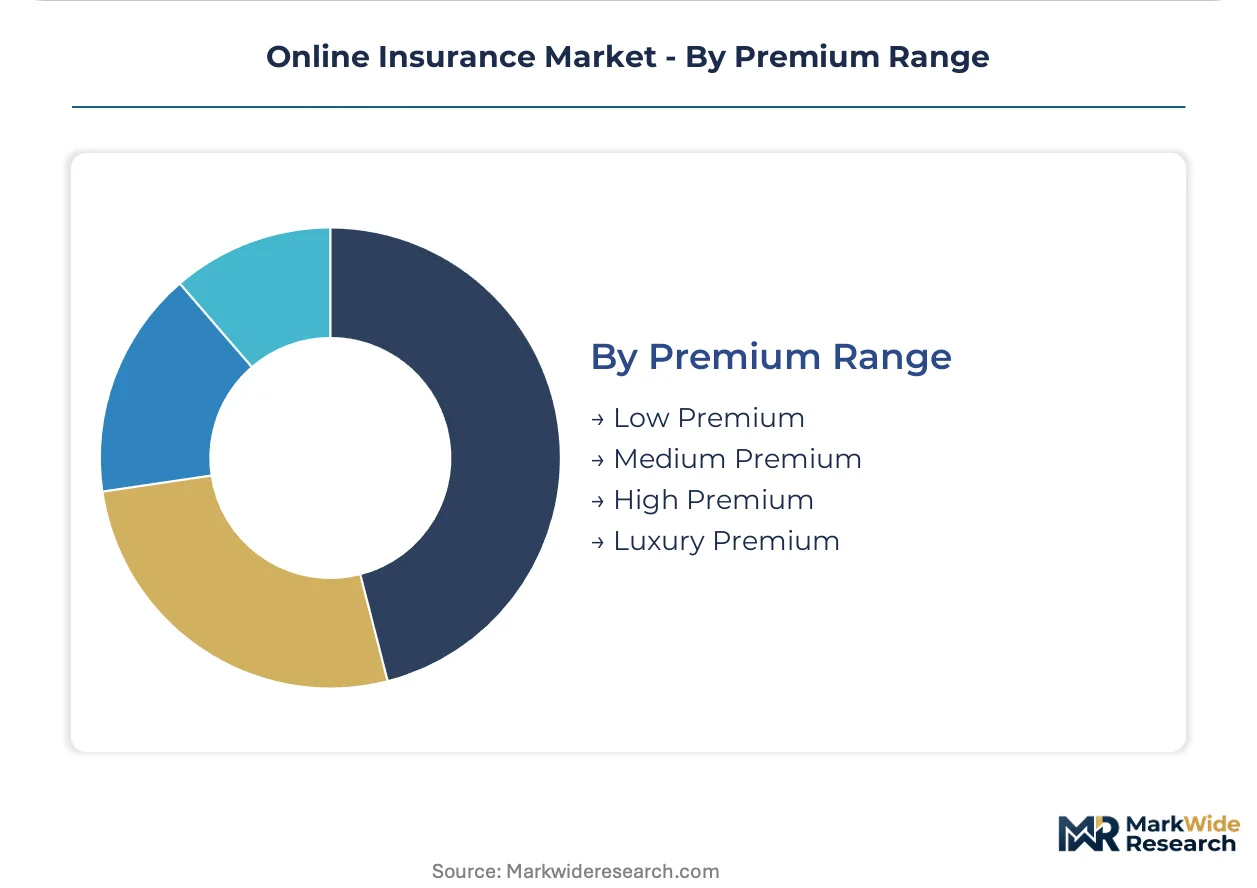
Premium Range:
Margin-based segmentation stratifies customers by willingness to pay for service tier differentiation and coverage breadth.
- Low Premium:Simplified issue products with minimal underwriting and claims automation target price-sensitive individual purchasers in India and emerging markets. High volume and low touch economics require API-first infrastructure.
- Medium Premium:Standard coverage tiers with balanced digital and human servicing represent the competitive battleground for mid-market carriers in the United States and Germany. Telematics-enabled auto policies cluster here.
- High Premium:Comprehensive coverage with dedicated claims handlers and concierge services attracts affluent families and small business owners. GDPR-compliant data frameworks enable cross-border sales of these products within the European Union.
- Luxury Premium:Bespoke coverage for high-net-worth individuals with complex asset portfolios demands specialized underwriting and white-glove service. Human advisory channels retain near-total dominance in this tier.
Medium premium policies generate the largest absolute premium volume; low premium products are gaining share fastest as embedded distribution democratizes access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border fiber connectivity through the transatlantic submarine cable systems underwrites digital insurance platform reach into European markets. Cloud region density in Frankfurt, London, and Dublin determines latency-sensitive underwriting engine placement.
United States
Telematics-enabled auto insurance adoption concentrates in Texas and California where mileage-based pricing attracts suburban commuters. State insurance commissioners in Florida and California enforce distinct rate approval timelines that fragment product launch schedules. The I-95 Northeast corridor hosts the densest cluster of insurtech engineering talent in Boston and New York.
Germany
BaFin's algorithmic disclosure mandates reshape digital sales channel compliance costs for direct-to-consumer platforms. The EU AI Act's high-risk system classification imposes documentation burdens on automated underwriting engines. Munich and Frankfurt maintain continental Europe's deepest concentration of actuarial-data science hybrid talent pools.
India
IRDAI's sandbox licensing framework accelerates embedded insurance deployment through fintech partnerships in travel and ride-hailing apps. Smartphone penetration in Maharashtra and Karnataka drives mobile-first policy issuance growth. Mumbai's BFSI corridor anchors back-office operations for multiple digital-first carriers.
United Kingdom
FCA consumer duty rules tighten digital sales disclosure standards for comparison website intermediaries. Lloyd's of London syndicates experiment with parametric climate products through satellite-triggered payout mechanisms. The Square Mile retains dominance in commercial specialty lines that resist full digitization.
Online Insurance Market Vendor Landscape
On the supply side, the industry is bifurcated between legacy carriers with captive distribution and venture-backed insurtechs competing for mobile-native customer acquisition. Incumbents leverage proprietary risk-engineering platforms and decades of claims data reserves. Challengers deploy AI-driven automation to compress expense ratios below traditional benchmarks. Dominant competitive moves include API-first core system replacement and embedded distribution partnerships at transaction points.
Within the insurtech challenger tier, Lemonade and Root Insurance exemplify algorithmic-native entrants that built pricing engines without legacy mainframe dependencies. Allianz anchors the incumbent defense with proprietary commercial lines platforms that sustain pricing power through risk-engineering depth. Progressive occupies a hybrid position, having rebuilt core systems around telematics data streams that enable dynamic premium adjustments.
| Leading Market Players |
|---|
| Allianz |
| AXA |
| State Farm |
| Progressive |
| Lemonade |
| Next Insurance |
| Root Insurance |
| Oscar Health |
| Policygenius |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure concentration in the United States and Ireland concentrates data hosting costs for algorithmic underwriting platforms, directing margin pools toward carriers with captive server capacity or long-term hyperscaler contracts. This upstream compute dependency shapes pricing power across direct-to-consumer distribution tiers.
Pricing Analysis
Volume-discount tiering structures dominate direct online platforms, with premium pricing attached to telematics-enabled auto policies and AI-driven claims automation. Price differentiation rests on data granularity—real-time driving behavior commands premium positioning over static demographic models—and regulatory compliance burden, where GDPR-aligned consent frameworks add service costs. Pricing pressure stems from insurtech challengers compressing acquisition costs through embedded distribution APIs. Individual policyholders exhibit highest price sensitivity, while small businesses purchasing through point-of-sale platforms accept modest premiums for instant certificate generation.
Supply Chain Analysis
Supplier-financing facilities extended by hyperscalers to insurtech challengers compress working capital requirements for platform development. Geographic supply concentrates in the United States, Germany, and India for actuarial-data science talent and regulatory sandbox access. Raw material dependencies center on telematics hardware from Taiwan, smartphone sensors from South Korea, and satellite data feeds from United States aerospace providers. Supply chain risk runs through single-source vulnerability in cloud region concentration for real-time quoting engines. Distribution runs through API-first architectures connecting embedded partners at transaction points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in online insurance hinges on interoperability standards enabling seamless data exchange between underwriting engines and distribution endpoints, with open banking frameworks accelerating this ecosystem shift.
For Market Incumbents: Insulate core commercial lines profitability through proprietary risk-engineering platforms that algorithmic-native entrants cannot replicate without decades of claims data reserves. Accelerate API-first core system replacement to compress policy issuance cycles. Vertical integration into captive telematics hardware supply hedges against sensor cost volatility from Taiwan and South Korea. For New Entrants and Emerging Players: India's IRDAI-sandboxed fintech partnerships represent the most penetrable white-space for embedded insurance deployment at ride-hailing and travel booking transaction points. Target small business commercial property coverage through point-of-sale API integrations that bypass incumbent agent networks. Pursue parametric climate products in drought-prone states where satellite-triggered payouts bypass traditional loss adjustment infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed insurtechs that have scaled customer acquisition but face unit-economic pressure from rising cloud compute and compliance costs. Long-term viability favors platforms with demonstrated retention economics in telematics-enabled auto or health insurance segments. Monitor IRDAI sandbox graduation rates and EU AI Act enforcement patterns as inflection indicators for regulatory-driven consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Core System Replacement | Enables real-time quoting that matches Lemonade's sub-minute issuance benchmarks. |
| Embedded Distribution Partnership | Captures small business demand at Shopify and QuickBooks transaction points. |
| Telematics Data Platform Investment | Feeds dynamic pricing models that Progressive deploys for retention advantage. |
| GDPR-Compliant Consent Framework | Satisfies BaFin and CNIL mandates ahead of EU AI Act enforcement windows. |
| Parametric Climate Product Launch | Automates payouts through satellite triggers in Indian drought-prone regions. |
Methodological Framework
A standing panel of chief underwriting officers, insurtech product managers, regulatory compliance leads, and embedded distribution partners provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from IRDAI sandbox disclosures, BaFin algorithmic sales guidelines, SEC insurer 10-K filings, and cloud hyperscaler infrastructure reports. Bottom-up policy volume estimates triangulated against top-down premium pool assessments across the analysis window.
Scenario-bracketing framed projections across regulatory intervention, technology adoption, and competitive entry pathways. Segmentation dimensions modeled include product type, customer archetype, distribution channel, and premium tier alongside regulatory jurisdiction clustering. CAGRs derived from historical trajectory analysis adjusted for telematics penetration curves and embedded insurance API deployment rates. Forecast inputs incorporated IRDAI sandbox licensing velocity and EU AI Act implementation timelines.
Practitioners should monitor regulatory sandbox graduation failures and cloud region service disruptions for early signals of forecast deviation. Assumptions reflect current algorithmic underwriting adoption patterns and embedded distribution partnership economics. Macroeconomic contraction affecting small business formation, state-level rate approval delays in California and Florida, or GDPR enforcement escalation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Liability Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Global AI in Auto-Insurance Market
Insurance
Trade Credit Insurance Market
Insurance
Drone Insurance Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
Cargo Insurance Market
Insurance
India Travel Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Parametric Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
India Online Insurance Market
Insurance
Mobile Phone Insurance Market