
 Eyewear Packaging Market | 2026-2036
Eyewear Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Eyewear Packaging Market Foresight
Premium-grade rigid box specifications are redrawing competitive boundaries in eyewear packaging. EssilorLuxottica SA leverages vertical integration from lens production to retail presentation to sustain packaging quality control across its global store network. Gatto Astucci Spa specializes in leather-clad luxury cases that anchor the high-margin accessories segment for European fashion houses. Giorgio Fedon & Figli Spa competes through its heritage positioning in handcrafted Italian eyewear cases.
Eyewear packaging denotes the protective and presentational enclosure systems engineered for spectacles, sunglasses, and optical frames, typically incorporating molded pulp trays, velvet-lined cavities, and hinge-reinforced board constructions to prevent lens abrasion and frame deformation during transit and retail display. The primary commercial purpose centers on brand differentiation at point-of-sale while ensuring product integrity through the distribution chain. Boxes dominate the packaging type dimension as the standard format for prescription eyewear, though pouches represent the fastest-growing category driven by foldable frame programs and travel retail expansion. Plastic retains volume leadership in material composition, yet paper-based alternatives are capturing margin pools as sustainability-linked procurement criteria harden across European and North American retail channels.
The EU Packaging and Packaging Waste Regulation is mandating recycled content thresholds and extended producer responsibility frameworks that reshape material selection across the value chain. FDA oversight of indirect food-contact substrates and California's Proposition 65 labeling requirements for metal components constrain formulation choices for brands distributing in the United States. China's GB standards for packaging recyclability and India's BIS certification for imported paperboard add compliance layers for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating material platforms that satisfy the strictest territorial standard without fragmenting production economics.
Market Dynamics
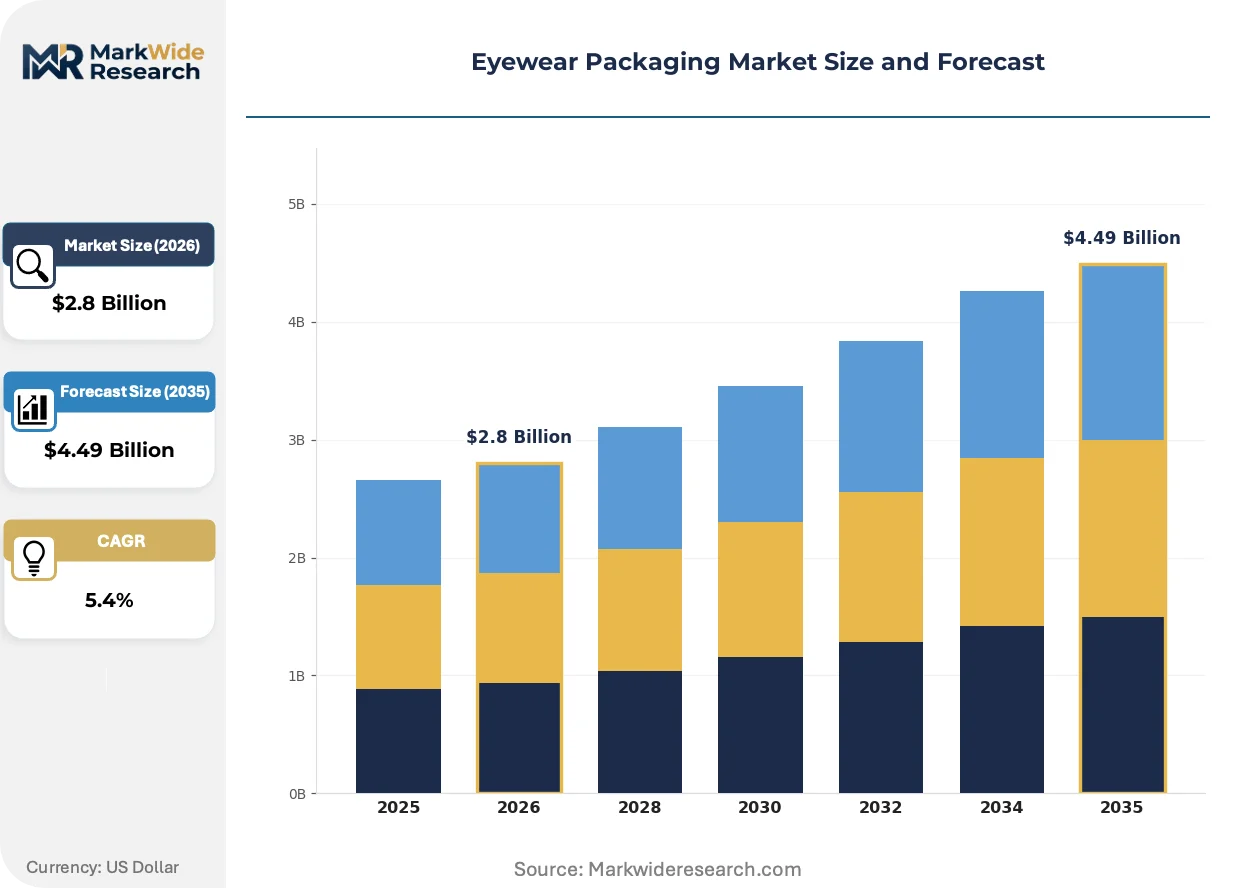
The EU Packaging and Packaging Waste Regulation is forcing material substitution across the eyewear packaging value chain, compressing lead times for recycled content qualification while premium retailers simultaneously expand branded packaging programs.
Growth Catalysts
- EU Green Deal packaging mandates:Recycled content thresholds under the EU Packaging and Packaging Waste Regulation are pulling fiber-based alternatives into prescription eyewear boxes ahead of compliance deadlines.
- Foldable frame engineering:Travel retail expansion of collapsible sunglasses programs is accelerating pouch format adoption across airport duty-free channels.
- Belluno manufacturing cluster:Italy's concentrated eyewear production base generates localized packaging demand that sustains specialized converter economics.
Market Restraints
- Recycled fiber input volatility:Post-consumer pulp quality inconsistency raises rejection rates for molded tray specifications in premium optical retail.
- Chinese converter concentration:Mid-tier plastic case production clusters in Zhejiang and Guangdong provinces create single-source vulnerability for volume brands.
- Metal component labeling friction:California Proposition 65 warning requirements for hinge hardware add compliance cost layers to US-bound shipments.
Strategic Opportunities
- Indian optical retail expansion:Underpenetrated organized retail in tier-two Indian cities offers first-mover positioning for standardized case suppliers.
- Pharma-eyewear convergence:Prescription lens e-commerce platforms are creating direct-to-consumer packaging specifications bypassing traditional wholesale formats.
- Extended producer responsibility credits:EU member state recycling offset schemes reward mono-material construction that simplifies end-of-life processing.
Industry Challenges
- Color-matching skill scarcity:Leather dye consistency for luxury case programs requires artisan expertise concentrated in Northern Italian tanneries.
- Multi-jurisdiction certification timelines:Simultaneous FDA indirect food-contact review and BIS paperboard import clearance extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eyewear Packaging Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Boxes, Pouches, Sleeves, Blisters Material: Plastic, Paper, Metal, Glass End User: Retailers, Wholesalers, E-commerce, Manufacturers Design Style: Luxury, Minimalist, Eco-friendly, Custom |
| Companies Covered | Classic Packaging, MARBER S.R.L., KLING GMBH, Hoya, Silhouette, Packman Packaging Private Limited, Gatto Astucci Spa, EssilorLuxottica SA, Giorgio Fedon & Figli Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eyewear Packaging Market Shifts & Advancements
Molded pulp engineering is displacing conventional plastic tray formats while regulatory pressure on recyclability compresses material innovation cycles across converter R&D programs.
Algae-derived biopolymer formulations are decomposing the petroleum-based tray monopoly in premium eyewear packaging. Italian fashion houses are piloting these materials for spring collection cases. The technology is decomposing cost barriers between sustainable positioning and margin preservation.
REACH SVHC disclosure requirements are tightening supply chain documentation burdens for metal hinge components sourced through Asian trading networks. European converters are consolidating supplier panels to reduce chemical inventory audit complexity. Small-batch Italian case manufacturers face disproportionate compliance cost absorption relative to volume competitors.
Direct optical brand e-commerce is fragmenting procurement into SKU-level specifications rather than annual program commitments. Online-native eyewear retailers are unbundling case inclusion from frame purchases, creating demand for separately merchandised accessory packaging. This pattern concentrates in North American and Northern European markets where subscription lens replacement programs have normalized digital purchase cycles.
Eyewear Packaging Market Segmentation
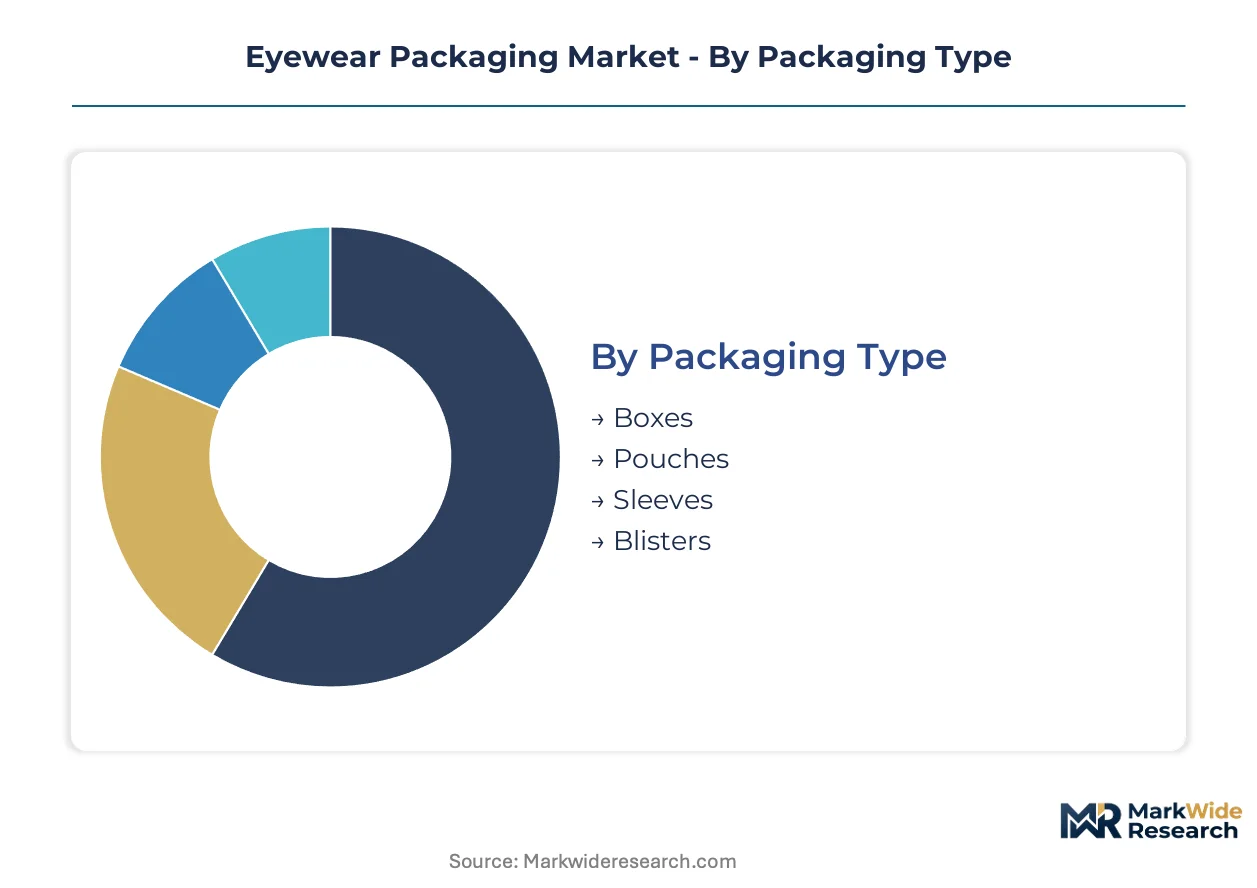
Packaging specifications in eyewear diverge sharply across distribution channels, with e-commerce fulfillment driving crush-resistant structural requirements while luxury retail prioritizes tactile presentation surfaces. Material compliance timelines under EU regulation are compressing procurement decisions, forcing converters to qualify alternatives before legacy formats face substitution mandates.
Packaging Type:
Rigid formats face intensifying substitution pressure from collapsible alternatives as travel retail expands and frame engineering enables slimmer protective profiles.
- Boxes:Hinge-reinforced board constructions with velvet-lined cavities remain the default specification for prescription eyewear distributed through optical retailers. Demand concentrates in Italy's Belluno manufacturing cluster where EssilorLuxottica's vertical integration sustains captive converter relationships. EU recycled content thresholds are forcing fiber-based tray substitutions that raise rejection rates for molded pulp quality consistency.
- Pouches:Soft-shell microfiber or synthetic leather enclosures dominate foldable frame programs and airport duty-free channels where space efficiency drives procurement. North American online-native retailers are unbundling pouch inclusion from frame purchases, creating separately merchandised accessory demand. Travel retail expansion across Dubai, Singapore, and Frankfurt airports accelerates format adoption.
- Sleeves:Cardboard slipcases serve budget optical chains and promotional eyewear programs where cost minimization overrides protective specifications. Indian organized retail expansion in tier-two cities generates volume demand for standardized sleeve formats.
- Blisters:Thermoformed plastic clamshells persist in mass-market sunglasses distribution through big-box retailers, though regulatory pressure on single-use plastics constrains growth trajectories in European markets.
Boxes anchor the volume base while pouches gain share at the steepest rate.
Material:
Cost tier stratification separates petroleum-derived substrates from fiber alternatives, with premium positioning commanding margin premiums that offset sustainable material premiums.
- Plastic:ABS and polypropylene formulations retain volume leadership in molded tray production, particularly for hinge-reinforced cases requiring dimensional stability. Chinese converter concentration in Zhejiang and Guangdong provinces creates single-source vulnerability for volume brands sourcing mid-tier specifications. California Proposition 65 labeling requirements for metal hinge hardware add compliance friction to US-bound plastic case shipments.
- Paper:Molded pulp engineering and rigid board constructions are capturing margin pools as sustainability-linked procurement criteria harden across European and North American retail channels. Post-consumer pulp quality inconsistency raises technical qualification barriers for premium optical retail applications.
- Metal:Aluminum and tinplate enclosures serve collectible and limited-edition eyewear programs where permanence signals brand equity. REACH SVHC disclosure requirements tighten supply chain documentation burdens for European converters sourcing hinge components through Asian trading networks.
- Glass:Tempered glass display cases and protective vitrines occupy niche applications in museum-quality presentation and archival storage, with negligible volume contribution to commercial packaging flows.
Plastic retains the widest application footprint while paper climbs the fastest on regulatory tailwinds.
End User:
Customer type determines specification complexity, with direct-to-consumer channels fragmenting procurement into SKU-level commitments rather than annual program volumes.
- Retailers:Premium optical chains and fashion house boutiques demand color-matched, logo-embossed cases that extend brand presence through post-purchase use. Italian leather-clad specifications from Gatto Astucci anchor the high-margin accessories segment for European luxury retailers.
- Wholesalers:Volume distributors prioritize standardized case specifications that minimize inventory SKUs while accommodating multiple frame geometries through adjustable interior fittings.
- E-commerce:Direct-to-consumer lens platforms are creating packaging specifications that bypass traditional wholesale formats, with crush-resistant corrugated mailers replacing retail presentation cases. Subscription lens replacement programs in North America and Northern Europe normalize digital purchase cycles that favor utilitarian protection over display aesthetics.
- Manufacturers:Captive packaging operations at integrated eyewear producers maintain quality control across global store networks, with EssilorLuxottica's in-house production exemplifying backward integration into presentation systems.
Retailers command the specification premium tier while e-commerce expands most quickly on channel shift dynamics.
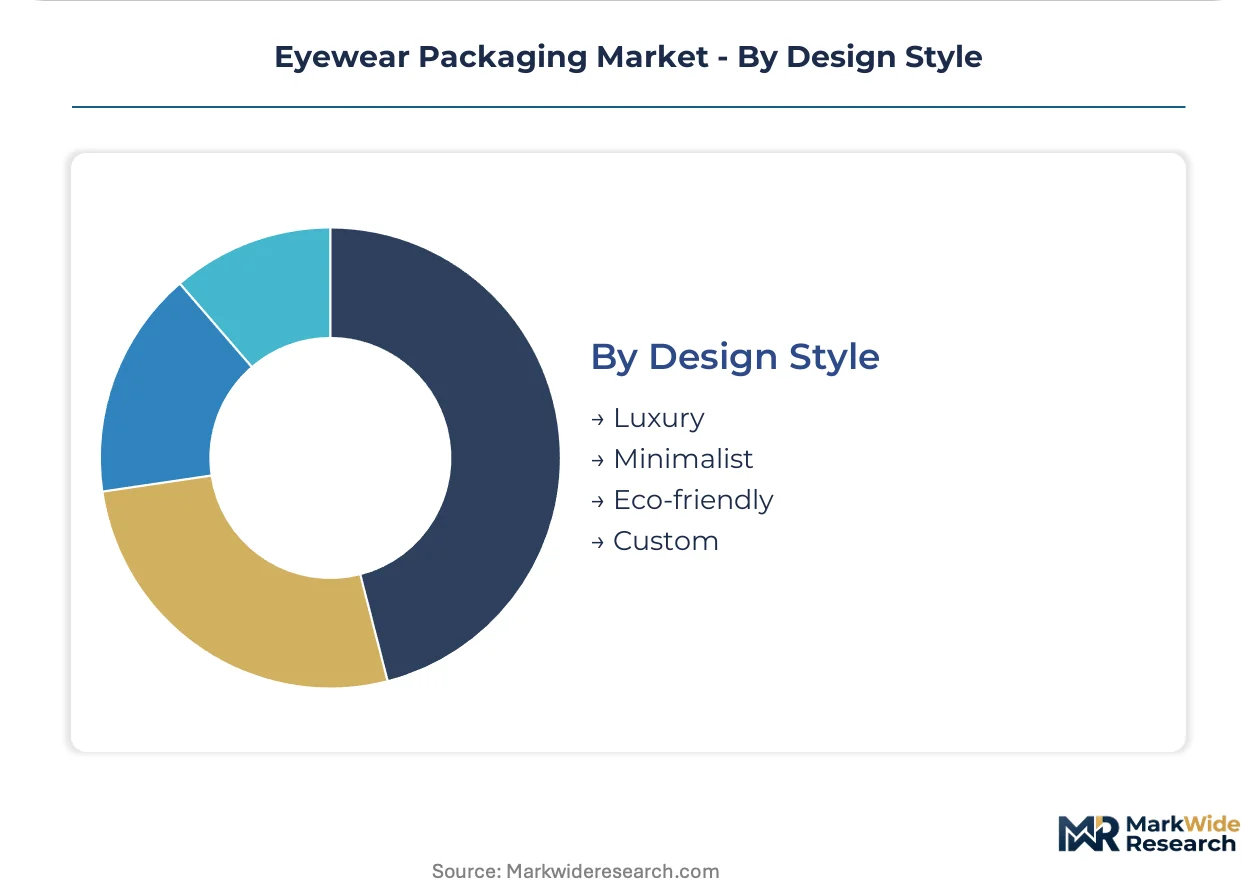
Design Style:
Margin concentration follows design differentiation, with heritage positioning and sustainability signaling commanding price premiums over commodity formats.
- Luxury:Handcrafted Italian leather cases from Giorgio Fedon & Figli leverage heritage positioning to anchor high-margin accessories for European fashion houses. Artisan dye consistency requirements concentrate expertise in Northern Italian tanneries, creating capability scarcity relative to volume competitors.
- Minimalist:Reduced-material specifications featuring raw kraft board and uncoated finishes appeal to Scandinavian and Japanese optical brands where restraint signals sophistication.
- Eco-friendly:Algae-derived biopolymer formulations are decomposing cost barriers between sustainable positioning and margin preservation, with Italian fashion houses piloting these materials for spring collection cases. EU member state recycling offset schemes reward mono-material construction that simplifies end-of-life processing.
- Custom:Bespoke specifications for limited-edition collaborations and influencer partnerships require short-run converter capabilities that fragment procurement relationships and extend lead times.
Luxury commands the highest unit economics while eco-friendly specifications show the steepest expansion trajectory on regulatory compliance and consumer preference convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Belluno province concentrates specialized converter capacity that supplies premium optical packaging across Europe. Converter relationships cluster around EssilorLuxottica's vertically integrated production network. Regulatory divergence between the EU Packaging and Packaging Waste Regulation, US FDA indirect food-contact rules, and India's BIS import standards fragments compliance investment.
Italy
Luxury eyewear manufacturing in the Belluno province generates localized demand for handcrafted leather cases and rigid board constructions. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that converters must meet by 2030. Artisan dye expertise concentrates in Northern Italian tanneries, creating capability scarcity for color-matched luxury specifications.
Germany
Optical retail chains in Munich and Hamburg drive standardized case procurement for prescription eyewear distribution. ECHA REACH SVHC disclosure requirements tighten documentation burdens for metal hinge components sourced through Asian trading networks. Stuttgart-based converters specialize in molded pulp engineering for sustainable tray alternatives.
United States
Direct-to-consumer lens platforms in California and New York fragment procurement into SKU-level specifications rather than annual program volumes. FDA oversight of indirect food-contact substrates constrains formulation choices for brands distributing nationally. Los Angeles and Miami serve as entry points for Asian-manufactured plastic cases facing California Proposition 65 labeling requirements.
China
Mid-tier plastic case production clusters in Zhejiang and Guangdong provinces supply volume brands with ABS and polypropylene formulations. GB standards for packaging recyclability add compliance layers for multinational suppliers accessing domestic distribution. Shenzhen and Wenzhou converters face margin pressure as European buyers shift toward fiber-based alternatives.
India
Organized optical retail expansion in tier-two cities generates volume demand for standardized sleeve and pouch formats. BIS certification for imported paperboard extends product launch timelines for European converters entering the market. Mumbai and Delhi-NCR serve as distribution hubs for both domestic manufacturing and imported premium specifications.
Eyewear Packaging Market Competitive Landscape
Concentration sits with vertically integrated eyewear producers and specialized Italian converters serving luxury fashion houses. The vendor base splits between captive packaging operations at major optical manufacturers and independent converters clustered around Northern Italy. Three archetypes dominate: heritage leather craftsmen, molded pulp engineers, and scale-driven Asian plastic fabricators. Competitive moves center on backward integration into presentation systems and rapid material platform shifts to meet EU recycled content deadlines.
Among Italy-based specialists, Gatto Astucci Spa and Giorgio Fedon & Figli Spa exemplify the heritage craftsmanship archetype through their positioning in handcrafted leather cases for European fashion houses. KLING GMBH represents German precision engineering in molded structural packaging. These three occupy positions that anchor the premium tier against volume-oriented competition from Asian manufacturing clusters.
| Leading Market Players |
|---|
| Classic Packaging |
| MARBER S.R.L. |
| KLING GMBH |
| Hoya |
| Silhouette |
| Packman Packaging Private Limited |
| Gatto Astucci Spa |
| EssilorLuxottica SA |
| Giorgio Fedon & Figli Spa |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day recycled fiber qualification cycles compress procurement windows while concentrating pricing power with Italian converters serving Belluno's vertically integrated eyewear manufacturers. This lead-time compression reinforces cost premiums for artisan leather specifications against commoditized Asian plastic alternatives.
Pricing Analysis
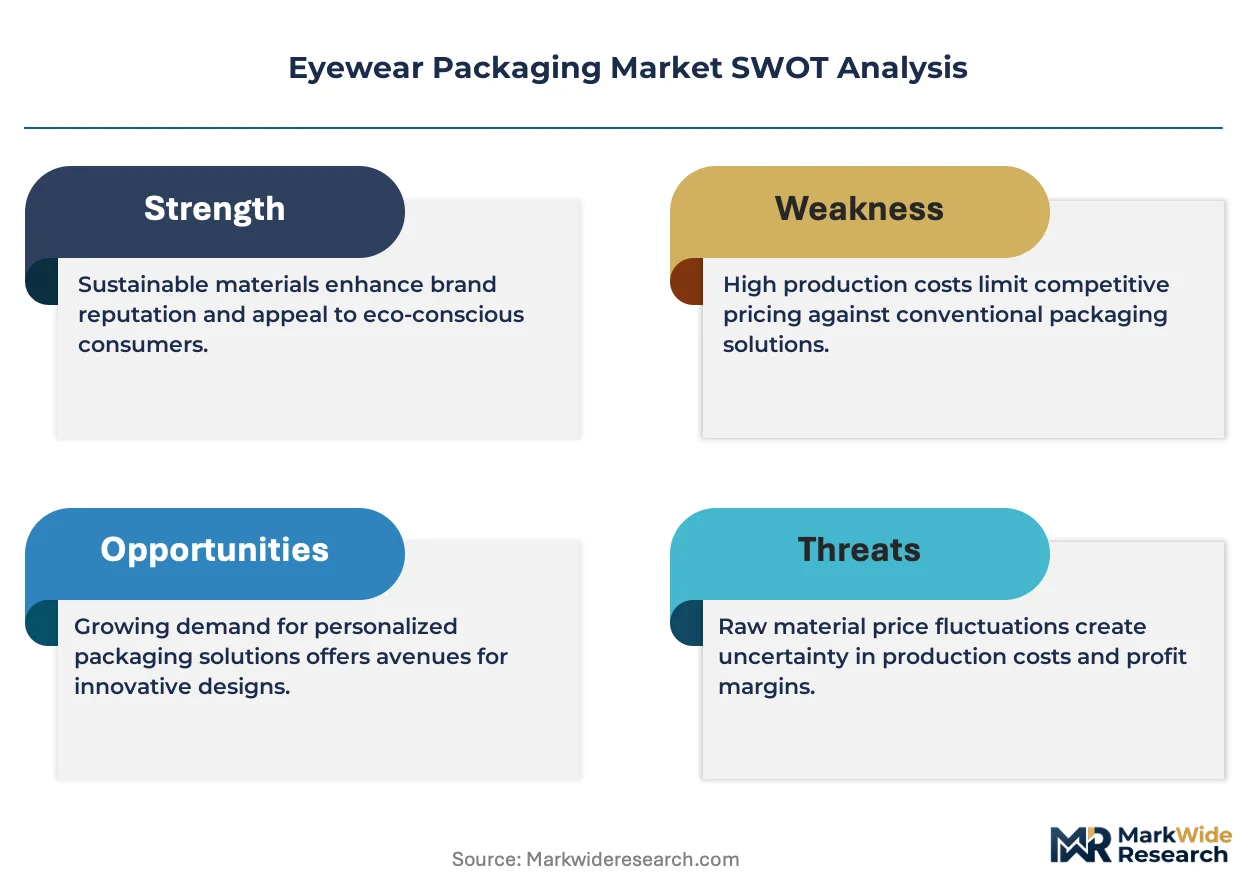
The EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across the eyewear packaging value chain. Three-tier pricing separates heritage Italian leather craftsmen from molded pulp engineers and volume Asian plastic fabricators. Price differentiation rests on certification grade and customization level, with REACH SVHC-compliant specifications commanding premiums over standard formats. Cost compression in mid-tier plastic cases is intensifying because Chinese converter concentration creates bidding pressure among Zhejiang and Guangdong suppliers. Mass-market volume buyers exhibit highest price sensitivity, while European luxury fashion houses absorb artisan premiums for color-matched leather specifications.
Supply Chain Analysis
Strategic stockpile preferences dominate among premium optical retailers buffering against Northern Italian tannery dye-batch variability, while just-in-time procurement governs standardized pouch formats for travel retail. Geographic supply concentrates in Italy, China, and India. Raw material dependencies center on post-consumer pulp, ABS polypropylene resin, and vegetable-tanned leather hides. Single-source vulnerability runs through Zhejiang province's molded case clusters. Distribution runs through captive converter relationships at EssilorLuxottica, independent Italian specialists, and Asian volume fabricators serving wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Eyewear packaging demand follows optical retail inventory cycles, with recovery signals emerging from prescription lens e-commerce platform expansion across North America and Northern Europe.
For Market Incumbents: Secure backward integration into algae-derived biopolymer R&D to preempt regulatory substitution mandates. Consolidate supplier panels for metal hinge components to reduce REACH SVHC audit complexity. Captive production of molded pulp alternatives defends margin position against fiber-based conversion deadlines.
For New Entrants and Emerging Players: BIS certification fast-track for imported paperboard opens tier-two Indian optical retail expansion. Target underpenetrated organized retail in Mumbai and Delhi-NCR satellite cities with standardized sleeve formats. Direct-to-consumer lens platform partnerships bypass entrenched wholesale distributor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EU recycled content thresholds and extended producer responsibility frameworks reshape material economics. Acquisition targets cluster at Italian molded pulp engineering specialists and algae-biopolymer pilot-scale converters. Monitor EU member state recycling offset scheme implementation as inflection indicator for mono-material construction demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer R&D | Algae-derived formulations decompose cost barriers between sustainable positioning and margin preservation for Italian fashion houses. |
| Supplier Panel Consolidation | Reduced chemical inventory audit complexity addresses REACH SVHC disclosure tightening for metal hinge components sourced through Asian networks. |
| Direct-to-Consumer Packaging Development | Crush-resistant corrugated mailers bypass traditional wholesale formats for California and New York lens platform fulfillment. |
| Indian Market Certification Investment | BIS paperboard clearance capability captures tier-two city optical retail expansion in Mumbai and Delhi-NCR distribution hubs. |
| Mono-Material Construction Pivot | EU member state recycling offset eligibility simplifies end-of-life processing and qualifies converters for sustainability-linked procurement criteria. |
Research Methodology
Operator-level perspectives from packaging procurement managers at optical retailers, converter operations directors in Northern Italy, leather tannery artisans, and regulatory compliance officers anchored the qualitative base. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, ECHA REACH SVHC candidate list updates, BIS certification databases, and Italian industrial cluster trade data. Bottom-up volume modeling triangulated against top-down value projections across the analysis window.
Sensitivity analysis tested recycled fiber input cost trajectories and regulatory compliance timeline scenarios throughout the forecast period. Segmentation dimensions modeled include packaging type, material substrate, end-user channel, and design style tier. CAGRs were derived from fitted growth curves calibrated to channel shift dynamics and substitution elasticity parameters. Industry-specific inputs incorporated EU Green Deal mandate implementation schedules and foldable frame engineering adoption curves.
Underlying assumptions cover regulatory compliance deadlines, raw material quality consistency, and channel migration patterns, with deviation risk concentrated in post-consumer pulp rejection rate volatility and multi-jurisdiction certification timeline extensions. Practitioners should keep alternative scenarios live as EU member state recycling offset scheme designs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Packing Boxes Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Inverted Squeeze Bottle Market
Packaging Containers
Food Grade Bottles Market
Packaging Containers
Correx Trays Market
Packaging Containers
Euro Box Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
Portion Packs Market
Packaging Containers
Logistics Packaging Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Foldable Mailer Box Market