
 Eye Health Ingredients Market | 2026-2036
Eye Health Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Health Ingredients Market Analysis
China's Zhejiang province is narrowing its carotenoid supply gap through expanded fermentation capacity for astaxanthin and lutein. Kemin Industries leverages vertically integrated marigold extraction from seed to finished extract across India and the United States. DSM Nutritional Products sustains synthetic vitamin A leadership through backward integration into citral chemistry at its Swiss manufacturing complex. OmniActive Health Technologies specializes in clinically validated lutein isomers for supplement and beverage applications.
Eye health ingredients comprise bioactive compounds including carotenoids, omega fatty acids, vitamins, and antioxidants formulated to support retinal function, macular pigment density, and ocular surface integrity. Lutein and zeaxanthin accumulate in the macula at 0.3-1.0 micromolar concentrations, filtering blue light and quenching reactive oxygen species. Carotenoids dominate current value pools due to extraction complexity and clinical substantiation requirements, while omega fatty acids represent the fastest-growing category as DHA integration into infant nutrition and dry eye therapeutics expands. Nutritional supplements anchor volume demand, though functional beverages incorporating liquid delivery formats are gaining shelf space in pharmacy and convenience channels.
FDA GRAS notifications and EFSA health claims authorization shape ingredient marketability in the United States and European Union respectively, with Japan's Consumer Affairs Agency adding FOSHU oversight for functional eye health products. China's NMPA and SAMR enforce dual-use food-drug boundaries that restrict certain carotenoid dosage claims. Stakeholders must monitor evolving substantiation thresholds across FDA, EFSA, and Japan's regulatory frameworks to align clinical investment with permissible marketing language.
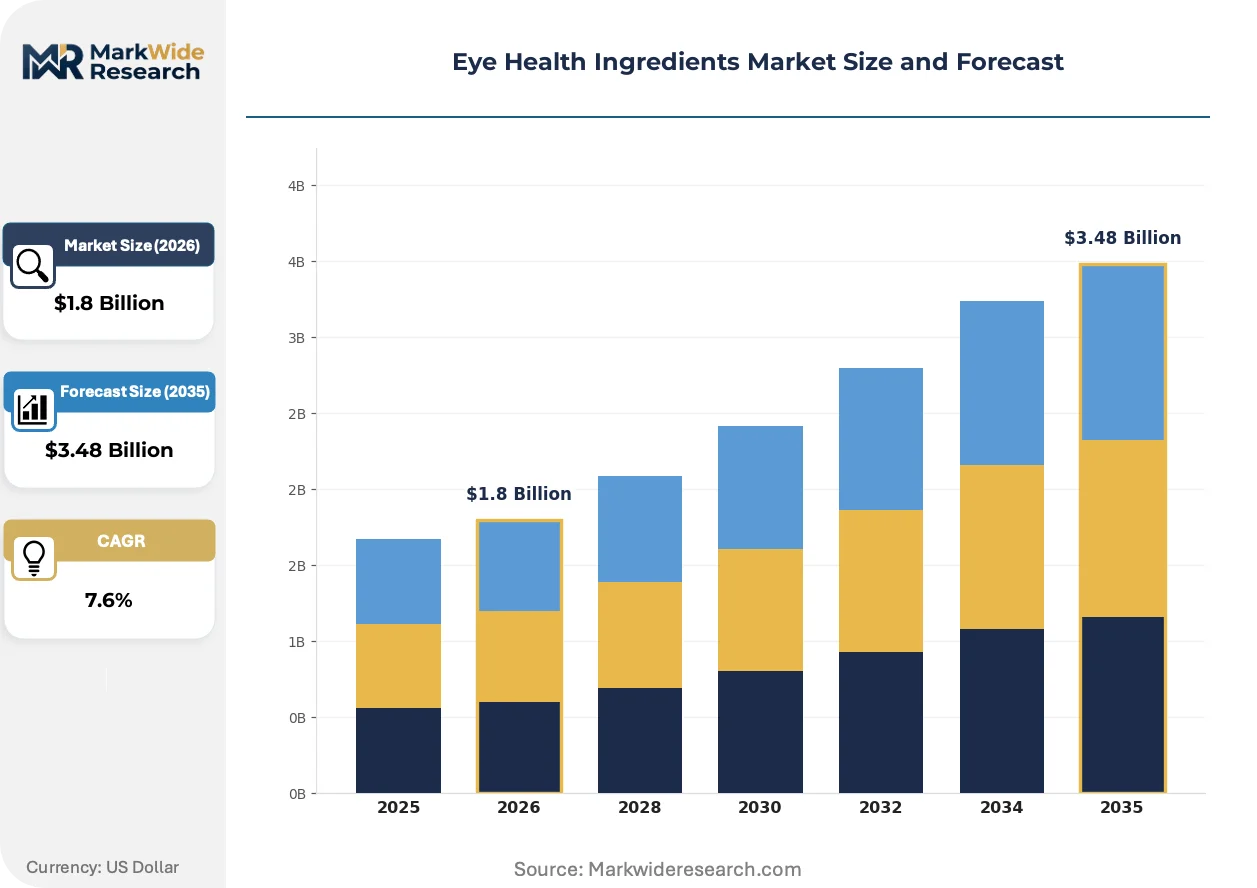
Market Dynamics
Carotenoid extraction from marigold flowers is displacing petrochemical synthesis as the dominant production pathway, tightening supply chains around vertically integrated agricultural processors and reshaping cost structures across lutein and zeaxanthin concentrates.
Growth Catalysts
- Japan's METI functional food claims:The Consumer Affairs Agency's FOSHU oversight framework accelerates eye health product penetration through convenience retail channels, validating clinical substantiation investments.
- Blue light filtering demand:Digital screen exposure drives lutein and zeaxanthin formulation into beverage and supplement applications targeting retinal protection.
- EFSA novel food guidelines:Tightened authorization standards in Germany elevate barrier-to-entry for new entrants while securing premium positioning for compliant concentrate suppliers.
Market Restraints
- Marigold agricultural concentration:Raw material sourcing clusters in specific growing regions, exposing processors to climate volatility and seasonal price swings.
- China's dual-use food-drug boundaries:NMPA and SAMR enforcement restricts carotenoid dosage claims, compressing permissible marketing language for imported formulations.
- Fermentation capacity limitations:Microbial astaxanthin production requires specialized bioreactor infrastructure that remains concentrated among limited contract manufacturers.
Strategic Opportunities
- Dry eye therapeutics expansion:Omega-3 DHA integration into prescription and over-the-counter ocular surface treatments opens pharmaceutical-grade ingredient demand.
- Liquid delivery format innovation:Functional beverages incorporating carotenoid emulsions capture pharmacy and convenience channel shelf space previously dominated by capsules.
- India's contract manufacturing emergence:Seed-to-extract vertical integration capabilities attract Western brand owners seeking supply chain redundancy.
Industry Challenges
- Clinical substantiation timelines:EFSA health claims authorization requires multi-year intervention studies, delaying product launch schedules and freezing R&D capital.
- Carotenoid stability formulation:Oxidation-sensitive molecules demand sophisticated encapsulation technologies that extend development cycles and raise per-unit production costs.
- Cross-regulatory compliance fragmentation:Divergent FDA GRAS notification and EFSA novel food requirements force parallel documentation investments for multi-market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Health Ingredients Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Carotenoids, Omega Fatty Acids, Antioxidants Application: Nutritional Supplements, Functional Foods, Beverages, Cosmetics End User: Consumers, Healthcare Professionals, Pharmacies, Manufacturers Delivery Format: Capsules, Tablets, Powders, Liquids |
| Companies Covered | Kemin Industries, OmniActive Health Technologies, BASF SE, AIDP Inc., Allied Biotech Corporation, DSM Nutritional Products, Archer Daniels Midland Company, BI Nutraceuticals, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Health Ingredients Market Emerging Trajectories
Fermentation-based carotenoid production and advanced encapsulation technologies are compressing traditional extraction economics while regulatory frameworks on both sides of the Atlantic tighten substantiation requirements for eye health positioning.
Microbial fermentation for astaxanthin and lutein is collapsing the cost premium between algal and petrochemical-derived carotenoids. Contract manufacturers in Zhejiang province are scaling bioreactor capacity to serve European dietary supplement formulators. This technology is collapsing the historical price floor that protected marigold extraction margins.
EFSA's tightened novel food guidelines are extending authorization timelines for non-traditional carotenoid sources. German ingredient importers now demand comprehensive toxicology dossiers before contract execution. Concentrate suppliers are responding by consolidating clinical investment around marigold-derived matrices with established safety profiles.
Japanese convenience retail channels are absorbing functional eye health beverages at the expense of traditional pharmacy distribution. METI-approved FOSHU claims enable on-pack positioning that compressed consumer education requirements. This channel rotation is most visible in Tokyo and Osaka metropolitan areas where aging demographics concentrate purchasing power.
Eye Health Ingredients Market Segmentation
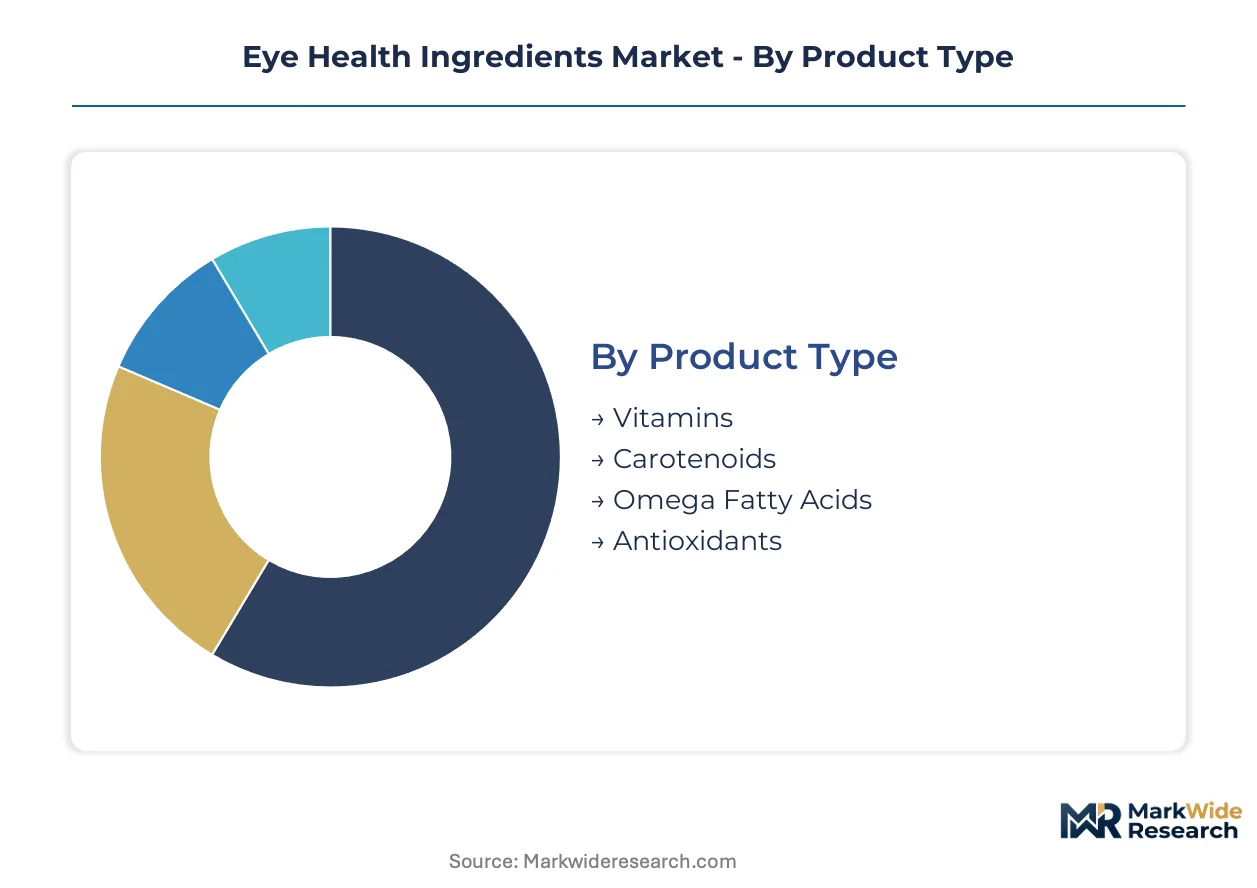
Ingredient positioning in eye health markets hinges on matching molecular stability requirements to channel-specific formulation constraints. Carotenoid oxidation profiles and omega fatty acid emulsion compatibility drive divergent margin structures across delivery formats.
Product Type:
After-sales technical support intensity concentrates around carotenoid concentrates where EFSA novel food dossier maintenance and stability troubleshooting demand dedicated account engineering.
- Carotenoids:Lutein and zeaxanthin concentrates extracted from marigold flowers or fermented biomass accumulate in retinal macula at micromolar concentrations. German dietary supplement manufacturers now source these under tightened EFSA guidelines, while Zhejiang province scales fermentation capacity to narrow supply gaps.
- Omega Fatty Acids:DHA and EPA formulations target dry eye therapeutics and infant nutrition applications with pharmaceutical-grade purity requirements. Japan's METI functional food claims accelerate integration into convenience retail beverages, outpacing traditional supplement channels.
- Vitamins:Synthetic vitamin A and E derivatives dominate cost-sensitive mass-market formulations.
- Antioxidants:Polyphenol and flavonoid extracts from berry and botanical sources serve premium positioning segments.
By volume, carotenoids lead. By growth pace, omega fatty acids are ahead.
Application:
Cost tier stratification separates pharmaceutical-grade ocular therapeutics from mass-market functional foods, with beverage applications commanding premium emulsion technology investments.
- Nutritional Supplements:Capsule and tablet formats anchor volume demand through pharmacy and e-commerce channels, with lutein-zeaxanthin combinations dominating shelf space. Clinical substantiation investments by concentrate suppliers secure premium positioning against commodity vitamin competitors.
- Beverages:Liquid carotenoid emulsions capture convenience retail shelf space in Japan's Tokyo and Osaka metropolitan areas, where METI-approved FOSHU claims compress consumer education requirements. Oxidation-sensitive formulations demand sophisticated encapsulation that extends development cycles.
- Functional Foods:Fortified dairy and bakery applications serve aging demographic segments in Germany and Japan.
- Cosmetics:Topical eye serums incorporate antioxidant carotenoids for periorbital anti-aging claims.
Supplements generate the highest absolute volumes. Beverages are climbing the fastest as channel rotation accelerates.
End User:
Customer type determines specification stringency, with healthcare professionals and pharmacies demanding batch-level certificates of analysis that consumer channels rarely require.
- Consumers:Direct-to-purchaser sales through e-commerce and convenience retail dominate volume, particularly in Japan where aging demographics concentrate purchasing power. Self-directed purchasing favors on-pack FOSHU claims and recognizable carotenoid branding over complex clinical data.
- Healthcare Professionals:Ophthalmologists and optometrists prescribe pharmaceutical-grade omega-3 formulations for dry eye syndrome, requiring documentation of EPA/DHA ratios and oxidation markers. This channel sustains premium pricing for prescription and medical-grade ingredients.
- Pharmacies:Professional counseling environments bridge consumer self-selection and clinical recommendation.
- Manufacturers:Contract formulators and finished goods producers source concentrates under long-term supply agreements with stability guarantees.
Consumers account for the largest volume flows. Healthcare professionals are gaining share fastest as dry eye therapeutics expand.
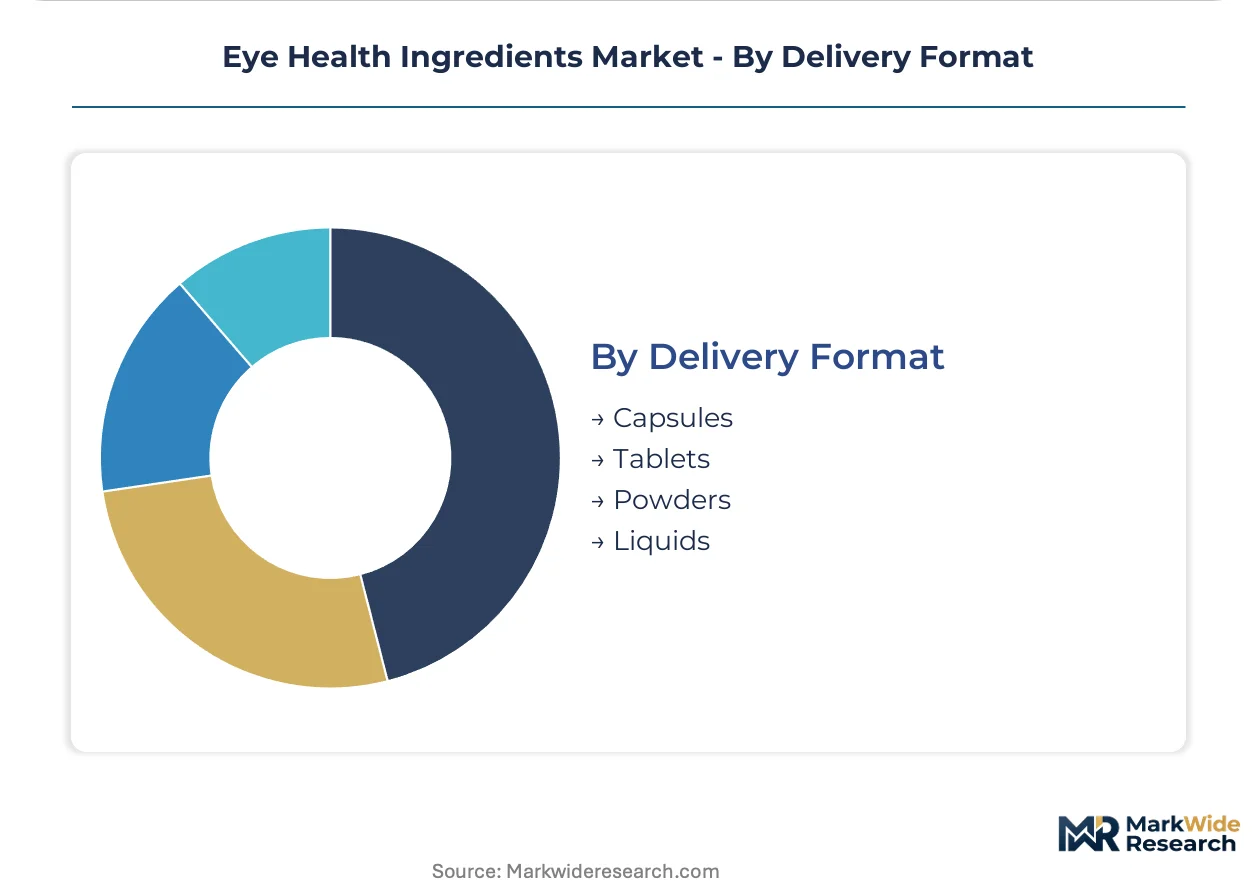
Delivery Format:
Supply concentration in liquid emulsion technology creates margin differentiation, with bioreactor-derived carotenoid suspensions commanding premium positioning against powder alternatives.
- Liquids:Carotenoid and omega fatty acid emulsions enable functional beverage applications and pediatric formulations where swallowing constraints limit solid doses. Japanese convenience retail channels absorb these formats at the expense of traditional pharmacy distribution.
- Capsules:Softgel and hardshell formats dominate carotenoid stabilization, with gelatin and plant-based shells differentiated by clean-label positioning. Marigold-derived lutein concentrates fill the majority of volume here.
- Tablets:Compressed powder formats serve cost-sensitive vitamin and mineral combinations.
- Powders:Bulk concentrates supply contract manufacturers and food fortification applications.
Capsules lead by volume. Liquids are expanding most quickly as beverage applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marigold cultivation clusters in India and China concentrate lutein-zeaxanthin extraction capacity, while Japanese functional food regulations and German novel food standards reshape demand geography across three continents.
United States
FDA GRAS notifications govern carotenoid and omega fatty acid formulation approvals for supplement and beverage applications. The agency's notification pathway enables rapid market entry for established safety profiles. Iowa and Illinois agricultural processors supply marigold oleoresin to domestic extractors while California formulators pioneer liquid delivery innovations.
Germany
EFSA novel food guidelines tightened authorization standards for non-traditional carotenoid sources entering dietary supplement channels. The Federal Office of Consumer Protection and Food Safety enforces toxicology dossier requirements that elevate barrier-to-entry. Bavarian ingredient importers now demand comprehensive safety documentation before contract execution with concentrate suppliers.
Japan
METI functional food claims approval accelerates eye health product penetration through convenience retail channels in Tokyo and Osaka metropolitan areas. The Consumer Affairs Agency's FOSHU oversight framework validates clinical substantiation investments. Aging demographics concentrate purchasing power in urban centers where beverage applications displace traditional pharmacy distribution.
China
NMPA and SAMR enforce dual-use food-drug boundaries that restrict carotenoid dosage claims for imported formulations. Zhejiang province contract manufacturers scale fermentation capacity for microbial astaxanthin and lutein production. This bioreactor expansion narrows supply gaps previously filled by marigold-derived concentrates.
India
FSSAI standards govern carotenoid concentrate imports while domestic seed-to-extract vertical integration attracts Western brand owners seeking supply chain redundancy. Karnataka and Tamil Nadu agricultural belts host marigold cultivation clusters feeding integrated extraction facilities. Contract manufacturers in these states leverage backward integration into seed genetics and oleoresin processing.
Eye Health Ingredients Market Vendor Landscape
Vertically integrated agricultural processors and specialized health technology developers split the market between captive supply security and clinical validation depth. The structure favors players with multi-year EFSA dossier investments or seed-to-extract control over marigold supply chains. Three archetypes dominate: plantation-integrated extractors, fermentation-based biotech specialists, and synthetic chemistry incumbents. Competitive moves concentrate on geographic capacity expansion and regulatory dossier consolidation rather than price warfare.
Among plantation-integrated extractors, Kemin Industries exemplifies backward integration from seed genetics through finished oleoresin, while OmniActive Health Technologies occupies a position emphasizing clinically validated isomer specifications. DSM Nutritional Products anchors the synthetic chemistry tier with citral-based vitamin A production. These three represent divergent strategic bets on natural extraction versus fermentation versus petrochemical synthesis pathways.
| Leading Market Players |
|---|
| Kemin Industries |
| OmniActive Health Technologies |
| BASF SE |
| AIDP Inc. |
| Allied Biotech Corporation |
| DSM Nutritional Products |
| Archer Daniels Midland Company |
| BI Nutraceuticals |
| Lonza Group |
| Others |
Supply Flow & Price Mechanics
Marigold agricultural concentration in Karnataka and Tamil Nadu exposes processors to monsoon volatility, compressing both premium-to-economy tier spreads and forcing geographic diversification across seed-to-extract networks. This climate dependency reshapes procurement strategies as buyers seek supply chain redundancy against seasonal price swings.
Pricing Analysis
EFSA novel food guidelines dictate the pricing tier structure across European dietary supplement channels. Three-tier pricing separates pharmaceutical-grade carotenoid concentrates from food-grade emulsions and feed-grade oleoresins. Certification tier and volume scale differentiate premiums, with clinical dossier maintenance commanding the widest spreads. Cost compression in standard-grade lutein intensifies as Zhejiang fermentation capacity scales. Healthcare professionals show the least price sensitivity due to prescription-grade purity requirements.
Supply Chain Analysis
Contract manufacturers in Zhejiang province and integrated processors in Karnataka hold the dominant extraction and fermentation capacity. Raw material supply draws from marigold cultivation clusters in India, petrochemical citral streams in Switzerland, and algal biomass in China. Single-source vulnerability concentrates around monsoon-dependent marigold harvests. Distribution runs through long-term offtake agreements with Western dietary supplement formulators and Japanese functional beverage producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
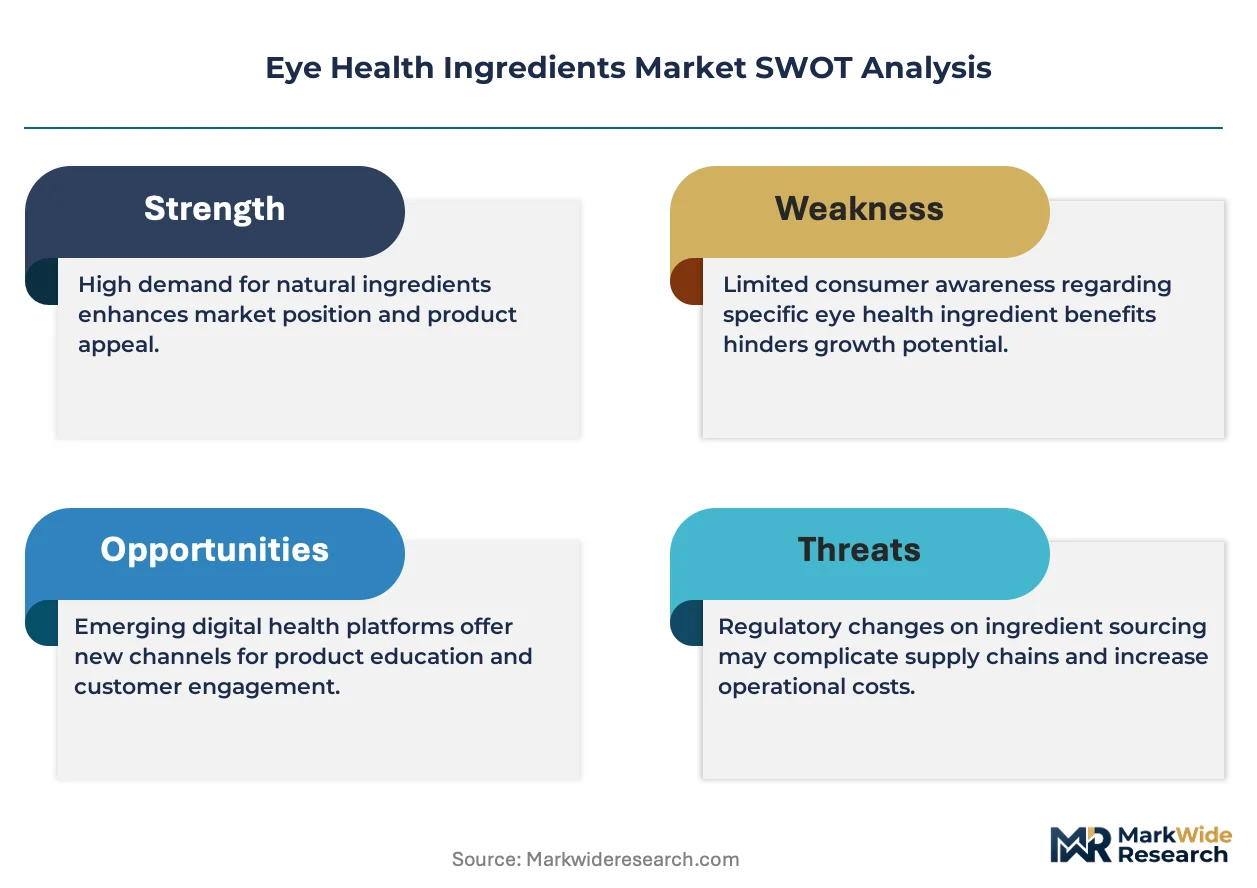
The Eye Health Ingredients Market functions as a regulatory-moat business where EFSA dossier entrenchment creates switching costs that freeze out commodity competitors. Network effects concentrate among suppliers with validated clinical substantiation libraries.
For Market Incumbents: Build regulatory dossier depth as the primary moat. Consolidate EFSA novel food authorization libraries to raise entry barriers against fermentation-based challengers from Zhejiang. Add capacity in Tamil Nadu seed processing to capture climate-hedging premiums from risk-averse Western brand owners. For New Entrants and Emerging Players: Japanese convenience retail channels in Osaka and Tokyo represent the most penetrable entry point for liquid carotenoid emulsions with METI-approved FOSHU positioning. Bypass EFSA authorization timelines by targeting US FDA GRAS notification pathways first. Partner with established encapsulation technology providers to solve oxidation stability without captive R&D investment. For Investors and Strategic Acquirers: EFSA's tightened toxicology requirements reshape the acquisition landscape toward targets with pre-validated marigold-derived safety profiles. Five-to-ten year viability favors plantation-integrated extractors over synthetic chemistry incumbents facing feedstock volatility. Watch Zhejiang fermentation cost curves as the inflection signal for natural extraction margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Consolidation | Multi-year toxicology investments secure premium positioning against unvalidated fermentation entrants in German channels. |
| Seed-to-Extract Vertical Integration | Captive marigold genetics and oleoresin processing in Karnataka insulate margins from climate-driven raw material volatility. |
| Liquid Emulsion Format Expansion | Functional beverage applications capture Tokyo convenience retail shelf space previously dominated by capsule formats. |
| Fermentation Capacity Scale-Up | Bioreactor expansion in Zhejiang collapses cost premiums between algal and petrochemical-derived carotenoid sources. |
| Clinical Substantiation Partnerships | Ophthalmology research collaborations validate lutein-zeaxanthin isomer specifications for healthcare professional channel access. |
Methodological Framework
Initial hypotheses were tested against primary input from dietary supplement formulators, regulatory affairs specialists at concentrate suppliers, ophthalmology clinicians, and pharmacy category buyers, then refined through secondary validation against EFSA novel food registers, FDA GRAS notification databases, METI FOSHU approval listings, and customs trade flows for marigold oleoresin. Bottom-up volume estimates from extraction capacity and top-down demand triangulation from end-use consumption patterns were cross-referenced.
Demand-supply balance modeling across the projection horizon incorporated ingredient type segmentation by molecular stability profile, application tier by channel regulatory stringency, and delivery format by encapsulation technology requirements. CAGRs were derived from elasticity-adjusted penetration curves and per-capita consumption benchmarks. Forecast inputs included aging demographic trajectories in Japan, EFSA authorization pipeline velocity, and fermentation yield improvement curves from Zhejiang contract manufacturers.
Practitioners should monitor EFSA novel food authorization timelines, monsoon patterns in South Indian marigold belts, and Zhejiang bioreactor utilization rates for early signals of forecast revision. Quarterly review of METI FOSHU approval velocity and German import customs data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Native Collagen Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Micro-Ecological Regulators Market
Nutraceuticals
US and China Glucose Market
Nutraceuticals
Cordyceps Sinensis and Militaris Market
Nutraceuticals
Tetrahydropalmatine Market
Nutraceuticals
Nootropics Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
US Collagen Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Coenzyme Q10 Market
Nutraceuticals
Global Synbiotics Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
Pet Nutraceuticals Market