
 South America Pet Nutraceuticals Market | 2026-2036
South America Pet Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
South America Pet Nutraceuticals Market Insights
ANVISA's pet supplement registration pathway is unwinding competitive access across Brazil and Argentina, forcing reformulation cycles on imported portfolios. Mars Incorporated leverages its veterinary channel partnerships to sustain shelf presence in Brazilian pet specialty retail. Nestlé Purina PetCare anchors its position through direct-to-veterinarian distribution networks in São Paulo and Buenos Aires. Virbac competes by specializing in condition-specific formulations targeting joint and dermatological health segments.
Pet nutraceuticals comprise bioactive compounds including vitamins, minerals, herbs, and probiotics delivered in pills, powders, chews, or liquid matrices, formulated to support physiological functions beyond basic nutrition in companion animals. Manufacturing employs cold-press tableting and microencapsulation to preserve probiotic viability through gastric transit. Probiotics and vitamins lead product type revenue due to veterinary endorsement and repeat purchase frequency, while chews command margin premiums through palatability-driven compliance. E-commerce distribution channels represent the fastest-growing access point, displacing traditional retail store dependence among urban pet owners.
ANVISA in Brazil and SENASA in Argentina govern ingredient safety thresholds and import clearance protocols for pet nutraceuticals, with MAPA overseeing feed-grade additive classifications that constrain cross-category marketing claims. These frameworks elevate compliance costs for multinational entrants while creating protected terrain for domestically certified manufacturers. Stakeholders must monitor pending harmonization between Mercosur veterinary product standards and national registration timelines to anticipate portfolio rebalancing requirements.
Market Dynamics
ANVISA's pet supplement registration pathway is compressing competitive access timelines, forcing multinational portfolios through reformulation cycles while veterinary clinics in São Paulo and Buenos Aires expand dispensing services.
Growth Catalysts
- Veterinary channel expansion:Brazilian and Argentine clinics now stock condition-specific formulations, converting professional endorsement into repeat purchase loyalty.
- MAPA fortification mandates:Brazil's tightening ingredient disclosure requirements favor certified domestic manufacturers with established compliance infrastructure.
- Microencapsulation advances:Cold-press tableting technologies preserve probiotic viability through gastric transit, unlocking veterinary-grade efficacy claims.
Market Restraints
- Import clearance friction:ANVISA and SENASA protocols elevate compliance costs for cross-border entrants, protecting incumbent domestic suppliers.
- Active ingredient concentration:Regional supply of pharmaceutical-grade prebiotics concentrates in southern Brazil, creating input vulnerability.
- Cross-category claim constraints:MAPA's feed-grade additive classifications prevent nutritional supplement marketers from leveraging therapeutic positioning.
Strategic Opportunities
- E-commerce channel acceleration:Urban pet owners in Rio de Janeiro and Santiago de Chile bypass traditional retail, opening direct-to-consumer formulation customization.
- Mercosur harmonization:Pending veterinary product standard alignment would streamline multi-country portfolio deployment across Argentina, Brazil, Paraguay, and Uruguay.
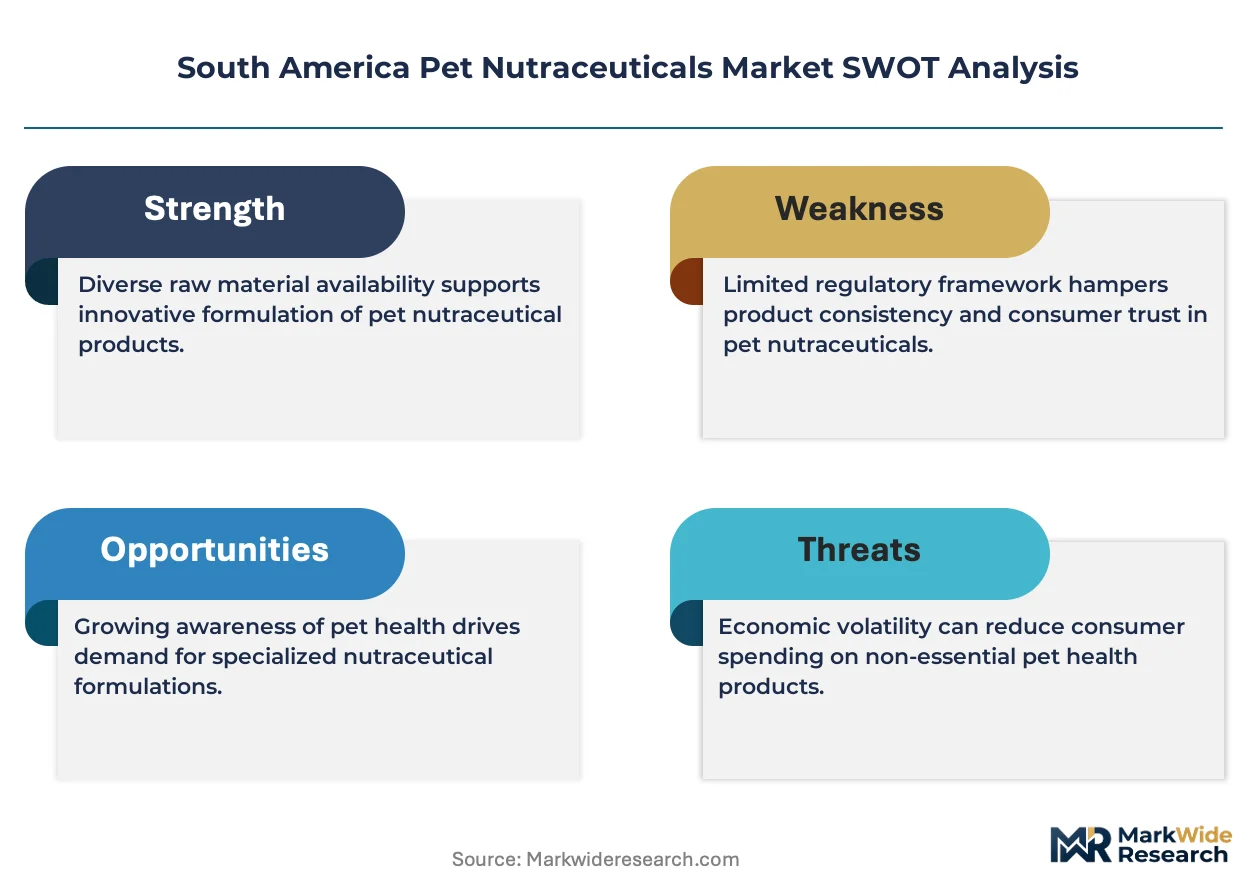
- Condition-specific segmentation:Joint health and dermatological applications remain underdeveloped relative to gastrointestinal and immune positioning.
Industry Challenges
- Registration timeline compression:ANVISA's evolving documentation requirements strain regulatory affairs capacity at importer organizations.
- Veterinary salesforce scaling:Direct-to-clinic distribution networks in Buenos Aires and São Paulo demand specialized technical representatives with clinical nutrition credentials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Pet Nutraceuticals Market |
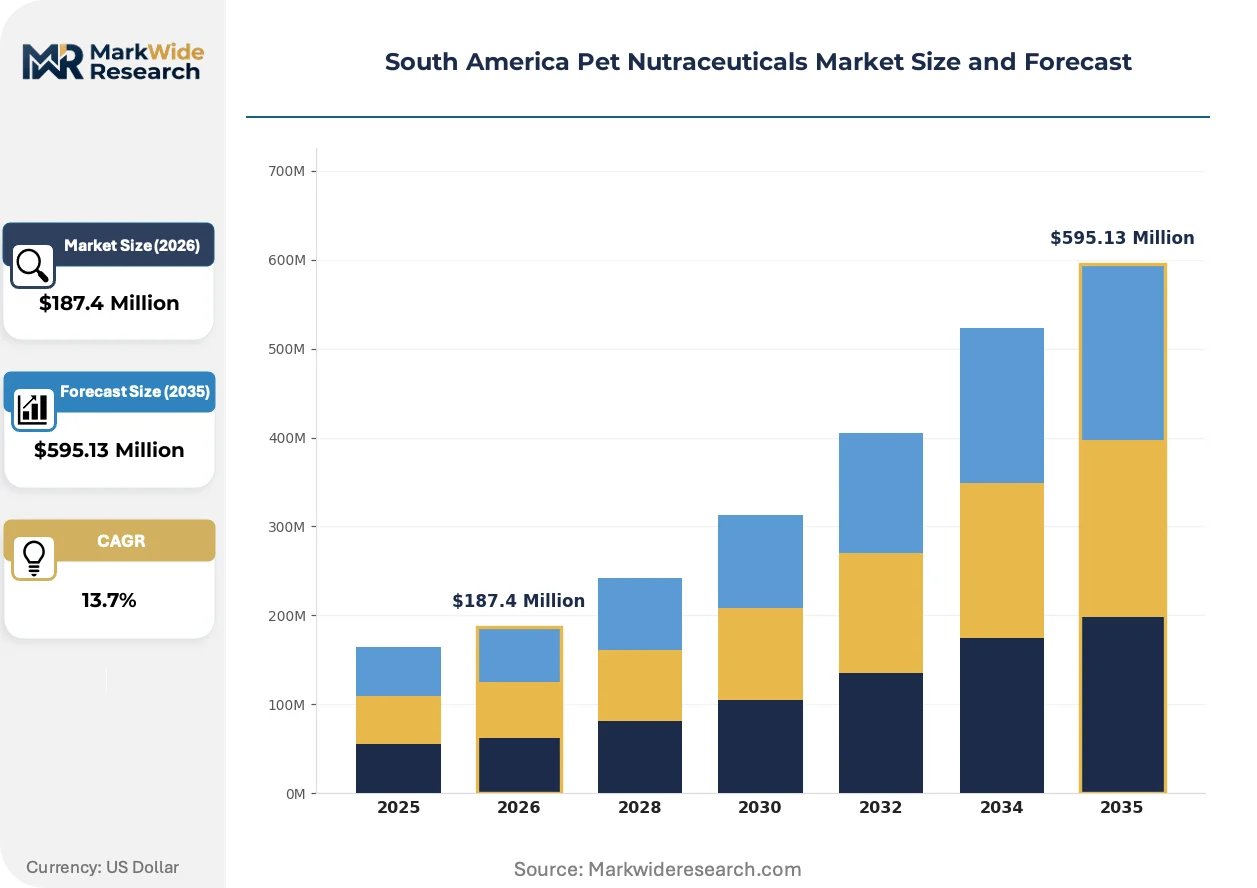
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $595.13 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbs, Probiotics End User: Pet Owners, Veterinary Clinics, Pet Stores, Online Retailers Form: Pills, Powders, Chews, Liquid Distribution Channel: Direct Sales, E-commerce, Retail Stores, Distributors |
| Companies Covered | ADM, Alltech, Mars Incorporated, Nestlé Purina PetCare, Vetoquinol, Virbac, Dechra Pharmaceuticals, Nutramax Laboratories, Kemin Industries, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Pet Nutraceuticals Market Trends and Innovations
Formulation science and channel architecture are reshaping how bioactive compounds reach companion animals across South American metropolitan corridors.
Microencapsulation technology is fragmenting competitive positioning in the probiotics segment. São Paulo-based veterinary clinics now specify enteric-coated formulations as standard of care for gastric-sensitive patients. This capability gap separates domestic manufacturers with in-house spray-drying capacity from import-reliant competitors.
ANVISA's 2023 pet supplement registration pathway revision is elevating documentation requirements for imported products. Foreign manufacturers now face extended review timelines for novel ingredient submissions. Brazilian domestic producers with pre-established ingredient master files capture shelf space in specialty retail chains.
Subscription-based replenishment models are capturing urban pet owner loyalty in Rio de Janeiro and Santiago. Automated delivery platforms displace periodic veterinary clinic visits for routine supplement purchases. This channel shift concentrates customer lifetime value metrics with platform operators rather than formulation brands.
South America Pet Nutraceuticals Market Segmentation
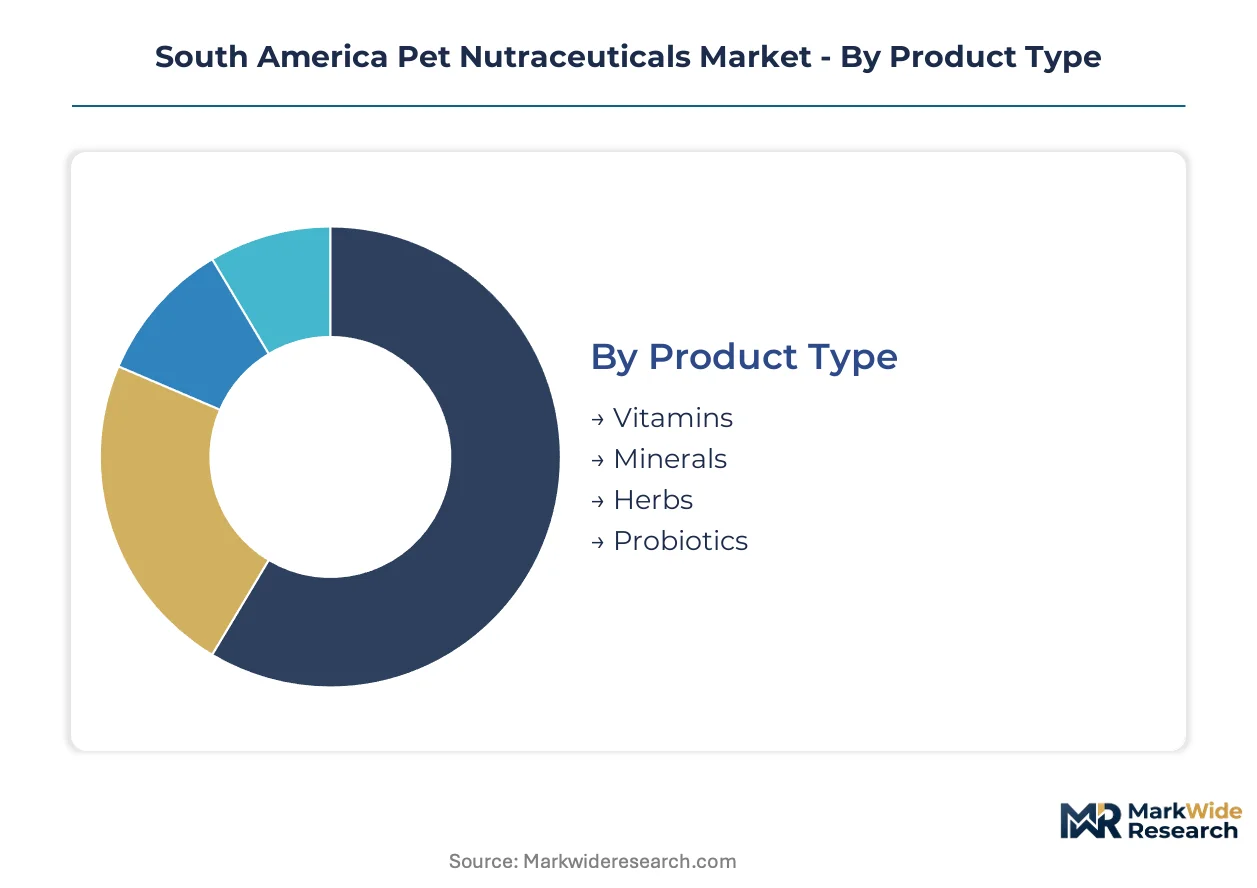
Segmentation in South America pet nutraceuticals reflects regulatory fragmentation across ANVISA and SENASA jurisdictions, where product classification determines registration pathway, distribution eligibility, and permissible health claims. Understanding these divides enables portfolio architects to align formulation investments with accessible channels and compliant positioning.
Product Type:
ANVISA's ingredient master file requirements create divergent competitive access between domestically certified bioactives and import-dependent novel compounds, concentrating manufacturing investment in São Paulo's pharmaceutical corridor.
- Probiotics:Live microbial cultures delivered through microencapsulated matrices preserve viability through gastric transit. São Paulo veterinary clinics specify enteric-coated formulations as standard of care for gastric-sensitive patients, with MAPA's feed-grade additive classifications constraining therapeutic marketing claims. Established volume favors probiotics; emerging adoption favors condition-specific mineral complexes.
- Vitamins:Synthetic and natural fat-soluble and water-soluble compounds formulated to correct deficiencies or support metabolic function. Repeat purchase frequency concentrates in Rio de Janeiro's urban pet owner base, where subscription replenishment models displace periodic clinic visits. Established volume favors vitamins; emerging adoption favors herbal adaptogens.
- Minerals:Chelated and inorganic elemental supplements addressing skeletal, enzymatic, and electrolyte functions.
- Herbs:Botanical extracts including glucosamine sources, omega fatty acid carriers, and calming agents subject to SENASA phytosanitary clearance.
Established volume favors vitamins; emerging adoption favors probiotics.
End User:
Channel access restrictions under ANVISA's veterinary product regulations segment demand by prescription authority and dispensing infrastructure investment.
- Veterinary Clinics:Licensed practitioners in Buenos Aires and São Paulo metropolitan corridors prescribe condition-specific formulations with professional endorsement converting to repeat purchase loyalty. Direct-to-clinic distribution networks demand specialized technical representatives with clinical nutrition credentials.
- Pet Owners:Individual consumers purchasing through retail or digital channels for preventive or wellness-oriented supplementation. Urban pet owners in Santiago de Chile and Rio de Janeiro bypass traditional retail for automated delivery platforms, concentrating customer lifetime value with platform operators.
- Pet Stores:Specialty retail chains in Brazilian metropolitan corridors stocking mass-market formulations with established ingredient master files.
- Online Retailers:E-commerce platforms and subscription services capturing replenishment-driven purchases across Mercosur urban corridors.
Veterinary clinics anchor premium positioning; online retailers are climbing the fastest.
Form:
Manufacturing capability and palatability engineering determine margin structure and compliance feasibility across import and domestic production bases.
- Chews:Palatable molded matrices combining bioactive payloads with flavor systems to drive compliance in companion animals. Palatability-driven formulations command margin premiums in São Paulo specialty retail, where pet owner willingness-to-pay escalates for administration ease.
- Pills:Compressed tablets and capsules employing cold-press tableting for probiotic viability preservation. Standard dosage forms dominate veterinary dispensing in Buenos Aires clinics with established compliance infrastructure.
- Powders:Free-flowing granules for topical application or mixing with feed, subject to MAPA feed-grade additive classification constraints.
- Liquid:Aqueous or oil-based suspensions for precise dosing in small companion animals or species with specific administration requirements.
Chews capture margin premiums; powders face claim restriction headwinds.
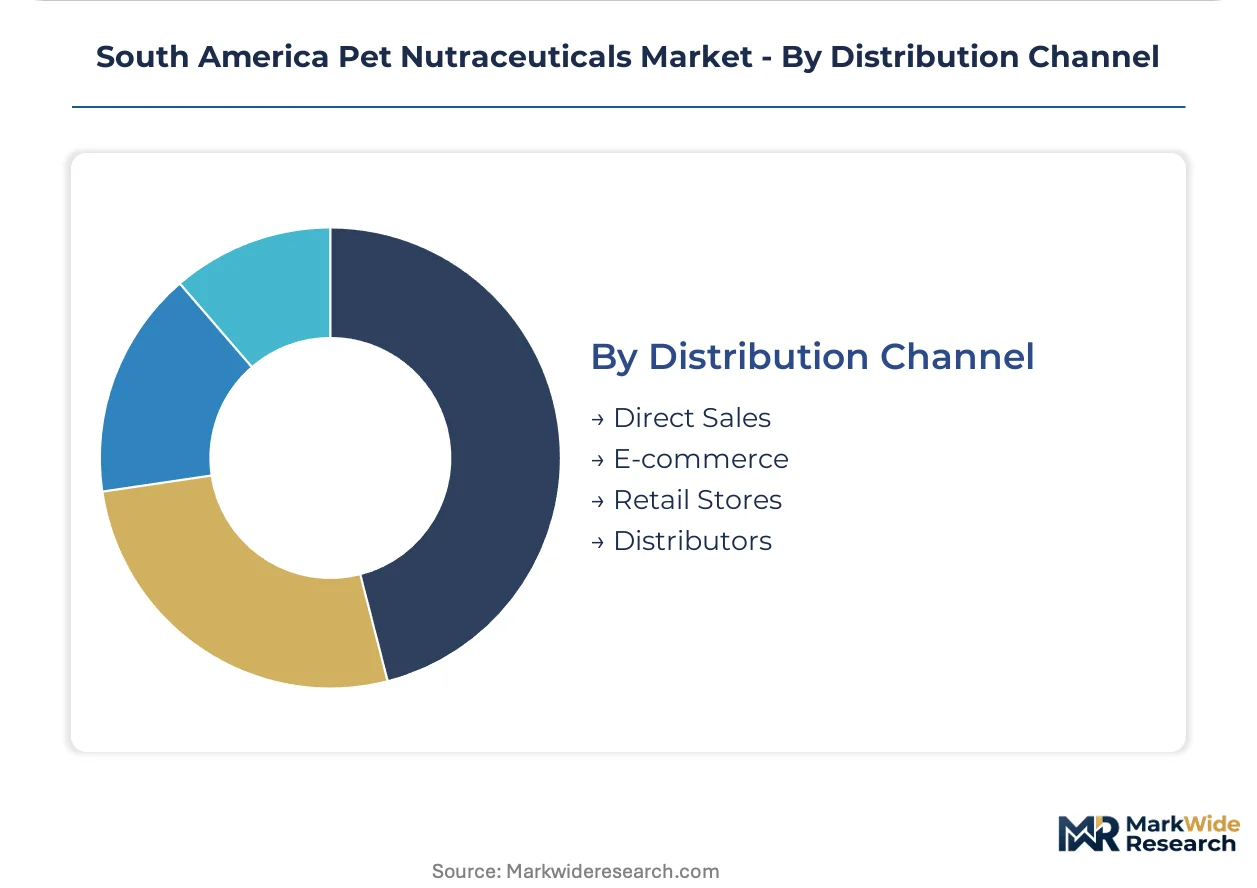
Distribution Channel:
Channel economics and regulatory clearance velocity segment access strategies between domestic certified manufacturers and import-dependent portfolios.
- E-commerce:Direct-to-consumer digital platforms enabling formulation customization and subscription replenishment. Urban pet owners in Rio de Janeiro and Santiago concentrate purchases through automated delivery, displacing traditional retail dependence.
- Direct Sales:Manufacturer-controlled veterinary and clinic relationships bypassing wholesale intermediaries. Nestlé Purina PetCare anchors position through direct-to-veterinarian networks in São Paulo and Buenos Aires.
- Retail Stores:Pet specialty and mass-market chains with shelf space allocation tied to established ANVISA registration timelines.
- Distributors:Regional wholesale intermediaries managing import clearance and inventory for cross-border entrants facing SENASA protocol friction.
Direct sales defend margin position; e-commerce is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary clinics and urban pet owners in South America's metropolitan corridors drive nutraceutical procurement patterns. Brazil's São Paulo and Rio de Janeiro anchor volume concentration. Argentina's Buenos Aires corridor sustains premium positioning. Chile's Santiago and Colombia's Bogotá emerge as high-growth access points.
Brazil
São Paulo's veterinary clinic density exceeds any other South American metro, with MAPA's feed-grade additive classifications constraining cross-category marketing claims. ANVISA's pet supplement registration pathway compresses competitive access timelines for imported portfolios. Domestic manufacturers in São Paulo's pharmaceutical corridor leverage pre-established ingredient master files to capture specialty retail shelf space.
Argentina
Buenos Aires metropolitan veterinarians prescribe condition-specific formulations with professional endorsement converting to repeat purchase loyalty. SENASA governs ingredient safety thresholds and import clearance protocols, elevating compliance costs for cross-border entrants. Direct-to-clinic distribution networks demand specialized technical representatives with clinical nutrition credentials.
Chile
Santiago's urban pet owners bypass traditional retail for automated delivery platforms, concentrating customer lifetime value with platform operators. The country's national pharmaceutical regulator maintains veterinary product standards that align with emerging Mercosur harmonization discussions. Subscription-based replenishment models capture preventive supplementation demand in affluent metropolitan districts.
Colombia
Bogotá's emerging middle-class pet ownership expands addressable market for mass-market vitamin and probiotic formulations. Import-dependent supply chains face clearance friction at national borders, protecting incumbent distributors with established logistics infrastructure. E-commerce platforms displace periodic veterinary visits for routine supplement purchases among digitally native consumers.
Uruguay
Montevideo's small but affluent pet owner base sustains premium chew and liquid formulation demand. Pending Mercosur veterinary product standard alignment would streamline multi-country portfolio deployment from Brazilian manufacturing bases. Regional distributors use Uruguay as a test market for novel delivery formats before broader South American rollout.
South America Pet Nutraceuticals Market Competitive Landscape
Player mix skews toward multinational pet care conglomerates with veterinary channel infrastructure. Tiered competitive structure separates prescription-grade formulators from mass-market supplement suppliers. Strategic archetypes include veterinary-direct specialists, retail-brand owners, and ingredient technology licensors. Dominant competitive moves encompass direct-to-clinic distribution expansion and microencapsulation capability acquisition.
Within the veterinary-direct tier, Mars Incorporated and Nestlé Purina PetCare exemplify channel-anchored positioning through São Paulo and Buenos Aires metropolitan networks. Virbac occupies a specialist position in condition-specific formulations. ADM and Kemin Industries represent ingredient technology suppliers enabling domestic manufacturer formulation upgrades. These anchors illustrate how regulatory compliance infrastructure and veterinary relationship depth determine competitive access velocity across ANVISA and SENASA jurisdictions.
| Leading Market Players |
|---|
| ADM |
| Alltech |
| Mars Incorporated |
| Nestlé Purina PetCare |
| Vetoquinol |
| Virbac |
| Dechra Pharmaceuticals |
| Nutramax Laboratories |
| Kemin Industries |
| Others |
Pricing and Supply Chain Analysis
Ninety-day ANVISA registration timelines for novel ingredient submissions compress inventory turns for import-dependent portfolios, concentrating pricing power with São Paulo-based domestic manufacturers holding pre-established ingredient master files. This lead-time asymmetry feeds directly into margin structures across veterinary and retail channels.
Pricing Analysis
Cost-plus contracts with pharmaceutical-grade prebiotic suppliers index to spot lactose and maltodextrin benchmarks, creating input price volatility that squeezes mid-tier formulators. Three-tier pricing structure across premium enteric-coated, standard tablet, and economy powder levels separates veterinary-grade efficacy claims from mass-market positioning. Cost compression in economy powders intensifies as MAPA feed-grade classifications prevent therapeutic premium capture. Urban pet owners in Rio de Janeiro display lowest price sensitivity for palatability-driven chews, while Bogotá's emerging middle-class buyers gravitate toward value-positioned vitamin complexes.
Supply Chain Analysis
Brazil and Argentina anchor regional manufacturing, with São Paulo's pharmaceutical corridor housing spray-drying capacity for microencapsulated probiotics and Buenos Aires concentrating condition-specific formulation R&D. Active ingredient supply draws from southern Brazilian prebiotic fermenters and imported European pharmaceutical-grade mineral chelates. Single-source vulnerability concentrates in enteric-coating polymer supply, where global specialty chemical producers dominate. Distribution runs through veterinary clinic direct-sales networks for premium tiers and e-commerce platforms for replenishment-driven volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of regulatory affairs capacity with ANVISA and SENASA filing expertise constrains competitive entry velocity, privileging incumbents with established compliance infrastructure and relationships with São Paulo's veterinary clinic networks.
For Market Incumbents: Fortify position by acquiring domestic spray-drying capacity to capture microencapsulation premiums and deepen backward integration into probiotic strain cultivation. Lock in exclusive direct-to-clinic distribution contracts in Buenos Aires before SENASA harmonization opens multi-country deployment pathways. Threat from subscription-platform operators disintermediating brand relationships demands channel control investment. For New Entrants and Emerging Players: Anchor in Santiago's e-commerce corridor where automated replenishment models concentrate customer lifetime value with platform operators rather than incumbent brands. Target Bogotá's underdeveloped joint health and dermatological segments with condition-specific formulations bypassing MAPA's feed-grade claim restrictions. Go-to-market angle: partner with regional distributors holding established SENASA clearance infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microencapsulation manufacturing as São Paulo clinics standardize on enteric-coated formulations. Long-term viability favors vertically integrated domestic producers with captive strain libraries and ANVISA master files. Acquisition target archetype: mid-scale Brazilian manufacturers with veterinary channel relationships and unused spray-drying capacity. Signal to watch: Mercosur harmonization implementation timelines as portfolio rebalancing trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Capability Acquisition | Spray-drying capacity in São Paulo separates veterinary-grade entrants from import-reliant competitors. |
| Direct-to-Veterinarian Distribution Expansion | Nestlé Purina PetCare's São Paulo and Buenos Aires networks demonstrate channel-anchored pricing power. |
| Ingredient Master File Investment | ANVISA pre-registration compresses competitive access timelines for domestic versus imported portfolios. |
| Condition-Specific Formulation Development | Virbac's joint and dermatological specialization captures underserved segments beyond gastrointestinal positioning. |
| E-commerce Platform Partnership | Rio de Janeiro and Santiago subscription models concentrate customer lifetime value away from traditional retail. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across veterinary clinic networks, pet specialty retail procurement, and domestic manufacturing facilities. Primary interviews captured prescribing patterns from São Paulo and Buenos Aires veterinarians, inventory management practices from Rio de Janeiro e-commerce platform operators, and regulatory navigation strategies from ANVISA compliance officers. Secondary validation drew from ANVISA registration databases, MAPA feed-grade additive classifications, SENASA import clearance protocols, and Mercosur veterinary product harmonization documentation. Bottom-up volume estimates triangulated against top-down market sizing from trade flow analysis.
Across the analysis window, the forecasting framework modeled product type segmentation by bioactive compound category, end-user channel access restrictions, form-based manufacturing capability requirements, and distribution channel economics. CAGRs derived from regression analysis against veterinary clinic density, urban pet ownership penetration, and e-commerce adoption curves. Industry-specific inputs included ANVISA registration timeline compression effects and MAPA disclosure mandate implementation trajectories.
Material uncertainties — regulatory harmonization delays, prebiotic input price spikes, veterinary clinic dispensing policy shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about ANVISA pathway stability and Mercosur alignment progress. Recalibration cycles align with material shifts in registration timeline announcements and harmonization treaty ratification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Oxiracetam Market
Nutraceuticals
Cognitive Health Ingredients Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Immunostimulants Market
Nutraceuticals
Global Synbiotics Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
Herbal Nutraceuticals Market
Nutraceuticals
Cordyceps Sinensis and Militaris Market
Nutraceuticals
Levocarnitine Market
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
Fish-Oil Based Drugs Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
Tetrahydropalmatine Market