
 Micro-Ecological Regulators Market | 2026-2036
Micro-Ecological Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Ecological Regulators Market Insights
Direct-to-practitioner distribution is tilting toward consolidated nutraceutical platforms that bundle formulation services with strain documentation. DuPont leverages its microbial library depth to anchor supply relationships with pharmaceutical compounders across North America and Europe. Chr. Hansen competes through specialized culture collections that sustain premium positioning in dairy and dietary supplement channels.
Micro-ecological regulators comprise live microorganisms, fermentable substrates, or combined formulations that modulate host microbial communities, typically requiring minimum viable counts of 10^6 to 10^9 CFU per gram for probiotic efficacy. These agents restore, maintain, or enhance symbiotic gut, skin, or environmental microbiomes in industrial and therapeutic settings. Probiotics occupy the largest revenue pool due to established clinical dossiers and practitioner familiarity, while synbiotics represent the fastest-expanding category as formulators pursue synergistic efficacy claims. Human nutrition and functional foods concentrate margin capture, whereas animal feed applications compete primarily on cost-per-dose metrics.
EFSA's qualified health claims framework, FDA's New Dietary Ingredient notification pathway, and China's NMPA biologics registration requirements collectively shape strain approval timelines and commercialization costs. The EU Green Deal's bioeconomy targets and REACH-derived substance safety protocols further constrain raw material sourcing for fermentation media. Stakeholders must monitor evolving pharmacovigilance obligations for live biotherapeutic products as regulators recategorize certain strains between food and drug jurisdictions.
Market Dynamics
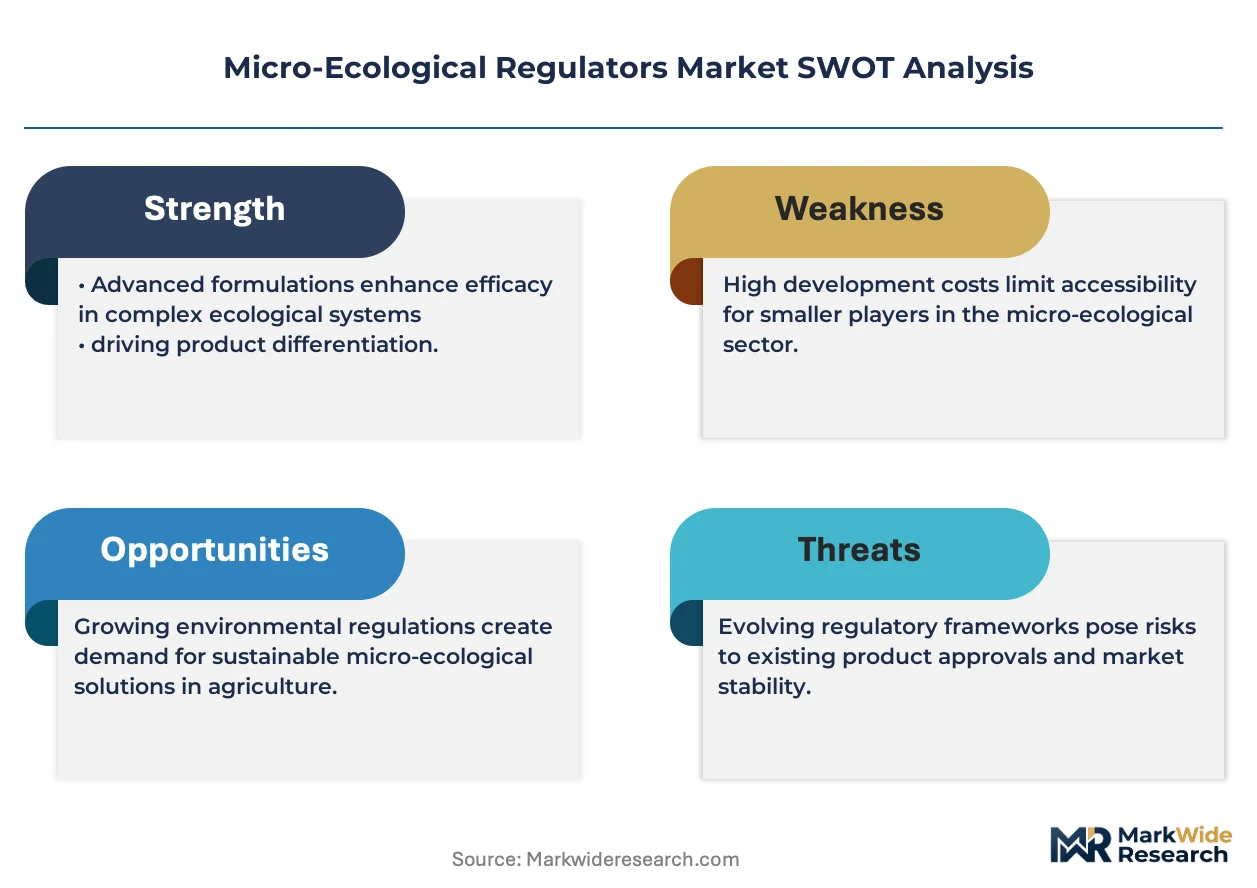
Stricter clinical substantiation requirements from EFSA and FDA are forcing manufacturers to restructure R&D budgets toward human intervention trials. This regulatory elevation favors well-capitalized players with existing strain documentation libraries.
Growth Catalysts
- EFSA Qualified Health Claims Framework:The pathway incentivizes investment in human nutrition dossiers. Functional food manufacturers now allocate resources toward strain-specific clinical evidence.
- Fermentation Technology Clusters:German pharmaceutical-grade probiotic facilities have expanded production capacity. This infrastructure concentration reduces strain-to-market timelines for European suppliers.
- Practitioner Channel Consolidation:Nutraceutical platforms bundle formulation services with strain documentation. Direct-to-practitioner distribution tilts toward these consolidated intermediaries.
Market Restraints
- Fermentation Media Sourcing Constraints:REACH-derived substance safety protocols limit raw material availability. EU Green Deal bioeconomy targets further tighten feedstock procurement.
- Strain Approval Timeline Uncertainty:China's NMPA biologics registration requirements extend commercialization cycles. Dual-track food-drug jurisdiction debates delay market entry.
- Live Biotherapeutic Product Reclassification Risk:Regulators recategorize certain strains between jurisdictions. Pharmacovigilance obligations for live products remain undefined.
Strategic Opportunities
- Synbiotic Formulation White Space:Combined live microorganism and fermentable substrate products represent underdeveloped positioning. Formulators pursue synergistic efficacy claims ahead of competitors.
- Animal Feed Premiumization:Cost-per-dose metrics currently dominate feed applications. Clinical substantiation investment could unlock value-based pricing in livestock microbiome modulation.
- Skin Microbiome Therapeutics:Topical micro-ecological regulators lack established clinical frameworks. Early movers in dermatological applications secure practitioner mindshare.
Industry Challenges
- Strain Characterization Talent Scarcity:Genomic identification and phenotypic profiling capabilities outpace qualified personnel supply. Fermentation science programs produce insufficient throughput.
- Cross-Jurisdictional Dossier Harmonization:FDA New Dietary Ingredient notifications, EFSA health claims, and NMPA biologics registrations demand non-overlapping evidence packages. Parallel track development drains resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Ecological Regulators Market |
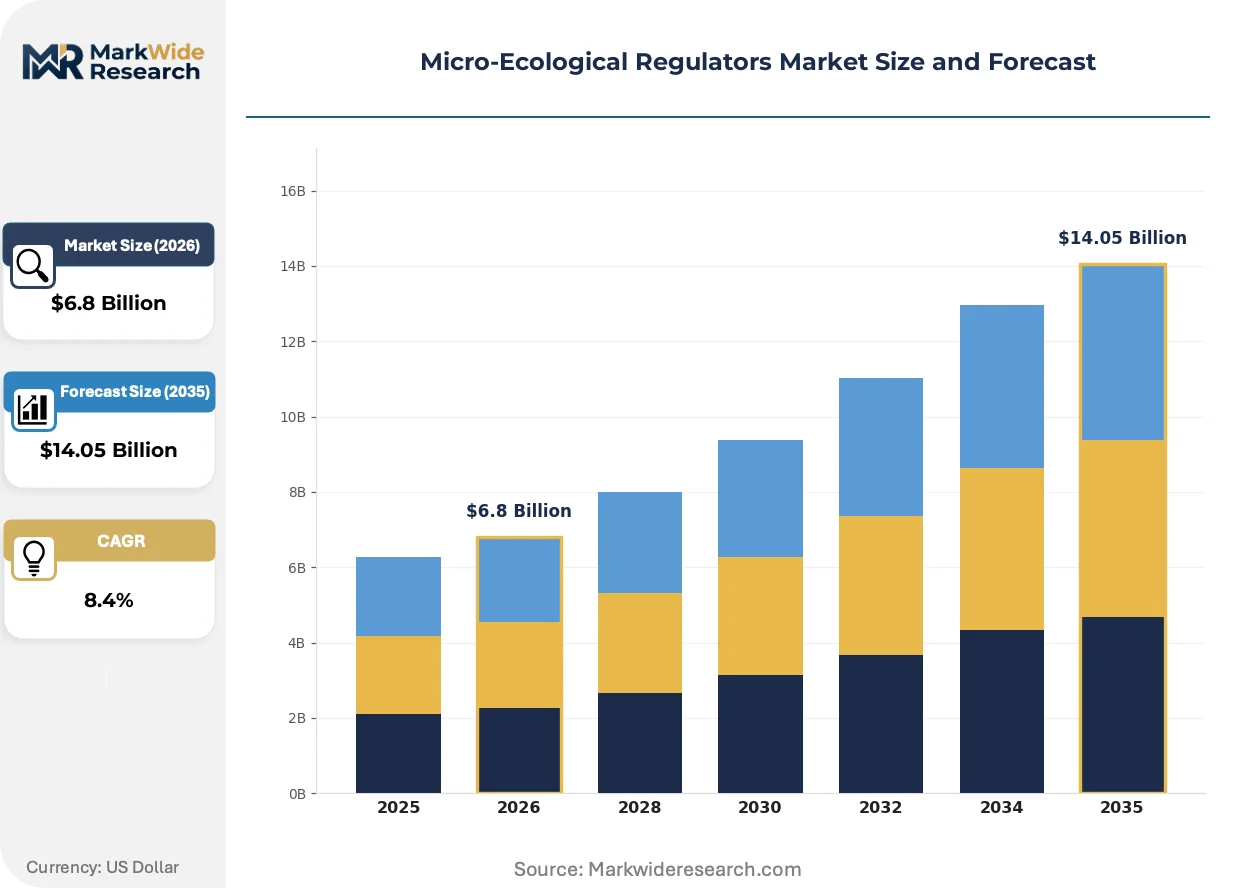
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Synbiotics, Fermented Products Application: Animal Feed, Human Nutrition, Functional Foods, Pharmaceuticals Delivery Mode: Dry Powder, Liquid, Granules, Capsules End User: Agriculture, Healthcare, Food & Beverage, Personal Care |
| Companies Covered | DuPont, Sabinsa Corporation, Chr. Hansen, BioGaia, Novozymes, Yakult, China-Biotics, Beneo, Daflorn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Ecological Regulators Market Trends and Innovations
Next-generation sequencing and metabolomics integration are compressing strain characterization timelines. Manufacturers now map microbial community interactions at scale previously reserved for pharmaceutical development.
Single-cell encapsulation technology is collapsing the viability gap between production and consumption endpoints. Functional beverage manufacturers adopt this stabilization approach to maintain 10^9 CFU counts through shelf life. The structural consequence is expanded distribution reach into ambient retail channels previously inaccessible to live cultures.
REACH substance safety protocols and EU Green Deal bioeconomy targets are constraining fermentation media formulation options. Manufacturers reformulate growth substrates to exclude flagged chemical inputs. Dairy and dietary supplement channels face input cost pressure as compliant alternatives command scarcity premiums.
Consolidated nutraceutical platforms displace fragmented distributor networks in practitioner-facing channels. Formulation services bundled with strain documentation capture margin previously distributed across multiple intermediaries. Germany and North American metropolitan clusters exhibit the most pronounced channel concentration.
Micro-Ecological Regulators Market Segmentation
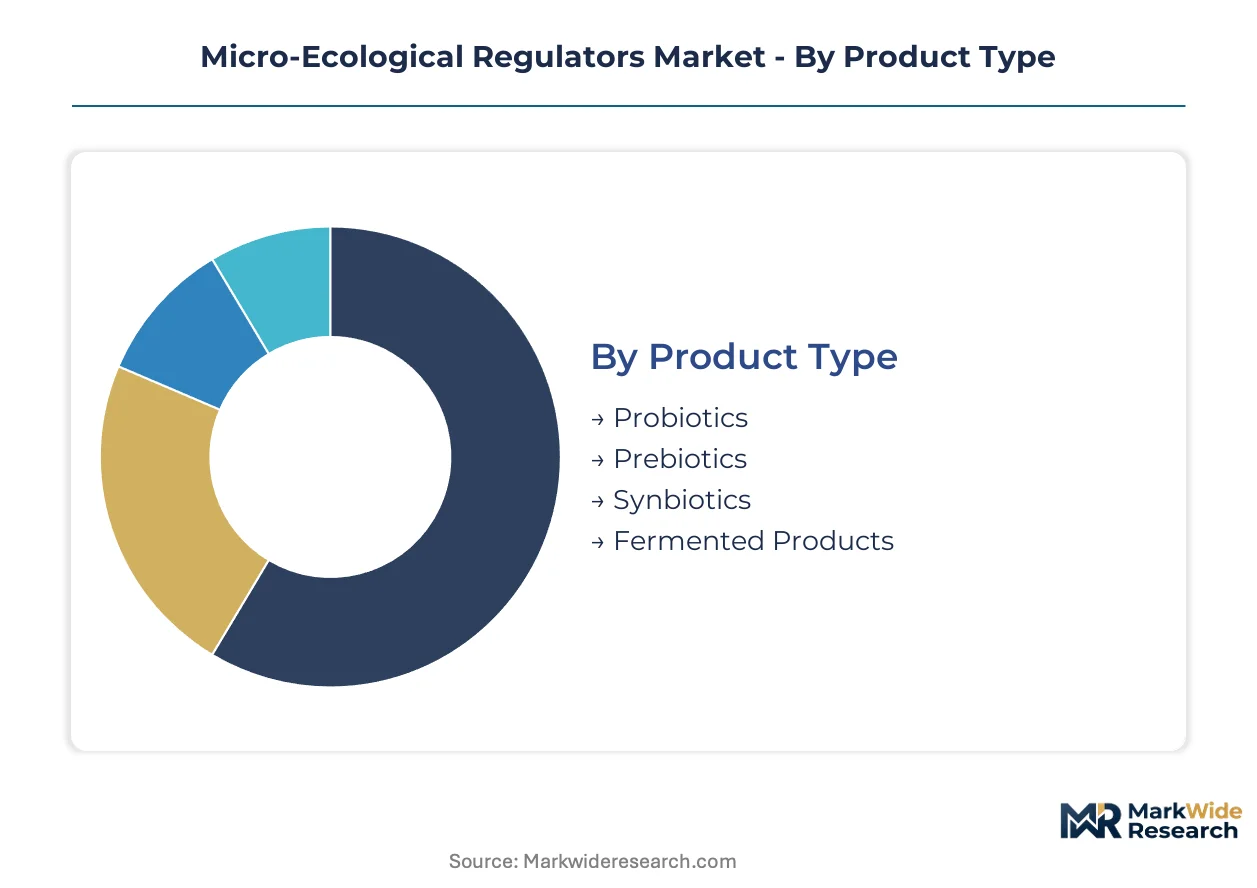
Segmentation in micro-ecological regulators reveals divergent margin structures and regulatory exposure across product categories. Cycle times vary dramatically—fermentation-derived probiotics require years of strain documentation while formulation innovations in delivery modes turn over quarterly.
Product Type:
Cycle times stretch from multi-year strain development for live cultures to rapid substrate sourcing for fermentable fibers. Probiotics demand the longest validation timelines due to viability requirements.
- Probiotics:Live microorganisms requiring 10^6 to 10^9 CFU per gram for efficacy. Demand concentrates in Germany's pharmaceutical-grade facilities where EFSA health claims documentation drives practitioner channel adoption. Strain-specific clinical dossiers anchor premium positioning.
- Synbiotics:Combined live microorganism and fermentable substrate formulations. Functional food manufacturers in North America pursue synergistic efficacy claims ahead of regulatory clarity. This segment climbs the fastest as formulators seek differentiated positioning.
- Prebiotics:Non-digestible fermentable substrates that selectively stimulate beneficial gut bacteria. Dairy applications in France and the Netherlands dominate procurement.
- Fermented Products:Traditional or controlled fermentation outputs with inherent microbial content. Asian markets sustain volume through established consumption patterns.
Probiotics anchor the volume base while synbiotics gain share at the steepest rate.
Application:
Cost tiers separate clinical-grade therapeutic applications from commodity feed additives. Human-facing segments command tenfold price multiples over agricultural uses.
- Human Nutrition:Dietary supplements and direct consumption formats with strain-specific dosing. Investment from functional food manufacturers sustains margin expansion. EFSA and FDA substantiation requirements elevate clinical trial spending.
- Pharmaceuticals:Live biotherapeutic products facing drug jurisdiction reclassification risks. China's NMPA biologics registration extends commercialization timelines. Early movers secure practitioner relationships ahead of formalized frameworks.
- Functional Foods:Fortified beverages and ambient-stable formats enabled by single-cell encapsulation. Shelf-life viability requirements constrain formulation options.
- Animal Feed:Cost-per-dose metrics dominate procurement. Livestock microbiome modulation competes primarily on volume pricing with limited clinical substantiation investment.
Human nutrition commands the premium tier while animal feed sustains the volume foundation.
Delivery Mode:
Supply concentration clusters around powder processing infrastructure in Germany and North American metropolitan areas. Liquid formats face distribution radius constraints.
- Dry Powder:Dominant format for probiotic stability through shelf life. German fermentation technology clusters and North American compounding facilities anchor production capacity. REACH-compliant media sourcing elevates input costs.
- Capsules:Practitioner-facing channels favor this format for precise dosing. Consolidated nutraceutical platforms bundle encapsulation with strain documentation.
- Liquid:Functional beverage applications require cold-chain infrastructure. Ambient stability gaps limit retail penetration.
- Granules:Intermediate format for bulk feed and industrial blending. Agricultural end-users in Brazil and Argentina drive procurement.
Dry powder captures the widest distribution while capsules expand most quickly in practitioner channels.
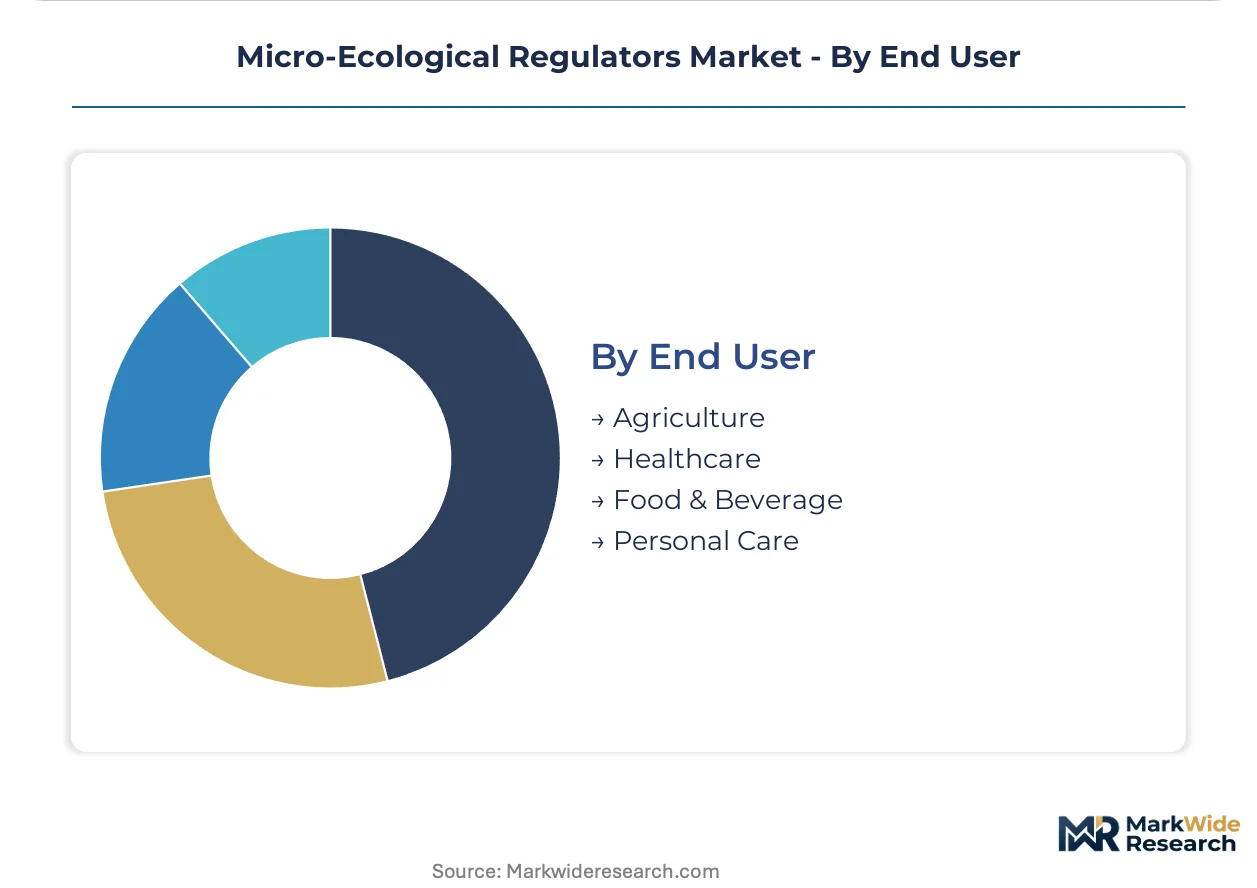
End User:
Customer sophistication separates pharmaceutical-grade purchasers from agricultural commodity buyers. Healthcare and food sectors demand parallel documentation tracks.
- Healthcare:Clinical practitioners and therapeutic developers requiring pharmacovigilance-grade strain tracking. FDA New Dietary Ingredient notifications and EFSA qualified health claims frameworks shape procurement specifications.
- Food & Beverage:Functional product developers pursuing dual-track food-drug positioning. Single-cell encapsulation adoption enables ambient retail expansion previously inaccessible to live cultures.
- Agriculture:Livestock and crop applications competing on cost efficiency. Feed integrators in the US Midwest and Brazilian protein belts concentrate demand.
- Personal Care:Skin microbiome therapeutics lacking established clinical frameworks. Early movers in dermatological applications secure formulation partnerships.
Food and beverage sustains the broadest customer base while personal care presents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's probiotic distribution reach into ambient retail channels previously inaccessible to live cultures. German fermentation technology clusters leverage this logistics backbone to compress strain-to-market timelines.
United States
Functional food manufacturers in the Midwest and California sustain investment in human nutrition dossiers. FDA's New Dietary Ingredient notification pathway shapes strain approval timelines and commercialization costs. North American metropolitan compounding facilities anchor dry powder production capacity for practitioner-facing capsules.
Germany
EFSA's qualified health claims framework elevates clinical substantiation requirements for strain-specific positioning. The EU Green Deal's bioeconomy targets constrain fermentation media sourcing through REACH-derived substance safety protocols. Bavaria and North Rhine-Westphalia host pharmaceutical-grade probiotic facilities that have expanded production capacity.
China
NMPA's biologics registration requirements extend commercialization cycles for live biotherapeutic products. Dual-track food-drug jurisdiction debates delay market entry for certain strain categories. Yangtze River Delta fermentation infrastructure concentrates synbiotic formulation activity ahead of regulatory clarity.
Japan
PMDA oversight of functional food claims drives investment in human intervention trials for established consumption formats. METI's support for fermentation technology sustains traditional and controlled fermentation output volumes. Kanto region dairy applications dominate procurement for prebiotic substrates.
Micro-Ecological Regulators Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying strain libraries and culture collections. The vendor base organizes around three tiers: multinational life science conglomerates with microbial library depth, specialized culture collection houses, and regional fermentation technology providers. Strategic archetypes include strain documentation bundlers, formulation service integrators, and captive supply verticalists. Dominant competitive moves encompass geographic capacity expansion and practitioner channel consolidation through bundled service platforms.
Within the multinational tier, DuPont leverages its microbial library depth to anchor supply relationships, while Chr. Hansen occupies a position exemplifying specialized culture collection premium positioning. Among Asia-Pacific-based operators, Yakult represents the established consumption format archetype, and China-Biotics sits within the regional fermentation technology provider category. These three named entities illustrate the competitive structure without exhausting its full composition.
| Leading Market Players |
|---|
| DuPont |
| Sabinsa Corporation |
| Chr. Hansen |
| BioGaia |
| Novozymes |
| Yakult |
| China-Biotics |
| Beneo |
| Daflorn |
| Others |
Pricing and Supply Chain Analysis
German fermentation technology clusters concentrate pharmaceutical-grade probiotic capacity, anchoring margin capture in strain-documented human nutrition segments while feed-grade applications compete on cost efficiency downstream. REACH-compliant media sourcing elevates input costs for culture production, compressing margins at the standard tier while premium positioning sustains pricing power through EFSA health claims documentation.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade strains from commodity feed additives by a tenfold multiple, with certification level and strain-specific clinical dossiers driving premium-mid-economy pricing differentiation. Cost compression in standard-tier synbiotics is intensifying as REACH-compliant fermentation media command scarcity premiums. Healthcare practitioners exhibit the least price sensitivity due to reimbursement-adjacent positioning, while livestock integrators in Brazil and Argentina drive procurement on pure cost-per-dose metrics.
Supply Chain Analysis
Extended payment terms from consolidated nutraceutical platforms now dominate supplier-financing structures, with strain documentation bundling capturing margin previously distributed across fragmented distributor networks. Production gravity centers on Germany, the United States, and China's Yangtze River Delta, with fermentation media sourcing drawing from dairy-derived substrates, plant-based hydrolysates, and pharmaceutical-grade yeast extracts. Single-source vulnerability concentrates in German pharmaceutical-grade facilities for practitioner-facing capsules. Distribution runs through direct-to-practitioner platforms in North American metropolitan clusters and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synbiotic formulation white space and skin microbiome therapeutics represent early-cycle expansion vectors, with practitioner channel consolidation accelerating adoption ahead of formalized regulatory frameworks.
For Market Incumbents: Harden strain documentation libraries against emerging culture collection competitors by expanding genomic identification capabilities in Bavaria and North Rhine-Westphalia. Captive supply of fermentation media buffers REACH-derived input cost volatility. Channel control through bundled formulation services defends margin position against platform consolidation. For New Entrants and Emerging Players: Ambient-stable functional beverages enabled by single-cell encapsulation technology represent the most penetrable entry point, with North American metropolitan retail channels lacking established live culture distribution. Skin microbiome therapeutics in dermatological applications offer practitioner mindshare capture ahead of clinical framework formalization. Direct-to-practitioner platform partnerships accelerate strain adoption without legacy distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward specialized culture collection houses with phenotypic profiling capabilities and established EFSA dossier pathways. Long-term viability across a 5-10 year window hinges on regulatory recategorization of live biotherapeutic products between food and drug jurisdictions. The signal to watch is NMPA biologics registration clarity for dual-track positioning in China.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Documentation Library Expansion | EFSA-qualified health claims anchor premium positioning against commodity competitors. |
| Fermentation Media Backward Integration | REACH-compliant substrate sourcing reduces input cost volatility for German facilities. |
| Single-Cell Encapsulation Technology Licensing | Ambient retail channel expansion unlocks functional beverage distribution previously inaccessible. |
| Practitioner Platform Partnership | Consolidated nutraceutical intermediaries bundle formulation services with strain adoption. |
| Synbiotic Formulation Pipeline Diversification | Combined live microorganism and fermentable substrate products capture fastest-expanding category share. |
Research Methodology
Desk research of EFSA qualified health claims registers, FDA New Dietary Ingredient notifications, and NMPA biologics filings preceded structured interviews with fermentation technology directors, regulatory affairs leads at culture collection houses, practitioner-facing nutraceutical platform executives, and livestock feed procurement managers. Secondary validation drew from customs trade data, REACH substance safety protocols, and EU Green Deal bioeconomy target disclosures. Bottom-up strain-level volume estimates triangulated against top-down category expenditure projections.
Assumptions held EFSA and FDA substantiation timelines stable while varying NMPA registration clarity scenarios across the projection horizon. Segmentation dimensions modeled encompass product type, application tier, delivery mode stability requirements, and end-user sophistication level. CAGRs derived from strain-specific adoption curves weighted by practitioner channel penetration rates and fermentation capacity expansion timelines in Germany and North America.
Macroeconomic conditions sit as an overlay; deviation in feedstock commodity prices or biologics registration urgency would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory recategorization risk and pharmacovigilance obligation evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
North America Effervescent Tablet Market
Nutraceuticals
Nattokinase Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Pet Nutraceuticals Market
Nutraceuticals
Piracetam Market
Nutraceuticals
Hydrolyzed Bovine Collagen Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Cordyceps Sinensis and Militaris Market
Nutraceuticals
Global Synbiotics Market
Nutraceuticals
PMS and Menstrual Health Supplements Market
Nutraceuticals
Immunostimulants Market
Nutraceuticals
US Collagen Market
Nutraceuticals
Oxiracetam Market
Nutraceuticals
Anti-Inflammatory Peptides Market
Nutraceuticals
Global Nicotinamide Mononucleotide (NMN) Market
Nutraceuticals
Magtein Market