
 Global Eye Health Supplement Market | 2026-2036
Global Eye Health Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Eye Health Supplement Market Foresight
Asset-light contract manufacturing and white-label financing is reconfiguring competitive entry barriers for mid-tier entrants in eye health supplements. Bausch + Lomb leverages its established ophthalmology channel infrastructure to sustain pharmacy shelf presence across North America. Kemin Industries anchors its position through captive supply of FloraGLO lutein, controlling upstream botanical extraction. Vitabiotics Ltd differentiates via clinically positioned branding in European retail environments.
Eye health supplements comprise orally administered nutraceuticals formulated with carotenoids, essential fatty acids, and trace minerals at specified dosages to support retinal function and ocular surface integrity. These products undergo tablet or softgel manufacturing with validated dissolution profiles to ensure bioavailability of lipophilic actives like lutein and zeaxanthin for macular pigment maintenance. Lutein and zeaxanthin segments lead value generation due to their AREDS2 validation and concentrated use in age-related macular degeneration applications. Omega-3 fatty acids represent the fastest-expanding category as dry eye relief protocols integrate EPA/DHA into clinical recommendations. Distribution through online retailers captures accelerating margin pools as direct-to-consumer subscription models bypass traditional pharmacy markups.
The FDA oversees dietary supplement cGMP compliance and structure-function claim boundaries, while EFSA enforces health claim authorization under EU Regulation 1924/2006, compelling reformulation and label revision for European market access. Japan's Consumer Affairs Agency monitors FOSHU and qualified health claim designations, creating segmented regulatory pathways for functional eye health products. Stakeholders must monitor evolving substantiation thresholds for carotenoid-specific claims as regulators demand tighter clinical evidence linking intake to measurable visual outcomes.
Market Dynamics
Contract manufacturing networks are compressing capital requirements for eye health supplement entrants, while AREDS2 formulation standards consolidate demand around clinically validated carotenoid dosages. Regulatory substantiation thresholds in major markets are simultaneously elevating R&D barriers and rewarding incumbent clinical data portfolios.
Growth Catalysts
- Aging Demographics:Japan's expanding geriatric care procurement of lutein-based formulations creates institutional volume anchors. Facilities prioritize macular health protocols for resident populations.
- AREDS2 Validation:The NIH-backed formulation protocol drives physician recommendation rates for lutein-zeaxanthin combinations. Clinical endorsement converts skeptical consumers in United States ophthalmology channels.
- Omega-3 Integration:Dry eye syndrome treatment guidelines now incorporate EPA/DHA supplementation. Optometry practices in Germany and Australia prescribe alongside conventional therapies.
Market Restraints
- Raw Material Concentration:Marigold flower cultivation for lutein extraction concentrates in India and China. Weather volatility and agricultural commodity cycles transmit directly to formulation costs.
- EFSA Claim Authorization:EU Regulation 1924/2006 demands randomized controlled trials for eye health substantiation. Smaller brands lack capital to generate acceptable clinical packages.
- Pharmaceutical Substitution:Prescription dry eye therapies (cyclosporine, lifitegrast) capture severe cases. Supplement positioning remains limited to prevention and mild symptom management.
Strategic Opportunities
- Brazil's Underpenetrated Retail:ANVISA regulatory pathways for functional foods create first-mover positioning. Pharmacy chains in São Paulo and Rio de Janeiro seek differentiated supplement assortments.
- Subscription Commerce:Direct-to-consumer replenishment models bypass pharmacy margin stacking. United States digital-native brands capture lifetime value through automated dosing compliance.
- Blue Light Positioning:Device-screen exposure narratives expand addressable population beyond aging segments. Marketing to digital professionals in South Korea and United Kingdom builds preventive consumption habits.
Industry Challenges
- Bioavailability Engineering:Lipophilic carotenoid absorption varies significantly by delivery format. Softgel dissolution profile optimization requires specialized formulation chemistry expertise that concentrates among legacy manufacturers.
- Cross-Border Label Harmonization:Structure-function claim boundaries differ between FDA, EFSA, and Japan's Consumer Affairs Agency. Multi-market brands maintain parallel SKU inventories with jurisdiction-specific packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Eye Health Supplement Market |
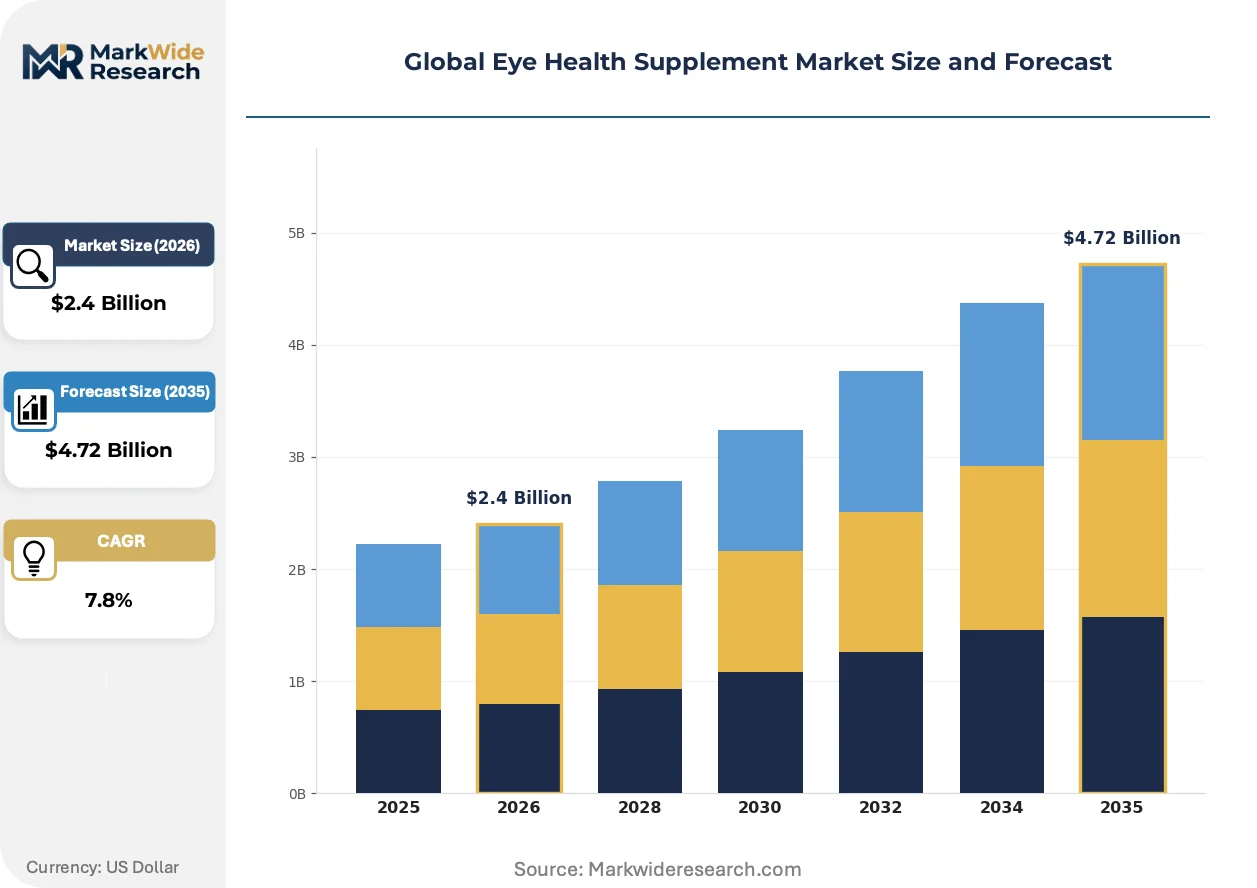
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lutein, Zeaxanthin, Vitamin A, Omega-3 Fatty Acids, Bilberry Extract, Zinc Application: Age-Related Macular Degeneration, Dry Eye Relief, Cataract Prevention, Visual Acuity Enhancement End User: Pharmacies, Eye Care Clinics, Wellness Centers, Geriatric Care Facilities Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Healthcare Providers |
| Companies Covered | Bausch + Lomb, Vitabiotics Ltd, Amway International, The Nature's Bounty Co., ZeaVision LLC, EyePromise, MacuHealth, ScienceBased Health, Kemin Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Eye Health Supplement Market Shifts & Advancements
Digital health integration and personalized nutrition platforms are reconfiguring how eye health supplements reach consumers and demonstrate efficacy. Formulation science advances alongside distribution technology to reshape competitive positioning.
Microencapsulation technology is virtualizing traditional softgel manufacturing for carotenoid delivery. Startups in Netherlands and California adopt spray-drying and lipid-shell engineering to improve lutein stability in powder formats. Pharmaceutical-grade contract manufacturers now offer these platforms to mid-tier brands, compressing the capital gap between concept and commercial scale.
EFSA's tightened health claim authorization under EU Regulation 1924/2006 is forcing reformulation and label revision across European portfolios. Brands lacking approved claims retreat to generic "wellness" positioning, surrendering pharmacy shelf space to clinically substantiated competitors. German and French retailers now demand EFSA-approved claim documentation before listing new eye health SKUs.
Direct-to-consumer subscription models are displacing pharmacy-centric distribution in United States and United Kingdom markets. Millennials and Generation Z buyers prefer automated replenishment with telehealth-adjacent eye screening integrations. Digital-native brands capture margin pools that traditional retail markups previously absorbed, redirecting capital toward influencer partnerships and personalized dosing algorithms.
Global Eye Health Supplement Market Segmentation
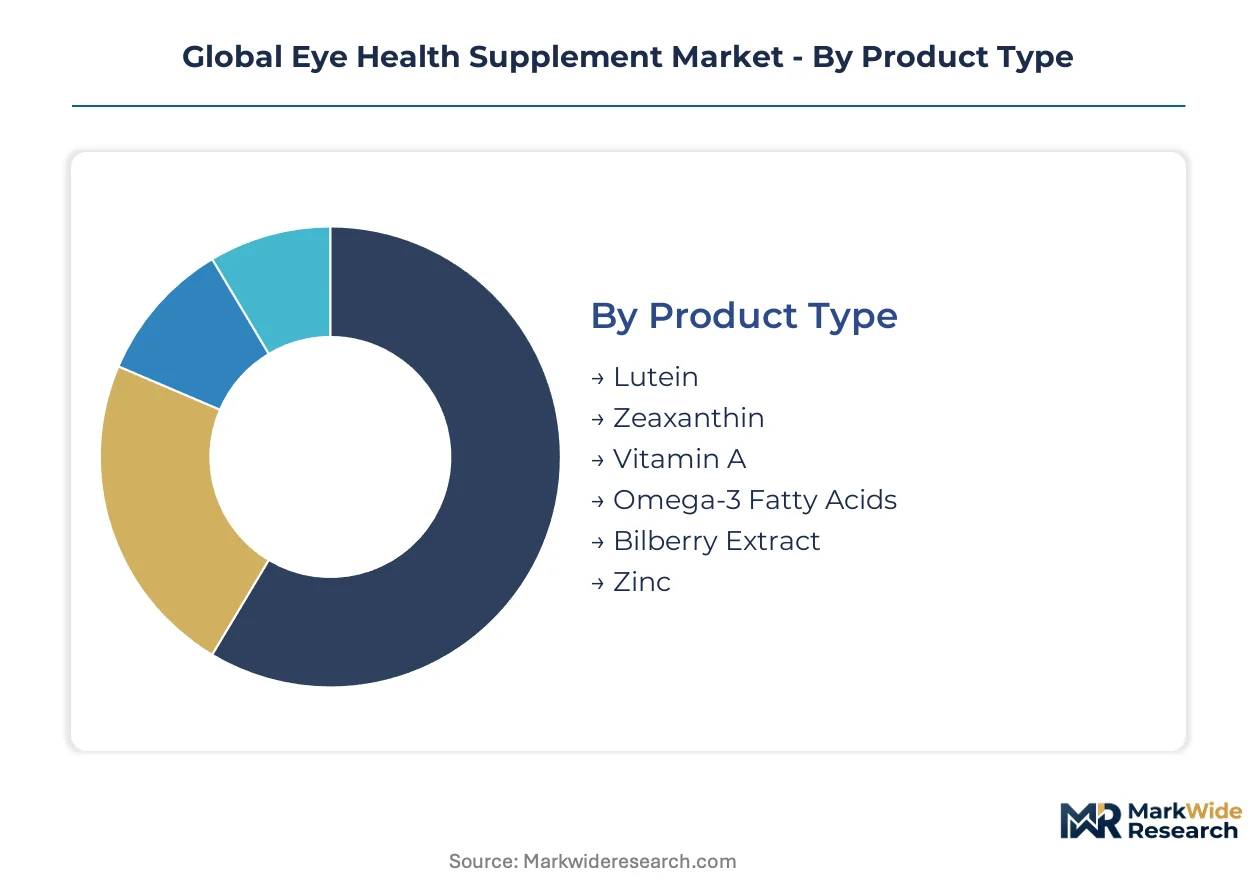
Segmentation in the eye health supplement market reveals how formulation science, clinical validation, and channel economics create distinct competitive battlegrounds. Each dimension carries different margin profiles and regulatory exposure, forcing portfolio decisions that balance volume scale against substantiation investment.
Product Type:
Inventory velocity varies dramatically across this category, with commodity minerals turning fastest and specialized botanical extracts requiring longest procurement cycles.
- Lutein:Marigold-derived carotenoid concentrates at 10-20mg dosages for macular pigment density maintenance. Japanese geriatric care facilities in Osaka and Fukuoka now specify FloraGLO-sourced material for resident protocols, tightening supply allocation for retail brands.
- Omega-3 Fatty Acids:EPA/DHA concentrates from marine or algal sources formulated for meibomian gland function support. German optometry practices in Munich and Hamburg increasingly prescribe alongside conventional dry eye therapies, expanding clinical channel penetration beyond supplement aisles.
- Zeaxanthin:Isomer-specific carotenoid dosed at 2-4mg alongside lutein in AREDS2-aligned formulations.
- Vitamin A:Retinol and beta-carotene variants for night vision and corneal surface integrity protocols.
- Bilberry Extract:Anthocyanin-standardized botanical for microcirculation and retinal oxygenation claims.
- Zinc:Mineral cofactor at 25-80mg dosages completing AREDS2 mineral matrices.
Lutein anchors the volume base while Omega-3 Fatty Acids gain share at the steepest rate.
Application:
Revenue concentration follows disease prevalence demographics, with aging-linked indications commanding premium pricing against preventive positioning.
- Age-Related Macular Degeneration:AREDS2-validated protocols dominate physician recommendation channels. United States ophthalmology practices in Boston and Philadelphia drive prescription-adjacent supplement dispensing with clinical endorsement converting skeptical Medicare-age consumers.
- Dry Eye Relief:Omega-3 and antioxidant combinations target evaporative and aqueous-deficient subtypes. Australian optometry chains in Sydney and Melbourne now stock clinical-grade formulations alongside conventional therapies, blurring the pharmacy-clinic boundary.
- Cataract Prevention:Antioxidant positioning for lens opacity delay remains limited by EFSA claim rejection history.
- Visual Acuity Enhancement:Blue light and digital eye strain narratives expand addressable population beyond clinical diagnoses.
Age-Related Macular Degeneration commands the largest revenue pool while Dry Eye Relief expands most quickly across practitioner channels.
End User:
Procurement authority and reimbursement pathways create four distinct customer types with incompatible contract terms and compliance requirements.
- Pharmacies:Retail and hospital dispensaries with formulary committees and shelf-space negotiations. CVS and Walgreens in the United States now demand EFSA-equivalent substantiation documentation for premium positioning, elevating listing barriers.
- Eye Care Clinics:Ophthalmology and optometry practices with direct patient influence and dispensing privileges. Clinics in Seoul's Gangnam district bundle supplements with refractive surgery packages, capturing lifetime value through procedure adjacency.
- Wellness Centers:Preventive health facilities with subscription models and lifestyle coaching integration.
- Geriatric Care Facilities:Institutional procurement for resident populations with standardized protocols. Japanese facilities in Kanagawa and Aichi prefectures specify lutein inclusion in macular health programs, creating volume anchors with annual contracting cycles.
Pharmacies retain the broadest reach while Eye Care Clinics deliver the highest per-patient conversion rates.
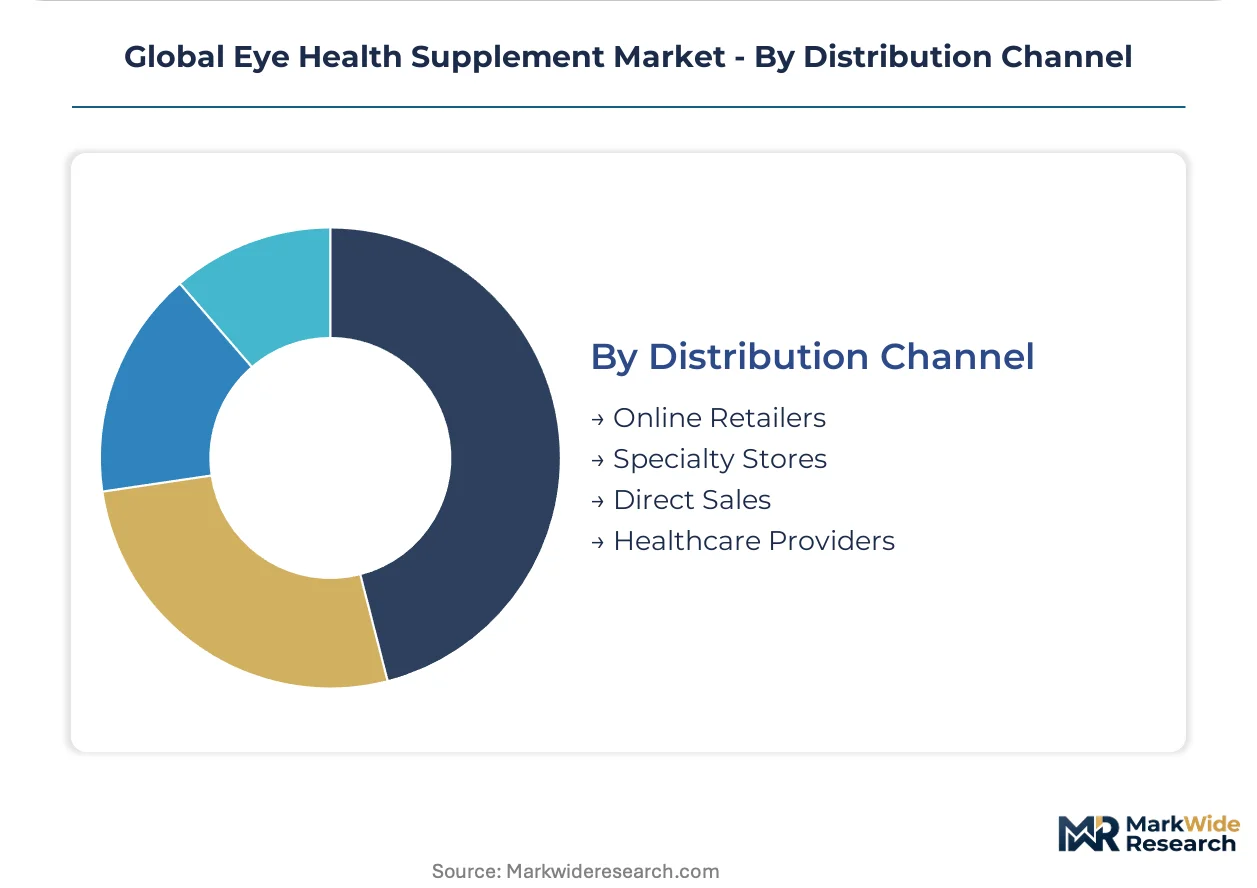
Distribution Channel:
Margin capture and customer acquisition economics diverge sharply between digital-native and legacy infrastructure.
- Online Retailers:Amazon, iHerb, and brand-direct sites with subscription automation and influencer attribution. United Kingdom digital-native brands leverage TikTok and Instagram targeting for millennial blue-light positioning, bypassing pharmacy markups entirely.
- Specialty Stores:Health food and vitamin-focused retail with educated staff and premium assortment curation. GNC and Holland & Barrett maintain dedicated eye health sections with trained associates driving basket attachment.
- Direct Sales:Multi-level marketing and practitioner-exclusive lines with relationship-based distribution.
- Healthcare Providers:Clinic-dispensed and hospital formulary placement with insurance-adjacent positioning.
Online Retailers capture volume leadership while Healthcare Providers deliver the stickiest patient relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in eye health supplements favor net-importing developed markets with aging populations, while raw material extraction concentrates in agrarian economies with lower domestic consumption. Finished formulation exports from the United States and Germany meet institutional procurement demand across Asia-Pacific and Latin America.
United States
Medicare-age consumers drive AREDS2-formulated product demand through ophthalmology channel recommendations. FDA cGMP compliance and structure-function claim boundaries shape domestic formulation standards. Boston and Philadelphia clinical clusters anchor prescription-adjacent supplement dispensing with physician endorsement converting skeptical patient populations.
Japan
Geriatric care facilities in Osaka and Fukuoka specify lutein-based protocols for resident macular health programs. Consumer Affairs Agency FOSHU and qualified health claim designations create segmented regulatory pathways for functional positioning. Kanagawa and Aichi prefectures institutionalize annual contracting cycles for lutein procurement in standardized resident care.
Germany
Munich and Hamburg optometry practices increasingly prescribe omega-3 EPA/DHA alongside conventional dry eye therapies. EFSA health claim authorization under EU Regulation 1924/2006 demands randomized controlled trial substantiation for eye health positioning. German retailers now require approved claim documentation before listing new eye health SKUs.
Australia
Sydney and Melbourne optometry chains stock clinical-grade formulations alongside conventional therapies, blurring pharmacy-clinic boundaries. TGA therapeutic goods administration oversees complementary medicine listing requirements with distinct evidence standards. Practitioner channel penetration expands fastest among English-speaking markets with integrated eye care protocols.
Brazil
ANVISA regulatory pathways for functional foods create first-mover positioning in underpenetrated retail. São Paulo and Rio de Janeiro pharmacy chains seek differentiated supplement assortments with preventive health narratives. Import dependency for finished formulations creates distribution partnerships with North American and European manufacturers.
Global Eye Health Supplement Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive botanical extraction and validated dissolution chemistry. The vendor base stratifies across three tiers: multinational ophthalmology channel operators with pharmacy shelf dominance, mid-tier contract manufacturing brands with white-label agility, and specialized carotenoid extractors with upstream cultivation control. Dominant competitive moves include backward integration into marigold cultivation regions and technology licensing for microencapsulation delivery formats.
Within the ophthalmology platform tier, Bausch + Lomb represents established channel infrastructure with North American pharmacy presence. Kemin Industries exemplifies upstream vertical control through captive FloraGLO lutein supply and botanical extraction specialization. Vitabiotics Ltd occupies a clinically positioned branding niche in European retail environments with EFSA-aligned substantiation strategies.
| Leading Market Players |
|---|
| Bausch + Lomb |
| Vitabiotics Ltd |
| Amway International |
| The Nature's Bounty Co. |
| ZeaVision LLC |
| EyePromise |
| MacuHealth |
| ScienceBased Health |
| Kemin Industries, Inc. |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor transmits freight cost volatility directly into lutein concentrate landed costs, compressing margins for European contract manufacturers while amplifying price differentiation between FloraGLO-certified and generic marigold extract tiers. This logistics chokepoint concentrates pricing power with Indian and Chinese botanical extractors who control upstream cultivation, forcing downstream brands to absorb tariff exposure or surrender pharmacy shelf positioning.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing structures for geriatric care facilities in Japan and institutional procurement channels in Germany. Three-tier pricing structure across premium AREDS2-validated, standard clinical-grade, and economy wellness-positioned tiers separates Kemin-captive supply from white-label competitors. Cost compression in economy tiers is intensifying because Indian marigold harvest volatility transmits directly to spot concentrate markets. Medicare-age direct-to-consumer buyers show lowest price sensitivity, while pharmacy chain procurement teams in Brazil and Australia drive hardest volume discount negotiations.
Supply Chain Analysis
Tariff exposure between India and the European Union dominates supply chain risk calculus for lutein concentrate sourcing. Marigold flower cultivation concentrates in India and China, with secondary extraction capacity in Mexico and Spain. Raw material dependencies rest on agricultural monsoon cycles, phospholipid encapsulation inputs, and pharmaceutical-grade gelatin for softgel shells. Single-source vulnerability concentrates in Kemin Industries' captive FloraGLO supply for premium tier formulations. Distribution runs through pharmaceutical wholesale networks in North America, specialized pharmacy chains in Germany, and direct-to-consumer subscription platforms in the United States and United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prescription dry eye therapies including cyclosporine and lifitegrast threaten to capture severe symptom cases, forcing supplement incumbents to defend prevention-positioned market share through clinical channel entrenchment.
For Market Incumbents: Pre-empt pharmaceutical substitution by deepening ophthalmology practice dispensing relationships in Boston and Philadelphia clinical clusters. Secure backward integration into marigold cultivation regions in India to insulate formulation costs from agricultural commodity cycles. EFSA claim authorization investments represent the critical defensive lever against generic wellness-positioned competitors retreating from pharmacy shelves. For New Entrants and Emerging Players: Pursue Brazil's underpenetrated retail environment through ANVISA functional food regulatory pathways before incumbent portfolio expansion. Target millennial blue-light positioning in South Korea and United Kingdom markets with digital-native subscription models bypassing traditional pharmacy markups. Telehealth-adjacent eye screening integrations offer the most penetrable go-to-market angle for automated replenishment capture. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational consumer health conglomerates seeking to divest non-core supplement portfolios lacking EFSA-aligned substantiation. Long-term viability hinges on clinical data asset accumulation rather than brand equity alone. Watch for FDA structure-function claim enforcement tightening as the inflection signal separating substantiated from generic-positioned assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Kemin Industries' captive Indian marigold sourcing insulates FloraGLO supply from agricultural volatility. |
| EFSA Health Claim Authorization | Approved substantiation under EU Regulation 1924/2006 secures German and French pharmacy shelf access. |
| Direct-to-Consumer Subscription Launch | Automated replenishment models in the United States bypass CVS and Walgreens margin stacking entirely. |
| Microencapsulation Technology Licensing | Dutch and California startups compress capital requirements for mid-tier brands entering powder formats. |
| Blue Light Positioning Extension | South Korean digital professional targeting expands addressable population beyond aging AMD demographics. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with ophthalmology practice administrators, geriatric care procurement directors, pharmacy chain category buyers, and contract manufacturing executives; and secondary validation through FDA cGMP inspection records, EFSA health claim authorization databases, Japanese Consumer Affairs Agency FOSHU registrations, and customs trade data for marigold extract flows. Bottom-up SKU-level volume triangulation against top-down demographic prevalence modeling anchored projection integrity.
Forecast inputs span lutein and omega-3 fatty acid product types, age-related macular degeneration and dry eye relief applications, pharmacy and eye care clinic end users, and online retailer versus healthcare provider distribution channels across the analysis window. CAGRs derive from segment-level growth rate blending with population aging trajectories and clinical guideline adoption curves. AREDS2 protocol penetration rates and omega-3 dry eye prescription integration patterns serve as industry-specific demand drivers.
Sensitivities concentrate around EFSA claim authorization timeline shifts, Indian monsoon disruption to marigold harvests, and pharmaceutical dry eye therapy pricing competition. Forecasts reflect documented assumptions on regulatory substantiation thresholds and clinical endorsement conversion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
US and China Glucose Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
Global Synbiotics Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
Medicinal Mushrooms Market
Nutraceuticals
Fish-Oil Based Drugs Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
High Potency Apis Market
Nutraceuticals
North America Collagen Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
Piracetam Market
Nutraceuticals
Oxiracetam Market
Nutraceuticals
Cordyceps Militaris Extract Market
Nutraceuticals
Nattokinase Market
Nutraceuticals
Cordyceps Sinensis and Militaris Market