
 Postbiotics Market | 2026-2036
Postbiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Postbiotics Market Intelligence
Japan is fragmenting postbiotic manufacturing capacity across Tokyo and Osaka biotech corridors. DSM-Firmenich AG leverages its nutraceutical ingredient platform to dominate precision fermentation of metabolite concentrates. Kerry Group plc sustains R&D intensity in cell wall component extraction for immune-support applications. Cargill, Incorporated anchors North American supply through backward integration into corn-derived prebiotic feedstocks that pair with postbiotic formulations.
Postbiotics comprise non-viable microbial cells, cell fragments, or metabolites that confer health benefits without colonizing the host gut, typically manufactured through controlled fermentation followed by heat inactivation or enzymatic lysis to preserve bioactive integrity. Metabolites and short-chain fatty acids command the deepest margin pools due to their concentration requirements and clinical validation burden for digestive health positioning. Functional beverages represent the fastest-growing delivery form as personal care brands and dietary supplement manufacturers seek format differentiation beyond standard capsules and powders.
EFSA novel food regulations in Europe, FDA GRAS self-affirmation pathways in the United States, and Japan's FOSHU framework under METI collectively shape product standards, claims substantiation, and cross-border market access timelines for postbiotic suppliers. The EU Green Deal's biorefinery incentives are redirecting fermentation capacity toward sustainable feedstock utilization, tightening compliance costs for non-European exporters. Stakeholders must monitor regulatory divergence on viable-versus-non-viable microbial definitions to avoid reformulation costs and market exclusion.
Market Dynamics
Cell-free fermentation technology is collapsing production economics for heat-killed microbial preparations, compressing cost structures while EFSA novel food guidance in Europe and METI-backed functional claims in Japan simultaneously expand addressable regulatory pathways for bioactive metabolite concentrates.
Growth Catalysts
- Japan's FOSHU framework:METI streamlined approval for non-viable probiotic health claims, accelerating functional food launches in Tokyo and Osaka biotech corridors.
- Metabolite concentration demand:Short-chain fatty acid preparations for digestive health positioning command premium formulation slots in functional beverage pipelines.
- EU Green Deal biorefinery incentives:Fermentation capacity redirection toward sustainable feedstock utilization creates compliant supply anchors for European functional food producers.
Market Restraints
- Clinical validation burden:EFSA novel food substantiation requirements impose multi-year timelines and substantial toxicology investment for metabolite concentrates seeking digestive health positioning.
- Feedstock supply concentration:North American corn-derived prebiotic supply chains face weather volatility and ethanol competition, squeezing backward-integrated postbiotic formulators.
- Heat inactivation technical limits:Enzymatic lysis preservation methods remain capital-intensive at scale, constraining bioactive integrity in high-volume manufacturing.
Strategic Opportunities
- FDA GRAS self-affirmation pathway:US regulatory flexibility enables faster market entry for cell wall component extracts targeting immune-support applications compared to European novel food routes.
- Functional beverage format expansion:Personal care brands and dietary supplement manufacturers seek liquid delivery differentiation beyond capsule and powder saturation.
- Precision fermentation convergence:Integration of metabolomics analytics with controlled fermentation unlocks custom bioactive profiling for condition-specific formulations.
Industry Challenges
- Fermentation scale-up talent scarcity:Specialized bioprocess engineers capable of optimizing cell-free systems command premium compensation, constraining mid-tier manufacturer expansion.
- Cross-border claim harmonization:Divergent viable-versus-non-viable microbial definitions between EFSA, FDA, and METI frameworks force parallel formulation development for multi-regional launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postbiotics Market |
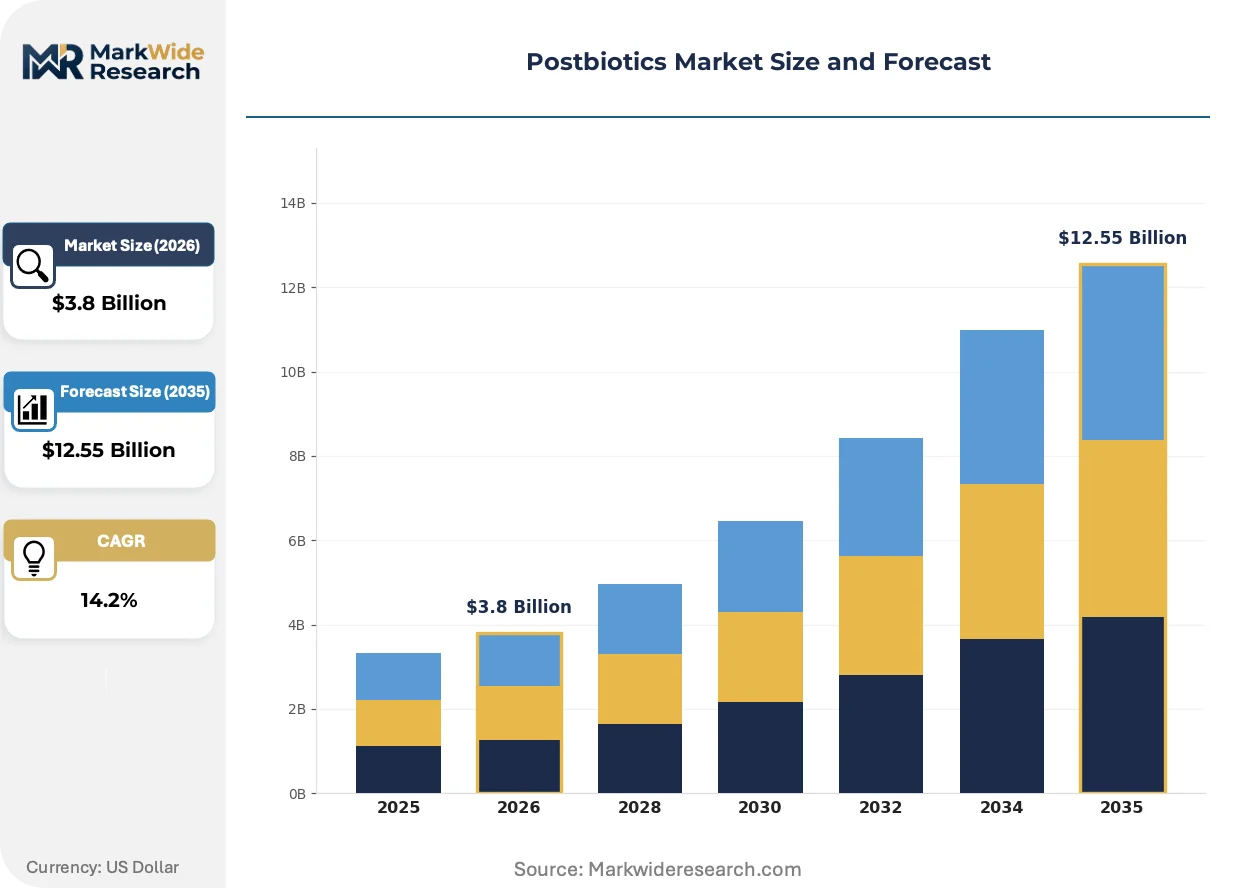
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metabolites, Cell Wall Components, Enzymes, Short-Chain Fatty Acids, Exopolysaccharides Application: Digestive Health, Immune Support, Skin Care, Weight Management, Oral Health End User: Dietary Supplement Manufacturers, Functional Food Producers, Personal Care Brands, Pharmaceutical Companies, Animal Nutrition Firms Delivery Form: Capsules, Powders, Liquid Concentrates, Tablets, Functional Beverages |
| Companies Covered | DSM-Firmenich AG, MCLS Europe B.V., Archer-Daniels-Midland Company, Sabinsa Corporation, Phileo by Lesaffre, Cargill, Incorporated, Kerry Group plc, Lallemand Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postbiotics Market Strategic Shifts & Innovations
Biomanufacturing platforms are compressing development cycles while regulatory jurisdictions compete to establish dominant standards for bioactive metabolite classification and health claim substantiation.
Continuous flow fermentation systems are collapsing batch-to-batch variability in metabolite yield consistency. Functional beverage manufacturers in Germany and France are adopting these platforms to secure supply chain predictability. The technology is collapsing quality assurance overhead previously absorbed by extensive release testing protocols.
EFSA's evolving novel food guidance on heat-treated microbial biomass is tightening compositional disclosure requirements for postbiotic preparations. European functional food producers must now quantify cell wall fragment profiles beyond aggregate non-viable cell counts. Metabolite concentrate suppliers with pre-existing analytical infrastructure are capturing formulation partnerships that commodity biomass providers cannot service.
Ingredient buyers are consolidating supplier relationships around vertically integrated fermentation operators with captive analytical capabilities. Dietary supplement contract manufacturers are displacing spot-market procurement of commodity postbiotic powders with multi-year supply agreements bundling bioactive characterization. Japan's METI-registered functional food producers demonstrate the most advanced procurement sophistication, specifying metabolite potency tiers rather than generic non-viable cell counts.
Postbiotics Market Segmentation
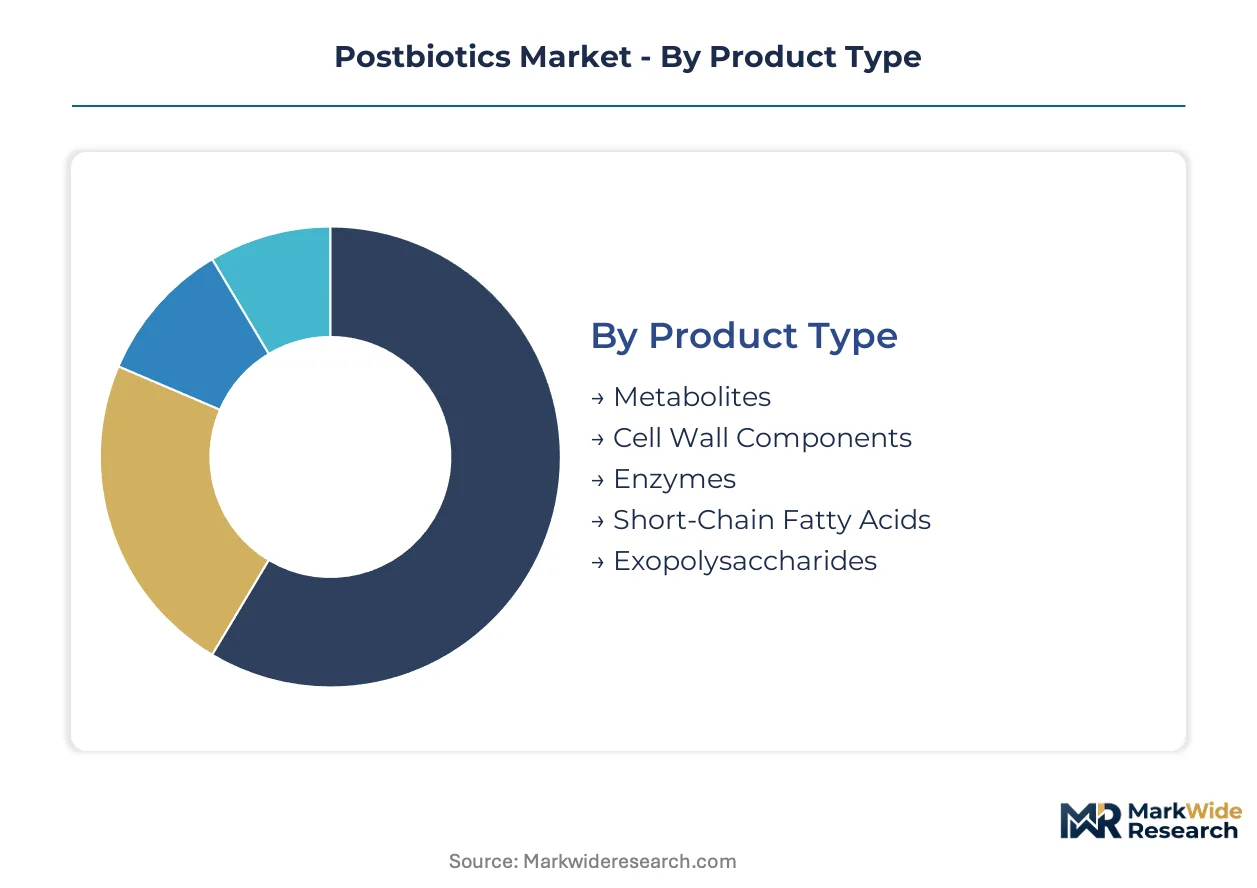
Postbiotics fragment across bioactive classes, therapeutic targets, and delivery technologies that each carry distinct manufacturing economics and regulatory substantiation burdens. Suppliers configure production platforms around specific segment requirements rather than serving interchangeable commodity demand.
Product Type:
Cost tier stratification separates precision-fermented metabolite concentrates from commodity biomass preparations.
- Metabolites:Concentrated bioactive compounds including organic acids and peptides manufactured through controlled fermentation with metabolomics-guided extraction. Functional beverage pipelines in Japan and Germany absorb the majority of high-potency output for digestive health positioning.
- Short-Chain Fatty Acids:Butyrate, propionate, and acetate preparations requiring cryogenic stabilization and enteric coating for bioavailability. EFSA novel food substantiation timelines stretch longest for this segment due to toxicity data requirements.
- Cell Wall Components:Peptidoglycan and lipoteichoic acid fragments from enzymatic lysis targeting immune modulation.
- Enzymes:Cell-free fermentation outputs with catalytic activity preserved through spray-drying optimization.
- Exopolysaccharides:High-molecular-weight fermentation byproducts with viscosity and moisture-retention properties suited to topical applications.
Metabolites command the established base. The steepest expansion runs through Short-Chain Fatty Acids.
Application:
Application focus determines clinical validation investment and permissible claim language across regulatory jurisdictions.
- Digestive Health:The primary substantiation target for postbiotic bioactives, with gut barrier function and microbiome modulation claims supported by transit time and inflammation biomarker studies. Japanese FOSHU approvals concentrate heavily in this space.
- Immune Support:Gut-associated lymphoid tissue targeting through pattern-recognition receptor activation, requiring cytokine response data and challenge study designs that extend development timelines.
- Skin Care:Topical microbiome modulation and anti-inflammatory positioning for atopic dermatitis and barrier repair formulations.
- Weight Management:Metabolic signaling claims around satiety and energy expenditure with heavier evidentiary burdens than digestive endpoints.
- Oral Health:Cariogenic bacteria inhibition through bioactive metabolite delivery in functional beverages and lozenges.
Digestive Health anchors current revenue. Immune Support is climbing the fastest as cell wall component extraction advances.
End User:
Customer type dictates procurement sophistication, specification granularity, and contract structure preferences.
- Functional Food Producers:German and French manufacturers lead procurement of heat-killed microbial preparations under EFSA novel food guidance, specifying metabolite potency tiers and cell wall fragment profiles rather than aggregate biomass metrics.
- Dietary Supplement Manufacturers:Contract manufacturers displacing spot-market procurement with multi-year supply agreements bundling bioactive characterization and release testing protocols.
- Personal Care Brands:Emerging demand for exopolysaccharide and metabolite concentrates in microbiome-friendly topical formulations.
- Pharmaceutical Companies:Exploratory development of postbiotic drug candidates requiring GMP fermentation and IND-enabling toxicology packages.
- Animal Nutrition Firms:Feed additive applications for gut health in poultry and swine production, with lower specification thresholds than human applications.
Functional Food Producers dominate contract value. Personal Care Brands are gaining share fastest as topical microbiome positioning expands.
Delivery Form:
Format selection constrains bioactive stability requirements and manufacturing partner qualifications.
- Functional Beverages:Liquid delivery systems requiring acid stability and shelf-life validation for metabolite concentrates, with German and French manufacturers adopting continuous flow fermentation platforms to secure supply predictability.
- Liquid Concentrates:Bulk bioactive suspensions for downstream formulation, demanding cold chain integrity and oxygen barrier packaging.
- Capsules:Enteric-coated and standard gelatin formats for targeted release in the small intestine.
- Powders:Spray-dried and freeze-dried preparations with flowability specifications for tableting and sachet filling.
- Tablets:Compressed formats with disintegration time requirements and excipient compatibility constraints.
Capsules hold the established volume base. Functional Beverages show the steepest trajectory as format differentiation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's FOSHU framework anchors Japan's dominance in postbiotic functional claims, while EFSA novel food guidance and FDA GRAS pathways create divergent regulatory entry costs across major markets. Manufacturing capacity clusters around fermentation biotechnology corridors in three continents.
Japan
Tokyo and Osaka biotech corridors fragment manufacturing capacity across precision fermentation operators. METI streamlined approval for non-viable probiotic health claims under FOSHU, accelerating functional food launches. Japanese functional food producers specify metabolite potency tiers rather than generic biomass metrics.
Germany
Functional food producers in Bavaria and North Rhine-Westphalia scale postbiotic procurement under EFSA novel food guidance. The EU Green Deal's biorefinery incentives redirect fermentation capacity toward sustainable feedstock utilization. Continuous flow fermentation adoption concentrates in Frankfurt-Rhine-Main chemical clusters.
United States
FDA GRAS self-affirmation pathways enable faster market entry for immune-support cell wall extracts than European routes. Corn-derived prebiotic supply chains in Iowa and Illinois face ethanol competition and weather volatility. Chicago and Minneapolis dietary supplement contract manufacturers displace spot-market procurement with multi-year bioactive characterization agreements.
France
Heat-killed microbial preparation demand concentrates among Île-de-France functional beverage manufacturers. EFSA novel food substantiation requirements impose multi-year toxicology timelines for metabolite concentrates. Lyon biotech clusters develop enzymatic lysis preservation methods for bioactive integrity.
Netherlands
DSM-Firmenich AG leverages its Randstad nutraceutical ingredient platform for precision fermentation of metabolite concentrates. Rotterdam biorefinery infrastructure supports EU Green Deal compliance for sustainable feedstock utilization. Wageningen research clusters advance cell-free fermentation cost reduction.
Postbiotics Market Key Industry Players
Specialized fermentation biotechs and diversified ingredient conglomerates split the market between precision metabolite concentrates and commodity biomass preparations. Consolidation pressure intensifies as EFSA disclosure requirements favor operators with captive analytical infrastructure. Three archetypes dominate: vertically integrated fermentation platforms, nutraceutical ingredient conglomerates with backward prebiotic control, and contract manufacturing specialists. Competitive moves center on multi-year supply agreement bundling and continuous flow fermentation technology licensing.
Within the diversified ingredient tier, DSM-Firmenich AG and Cargill, Incorporated exemplify contrasting scale strategies, while Kerry Group plc occupies a position bridging fermentation technology and extraction expertise. Dutch and Irish headquartered operators anchor European supply relationships, whereas North American conglomerates leverage agricultural feedstock integration. These three entities represent the dominant competitive anchors shaping procurement sophistication standards.
| Leading Market Players |
|---|
| DSM-Firmenich AG |
| MCLS Europe B.V. |
| Archer-Daniels-Midland Company |
| Sabinsa Corporation |
| Phileo by Lesaffre |
| Cargill, Incorporated |
| Kerry Group plc |
| Lallemand Inc. |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Single-source dependency on North American corn-derived prebiotic feedstocks determines both pricing tier spreads and supply chain shape, with ethanol competition and weather volatility squeezing backward-integrated formulators while precision-fermented metabolite concentrates command premium positioning.
Pricing Analysis
Japanese buyers pay substantial premiums over German and French procurement for metabolite potency-tier specifications under METI's FOSHU framework. Three-tier pricing structure across premium, standard, and economy levels separates precision-fermented concentrates from commodity biomass preparations, with EFSA novel food substantiation costs driving premium tier expansion. Cost compression in standard-tier heat-killed preparations is intensifying because cell-free fermentation technology collapses production economics. Dietary supplement contract manufacturers show highest price sensitivity, while Japanese functional food producers demonstrate least sensitivity due to metabolite potency-tier procurement sophistication.
Supply Chain Analysis
Extended payment terms from Dutch and Irish ingredient conglomerates to German and French functional food producers are reshaping working capital requirements across the value chain. Supply concentrates in the Netherlands, Japan, and the United States, with Rotterdam biorefinery infrastructure, Tokyo-Osaka biotech corridors, and Iowa-Illinois corn belts anchoring regional production. Raw material dependencies center on corn-derived prebiotics, fermentation feedstocks, and cryogenic stabilization agents for short-chain fatty acid preservation. Single-source vulnerability runs through North American corn supply chains facing ethanol competition. Distribution runs through multi-year supply agreements bundling bioactive characterization rather than spot-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from the clinical validation burden cycle, with EFSA novel food guidance timelines compressing as metabolomics analytics accelerate substantiation pathways.
For Market Incumbents: Build regulatory data moats through preemptive EFSA novel food dossier investment before disclosure requirements tighten further. DSM-Firmenich AG and Kerry Group plc should expand captive analytical infrastructure to capture formulation partnerships commodity biomass providers cannot service. Cargill must defend against fermentation scale-up talent scarcity by anchoring bioprocess engineering compensation premiums in Minneapolis and Chicago clusters. For New Entrants and Emerging Players: Establish a beachhead in functional beverage format expansion where personal care brands seek liquid delivery differentiation beyond capsule saturation. White-space targets include topical microbiome applications for personal care brands and animal nutrition feed additives with lower specification thresholds. The most penetrable entry point is exopolysaccharide concentrates for skin care, with go-to-market through contract manufacturing partnerships bundling release testing protocols. For Investors and Strategic Acquirers: EFSA's evolving novel food guidance on heat-treated microbial biomass reshapes the acquisition landscape toward vertically integrated fermentation operators with pre-existing analytical infrastructure. Long-term viability centers on precision fermentation convergence with metabolomics analytics unlocking custom bioactive profiling. Target acquisition archetypes are mid-tier European manufacturers with continuous flow fermentation licensing potential. The signal to watch is METI FOSHU approval velocity for non-viable probiotic health claims as Japan's regulatory leadership indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Fermentation Adoption | German and French manufacturers secure supply chain predictability through batch-to-batch yield consistency. |
| EFSA Novel Food Dossier Investment | Preemptive toxicology data packages compress multi-year substantiation timelines for metabolite concentrates. |
| Multi-Year Supply Agreement Bundling | Dietary supplement contract manufacturers displace spot-market procurement with bioactive characterization contracts. |
| Precision Fermentation Convergence | Integration of metabolomics analytics unlocks custom bioactive profiling for condition-specific formulations. |
| Functional Beverage Format Expansion | Liquid delivery systems capture format differentiation beyond saturated capsule and powder markets. |
Research Approach
A standing panel of fermentation bioprocess engineers, functional food procurement directors, regulatory affairs specialists, and dietary supplement contract manufacturers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from EFSA novel food guidance documents, METI FOSHU registration databases, FDA GRAS notification filings, and EU Green Deal biorefinery incentive records. Bottom-up segment sizing triangulated against top-down market envelope checks.
Scenario-bracketing around regulatory approval velocity, feedstock price volatility, and fermentation technology adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, therapeutic application, end-user category, and delivery format. CAGRs were derived from growth driver elasticity analysis against baseline penetration assumptions. Industry-specific forecast inputs incorporated EFSA disclosure requirement evolution and METI functional claim streamlining.
Stress conditions across corn price volatility, regulatory timeline extension, and precision fermentation scale-up delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EFSA novel food guidance stability, METI FOSHU framework continuity, and cell-free fermentation cost reduction trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
Native Collagen Market
Nutraceuticals
LAMEA Digestive Enzymes Market
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Chondroitin Market
Nutraceuticals
Asia-Pacific Effervescent Tablet Market
Nutraceuticals
South America Pet Nutraceuticals Market
Nutraceuticals
PMS and Menstrual Health Supplements Market
Nutraceuticals
Magtein Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Pet Nutraceuticals Market
Nutraceuticals
Europe Nutricosmetics Market
Nutraceuticals
Fish-Oil Based Drugs Market
Nutraceuticals
Global Synbiotics Market
Nutraceuticals
North America Collagen Market
Nutraceuticals
Micro-Ecological Regulators Market