
 Bone and Teeth Supplements Market | 2026-2036
Bone and Teeth Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Bone and Teeth Supplements Market Analysis
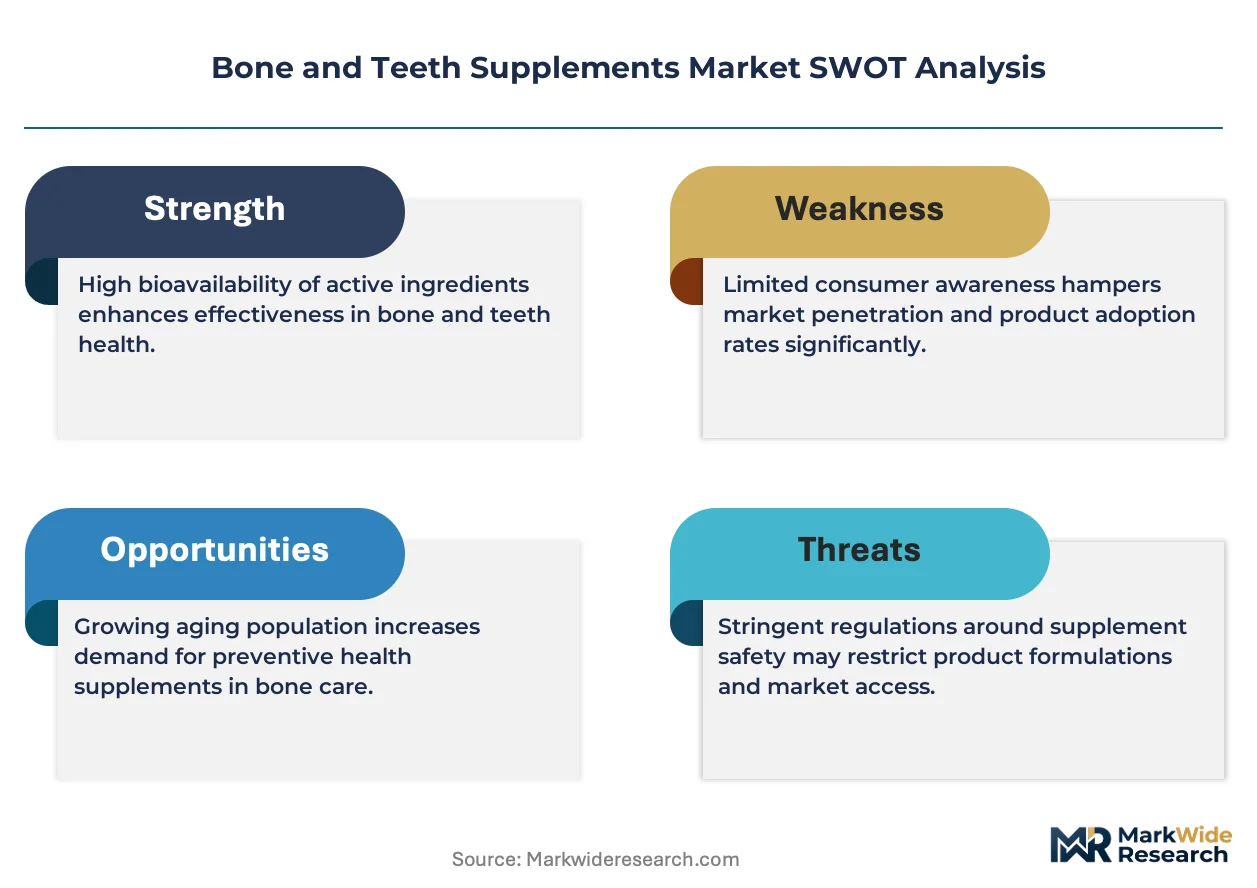
Direct-to-consumer nutrigenomics testing is fragmenting how bone and teeth supplement brands formulate and market their products, replacing one-size-fits-all SKUs with personalized micronutrient stacks. Thorne leverages its physician-dispensed channel to sustain premium positioning in practitioner-grade mineral complexes. NOW Foods anchors the mass-market tier through vertical control over raw material sourcing. Garden of Life differentiates via certified organic and non-GMO supply chains that command shelf space in natural retail.
Bone and teeth supplements comprise bioavailable mineral salts, fat-soluble vitamins, and co-factors engineered to support skeletal mineralization, dental enamel integrity, and calcium homeostasis, with formulations typically specifying elemental calcium content per serving and vitamin D3 IU potency for therapeutic equivalence. The calcium supplements segment dominates volume due to established osteoporosis prevention protocols, while gummies represent the fastest-growing form as palatability drives pediatric and elderly compliance. Online retail channels capture expanding margin pools through subscription models that reduce customer acquisition costs.
FDA's Current Good Manufacturing Practices and the FTC's substantiation doctrine jointly elevate barriers for new entrants lacking clinical validation infrastructure. The USDA organic seal and NSF International certification operate as parallel gatekeeping mechanisms that influence pharmacy and health store stocking decisions. Stakeholders must monitor evolving state-level scope-of-practice laws that determine whether dentists and pharmacists can recommend therapeutic doses beyond general wellness thresholds.
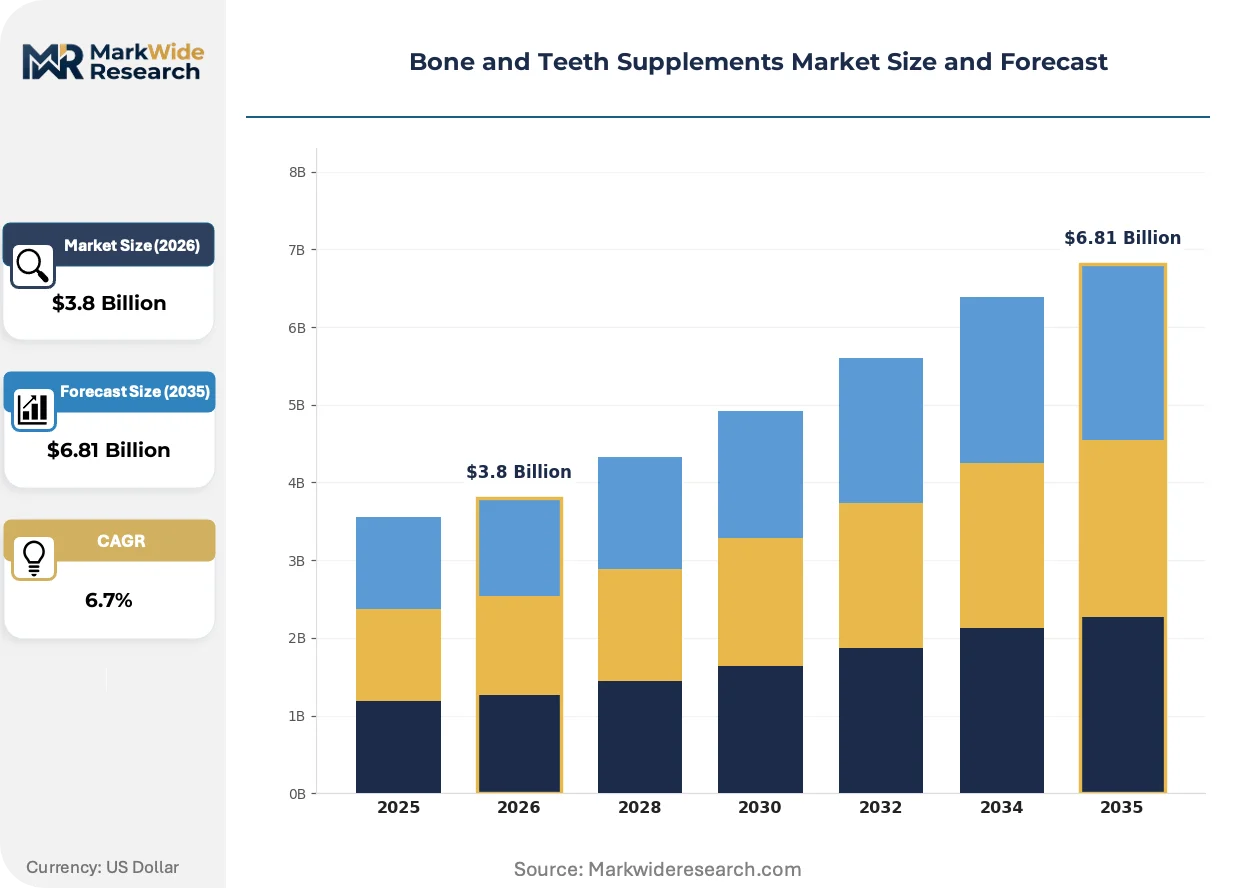
Market Dynamics
Nutrigenomics testing is fragmenting bone and teeth supplement formulation, replacing standardized SKUs with personalized micronutrient stacks that demand flexible manufacturing infrastructure and real-time supply chain reconfiguration.
Growth Catalysts
- Aging suburban demographics:Preventive skeletal health protocols among United States retirees expand calcium and vitamin D3 consumption beyond therapeutic deficiency treatment into wellness maintenance routines.
- FDA Current Good Manufacturing Practices:Quality verification tightening elevates compliant manufacturers above informal competitors, concentrating shelf space in pharmacy and health store channels.
- Gummy format innovation:Palatability engineering drives pediatric and elderly compliance, converting non-adherent populations into recurring purchasers through taste-masked mineral delivery systems.
Market Restraints
- Elemental calcium raw material volatility:Oyster shell and limestone-derived carbonate sources face marine ecosystem harvesting restrictions and quarry permitting delays that compress margin predictability.
- Certification infrastructure costs:NSF International and USDA organic validation require dedicated quality assurance personnel and third-party laboratory relationships that exclude sub-scale entrants.
- Bioavailability ceiling:Calcium citrate malate achieves superior absorption rates over carbonate forms, but manufacturing complexity limits cost-competitive scaling for mass-market positioning.
Strategic Opportunities
- Subscription commerce penetration:Direct-to-consumer recurring revenue models reduce customer acquisition costs and capture lifetime value through automated replenishment algorithms.
- Practitioner channel expansion:Physician-dispensed mineral complexes command premium pricing through clinical credibility and insurance-adjacent reimbursement positioning.
- Certified organic supply chains:Non-GMO verification and regenerative agriculture sourcing unlock natural retail shelf space and price premiums in health-conscious consumer segments.
Industry Challenges
- Formulation talent scarcity:Food science PhDs with mineral chelation expertise and regulatory submission experience command compensation premiums that strain mid-cap R&D budgets.
- Dual-label compliance timelines:Simultaneous FDA structure-function claim substantiation and FTC advertising review create launch delays that miss seasonal demand windows.
- State scope-of-practice fragmentation:Inconsistent dentist and pharmacist prescribing authority across jurisdictions complicates territory-by-territory sales force deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone and Teeth Supplements Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Supplements, Vitamin D3, Phosphorus, Magnesium Form: Tablets, Capsules, Powder, Gummies End User: Adults, Children, Elderly, Athletes Distribution Channel: Online Retail, Pharmacies, Health Stores, Supermarkets |
| Companies Covered | Nature's Bounty, Garden of Life, NOW Foods, Solgar, GNC Holdings, Amway, Herbalife, Thorne, Pure Encapsulations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone and Teeth Supplements Market Emerging Trajectories
Digital health integration is restructuring how bone and teeth supplements are discovered, dosed, and monitored, collapsing the traditional physician-pharmacy-retail triad into algorithm-driven recommendation engines.
Artificial intelligence platforms are virtualizing personalized supplement stacking by analyzing genetic polymorphisms, serum vitamin D levels, and dietary intake patterns to generate individualized calcium-magnesium-vitamin K2 ratios. Long-term care facility administrators and concierge medicine practices are piloting these systems to reduce polypharmacy conflicts. This virtualization compresses the SKU proliferation burden onto contract manufacturers while shifting value capture toward data analytics providers.
EMA's novel food classification pathway for algae-derived calcium is creating accelerated market entry mechanisms for marine-sourced mineral alternatives. European manufacturers gain twelve-to-eighteen month timeline advantages over traditional novel food applications. German and Dutch ingredient suppliers are capturing first-mover shelf space in natural retail channels ahead of terrestrial carbonate competitors.
Subscription bundling is displacing single-SKU purchasing as the dominant household replenishment model. Amazon Subscribe & Save and specialized wellness platforms aggregate bone health, dental enamel support, and general multivitamin categories into personalized quarterly shipments. United States suburban aging demographics exhibit highest conversion rates, with sixty-day replenishment cycles replacing opportunistic retail purchasing.
Bone and Teeth Supplements Market Segmentation
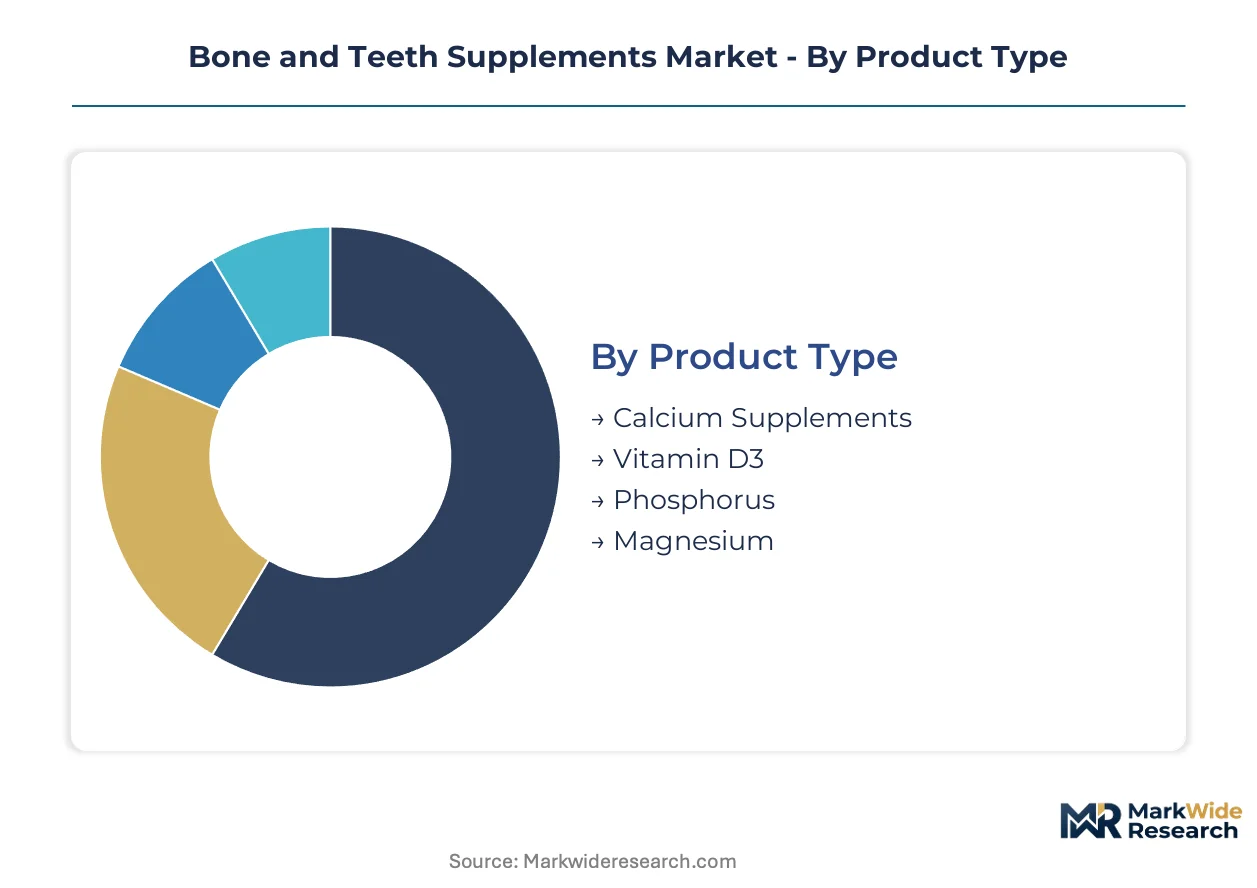
Segmentation in bone and teeth supplements determines formulation priorities, shelf placement economics, and compliance requirements across divergent consumption contexts. Cycle times vary dramatically: pediatric gummies turn inventory weekly while practitioner-dispensed capsules sit for months. Understanding these velocity differentials shapes capital allocation and manufacturing slotting decisions.
Product Type:
Calcium Supplements command the longest production cycles due to raw material sourcing complexity, while Vitamin D3 SKUs rotate fastest through automated encapsulation lines.
- Calcium Supplements:Carbonate, citrate, and chelated forms deliver elemental calcium in doses calibrated to osteoporosis prevention protocols. Long-term care facilities in the United States stock therapeutic-grade tablets for geriatric populations, though marine-derived sourcing faces tightening ecosystem harvesting restrictions.
- Vitamin D3:Cholecalciferol formulations specify IU potency for therapeutic equivalence with prescription alternatives. Suburban aging demographics seeking preventive skeletal health solutions drive replenishment velocity through subscription channels.
- Phosphorus:Dicalcium phosphate and bone meal derivatives support remineralization alongside calcium cofactors. Sports nutrition applications target athletes with high-turnover bone remodeling demands.
- Magnesium:Oxide, citrate, and glycinate variants modulate calcium absorption kinetics and parathyroid hormone regulation. Natural retail channels favor chelated forms for bioavailability positioning.
Calcium Supplements anchors the volume base while Vitamin D3 gains share at the steepest rate.
Form:
Cost tiers separate pharmaceutical-grade tablets from mass-market gummies, with powder formats occupying the value-engineered middle.
- Tablets:Compressed mineral matrices with disintegration specifications for gastric release. Pharmacy channels favor scored tablets for dose-splitting flexibility in elderly compliance protocols.
- Capsules:Gelatin or vegetable-based shells encasing powder or beadlet formulations. Physician-dispensed channels capture premium pricing through clinical credibility positioning.
- Gummies:Pectin or gelatin matrices with taste-masked mineral delivery systems. Palatability engineering converts non-adherent pediatric and elderly populations into recurring purchasers.
- Powder:Unflavored or flavored bulk mineral blends for beverage fortification. Fitness and wellness segments favor dose customization flexibility.
Tablets dominate absolute tonnage while Gummies climb the fastest on compliance-driven household penetration.
End User:
Application contexts separate therapeutic deficiency treatment from wellness maintenance, with athletes representing a discrete performance-optimization niche.
- Adults:Working-age consumers pursuing preventive skeletal health protocols through multivitamin-plus-mineral combinations. Online retail subscription models capture this segment through automated replenishment algorithms.
- Elderly:Geriatric populations in long-term care facilities and aging suburban demographics with elevated fracture risk profiles. FDA Current Good Manufacturing Practices compliance filters informal competitors from this quality-sensitive segment.
- Children:Pediatric bone development support with palatability-engineered delivery systems. Gummy formats dominate this compliance-driven category.
- Athletes:High-impact sport participants with elevated bone remodeling rates and stress fracture prevention needs. Sports nutrition specialty retailers stock effervescent and rapid-dissolve formats.
Elderly users concentrate the highest per-capita spend while Adults expand the subscriber base most rapidly.
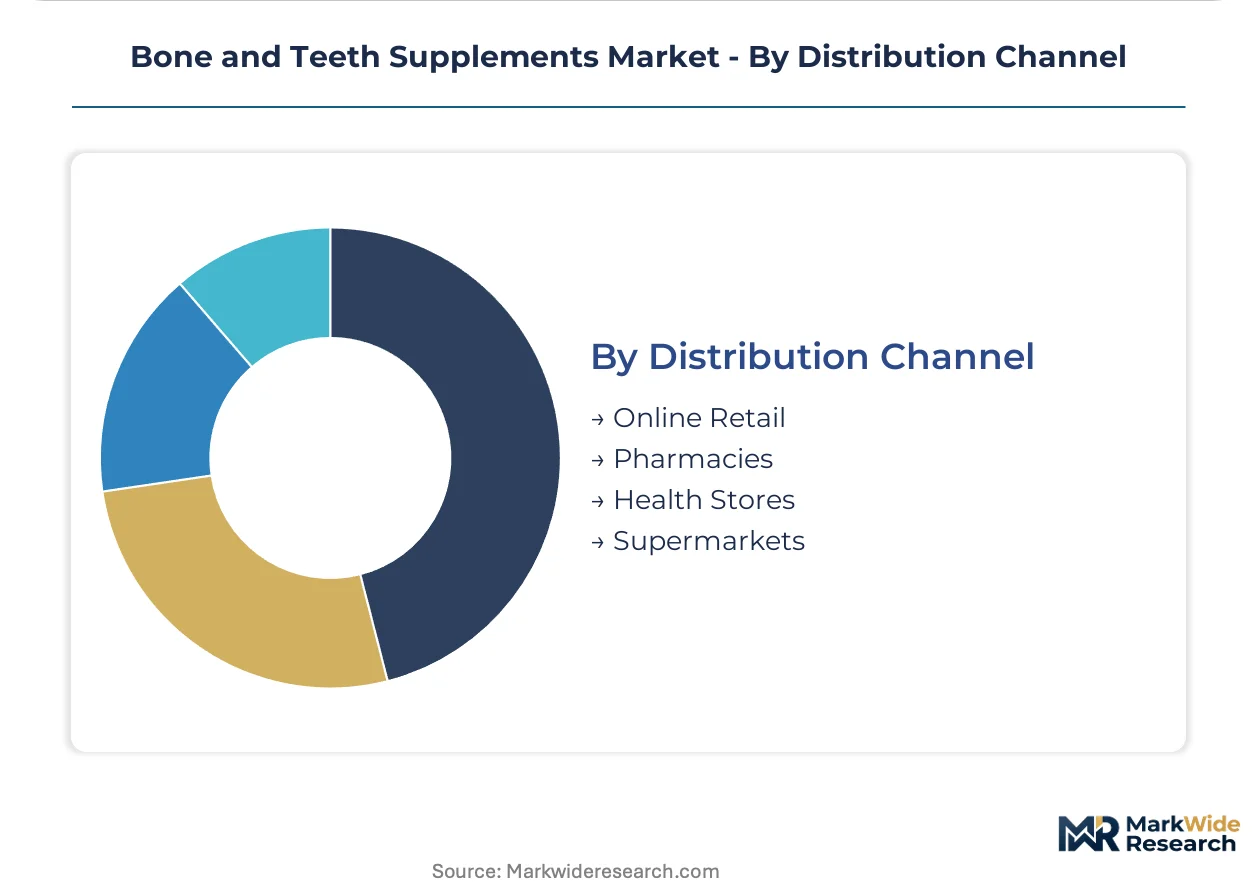
Distribution Channel:
Margin structures separate direct-to-consumer subscriptions from brick-and-mortar retail with its certification-gated shelf access.
- Online Retail:Direct-to-consumer platforms with subscription bundling and algorithm-driven replenishment. Customer acquisition cost economics favor sixty-day replenishment cycles over opportunistic purchasing.
- Pharmacies:Chain and independent drugstores with NSF International certification requirements for stocking decisions. Insurance-adjacent positioning supports practitioner-grade mineral complexes.
- Health Stores:Natural retail channels with USDA organic and non-GMO verification as parallel gatekeeping mechanisms. Regenerative agriculture sourcing unlocks price premiums in health-conscious segments.
- Supermarkets:Mass-market placement with vertical control over raw material sourcing enabling cost-competitive positioning. NOW Foods anchors this tier through captive supply chains.
Pharmacies retain the highest trust premiums while Online Retail captures the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German algae-calcium suppliers export to United States natural retail channels under accelerated EMA novel food pathways, while Chinese carbonate producers serve Southeast Asian contract manufacturers facing marine ecosystem harvesting restrictions.
United States
Aging suburban demographics in Florida and Arizona drive preventive skeletal health consumption through subscription commerce models. FDA Current Good Manufacturing Practices enforcement elevates compliant manufacturers above informal competitors in pharmacy channels. Long-term care facilities in Texas and California concentrate geriatric per-capita spending on therapeutic-grade mineral complexes.
Germany
EMA novel food classification for algae-derived calcium accelerates marine-sourced mineral entry timelines against terrestrial carbonate competitors. German and Dutch ingredient suppliers capture first-mover shelf space in natural retail ahead of limestone-derived alternatives. Industrial clusters around Hamburg and Rotterdam coordinate marine calcium extraction with regenerative agriculture certification protocols.
China
Limestone quarry permitting delays and marine ecosystem harvesting restrictions compress margin predictability for carbonate raw material sourcing. SAMR dietary supplement labeling requirements tighten quality verification protocols for domestic and export-bound production. Manufacturing concentration in Shandong and Jiangsu provinces supplies Southeast Asian contract manufacturers with cost-competitive mineral salts.
Japan
PMDA oversight of functional food claims shapes formulation substantiation requirements for bone health positioning. METI standards for bioavailability testing influence regional R&D investment patterns. Tokyo-Osaka corridor houses specialist mineral chelation expertise serving domestic and export markets.
India
FSSAI dietary supplement regulations create compliance thresholds for domestic market entry amid rising preventive health awareness. CDSCO oversight intersects with traditional medicine distribution channels for bone health formulations. Maharashtra and Gujarat pharmaceutical clusters manufacture cost-competitive mineral complexes for Middle East and African export markets.
Bone and Teeth Supplements Market Vendor Landscape
On the supply side, the industry is structured around three distinct capability tiers. Pharmaceutical-grade manufacturers with clinical validation infrastructure occupy premium positioning through practitioner channels. Mass-market specialists with vertical raw material control compete on cost-engineered carbonate formulations. Flexible contract manufacturers serve nutrigenomics-driven personalized stack providers requiring rapid SKU reconfiguration. Dominant competitive moves include certification-driven shelf access consolidation and subscription commerce infrastructure buildout.
Among practitioner-grade specialists, Thorne and Pure Encapsulations exemplify the clinical credibility archetype through physician-dispensed channel positioning. NOW Foods anchors the mass-market tier with cost-competitive carbonate sourcing. Garden of Life occupies the certified organic verification segment commanding natural retail price premiums.
| Leading Market Players |
|---|
| Nature's Bounty |
| Garden of Life |
| NOW Foods |
| Solgar |
| GNC Holdings |
| Amway |
| Herbalife |
| Thorne |
| Pure Encapsulations |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor shapes cost dynamics across the bone and teeth supplements market, concentrating supply leverage with German algae-calcium suppliers while downstream price differentiation separates practitioner-grade mineral complexes from mass-market carbonate formulations.
Pricing Analysis
Formulation-generation pricing gaps separate next-gen nutrigenomics-personalized stacks from current standardized SKUs and prior-gen basic carbonate tablets. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and clinical validation depth. Pricing pressure stems from elemental calcium raw material volatility as marine ecosystem harvesting restrictions tighten. Long-term care facilities exhibit lowest price sensitivity while mass-market suburban aging demographics show highest responsiveness to subscription discounting.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for carbonate raw material sourcing. Concentration in China, Germany, and the Netherlands anchors global mineral salt availability, with Shandong province limestone quarries and Hamburg marine extraction clusters feeding contract manufacturers. Oyster shell and algae-derived calcium dependencies create single-source vulnerability for bioavailable formulations. Distribution runs through direct-to-consumer subscription platforms, pharmacy chains with NSF certification requirements, and natural retail channels gating access via USDA organic verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nutrigenomics fragmentation creates white-space opportunities as personalized micronutrient stacks displace standardized formulations, opening niches for flexible manufacturers and data-analytics-enabled providers.
For Market Incumbents: Insulate market position by deepening captive supply of certified organic raw materials and securing exclusive practitioner channel partnerships with long-term care facility networks. FDA Current Good Manufacturing Practices enforcement elevates compliant manufacturers above informal competitors, making certification infrastructure a defensive moat against price-pressured entrants lacking clinical validation capabilities.
For New Entrants and Emerging Players: Subscription commerce infrastructure for aging suburban demographics represents the most penetrable entry point, with algorithm-driven replenishment algorithms capturing lifetime value through sixty-day cycles. Target white-space in pediatric gummy formulations with taste-masked mineral delivery systems, leveraging palatability engineering to convert non-adherent populations. Go-to-market through specialized wellness platforms rather than competing for pharmacy shelf space against entrenched brands.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap contract manufacturers with flexible SKU reconfiguration capabilities serving nutrigenomics-driven personalized stack providers. Long-term viability over a multi-year horizon hinges on data-analytics integration and subscription commerce infrastructure rather than traditional manufacturing scale. Monitor EMA novel food classification pathway expansion as signal for marine-sourced mineral alternative acceleration against terrestrial carbonate incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Commerce Infrastructure Buildout | Amazon Subscribe & Save and specialized wellness platforms capture recurring revenue from aging suburban demographics through automated replenishment algorithms. |
| Certified Organic Supply Chain Certification | USDA organic and non-GMO verification unlocks natural retail shelf space and price premiums in health-conscious consumer segments. |
| Practitioner Channel Partnership Expansion | Physician-dispensed mineral complexes command premium pricing through clinical credibility and insurance-adjacent reimbursement positioning. |
| Nutrigenomics Platform Integration | AI-driven personalized supplement stacking analyzes genetic polymorphisms and serum levels to generate individualized calcium-magnesium-vitamin K2 ratios. |
| Marine-Sourced Mineral Alternative Development | EMA novel food classification pathway for algae-derived calcium accelerates market entry timelines against terrestrial carbonate competitors. |
Methodological Framework
Desk research of FDA enforcement actions, EMA novel food classifications, and NSF International certification databases preceded structured interviews with formulation scientists at contract manufacturers, procurement directors at long-term care facility networks, and category buyers at natural retail chains. Primary fieldwork with supply chain managers and regulatory affairs specialists validated secondary findings on raw material sourcing patterns and compliance timelines. Bottom-up SKU velocity analysis and top-down channel revenue estimation were triangulated against trade data and customs records.
Assumptions held fixed include FDA Current Good Manufacturing Practices enforcement intensity and EMA novel food pathway processing timelines, while variables included state-level scope-of-practice law evolution and marine ecosystem harvesting restriction severity. The analytical framework modeled volume and value across product type, form, end user, and distribution channel dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macro demographic projections and channel shift elasticity parameters, with bioavailability ceiling constraints and certification infrastructure costs as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in freight rates, limestone quarry permitting velocity, or geriatric healthcare reimbursement policies would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and consumer subscription adoption patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Pet Herbal Supplements Market
Dietary Supplements
Glucosamine Salt Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Veterinary Dietary Supplements Market
Dietary Supplements
Cold and Flu Supplements Market
Dietary Supplements
Hair Supplements Market
Dietary Supplements
Serotonin Supplement Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Vitamin D Deficiency Treatment Market
Dietary Supplements
Alpha Lipoic Acid Market
Dietary Supplements
Womens Health and Beauty Supplements Market