
 Cartino Collagen Market | 2026-2036
Cartino Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Cartino Collagen Market Analytics
Precision enzymatic hydrolysis is rewriting how collagen peptides achieve bioactive peptide yields above ninety percent, enabling functional claims previously reserved for synthetic compounds. Gelita AG leverages captive bovine and porcine supply chains to sustain cost leadership across European nutraceutical contracts. Rousselot anchors its position through marine collagen specialization, competing directly with Nitta Gelatin Inc. in Asia-Pacific cosmetic ingredient tenders. Advanced BioMatrix, Inc. differentiates by dominating research-grade collagen matrices for three-dimensional cell culture applications in regenerative medicine.
Cartino Collagen comprises type I and type III collagen fibers extracted through controlled acid or enzymatic processing of bovine, porcine, or marine tissues, yielding molecular weights between two thousand and ten thousand Daltons for optimal intestinal absorption in functional nutrition applications. Its primary industrial purpose centers on providing structural scaffolding for dermal fillers, biodegradable sutures, and edible film formulations where thermal stability and triple-helix integrity determine performance. Hydrolyzed collagen captures the deepest margin pools in medical device coatings where endotoxin thresholds below zero point five EU per gram command certification premiums. Collagen peptides lead volume growth in nutraceutical gummies and ready-to-drink beauty beverages, while gelatin maintains mature demand in food emulsification despite slower expansion. Medical device applications represent the fastest-growing segment as surgeons adopt collagen hemostats and wound dressings with integrated antimicrobial agents.
EMA medical device regulation and EFSA health claim assessments shape product development timelines and label permissibility across European formulations. REACH chemical registration requirements and ISO 22442 standards for collagen sourced from animal tissues govern supply chain traceability and viral inactivation protocols. Stakeholders must monitor evolving EMA guidance on collagen-derived implantables and anticipate how EU Green Deal sourcing mandates will redirect raw material procurement toward certified sustainable fisheries and closed-loop rendering operations.
Market Dynamics
Precision enzymatic hydrolysis is compressing production timelines while elevating bioactive peptide yields above ninety percent, forcing manufacturers to retool extraction facilities or cede margin to specialized biotech suppliers.
Growth Catalysts
- EU REACH compliance:Tightening purity benchmarks for collagen imports are accelerating consolidation among certified suppliers capable of endotoxin thresholds below zero point five EU per gram.
- Functional nutrition:Hydrolyzed collagen procurement by nutraceuticals formulators is deepening as ready-to-drink beauty beverages and gummies capture shelf space in German and French retail channels.
- Rhine-Main biotechnology cluster:Dedicated extraction facilities serving pharmaceutical and medical device clients are concentrating technical talent and captive bovine supply chains within a two-hundred-kilometer radius.
Market Restraints
- Bovine tissue input volatility:Rendering industry consolidation and livestock disease surveillance protocols are compressing raw material availability during seasonal peaks.
- Marine collagen supply concentration:Certified sustainable fisheries certification remains limited to North Atlantic and Pacific Northwest operations, constraining volume scaling for cosmetic ingredient tenders.
- EFSA novel food approval pathway:Eighteen-to-twenty-four-month assessment timelines for new collagen sources are blocking formulation launches ahead of competitor windows.
Strategic Opportunities
- Regenerative medicine matrices:Three-dimensional cell culture applications are opening premium pricing tiers for research-grade collagen with defined fiber architecture and lot-to-lot consistency.
- EU Green Deal sourcing mandates:Closed-loop rendering operations and certified sustainable fisheries procurement are becoming bid prerequisites for public hospital and institutional contracts.
- Antimicrobial integration:Collagen hemostats and wound dressings with embedded ionic silver or chitosan are capturing surgeon preference in ambulatory surgical centers.
Industry Challenges
- ISO 22442 viral inactivation expertise:Documented TSE/BSE risk mitigation protocols require specialized quality assurance personnel that extraction facilities struggle to recruit and retain.
- EMA medical device regulation recertification:Collagen-derived implantables face tightened clinical evidence requirements that extend approval timelines and inflate regulatory affairs overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cartino Collagen Market |
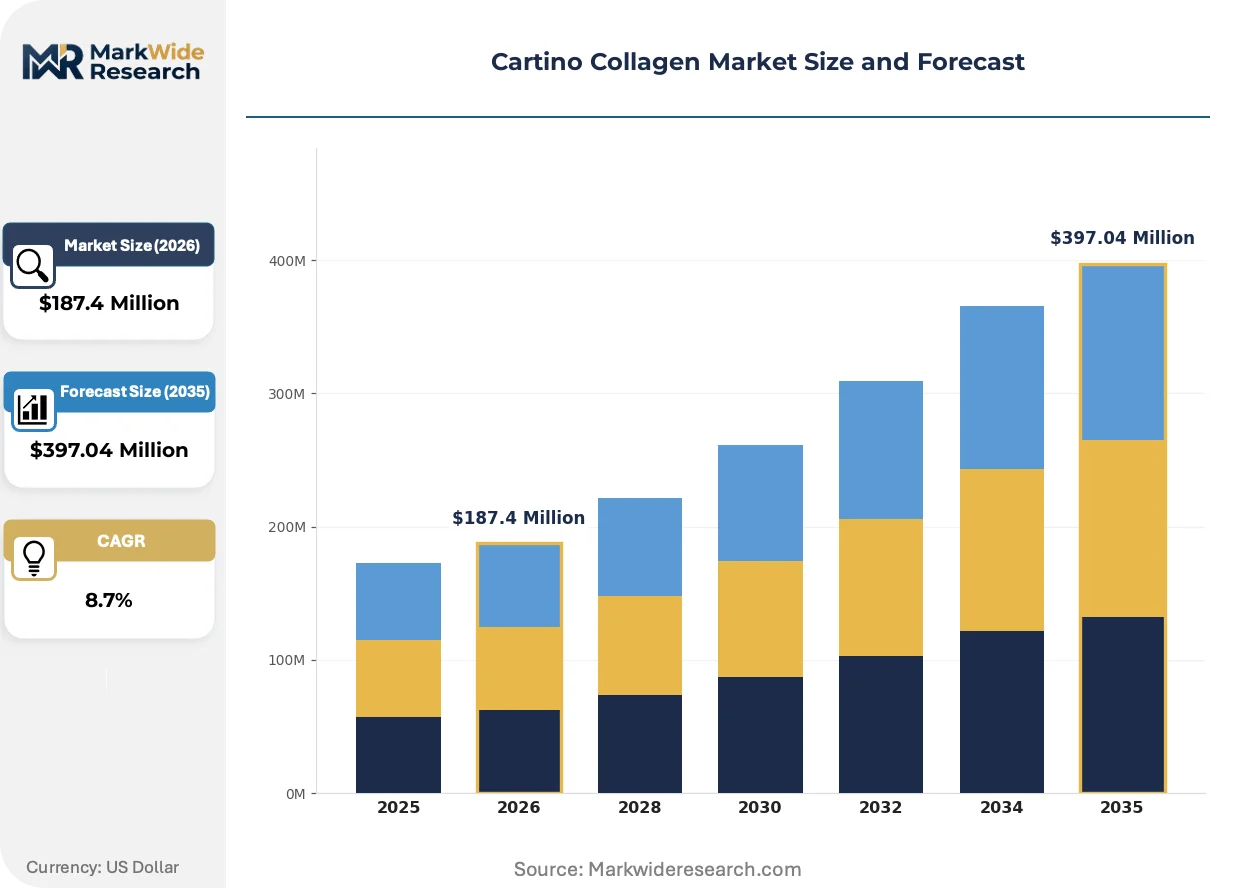
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Collagen Powder Application: Cosmetics, Nutraceuticals, Food & Beverage, Medical Devices Form: Liquid, Capsules, Powder, Gummies Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Pharmacies |
| Companies Covered | Gelita AG, Rousselot, Nitta Gelatin Inc., Weishardt Group, Advanced BioMatrix, Inc., Collagen Solutions Plc, Gelnex, Amicogen, Symatese, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cartino Collagen Market Evolving Landscape
Extraction technology convergence with digital process control is collapsing batch-to-batch variability while regulatory digitization compresses compliance documentation cycles across European and Asian markets.
Precision enzymatic hydrolysis with real-time molecular weight monitoring is digitizing quality assurance workflows that previously required offline chromatography. Medical device manufacturers in Germany and Switzerland are adopting these systems to satisfy EMA documentation requirements for implantable collagen. The technology is digitizing audit trail generation and reducing release hold times from seventy-two hours to four hours.
EU MDR and EFSA health claim digitization mandates are forcing reformulation of legacy collagen products that relied on pre-2021 label permissibility. Manufacturers must resubmit technical documentation through centralized EU portals with structured data fields replacing PDF submissions. Nutraceuticals segments targeting beauty-from-within claims face the steepest compliance burden as EFSA rejects eighty percent of submitted dossiers for insufficient bioavailability evidence.
Surgeon preference for pre-moistened collagen hemostats is displacing traditional dry-sponge formats in ambulatory settings across France and the United Kingdom. Hospital procurement committees are consolidating vendor lists to three approved suppliers per category, compressing switching costs and locking in volume commitments. The shift is most visible in NHS supply frameworks where integrated antimicrobial claims have become mandatory evaluation criteria.
Cartino Collagen Market Segmentation
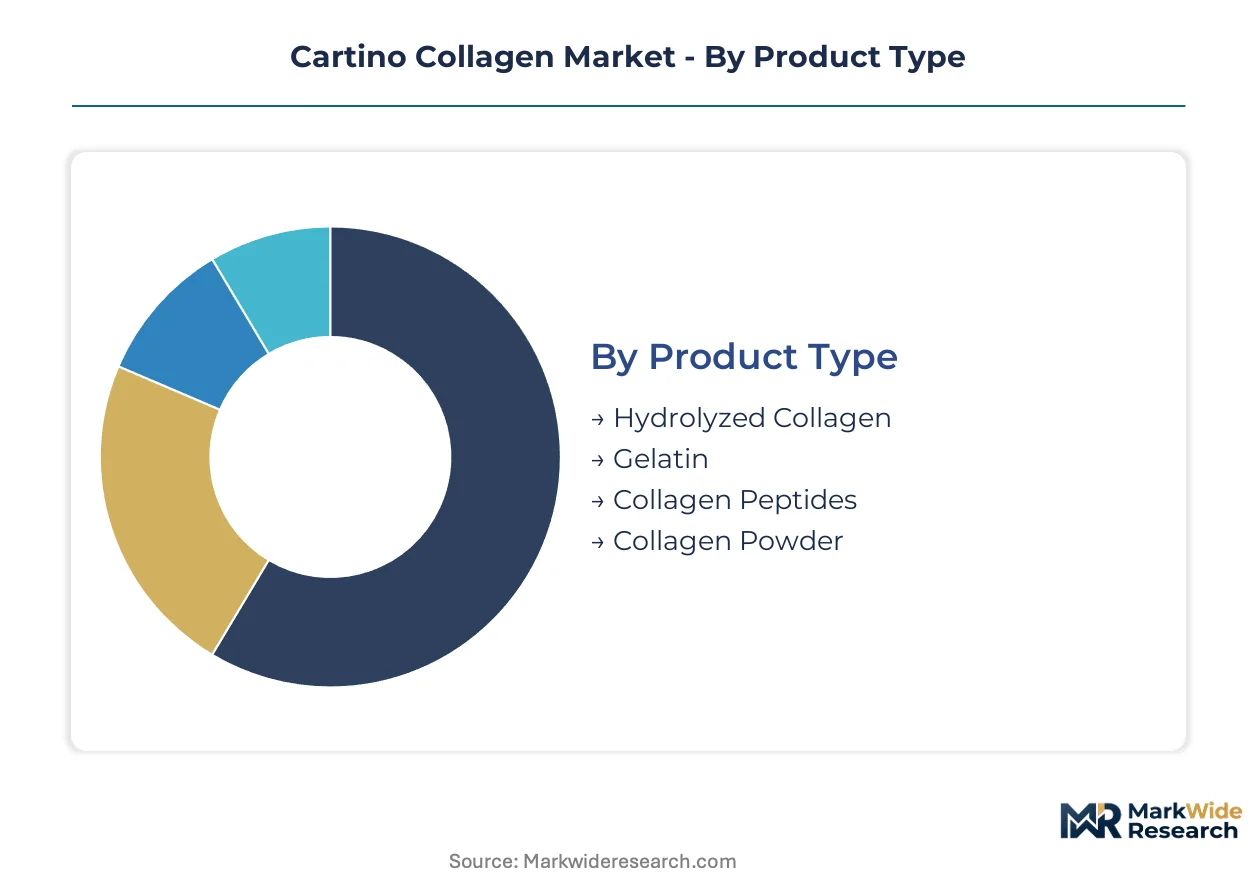
Cartino Collagen producers must align technical specifications with channel-specific service requirements, as medical device contracts demand lot-to-lot certification support while nutraceutical gummies require rapid formulation turnaround. Segmentation reveals where margin pools concentrate and which product formats justify dedicated production assets.
Product Type:
After-sales service intensity varies sharply across collagen formats, with hydrolyzed collagen requiring endotoxin documentation and medical-grade certificates that tie up quality assurance teams for days per shipment.
- Hydrolyzed Collagen:Enzymatically cleaved peptides with molecular weights between 2,000 and 10,000 Daltons optimize intestinal absorption for functional nutrition applications. Demand concentrates in Germany's Rhine-Main biotechnology cluster, where Gelita AG and Rousselot operate dedicated extraction facilities serving pharmaceutical clients across the continent. REACH compliance and EFSA novel food approval pathways tighten purity benchmarks, forcing manufacturers to maintain specialized regulatory affairs staff.
- Gelatin:Partially hydrolyzed collagen with gelling properties between 80-300 bloom strength dominates food emulsification and capsule shell production. Mature demand in conventional food manufacturing limits growth velocity, though EMA medical device regulation sustains premium pricing for pharmaceutical-grade lots with documented TSE/BSE risk mitigation.
- Collagen Peptides:Bioactive fractions targeting beauty-from-within claims in ready-to-drink beverages and functional foods.
- Collagen Powder:Bulk format for industrial-scale nutraceutical compounding and sports nutrition formulations.
Hydrolyzed collagen holds the largest share; momentum sits with collagen peptides as EFSA health claim assessments reshape label permissibility.
Application:
Application segmentation tracks where collagen's functional properties command price premiums versus commodity substitution risk.
- Cosmetics:Marine-sourced type I collagen dominates anti-aging topicals and dermal fillers where triple-helix integrity determines performance. French and German formulators drive procurement of certified sustainable fisheries material, constrained by limited North Atlantic and Pacific Northwest certification capacity.
- Medical Devices:Collagen hemostats, wound dressings, and biodegradable sutures require ISO 22442 viral inactivation protocols and endotoxin thresholds below 0.5 EU per gram. Surgeon preference for pre-moistened formats with integrated antimicrobial agents is displacing traditional dry-sponge products in NHS and French hospital supply frameworks.
- Nutraceuticals:Hydrolyzed collagen procurement deepens as gummies and beauty beverages capture shelf space in German and French retail channels.
- Food & Beverage:Gelatin maintains stable demand for confectionery, dairy stabilization, and edible film applications despite slower expansion.
Medical devices hold the largest share; nutraceuticals are expanding most quickly as ready-to-drink formats proliferate.
Form:
Form selection determines manufacturing asset allocation and shelf-stability investment requirements across customer segments.
- Gummies:Pectin or gelatin-based delivery systems capture the fastest volume growth in beauty-from-within positioning, requiring precision moisture control and flavor masking technology to mask collagen's intrinsic taste profile.
- Powder:Bulk format serving sports nutrition and clinical nutrition compounding with the lowest per-dose cost structure and longest shelf stability.
- Liquid:Ready-to-drink collagen shots and beauty beverages command premium positioning in German and French convenience retail.
- Capsules:Hard-shell gelatin or HPMC delivery for clinical dosing precision in medical and nutraceutical applications.
Powder holds the largest share; gummies are gaining share fastest as format innovation attracts younger demographics.
Distribution Channel:
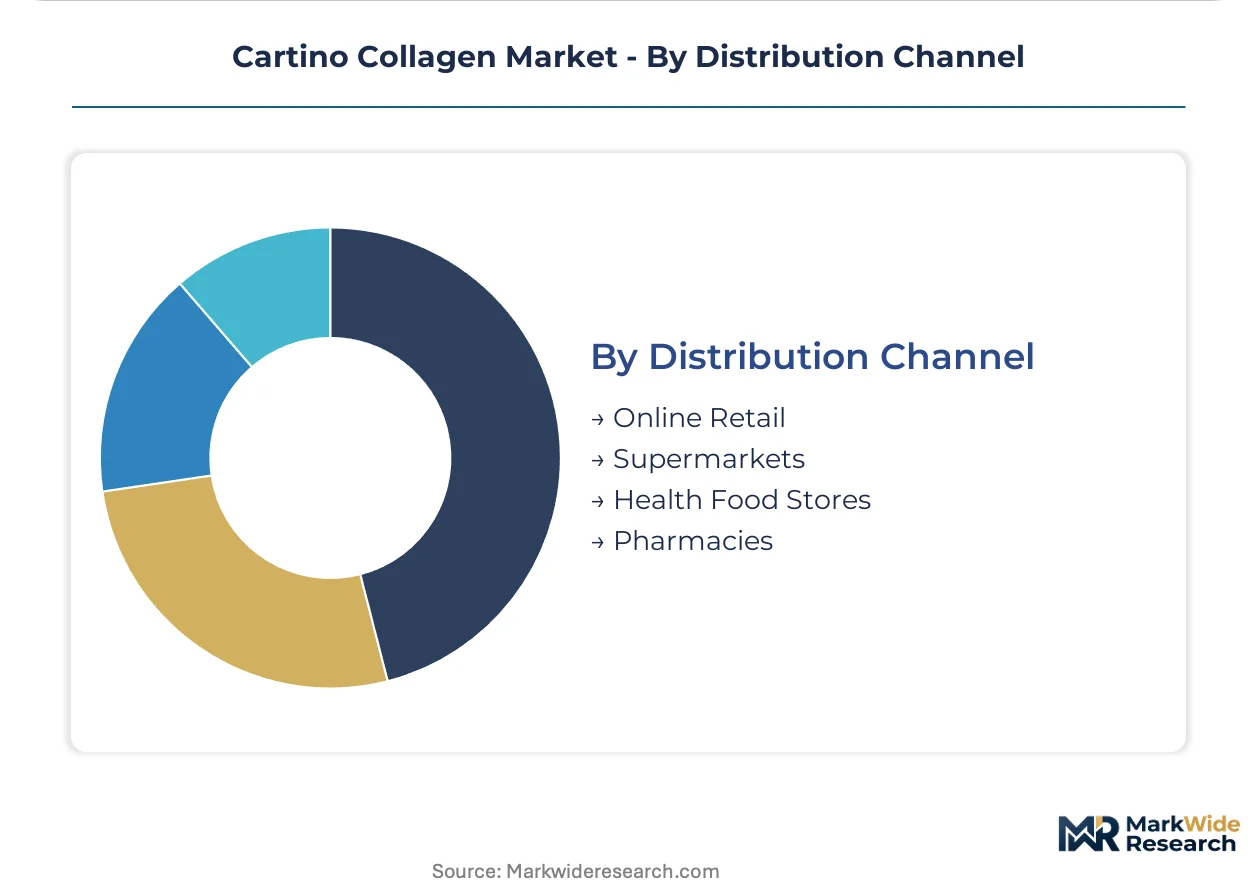
Channel segmentation reveals where technical consultation requirements and margin structures diverge most sharply.
- Pharmacies:Medical-grade collagen for wound care and clinical nutrition requires trained staff consultation and cold-chain integrity documentation. German pharmacy chains consolidate procurement through three approved suppliers per category, locking in volume commitments for collagen hemostats with integrated antimicrobial claims.
- Online Retail:Direct-to-consumer collagen peptides and beauty beverages bypass traditional wholesale markups, though EFSA health claim digitization mandates force reformulation of legacy products that relied on pre-2021 label permissibility.
- Health Food Stores:Specialist retailers curate premium-positioned hydrolyzed collagen with sustainability certifications and third-party testing verification.
- Supermarkets:Mass-market gelatin and food-grade collagen peptides compete on price-per-gram in conventional grocery placement.
Pharmacies hold the largest share; online retail shows the steepest expansion trajectory as subscription models lock in recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German extraction facilities export hydrolyzed collagen to French nutraceutical formulators and Swiss medical device manufacturers, creating a Rhine-Alpine trade corridor that channels over half of European volume through certified rendering operations.
Germany
Rhine-Main biotechnology cluster concentrates Gelita AG and Rousselot extraction facilities serving pharmaceutical clients across the continent. EFSA novel food approval pathways tighten purity benchmarks for collagen imports, forcing manufacturers to maintain specialized regulatory affairs staff. Hesse-based rendering operations source captive bovine supply chains within a two-hundred-kilometer radius.
France
Cosmetic formulators in Île-de-France drive procurement of marine-sourced type I collagen for anti-aging topicals and dermal fillers. ANSM medical device regulations mandate ISO 22442 viral inactivation protocols for collagen hemostats entering hospital supply frameworks. Paris-region laboratories specialize in triple-helix integrity testing for premium dermal filler applications.
Switzerland
Swissmedic certification requirements sustain premium pricing for pharmaceutical-grade gelatin used in capsule shell production. Basel-area medical device manufacturers adopt pre-moistened collagen hemostats with integrated antimicrobial agents for ambulatory surgical centers. Zürich-based quality assurance firms provide lot-to-lot certification support for export-bound collagen matrices.
United Kingdom
NHS supply frameworks consolidate vendor lists to three approved suppliers per category for collagen wound dressings. MHRA post-Brexit regulatory divergence creates parallel documentation requirements for EU-sourced collagen imports. Greater London procurement committees mandate integrated antimicrobial claims as mandatory evaluation criteria for hospital contracts.
Italy
Lombardy-based food manufacturers maintain stable demand for gelatin in confectionery and dairy stabilization applications. Italian cosmetic ingredient tenders favor Rousselot marine collagen competing directly with Asia-Pacific suppliers for anti-aging topical formulations. Milan-region research institutions collaborate on three-dimensional cell culture matrices for regenerative medicine applications.
Cartino Collagen Market Competitive Landscape
On the supply side, the industry is consolidating around extraction specialists with documented TSE/BSE risk mitigation protocols and REACH-registered facilities. Tiered competitive positioning separates integrated rendering-to-peptide manufacturers from standalone hydrolysis operators dependent on third-party raw material supply. Two strategic archetypes dominate: captive supply chain operators controlling bovine rendering through backward integration, and marine collagen specialists sourcing certified sustainable fisheries material. Capacity expansion and regulatory certification acceleration constitute the dominant competitive moves as EMA medical device regulation recertification timelines extend.
Within the integrated extraction tier, Gelita AG and Rousselot occupy positions exemplifying divergent raw material strategies—captive bovine and porcine supply chains versus marine specialization. Advanced BioMatrix, Inc. represents the research-grade matrix archetype, serving three-dimensional cell culture applications where defined fiber architecture commands premium positioning. These three entities anchor the competitive structure: German and French integrated operators controlling continental nutraceutical contracts, and a US-based specialist dominating regenerative medicine matrices.
| Leading Market Players |
|---|
| Gelita AG |
| Rousselot |
| Nitta Gelatin Inc. |
| Weishardt Group |
| Advanced BioMatrix, Inc. |
| Collagen Solutions Plc |
| Gelnex |
| Amicogen |
| Symatese |
| Others |
Value Network & Pricing Analysis
Undercapacity in German enzymatic hydrolysis facilities is compressing spot availability for pharmaceutical-grade hydrolyzed collagen while forcing nutraceutical buyers into longer-term offtake commitments at elevated contract rates.
Pricing Analysis
Next-generation precision enzymatic hydrolysis systems command thirty to forty percent premiums over legacy acid-extraction output, while conventional gelatin production lines face margin compression from energy-intensive thermal processing. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22442-certified medical device grades from food-grade hydrolyzed collagen and bulk gelatin for industrial applications. Price differentiation hinges on endotoxin documentation burden and REACH registration status, with certified suppliers capturing sustainable premiums. Cost compression in standard-tier nutraceutical peptides is intensifying because French and German retailers are consolidating vendor lists to three approved suppliers per category. Hospital procurement committees exhibit lowest price sensitivity for pre-moistened collagen hemostats with integrated antimicrobial claims, while online direct-to-consumer channels show highest elasticity to per-gram pricing.
Supply Chain Analysis
Extended payment terms from sixty to ninety days are becoming standard for Rhine-Main biotechnology cluster extraction facilities serving pharmaceutical clients, straining working capital for standalone hydrolysis operators without backward integration into rendering. Geographic supply concentration centers on Germany, France, and Switzerland for pharmaceutical-grade collagen, with marine sourcing concentrated in North Atlantic and Pacific Northwest certified sustainable fisheries. Raw material dependencies rest on captive bovine rendering output, porcine tissue supply chains, and certified wild-caught marine biomass. Single-source vulnerability runs through the Rhine-Main rendering corridor where livestock disease surveillance protocols can abruptly constrain input availability. Distribution feeds from dedicated extraction facilities through pharmaceutical wholesalers, GPO contracts, and direct hospital supply frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cartino Collagen sits in early-cycle expansion as surgeon adoption of antimicrobial-integrated hemostats accelerates penetration in ambulatory surgical centers across France and the United Kingdom.
For Market Incumbents: Harden quality assurance infrastructure against EMA medical device regulation recertification timelines by embedding specialized TSE/BSE risk mitigation personnel within extraction facilities. Deepen backward integration into closed-loop rendering operations to secure captive bovine supply chains within the two-hundred-kilometer Rhine-Main radius, insulating against raw material volatility from rendering industry consolidation. For New Entrants and Emerging Players: Swiss regenerative medicine matrices present underpenetrated white space where research-grade collagen with defined fiber architecture commands premium positioning absent dominant specialists. Target three-dimensional cell culture applications in Lombardy and Milan-region research institutions through collaborative development agreements with academic medical centers, bypassing established pharmaceutical-grade certification barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extraction specialists with documented ISO 22442 protocols and long-term hospital supply framework contracts spanning multiple European markets. Five-to-ten year viability favors acquisition of marine collagen specialists with certified sustainable fisheries relationships as EU Green Deal sourcing mandates redirect procurement. Watch EFSA health claim digitization rejection rates as the inflection indicator for nutraceutical peptide margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Acceleration | Early REACH compliance locks in supplier status ahead of tightening ECHA purity benchmarks for collagen imports. |
| Antimicrobial Integration Partnership | Collaboration with ionic silver or chitosan suppliers captures surgeon preference in NHS and French hospital frameworks. |
| Marine Certification Expansion | Certified sustainable fisheries procurement beyond North Atlantic opens volume scaling for cosmetic ingredient tenders. |
| Enzymatic Hydrolysis Retrofit | Real-time molecular weight monitoring systems reduce release hold times from seventy-two hours to four hours for EMA documentation. |
| Regenerative Medicine Matrix Development | Defined fiber architecture collagen targets three-dimensional cell culture premiums in Basel and Zürich research clusters. |
Research Methodology
A standing panel of extraction facility technical directors, pharmaceutical procurement managers, EMA regulatory affairs specialists, and hospital supply framework administrators provided ongoing calibration against market developments throughout the study period. Primary fieldwork combined structured interviews with Gelita AG and Rousselot operations personnel, French cosmetic formulators in Île-de-France, and Swiss medical device manufacturers in Basel. Secondary validation drew from EMA medical device guidance documents, EFSA novel food approval dossiers, ISO 22442 standards publications, and REACH registration databases. Bottom-up volume estimates from extraction facility capacity utilization were triangulated against top-down demand projections from nutraceutical and medical device end-use segments.
Scenario-bracketing framed optimistic, baseline, and constrained trajectories based on EFSA health claim approval velocity and EU Green Deal sourcing mandate implementation pace. The analytical framework modeled product type, application, form, and distribution channel dimensions across the projection horizon, with geographic clustering around the Rhine-Alpine trade corridor. CAGRs were derived from segment-level volume growth rates applied to price trajectories reflecting certification tier premiums. Industry-specific inputs included livestock disease surveillance protocol stringency and certified sustainable fisheries capacity expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by marine collagen specialists or accelerated EMA recertification investments by integrated rendering-to-peptide manufacturers would shift outcomes from baseline projections. Macroeconomic deviation in livestock input costs, regulatory acceleration of EU Green Deal mandates, or technological breakthroughs in recombinant collagen production would prompt revision of demand and pricing assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Asia-Pacific Pet Nutraceuticals Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
North America Collagen Market
Nutraceuticals
Nootropics Market
Nutraceuticals
Levocarnitine Market
Nutraceuticals
Eye Health Ingredients Market
Nutraceuticals
Immunostimulants Market
Nutraceuticals
Europe Nutricosmetics Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Postbiotics Market
Nutraceuticals
Tetrahydropalmatine Market
Nutraceuticals
Medicinal Mushrooms Market
Nutraceuticals
Ayurvedic Products Market
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
Herbal Nutraceuticals Market
Nutraceuticals
Anti Aging Agent Market