
 Audio Over IP Solutions Market | 2026-2036
Audio Over IP Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Audio Over IP Solutions Market Outlook
Network engineering talent scarcity is redrawing competitive dynamics across the Audio Over IP Solutions landscape. Crestron Electronics leverages its control-system heritage to dominate commercial installation verticals with tightly integrated AV-over-IP ecosystems. Haivision Systems Inc. anchors broadcast and streaming workflows through low-latency contribution links that extend into live production environments. Kramer Electronics Ltd. competes on modular signal-management architectures that simplify migration from baseband to packet-switched audio transport.
Audio Over IP Solutions encompass networked hardware and software systems that encode, route, and synchronize audio streams using standard Ethernet infrastructure, typically operating at 48 kHz sample rates with sub-millisecond latency targets for professional applications. These systems replace dedicated analog and digital audio cabling with switched packet networks, enabling scalable channel counts and centralized management in broadcast facilities, performance venues, and corporate campuses. Dante technology occupies the largest installed base among network protocols due to its extensive licensee ecosystem and backward-compatible device certification program. AES67 interoperability is gaining traction in broadcast-centric deployments where multi-vendor integration between RAVENNA, Dante, and Livewire domains remains mandatory. Commercial installations represent the fastest-expanding application segment as enterprises retrofit conference infrastructure to support hybrid work models and spatial audio conferencing.
FCC equipment authorization requirements shape US market access for networked audio transmitters, while EU CE marking and the Radio Equipment Directive enforce electromagnetic compatibility and spectrum-efficiency standards for IP-connected devices sold in Europe. Japan's MIC technical regulations govern QoS parameters for real-time media transport over domestic networks, influencing product calibration for Japanese broadcasters and integrators. Stakeholders must monitor how ITU-T standards for media over IP converge with regional telecom regulations to determine whether audio networking migrates toward common carrier infrastructure or remains on isolated AV LANs.
Market Dynamics
Broadcast infrastructure migration from baseband SDI to packet-switched Ethernet is compressing equipment replacement cycles and forcing interoperability between proprietary network protocols. This transition concentrates purchasing power among systems integrators capable of bridging legacy and IP-native architectures.
Growth Catalysts
- Hybrid Work Infrastructure:Enterprise retrofitting of conference systems to support spatial audio and remote collaboration is pulling professional-grade networked audio into commercial real estate.
- EU Radio Equipment Directive:Harmonized electromagnetic compatibility standards for IP-connected devices reduce national-type approval burdens and accelerate cross-border equipment deployment.
- Live Production IP Migration:Sports and entertainment venues are replacing copper snake cables with redundant Ethernet topologies to enable flexible stage configurations and centralized DSP management.
Market Restraints
- Copper and Semiconductor Input Volatility:Ethernet switch ASICs and magnetics face allocation constraints that extend lead times for networked audio endpoints.
- German Manufacturing Cluster Concentration:Professional audio OEM supply chains cluster around Berlin and Hamburg, creating geographic single-point vulnerability for component sourcing.
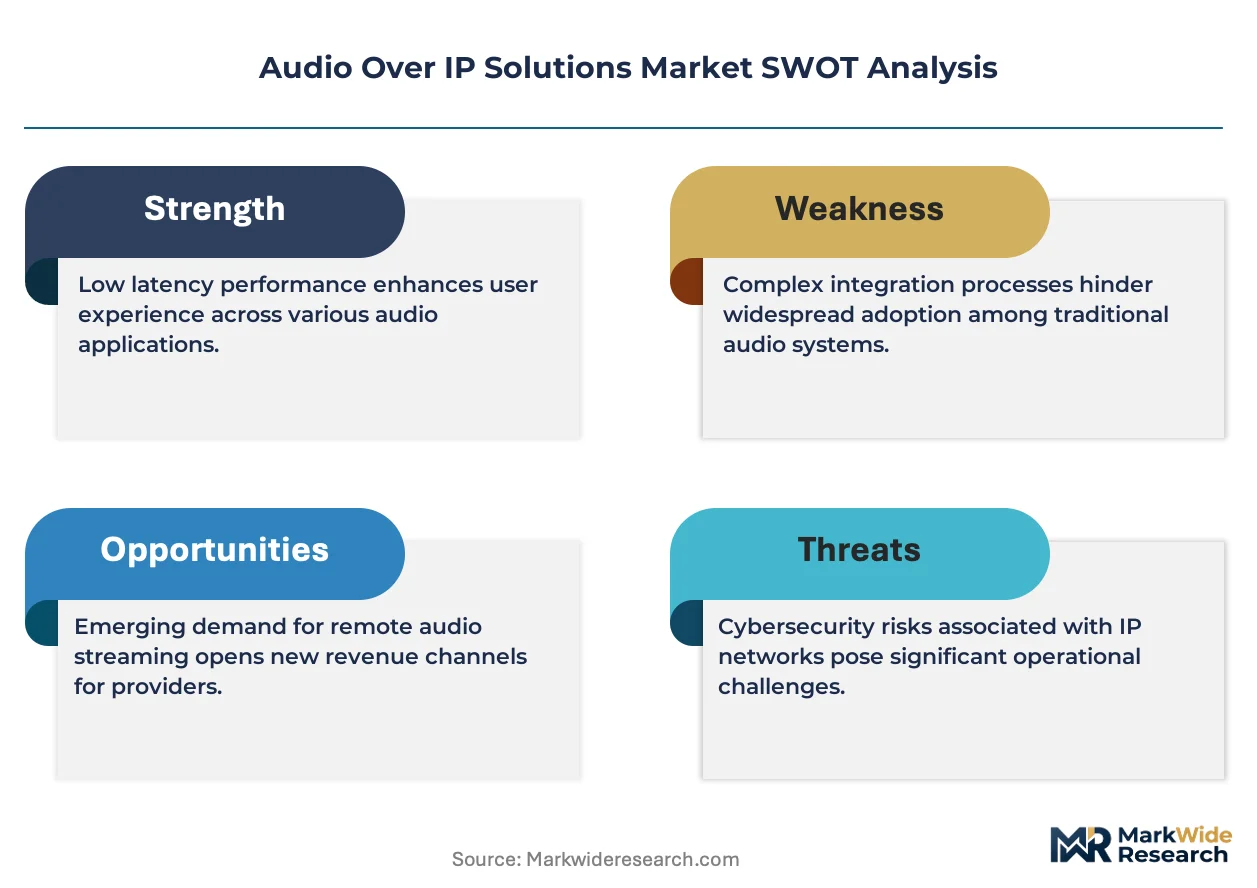
- Latency Floor in Unmanaged Networks:Sub-millisecond synchronization targets require dedicated AV LANs or managed switches, limiting deployment flexibility in cost-constrained installations.
Strategic Opportunities
- Underpenetrated Indian Broadcast Sector:TRAI infrastructure mandates for digital terrestrial transmission are opening equipment refresh cycles in regional television networks.
- Healthcare Acoustic Monitoring:HIPAA-compliant networked audio systems for patient monitoring and surgical collaboration represent an emerging vertical with distinct certification requirements.
- Dante-AES67 Convergence:Interoperability between dominant proprietary protocols and open standards enables multi-vendor integration previously blocked by ecosystem lock-in.
Industry Challenges
- Network Engineering Talent Scarcity:Broadcast technicians with packet-switching expertise remain scarce relative to baseband-trained staff, slowing deployment velocity.
- Legacy PPM Metering Integration:Studios maintaining analog peak program meters face calibration complexity when bridging to IP-based loudness monitoring per ITU-R BS.1770.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio Over IP Solutions Market |
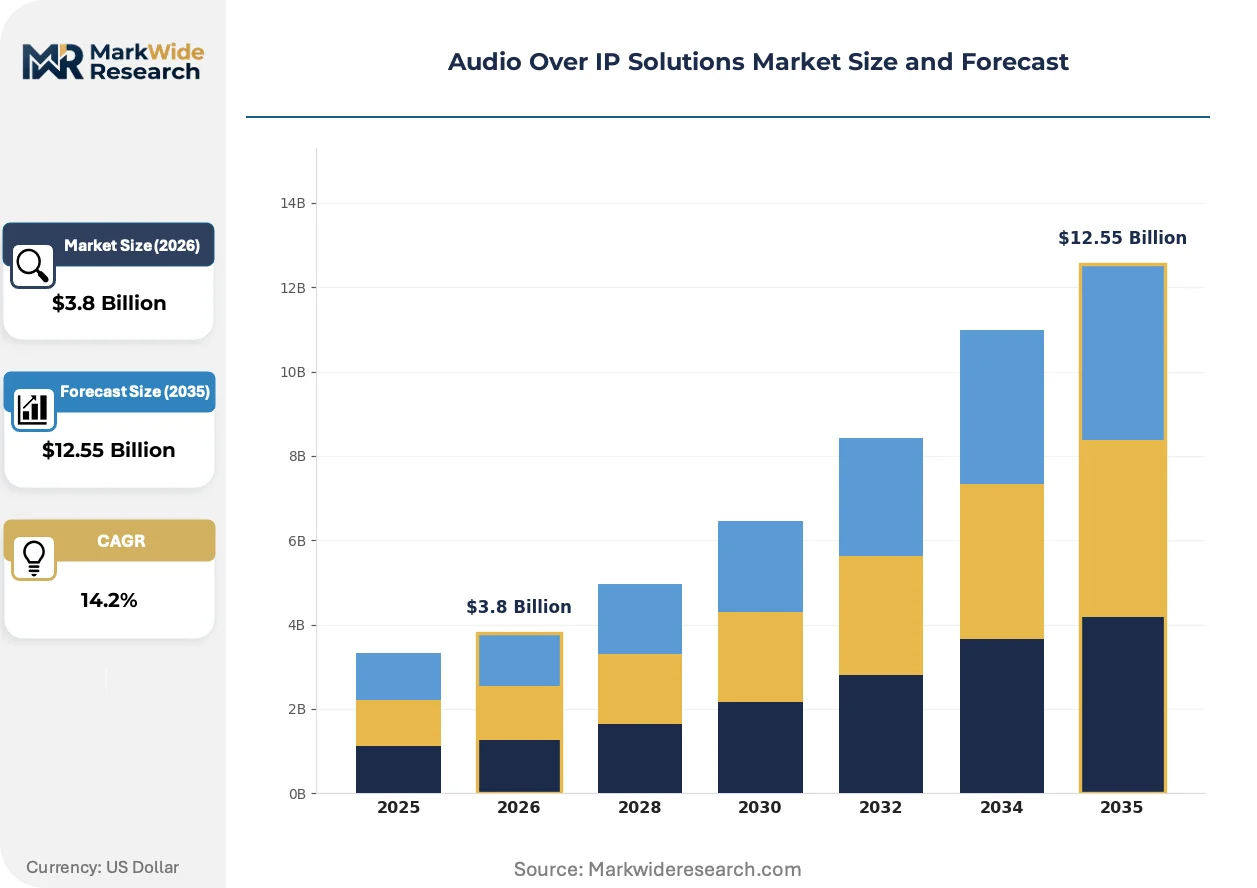
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Interfaces, Digital Interfaces, Switches, Networking Equipment Technology: VoIP, AES67, RAVENNA, Dante Application: Broadcasting, Live Events, Commercial Installations, Home Theater End User: Studios, Event Planners, Corporations, Venue Owners |
| Companies Covered | Atlona Inc., ZeeVee Inc., Crestron Electronics, Genelec, Visionary, Extron Electronics, Kramer Electronics Ltd., Haivision Systems Inc., AMX by Harman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio Over IP Solutions Market Strategic Shifts
Software-defined signal processing is separating audio routing intelligence from dedicated hardware, enabling subscription-based feature licensing and cloud-managed edge devices. This shift compresses capital requirements while expanding recurring revenue potential for infrastructure vendors.
DSP virtualization is decomposing hardware-based mixing consoles into disaggregated compute, control surface, and I/O stagebox elements. Broadcast facilities in North America are adopting this architecture to scale channel counts without forklift console replacements. The technology is decomposing traditional vendor lock-in by enabling best-of-breed component sourcing across multiple suppliers.
FCC equipment authorization requirements for networked audio transmitters are tightening spurious emission limits in the 2.4 GHz and 5 GHz bands. This regulatory pressure is forcing firmware recalibration and antenna redesign for wireless IP audio endpoints. US broadcast integrators are responding by specifying pre-certified module architectures that accelerate deployment timelines.
Enterprise AV procurement is consolidating under IT department governance rather than facilities management, shifting vendor evaluation criteria toward cybersecurity hardening and SNMP monitoring compatibility. Systems integrators are adapting by embedding zero-trust network architectures and automated certificate management into installation workflows. This pattern is most visible in Fortune 500 campus deployments across the United States.
Audio Over IP Solutions Market Segmentation
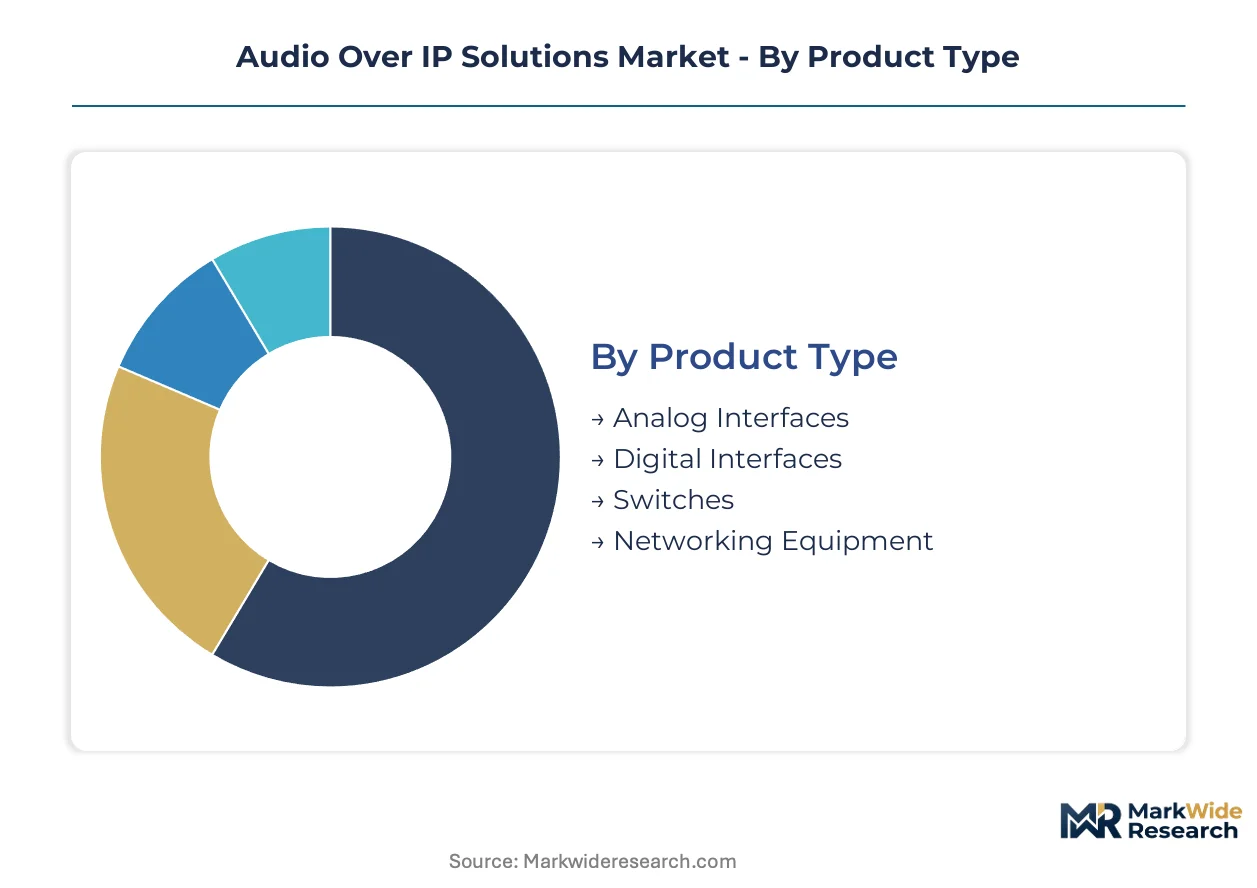
Segmentation in Audio Over IP Solutions reveals how protocol ecosystems, hardware form factors, and customer sophistication levels create distinct margin architectures. Vendors configure pricing and service models differently across these boundaries.
Product Type:
Margin pools concentrate in networking equipment and switches where firmware differentiation and managed service attach rates sustain premium pricing.
- Networking Equipment:Ethernet switches with AV-optimized QoS policies and redundant power supplies form the backbone of professional installations. Demand clusters in German broadcast integration projects around Berlin and Hamburg, where facilities demand sub-microsecond synchronization precision for multi-studio complexes.
- Switches:Managed layer-2 and layer-3 switches with IGMP snooping and PTP clocking support enable scalable channel counts. US broadcasters migrating from SDI infrastructure specify these for control-room backbone replacements, prioritizing Dante compatibility and AES67 bridging capabilities.
- Analog Interfaces:Stagebox units with microphone preamplification and A/D conversion bridge legacy transducer infrastructure to packet networks.
- Digital Interfaces:AES3, MADI, and SDI-to-IP gateways preserve investment in existing digital audio equipment during facility transitions.
The dominant share belongs to Networking Equipment, while Switches is closing the gap fastest.
Technology:
Protocol licensing economics separate recurring-revenue ecosystems from standards-based deployments with lower vendor capture.
- Dante:Audinate's proprietary protocol commands the largest installed base through extensive licensee networks and backward-compatible certification. Commercial installations across US corporate campuses specify Dante-native endpoints for simplified IT department governance and cloud-based device management.
- VoIP:SIP-based and proprietary enterprise voice protocols extend into professional audio through standards-based interoperability. Healthcare acoustic monitoring systems in US hospital networks adopt VoIP architectures for HIPAA-compliant integration with existing nurse call infrastructure.
- AES67:The open interoperability standard enables multi-vendor integration between Dante, RAVENNA, and Livewire domains in broadcast-centric deployments.
- RAVENNA:ALC Networx's open standard targets high-channel-count broadcast and installed sound with precision timing for layer-3 routed networks.
Dante holds the revenue concentration, yet AES67 is climbing the fastest as broadcasters mandate protocol-agnostic interoperability.
Application:
Deployment complexity and uptime requirements create tiered service revenue opportunities across use cases.
- Commercial Installations:Enterprise conference room retrofits and campus-wide AV distribution demand scalable, IT-managed infrastructure. Hybrid work models in US Fortune 500 headquarters are pulling professional-grade networked audio into real estate capital budgets with multi-year service contracts.
- Broadcasting:Television and radio facilities require redundant topologies with guaranteed latency for live production. North American broadcasters replacing SDI infrastructure with IP-native routing systems are compressing equipment refresh cycles and forcing interoperability testing between proprietary protocols.
- Live Events:Touring sound and fixed entertainment venues prioritize rapid deployment and flexible stage configurations over permanent infrastructure.
- Home Theater:Residential multi-room audio and high-end cinema installations represent a price-sensitive segment with consumer-grade reliability expectations.
Broadcasting retains the largest project value per deployment, though Commercial Installations is expanding most quickly.
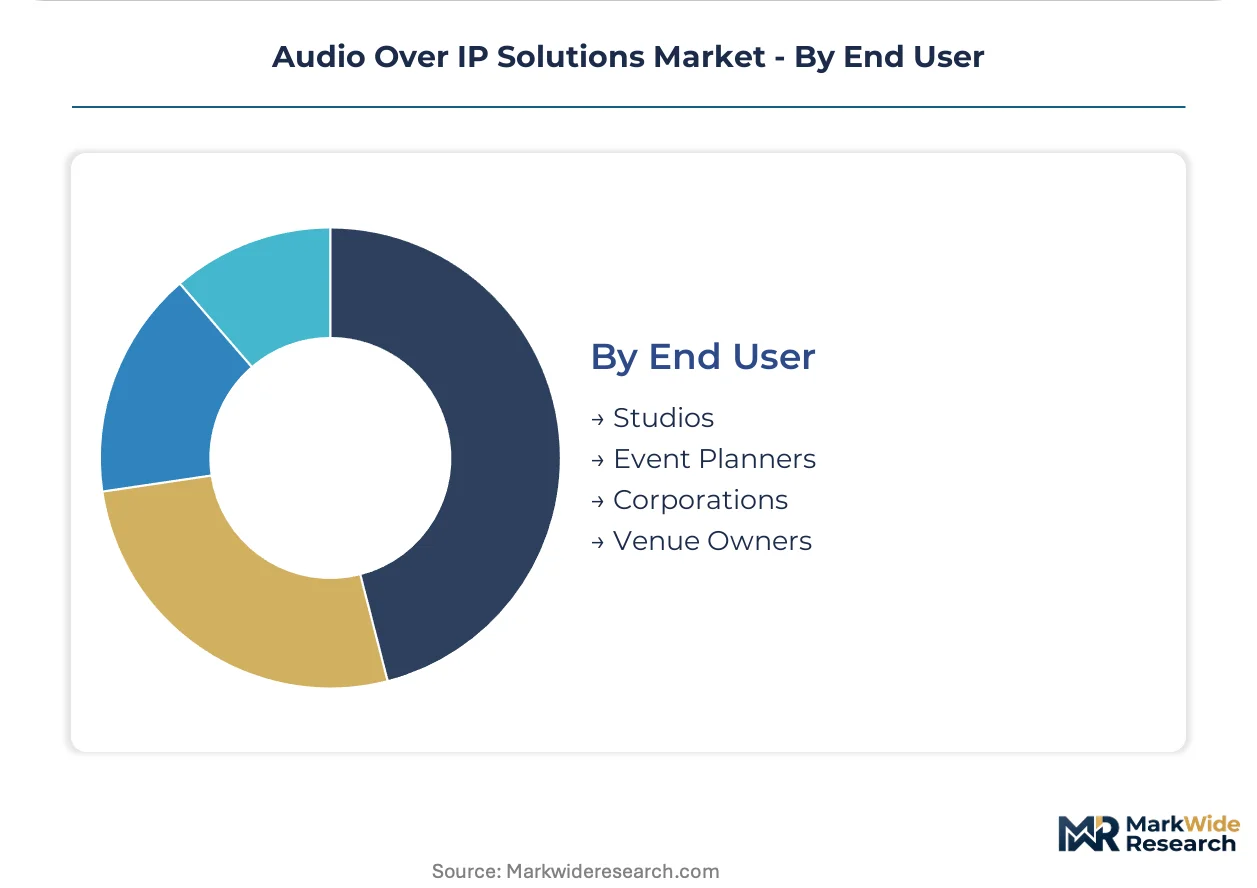
End User:
Technical sophistication and procurement authority shape vendor engagement models and pricing transparency.
- Corporations:IT-governed procurement with cybersecurity hardening requirements and SNMP monitoring compatibility. US enterprise campuses are consolidating AV procurement under CIO oversight, shifting evaluation criteria toward zero-trust architectures and automated certificate management.
- Studios:Recording and post-production facilities with specialized acoustic requirements and legacy equipment integration needs. German professional audio manufacturers serve these customers through direct technical sales relationships with calibration and support services.
- Event Planners:Rental and staging companies prioritizing rapid deployment, ruggedized hardware, and flexible rental terms over permanent installation economics.
- Venue Owners:Sports arenas, performing arts centers, and houses of worship balancing capital constraints with operational reliability requirements.
Corporations command the steepest expansion trajectory, while Studios maintains the highest margin per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German professional audio manufacturing clusters while US enterprise deployments absorb premium through IT-governed procurement budgets. Facility upgrade cycles in North American broadcast studios outpace European public-sector spending constraints. Asian markets remain price-sensitive with protocol licensing costs driving vendor selection.
United States
Enterprise campus retrofits for hybrid work infrastructure and broadcast SDI-to-IP migration drive equipment procurement. FCC equipment authorization requirements for networked audio transmitters enforce spurious emission limits in 2.4 GHz and 5 GHz bands. Los Angeles and New York broadcast integration clusters specialize in redundant Ethernet topologies for live production environments.
Germany
Professional audio OEM supply chains and broadcast integrator networks sustain equipment refresh demand. EU CE marking and the Radio Equipment Directive harmonize electromagnetic compatibility standards across member states. Berlin and Hamburg manufacturing clusters concentrate precision timing hardware for multi-studio broadcast complexes.
Japan
Domestic broadcasters and performance venues require sub-millisecond latency guarantees for real-time media transport. MIC technical regulations govern QoS parameters for IP-connected devices sold in Japanese markets. Tokyo and Osaka integration firms specialize in bridging legacy baseband infrastructure to packet-switched architectures.
United Kingdom
Post-production studios and corporate AV departments prioritize AES67 interoperability for multi-vendor integration. GDPR compliance requirements shape data handling protocols for cloud-managed audio devices. London broadcast facilities lead European adoption of DSP virtualization for disaggregated mixing console architectures.
India
Regional television networks face equipment refresh cycles under TRAI infrastructure mandates for digital terrestrial transmission. Central government PLI scheme incentives attract component manufacturing investment. Mumbai and Bangalore integration markets develop cost-optimized Dante-AES67 bridging solutions for price-constrained deployments.
Audio Over IP Solutions Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Audio Over IP Solutions landscape. The vendor base stratifies between proprietary protocol licensors with recurring revenue ecosystems and standards-based hardware fabricators competing on manufacturing scale. Three archetypes dominate: control-system heritage vendors with integrated AV-over-IP ecosystems, broadcast-specialized contribution link providers, and modular signal-management architects. Competitive dynamics center on strategic partnerships between semiconductor suppliers and firmware developers, plus geographic expansion through systems integrator certification programs.
Among North American control-system vendors, Crestron Electronics occupies a position exemplifying tightly integrated commercial installation ecosystems. Haivision Systems Inc. and Kramer Electronics Ltd. anchor the broadcast and modular signal-management archetypes respectively. These three represent distinct strategic postures: enterprise IT governance capture, low-latency live production specialization, and migration-friendly hardware architectures.
| Leading Market Players |
|---|
| Atlona Inc. |
| ZeeVee Inc. |
| Crestron Electronics |
| Genelec |
| Visionary |
| Extron Electronics |
| Kramer Electronics Ltd. |
| Haivision Systems Inc. |
| AMX by Harman |
| Others |
Value Chain & Pricing Dynamics
Ethernet switch ASIC fabrication at scale economies in Taiwan and South Korea compresses cost floors for networked audio endpoints while concentrating premium capture among firmware developers who configure QoS policies and PTP clocking algorithms. This scale dynamic funnels margin toward German precision timing hardware clusters and US-based Dante ecosystem licensors, leaving assembly-dependent vendors exposed to input volatility.
Pricing Analysis
Configured-to-order pricing for broadcast-grade networking equipment with redundant power supplies and AES67 bridging capabilities commands spreads exceeding standard commercial installation hardware. Three-tier pricing structure across premium, standard, and economy levels segments by synchronization precision and channel density, with IT-governed enterprise campuses absorbing premium tiers for zero-trust security hardening. Pricing pressure stems from semiconductor allocation constraints extending lead times for magnetics and PHY components. Event planners and rental staging companies exhibit highest price sensitivity, while North American broadcasters facing SDI migration deadlines show lowest elasticity.
Supply Chain Analysis
Germany and the United States anchor precision timing hardware and DSP virtualization software development respectively, while Taiwan and China feed Ethernet switch ASICs and magnetics into assembly channels. Professional audio OEMs draw from copper cabling, FPGA silicon, and clock oscillator inputs with limited dual-source alternatives. Single-source vulnerability concentrates around Berlin-Hamburg manufacturing clusters for broadcast-grade stagebox units. Distribution runs through certified systems integrators who bridge specification, installation, and post-deployment managed services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment refresh cycles in broadcast infrastructure and enterprise hybrid work retrofits position this market for cyclical recovery, with SDI-to-IP migration compressing replacement timelines across North American facilities.
For Market Incumbents: Shield installed base erosion by embedding cloud-managed subscription tiers into hardware endpoints, countering software-defined signal processing entrants who separate routing intelligence from dedicated appliances. Deepen backward integration into FPGA firmware development to reduce exposure to semiconductor allocation volatility. Prioritize certification investment in FCC pre-certified module architectures that accelerate US deployment timelines for integrator partners.
For New Entrants and Emerging Players: Anchor in Indian regional television networks where TRAI infrastructure mandates for digital terrestrial transmission are opening equipment refresh cycles with limited incumbent saturation. Target cost-optimized Dante-AES67 bridging solutions for price-constrained Mumbai and Bangalore integration markets. Pursue direct technical sales relationships with German studio customers who demand calibration and support services beyond standard distribution channels.
For Investors and Strategic Acquirers: Modular signal-management architects with migration-friendly hardware portfolios represent compelling acquisition targets, given their positioning for baseband-to-packet infrastructure transitions. Long-term viability hinges on protocol-agnostic interoperability rather than proprietary ecosystem lock-in. Monitor Dante-AES67 convergence velocity as inflection indicator for multi-vendor integration demand and standards-based hardware fabricator margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Protocol-Agnostic Interoperability Certification | AES67 bridging capabilities unlock multi-vendor integration previously blocked by Dante ecosystem lock-in. |
| Cloud-Managed Edge Device Deployment | Subscription-based feature licensing compresses capital requirements while expanding recurring revenue capture. |
| Zero-Trust Network Architecture Integration | Automated certificate management satisfies CIO-governed procurement criteria in Fortune 500 campus deployments. |
| Healthcare Acoustic Monitoring Vertical Entry | HIPAA-compliant networked audio systems address patient monitoring and surgical collaboration certification requirements. |
| Indian Manufacturing Localization Partnership | Central government PLI scheme incentives attract component investment for cost-optimized regional supply. |
Study Parameters
Operator-level perspectives from broadcast integration engineers, IT procurement officers at Fortune 500 campuses, professional audio OEM technical sales directors, and certified systems integrators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC equipment authorization filings, EU CE marking databases, TRAI infrastructure mandate documentation, and semiconductor customs records. Bottom-up channel checks across German manufacturing clusters and US enterprise deployments triangulated against top-down equipment refresh cycle modeling.
Sensitivity analysis across protocol adoption curves, semiconductor allocation scenarios, and regional regulatory enforcement intensity shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, protocol technology, application vertical, end-user sophistication tier, and geographic procurement authority cluster. CAGRs derived from equipment replacement velocity indices and IT governance penetration rates across commercial real estate, with inputs from SDI depreciation schedules and hybrid work infrastructure capital allocation surveys.
Underlying assumptions cover sustained SDI-to-IP migration momentum, stable electromagnetic compatibility regulatory enforcement, and continued Dante ecosystem licensee expansion, with deviation risk concentrated in semiconductor supply disruption and network engineering talent scarcity slowing deployment velocity. Recalibration cycles align with material shifts in broadcast infrastructure capital budgets, EU Radio Equipment Directive amendments, and enterprise hybrid work policy permanence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Cloud OSS BSS Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Global DDI Market
Digital Solutions
Human Resource (HR) Technology Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
Hiking Apps Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Kuwait ICT Market
Digital Solutions
Ediscovery Market
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
Global Freelance Platforms Market