
 Industrial Operational Intelligence Solution Market | 2026-2036
Industrial Operational Intelligence Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Operational Intelligence Solution Market Analysis
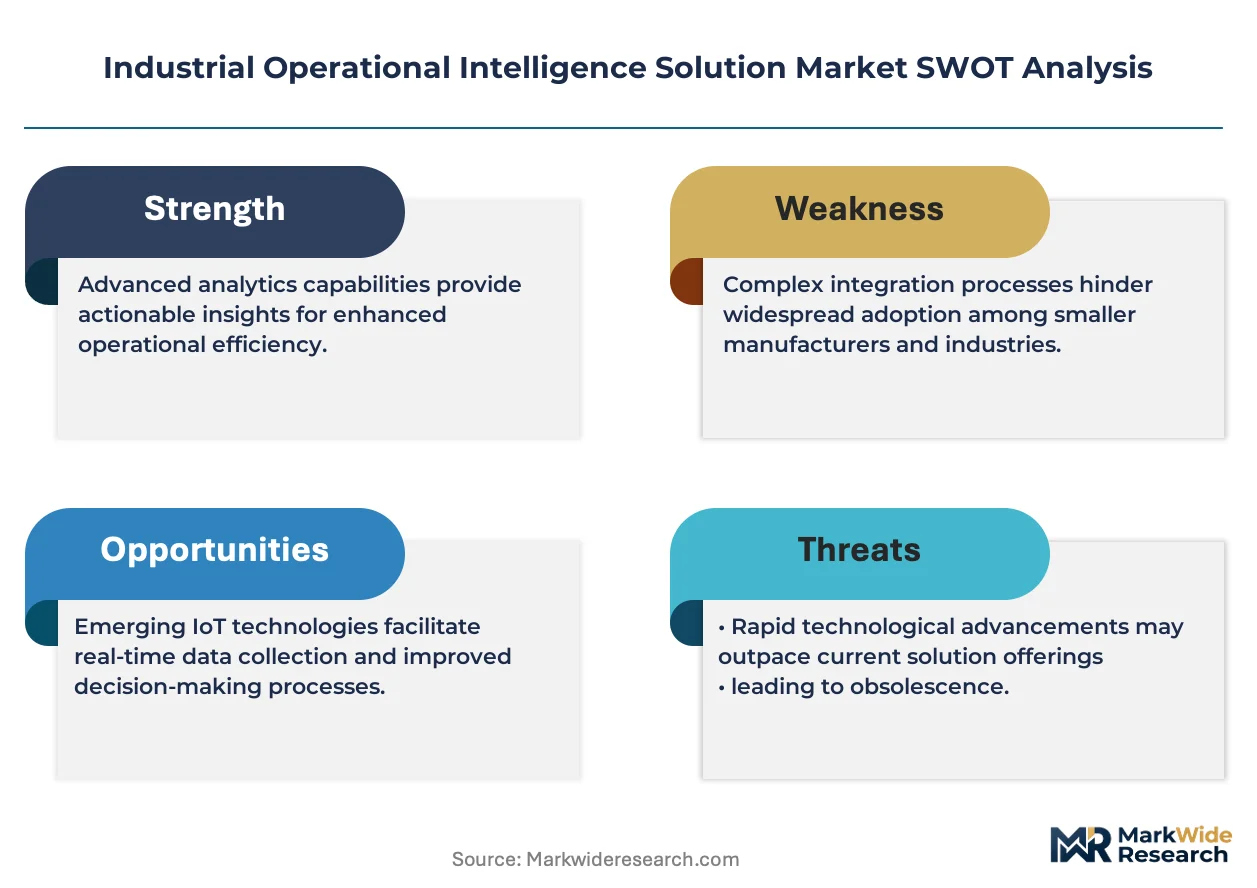
Germany's Ruhr industrial belt is reshaping competitive dynamics for operational intelligence platforms as manufacturers modernize brownfield assets. Siemens AG leverages deep vertical integration across automation hardware and analytics software to dominate local deployment cycles. Honeywell International Inc. sustains R&D intensity in edge-to-cloud architectures that serve process industries. Rockwell Automation Inc. competes through channel control in mid-market manufacturing, where retrofit demand outpaces greenfield installations.
Industrial operational intelligence solutions integrate real-time data ingestion, advanced analytics, and visualization layers to optimize asset performance and production workflows across distributed manufacturing environments. These systems typically process operational technology data at sub-second intervals while maintaining deterministic response thresholds for safety-critical control loops. Analytics platforms command the largest installed base among product types, though edge computing deployments are expanding fastest as latency requirements tighten for autonomous process adjustments. Cloud-based models capture growing share in logistics and supply chain verticals where multi-site visibility outweighs on-premises control priorities.
EMA's guidance on artificial intelligence in medical device manufacturing and FDA's 21 CFR Part 11 electronic records requirements are elevating validation burdens for pharmaceutical and food processing adopters. REACH chemical reporting obligations and EU Green Deal carbon accounting mandates are forcing energy-intensive sectors to embed emissions tracking directly into operational dashboards. Stakeholders must weigh compliance module integration against core analytics ROI as regulatory scope broadens beyond traditional quality and safety domains.
Market Dynamics
Manufacturers retrofitting brownfield facilities with real-time analytics infrastructure are compressing deployment cycles and forcing platform vendors to integrate legacy protocol translation layers into standard offerings.
Growth Catalysts
- EU AI Act compliance mandates:Risk classification requirements for automated decision systems in industrial settings are accelerating procurement of validated operational intelligence platforms with embedded audit trails.
- Automotive OEM predictive maintenance:German machinery builders and vehicle manufacturers are deploying edge analytics to minimize unplanned downtime in high-volume production lines.
- REACH chemical reporting obligations:Energy-intensive processors are embedding emissions tracking modules directly into operational dashboards to satisfy EU Green Deal carbon accounting requirements.
Market Restraints
- Semiconductor component volatility:Industrial edge devices face input cost instability from specialized chip shortages affecting deterministic control hardware.
- OT-IT convergence complexity:Sub-second latency requirements for safety-critical control loops create technical barriers to cloud-native analytics migration.
- FDA 21 CFR Part 11 validation burden:Pharmaceutical manufacturers face extended compliance timelines for electronic records systems in operational data environments.
Strategic Opportunities
- Process industry edge computing:Refineries and chemical plants represent underpenetrated demand for autonomous process adjustment capabilities.
- ISO 50001 energy management convergence:Integration of carbon accounting with operational KPIs creates white space for unified platform vendors.
- Mid-market manufacturing channel control:Retrofit demand among smaller German machinery operators outpaces greenfield installation cycles.
Industry Challenges
- Control systems engineering talent scarcity:Shortage of professionals capable of bridging deterministic OT networks with probabilistic analytics architectures.
- Brownfield protocol heterogeneity:Legacy PLCs and SCADA systems require costly middleware development for standardized data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Operational Intelligence Solution Market |
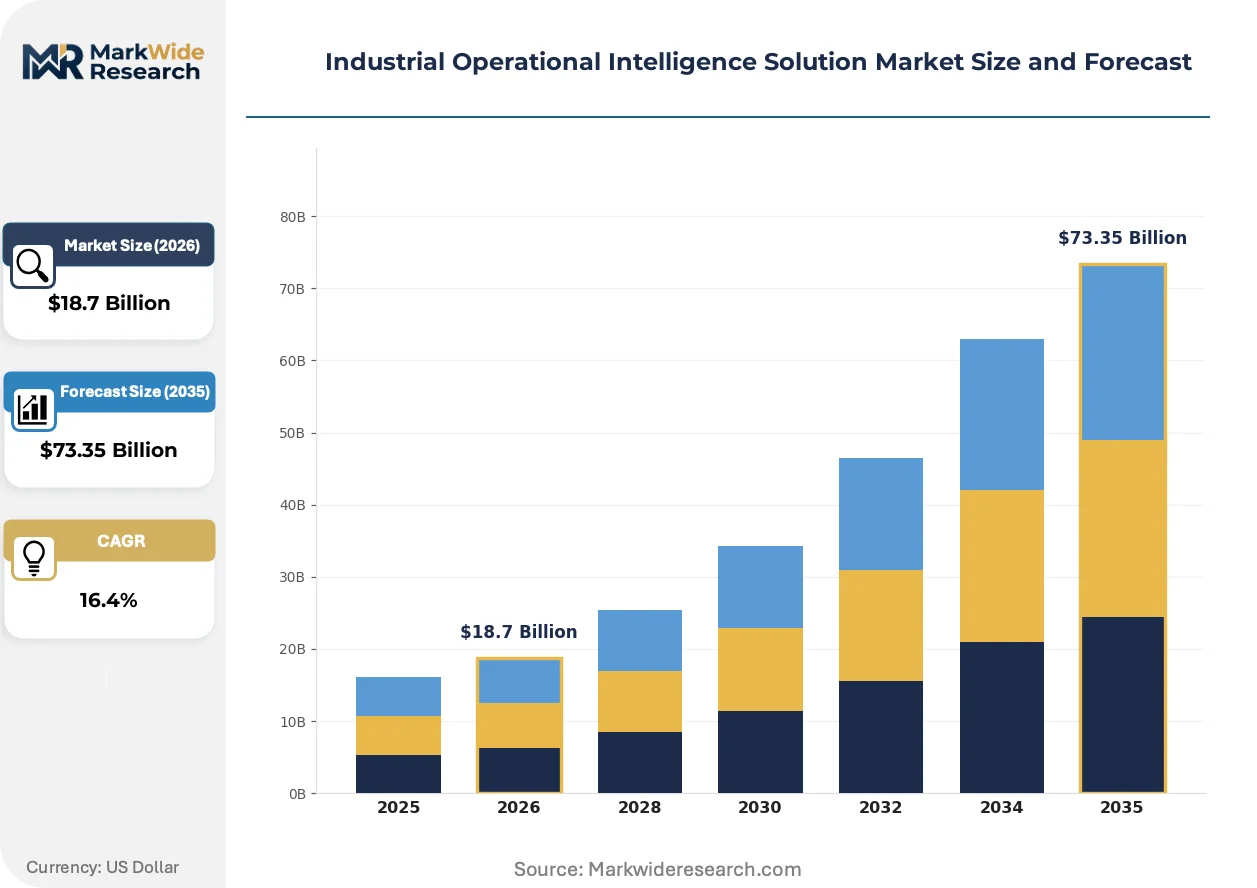
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
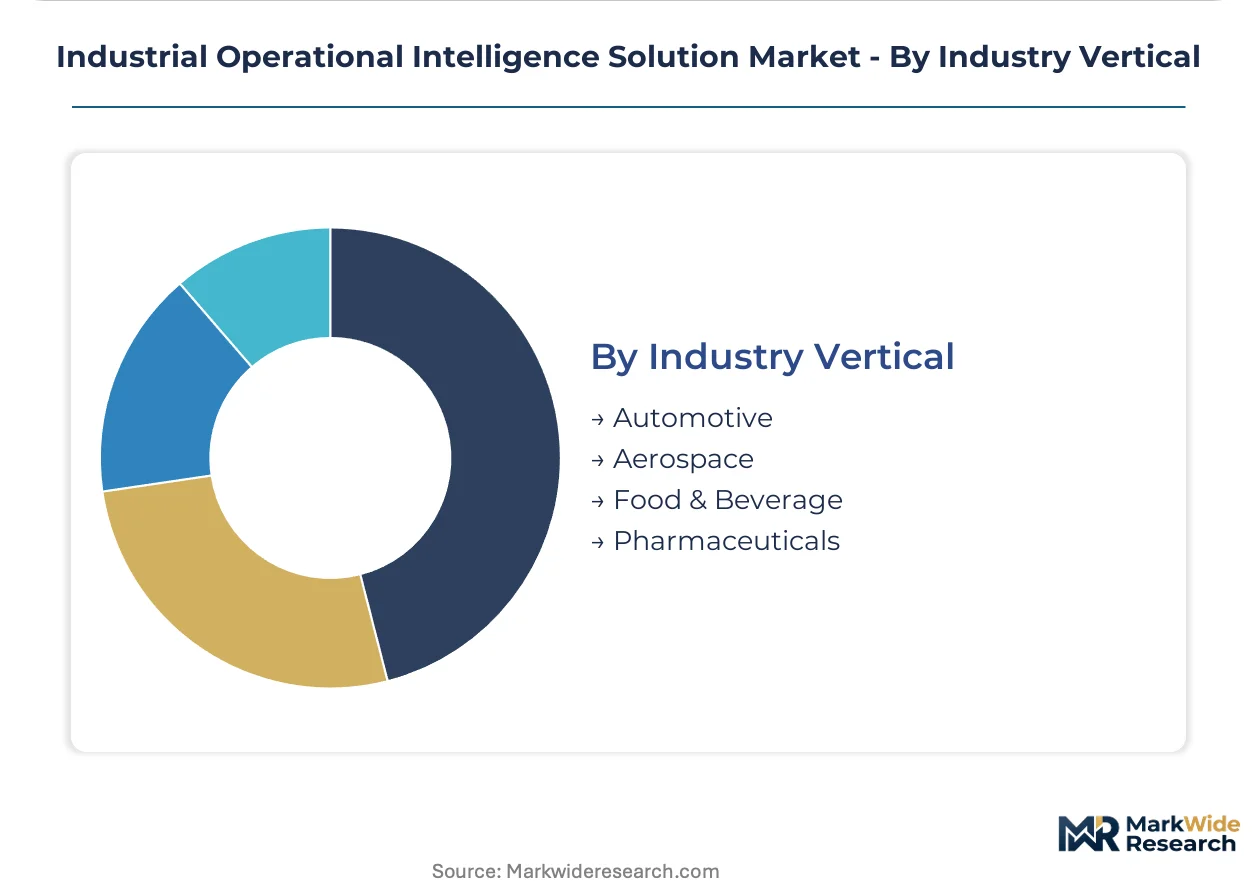
| Segmentation | Product Type: Analytics Platform, Monitoring Tools, Reporting Software, Visualization Solutions Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Manufacturing, Energy, Logistics, Supply Chain Industry Vertical: Automotive, Aerospace, Food & Beverage, Pharmaceuticals |
| Companies Covered | Siemens AG, Honeywell International Inc., Rockwell Automation Inc., ABB Ltd., Schneider Electric SE, PTC Inc., SAP SE, Splunk Inc., AVEVA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Operational Intelligence Solution Market Emerging Trajectories
Real-time operational intelligence is converging with autonomous control systems, compressing the gap between analytics insight and automated response. Three developments are restructuring competitive requirements.
Edge-to-cloud orchestration layers are hybridizing deterministic control with probabilistic optimization. These architectures process safety-critical loops locally while feeding aggregate data to centralized learning models. Automotive stamping plants in Germany's industrial corridor are deploying such systems to enable millisecond-level press adjustments. The technology is hybridizing traditional automation vendor business models toward subscription-based analytics services.
EMA guidance on artificial intelligence in medical device manufacturing is elevating validation protocols for pharmaceutical operational data systems. The framework mandates documented algorithmic transparency for any AI-driven process control. Contract manufacturers in Ireland and Switzerland are rebuilding quality management systems to accommodate these requirements. Compliance investments are diverting R&D budgets from core analytics functionality toward audit infrastructure.
After-sales service unbundling is fragmenting traditional platform vendor revenue streams. Machinery OEMs now procure analytics modules separately from automation hardware, forcing suppliers to interoperate through open APIs. German automotive suppliers are driving this disaggregation to avoid vendor lock-in across multi-site deployments. Channel relationships are reorganizing around software-centric value propositions rather than integrated system sales.
Industrial Operational Intelligence Solution Market Segmentation
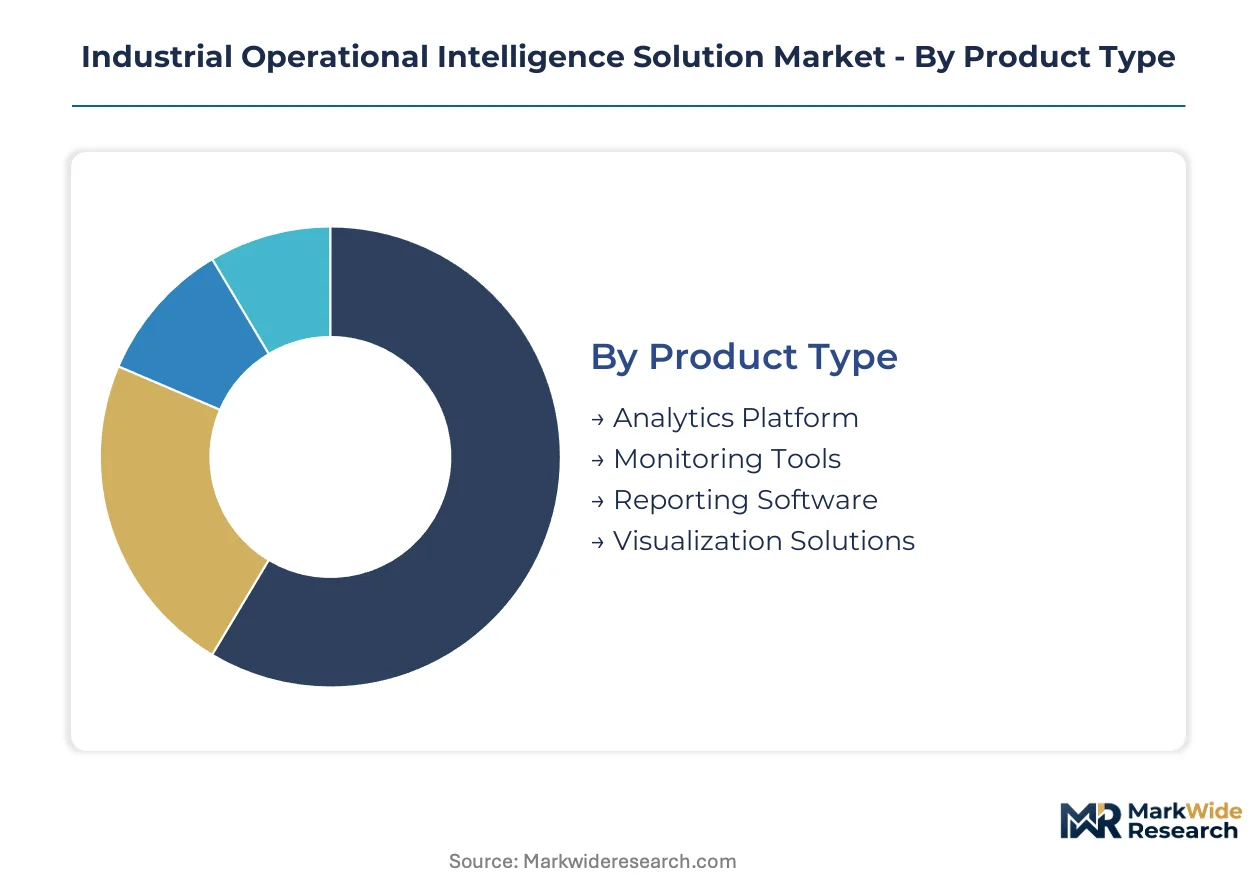
Industrial operational intelligence platforms serve heterogeneous buyer requirements across automation maturity levels, data sovereignty constraints, and regulatory exposure. Segmentation reveals where platform vendors must differentiate architecture, pricing, and compliance modules to capture expansion opportunities.
Product Type:
Cost tier separates buyers seeking comprehensive analytics suites from those prioritizing point solutions for specific operational pain points.
- Analytics Platform:Integrated environments combining real-time ingestion, machine learning pipelines, and predictive modeling for asset performance optimization. German automotive OEMs concentrate procurement here, driven by EU AI Act validation requirements for automated decision systems in production environments.
- Monitoring Tools:Specialized instrumentation for condition-based maintenance and anomaly detection with deterministic alerting thresholds. Process industries in energy-intensive sectors embed these for REACH carbon accounting compliance, requiring direct emissions tracking integration.
- Reporting Software:Structured output generation for regulatory submission and internal KPI dashboards.
- Visualization Solutions:Human-machine interface layers for operational dashboards and control room displays.
Analytics Platform commands the established base. The steepest expansion runs through Monitoring Tools.
Deployment Model:
Application criticality and latency tolerance dictate infrastructure placement across the edge-to-cloud continuum.
- On-Premises:Fully captive infrastructure for environments with strict data residency mandates or air-gapped security requirements. Pharmaceutical manufacturers under FDA 21 CFR Part 11 obligations favor this model for electronic records validation control.
- Edge Computing:Distributed processing nodes co-located with OT equipment for sub-100ms response loops. Automotive stamping operations in Germany's Ruhr belt deploy these for autonomous press adjustment, bypassing cloud latency for safety-critical functions.
- Cloud-Based:Centralized multi-tenant platforms prioritizing cross-site visibility over local control.
- Hybrid:Orchestrated architectures splitting deterministic control at edge from aggregate analytics in cloud.
On-Premises retains the largest installed footprint. Edge Computing gains share fastest as autonomous process adjustment requirements proliferate.
End User:
Customer operational maturity and retrofit urgency shape solution packaging and implementation velocity.
- Manufacturing:Discrete and process production environments requiring asset performance optimization and workflow orchestration. Brownfield modernization in Germany's machinery sector drives concentrated demand for protocol translation layers and legacy PLC integration.
- Energy:Power generation, transmission, and distribution operators managing grid stability and renewable intermittency. EU Green Deal carbon accounting mandates force embedded emissions tracking into operational dashboards.
- Logistics:Warehouse and transportation operators prioritizing multi-site visibility and inventory optimization.
- Supply Chain:End-to-end demand planning and supplier coordination across distributed networks.
Manufacturing anchors current revenue. Energy verticals show the steepest expansion trajectory through decarbonization compliance investments.
Industry Vertical:
Regulatory exposure and automation legacy differentiate procurement priorities across sectoral buyers.
- Automotive:High-volume production lines with zero-defect quality requirements and predictive maintenance imperatives. German OEMs and Tier-1 suppliers lead retrofit investment, compressing deployment cycles for real-time analytics infrastructure.
- Pharmaceuticals:Batch processing environments under stringent validation protocols for electronic records and AI-driven process control. EMA guidance on algorithmic transparency elevates audit infrastructure requirements above core analytics functionality.
- Aerospace:Complex assembly operations with traceability mandates and long-cycle production planning.
- Food & Beverage:Hygiene-critical processing with batch consistency and allergen management requirements.
Automotive commands the established base. Pharmaceuticals climb fastest as AI validation burdens reshape procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors European procurement patterns for operational intelligence platforms, with Germany's industrial corridor generating concentrated retrofit demand among automotive OEMs and machinery builders.
Germany
Automotive stamping plants and chemical processors drive edge analytics deployment across the Ruhr industrial belt. REACH chemical reporting obligations under ECHA mandate embedded emissions tracking modules. Stuttgart's machinery OEM cluster compresses deployment cycles for legacy PLC integration and protocol translation layers.
United States
Pharmaceutical manufacturers under FDA 21 CFR Part 11 obligations favor on-premises infrastructure for electronic records validation control. Process industries in the Gulf Coast petrochemical corridor invest in autonomous process adjustment capabilities. Houston's energy sector operators embed carbon accounting into operational dashboards to satisfy EPA reporting requirements.
China
Dual carbon goals from MIIT accelerate procurement of energy management convergence platforms in steel and cement processing. NMPA guidance on AI-driven medical device manufacturing elevates validation protocols for operational data systems. Yangtze River Delta manufacturing clusters deploy hybrid edge-to-cloud architectures for multi-site visibility.
Japan
METI standards for smart factory interoperability drive standardization investments among automotive suppliers and electronics assemblers. PMDA oversight of AI-enabled process control in pharmaceutical manufacturing reshapes quality management system requirements. Nagoya's automotive production corridor concentrates demand for predictive maintenance platforms with deterministic alerting thresholds.
India
PLI scheme incentives for advanced manufacturing attract operational intelligence platform deployment in electronics and automotive component production. BIS certification requirements for industrial automation equipment create compliance-driven procurement criteria. Tamil Nadu's automotive supplier cluster and Gujarat's chemical processing belt represent concentrated retrofit opportunities.
Industrial Operational Intelligence Solution Market Vendor Landscape
Industrial automation conglomerates and specialized analytics software vendors split the market through divergent approaches to OT-IT convergence. The competitive structure remains tiered, with integrated hardware-software providers commanding premium positioning in brownfield modernization cycles while pure-play analytics firms capture cloud-native demand in logistics verticals. Two strategic archetypes dominate: vertically integrated automation vendors with captive hardware distribution, and independent software platforms emphasizing open API interoperability. M&A activity concentrates on edge computing capabilities and legacy protocol translation technologies.
Within the integrated automation tier, Siemens AG and Honeywell International Inc. anchor competitive positioning through deep vertical control across hardware and software layers. Rockwell Automation Inc. occupies a distinct position in mid-market channel relationships. These three exemplify how European and North American industrial conglomerates leverage existing PLC and SCADA installed bases to accelerate analytics platform adoption, while independent competitors challenge through subscription-based pricing and interoperability commitments.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International Inc. |
| Rockwell Automation Inc. |
| ABB Ltd. |
| Schneider Electric SE |
| PTC Inc. |
| SAP SE |
| Splunk Inc. |
| AVEVA Group |
| Others |
Supply Flow & Price Mechanics
Rhine-Alpine freight corridors linking Rotterdam to Milan transmit cost volatility from semiconductor component shortages directly into edge device pricing tiers, while downstream buyers in Germany's automotive belt face widening spreads between validated EU AI Act-compliant platforms and unvalidated alternatives.
Pricing Analysis
Geographic price spreads between German automotive OEM procurement and mid-market machinery operators in Eastern Europe exceed 40 percent for equivalent analytics functionality. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers commanding certification-grade validation for FDA 21 CFR Part 11 and EU AI Act compliance. Cost compression in standard tiers is intensifying because channel partners unbundle after-sales service from hardware-software bundles. Mid-market manufacturing buyers exhibit highest price sensitivity, while pharmaceutical manufacturers under EMA guidance show lowest elasticity due to non-negotiable audit infrastructure requirements.
Supply Chain Analysis
Export control regimes restricting deterministic control chip flows from Netherlands-based ASML equipment constrain industrial edge device manufacturing capacity in Germany and Japan. Supply concentration rests on Taiwan and South Korea for advanced semiconductor fabrication, Germany for precision automation hardware, and China for rare earth magnet components in servo motors. Raw material dependencies include silicon wafers, gallium nitride substrates, and copper winding alloys. Single-source vulnerability in photolithography equipment creates chokepoint exposure. Distribution runs through authorized system integrators and OEM direct sales channels with 12-18 month deployment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial operational intelligence platforms are entering a cyclical recovery phase as brownfield retrofit demand from Germany's machinery sector absorbs excess edge computing inventory accumulated during 2022-2023 supply chain disruptions.
For Market Incumbents: Harden defensive positioning by deepening captive production of legacy protocol translation modules to lock in brownfield modernization cycles. Acquire edge computing specialists with deterministic control expertise to counter pure-play analytics vendors threatening mid-market channel relationships. Channel control in Stuttgart's machinery OEM cluster remains the critical lever against disaggregated procurement trends. For New Entrants and Emerging Players: Build out interoperability certifications for open API architectures targeting German automotive suppliers seeking to avoid Siemens-dominated vendor lock-in. Process industry edge computing in Gulf Coast petrochemical corridors represents the most penetrable white space, with autonomous process adjustment capabilities underserved by incumbent automation conglomerates. Lead with subscription-based pricing to bypass capital expenditure approval cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core software units amid pressure to rationalize overlapping analytics portfolios. Long-term viability hinges on regulatory compliance module depth rather than core algorithmic performance. Watch for EMA guidance expansion into AI validation requirements as the inflection signal for pharmaceutical-focused platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Orchestration Development | Hybrid architectures enable millisecond-level press adjustments for German automotive stamping plants. |
| Legacy Protocol Translation Acquisition | Brownfield PLC integration capabilities compress deployment cycles in Ruhr industrial belt retrofits. |
| EU AI Act Compliance Certification | Validated audit trails satisfy risk classification mandates for automated decision systems in production. |
| Mid-Market Channel Partnership Expansion | System integrator relationships capture retrofit demand outpacing greenfield installations. |
| Pharmaceutical Validation Infrastructure Investment | Algorithmic transparency documentation meets EMA guidance for medical device manufacturing. |
Methodological Framework
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and control systems integrators anchors the qualitative findings against secondary validation from SEC 10-K filings, customs and trade data, ECHA chemical registration databases, and EU emissions trading scheme disclosures. Bottom-up sizing of edge device shipments and top-down triangulation against automation vendor reported segment revenues converge on volume estimates.
Calibration against historical deployment cycles in Germany's automotive corridor and process industry capital expenditure patterns shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical regulatory exposure, integration complexity, and regional adoption pattern. CAGRs derive from curve-fitting observed procurement velocity against compliance mandate timelines. Industry-specific forecast inputs incorporate REACH reporting obligation phase-ins and FDA software validation guideline updates.
Stress conditions across semiconductor lead time volatility, EU AI Act enforcement intensity, and brownfield protocol heterogeneity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about OT-IT convergence adoption curves and regulatory scope expansion. Material shifts in export control regimes for deterministic control hardware would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Product Design and Development Market
Digital Solutions
Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
Utility App Market
Digital Solutions
Inventory Management Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Germany Content Services Platform Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
Revenue Management Software Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Chile ICT Market
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
Smart Card in Government Market
Digital Solutions
US Transcription Market
Digital Solutions
Spain Digital Twin Market