
 Inspection Lighting Fixture Market | 2026-2036
Inspection Lighting Fixture Market Size, Share, and Industry Trends Forecast 2026-2036
Inspection Lighting Fixture Market Foresight
LED solid-state technology is tilting the engineering stack away from legacy gas-discharge architectures toward chip-on-board and tunable spectral platforms. Luxo leverages its Nordic manufacturing heritage to dominate articulated-arm task luminaires for quality-control stations. Acuity Brands anchors North American commercial-industrial distribution through deep specification relationships with MRO distributors. Waldmann sustains German engineering credibility in machine-integrated inspection lighting for automotive paint booths.
Inspection lighting fixtures are engineered luminaires delivering controlled illuminance, color rendering indices exceeding 90, and glare-free beam patterns for defect detection in precision manufacturing. These fixtures typically incorporate aluminum heat sinks, polycarbonate or tempered glass lenses, and driver electronics calibrated to maintain consistent lux levels across 50,000-hour operational lives. LED product types now command the largest revenue share as lumen-per-watt efficiency crosses thresholds that make xenon and halogen alternatives structurally uncompetitive for new installations. Aerospace end-user demand represents the fastest-growing segment as airframe manufacturers tighten surface-defect protocols for composite materials. Portable installation formats carry premium pricing due to battery-pack integration and ingress-protection engineering for field inspection environments.
EPA energy-efficiency mandates and OSHA workplace-illumination standards shape product design requirements and market access conditions for equipment deployed in US facilities. The EU RoHS directive and CE marking framework restrict hazardous substance content and establish conformity pathways for fixtures sold into European manufacturing plants. Stakeholders must monitor how evolving photobiological safety standards from IEC and ISO influence spectral-output specifications and certification costs.
Market Dynamics
LED solid-state technology is compressing fixture lifecycles while the EU F-Gas Regulation accelerates mercury-lamp phaseouts, forcing capital redeployment across precision manufacturing facilities.
Growth Catalysts
- Aerospace surface-defect protocols:Airframe manufacturers tighten inspection standards for carbon-fiber composites, mandating high-CRI task lighting at assembly stations.
- EU F-Gas Regulation:The phaseout of mercury-containing fluorescent lamps creates replacement demand for LED retrofits in German automotive paint booths.
- Chip-on-board thermal management:Advances in aluminum heat-sink engineering enable 50,000-hour operational lifespans that structurally displace xenon alternatives.
Market Restraints
- Driver electronics cost volatility:Semiconductor supply concentration in East Asia creates input price instability for luminaire manufacturers.
- Photobiological safety certification:IEC spectral-output standards extend product validation timelines and raise compliance expenditures.
- Legacy fixture installed base:Functional gas-discharge units in mature industrial facilities delay replacement cycles despite efficiency penalties.
Strategic Opportunities
- Portable battery-integrated formats:Field inspection environments in wind-tower maintenance create premium pricing potential for IP-rated mobile luminaires.
- Tunable spectral platforms:Convergence of chip-on-board LEDs with IoT controls enables wavelength-adjustable systems for paint-matching applications.
- OSHA workplace-illumination standards:Updated federal mandates in the US drive specification upgrades for MRO distributor channels.
Industry Challenges
- Optical engineering talent scarcity:Specialized lens-design expertise for glare-free beam patterns concentrates in German precision-engineering clusters.
- Legacy control-system integration:Retrofitting smart LED drivers into existing DALI or analog infrastructures creates commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inspection Lighting Fixture Market |
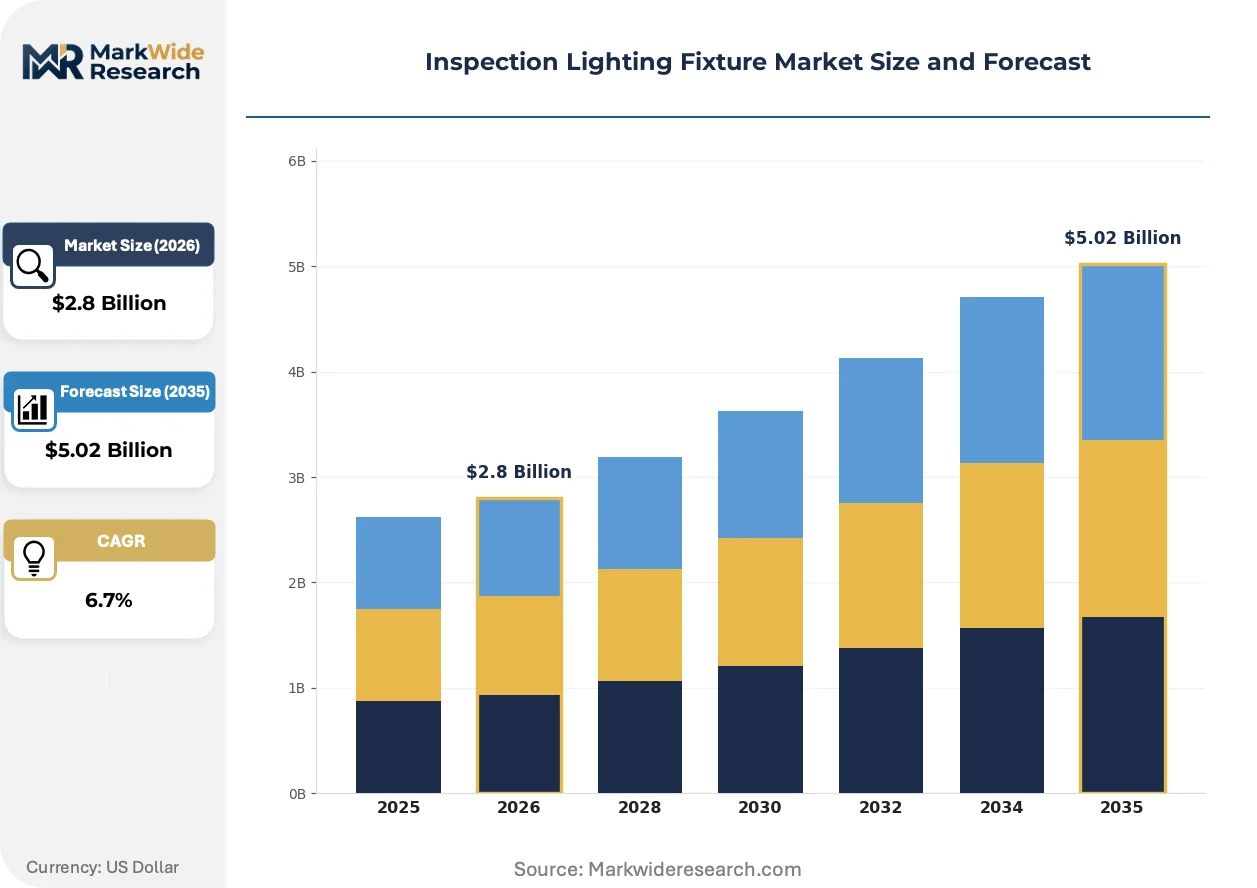
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Xenon, Fluorescent, Halogen End User: Manufacturing, Automotive, Aerospace, Electronics Installation: Suspended, Wall-mounted, Portable, Fixed Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Luxo, Dazor, Acuity Brands, Cree Lighting, O.C. White, Signify, Burton Medical, Cooper Lighting, Waldmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inspection Lighting Fixture Market Shifts & Advancements
Digital spectral control and connected fixture architectures are redefining how inspection tasks interface with quality-management systems across precision manufacturing.
Spectral-tunable LED engines are virtualizing the function of fixed-wavelength inspection lamps. Aerospace composite manufacturers adopt these platforms to switch between ultraviolet crack-detection and visible-light surface inspection without hardware swaps. The technology is virtualizing capital allocation decisions by collapsing multiple single-purpose fixtures into one reconfigurable unit.
The EU F-Gas Regulation bans mercury-containing lamps from January 2027, compressing retrofit timelines for fluorescent-dependent facilities. German automotive OEMs accelerate LED specification in paint-booth contracts to preempt compliance risk. Machine-integrated fixture suppliers face recertification costs but gain specification lock-in from early-mover positioning.
Buying committees now unbundle fixture procurement from installation and maintenance contracts, fragmenting vendor relationships. MRO distributors lose exclusivity as end-users source luminaires directly from manufacturers while outsourcing commissioning to electrical contractors. This pattern is most visible in North American commercial-industrial facilities with mature specification engineering capabilities.
Inspection Lighting Fixture Market Segmentation
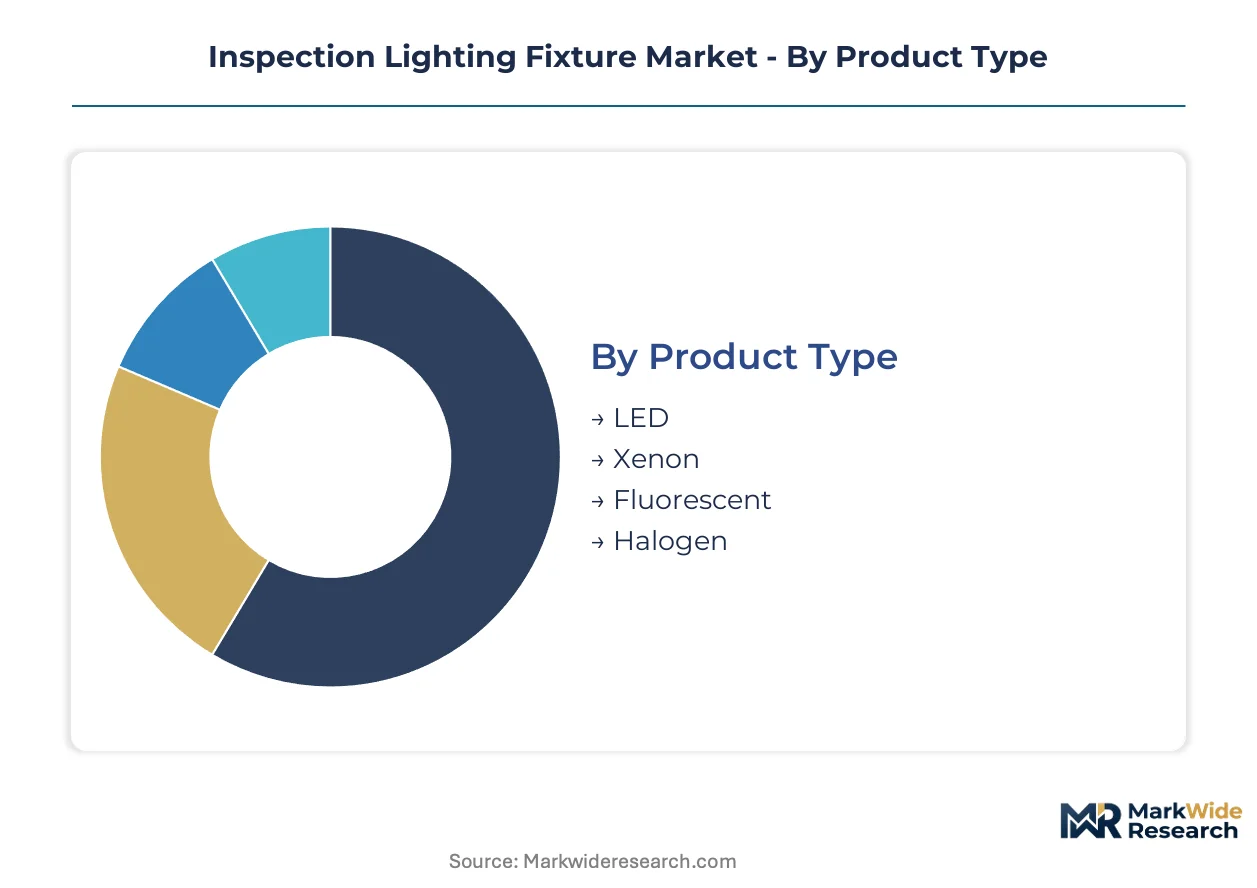
Segmentation in inspection lighting fixtures reveals how technical specifications, mounting constraints, and end-use severity create distinct procurement patterns. Manufacturers configure product portfolios around these divides to capture specification authority in precision manufacturing environments.
Product Type:
Technology maturity and regulatory phaseouts determine cost-to-performance positioning across the engineering stack.
- LED:Solid-state chip-on-board architectures deliver tunable spectral output and 50,000-hour operational lifespans. EU F-Gas Regulation mandates accelerate specification in German automotive paint booths where mercury-lamp retrofits face hard deadlines.
- Xenon:Gas-discharge technology maintains residual demand in ultraviolet crack-detection applications requiring intense point-source output. Aerospace NDT protocols in US airframe facilities sustain niche procurement despite LED encroachment.
- Fluorescent:Mercury-vapor linear tubes face structural phaseout under REACH and RoHS restrictions across European manufacturing plants.
- Halogen:Tungsten-halogen incandescence persists in low-cost portable formats for field maintenance where spectral precision is secondary to immediate availability.
LED commands the established base. The steepest expansion runs through chip-on-board platforms with integrated thermal management.
End User:
Application severity and defect-detection protocols create divergent specification requirements across precision industries.
- Manufacturing:General industrial quality-control stations demand consistent CRI 90+ output for surface-defect identification. OSHA workplace-illumination standards drive specification upgrades in US metal fabrication and machining facilities.
- Automotive:Paint-matching booths and final inspection lines require spectral-tunable systems for color consistency validation. German OEMs specify machine-integrated fixtures to preempt EU F-Gas compliance exposure.
- Aerospace:Carbon-fiber composite inspection mandates high-CRI task lighting at assembly stations. FAA surface-defect protocols for airframe manufacturers tighten lux-level requirements for crack detection.
- Electronics:PCB solder-joint inspection demands glare-free beam patterns and minimal heat emission. Semiconductor cleanrooms in South Korea and Taiwan specify low-profile suspended formats to preserve laminar airflow.
Aerospace climbs the fastest as composite airframe production scales. Manufacturing retains the largest installed base across mature industrial corridors.
Installation:
Mounting configuration determines ingress-protection engineering and commissioning complexity in deployment environments.
- Suspended:Overhead cable or pendant mounting dominates cleanroom and paint-booth applications where floor space is constrained. German precision-engineering clusters specify articulated-arm variants for adjustable task positioning.
- Portable:Battery-integrated mobile units command premium pricing for wind-tower maintenance and field NDT operations. IP65+ ratings protect driver electronics from particulate and moisture ingress in outdoor deployment.
- Wall-mounted:Fixed-position bracket installation serves permanent inspection stations in automotive assembly lines where workflow geometry is static.
- Fixed:Hardwired ceiling or structural mounting provides highest reliability for 24/7 continuous-operation facilities with minimal reconfiguration needs.
Suspended formats anchor revenue concentration in machine-integrated applications. Portable configurations gain share fastest in renewable energy maintenance sectors.
Power Rating:
Wattage tiers map directly to illuminance output, thermal load, and driver electronics cost structures.
- Low Power:Sub-20W LED engines serve benchtop electronics inspection and small-part metrology where heat dissipation is minimal.
- Medium Power:20-50W systems balance output and efficiency for general manufacturing quality stations across US commercial-industrial facilities.
- High Power:50-100W chip-on-board arrays penetrate aerospace paint booths and large-surface composite inspection where lux requirements exceed 1,500.
- Ultra High Power:Above-100W specialized luminaires address ultraviolet curing and high-speed line inspection in automotive OEM contracts.
Medium power dominates unit volume in retrofit markets. Ultra high power posts the steepest trajectory as automotive line speeds intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The inspection lighting fixture trade flows reflect Germany's precision-engineering export dominance against import dependence in emerging manufacturing hubs. Net exporters cluster around EU regulatory leadership, while aerospace-intensive economies source high-CRI task luminaires from established supply bases.
Germany
Automotive paint booths and machine-integrated inspection stations drive specification volume. The EU F-Gas Regulation's January 2027 mercury-lamp ban accelerates LED retrofit contracts. The Stuttgart-Munich engineering corridor concentrates Waldmann and Luxo manufacturing for automotive OEM compliance programs.
United States
Aerospace composite inspection and OSHA-mandated workplace upgrades sustain demand across airframe facilities. FAA surface-defect protocols for carbon-fiber airframes tighten lux-level requirements. The Pacific Northwest aerospace cluster and Southeast automotive belt anchor specification authority for MRO distributors.
China
Electronics PCB inspection and semiconductor cleanroom expansion create volume demand for low-profile suspended formats. MIIT energy-efficiency directives pressure domestic manufacturers toward solid-state architectures. The Yangtze River Delta and Pearl River Delta concentrate electronics manufacturing requiring glare-free beam engineering.
Japan
Precision metrology and automotive quality-control stations maintain premium specification standards. METI industrial efficiency programs incentivize 50,000-hour LED lifespans in continuous-operation facilities. The Chubu-Nagoya automotive engineering belt drives machine-integrated fixture procurement.
South Korea
Semiconductor cleanroom construction and display-panel inspection sustain demand for minimal-heat-emission luminaires. MFDS and KOSHA workplace standards align with IEC photobiological safety certifications. The Seoul Capital Area and Busan-Ulsan manufacturing zones specify suspended formats for laminar airflow preservation.
Inspection Lighting Fixture Market Competitive Landscape
On the supply side, the industry is consolidating around Nordic-German precision engineering heritage and North American distribution scale. Tiered competitive positioning separates specification-led task luminaire specialists from volume-driven commercial-industrial suppliers. Strategic archetypes include articulated-arm engineering specialists, MRO channel anchors, and machine-integrated fixture developers. Dominant competitive moves encompass geographic specification lock-in through early regulatory compliance and portfolio diversification into tunable spectral platforms.
Within the precision-engineering specialist tier, Luxo leverages its Nordic manufacturing heritage while Waldmann occupies German automotive paint-booth specification channels. Acuity Brands anchors North American commercial-industrial distribution through specification relationships with MRO networks. These three exemplify how engineering credibility and channel control create defensive positioning against LED commoditization pressures.
| Leading Market Players |
|---|
| Luxo |
| Dazor |
| Acuity Brands |
| Cree Lighting |
| O.C. White |
| Signify |
| Burton Medical |
| Cooper Lighting |
| Waldmann |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese LED chip fabrication is compressing component costs while simultaneously eroding supplier pricing power across German and Nordic fixture assemblers. This utilization imbalance forces tier-one manufacturers toward specification-led differentiation and extended warranty bundling to defend margin structures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the inspection lighting fixture market. Price differentiation hinges on IEC photobiological safety certification tier and volume scale commitments from automotive OEMs. Cost compression in mid-power LED tiers is intensifying because semiconductor foundry overcapacity in East Asia feeds component spot-market softness. Tier-one aerospace procurement teams exhibit lowest price sensitivity due to FAA-mandated surface-defect protocol compliance, while metal fabrication job shops in mature industrial corridors represent the most price-elastic segment.
Supply Chain Analysis
Extended payment terms from German automotive OEMs now stretch to 90-120 days, forcing tier-two Taiwanese driver electronics suppliers into supply-chain finance facilities. Aluminum heat-sink fabrication concentrates in China, Germany, and Mexico, while chip-on-board LED engines draw from South Korean and Chinese foundries. Single-source vulnerability in gallium nitride wafer supply creates exposure to export restriction shocks. Distribution runs through MRO distributor networks in North America and direct manufacturer relationships in European precision-engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inspection lighting fixture market represents high-growth disruption as solid-state LED architectures displace mercury-lamp infrastructure ahead of hard regulatory deadlines. The EU F-Gas Regulation's January 2027 compliance inflection compresses replacement timelines and concentrates specification authority among early-mover suppliers.
For Market Incumbents: Insulate specification lock-in by accelerating EU F-Gas compliance certification ahead of the 2027 deadline, locking out laggard competitors from German automotive paint-booth contracts. Deepen backward integration into chip-on-board thermal management engineering to capture margin from driver electronics cost volatility. Prioritize articulated-arm IP development to defend against emerging Asian competitors in portable format segments.
For New Entrants and Emerging Players: Southeast Asian electronics manufacturing corridors present underpenetration for low-profile suspended formats serving semiconductor cleanroom expansion. Wind-tower maintenance operators in North American renewable energy clusters offer white-space demand for IP65-rated battery-integrated portable units. Pursue specification authority through direct engagement with electrical contractors rather than contested MRO distributor channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across chip-on-board LED engine manufacturing as foundry scale economies mature. Long-term viability over the coming decade favors acquisition targets with established IEC photobiological safety certification pathways and machine-integrated fixture engineering capabilities. Monitor EU F-Gas Regulation enforcement intensity and German automotive OEM contract award velocity as primary inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Tunable Spectral Platform Development | Enables wavelength-adjustable systems for automotive paint-matching applications without hardware swaps. |
| EU F-Gas Compliance Prepositioning | Captures specification lock-in from German automotive OEMs ahead of January 2027 mercury-lamp ban. |
| Portable Battery-Integrated Format Launch | Addresses premium pricing potential in wind-tower maintenance and field NDT deployment environments. |
| Backward Integration into Thermal Management | Secures margin control over aluminum heat-sink engineering for 50,000-hour operational lifespan claims. |
| Direct Electrical Contractor Engagement | Circumvents MRO distributor exclusivity fragmentation in North American commercial-industrial procurement. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Plant engineers, quality-control directors at aerospace OEMs, automotive paint-booth specification leads, MRO distributor category managers, and electrical contractor project supervisors provided operational perspective. Secondary sources include EU F-Gas Regulation implementation documents, OSHA workplace-illumination standard updates, IEC photobiological safety technical specifications, and SEC filings from listed lighting fixture manufacturers. Bottom-up demand modeling triangulates against top-down market sizing across product type, end-user industry, installation format, and power rating segments.
Calibration against historical retrofit cycle data and regulatory compliance timeline acceleration ensures forecast robustness across the projection horizon. Segmentation dimensions span LED chip-on-board versus legacy gas-discharge architectures, aerospace versus automotive versus electronics end-use applications, suspended versus portable versus fixed mounting configurations, and low through ultra-high power wattage tiers. CAGRs derive from regression analysis of technology substitution curves and capital expenditure patterns in precision manufacturing facilities. Industry-specific inputs incorporate EU F-Gas Regulation phaseout velocity and FAA surface-defect protocol amendment trajectories.
Practitioners should monitor semiconductor supply concentration shifts and EU regulatory enforcement intensity for early signals of forecast deviation. Forecasts reflect assumptions regarding technology substitution rates, regulatory deadline adherence, and capital redeployment timelines in mature industrial facilities. Macroeconomic contraction, tariff escalation on aluminum or semiconductor components, or technological breakthrough in alternative solid-state architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
US Indoor LED Lighting Market
Lighting
Europe Decorative Lighting Market
Lighting
Solar Spotlights Market
Lighting
High-End Lighting Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Global Lighting Control System Market
Lighting
GCC Smart Lighting Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
Lighting Control Components Market
Lighting
North America Smart Lighting Market
Lighting
Germany Indoor LED Lighting Market
Lighting
Wireless Lighting Market
Lighting
Miniature Bulbs Market
Lighting
Malaysia LED Lighting Controllers Market
Lighting
Human Centric Lighting Market
Lighting
Explosion Proof Lighting Market