
 Nigeria Power Market | 2026-2036
Nigeria Power Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Power Market Outlook
Gas-to-solar hybridization is recalibrating plant economics across Nigerian generation assets. Transcorp Power Limited leverages its integrated gas infrastructure to sustain baseload competitiveness in the Lagos-Ibadan corridor. Egbin Power PLC anchors the national grid with West Africa's largest thermal complex, while Mainstream Energy Solutions Limited specializes in hydroelectric operations across the Kainji-Jebba cascade.
Nigeria Power encompasses electricity generation, transmission, and distribution infrastructure operating across voltage classes from 11 kV distribution to 330 kV transmission, with installed thermal capacity predominantly fueled by domestic gas from the Niger Delta basin. The system serves industrial load centers, urban residential clusters, and rural settlements through a combination of grid-connected and isolated mini-grid architectures. Thermal generation occupies the dominant share of current output, though renewable segments are attracting capital as solar PV costs decline and regulatory frameworks mature. The 100-500 MW capacity band captures concentrated investment from captive power seekers in cement and fertilizer manufacturing, while distribution service types present the most acute structural constraint due to legacy infrastructure deficits and revenue collection gaps.
The Nigerian Electricity Regulatory Commission sets tariff methodologies and licensing terms that determine developer returns across generation and distribution segments. The Rural Electrification Agency administers off-grid regulations and mini-grid permits that shape rural market access conditions for independent power producers. Stakeholders must monitor regulatory clarity on cost-reflective tariff implementation and the liquidity of the Nigerian Bulk Electricity Trader as determinants of capital deployment timing.
Market Dynamics
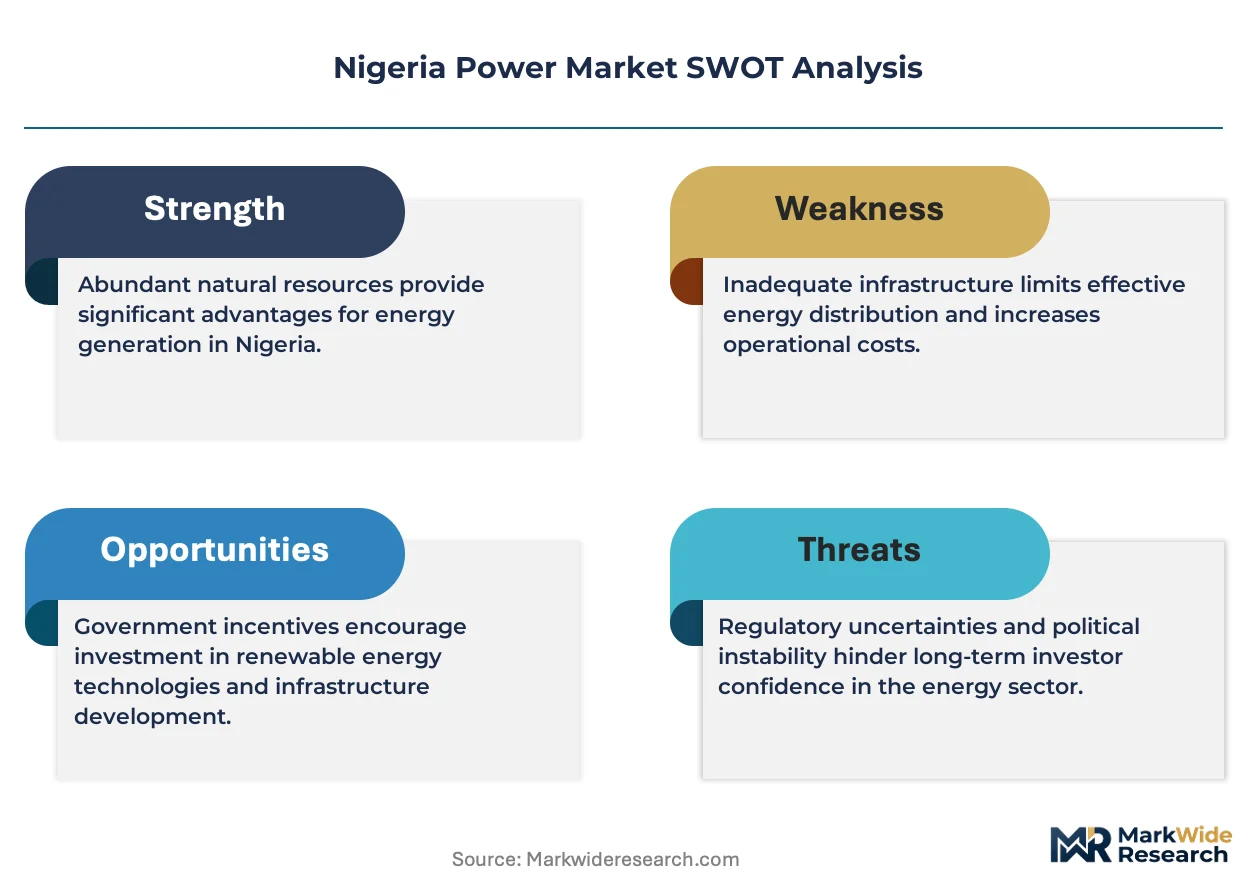
Gas-to-solar hybridization is recalibrating plant economics across Nigerian generation assets, forcing developers to restructure capital deployment around dual-fuel flexibility rather than single-source dependency.
Growth Catalysts
- Rural Electrification Agency mini-grid licensing:The REA's simplified permitting framework for solar mini-grids is accelerating off-grid deployment in unserved settlements across northern states.
- Cement sector captive demand:Industrial clusters in the Niger Delta are procuring dedicated 100-500 MW capacity blocks to secure baseload supply independent of grid instability.
- Domestic gas reserve monetization:Thermal developers are leveraging Niger Delta basin feedstock to sustain cost-competitive output against imported fuel alternatives.
Market Restraints
- Nigerian Bulk Electricity Trader liquidity constraints:Payment arrears to generation companies are compressing developer cash flows and deterring greenfield investment.
- Transmission infrastructure deficit:The 330 kV backbone suffers persistent technical losses and inadequate wheeling capacity to evacuate new generation.
- Distribution network dilapidation:Legacy 11 kV infrastructure across DisCo territories records collection inefficiencies exceeding 40 percent of billed revenue.
Strategic Opportunities
- Agro-processing electrification:Rice milling and cold chain clusters in Kebbi and Benue states present anchor load profiles for isolated mini-grid business models.
- Nigerian Electricity Regulatory Commission cost-reflective tariff pathway:The Multi-Year Tariff Order framework offers revenue predictability for investors willing to accept regulated returns.
- Battery storage hybridization:Lithium-ion integration with existing gas turbines is enabling frequency regulation services and peak shaving for Lagos-Ibadan industrial corridors.
Industry Challenges
- Grid synchronization engineering shortage:Qualified protection and control specialists capable of integrating variable renewable output with thermal baseload remain scarce in the domestic labor pool.
- Legacy meter asset incompatibility:DisCos face capital-intensive replacement cycles for electromechanical meters that cannot support time-of-use billing or remote disconnect functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Power Market |
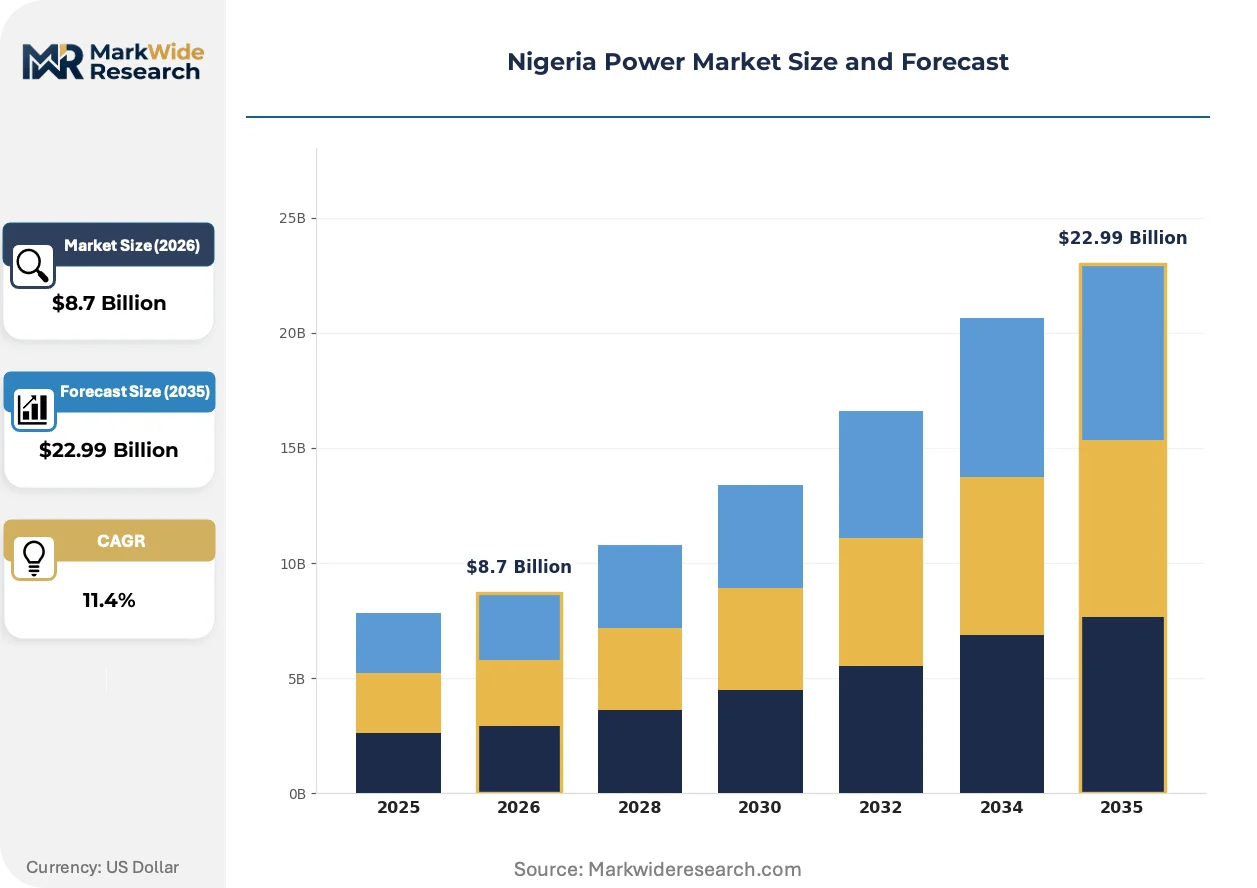
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Thermal, Hydro, Nuclear End User: Residential, Commercial, Industrial, Government Service Type: Generation, Transmission, Distribution, Maintenance Capacity: Under 100 MW, 100-500 MW, 501-1000 MW, Above 1000 MW |
| Companies Covered | Transcorp Power Limited, Egbin Power PLC, First Independent Power Ltd, BEDC Electricity PLC, Abuja Electricity Distribution Company PLC, Mainstream Energy Solutions Limited, The Transmission Company of Nigeria, Yola Electricity Distribution Company, Sapele Power Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Power Market Strategic Shifts
Technology convergence and regulatory recalibration are compressing deployment timelines for decentralized generation assets while elevating performance standards for grid-connected infrastructure.
Containerized solar PV plus battery systems are absorbing stranded capacity from underutilized distribution feeders in Kaduna and Enugu states. Commercial and industrial off-takers in these corridors are deploying 2-10 MW modular blocks within 90-day procurement cycles. This absorption pattern is compressing the addressable market for traditional diesel backup generators in the 500 kW to 5 MW range.
The Nigerian Electricity Regulatory Commission's Service Based Tariff framework mandates incremental performance benchmarks for distribution companies. DisCos must now demonstrate measurable reduction in outage frequency and duration to qualify for tariff adjustments. Lagos and Abuja distribution territories are responding with accelerated transformer rehabilitation and feeder segmentation programs.
Industrial procurement committees are consolidating vendor relationships around integrated engineering-procurement-construction contractors capable of delivering hybrid gas-solar solutions. Cement and steel producers in Ogun and Delta states are favoring single-point accountability over fragmented equipment sourcing. This concentration is visible most acutely in the 50-200 MW engineering packages tendered by manufacturing conglomerates seeking captive power independence.
Nigeria Power Market Segmentation
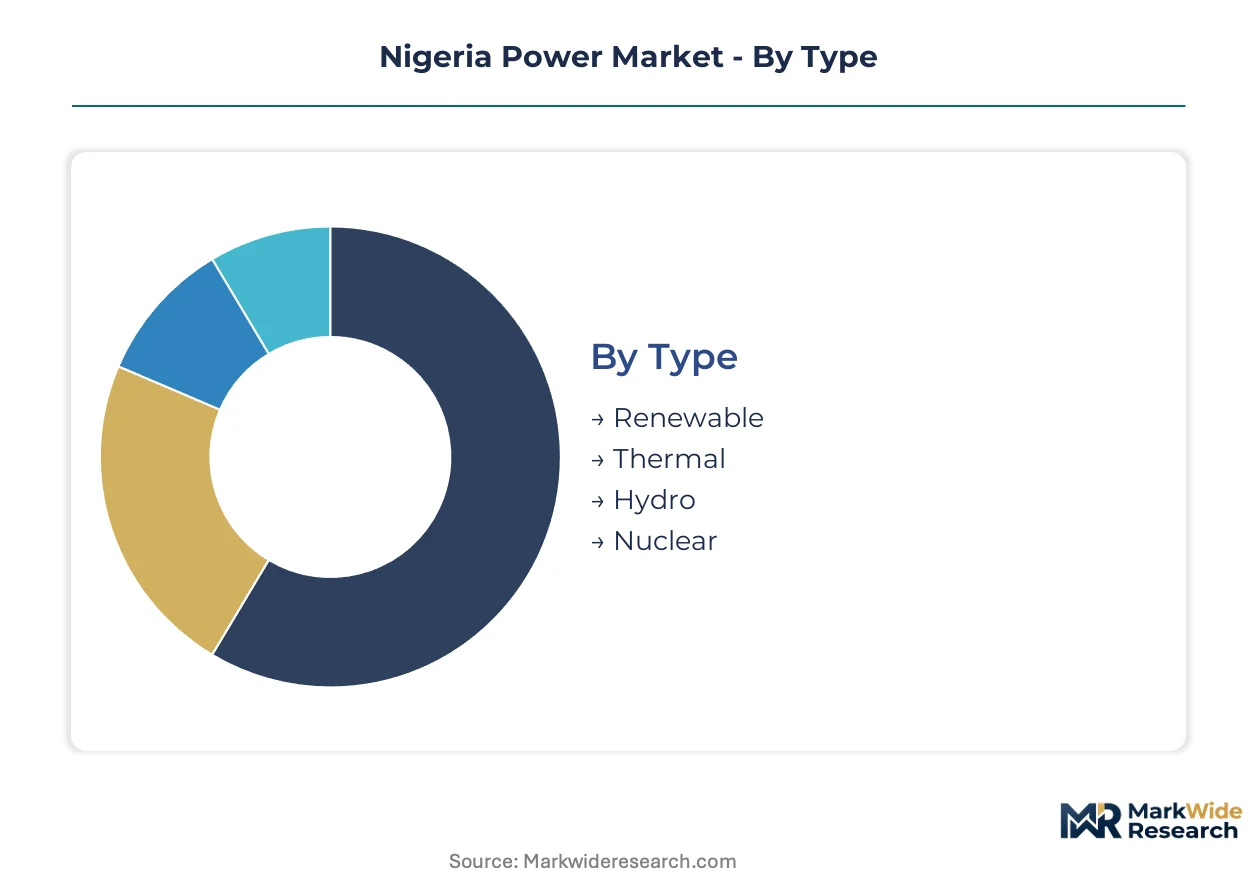
Power asset configuration in Nigeria diverges sharply across buyer priorities. Generation technology choices, end-use load profiles, and service procurement models each create distinct commercial entry points for developers and equipment suppliers.
Type:
Buyers differentiate primarily by fuel security preference and capital recovery timeline rather than carbon intensity alone.
- Thermal:Gas-fired turbines and reciprocating engines dominate current installed base, leveraging Niger Delta domestic feedstock to deliver dispatchable output. Cement and steel producers in Ogun and Delta states anchor demand for combined-cycle configurations that guarantee baseload independence from grid instability.
- Renewable:Solar PV arrays with lithium-ion storage are capturing commercial and industrial off-takers in Kaduna and Enugu states seeking 90-day deployment cycles. The Rural Electrification Agency's mini-grid licensing framework is accelerating village-scale deployments across northern settlements previously dependent on diesel generators.
- Hydro:Run-of-river and reservoir stations along the Niger and Benue river systems supply grid-firming capacity. Mainstream Energy Solutions operates the Kainji-Jebba cascade that anchors northwestern baseload.
- Nuclear:No operational capacity exists; feasibility studies for small modular reactor deployment remain preliminary with the Nigerian Atomic Energy Commission.
Volume sits with thermal assets; growth tilts toward renewable hybridization.
End User:
Load characteristics and tariff tolerance separate procurement behaviors across customer classes.
- Industrial:Manufacturing clusters in Lagos-Ibadan and Kano corridors procure 100-500 MW captive blocks through engineering-procurement-construction contracts. Dangote Cement and BUA Group operations demand guaranteed availability above cost minimization.
- Commercial:Shopping complexes, hospitality chains, and banking infrastructure in Abuja and Port Harcourt deploy 2-10 MW containerized solar-plus-storage systems. Nigerian Electricity Regulatory Commission Service Based Tariff exposure drives interest behind-the-meter solutions.
- Residential:Urban metered customers in DisCo territories face collection inefficiencies exceeding 40 percent; rural settlements without grid access represent the addressable base for solar mini-grid developers.
- Government:Federal ministries and state hospitals procure through Bureau of Public Procurement frameworks with extended payment cycles that strain developer liquidity.
Revenue concentration clusters in industrial offtake; expansion opportunity concentrates in commercial distributed generation.
Service Type:
Value chain positioning determines exposure to Nigerian Bulk Electricity Trader payment arrears versus direct customer relationships.
- Generation:Independent power producers sell output to the Nigerian Bulk Electricity Trader under power purchase agreements with tariff adjustments governed by Multi-Year Tariff Order methodology. Egbin Power and Transcorp Power anchor thermal capacity.
- Distribution:Eleven DisCo franchises hold exclusive licenses for 11 kV and 33 kV network operations with performance benchmarks tied to Service Based Tariff qualification. Transformer rehabilitation and feeder segmentation absorb capital deployment.
- Transmission:The Transmission Company of Nigeria manages 330 kV backbone infrastructure with persistent technical losses and inadequate wheeling capacity constraining new generation evacuation.
- Maintenance:Third-party operations and maintenance contractors service gas turbines and balance-of-plant equipment for industrial captive power operators seeking to avoid original equipment manufacturer dependency.
Capital intensity peaks in generation; margin stability favors maintenance and industrial captive distribution.
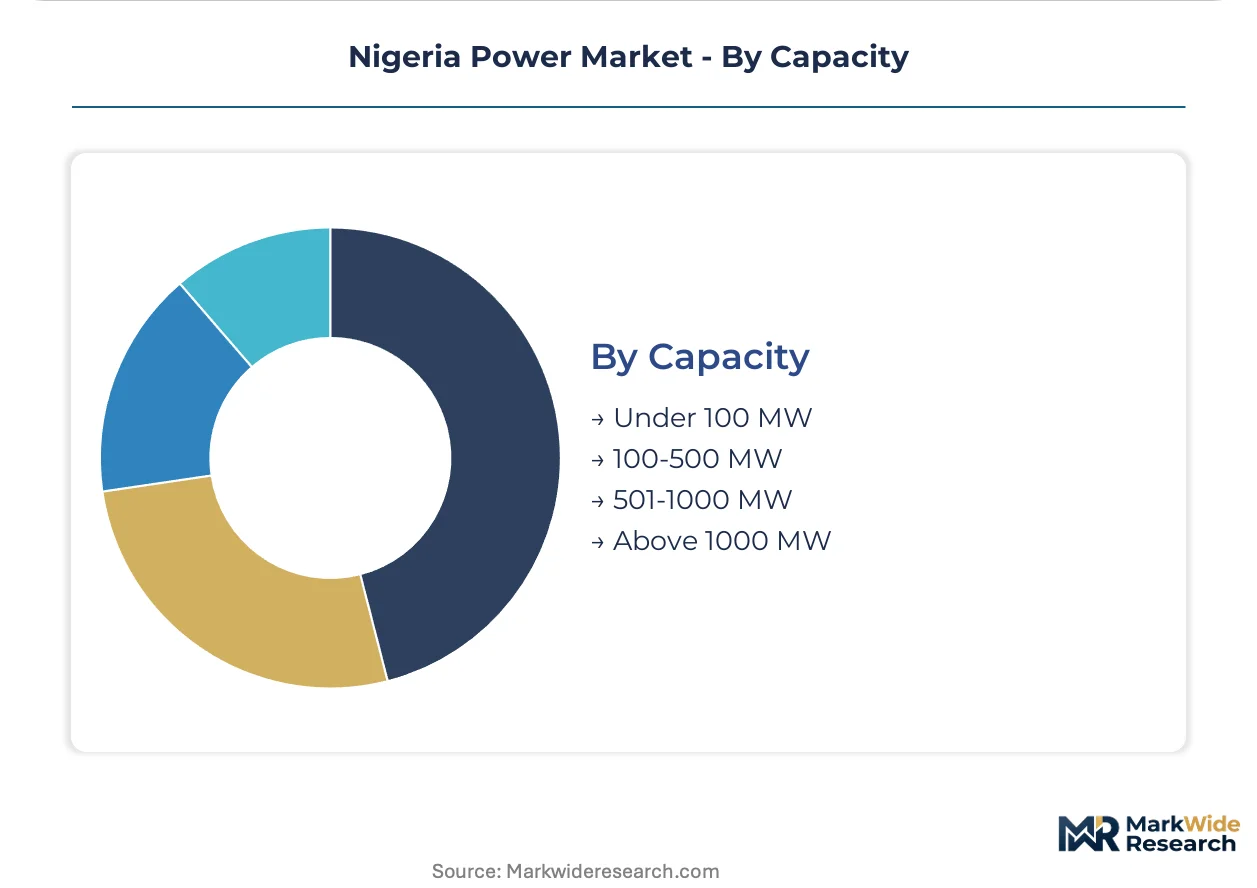
Capacity:
Project scale dictates financing structure, technology selection, and regulatory jurisdiction.
- 100-500 MW:Combined-cycle gas turbines and utility-scale solar arrays serve cement, fertilizer, and steel producers seeking baseload autonomy. Engineering-procurement-construction contractors deliver integrated hybrid solutions with single-point accountability.
- Under 100 MW:Modular solar PV, battery storage, and reciprocating engine configurations address commercial and industrial load centers. Containerized systems compress procurement cycles to 90 days in Kaduna and Enugu states.
- 501-1000 MW:Large thermal complexes require gas pipeline infrastructure and grid interconnection agreements with the Transmission Company of Nigeria. Egbin Power's Lagos facility represents the dominant domestic example.
- Above 1000 MW:No operational assets exist at this scale; future hydroelectric expansion on the Mambilla plateau would require transmission corridor development through challenging terrain.
Investment flow concentrates in the 100-500 MW band; pipeline visibility is strongest for sub-100 MW distributed solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nigerian Export Processing Zones Authority licenses industrial enclaves that concentrate captive power demand. Tax holidays and duty exemptions on generation equipment imports draw manufacturing clusters to designated corridors. These zones anchor regional variation in power infrastructure development.
Lagos-Ibadan Corridor
Dangote Cement and BUA Group operations drive 100-500 MW captive power procurement in Ogun State. The Nigerian Electricity Regulatory Commission Service Based Tariff framework mandates performance benchmarks for Ikeja Electric. Containerized solar-plus-storage systems compress deployment cycles to 90 days for commercial off-takers in Lagos Island business districts.
Niger Delta Basin
Domestic gas reserve monetization sustains thermal generation economics across Rivers and Delta states. The Nigerian Bulk Electricity Trader power purchase agreements govern independent power producer returns in Port Harcourt industrial zones. Egbin Power anchors grid stability through West Africa's largest thermal complex sited near Lagos.
Kano Industrial Cluster
Textile and agro-processing facilities in Kano and Kaduna states procure modular 2-10 MW solutions behind the meter. The Rural Electrification Agency mini-grid licensing framework accelerates solar deployment in unserved northern settlements. Northern DisCo territories record the highest collection inefficiencies, exceeding 40 percent of billed revenue.
Abuja Federal Capital Territory
Government ministries and embassy compounds demand guaranteed power availability through independent power producer arrangements. The Bureau of Public Procurement frameworks extend payment cycles that strain developer liquidity. Abuja Electricity Distribution Company rehabilitates transformer assets to qualify for tariff adjustments under performance-based regulation.
Southeast Manufacturing Belt
Steel and ceramics producers in Enugu and Anambra states favor reciprocating engine configurations for operational flexibility. The Transmission Company of Nigeria's 330 kV backbone suffers inadequate wheeling capacity constraining new generation evacuation. Sapele Power Plc operates legacy thermal assets serving industrial load centers across the region.
Nigeria Power Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated generation developers commanding premium positions in captive power while modular equipment suppliers capture distributed commercial demand. The market structures around three tiers: utility-scale thermal operators, hydroelectric baseload providers, and emerging solar hybrid specialists. Consolidation pressure concentrates among generation assets where Nigerian Bulk Electricity Trader liquidity constraints favor balance-sheet strength. Strategic moves center on gas-to-solar hybridization retrofits and engineering-procurement-construction integration for industrial offtakers.
Among Nigerian-anchored power developers, Transcorp Power Limited and Egbin Power PLC exemplify the integrated thermal operator archetype with gas infrastructure leverage, while Mainstream Energy Solutions Limited represents the hydroelectric specialist position across the Kainji-Jebba cascade. These entities occupy positions that reflect the market's segmentation between baseload grid supply and captive industrial solutions.
| Leading Market Players |
|---|
| Transcorp Power Limited |
| Egbin Power PLC |
| First Independent Power Ltd |
| BEDC Electricity PLC |
| Abuja Electricity Distribution Company PLC |
| Mainstream Energy Solutions Limited |
| The Transmission Company of Nigeria |
| Yola Electricity Distribution Company |
| Sapele Power Plc |
| Others |
Value Chain & Pricing Dynamics
Captive gas infrastructure integration anchors both supply security and pricing power for thermal generators serving Nigeria's industrial corridors. Developers with upstream control over Niger Delta feedstock command premium positioning in power purchase negotiations, while modular solar entrants compete on deployment velocity rather than fuel cost leverage.
Pricing Analysis
Volume concentrates in long-term offtake contracts with cement and steel producers, while margins accrue to hybrid engineering-procurement-construction providers. Price differentiation separates integrated gas-solar solutions from standalone diesel backup through reliability guarantees and fuel hedge value. Pricing pressure stems from Nigerian Bulk Electricity Trader liquidity constraints compressing independent power producer returns. Industrial offtakers demonstrate lowest price sensitivity due to grid instability costs, while commercial distributed generation buyers prioritize capital efficiency.
Supply Chain Analysis
Equipment certification through Nigerian Electricity Regulatory Commission standards gates supplier participation in grid-connected projects. Generation hardware draws from China, Germany, and South Korea for turbines, inverters, and switchgear components. Lithium-ion cells and solar modules feed from East Asian manufacturing hubs. Single-source vulnerability concentrates in gas turbine original equipment manufacturer networks. Distribution runs through engineering-procurement-construction contractors with Bureau of Public Procurement registration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria's power market operates as a supply-constrained environment where transmission wheeling deficits and DisCo collection inefficiencies prop pricing for captive solutions. The 330 kV backbone inadequacy sustains premium capture for behind-the-meter alternatives.
For Market Incumbents: To counter modular solar hybridization threatening thermal market share, Transcorp Power and Egbin Power should accelerate gas-to-solar retrofit engineering capabilities and secure exclusive pipeline access through Niger Delta joint ventures. Backward integration into gas processing infrastructure preserves fuel cost advantages against renewable entrants.
For New Entrants and Emerging Players: Enter via the Rural Electrification Agency mini-grid licensing pathway targeting unserved northern settlements with containerized solar-plus-storage configurations. The commercial and industrial segment in Kaduna and Enugu states presents the most penetrable white space, accessible through 90-day deployment value propositions and direct power purchase agreements bypassing Nigerian Bulk Electricity Trader exposure.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated energy conglomerates seeking captive generation portfolios. Long-term viability centers on developers with demonstrated offtaker relationships and hybrid technology integration capabilities. Watch Nigerian Electricity Regulatory Commission cost-reflective tariff implementation as the inflection signal for distribution segment rehabilitation capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Gas-to-Solar Hybrid Retrofit | Enables thermal operators to capture renewable premiums while preserving baseload reliability for industrial offtakers. |
| Mini-Grid Licensing Acceleration | Rural Electrification Agency permits unlock village-scale deployment economics previously blocked by regulatory uncertainty. |
| Captive Power Engineering Integration | Single-point EPC accountability reduces procurement friction for cement and steel producers seeking 100-500 MW blocks. |
| Distribution Transformer Rehabilitation | DisCo investment in 11 kV infrastructure qualifies operators for Service Based Tariff adjustments under performance benchmarks. |
| Battery Storage Hybridization | Lithium-ion integration with gas turbines enables frequency regulation services for Lagos-Ibadan industrial corridors. |
Study Parameters
Multi-period observation of Nigerian Bulk Electricity Trader payment flows, Rural Electrification Agency licensing volumes, and Transmission Company of Nigeria wheeling capacity anchored the trend analysis, supplemented by interviews with independent power producer development officers, EPC contractor project managers, DisCo technical directors, and Nigerian Electricity Regulatory Commission tariff specialists. Secondary validation drew from Bureau of Public Procurement contract disclosures, Nigerian Electricity Supply Industry statistics, and generation company financial filings. Bottom-up project pipeline assessment triangulated against top-down macroeconomic demand modeling.
Input-output matrices mapped fuel source, generation capacity tier, and regulatory framework segmentation across the projection horizon. CAGRs derived from capacity addition schedules, offtaker contract tenors, and capital cost trajectories for solar PV and battery storage technologies. Modeled variables included gas price volatility scenarios, mini-grid deployment licensing velocity, and Service Based Tariff compliance thresholds.
Revisions become necessary when Nigerian Electricity Regulatory Commission tariff methodology shifts, Nigerian Bulk Electricity Trader liquidity crises deepen, or transmission infrastructure investment accelerates beyond baseline assumptions. A model refresh is warranted upon material change in Rural Electrification Agency permitting velocity or industrial captive power procurement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Direct Current Power System Market
Power
Modular PSA Nitrogen Generator Market
Power
Controllable Shunt Reactor for UHV Market
Power
Residential Portable Inverter Generator Market
Power
Electric Power Sports Market
Power
Global Advanced Marine Power Supply Market
Power
Power Capacitors Market
Power
Resonant Power Converters Market
Power
Solar Plants Controllers Market
Power
Power Purchase Agreement Market
Power
Iran Power Market
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
Saudi Arabia Power Market
Power
North America CHP Market
Power
Canada Thermal Power Market
Power
Rotating Phase Converter Market