
 EV Platform Market | 2026-2036
EV Platform Market Size, Share, and Industry Trends Forecast 2026-2036
EV Platform Market Intelligence
A shift from traditional OEMs towards new electric-native vehicle assemblers is rebalancing the customer base for standalone EV platforms. The Volkswagen Group leverages its modular MEB platform across multiple brands to achieve scale. General Motors differentiates with its Ultium battery and platform architecture. Meanwhile, BYD sustains a competitive advantage through its in-house production of batteries and other core platform components.
An EV platform is a standardized chassis structure that integrates the battery pack, motors, and drivetrain components, often in a 'skateboard' configuration. This design provides a scalable foundation for developing various vehicle models with reduced cost and time. Battery Electric platforms command the majority of investment and development focus. While Personal Transportation applications constitute the core market, platforms designed for Commercial Fleet use cases are seeing the most significant new investment.
Regulatory frameworks are a primary catalyst for platform development. The US EPA's vehicle emissions standards, China's dual carbon goals, and the EU Green Deal all mandate a transition to zero-emission vehicles. These policies directly compel automakers to invest in dedicated EV architectures. The central strategic decision for vehicle manufacturers now revolves around building proprietary platforms versus licensing third-party designs.
Market Dynamics
The imperative to standardize components for cost reduction, driven by stringent emissions regulations like the EU Green Deal and China's dual carbon goals, is the central force shaping the EV platform market. This compels automakers to adopt modular architectures to compete on scale.
Growth Catalysts
- Regulatory Mandates:Policies including the US EPA's emissions standards and the EU Green Deal require a transition to zero-emission vehicles, directly stimulating investment in dedicated EV architectures over modifying internal combustion engine platforms.
- Modular Architecture Adoption:The use of standardized skateboard chassis designs enables automakers to achieve economies of scale and accelerate the launch of diverse models, from sedans to light commercial vehicles, from a common base.
- Commercial Fleet Electrification:Demand from logistics and last-mile delivery operators for purpose-built electric vans and trucks necessitates the development of durable, high-utilization platforms distinct from those used in personal transport.
Market Restraints
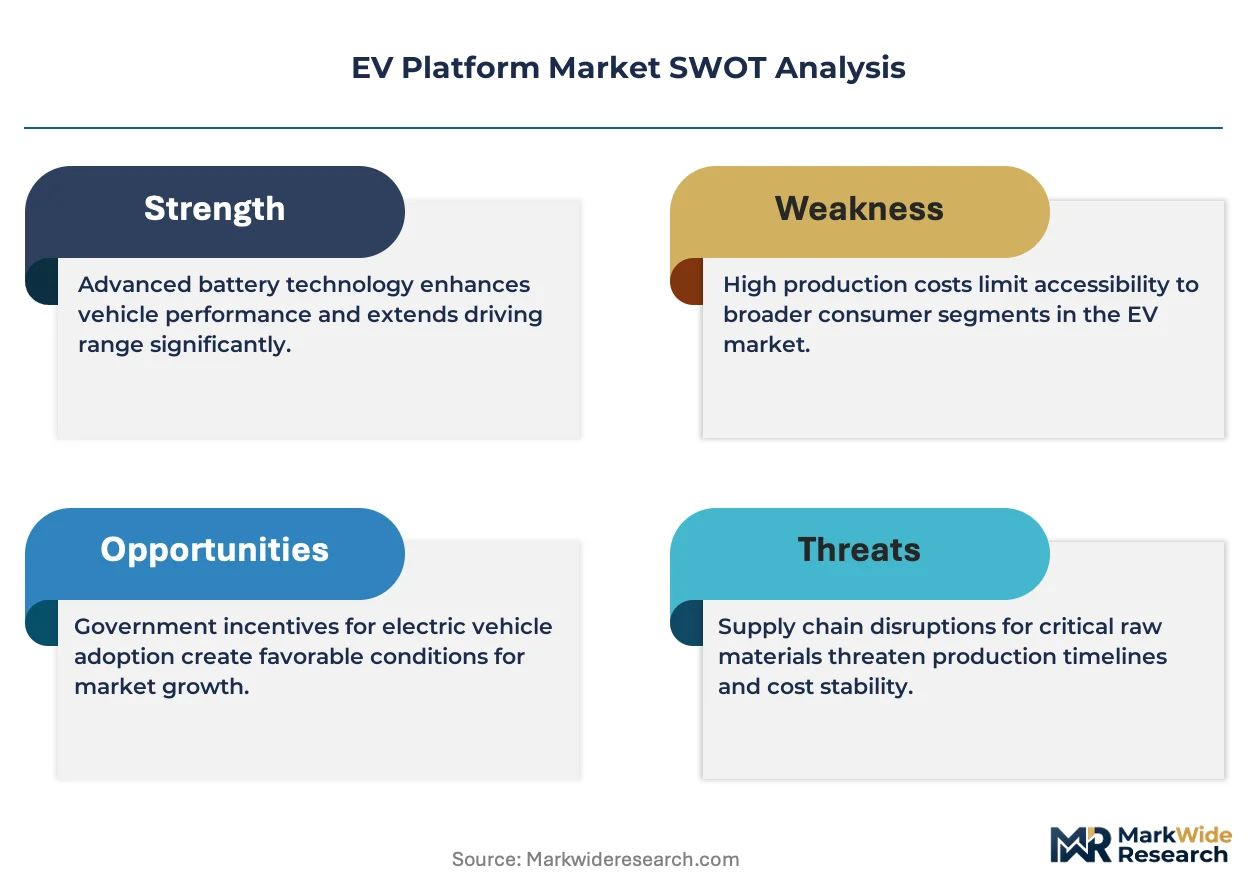
- Battery Pack Cost Volatility:The high and fluctuating costs of raw materials such as lithium, cobalt, and nickel create significant uncertainty in platform pricing and profitability, particularly for intended mass-market vehicle segments.
- Semiconductor Supply Concentration:A heavy reliance on a few semiconductor foundries, primarily located in Taiwan and South Korea, for essential powertrain and battery management system components creates a persistent supply chain vulnerability.
- Charging Infrastructure Inconsistency:A lack of universal standards for charging connectors and communication protocols across key regions complicates platform development, adding cost and limiting interoperability for global vehicle programs.
Strategic Opportunities
- Purpose-Built Commercial Platforms:Designing platforms for specialized commercial uses, such as refrigerated last-mile delivery or mobile repair services, provides access to higher-margin segments with specific performance requirements.
- Emerging Market Licensing:Offering proven, lower-cost platform designs for license to local manufacturers in India and Southeast Asia creates a new revenue stream and accelerates EV adoption in these regions.
- Structural Battery Integration:Developing cell-to-chassis designs where the battery pack contributes to the vehicle's structural integrity can reduce overall weight, lower costs, and improve vehicle dynamics, creating a performance advantage.
Industry Challenges
- Software Engineering Skill Gaps:A widespread shortage of talent in software engineering for battery management systems and vehicle operating systems slows development cycles and hampers the implementation of advanced features like over-the-air updates.
- High Capital Expenditure:The immense capital investment needed to design new platforms, retool existing manufacturing plants, and secure battery production capacity presents a significant financial barrier for many automakers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Platform Market |
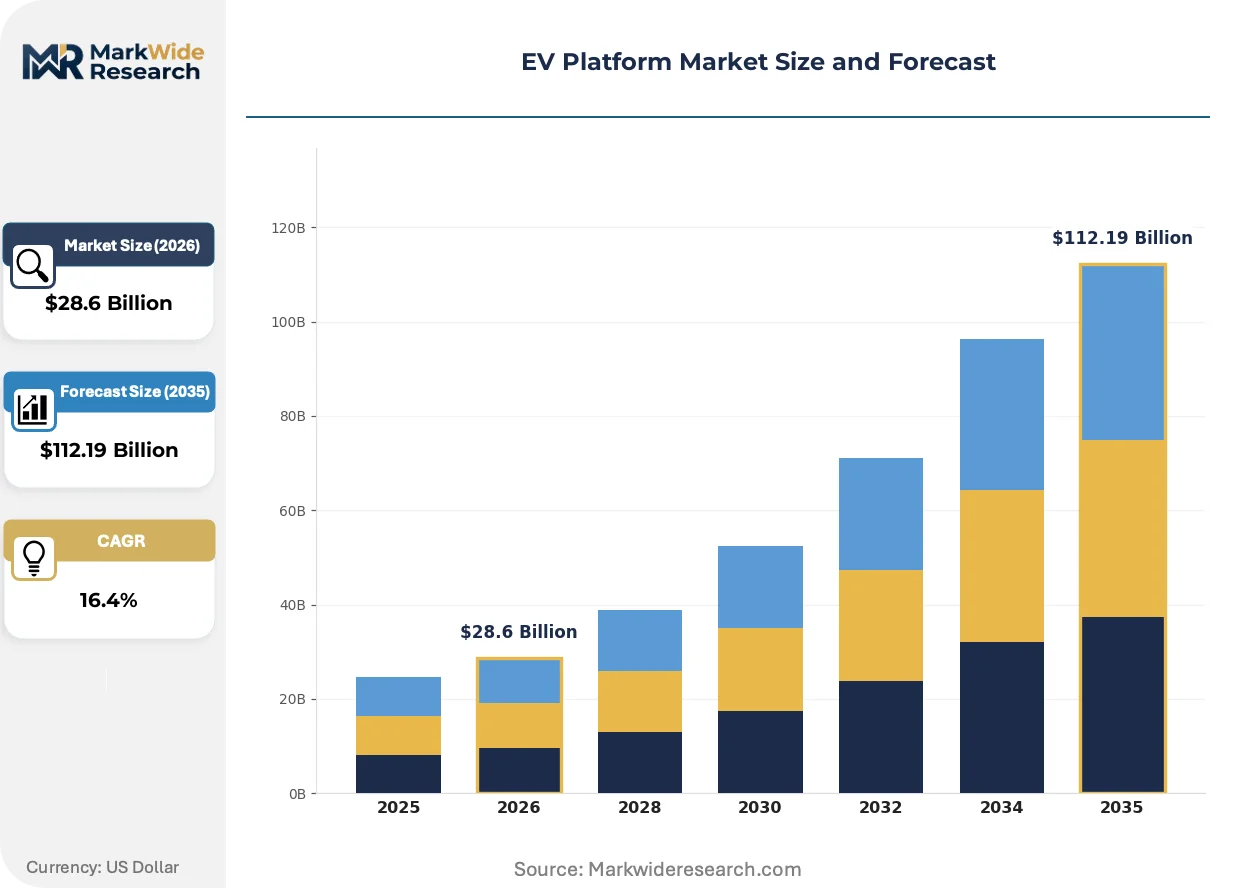
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Battery Electric, Plug-in Hybrid, Fuel Cell, Extended Range Technology: Modular Architecture, Scalable Design, Integrated Powertrain, Cloud Connectivity, Over-the-Air Updates Use Case: Urban Mobility, Commercial Fleet, Personal Transportation, Public Transit, Shared Mobility End User Industry: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Li Auto, NIO, Tesla, General Motors, BMW, BYD, XPeng, Geely-Volvo, Volkswagen Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Platform Market Strategic Shifts & Innovations
Integration of core components and software-defined functionalities is fundamentally altering EV platform design. This evolution moves platforms beyond simple mechanical structures to become integrated electronic and data systems, changing the basis of competition for vehicle manufacturers.
The 800-volt electrical architecture provides the capability for significantly faster charging speeds and improved thermal management compared to legacy 400-volt systems. Premium and performance vehicle segments are rapidly adopting this technology to offer a competitive advantage in charging time. This higher-voltage standard is overtaking the 400-volt system as the default for new, dedicated EV platform developments aimed at reducing range anxiety.
China's dual carbon policy and associated New Energy Vehicle (NEV) mandates create direct incentives for automakers to prioritize the development and sale of battery electric vehicles. This policy framework is forcing a rapid phase-out of internal combustion engine development and channeling investment into scalable EV platforms. Automakers operating in China must meet escalating NEV credit targets, making dedicated EV platform strategies essential for market compliance.
A growing number of smaller automakers and new market entrants are opting to license third-party EV platforms instead of developing proprietary architectures from scratch. This shift disrupts the traditional model of in-house R&D, creating a new customer base for specialist platform providers and established OEMs. This trend is most visible in Europe and North America, where startups aim to accelerate their time-to-market by leveraging proven skateboard chassis designs.
EV Platform Market Segmentation
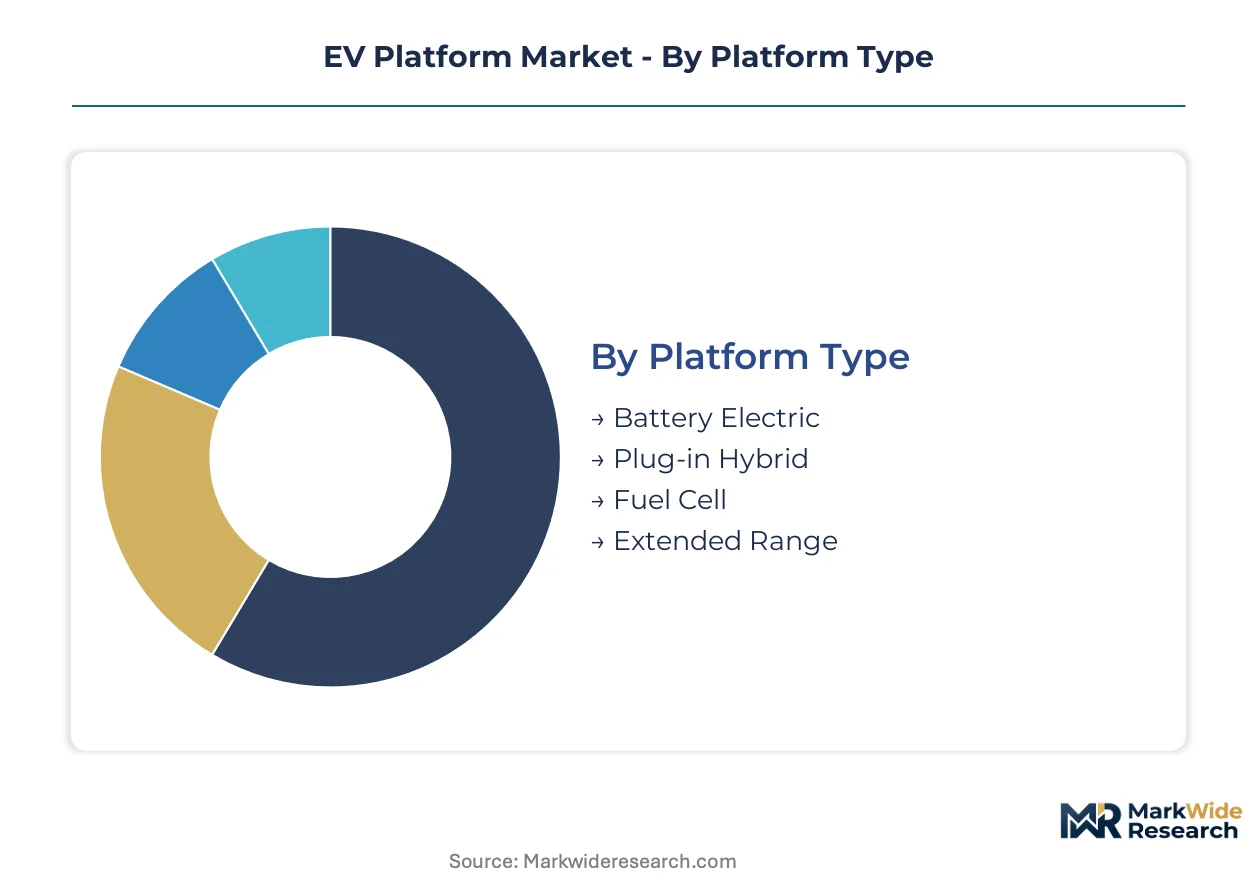
Segmentation of the EV platform market provides critical insights into the diverse technological approaches and application-specific demands driving market evolution. Understanding these segments helps automakers and suppliers tailor their development strategies to specific end-user needs and regulatory environments. This detailed analysis highlights where investment and innovation are most concentrated across various dimensions.
Platform Type:
The market for EV platforms differentiates by the core powertrain technology integrated into the chassis.
- Battery Electric:These platforms integrate large battery packs and electric motors as the sole propulsion source, offering zero tailpipe emissions. Demand concentrates heavily from personal transport and commercial fleets in China, driven by stringent government incentives and environmental mandates.
- Fuel Cell:Fuel Cell Electric Vehicle (FCEV) platforms utilize hydrogen stored in tanks to generate electricity via a fuel cell stack, powering electric motors. Demand is emerging for heavy-duty commercial vehicles in Germany, where long-range capabilities and fast refueling are critical for logistics operations.
- Plug-in Hybrid:These platforms combine an internal combustion engine with an electric powertrain and a battery that can be externally charged, appealing to markets with evolving charging infrastructure.
- Extended Range:Extended Range Electric Vehicle (EREV) platforms feature a small internal combustion engine that acts purely as a generator to charge the battery, extending the vehicle's operational range for specific use cases.
Mature deployment sits with Plug-in Hybrid platforms. Newer deployment is concentrated in Fuel Cell platforms.
Technology:
Functional capabilities define the technological sophistication of EV platforms, impacting their adaptability and user experience.
- Modular Architecture:This design principle employs standardized interfaces and interchangeable components, allowing for efficient production of various vehicle models from a common base. Automakers seeking scale across Europe, such as the Volkswagen Group, widely adopt this approach for cost reduction and faster development cycles.
- Over-the-Air Updates:This technology enables remote software updates for vehicle systems, including battery management and infotainment, without requiring a physical service visit. Premium vehicle segments in the US increasingly leverage OTA capabilities to deliver new features and improve performance post-sale.
- Scalable Design:Scalable platforms allow a single underlying architecture to underpin a wide range of vehicle sizes and types, optimizing manufacturing efficiency and reducing development costs for diverse product portfolios.
- Integrated Powertrain:This segment involves combining the electric motor, gearbox, and power electronics into a single, compact unit, improving overall system efficiency and packaging within the platform.
- Cloud Connectivity:Platforms with cloud connectivity enable real-time data exchange for advanced telematics, navigation, and remote diagnostics, enhancing the vehicle's intelligence and user services.
Modular Architecture forms the foundational approach, while Over-the-Air Updates represent the fastest-growing functional enhancement.
Use Case:
The operational context for electric vehicles significantly influences platform design requirements and market demand.
- Commercial Fleet:Platforms designed for commercial fleets prioritize durability, high payload capacity, and specific charging needs for continuous operation. Demand is robust from last-mile delivery operators in the UK, driven by the need for operational efficiency and urban emissions regulations.
- Personal Transportation:This segment focuses on platforms optimized for individual consumer use, emphasizing range, comfort, advanced safety features, and fast charging speeds. Individual consumers in Germany are a primary market, influenced by environmental awareness and performance expectations.
- Urban Mobility:Platforms in this category are optimized for short distances, frequent stops, and compact vehicle dimensions, serving city environments for ride-hailing or short-distance commuting.
- Public Transit:These platforms are engineered for large passenger capacity and high duty cycles, typically used for electric buses and shuttles in metropolitan areas, requiring robust and reliable designs.
- Shared Mobility:This segment requires platforms capable of handling multiple users and diverse usage patterns, such as those found in car-sharing services, prioritizing durability and ease of maintenance.
Personal Transportation remains the largest segment, but Commercial Fleet use cases are gaining share fastest.
End User Industry:
The role within the automotive supply chain dictates the primary end-user for EV platform technologies.
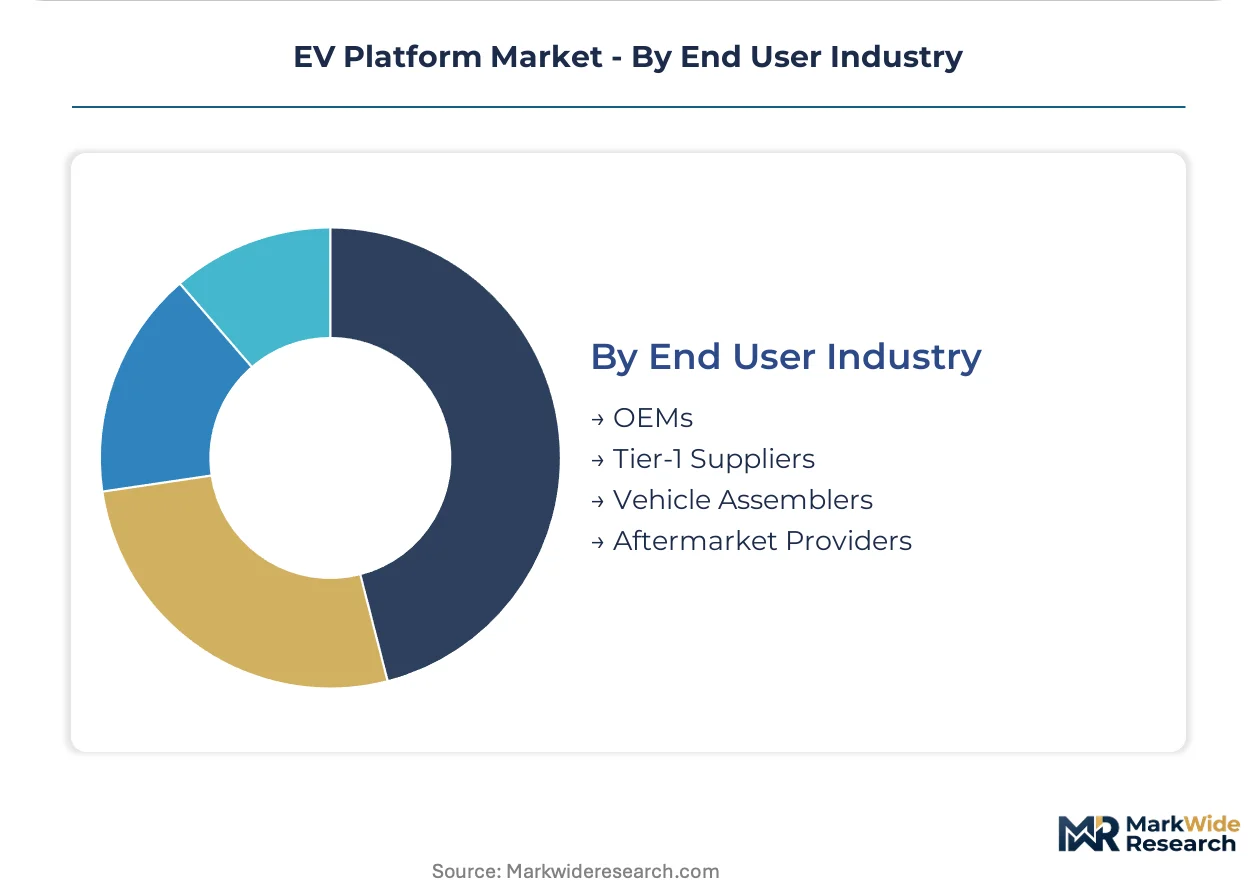
- OEMs:Original Equipment Manufacturers either develop platforms in-house or license them for their proprietary vehicle lines, ensuring brand differentiation and achieving scale economies. The Volkswagen Group in Europe exemplifies this strategy, leveraging its MEB platform across multiple brands.
- Tier-1 Suppliers:These companies develop modular sub-systems or complete skateboard platforms, often supplying them to multiple automakers or new market entrants. Magna International, for instance, supplies specialized platforms to startups, expanding market reach with specialized expertise.
- Vehicle Assemblers:This category includes companies that purchase pre-engineered platforms from third parties and integrate their own body designs, interiors, and branding, thereby accelerating their time-to-market for new electric vehicle models.
- Aftermarket Providers:These entities focus on offering components, upgrades, or services specifically for existing EV platforms, addressing maintenance needs, performance enhancements, and customization requirements post-sale.
OEMs represent the largest end-user group, while Tier-1 Suppliers are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for EV platforms concentrates heavily in regions with strong governmental support and established automotive manufacturing capabilities. China's aggressive electrification targets and Europe's stringent emissions standards are significant market drivers. These policies compel automakers to invest substantially in dedicated EV architectures.
China
Demand for battery electric platforms is robust, fueled by aggressive New Energy Vehicle (NEV) mandates. China's dual carbon goals directly incentivize domestic automakers to develop and deploy scalable EV platforms. The Yangtze River Delta region, particularly around Shanghai, remains a hub for platform innovation and mass production.
Germany
Personal transportation and commercial fleet electrification drive significant platform investment across Germany. The EU Green Deal mandates a swift transition to zero-emission vehicles, accelerating platform development by major OEMs. Bavaria, home to key automotive players, sees concentrated R&D efforts in modular EV architectures.
United States
Commercial fleet operators and premium vehicle segments are increasing demand for advanced EV platforms in the United States. The US EPA's vehicle emissions standards and incentives under the IRA accelerate investment in domestic EV manufacturing. California, a leading market for EV adoption, fosters innovation in software-defined vehicle platforms.
United Kingdom
Last-mile delivery operators and urban mobility initiatives are major demand drivers for EV platforms in the United Kingdom. Urban emissions regulations in cities like London compel fleet operators to adopt purpose-built electric vans. The Midlands, with its automotive heritage, is attracting investment in EV platform assembly and component manufacturing.
EV Platform Market Key Industry Players
Established producers occupy the standard tier, leveraging existing automotive expertise, while emerging entrants pursue niche applications and software-defined vehicle architectures. The market structure exhibits a tiered consolidation, with large automotive groups dominating proprietary platform development. Three strategic archetypes include integrated OEMs, specialist platform providers, and new market entrants. Capacity expansion and technology licensing are dominant competitive moves as companies seek to scale production and accelerate time-to-market.
Within the integrated OEM archetype, Volkswagen Group and General Motors exemplify the strategy of developing proprietary modular platforms for deployment across multiple internal brands. These established players leverage their extensive engineering capabilities to create scalable architectures, aiming for cost efficiencies and broad vehicle diversification. BYD, a prominent Chinese automotive giant, represents a vertically integrated approach, maintaining in-house control over battery and other core platform component production. These large-scale players often license their proven designs to smaller vehicle assemblers or new market entrants, accelerating broader EV adoption and market penetration.
| Leading Market Players |
|---|
| Li Auto |
| NIO |
| Tesla |
| General Motors |
| BMW |
| BYD |
| XPeng |
| Geely-Volvo |
| Volkswagen Group |
| Others |
Cost & Logistics Intelligence
Commercial fleet operators, driven by total cost of ownership models, primarily engage in long-term contract-based pricing for EV platforms. This approach seeks stability against raw material volatility.
Pricing Analysis
High-volume personal transportation platforms operate on tighter margins compared to specialized commercial fleet platforms. Contract-based long-term offtake agreements dominate the market, influenced by customization levels and volume scale. Cost compression in mass-market segments stems from battery pack cost volatility. Commercial fleet operators demonstrate higher price sensitivity for specialized platforms, while premium vehicle OEMs prioritize performance over cost.
Supply Chain Analysis
Reverse logistics for EV platforms are nascent, focusing on battery recycling and component remanufacturing to mitigate future resource scarcity. Geographic supply concentrates heavily in China, South Korea, and Germany for battery cells and power electronics. The market relies on critical raw materials like lithium, cobalt, and nickel. Single-source vulnerability in semiconductor foundries creates a persistent supply chain risk. Downstream distribution occurs directly from platform providers to vehicle assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV platform market is a consolidation play, where high capital expenditure requirements are forcing smaller, less capitalized players to exit or seek partnerships. This dynamic favors established automotive groups and well-funded platform specialists.
For Market Incumbents: Anchor core platform intellectual property through continuous R&D in structural battery integration and 800-volt architectures. Consolidate market share by licensing proven modular designs to smaller vehicle assemblers, countering the threat from new market entrants. Invest in domestic battery production capacity to mitigate raw material supply chain risks and secure competitive advantage.
For New Entrants and Emerging Players: Begin with specialized purpose-built commercial platforms for niche applications like refrigerated last-mile delivery, where established OEMs have less focus. Target emerging markets in Southeast Asia with lower-cost licensed designs, leveraging local manufacturing partnerships. A focused go-to-market angle involves offering complete vehicle integration services alongside the platform.
For Investors and Strategic Acquirers: The window for entry favors specialist platform providers with proprietary software and advanced battery management systems. Long-term viability hinges on companies that can scale production efficiently across diverse vehicle segments over the next decade. Target acquisition archetypes include Tier-1 suppliers developing modular skateboard platforms. Monitor the rate of 800-volt architecture adoption as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen Group leverages common architectures for cost efficiency across brands. |
| Battery Supply Agreement | Secures critical raw materials for sustained production volumes in China. |
| Software-Defined Vehicle Investment | Enhances over-the-air update capabilities for premium segments in the US. |
| Geographic Manufacturing Footprint | Establishes localized production hubs to serve commercial fleet demand in the UK. |
| Charging Infrastructure Partnership | Addresses range anxiety for personal transportation users in Germany. |
Research Approach
Multi-period observation of platform development cycles and regulatory compliance rates anchored the trend analysis, supplemented by interviews with EV platform engineers, OEM procurement leads, and fleet managers. Primary research involved discussions with industry stakeholders, validated by extensive secondary data. Sources included automotive reports, government policy documents, and financial filings, utilizing both bottom-up market sizing and top-down validation.
Segment-specific weighting across platform type, technology, and use case formed the basis of the forecast framework. The analytical framework projected market evolution over the projection horizon, modeling dimensions like vehicle class and OEM tier. Compound annual growth rates were derived from historical trends and projected technological adoption rates; battery cost trajectories and regulatory mandate schedules served as key inputs.
Underlying measurement precision varies by segment; personal transportation platforms carry tighter precision than public transit. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Geopolitical instability impacting raw material supply presents a significant risk factor; practitioners should monitor battery technology breakthroughs and policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Solar Golf Cart Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
South America Electric Vehicles Market
Electric Vehicles
South America Electric Bus Battery Pack Market
Electric Vehicles
North America Wireless Electric Vehicle Charging Market
Electric Vehicles
Poland E-Bike Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market