
 Global Flocculant and Coagulant Market | 2026-2036
Global Flocculant and Coagulant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flocculant and Coagulant Market Intelligence
Direct sales channels to large-scale industrial and municipal end-users are tilting the competitive balance away from smaller distributors. Kemira OYJ leverages its extensive manufacturing footprint to serve major pulp & paper clients. SNF Floerger specializes in polymer-based flocculants, dominating the high-performance segment. Ecolab Inc. sustains its market position through integrated service and chemical management solutions for the food & beverage sector.
Flocculants and coagulants are chemical agents designed to promote the aggregation of fine, suspended particles in a liquid into larger flocs. This process, critical for solid-liquid separation, relies on charge neutralization and polymer bridging mechanisms. Inorganic coagulants like aluminum and iron salts remain foundational in water treatment applications, while organic polymers represent the fastest-growing product type. The wastewater treatment application segment commands the largest share due to widespread industrial and municipal requirements.
The US EPA's Clean Water Act and Europe's Urban Waste Water Treatment Directive set stringent limits on effluent turbidity and contaminants, necessitating chemical treatment. In China, the MEE enforces GB standards for industrial wastewater, driving consumption in sectors like textiles and mining. Future success for suppliers depends on developing bio-based or natural flocculants that meet both performance metrics and evolving sustainability mandates.
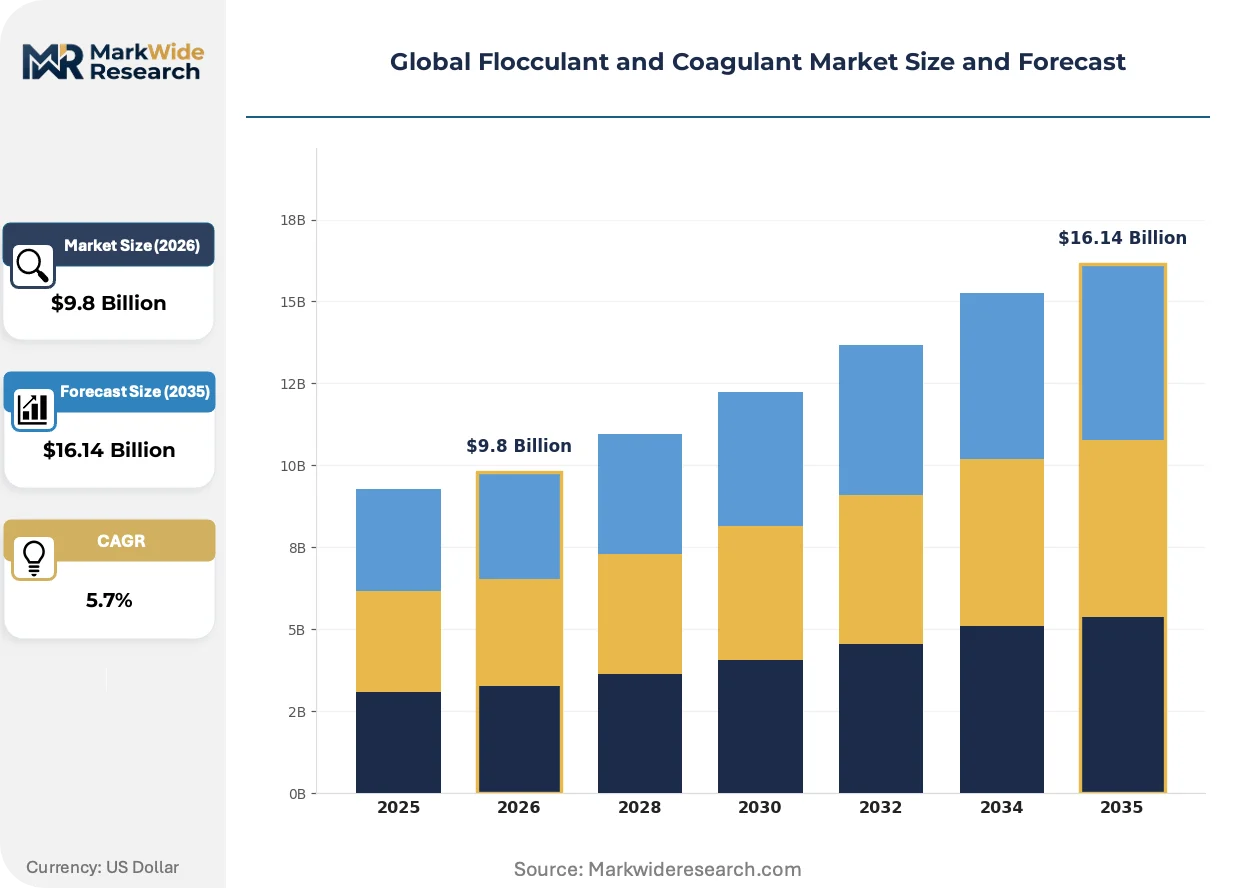
Market Dynamics
The central tension shaping the market is the dual regulatory pressure for stricter effluent quality and greater chemical sustainability. This forces a simultaneous pursuit of high-performance synthetic polymers for complex industrial waste and green, bio-based alternatives for municipal applications.
Growth Catalysts
- Stringent Regulations:China's enforcement of GB standards by the Ministry of Ecology and Environment (MEE) mandates advanced wastewater treatment, compelling adoption in the textile, chemical, and mining sectors.
- Infrastructure Expansion:Rapid urbanization across India and Southeast Asia necessitates the construction of new municipal water and wastewater treatment facilities, creating baseline demand for foundational coagulants and flocculants.
- Industrial Water Recycling:The pulp and paper industry's focus on closed-loop water systems to reduce consumption and comply with discharge limits drives consumption of specialized retention and drainage aids.
Market Restraints
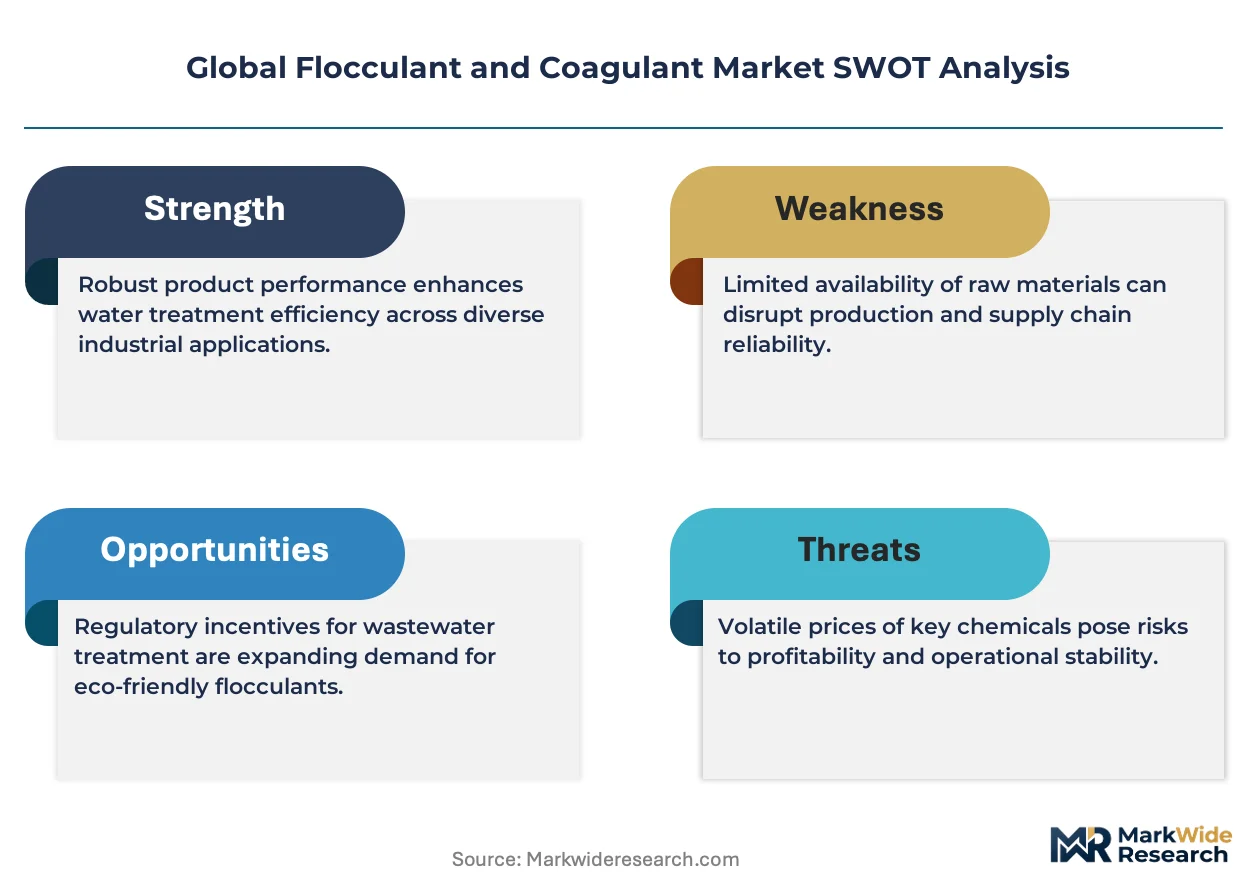
- Input Cost Volatility:The price of synthetic organic flocculants, particularly polyacrylamide-based products, is closely tied to volatile petrochemical feedstock costs, creating margin pressure and unpredictable end-user pricing.
- Performance Gaps:Natural and bio-based flocculants, while gaining traction due to sustainability mandates, often exhibit lower efficiency in high-turbidity or extreme-pH industrial wastewater compared to their synthetic counterparts.
- Sludge Management Costs:The use of inorganic coagulants like aluminum and iron salts generates significant volumes of chemical sludge, leading to high disposal and handling costs for treatment plant operators.
Strategic Opportunities
- Bio-Based Formulations:Developing high-performance flocculants from renewable sources like chitosan, starch, or tannins offers a path to meet both performance needs and evolving environmental, social, and governance (ESG) criteria from buyers.
- Aquaculture Water Treatment:The intensification of aquaculture creates a new application for specialized flocculants to manage water quality, control algal blooms, and remove suspended solids in recirculating aquaculture systems.
- Geographic Penetration:The mining industry in Latin American countries like Chile and Peru presents an underpenetrated market for advanced water treatment solutions to manage tailings and process water.
Industry Challenges
- Regulatory Compliance Timelines:Obtaining chemical registration and approval under comprehensive frameworks such as the EU's REACH regulation is a time-consuming and costly process, delaying the market entry of innovative formulations.
- Dosing Optimization:Inefficient or manual dosing of chemicals by end-users leads to overuse, increased operational costs, and suboptimal treatment performance, creating a need for better training and automated systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flocculant and Coagulant Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inorganic, Organic, Polymer-based, Composite, Natural End Use Industry: Water Treatment, Mining, Pulp & Paper, Textile Processing, Food & Beverage Application: Surface Water Treatment, Wastewater Treatment, Drinking Water Purification, Industrial Effluent Treatment, Sludge Dewatering Packaging Type: Powder Bags, Liquid Drums, Bulk Containers, Tablets, Granules |
| Companies Covered | Kemira OYJ, BASF SE, Ecolab Inc., SNF Floerger, Solenis LLC, Feralco AB, Buckman Laboratories, IXOM, Kurita Water Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flocculant and Coagulant Market Strategic Shifts & Innovations
A fundamental shift toward resource efficiency and circular economy principles is redefining product development and service models. Suppliers are moving beyond simple chemical provision to offer integrated solutions that address water scarcity, energy consumption, and sludge reduction.
Smart monitoring technology transforms flocculant application from a reactive to a predictive process. Real-time sensors measuring turbidity, pH, and particle charge feed data into automated dosing systems. Industrial and municipal water facilities are the primary adopters, seeking to minimize chemical waste and ensure consistent compliance. This innovation is digitizing the chemical management workflow, replacing manual adjustments with algorithmic precision.
European Union environmental policy creates significant demand for advanced treatment chemistries. The Urban Waste Water Treatment Directive, with its stringent limits on nutrient removal, compels municipal operators to upgrade facilities with enhanced coagulation and flocculation stages. This particularly affects plants in densely populated catchments across Germany and France, which must invest in tertiary treatment technologies to manage phosphorus and nitrogen loads.
Direct-to-customer service models are disrupting traditional distribution channels for specialty chemicals. Large end-users in the food and beverage and power generation sectors are entering into integrated water management contracts that bundle chemical supply with operational support, compliance reporting, and performance guarantees. This trend is most prominent in North America, where operators prioritize risk mitigation and total cost of ownership over simple unit pricing.
Global Flocculant and Coagulant Market Segmentation
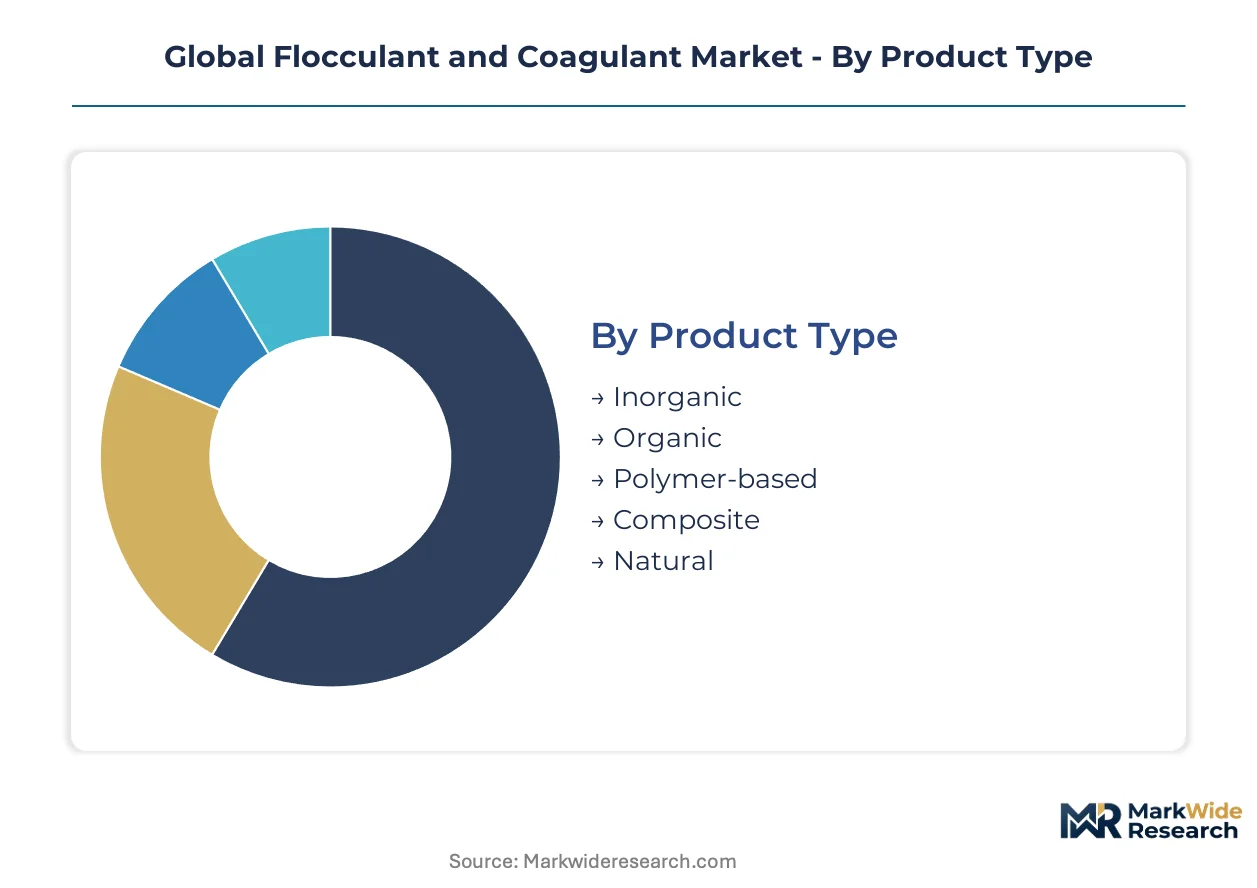
The market's segmentation reflects diverse chemical compositions and varied functional demands across numerous end-use sectors. Understanding these distinctions helps suppliers tailor products for specific industrial and municipal requirements. This granular view reveals where innovation is most impactful for different user groups.
Product Type:
The product type spectrum ranges from traditional inorganic compounds to advanced synthetic polymers, each engineered for specific coagulation and flocculation challenges.
- Polymer-based:These synthetic macromolecules, like polyacrylamide, facilitate strong bridging between particles, forming large, rapidly settling flocs. Demand concentrates in industrial wastewater treatment, particularly for sludge dewatering and high-turbidity effluents.
- Inorganic:Aluminum and iron salts, such as aluminum sulfate and ferric chloride, neutralize particle surface charges, initiating coagulation. Municipal water treatment facilities globally rely on these for primary clarification and contaminant removal.
- Organic:These include synthetic organic flocculants, often used where inorganic salts are unsuitable due to pH sensitivity or specific contaminant profiles.
- Composite:Composite flocculants combine inorganic and organic components, leveraging synergistic effects for enhanced performance in complex wastewater streams.
- Natural:Derived from renewable sources like starch or chitosan, natural flocculants meet sustainability mandates, finding use in sensitive environmental applications.
Established volume favors Inorganic; emerging adoption favors Natural.
End Use Industry:
Industrial sectors exhibit distinct requirements for flocculant and coagulant chemistries, driven by effluent characteristics and regulatory mandates.
- Water Treatment:This broad segment encompasses municipal drinking water and wastewater facilities, utilizing a range of chemicals for clarification, nutrient removal, and sludge management. Strict effluent quality standards, particularly in Europe, drive consistent demand.
- Mining:Flocculants are crucial for dewatering tailings, clarifying process water, and recovering valuable minerals in mining operations. Latin American countries like Chile present significant opportunities for advanced treatment solutions.
- Pulp & Paper:Specialized retention and drainage aids optimize paper machine efficiency and facilitate closed-loop water systems in the pulp and paper industry.
- Textile Processing:The textile sector employs flocculants to remove dyes, suspended solids, and chemical oxygen demand from its high-volume wastewater discharge.
- Food & Beverage:Food and beverage manufacturers use these chemicals for process water purification and treating effluent containing organic loads from production.
Wastewater Treatment commands the largest share; Mining presents the steepest expansion trajectory.
Application:
The specific application dictates the optimal choice of chemical agent, considering parameters like turbidity, pH, and target contaminant removal.
- Wastewater Treatment:This segment addresses industrial and municipal effluents, employing flocculants and coagulants to remove suspended solids, phosphorus, and nitrogen. Stringent regulations, such as China's GB standards, accelerate adoption in this area.
- Sludge Dewatering:Flocculants are essential in consolidating sludge volumes, reducing disposal costs and improving dewatering efficiency. Municipal treatment plants and industrial facilities rely on this process to manage solids.
- Surface Water Treatment:This involves clarifying raw water from rivers and lakes for various uses, requiring effective removal of suspended particles and organic matter.
- Drinking Water Purification:Coagulation and flocculation are primary steps in producing potable water, ensuring turbidity reduction and removal of pathogens and impurities.
- Industrial Effluent Treatment:Tailored chemical programs manage complex waste streams from manufacturing, ensuring compliance with discharge limits and promoting water reuse.
Wastewater Treatment applications drive the highest volumes; Sludge Dewatering applications are gaining share fastest.
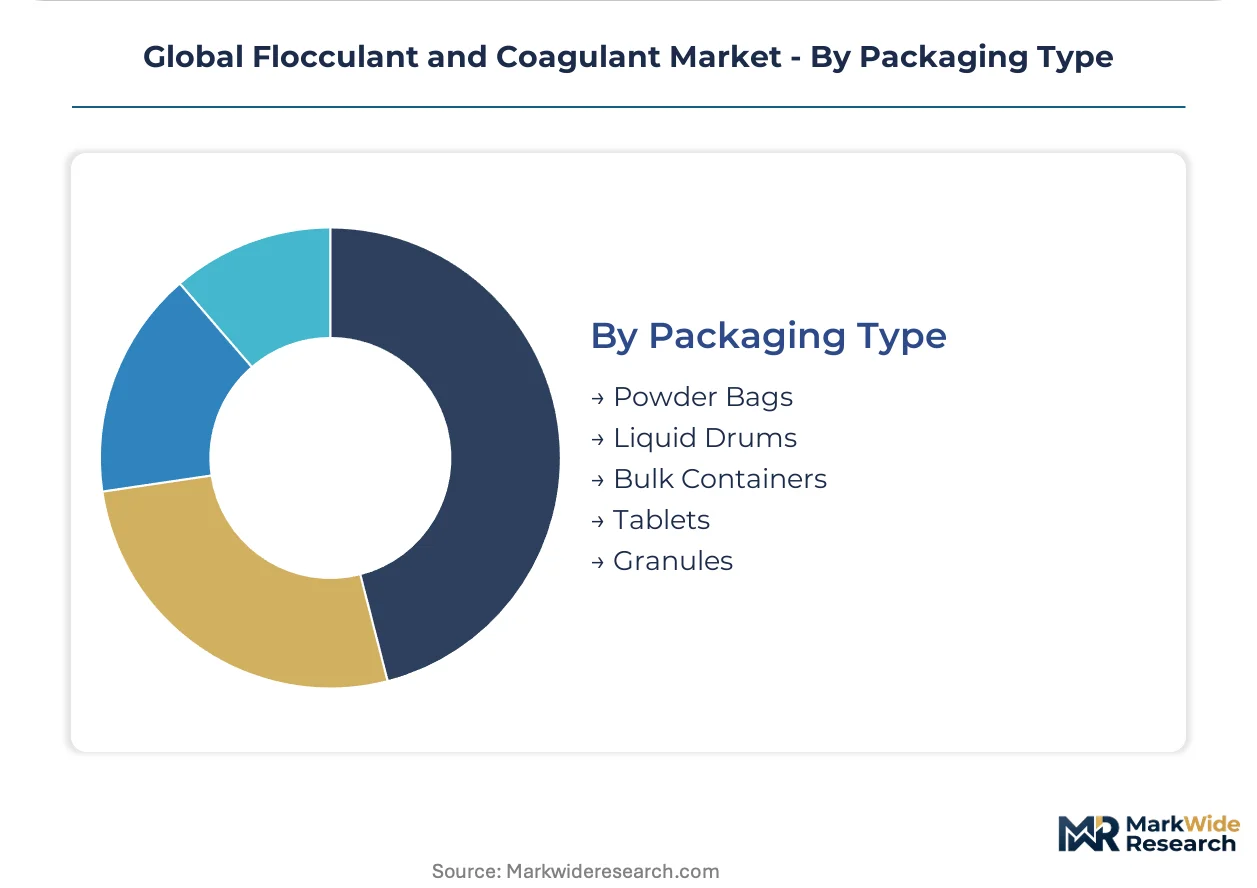
Packaging Type:
Packaging solutions cater to varying scales of use and handling requirements, from bulk industrial deliveries to smaller, user-friendly formats.
- Powder Bags:These offer cost-effective and transport-efficient delivery of dry flocculants, commonly polyacrylamide, for medium to large-scale operations. Municipal water treatment facilities often procure chemicals in this format for ease of storage.
- Bulk Containers:Large-volume intermediate bulk containers (IBCs) or tankers supply liquid coagulants and flocculants to major industrial users. This method minimizes handling and ensures continuous supply for high-consumption sites.
- Liquid Drums:Liquid drums provide a convenient option for smaller industrial users or specific chemical formulations requiring liquid delivery and easier dosing.
- Tablets:Tablet forms offer precise dosing and ease of handling for small-scale or specific applications, such as remote water purification or emergency kits.
- Granules:Granular flocculants provide a dust-free alternative to powders, improving safety and handling in various treatment settings.
Powder Bags represent the highest volume; Tablets are expanding most quickly in niche applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global flocculant and coagulant market demonstrates significant regional pricing-power asymmetry, particularly between established European suppliers and emerging Asian manufacturers. Demand dynamics in North America prioritize integrated service solutions, contrasting with volume-driven procurement in rapidly industrializing regions. This divergence shapes competitive strategies and product offerings across continents.
China
Chinese industrial demand for flocculants is compelling advanced wastewater treatment in textile, chemical, and mining sectors. The Ministry of Ecology and Environment (MEE) enforces stringent GB standards across manufacturing hubs. Industrial zones along the Yangtze River Delta are upgrading treatment facilities to meet these mandates.
India
India's rapid urbanization necessitates extensive construction of new municipal water and wastewater treatment facilities. The Bureau of Indian Standards (BIS) sets water quality parameters for these urban infrastructure projects. Major metropolitan areas like Delhi-NCR are constructing extensive new water treatment plants for growing populations.
Germany
German municipal operators require advanced treatment chemistries for enhanced coagulation and flocculation stages. Europe's Urban Waste Water Treatment Directive compels nutrient removal in urban wastewater facilities. Municipal operators in densely populated catchments across the Rhine-Ruhr region invest in tertiary treatment technologies.
United States
United States demand stems from municipal drinking water clarification and industrial effluent treatment needs. The US EPA's Clean Water Act sets stringent limits on effluent turbidity and contaminants. Facilities in the Great Lakes region focus on advanced treatment to protect freshwater resources.
Chile
Chilean mining operations require specialized flocculants for dewatering tailings and clarifying process water. The Chilean environmental authority enforces water management regulations for mining activities. Major copper mining regions in the Atacama Desert present significant opportunities for advanced water treatment solutions.
Global Flocculant and Coagulant Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying raw materials and basic chemicals. The global flocculant and coagulant market exhibits a tiered structure, with large multinational chemical companies competing with specialized regional players. Strategic archetypes include integrated solution providers, polymer chemistry innovators, and cost-efficient inorganic suppliers. These players often pursue portfolio diversification into bio-based products and strategic partnerships for geographic expansion.
Within the integrated solution provider archetype, Ecolab Inc. sustains its market position through bundled service and chemical management offerings for the food & beverage sector. SNF Floerger, a French-based specialist, represents the polymer chemistry innovator, dominating the high-performance segment with its polyacrylamide-based flocculants. Kemira OYJ, a Finnish company, anchors the pulp & paper sector by leveraging its extensive manufacturing footprint and direct sales channels to major clients. These companies exemplify the market's segmentation by end-use and product specialization.
| Leading Market Players |
|---|
| Kemira OYJ |
| BASF SE |
| Ecolab Inc. |
| SNF Floerger |
| Solenis LLC |
| Feralco AB |
| Buckman Laboratories |
| IXOM |
| Kurita Water Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Chinese chemical production hubs, expanding their capacities, exert influence on downstream pricing power for foundational flocculants and coagulants. This dynamic fosters a competitive environment for bulk products while specialty formulations maintain premium pricing.
Pricing Analysis
Configured-to-order pricing for specialized polymer formulations commands a premium over standard inorganic commodity chemicals. The dominant pricing model is a hybrid of contract-based long-term offtake for large industrial users and transactional sales for smaller buyers. Price differentiation stems from product performance, customization level, and bundled after-sales service. Pricing softness stems from volatile petrochemical feedstock costs, impacting polyacrylamide-based products. Large industrial and municipal end-users exhibit lower price sensitivity due to total cost of ownership considerations, while smaller distributors are more susceptible to unit pricing fluctuations.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming crucial for maintaining liquidity across the flocculant and coagulant value chain. Geographic supply concentrates in China for raw materials and basic chemicals, alongside established European manufacturers for advanced polymers. Production of synthetic organic flocculants relies heavily on petrochemical feedstocks, while inorganic salts draw from bauxite and iron ore. Commodity price volatility for these inputs presents a significant structural risk. Distribution runs through direct sales channels to major industrial and municipal end-users, complemented by specialized regional distributors for smaller accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense, as incumbents must navigate the increasing demand for bio-based alternatives. These green solutions threaten traditional synthetic polymers.
For Market Incumbents: Build intellectual property moats in bio-based formulations to counter the rising demand for sustainable solutions. Diversify manufacturing footprints into rapidly urbanizing regions like India and Southeast Asia to capitalize on new infrastructure projects. Invest in automated dosing technologies to offer integrated solutions, mitigating end-user operational costs and improving performance consistency. This strategy addresses both sustainability mandates and input cost volatility.
For New Entrants and Emerging Players: Build out specialized product lines targeting niche applications with high-performance requirements. Aquaculture water treatment and Latin American mining operations represent underpenetrated markets for advanced solutions. A successful go-to-market angle involves offering integrated service models that bundle chemical supply with technical support and performance guarantees. This approach differentiates from commodity suppliers and targets value-conscious buyers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service providers offering chemical management solutions to industrial end-users. Long-term viability rests with companies developing high-performance, bio-based flocculants that meet evolving ESG criteria. Target acquisition archetypes include specialized polymer chemistry innovators with strong R&D pipelines or regional players with established distribution networks in high-growth geographies. Regulatory shifts favoring sustainable chemistries or mandating advanced wastewater treatment serve as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Serves the rapidly growing municipal and industrial demand across India and Southeast Asia. |
| Bio-Based R&D Investment | Develops sustainable alternatives to meet evolving environmental regulations and buyer ESG criteria. |
| Integrated Service Offering | Bundles chemical supply with operational support, improving end-user efficiency and compliance. |
| Targeted Geographic Penetration | Captures underpenetrated markets like Latin American mining with specialized water treatment solutions. |
| Automated Dosing System Development | Optimizes chemical usage, reduces operational costs, and ensures consistent treatment performance for end-users. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary research anchors the qualitative findings of this analysis. We engaged with plant managers, R&D chemists, procurement specialists, and environmental compliance officers. Secondary validation drew from MEE reports, EPA filings, company annual reports, and trade association data. This approach ensured comprehensive data gathering and robust insights, triangulating information from bottom-up and top-down perspectives.
The calibration approach leveraged an analytical framework to project market dynamics across the analysis window. Segmentation dimensions modeled included product type, end-use industry, application, packaging type, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected future demand. Key forecast inputs included industrial output growth, municipal infrastructure spending in emerging economies, and regulatory enforcement levels.
Sensitivities concentrate around petrochemical price shocks and the pace of new environmental mandates. Forecasts reflect assumptions regarding technological advancements and global economic stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
Global Turbidity Meters Market
Water & Sludge Treatment
Europe Membrane Bioreactor (MBR) Market
Water & Sludge Treatment
Europe Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
Water Recycle and Reuse Technologies Market
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Water Treatment Chemicals Market
Water & Sludge Treatment
Produced Water Treatment Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market