
 United States Managed Services Market | 2026-2036
United States Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Managed Services Market Analytics
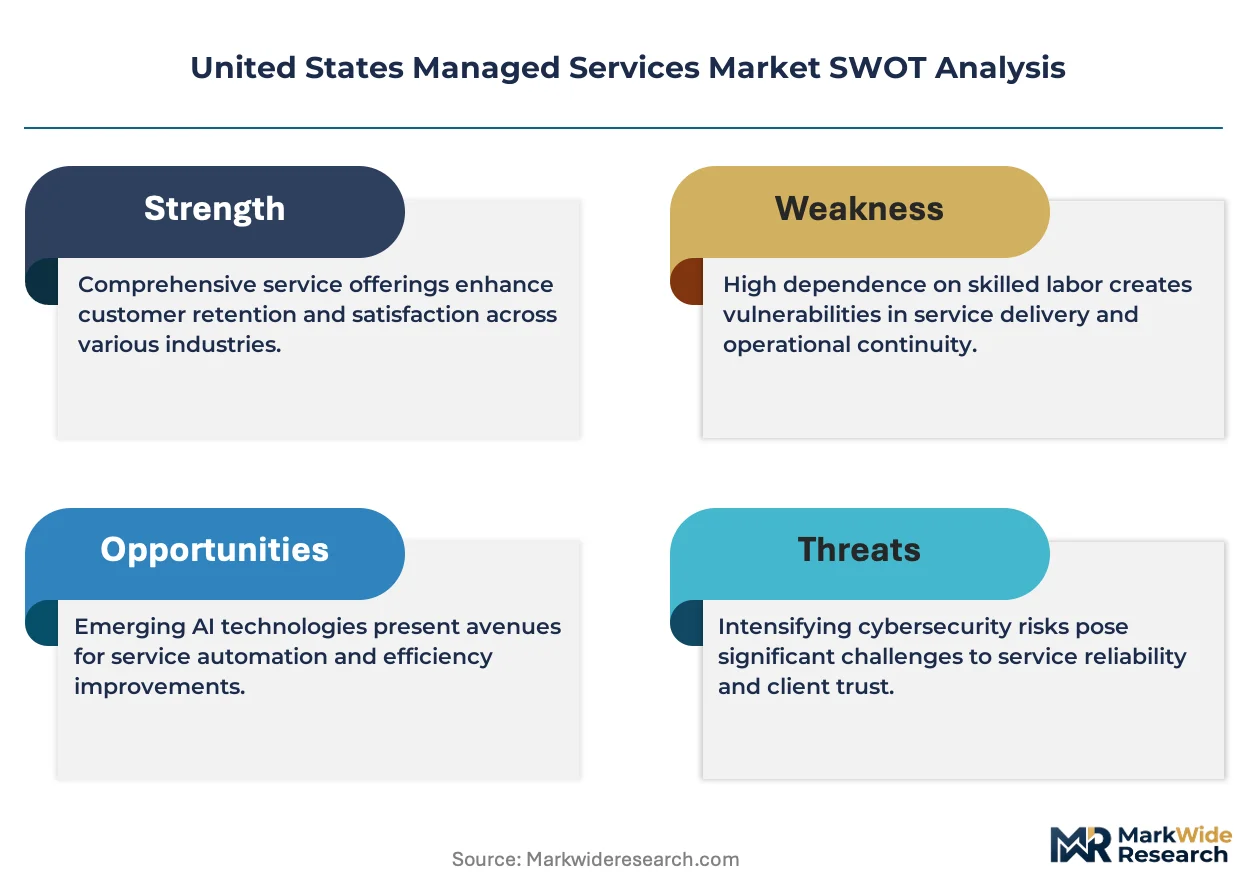
The SEC's cybersecurity disclosure rules is repositioning how mid-market firms budget for IT governance and incident response capabilities. IBM Corporation leverages decades of federal contracting relationships to anchor its position in regulated verticals. Microsoft Corporation extends its Azure-native managed services stack to compete directly with traditional outsourcing incumbents. Accenture specializes in industry-specific transformation programs that differentiate its offerings from commodity infrastructure management.
United States Managed Services encompass the ongoing outsourcing of IT functions—including infrastructure monitoring, application management, security operations, and cloud administration—to third-party providers operating under defined service-level agreements with measurable uptime and response-time parameters. These arrangements allow client organizations to convert fixed technology costs into variable operating expenditures while accessing specialized expertise unavailable in-house. Security Services commands premium pricing due to regulatory pressure and talent scarcity, while Cloud Services represents the fastest-expanding deployment channel as enterprises accelerate workload migration. Network Management remains mature with stable margins, though Hybrid deployment models are capturing growing interest from organizations seeking to balance legacy system retention with cloud scalability.
FDA oversight of healthcare data integrity, SEC cybersecurity mandates, and NIST framework adoption collectively shape compliance-driven procurement criteria across buyer segments. HIPAA enforcement actions and state-level data breach notification laws further tighten accountability standards for managed service providers handling protected information. Stakeholders must weigh vendor specialization against platform breadth when selecting partners capable of navigating overlapping federal and state regulatory obligations.
Market Dynamics
SEC cybersecurity disclosure mandates are compressing procurement cycles for mid-market enterprises, forcing rapid vendor consolidation around providers capable of delivering continuous compliance monitoring and automated incident response workflows.
Growth Catalysts
- Healthcare Data Integrity Requirements:FDA oversight of electronic health records and medical device connectivity is driving hospital systems toward managed security operations centers with 24/7 threat detection capabilities.
- Texas Enterprise Density:Dallas-Fort Worth and Houston metro corridors concentrate Fortune 500 headquarters and energy sector infrastructure, creating concentrated demand for hybrid cloud management services.
- NIST Framework Adoption:Federal contractors across defense and civilian agencies must demonstrate continuous monitoring compliance, expanding the addressable market for FedRAMP-authorized managed service providers.
Market Restraints
- Certified Talent Scarcity:CompTIA Security+ and CISSP-credentialed professionals command compensation premiums that compress provider margins, particularly in smaller metropolitan markets.
- Legacy Infrastructure Lock-In:Financial services firms maintain mainframe-dependent core banking systems that resist cloud-native migration, fragmenting service delivery architectures.
- State-Level Regulatory Fragmentation:California's CCPA enforcement actions and New York's DFS cybersecurity rules create overlapping compliance obligations that increase contractual complexity.
Strategic Opportunities
- IRA Clean Energy Incentives:Renewable energy developers deploying grid-scale battery storage require industrial control system monitoring, opening vertical specialization pathways for operational technology security providers.
- AI-Augmented Service Desks:Large language model integration into tier-one support workflows promises deflation of per-ticket costs while improving mean-time-to-resolution metrics.
- Rural Healthcare Networks:Critical access hospitals in Montana, Wyoming, and the Dakotas remain underserved by national providers, presenting acquisition targets for regional managed service consolidators.
Industry Challenges
- Multi-Cloud Orchestration Complexity:Enterprises operating across AWS, Azure, and Google Cloud simultaneously struggle with inconsistent API governance and cost optimization visibility.
- Zero Trust Architecture Timelines:Federal agencies face OMB-mandated migration deadlines that outstrip available implementation capacity, creating project backlog risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Managed Services Market |
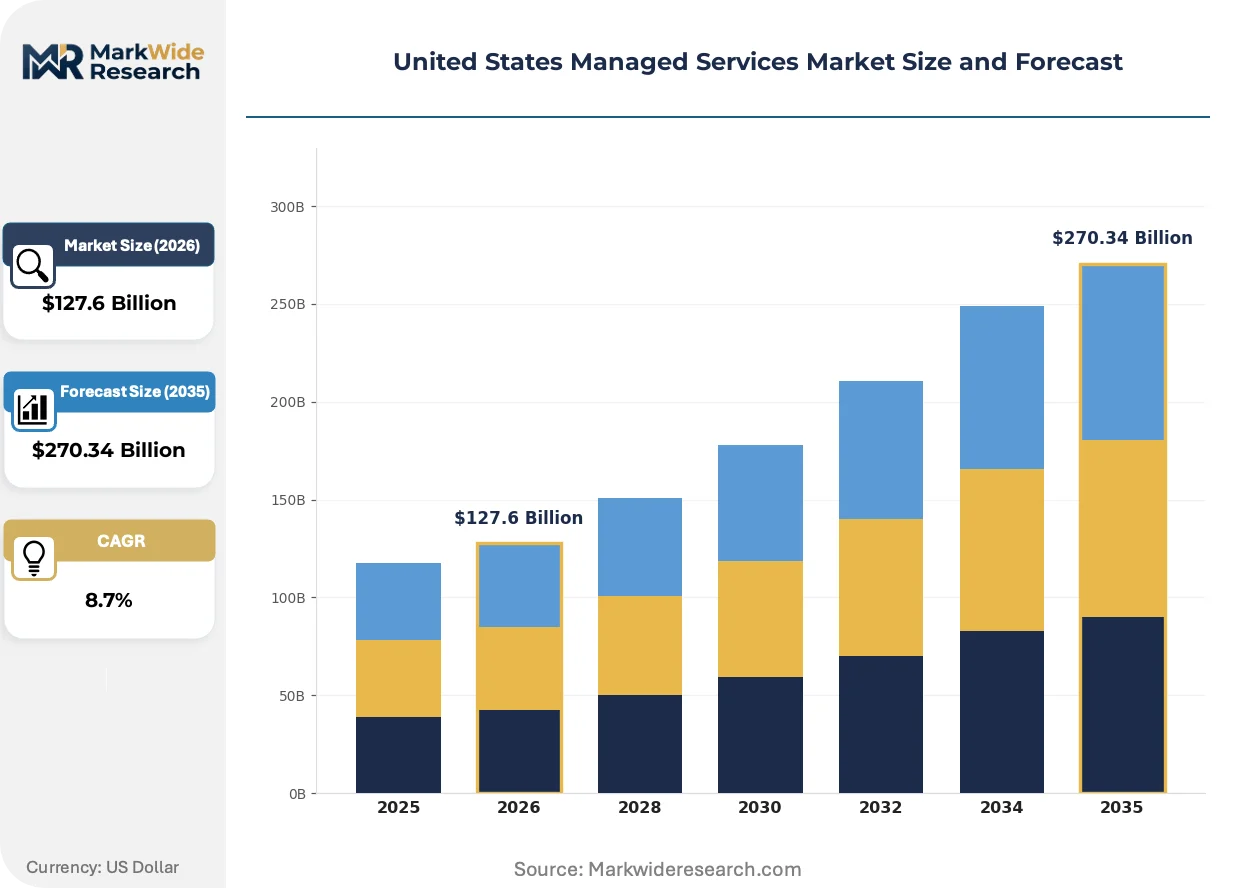
| Market Size in 2026 | $127.6 Billion |
| Market Size in 2035 | $270.34 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: IT Management, Cloud Services, Network Management, Security Services Deployment Model: On-Premises, Cloud-Based, Hybrid, Remote End User: Small Enterprises, Medium Enterprises, Large Corporations, Government Agencies Industry Vertical: Healthcare, Education, Retail, Manufacturing |
| Companies Covered | Accenture, IBM Corporation, AT&T Inc., Cisco Systems Inc., Cognizant, Tata Consultancy Services, DXC Technology, Fujitsu Limited, Microsoft Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Managed Services Market Evolving Landscape
Artificial intelligence is compressing the detection-to-response window for security incidents, while regulatory pressure accelerates consolidation around platforms capable of automated compliance evidence collection.
Extended detection and response platforms are unifying endpoint, network, and identity telemetry into single-pane-of-glass consoles. Mid-market manufacturers and state government agencies are adopting these consolidated stacks fastest, replacing point-solution security vendors. This unification is compressing procurement decisions from twelve-month evaluation cycles to ninety-day rapid deployments, favoring providers with pre-integrated technology partnerships.
SEC disclosure rules now require material cybersecurity incidents to be reported within four business days. Publicly traded healthcare systems and financial institutions must maintain continuous audit trails, driving demand for managed detection and response services with native SOAR capabilities. Texas-based energy infrastructure operators face particular scrutiny given critical infrastructure designations.
Consumption-based pricing models are displacing traditional per-seat or per-device contracts across enterprise buyers. Healthcare providers and municipal governments now prefer month-to-month variable commitments tied to actual ticket volume and storage consumption. California's tech sector pioneered this shift, with procurement teams negotiating outcome-based SLAs rather than input-based fees.
United States Managed Services Market Segmentation
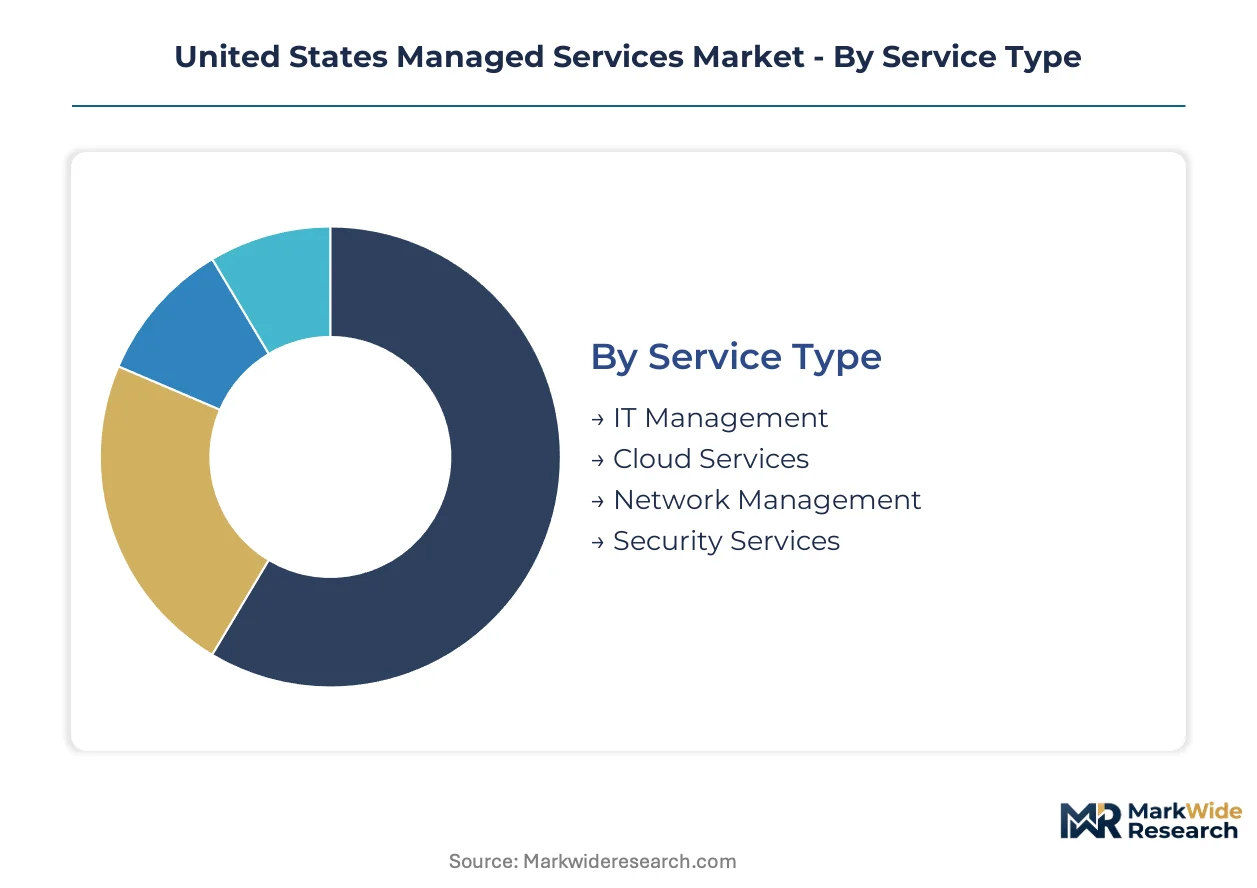
Service differentiation in United States managed services determines procurement priorities across regulated verticals. Buyers match deployment complexity, compliance exposure, and operational scale to specific provider capabilities when structuring outsourcing agreements.
Service Type:
Security Services demands the heaviest upfront capital investment for SOC infrastructure and threat intelligence platform licensing.
- Security Services:Continuous threat monitoring, incident response orchestration, and compliance audit trail generation. Demand concentrates among Texas energy infrastructure operators and California healthcare systems facing SEC disclosure mandates and HIPAA enforcement. Talent scarcity for CISSP-credentialed analysts compresses provider margins.
- Cloud Services:Workload migration management, multi-cloud orchestration, and consumption-based cost optimization. Enterprise buyers in New York financial services and Dallas-Fort Worth metro corridors drive adoption as hybrid architectures proliferate. Fastest-expanding deployment channel across all buyer segments.
- IT Management:Infrastructure monitoring, patch management, and service desk operations for legacy system maintenance.
- Network Management:SD-WAN deployment, bandwidth optimization, and uptime guarantee enforcement under strict SLAs.
Most installed capacity flows through IT Management. Expansion is steepest in Cloud Services.
Deployment Model:
Hybrid configurations command premium pricing as buyers balance legacy retention with cloud scalability requirements.
- Hybrid:Integrated on-premises and cloud workload management with unified governance frameworks. Manufacturing firms in Midwest industrial corridors and government agencies pursuing FedRAMP authorization favor this model. Addresses mainframe-dependent core systems resisting full cloud migration.
- Cloud-Based:Fully outsourced infrastructure with no client-side hardware maintenance obligations. State government agencies and retail chains with distributed footprints adopt rapidly to eliminate capital expenditure cycles. Consumption-based pricing dominates procurement negotiations.
- On-Premises:Provider-staffed operations within client data centers for maximum data sovereignty control.
- Remote:Geographically distributed technician access for endpoint management and user support.
Cloud-Based deployments carry the largest revenue base. Hybrid architectures are climbing the fastest as technical debt constrains wholesale migration.
End User:
Large Corporations drive contract value through multi-year agreements with stringent uptime penalties and dedicated account structures.
- Large Corporations:Fortune 500 entities requiring 24/7 coverage across global time zones with customized runbook documentation. Energy sector headquarters in Houston and technology firms in Silicon Valley anchor demand. Procurement teams negotiate outcome-based SLAs tied to business continuity metrics.
- Government Agencies:Federal, state, and municipal entities with FedRAMP, NIST, and state-specific compliance mandates. Defense contractors and civilian agencies under continuous monitoring requirements expand addressable market for authorized providers. Contract vehicles favor incumbent relationships.
- Medium Enterprises:Regional businesses with limited internal IT staff seeking predictable operating expenditure conversion.
- Small Enterprises:Cost-conscious buyers purchasing standardized service tiers through channel partners.
Government Agencies represent the most stable contract base. Medium Enterprises are expanding most quickly as SEC disclosure rules compress procurement cycles.
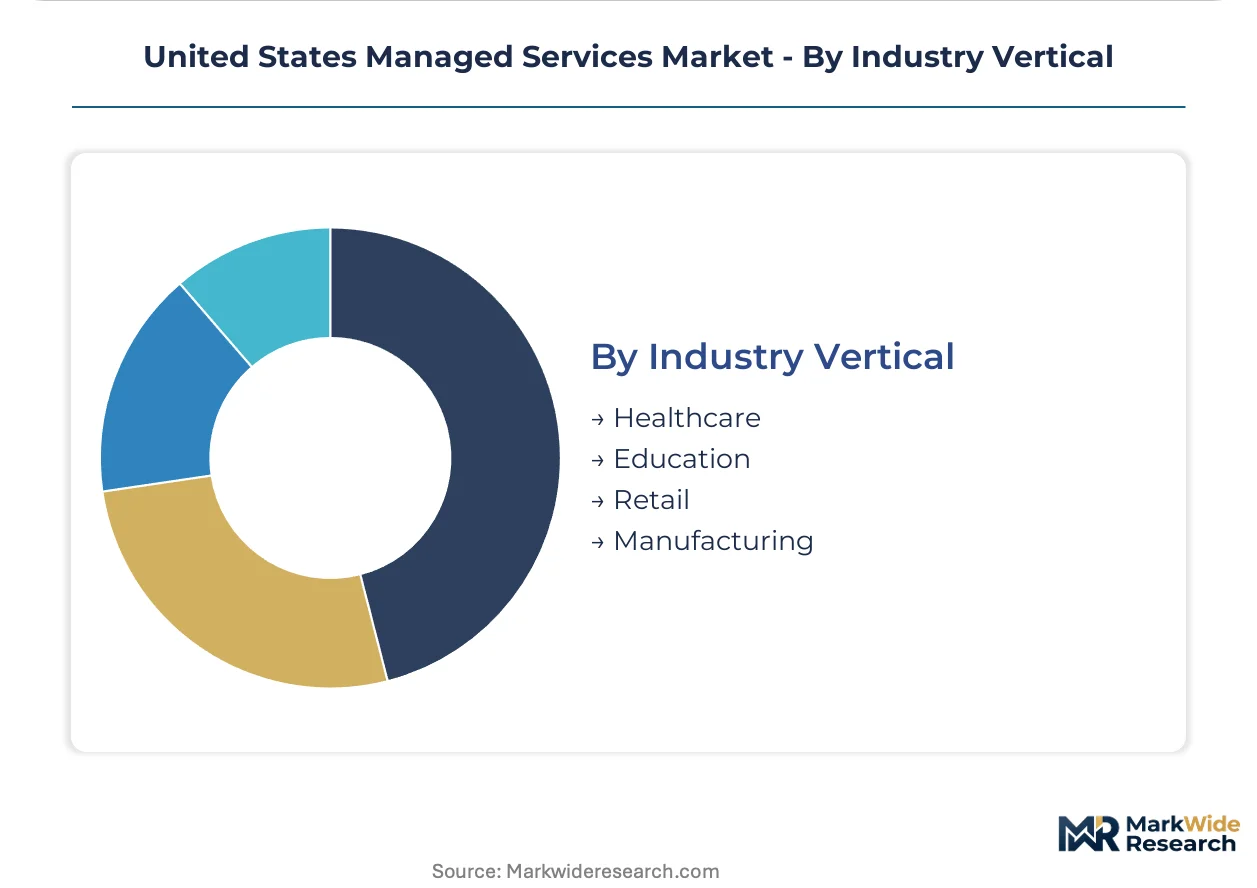
Industry Vertical:
Healthcare verticals absorb the highest per-seat pricing due to FDA oversight and breach notification liability exposure.
- Healthcare:Hospital systems, physician networks, and medical device operators requiring HIPAA-compliant data handling with audit-ready documentation. Critical access hospitals in Montana and Wyoming remain underserved, presenting consolidation targets. FDA electronic health record integrity rules intensify security operations center requirements.
- Manufacturing:Operational technology security for industrial control systems and supply chain continuity assurance. Renewable energy developers deploying grid-scale battery storage under IRA incentives create specialized monitoring demand. Legacy equipment interoperability challenges fragment solution architectures.
- Education:K-12 districts and universities managing endpoint proliferation with constrained budget cycles.
- Retail:Point-of-sale system protection and seasonal demand surge scaling for omnichannel operations.
Healthcare generates the highest margin profile. Manufacturing is gaining share fastest as operational technology security requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States managed services industry traces its commercial roots to the 1990s data center outsourcing wave that first scaled in New York financial services corridors and Northern California technology clusters.
Texas
Dallas-Fort Worth and Houston metro areas concentrate Fortune 500 headquarters and energy sector infrastructure. SEC cybersecurity disclosure mandates compress procurement cycles for mid-market enterprises headquartered here. Critical infrastructure operators face particular federal scrutiny given grid and pipeline designations.
California
Silicon Valley technology firms and Los Angeles healthcare systems drive cloud-native managed services adoption. CCPA enforcement actions tighten accountability standards for providers handling consumer data. San Francisco Bay Area procurement teams pioneered consumption-based pricing models now spreading nationally.
New York
Wall Street financial institutions and state government agencies anchor demand for FedRAMP-authorized providers. DFS cybersecurity rules impose contractual complexity on outsourced compliance monitoring. New York City metro corridors exhibit highest enterprise density for hybrid cloud migration velocity.
Mountain West
Critical access hospitals in Montana, Wyoming, and the Dakotas remain underserved by national managed service providers. Rural healthcare networks present acquisition targets for regional consolidators seeking geographic expansion. Limited local talent pools compress margins for security operations center staffing.
Midwest Industrial Corridor
Manufacturing firms in Illinois, Michigan, and Ohio balance legacy mainframe retention with cloud scalability requirements. Operational technology security for industrial control systems gains priority under IRA clean energy incentives. Chicago anchors demand for hybrid deployment models addressing technical debt constraints.
United States Managed Services Market Competitive Landscape
The competitive structure tilts toward diversified technology conglomerates with federal contracting pedigrees. Provider concentration remains moderate with distinct tiering between global integrators, cloud-native platforms, and specialized security boutiques. Three archetypes dominate: legacy outsourcing incumbents with decades-long government relationships, hyperscale cloud platforms extending native managed stacks, and vertical specialists targeting regulated healthcare and energy workflows. Consolidation through strategic acquisitions and technology licensing partnerships represents the primary competitive vector as mid-market buyers seek single-vendor accountability.
Within the legacy integrator tier, IBM Corporation and Accenture occupy positions shaped by decades of federal and Fortune 500 contracting relationships. Microsoft Corporation exemplifies the cloud-native archetype, leveraging Azure infrastructure to compete directly with traditional outsourcing models. Tata Consultancy Services represents the global delivery model, anchoring cost-competitive service desk and infrastructure management capabilities. These three patterns illustrate how vendor selection increasingly hinges on specialization breadth versus platform depth trade-offs.
| Leading Market Players |
|---|
| Accenture |
| IBM Corporation |
| AT&T Inc. |
| Cisco Systems Inc. |
| Cognizant |
| Tata Consultancy Services |
| DXC Technology |
| Fujitsu Limited |
| Microsoft Corporation |
| Others |
Value Network & Pricing Analysis
Horizontal integration across security operations center platforms anchors both supply positioning and pricing power for United States managed services providers. FedRAMP-authorized vendors with captive threat intelligence feeds command premium positioning against commodity infrastructure managers.
Pricing Analysis
Bundled security-cloud-network packages dominate enterprise procurement, though unbundled point solutions persist in mid-market segments. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized providers from regional boutiques and offshore delivery shops. Price differentiation centers on certification grade and after-sales compliance documentation depth. Cost compression in the standard tier is intensifying because CISSP-credentialed analyst wages inflate faster than contract escalators. State government agencies exhibit highest price sensitivity; energy sector critical infrastructure operators show least.
Supply Chain Analysis
Workforce availability constraints in India, the Philippines, and Eastern European delivery hubs shape provider staffing economics. Talent pipelines draw from CompTIA-certified technician pools, offshore engineering campuses, and domestic military transition programs. Supply chain risk centers on single-source vulnerability for cleared personnel with security clearances. Distribution runs through direct enterprise sales, channel partner networks, and federal contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in United States managed services rests on AI-augmented service desk automation compressing per-ticket delivery costs while security services command regulatory-premium pricing.
For Market Incumbents: Extend FedRAMP authorization coverage into emerging civilian agency verticals before cloud-native competitors capture continuous monitoring contracts. Acquire regional security boutiques in Mountain West healthcare corridors to preempt consolidation by private equity platforms. Talent scarcity for cleared analysts represents the critical margin pressure point; captive training pipelines offer defensive leverage. For New Entrants and Emerging Players: Enter via rural healthcare networks in Montana, Wyoming, and the Dakotas where national providers maintain minimal presence. Critical access hospitals present the most penetrable segment given underserved infrastructure and HIPAA enforcement exposure. Lead generation through state hospital association partnerships offers lower customer acquisition cost than direct enterprise pursuit. For Investors and Strategic Acquirers: Roll-up economics work for regional managed security specialists because fragmented ownership across fifty state regulatory regimes prevents national scale efficiency. Five-to-ten year viability favors platforms with hybrid cloud orchestration capabilities bridging legacy mainframe retention. Watch federal Zero Trust architecture implementation velocity as inflection indicator for security services demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies endpoint, network, and identity telemetry into single-pane consoles for mid-market manufacturers. |
| Acquisition of Specialist Firm | Captures CISSP-credentialed talent pools and FedRAMP authorization pathways in underserved geographies. |
| Geographic Expansion | Addresses critical access hospital demand in Mountain West states with limited national provider presence. |
| Strategic Partnership | Secures pre-integrated technology alliances that compress procurement cycles from twelve months to ninety days. |
| Product Launch | Deploys AI-augmented service desks with large language model integration for tier-one support deflation. |
Research Methodology
Bottom-up enterprise workload modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core of this study. Primary interviews with CISOs, federal procurement officers, healthcare IT directors, and managed service provider executives combined with secondary validation against SEC cybersecurity disclosure filings, FedRAMP authorization databases, and state hospital association infrastructure surveys. Triangulation across demand-side budgeting data and supply-side capacity announcements ensures cross-verification.
Input-output matrices map service type, deployment model, and end-user scale dimensions across the projection horizon. Segmentation modeling incorporates vertical industry, organization size tier, and geographic regulatory cluster variables. CAGRs derive from compounding annual deployment velocity assumptions adjusted for compliance mandate acceleration effects. Forecast inputs include hyperscaler capex trajectories and federal contractor continuous monitoring obligation timelines.
Inputs from federal procurement databases and hospital capital expenditure disclosures were available through the study window; gaps in private mid-market IT budgeting introduce uncertainty bands around medium enterprise segment projections. Forecasts reflect documented assumptions regarding SEC enforcement intensity and NIST framework adoption velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Asia-Pacific Enterprise Asset Management Market
Enterprise Services
Middle East and Africa Enterprise Software Market
Enterprise Services
North America Managed Services Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Europe IT Services Market
Enterprise Services
Workforce Management Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
Enterprise Collaboration Service Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Global Cloud Professional Services Market
Enterprise Services
Managed Services Market
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
IoT Professional Services Market
Enterprise Services
GCC Managed Service Market
Enterprise Services
Shared Services Market