
 Europe IT Services Market | 2026-2036
Europe IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IT Services Market Foresight
Channel partnerships between systems integrators and hyperscale cloud providers is reshaping how European enterprises procure IT services. Accenture plc leverages its multi-cloud orchestration capabilities to anchor large transformation programs across the continent. Capgemini SE sustains competitive positioning through deep manufacturing sector expertise, particularly in industrial IoT implementations. Tata Consultancy Services Limited dominates offshore delivery networks that feed European project pipelines with cost-optimized engineering talent.
Europe IT Services encompasses the design, development, integration, and management of software applications, infrastructure platforms, and digital business processes delivered through on-premise, cloud-based, or hybrid deployment models, typically governed by service-level agreements specifying uptime thresholds, security protocols, and data residency requirements. Cloud Services now captures the dominant margin pool as enterprises exit owned datacenter obligations, while Managed Services accelerates fastest among segments as CIOs transfer operational risk to external operators. Consulting maintains premium pricing in the transformation layer where business process redesign intersects with technology architecture, though Support Services faces compression from automated ticketing and remote monitoring tools.
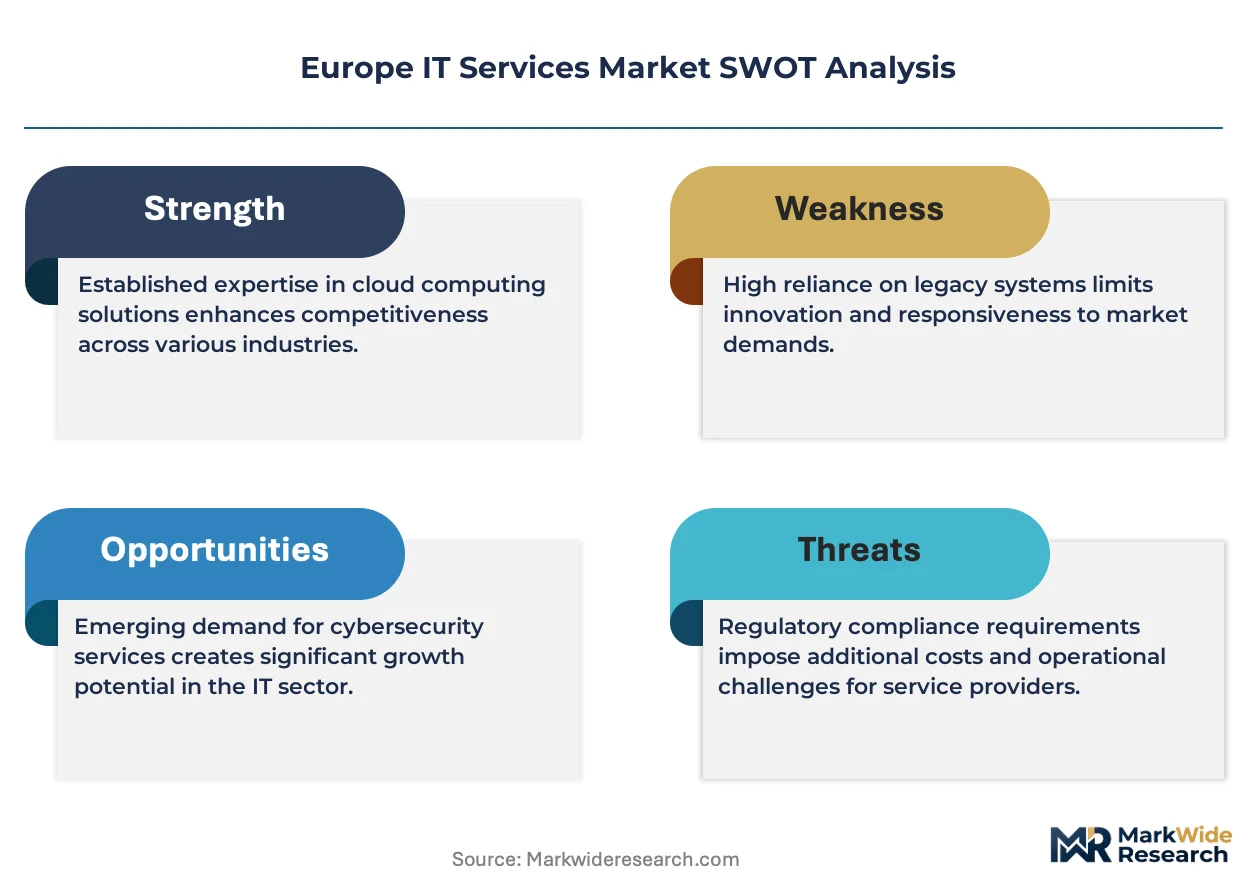
The EU AI Act and GDPR impose binding algorithmic transparency and data localization requirements that elevate compliance costs for providers serving European clients. EMA guidelines on digital health record interoperability and the EU Cybersecurity Act's certification frameworks further constrain market entry for non-compliant vendors. Stakeholders must monitor how the CSRD's sustainability reporting mandates reshape RFP criteria for public sector and regulated industry contracts.
Market Dynamics
The EU AI Act's binding risk-classification framework is forcing service providers to reengineer compliance architectures, creating a structural divide between compliant operators and vendors facing market exclusion.
Growth Catalysts
- Factory-floor digitization:German automotive manufacturers are expanding managed services contracts to integrate industrial IoT sensors with predictive maintenance platforms.
- GDPR data residency mandates:Financial institutions in France's Paris corridor are migrating core systems to hybrid cloud environments to satisfy cross-border data transfer restrictions.
- CSRD sustainability reporting:Public sector procurement criteria now embed carbon disclosure requirements, steering RFP volume toward certified green IT providers.
Market Restraints
- Engineering talent scarcity:Cloud architecture and AI governance specialists command premium compensation, compressing project margins for fixed-bid contracts.
- Hyperscale dependency:European enterprises route over half of cloud workloads through three dominant infrastructure providers, creating concentration risk in outage scenarios.
- Legacy system entanglement:Core banking and manufacturing execution systems built on COBOL and proprietary protocols resist API-based modernization without costly middleware layers.
Strategic Opportunities
- Edge computing expansion:Eastern European manufacturing clusters lack localized data processing capacity, opening greenfield deployment opportunities for low-latency industrial analytics.
- Sovereign cloud demand:Gaia-X federated infrastructure specifications create procurement pathways for EU-controlled data environments outside hyperscale ecosystems.
- Cybersecurity certification:The EU Cybersecurity Act's certification frameworks for cloud services and 5G components create first-mover advantages for compliant vendors in regulated verticals.
Industry Challenges
- Multi-jurisdiction compliance:Providers serving clients across Germany, France, and Benelux must maintain parallel data governance protocols, duplicating audit and documentation overhead.
- Skill-to-wage mismatches:Offshore delivery centers in Poland and Romania face retention pressure as Western European competitors recruit locally for hybrid work arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IT Services Market |
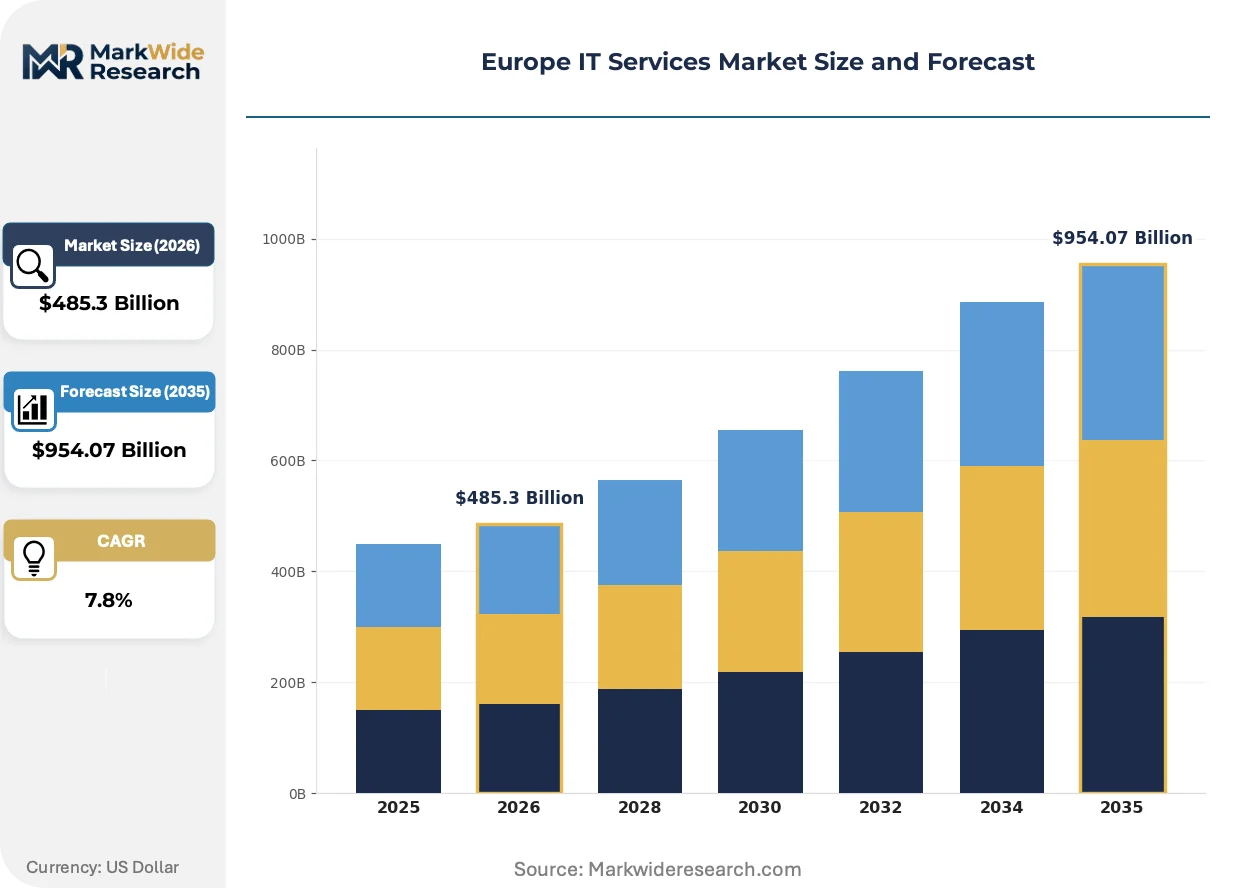
| Market Size in 2026 | $485.3 Billion |
| Market Size in 2035 | $954.07 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Managed Services, Consulting, Support Services End User: SMEs, Large Enterprises, Government, Educational Institutions Deployment Model: On-Premise, Cloud-Based, Hybrid, Offshore Industry Vertical: Healthcare, Finance, Retail, Manufacturing |
| Companies Covered | IBM Consulting, Cognizant Technology Solutions Corporation, Accenture plc, Wipro Limited, Infosys Limited, Capgemini SE, Atos SE, CGI Inc., Tata Consultancy Services Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IT Services Market Shifts & Advancements
Generative AI tooling is collapsing traditional service delivery timelines, compressing the gap between consulting diagnosis and implementation execution across European enterprise accounts.
Agentic AI orchestration platforms are collapsing the manual handoffs between business process analysis and code generation. German automotive suppliers and Dutch logistics operators are piloting these systems for supply chain optimization workflows. The technology is collapsing the traditional systems integration value chain by embedding implementation capacity directly into diagnostic layers.
The EU AI Act's risk-based classification system imposes documentation and human oversight obligations on high-risk applications including credit scoring and medical diagnostics. Providers must maintain algorithmic impact assessments and conformity declarations subject to market surveillance authority audits. Financial services and healthcare verticals in France and Germany are prioritizing compliance-ready platforms over functionality-first alternatives.
Enterprise buyers are consolidating vendor relationships to reduce interface complexity, replacing fragmented best-of-breed portfolios with integrated transformation partners. Systems integrators capturing end-to-end cloud migration and managed services contracts are displacing point-solution specialists. This concentration is most pronounced in the United Kingdom's financial services sector and Nordic public sector procurement frameworks.
Europe IT Services Market Segmentation
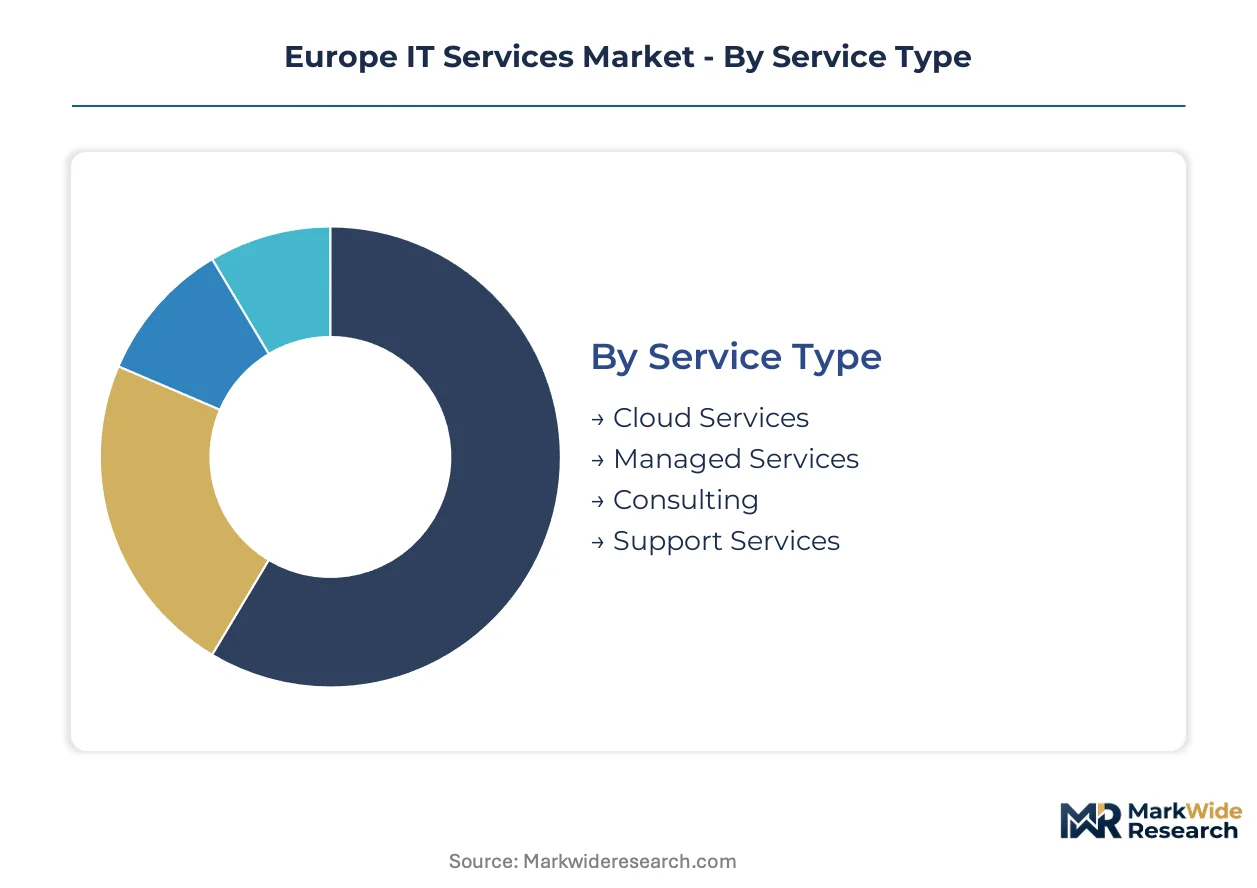
Europe IT Services market segmentation reveals how procurement priorities diverge across client scale, regulatory exposure, and infrastructure maturity. Understanding these fault lines clarifies where margin pools concentrate and which service configurations face commoditization pressure.
Service Type:
Enterprise buyers deploy distinct service combinations based on internal capability gaps and risk transfer preferences, creating tiered pricing power across the value chain.
- Cloud Services:Encompasses infrastructure-as-a-service, platform-as-a-service, and software-as-a-service delivery models governed by uptime SLAs and data residency clauses. German automotive manufacturers and French financial institutions drive demand for sovereign cloud configurations that satisfy GDPR cross-border transfer restrictions. The dominant share belongs to Cloud Services, while Managed Services is closing the gap fastest.
- Managed Services:Transfers operational responsibility for infrastructure monitoring, security operations, and application maintenance to external operators under outcome-based contracts. Factory-floor digitization initiatives across Bavarian and Baden-Württemberg industrial clusters expand multi-year managed services footprints.
- Consulting:Delivers business process redesign, technology architecture planning, and change management services at premium day rates.
- Support Services:Covers break-fix maintenance, help desk operations, and remote monitoring functions facing automation compression.
Cloud Services commands the dominant margin pool as enterprises exit owned datacenter obligations, while Managed Services expands most quickly as CIOs prioritize operational risk transfer.
End User:
Procurement sophistication and contract scale vary sharply across organizational types, shaping vendor engagement models and pricing architecture.
- SMEs:Mid-market enterprises purchase standardized service bundles through channel partners, prioritizing predictable monthly expenditures over customization depth. Benelux manufacturing SMEs increasingly adopt managed security services to address cyber insurance requirements without internal security operations centers.
- Large Enterprises:Multinational corporations negotiate bespoke transformation contracts with tier-one systems integrators, embedding multi-cloud orchestration and AI governance capabilities. Paris-based banking conglomerates and Frankfurt insurance groups anchor demand for hybrid cloud migration programs.
- Government:Public sector procurement operates under strict tendering rules with sustainability scoring criteria under CSRD-aligned frameworks.
- Educational Institutions:Universities and research centers procure discounted academic licensing and grant-funded cloud research infrastructure.
Large Enterprises generate the dominant contract volume, while Government segments are gaining procurement momentum fastest through EU-funded digital transformation initiatives.
Deployment Model:
Infrastructure location decisions reflect data sovereignty requirements, latency sensitivity, and legacy system interdependencies.
- On-Premise:Retained for workloads subject to strict data localization mandates or proprietary hardware dependencies. Core banking systems in France and medical imaging archives in Germany resist cloud migration due to regulatory interpretation risk.
- Cloud-Based:Public cloud deployment dominates net-new application development and customer-facing digital channels. Nordic enterprises lead adoption rates due to favorable fiber infrastructure and regulatory clarity.
- Hybrid:Combines on-premise control for sensitive data with cloud elasticity for variable workloads. Financial services corridors in Paris and Frankfurt prioritize hybrid configurations to balance GDPR compliance with scalability demands.
- Offshore:Delivery from Poland, Romania, and Bulgaria feeds European project pipelines with cost-optimized engineering capacity.
Hybrid deployments hold the dominant position in current infrastructure planning, while Cloud-Based models are climbing the fastest as net-native application portfolios expand.
Industry Vertical:
Sector-specific regulatory burdens and competitive pressures create divergent technology investment priorities and vendor selection criteria.
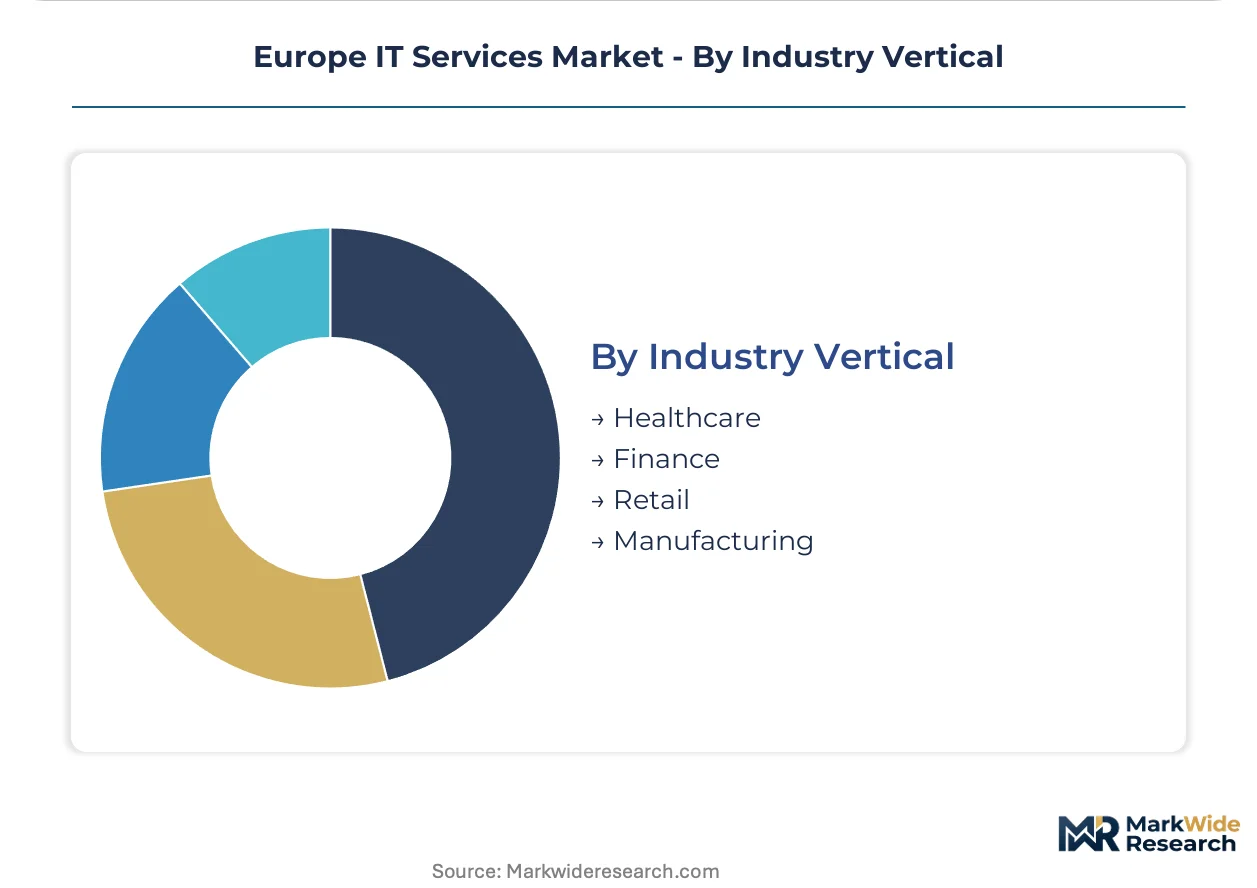
- Healthcare:EMA guidelines on digital health record interoperability and patient data protection constrain vendor eligibility. German university hospitals and French regional health agencies invest in compliant cloud infrastructure for clinical analytics.
- Finance:ECB supervisory expectations and EU AI Act risk classifications elevate compliance architecture requirements. Paris-based asset managers and Frankfurt payment processors migrate core systems to certified environments.
- Retail:Omnichannel fulfillment and customer data platforms drive demand for scalable e-commerce infrastructure.
- Manufacturing:Industrial IoT integration and predictive maintenance platforms anchor managed services expansion across German automotive supply chains.
Finance commands the dominant vertical spend, while Manufacturing is gaining share fastest through factory-floor digitization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German systems integrators command 20-30% pricing premiums over Polish and Romanian competitors for equivalent cloud migration contracts. French financial services corridors extract steeper discounts from providers due to concentrated buyer power and regulatory complexity.
Germany
Bavarian automotive manufacturers and Baden-Württemberg industrial clusters drive demand for factory-floor digitization and predictive maintenance platforms. The EU AI Act's risk-classification framework compels providers to maintain algorithmic impact assessments for high-risk manufacturing applications. Frankfurt's financial services corridor anchors hybrid cloud migration programs for banking conglomerates navigating ECB supervisory expectations.
France
Paris-based asset managers and insurance groups propel core system modernization toward certified cloud environments. GDPR cross-border data transfer restrictions shape procurement criteria for hybrid infrastructure deployments. The Île-de-France financial services corridor concentrates demand for compliance-ready AI governance platforms over functionality-first alternatives.
United Kingdom
London's banking sector consolidates vendor relationships to reduce interface complexity across cloud migration and managed services contracts. The Financial Conduct Authority's operational resilience requirements elevate due diligence standards for critical third-party providers. Edinburgh and Manchester financial centers follow London's procurement patterns with 12-18 month lag cycles.
Netherlands
Amsterdam's fintech ecosystem and Rotterdam logistics operators demand low-latency edge computing for supply chain optimization workflows. The Dutch Authority for Digital Infrastructure enforces strict data localization for government cloud contracts. The Randstad metropolitan cluster concentrates procurement volume for sovereign cloud configurations satisfying Gaia-X specifications.
Poland
Warsaw and Kraków delivery centers feed European project pipelines with cost-optimized engineering talent for cloud architecture and AI governance roles. The Polish Financial Supervision Authority aligns cybersecurity requirements with EU Cybersecurity Act certification frameworks. Silesian manufacturing clusters lack localized data processing capacity, opening greenfield edge computing deployment opportunities.
Europe IT Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain, supplying niche capabilities to broader transformation programs. The vendor base organizes around three strategic archetypes: global consulting firms anchoring end-to-end contracts, offshore delivery networks optimizing engineering costs, and regional specialists embedding compliance expertise. Consolidation pressure intensifies as enterprise buyers reduce vendor counts. M&A activity targets cybersecurity certification capabilities and sovereign cloud infrastructure assets.
Within the global consulting tier, Accenture plc and Capgemini SE exemplify multi-cloud orchestration positioning across European enterprise accounts. Tata Consultancy Services Limited anchors the offshore delivery archetype with cost-optimized engineering networks feeding project pipelines. These three entities represent distinct competitive vectors: consulting-led transformation, manufacturing sector depth, and scale-driven talent arbitrage.
| Leading Market Players |
|---|
| IBM Consulting |
| Cognizant Technology Solutions Corporation |
| Accenture plc |
| Wipro Limited |
| Infosys Limited |
| Capgemini SE |
| Atos SE |
| CGI Inc. |
| Tata Consultancy Services Limited |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's intermodal cost dynamics amplify supply concentration effects across European IT services, compressing margins for Polish and Romanian delivery centers while enabling German systems integrators to command substantial premiums for factory-floor digitization contracts.
Pricing Analysis
The customization-premium spread separates configured-to-order transformation programs from standardized managed services bundles. Subscription-based SaaS-tiered pricing dominates cloud migration contracts, while project-based models anchor consulting engagements. Price differentiation rests on GDPR compliance certification tier and vertical integration depth—sovereign cloud configurations command substantial premiums over public cloud alternatives. Cost compression in offshore delivery tiers intensifies as Western European competitors recruit Polish and Romanian engineers for hybrid arrangements. SMEs exhibit highest price sensitivity, purchasing through channel partners for predictable monthly expenditures, while large enterprises in Frankfurt and Paris prioritize compliance-ready platforms over cost minimization.
Supply Chain Analysis
Contract-manufacturing concentration for IT infrastructure components centers on Taiwan and South Korea for advanced semiconductors, with China anchoring server assembly and networking equipment production. The supply chain draws from specialized silicon foundries, memory module fabricators, and hyperscale data center component suppliers. Single-source vulnerability in advanced GPU and AI accelerator chips creates structural exposure to export control restrictions and logistics chokepoints at Rotterdam and Hamburg ports. Distribution runs through tier-one systems integrators and channel partners delivering bundled hardware-software-service packages to enterprise clients across the continent.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe IT Services Market sits in cyclical recovery as enterprise technology refresh budgets rebound from pandemic-era deferrals, with German automotive manufacturers accelerating factory-floor digitization investments.
For Market Incumbents: Harden compliance architecture investments to capture EU AI Act-mandated reengineering demand before non-compliant vendors face market exclusion. Accenture plc and Capgemini SE should deepen sovereign cloud certification capabilities to defend against hyperscale provider encroachment. Prioritize algorithmic impact assessment tooling and human-in-the-loop governance platforms as defensive moats. For New Entrants and Emerging Players: Pursue edge computing deployment opportunities in Silesian manufacturing clusters and Eastern European industrial zones lacking localized data processing capacity. The most penetrable white space sits in Gaia-X federated infrastructure specifications, where EU-controlled data environments outside hyperscale ecosystems command procurement preference. A compliance-first go-to-market angle—embedding CSRD carbon disclosure and EU Cybersecurity Act certification—opens public sector RFP access. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate IT service divisions lacking sovereign cloud or AI governance capabilities, particularly those serving French financial services corridors with dated compliance architectures. Long-term viability centers on vendors controlling end-to-end transformation workflows rather than point-solution specialists facing consolidation pressure. Watch hyperscale provider partnership exclusivity announcements as inflection indicators for systems integrator margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU AI Act and GDPR mandates steer public sector procurement toward compliant providers. |
| Edge Computing Deployment | Silesian and Baden-Württemberg manufacturing clusters require low-latency industrial analytics infrastructure. |
| AI Governance Platform Integration | Algorithmic impact assessment tooling embeds compliance directly into diagnostic layers. |
| Gaia-X Infrastructure Partnership | Federated specifications create procurement pathways outside hyperscale ecosystems. |
| Managed Services Expansion | CIOs transfer operational risk for factory-floor digitization and predictive maintenance platforms. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with European CIOs, cloud procurement officers, systems integration specialists, and channel partners; and secondary validation through SEC filings of tier-one providers, hyperscaler capex disclosures, EU regulatory filings on AI Act implementation, and customs data on IT equipment trade flows. Bottom-up project pipeline analysis across German automotive and French financial services verticals was triangulated against top-down market sizing from service type segmentation.
Forecast inputs considered deployment model migration patterns, regulatory compliance cost trajectories, and talent arbitrage dynamics across the analysis window. The analytical framework modeled service type, end user scale, deployment architecture, and industry vertical dimensions alongside regional adoption pattern variations. CAGRs were derived from weighted scenario analysis incorporating technology refresh cycles and procurement policy shifts. Cloud workload distribution trends and managed services contract renewal rates served as industry-specific forecast anchors.
Sensitivities concentrate around EU AI Act enforcement timelines, GDPR cross-border data transfer rulings, and hyperscale provider outage frequency. Forecasts embed assumptions on regulatory interpretation consistency across member states and engineering talent retention in Polish and Romanian delivery centers. Quarterly review of sovereign cloud procurement volume and CSRD-aligned RFP scoring criteria is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
United States Customer Technical Support Services Market
Enterprise Services
Telecom Enterprise Services Market
Enterprise Services
Mobile Enterprise Application Market
Enterprise Services
Multi Vendor Support Services Market
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
Enterprise Social Networks Market
Enterprise Services
Qatar Managed Services Market
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
Network Outsourcing Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
Field Service Management Market
Enterprise Services
Asia-Pacific Enterprise Asset Management Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Supplier Management Market