
 Global Immersive Technology Market | 2026-2036
Global Immersive Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immersive Technology Market Foresight
Defense and enterprise training is consolidating as the fastest-expanding demand vertical for immersive systems. Meta Platforms Inc. leverages its Quest hardware ecosystem and Horizon software stack to dominate consumer and enterprise VR adoption. Microsoft Corporation anchors corporate and military segments through its HoloLens mixed reality platform and Azure cloud integration. NVIDIA Corporation specializes in rendering infrastructure, supplying GPUs and Omniverse simulation engines that power real-time 3D environments across industrial applications.
Immersive technology encompasses hardware and software systems that generate or overlay digital environments perceptible through visual, auditory, and haptic sensory channels, typically requiring sub-20 millisecond motion-to-photon latency to prevent user disorientation. These systems serve industrial design, medical visualization, remote operations, and experiential commerce by substituting or augmenting physical presence with computationally generated spatial interfaces. Virtual Reality and Mixed Reality capture the dominant share of current hardware shipments, while 3D Reconstruction and Holography represent higher-margin niches where specialized sensor arrays and photonic components create defensible technology moats. Gaming and Entertainment & Media remain volume leaders, though Military Simulation and Remote Collaboration are outpacing them in annual growth as procurement cycles shorten and enterprise SaaS models mature.
The U.S. Federal Aviation Administration and Food and Drug Administration impose distinct certification burdens on immersive systems deployed for pilot training and surgical planning, respectively, while the EU AI Act classifies certain biometric inference applications as high-risk and mandates conformity assessments before CE marking. China's Ministry of Industry and Information Technology enforces GB standards for head-mounted display electromagnetic compatibility and youth usage duration limits. Stakeholders must track divergent national compliance timelines and pre-certify hardware architectures for multiple regulatory regimes before committing to regional manufacturing scale.
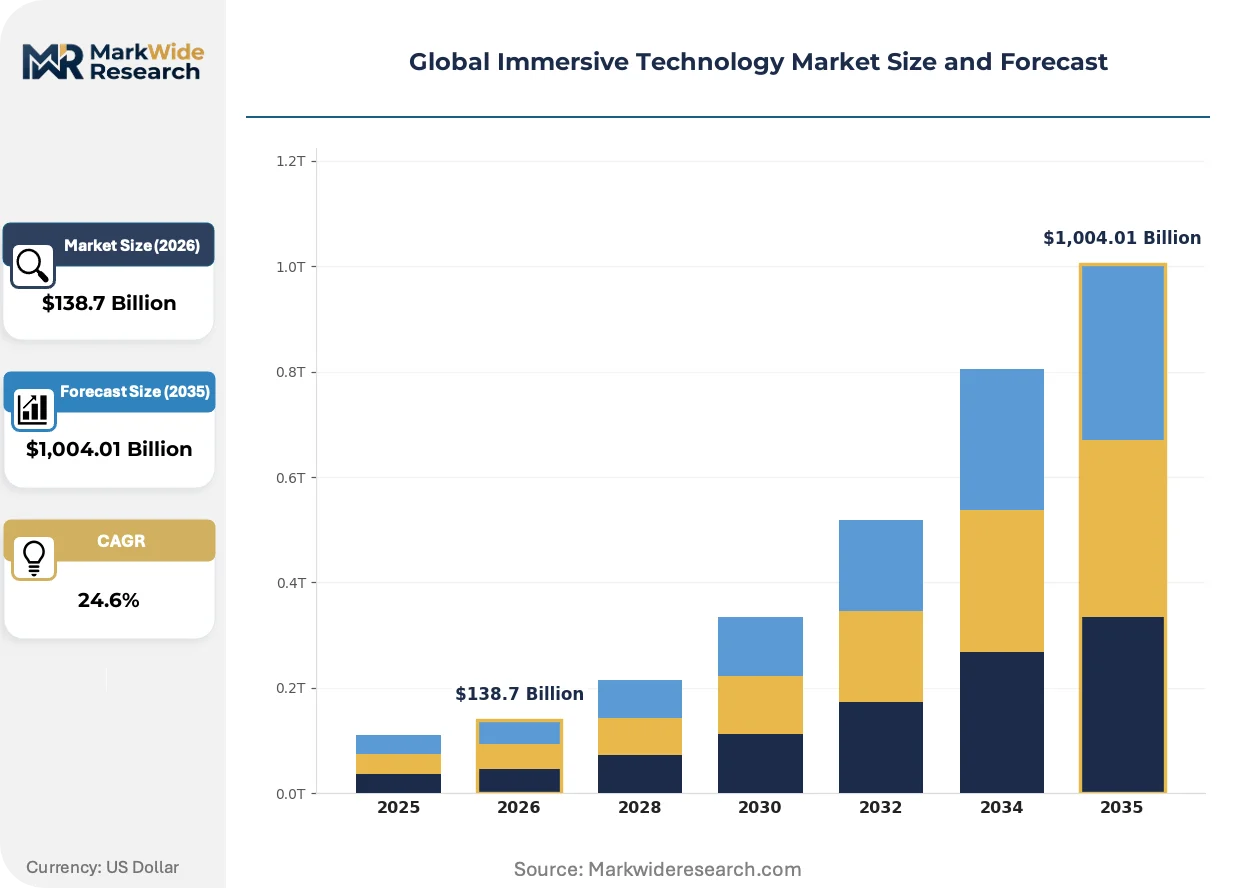
Market Dynamics
Defense procurement cycles are compressing as NATO member states accelerate mixed reality headset deployment for battlefield simulation, while the EU AI Act forces hardware manufacturers to redesign biometric data architectures before CE marking eligibility.
Growth Catalysts
- NATO Defense Modernization:Member state militaries are expanding tactical training programs using mixed reality systems for battlefield simulation and mission rehearsal.
- EU AI Act Compliance Infrastructure:Hardware manufacturers are redesigning data collection architectures to meet high-risk biometric inference conformity assessments for European market access.
- Sub-20ms Latency Standards:Motion-to-photon performance thresholds are expanding addressable use cases into surgical planning and pilot training where disorientation risks previously blocked adoption.
Market Restraints
- Photonic Component Supply Concentration:Specialized sensor arrays and holographic display modules depend on concentrated Asian manufacturing clusters, creating input volatility.
- FAA and FDA Certification Burdens:The U.S. Federal Aviation Administration and Food and Drug Administration impose distinct pre-market approval timelines for pilot training and surgical planning applications.
- GB Standard Electromagnetic Compatibility:China's Ministry of Industry and Information Technology enforces head-mounted display EMC testing and youth usage duration limits that fragment hardware design requirements.
Strategic Opportunities
- Industrial Omniverse Integration:Real-time 3D simulation engines are converging with digital twin platforms to create captive demand from automotive and aerospace design workflows.
- Healthcare SaaS Procurement Models:Enterprise software vendors are building dedicated immersive technology pipelines through subscription-based medical visualization platforms.
- Remote Operations Channel Innovation:Haptic feedback systems are enabling new distribution pathways through industrial equipment OEM service networks.
Industry Challenges
- Multi-Regime Pre-Certification:Stakeholders must pre-certify hardware architectures for FAA, FDA, EU AI Act, and GB standards before committing to regional manufacturing scale.
- Legacy System Integration Friction:Enterprise IT departments face complexity bridging sub-20ms immersive pipelines with existing ERP and PLM data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immersive Technology Market |
| Market Size in 2026 | $138.7 Billion |
| Market Size in 2035 | $1,004.01 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Virtual Reality, Augmented Reality, Mixed Reality, 3D Reconstruction, Holography Application: Gaming, Education & Training, Entertainment & Media, Military Simulation, Remote Collaboration End User: Software Developers, Content Creators, Educational Institutions, Defense Agencies, Corporate Training Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Meta Platforms Inc., Microsoft Corporation, Apple Inc., Sony Group Corporation, Google LLC, HTC Corporation, NVIDIA Corporation, Unity Software Inc., Magic Leap Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immersive Technology Market Shifts & Advancements
Spatial computing architectures are actively compressing the boundary between physical and digital presence, with rendering infrastructure, biometric compliance, and procurement model innovation converging to reshape competitive positioning.
Foveated rendering combined with AI-driven gaze tracking is unifying visual quality and computational efficiency in next-generation headsets. Medical visualization teams at major hospital systems are adopting these systems for surgical planning at accelerated procurement cycles. This unification is compressing hardware cost curves while expanding addressable use cases beyond gaming into clinical and industrial applications.
The EU AI Act's high-risk classification for biometric inference applications is mandating conformity assessments before CE marking for European deployments. Hardware manufacturers are redesigning on-device processing architectures to minimize cloud data transmission. Mixed reality headsets with eye-tracking capabilities face the steepest compliance timelines and are responding with edge-computing sensor fusion designs.
Enterprise buyers are consolidating vendor relationships through integrated hardware-software-service contracts rather than component procurement. Systems integrators and IT consultancies are displacing traditional AV distributors as the primary channel for industrial and healthcare deployments. This consolidation is most visible in the United States, where Department of Defense and healthcare system procurement pipelines favor single-source immersive technology platforms with Azure cloud integration.
Global Immersive Technology Market Segmentation
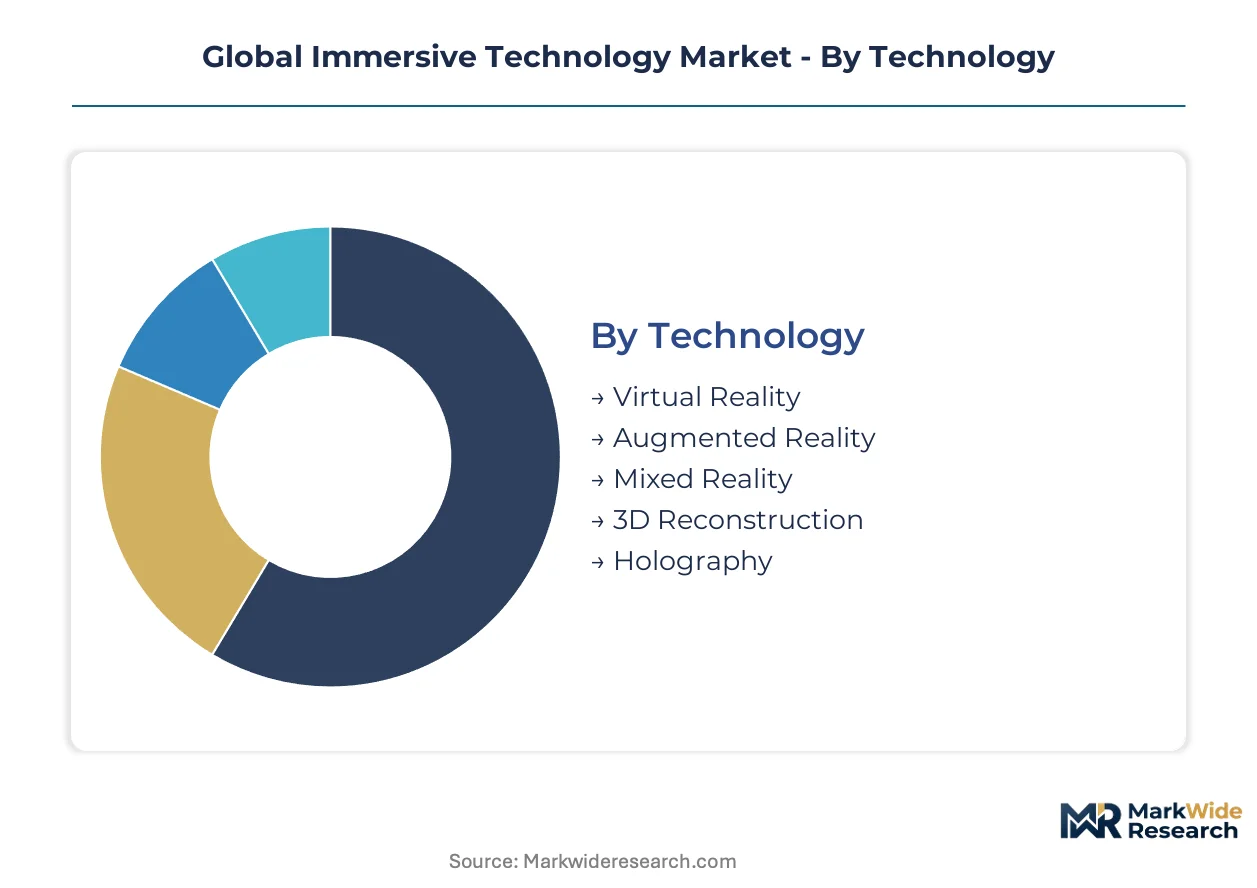
Immersive technology vendors face divergent engineering requirements across deployment contexts, from sub-20ms latency demands in surgical training to electromagnetic compliance for defense field use. Segmentation reveals where standardization yields scale economies versus where customization commands premium positioning.
Technology:
Customization intensity spans from commoditized display modules to proprietary photonic arrays, with hardware architecture decisions locking in downstream software ecosystem compatibility.
- Virtual Reality:Fully enclosed headsets with stereoscopic displays and 6DoF tracking dominate consumer shipment volumes. Demand concentrates in United States enterprise training programs where Meta's Quest ecosystem and dedicated procurement pipelines from the Department of Defense standardize hardware specifications.
- Mixed Reality:Passthrough camera arrays overlay digital content onto physical environments, requiring sensor fusion between optical see-through and video see-through architectures. NATO member state militaries are compressing procurement cycles for battlefield simulation systems, with Microsoft's HoloLens anchoring Azure-integrated deployments.
- Augmented Reality:Lightweight optical waveguide displays project contextual data without environment occlusion. Industrial maintenance workflows in German automotive manufacturing drive specialized requirements for ANSI Z87.1 eye safety compliance.
- 3D Reconstruction:Photogrammetry and LiDAR sensor arrays generate spatially accurate digital twins from physical environments. NVIDIA's Omniverse integration creates captive demand from aerospace design workflows requiring real-time physics simulation.
- Holography:Volumetric display systems using photonic components and interference pattern modulation serve high-margin niche applications. Medical visualization teams at Mayo Clinic and Cleveland Clinic deploy these for surgical planning where depth perception accuracy exceeds flat-screen limitations.
Leading the category by volume: Virtual Reality. Growing fastest: Mixed Reality.
Application:
Revenue per seat varies tenfold between entertainment consumption and certified training systems, with regulatory burden determining margin structure more than hardware bill-of-materials.
- Gaming:Consumer entertainment drives headset volume through content ecosystem lock-in. SteamVR and Meta Horizon platforms concentrate demand in United States and Japanese households, with foveated rendering reducing GPU requirements for mainstream adoption.
- Military Simulation:Mission rehearsal and tactical training systems require EM-hardened hardware and classified network air-gapping. The EU AI Act's biometric inference restrictions and NATO interoperability standards fragment procurement specifications across member states.
- Education & Training:Institutional procurement favors subscription SaaS models over perpetual licenses. Medical schools at Johns Hopkins and Stanford accelerate surgical simulation adoption as FDA 510(k) pathways clarify for digital therapeutics.
- Entertainment & Media:Location-based experiences and cinematic VR command premium ticket pricing. Dubai's Museum of the Future and Tokyo's teamLab installations drive specialized 360-degree camera rig demand.
- Remote Collaboration:Enterprise meeting replacement and industrial telepresence expand addressable use cases post-pandemic. Siemens and Boeing deploy HoloLens-guided remote expert systems for field technician support.
Volume leader: Gaming. Steepest expansion trajectory: Military Simulation.
End User:
Procurement sophistication ranges from individual creator tool selection to federal acquisition regulations with multi-year certification timelines.
- Defense Agencies:NATO and Five Eyes member militaries mandate TAA-compliant supply chains and JITC interoperability certification. United States Army IVAS program and British Army's Morpheus project consolidate mixed reality headset standards.
- Corporate Training:Fortune 500 learning and development departments favor integrated hardware-software-service contracts. Walmart and UPS deploy VR safety training at scale through Strivr and PIXO platforms.
- Educational Institutions:University procurement offices balance upfront cost against multi-year total cost of ownership. Arizona State and Singapore's Nanyang Technological University operate dedicated immersive learning labs with vendor partnership programs.
- Software Developers:Indie and enterprise studios license engines and SDKs based on target platform addressable market. Unity and Unreal Engine dominate, with Godot gaining traction among EU-based developers seeking open-source compliance flexibility.
- Content Creators:Independent producers and studio post-production houses select tools for pipeline integration with existing 2D workflows. volumetric capture stages in Los Angeles and London serve music video and advertising production.
Fastest-growing demand: Defense Agencies. Largest installed base: Corporate Training.
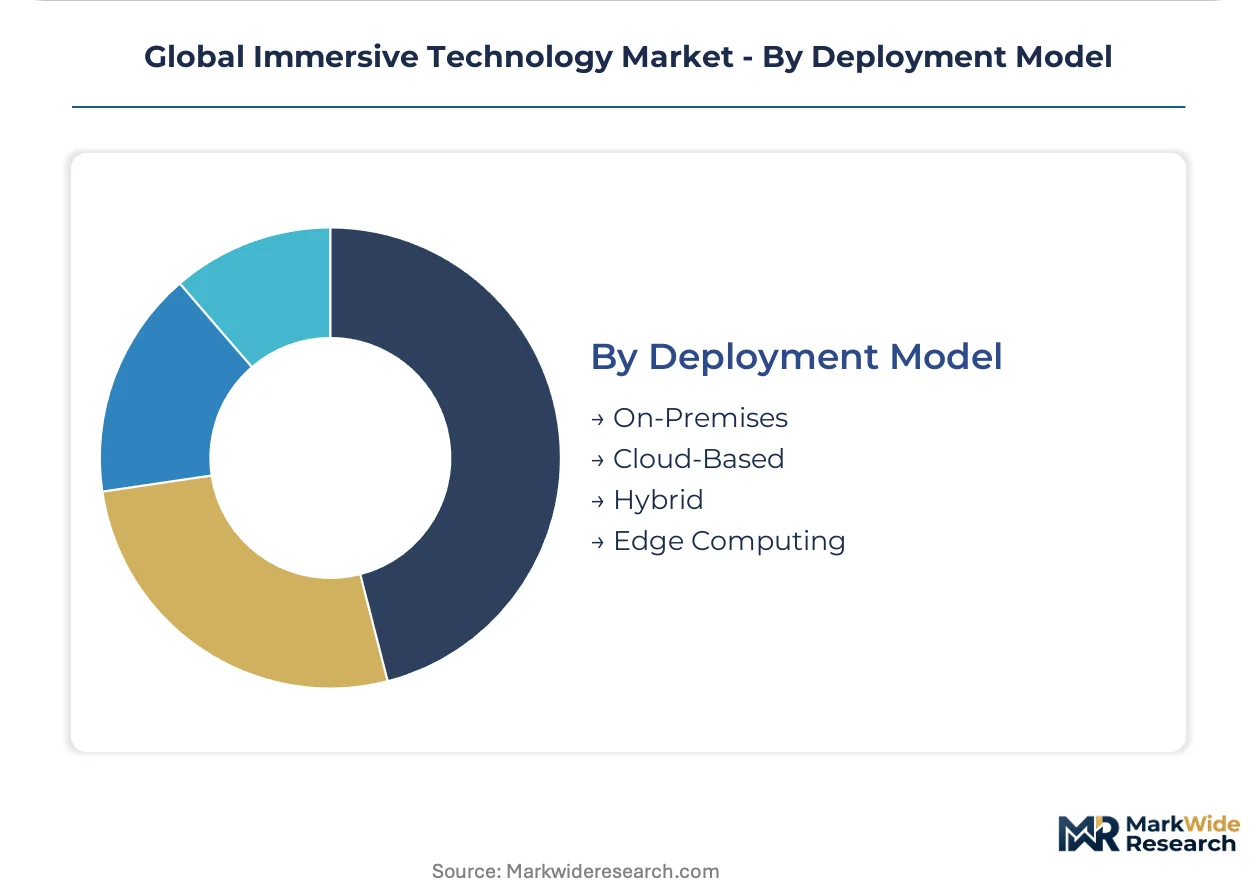
Deployment Model:
Data sovereignty requirements and latency sensitivity determine architecture choice, with hybrid configurations emerging as dominant pattern for regulated industries.
- Cloud-Based:Centralized rendering and storage enable thin-client headsets with lower unit costs. Healthcare systems in United States navigate HIPAA business associate agreement complexity with AWS and Azure healthcare clouds.
- Edge Computing:On-premise GPU clusters process sensor data with sub-20ms round-trip guarantees. German automotive manufacturers deploy edge-based digital twin synchronization for real-time design collaboration.
- Hybrid:Sensitive processing on-device with non-sensitive workloads cloud-offloaded balances compliance and capability. EU AI Act conformity assessments favor this architecture for biometric inference applications.
- On-Premises:Fully air-gapped systems serve classified environments and jurisdictions with data localization mandates. China's MIIT GB standards enforcement and Saudi Arabia's SDAIA requirements drive regional deployment variations.
Dominant architecture by new deployments: Hybrid. Expanding most quickly: Edge Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware manufacturing clusters in East Asia supply components to consumption centers in North America and Europe, where defense procurement and healthcare certification drive premium demand. Regulatory divergence across jurisdictions fragments deployment architectures.
United States
The Department of Defense and healthcare systems anchor immersive technology procurement through dedicated acquisition pipelines. The FDA and FAA impose distinct certification burdens on surgical planning and pilot training applications. Greater Boston and Seattle host concentrated medical visualization and cloud infrastructure development.
China
Domestic headset manufacturers serve industrial design and education markets under GB standards enforcement. The Ministry of Industry and Information Technology mandates electromagnetic compatibility testing and youth usage duration limits. Shenzhen and Beijing clusters specialize in display module production and AI-driven rendering engines.
Germany
Automotive manufacturers drive industrial mixed reality adoption for digital twin synchronization and real-time design collaboration. REACH and RoHS compliance requirements shape hardware material selection for European market access. Bavaria and Baden-Württemberg concentrate aerospace and automotive engineering workflows.
United Kingdom
The British Army's Morpheus project consolidates mixed reality standards alongside NATO interoperability requirements. Post-Brexit regulatory alignment with EU AI Act biometric inference classifications delays certain CE-marked product launches. London and Cambridge clusters focus on defense simulation and enterprise software integration.
Japan
Industrial maintenance and location-based entertainment sustain demand for optical waveguide and volumetric display systems. METI standards and PMDA pathways govern medical device classification for surgical planning tools. Tokyo and Osaka metropolitan areas concentrate volumetric capture stages and post-production facilities.
Global Immersive Technology Market Competitive Landscape
Top-tier vendors anchor integrated hardware-software-service ecosystems, while component specialists and regional fabricators occupy lower tiers with narrower scope. The market structure reflects consolidation around cloud-integrated platforms and fragmentation among niche photonic component suppliers. Three archetypes dominate: ecosystem orchestrators with captive software stacks, rendering infrastructure providers supplying simulation engines, and specialized sensor array manufacturers serving medical and defense verticals. Competitive moves center on strategic partnerships binding hardware to cloud infrastructure and portfolio diversification into adjacent biometric compliance architectures.
Within the ecosystem orchestrator tier, Meta Platforms Inc. and Microsoft Corporation represent contrasting approaches to enterprise and defense market penetration. NVIDIA Corporation occupies a position as rendering infrastructure anchor, supplying GPUs and simulation engines that power industrial digital twin workflows. Apple Inc. exemplifies the premium-tier hardware specialist archetype, with product positioning that commands margin through integrated silicon and proprietary optical designs. These three companies collectively illustrate how competitive positioning depends on vertical scope rather than hardware shipment volume alone.
| Leading Market Players |
|---|
| Meta Platforms Inc. |
| Microsoft Corporation |
| Apple Inc. |
| Sony Group Corporation |
| Google LLC |
| HTC Corporation |
| NVIDIA Corporation |
| Unity Software Inc. |
| Magic Leap Inc. |
| Others |
Supply & Pricing Matrix
Defense procurement programs in the United States and NATO member states anchor pricing power for mixed reality headsets, with volume commitments from the Department of Defense and British Army standardizing contract structures around multi-year hardware-software-service bundles.
Pricing Analysis
Cost-down pressure on enterprise-grade headsets accelerates because Meta's Quest ecosystem and Microsoft's HoloLens platforms compete for Department of Defense IVAS-scale contracts. Pricing stratifies across FAA-certified pilot training systems, FDA-cleared surgical planning devices, and uncertified enterprise collaboration tools. Certification tier and volume scale drive price differentiation, with healthcare systems showing highest price sensitivity due to reimbursement constraints while defense agencies prioritize interoperability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from automotive and aerospace manufacturers, while systems integrators displace traditional AV distributors for healthcare deployments. Manufacturing concentrates in China, Taiwan, and South Korea for display modules, photonic sensors, and GPU fabrication. Specialized holographic components draw from concentrated Asian clusters, creating single-source vulnerability for volumetric display arrays. Distribution runs through cloud infrastructure providers binding hardware to Azure and AWS healthcare clouds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foveated rendering with AI-driven gaze tracking is displacing fixed-fovea architectures, compressing hardware cost curves while expanding surgical planning and industrial design applications previously blocked by GPU constraints.
For Market Incumbents: Deepen backward integration into photonic sensor arrays to reduce dependence on Taiwanese and South Korean component suppliers facing tariff exposure. Lock in Department of Defense procurement pipelines through JITC interoperability certification ahead of NATO standardization, while defending margin position in healthcare SaaS against emerging platform-agnostic entrants. For New Entrants and Emerging Players: Edge-computing sensor fusion for EU AI Act biometric compliance represents the most penetrable wedge, with German automotive manufacturers and British defense contractors seeking alternatives to Microsoft-Azure bundled pricing. Target industrial maintenance workflows requiring ANSI Z87.1 eye safety compliance, selling through OEM service networks rather than direct enterprise IT procurement. For Investors and Strategic Acquirers: The window for entry favors specialized photonic component manufacturers with medical-grade depth perception IP and established Mayo Clinic or Cleveland Clinic validation. Long-term viability hinges on regulatory moat breadth across FDA, FAA, and EU AI Act conformity pathways. Watch for CE marking delays on biometric inference headsets as inflection signal for compliance-first acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Architecture | Edge-computing redesigns unlock CE-marked access for biometric inference headsets in German healthcare systems. |
| NATO Interoperability Certification | JITC validation secures Department of Defense and British Army Morpheus program procurement pipelines. |
| Healthcare SaaS Platform Integration | Subscription models through Strivr and PIXO displace perpetual licenses at Walmart and UPS training scale. |
| Omniverse Rendering Partnership | NVIDIA integration captures automotive digital twin demand from Siemens and Boeing design workflows. |
| Photonic Component Backward Integration | In-house sensor array production reduces exposure to Taiwanese supply concentration and tariff volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with immersive technology procurement officers at hospital systems, defense acquisition program managers, and enterprise IT directors. FDA 510(k) submissions, EMA medical device registrations, and NATO standardization documents provided compliance pathway validation. Bottom-up shipment estimates from display module suppliers reconciled with top-down enterprise software licensing disclosures across the analysis window.
Data-stream reconciliation across hardware shipment volumes, cloud infrastructure capex disclosures, and enterprise SaaS booking trends informed the analytical framework. Segmentation dimensions modeled include technology type, application vertical, end-user procurement sophistication, and deployment architecture across the projection horizon. CAGRs derived from regression analysis against defense budget appropriations, healthcare IT spending patterns, and automotive R&D allocation trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement acceleration or GB standards youth usage restriction expansion. Forecasts reflect assumptions regarding NATO procurement cycle compression and FDA digital therapeutics pathway clarity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Enterprise AR Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Somatosensory Virtual Fitting Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mixed Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Retail Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market