
 Global Mixed Reality Market | 2026-2036
Global Mixed Reality Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mixed Reality Market Foresight
Asian optical component foundries are restructuring supply chains for waveguide and micro-display substrates to serve mixed reality OEMs. Microsoft Corporation leverages its Azure cloud backbone to anchor enterprise deployments across manufacturing and defense verticals. Meta Platforms Inc. sustains heavy R&D intensity in spatial computing silicon and neural interface prototypes. Apple Inc. differentiates through premium ecosystem integration and proprietary vision processing architectures.
Mixed reality fuses optical see-through and video see-through displays with spatial mapping and gesture recognition to overlay persistent digital content onto physical environments, typically requiring sub-20ms motion-to-photon latency to prevent user disorientation. Head-mounted displays dominate hardware revenue as defense and healthcare practitioners drive replacement cycles, while smart glasses compete for industrial field-service share with lighter form factors. Training and simulation applications lead software spending as aerospace manufacturers and education institutes adopt virtual prototyping for risk reduction.
The FDA classifies therapeutic mixed reality devices as Class II medical instruments, requiring 510(k) clearance for surgical planning and rehabilitation applications. EMA's MDR framework and the EU AI Act impose conformity assessment obligations on biometric-enabled headsets sold in European member states. Stakeholders must monitor evolving spectrum allocation decisions by the FCC and national regulators in Japan and South Korea, as millimeter-wave and Wi-Fi 7 deployments directly affect untethered device performance thresholds.
Market Dynamics
Pentagon procurement cycles and EU biometric compliance mandates are compressing vendor qualification timelines while Asian optical foundries restructure capacity to serve defense and enterprise OEMs simultaneously.
Growth Catalysts
- Defense procurement acceleration:The Pentagon's mission rehearsal and maintenance training contracts are driving concentrated demand clusters around Seattle, Austin, and Washington DC corridors.
- EU AI Act compliance:CE marking requirements for biometric data processing are forcing device manufacturers to upgrade privacy architectures, creating replacement pull for certified hardware.
- Waveguide substrate supply:Taiwanese and South Korean optical component foundries are expanding cleanroom capacity specifically for mixed reality micro-display fabrication.
Market Restraints
- Silicon photonics cost structure:Custom spatial computing ASICs require multi-million dollar NRE commitments that freeze out mid-tier hardware vendors.
- Rare earth magnet concentration:Neodymium and dysprosium for compact haptic actuators source predominantly from Chinese state-controlled refiners.
- Sub-20ms latency ceiling:Motion-to-photon thresholds demand specialized display controllers that only three semiconductor houses currently manufacture at volume.
Strategic Opportunities
- India manufacturing incentives:The PLI scheme for electronics assembly is attracting mixed reality OEMs to establish final integration facilities near Chennai and Noida.
- Surgical planning certification:FDA Class II 510(k) pathways for therapeutic devices create premium pricing tiers for validated clinical hardware.
- Wi-Fi 7 convergence:Millimeter-wave and 6GHz spectrum deployments enable untethered enterprise headsets that bypass PC-tethered limitations.
Industry Challenges
- Spatial computing talent scarcity:Computer vision engineers with SLAM algorithm expertise command compensation premiums that inflate R&D budgets.
- Biometric compliance timelines:EMA MDR conformity assessments for European medical deployments extend certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mixed Reality Market |
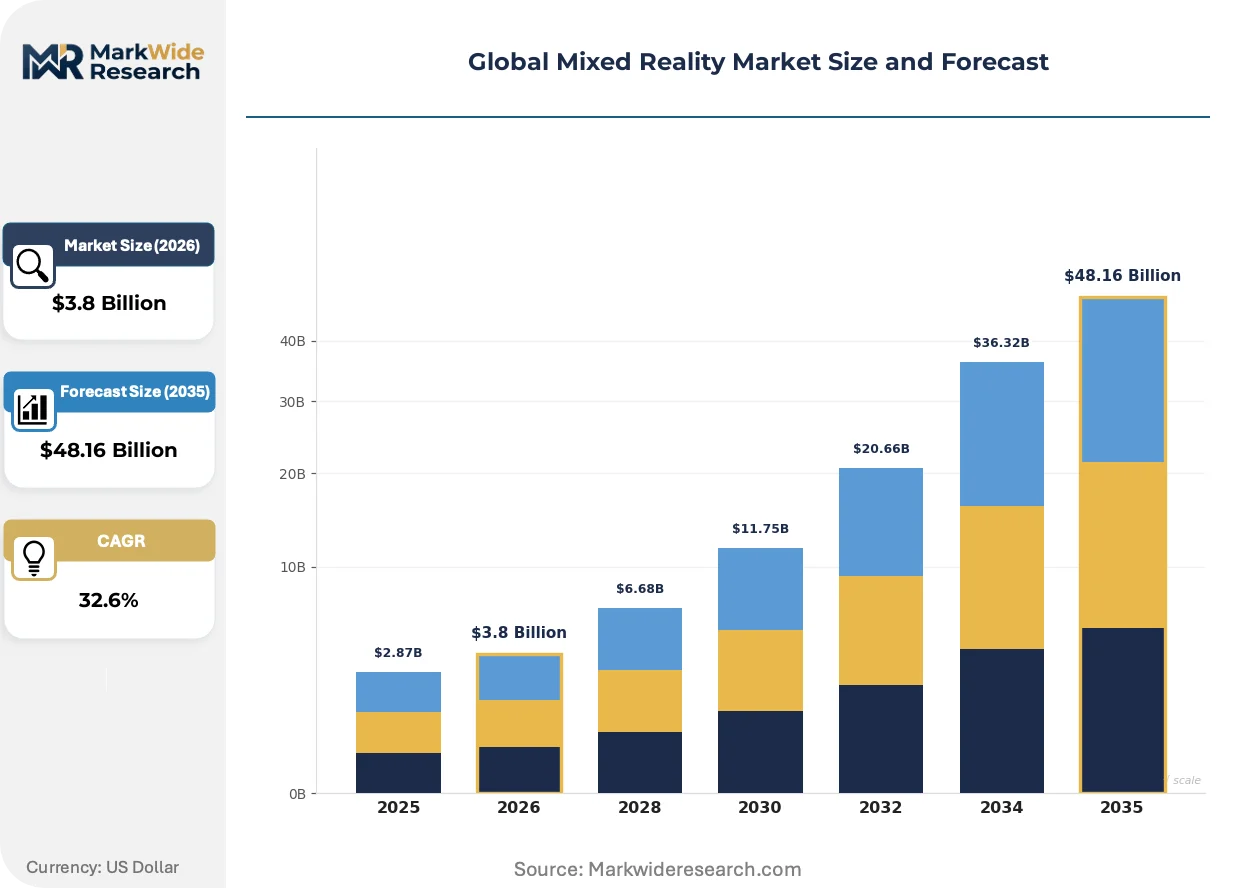
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $48.16 Billion |
| CAGR (2026 – 2036) | 32.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical See-Through, Video See-Through, Spatial Mapping, Gesture Recognition, Depth Sensing, Simultaneous Localization Application: Training & Simulation, Virtual Prototyping, Remote Assistance, Education, Retail Visualization, Real Estate Tours Device Type: Head-Mounted Displays, Projection-Based Displays, Spatial Displays, Handheld Devices, Smart Glasses, Wearable Sensors End User: Manufacturing, Defense & Aerospace, Education Institutes, Entertainment Providers, Architecture Firms, Healthcare Practitioners |
| Companies Covered | Microsoft Corporation, Meta Platforms Inc., Apple Inc., Google LLC, Samsung Electronics Co. Ltd., Magic Leap Inc., HTC Corporation, Sony Group Corporation, Unity Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mixed Reality Market Shifts & Advancements
Optical see-through architectures, biometric privacy mandates, and defense procurement centralization are compressing vendor margins while elevating technical barriers to market participation.
Silicon photonics is consolidating waveguide manufacturing by integrating laser sources, modulators, and detectors onto single substrates. Defense contractors and surgical device OEMs are adopting these monolithic designs to shrink headset volumes. This consolidation is compressing the supplier base from discrete component vendors to vertically integrated foundry operations.
The EU AI Act's biometric data processing rules are forcing hardware redesigns across European-bound devices. Manufacturers must implement on-device inference engines that process iris and facial geometry without cloud transmission. Medical and enterprise headset vendors face the steepest compliance costs, with some deferring EU launches pending certification clarity.
Enterprise buyers are consolidating vendor relationships around integrated platform providers rather than point-solution hardware vendors. Manufacturing and defense procurement offices now require Azure or AWS cloud backbone compatibility as a baseline qualification. This preference shift is most visible in United States federal contracting, where single-vendor accountability reduces integration risk.
Global Mixed Reality Market Segmentation
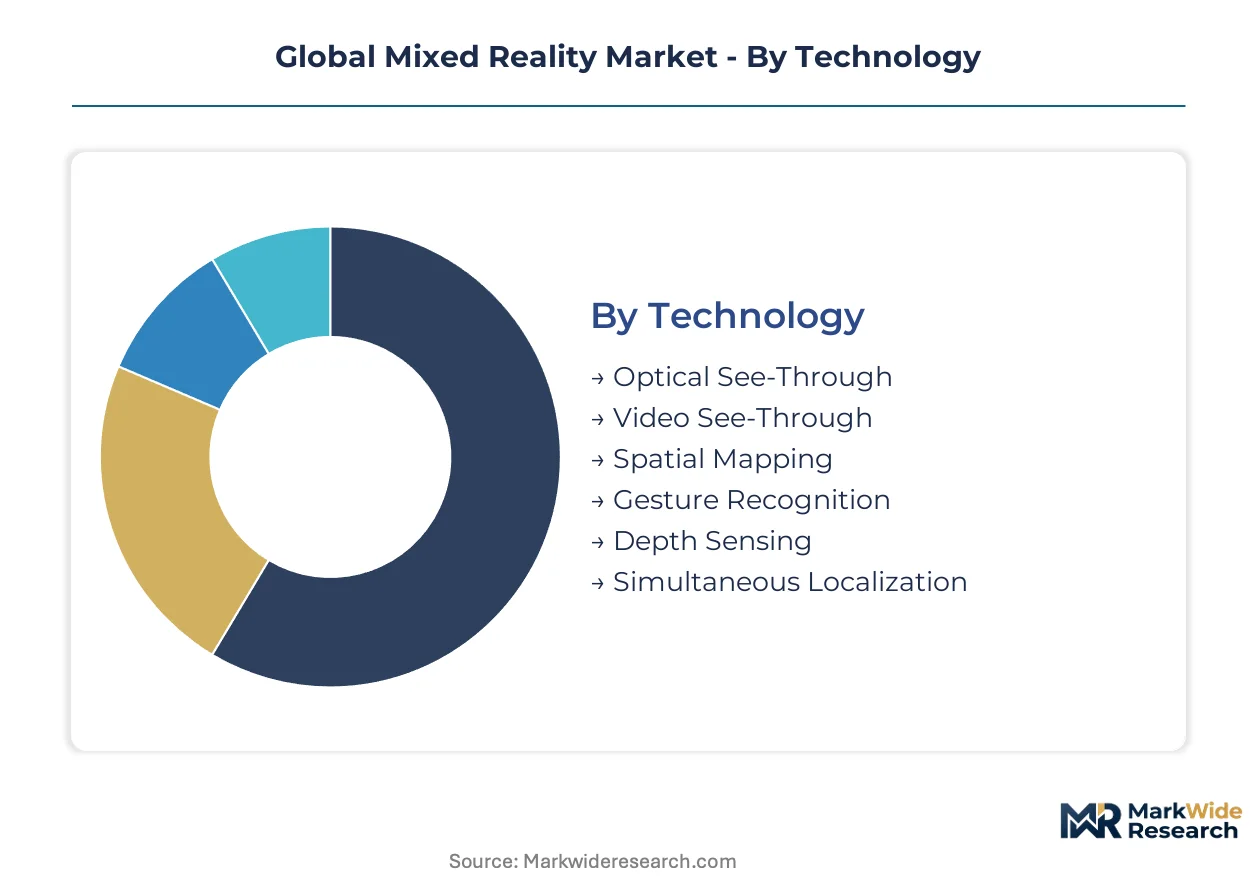
Mixed reality markets fragment across hardware architectures, software applications, and vertical use cases with sharply divergent technical requirements. Procurement patterns in defense and healthcare create concentrated demand pockets that reshape segment priorities faster than consumer adoption curves.
Technology:
Volume deployment favors mature optical architectures, while premium pricing attaches to integrated sensor fusion stacks that reduce latency below perceptual thresholds.
- Optical See-Through:Waveguide-based transparent displays overlay digital content without obstructing physical vision. Defense contractors in the United States specify these for pilot helmet-mounted systems where situational awareness preservation is non-negotiable.
- Video See-Through:Camera-fed passthrough displays enable higher contrast and field-of-view flexibility at the cost of processing overhead. Enterprise manufacturing deployments in Germany and Japan favor these for controlled indoor environments where occlusion handling matters more than outdoor transparency.
- Spatial Mapping:Real-time 3D environment reconstruction enables persistent digital object placement.
- Gesture Recognition:Computer vision-based hand tracking replaces physical controllers for sterile environments.
- Depth Sensing:Time-of-flight and structured light modules enable accurate surface detection.
- Simultaneous Localization:SLAM algorithms maintain device position tracking without external beacons.
Mature deployment sits with Optical See-Through. Newer deployment is concentrated in Video See-Through.
Application:
Customer procurement authority determines segment economics, with federal defense contracts commanding pricing multiples above education institute tenders.
- Training & Simulation:Risk-free skill acquisition environments replicate hazardous procedures without physical consequences. Aerospace manufacturers in France and the United Kingdom deploy these for maintenance certification programs that reduce aircraft downtime.
- Virtual Prototyping:Digital twin validation accelerates product development cycles before physical tooling commitment. Automotive OEMs in Germany and South Korea leverage these for interior ergonomics testing that compresses design iteration timelines.
- Remote Assistance:Expert guidance overlays for field technicians reduce specialist travel requirements.
- Education:Immersive curriculum delivery targets STEM visualization and historical reconstruction.
- Retail Visualization:Virtual product placement enables consumer preview without inventory commitment.
- Real Estate Tours:Spatial walkthroughs reduce physical site visit requirements for remote buyers.
Defense procurement anchors Training & Simulation volumes. Healthcare certification pathways are expanding Virtual Prototyping fastest.
Device Type:
Form factor tradeoffs between immersion depth and wearability duration create distinct procurement tiers across enterprise verticals.
- Head-Mounted Displays:Full-coverage optics with integrated compute deliver maximum immersion at weight penalties exceeding 500 grams. Pentagon contracts specify these for mission rehearsal systems where fidelity overrides comfort constraints.
- Smart Glasses:Sub-100 gram monocular or binocular overlays enable multi-hour wear for industrial field service. Logistics operators in the Netherlands and Singapore deploy these for warehouse picking guidance that maintains peripheral awareness.
- Projection-Based Displays:Spatial projected imagery eliminates head-worn hardware entirely.
- Spatial Displays:Volumetric screens enable group viewing without individual headsets.
- Handheld Devices:Smartphone-based AR maintains consumer accessibility without dedicated hardware investment.
- Wearable Sensors:Haptic feedback gloves and vests add tactile dimension to visual immersion.
Head-Mounted Displays dominate current procurement value. Smart Glasses are gaining share fastest in industrial deployments.
End User:
Compliance requirements fragment procurement specifications, with FDA and EMA medical device pathways imposing validation burdens absent from entertainment deployments.
- Defense & Aerospace:Mission-critical reliability standards mandate extended environmental testing and secure supply chain provenance. United States federal contracting clusters around Seattle and Washington DC corridors concentrate vendor qualification activity.
- Healthcare Practitioners:Therapeutic and surgical planning applications require Class II medical device clearance that extends development timelines. Rehabilitation centers in Switzerland and Australia pilot FDA-cleared systems for stroke recovery protocols.
- Manufacturing:Quality assurance and assembly guidance drive shop-floor deployment.
- Education Institutes:Budget-constrained adoption favors lower-cost handheld and projection solutions.
- Entertainment Providers:Location-based experiences and consumer content distribution target mass market scale.
- Architecture Firms:Design review and client presentation applications prioritize spatial scale accuracy.
Defense & Aerospace maintains the steepest expansion trajectory. Healthcare Practitioners represent the emerging premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet refineries in Chinese state-controlled supply chains anchor upstream material flows for compact haptic actuators. Waveguide substrate fabrication concentrates in Taiwanese and South Korean cleanroom facilities serving defense and enterprise OEMs simultaneously.
United States
Pentagon mission rehearsal contracts and enterprise healthcare pilots drive concentrated demand clusters around Seattle, Austin, and Washington DC corridors. FDA Class II 510(k) clearance requirements govern therapeutic surgical planning and rehabilitation device deployments. Microsoft Corporation leverages its Azure cloud backbone to anchor enterprise manufacturing and defense verticals from Redmond engineering facilities.
Germany
Automotive OEMs deploy virtual prototyping for interior ergonomics testing that compresses design iteration timelines. EMA MDR framework and EU AI Act conformity assessments impose extended certification cycles for biometric-enabled medical headsets. Industrial manufacturing deployments in Bavaria favor video see-through architectures for controlled indoor environments where occlusion handling dominates.
China
MIIT spectrum allocation decisions and GB standards development shape millimeter-wave deployment timelines for untethered device performance. State-controlled rare earth refiners supply neodymium and dysprosium for compact haptic actuators with concentrated upstream leverage. Domestic OEMs establish final integration capacity to serve regional demand while optical component foundries expand waveguide substrate cleanroom operations.
South Korea
MFDS medical device pathways and national spectrum regulators coordinate Wi-Fi 7 and millimeter-wave infrastructure investments affecting headset latency thresholds. Samsung Electronics Co. Ltd. sustains display controller and micro-display fabrication from Suwon and Pyeongtaek semiconductor complexes. Optical foundries in Gyeonggi-do province restructure capacity specifically for mixed reality micro-display substrate production.
India
PLI scheme electronics assembly incentives attract mixed reality OEMs to establish final integration facilities near Chennai and Noida. CDSCO regulatory frameworks for medical device imports create compliance thresholds for therapeutic headset deployments. Tamil Nadu and Uttar Pradesh manufacturing corridors concentrate assembly operations for export-oriented and domestic market supply.
Global Mixed Reality Market Competitive Landscape
Global majors compete with regional champions across cloud backbone integration and spatial computing silicon architectures. The vendor base stratifies into three tiers: integrated platform providers commanding federal contracting relationships, specialized optical hardware fabricators serving defense certification pathways, and mid-tier software vendors licensing spatial mapping engines. Strategic moves concentrate on M&A for SLAM algorithm talent and capacity expansion in Taiwanese waveguide foundries.
Within the integrated platform tier, Microsoft Corporation exemplifies cloud-anchored enterprise positioning, while Meta Platforms Inc. occupies a parallel trajectory in spatial computing silicon and neural interface prototypes. Apple Inc. represents premium ecosystem integration through proprietary vision processing architectures. These three entities anchor distinct competitive vectors rather than convergent positioning.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Meta Platforms Inc. |
| Apple Inc. |
| Google LLC |
| Samsung Electronics Co. Ltd. |
| Magic Leap Inc. |
| HTC Corporation |
| Sony Group Corporation |
| Unity Software Inc. |
| Others |
Supply & Pricing Matrix
Silicon photonics integration onto monolithic substrates is simultaneously collapsing waveguide manufacturing costs and concentrating supplier power among vertically integrated Taiwanese and South Korean foundries. This production-method transition forces defense contractors and medical OEMs to accept longer qualification timelines in exchange for unit cost reductions that reshape total cost of ownership calculations across procurement cycles.
Pricing Analysis
Warranty and service bundling separates Pentagon mission rehearsal contracts from commercial enterprise deployments, with federal buyers demanding multi-year sustainment packages that inflate upfront contract values. Three-tier pricing structure across FDA-cleared medical, defense-certified, and uncertified commercial tiers reflects compliance investment recovery. Cost compression in the commercial tier intensifies because mid-tier hardware vendors lack multi-million dollar NRE commitments for custom spatial computing ASICs. Healthcare practitioners show least price sensitivity due to Class II 510(k) clearance premiums, while education institutes face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements mandated by Pentagon procurement offices force defense contractors to qualify waveguide suppliers in both Taiwan and South Korea simultaneously. Neodymium and dysprosium for compact haptic actuators draw from Chinese state-controlled refiners, while micro-display controllers source from three semiconductor houses in the United States, South Korea, and Taiwan. Single-source vulnerability concentrates in rare earth magnet refining. Distribution runs through Azure and AWS cloud backbone integrations that enterprise buyers now require as baseline qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical see-through architectures are displacing video see-through as the dominant defense specification, creating a technology-transition phase that rewards early certification investments. Legacy camera-fed passthrough systems face accelerated replacement cycles as waveguide transparency becomes non-negotiable for pilot helmet-mounted deployments.
For Market Incumbents: Acquire SLAM algorithm talent pools to offset computer vision engineer compensation premiums that inflate R&D budgets. Consolidate supplier relationships around Taiwanese waveguide foundries with proven Pentagon qualification pathways. Defense procurement centralization around Seattle and Washington DC corridors threatens margin compression for vendors lacking federal contracting presence. Backward integration into micro-display controller fabrication reduces dependency on the three semiconductor houses currently manufacturing at volume. For New Entrants and Emerging Players: Launch via industrial smart glasses deployments in India and Southeast Asia where PLI scheme incentives reduce final integration costs. White-space concentrates in surgical planning certification pathways where FDA Class II 510(k) clearance creates premium pricing tiers. Warehouse picking guidance for logistics operators in the Netherlands and Singapore represents the most penetrable segment due to lighter form factor requirements and lower latency thresholds. Target healthcare rehabilitation centers in Switzerland and Australia piloting stroke recovery protocols. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated platform providers seeking single-vendor accountability for federal contracting relationships. Long-term viability hinges on cloud backbone compatibility as enterprise buyers consolidate vendor relationships. Acquisition target archetype: specialized optical hardware fabricators with EMA MDR conformity assessment completion. Watch EU AI Act biometric compliance timelines as inflection indicator—extended certification cycles signal consolidation pressure on European-bound device manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Waveguide Foundry Capacity Expansion | Taiwanese cleanroom investments serve simultaneous defense and medical OEM demand clusters. |
| On-Device Inference Engine Development | EU AI Act biometric compliance forces hardware redesigns without cloud transmission capabilities. |
| FDA Class II 510(k) Clearance Pathway | Therapeutic surgical planning devices command premium pricing tiers in healthcare procurement. |
| Azure Cloud Backbone Integration | Enterprise manufacturing and defense verticals require single-vendor accountability for procurement qualification. |
| Wi-Fi 7 and Millimeter-Wave Certification | FCC and South Korean spectrum allocations enable untethered headset performance thresholds. |
Research Methodology
Independent corroboration across defense procurement officers, biomedical engineers at rehabilitation centers, optical component foundry executives, and enterprise IT directors underwrites the qualitative findings. Primary interviews with Pentagon contracting specialists, FDA regulatory consultants, and SLAM algorithm researchers combined with secondary validation from SEC filings of major platform providers, EMA MDR submission databases, and FCC spectrum allocation records. Bottom-up demand modeling across device type segments triangulates against top-down market sizing from cloud backbone deployment disclosures.
Rate-of-change decomposition separates hardware unit growth from software and services value expansion across the analysis window. Segmentation dimensions include optical architecture type, application vertical, device form factor, and end-user compliance tier. CAGRs derive from installed base replacement cycles intersecting with procurement authorization timelines. Spatial computing talent scarcity and waveguide substrate cleanroom capacity constraints serve as industry-specific forecast inputs.
Spectrum allocation decisions by the FCC, MIIT, and South Korean regulators, EU AI Act certification clarity, and rare earth magnet supply disruptions are the dominant revision risks. Deviation in Pentagon procurement authorization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
VR HMD Shipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in BFSI Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Immersive Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market