
 Automotive AR and VR Market | 2026-2036
Automotive AR and VR Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive AR and VR Market Analysis
Aftermarket service revenue is reconfiguring toward immersive diagnostics and remote repair guidance. Varjo leverages industrial-grade optics to sustain premium positioning in professional training environments. Unity Technologies anchors real-time 3D content pipelines for automotive design studios. PTC differentiates through its industrial AR platform that competes directly with CAD-integrated visualization tools.
Automotive AR and VR encompasses head-mounted displays, windshield-projected overlays, and spatial computing systems that render digital information within or around physical vehicle environments, typically operating at sub-20 millisecond motion-to-photon latency to prevent simulator sickness. These technologies serve to enhance situational awareness, compress design iteration cycles, and standardize technical training across distributed workforces. Headsets capture the largest share of product-type revenue as fleet operators adopt VR for safety certification programs. Augmented Reality represents the fastest-expanding technology segment as OEMs embed HUD-based navigation and hazard alerts into production vehicles. Driver Assistance applications concentrate margin pools where regulatory mandates for advanced safety systems intersect with consumer willingness to pay for enhanced visibility.
NHTSA, the EU's F-Gas Regulation, and Japan's METI each impose distinct constraints on display thermal management, refrigerant-based cooling systems, and electronics recycling that shape component sourcing decisions. The EU AI Act adds algorithmic transparency requirements for computer-vision-based driver monitoring that extends development timelines for European deployments. Stakeholders must monitor divergence between U.S. permissiveness and European precautionary frameworks when allocating R&D budgets across regional product variants.
Market Dynamics
NHTSA guidelines on driver distraction are compressing display interface development cycles while OEMs accelerate headset deployment for safety certification programs. This regulatory pressure intersects with thermal management constraints from the EU's F-Gas Regulation to reshape component sourcing decisions across the value chain.
Growth Catalysts
- HUD-based navigation mandates:Augmented Reality represents the fastest-expanding technology segment as OEMs embed windshield-projected overlays and hazard alerts into production vehicles.
- Germany's engineering corridor:Demand concentrates in Stuttgart and Munich where automotive R&D clusters drive adoption of spatial computing systems for design iteration.
- EU AI Act transparency requirements:Algorithmic disclosure rules for computer-vision-based driver monitoring extend development timelines but create compliant-first competitive advantages for early movers.
Market Restraints
- Sub-20 millisecond latency thresholds:Motion-to-photon requirements for preventing simulator sickness constrain display controller architectures and increase bill-of-materials complexity.
- Refrigerant-based cooling restrictions:The EU's F-Gas Regulation limits thermal management options for high-brightness head-mounted displays, forcing alternative heat dissipation engineering.
- Electronics recycling mandates:Japan's METI requirements and EU WEEE directives impose end-of-life compliance costs that disproportionately affect modular headset architectures.
Strategic Opportunities
- Aftermarket immersive diagnostics:Service revenue is reconfiguring toward remote repair guidance and spatial troubleshooting for distributed technician workforces.
- Japan's METI digital transformation incentives:Government-backed programs for manufacturing technology adoption create subsidized entry pathways for VR-based safety training platforms.
- Real-time 3D pipeline convergence:Automotive design studios are integrating game engine workflows with CAD visualization, compressing concept-to-clay timelines through interoperable content formats.
Industry Challenges
- Optical engineering talent scarcity:Industrial-grade waveguide design and micro-display calibration require specialized skill sets concentrated in German and Finnish photonics clusters.
- Multi-regulatory certification timelines:Simultaneous NHTSA distraction compliance, EU AI Act algorithmic transparency, and F-Gas thermal management approvals extend product launch windows.
- Legacy vehicle integration complexity:Retrofitting AR HUDs into existing electrical architectures requires CAN bus protocol adaptation and power budget reallocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive AR and VR Market |
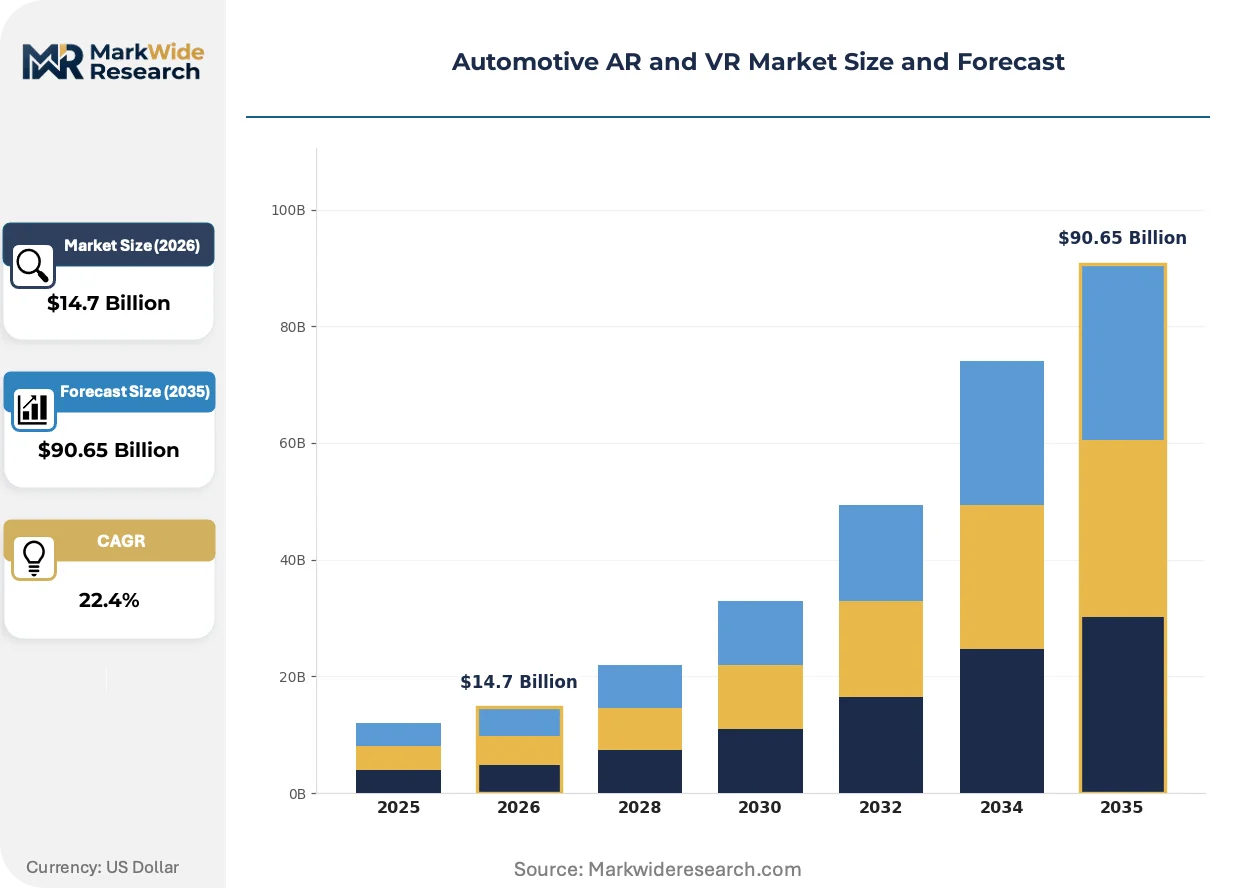
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $90.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Dashboards, Displays, Sensors Technology: Augmented Reality, Virtual Reality, Mixed Reality, Computer Vision Application: Driver Assistance, Vehicle Design, Maintenance Training, Customer Engagement End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Retailers |
| Companies Covered | Autodesk, Varjo, Xreal, PTC, Meta, Unity Technologies, Hyundai Motor, Tecknotrove, Holoride, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive AR and VR Market Emerging Trajectories
Display architectures are bifurcating between premium waveguide-based HUDs and cost-constrained TFT-LCD alternatives. This technical divergence reflects competing OEM strategies around safety-feature monetization versus mass-market penetration.
Waveguide combiner technology is migrating from aerospace and defense applications into automotive HUD programs. Tier-1 suppliers in Germany and Japan are adopting surface-relief grating architectures at accelerated qualification paces. This migration from military-specification origins is enabling slimmer dashboard packaging and wider field-of-view projection without enlarged optical volume.
The EU AI Act imposes algorithmic transparency requirements for computer-vision-based driver monitoring systems. European deployments now require documented training data provenance and decision-log audit trails. Computer-vision HUD modules face extended validation timelines, prompting some OEMs to segregate European product variants from US permissive frameworks.
Fleet operators are unbundling safety certification from hardware purchase, preferring per-seat VR training subscriptions over perpetual headset licenses. Commercial vehicle and logistics segments in North America and Germany are driving this shift. Subscription models reduce upfront capital requirements while ensuring content refresh cycles align with regulatory re-certification schedules.
Automotive AR and VR Market Segmentation
Segmentation in automotive AR and VR exposes divergent margin structures across hardware and software layers. Aftermarket service intensity varies dramatically by product type, with repair networks demanding sustained technical support that reshapes vendor economics.
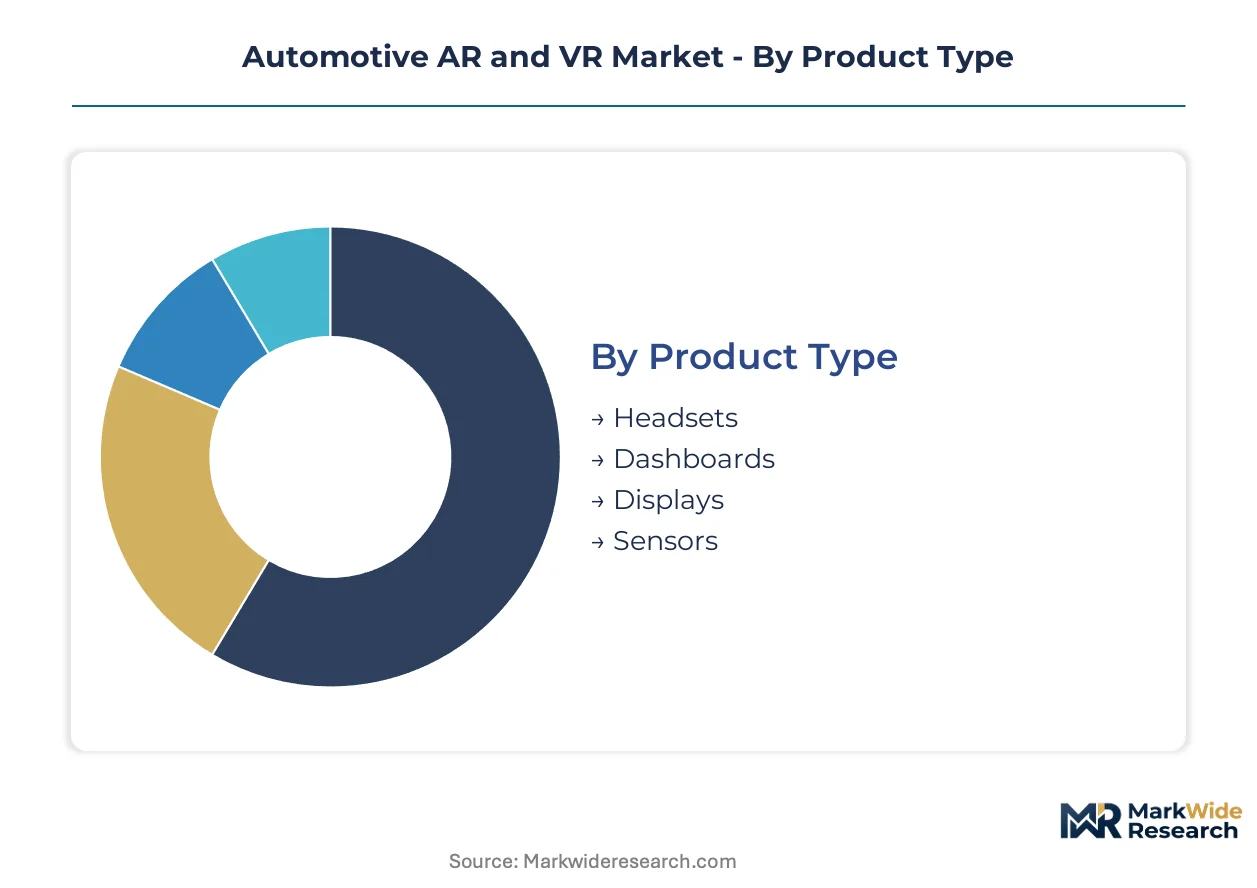
Product Type:
Aftermarket service intensity concentrates in modular hardware segments where field replacement and calibration cycles generate recurring revenue streams for component suppliers.
- Headsets:Encompass tethered and standalone head-mounted displays with sub-20 millisecond motion-to-photon latency specifications. Fleet operators in Germany's logistics corridors deploy these for safety certification programs, with per-seat subscription models displacing perpetual licenses.
- Dashboards:Integrated cockpit units combining projection surfaces with vehicle control interfaces. Stuttgart-based OEMs anchor demand as waveguide combiner technology migrates from aerospace applications into slimmer automotive packaging.
- Displays:Micro-display panels and projection engines for HUD systems. Thermal management constraints from the EU F-Gas Regulation force alternative heat dissipation engineering in high-brightness configurations.
- Sensors:Camera arrays and depth-sensing modules enabling spatial computing. Japan's METI digital transformation incentives subsidize adoption in manufacturing training environments.
Headsets hold the largest share; momentum sits with dashboards as HUD-based navigation mandates expand.
Technology:
Cost tier differentiation separates premium waveguide-based implementations from mass-market TFT-LCD alternatives, with thermal budgets and optical precision driving tier assignment.
- Augmented Reality:Windshield-projected overlays and spatial computing systems rendering digital information within physical vehicle environments. OEMs embed AR-based navigation and hazard alerts into production vehicles, with European deployments facing extended timelines from EU AI Act algorithmic transparency requirements.
- Virtual Reality:Fully immersive environments for design iteration and workforce training. Real-time 3D content pipelines from Unity Technologies anchor adoption in automotive design studios, compressing concept-to-clay timelines.
- Mixed Reality:Blended physical-digital environments combining passthrough video with synthetic content. Varjo leverages industrial-grade optics to sustain premium positioning in professional training applications.
- Computer Vision:Algorithmic systems processing camera feeds for driver monitoring and environmental perception. NHTSA guidelines on driver distraction reshape display interface requirements for vision-based assistance systems.
Augmented Reality commands premium pricing; Virtual Reality is expanding most quickly through fleet safety certification programs.
Application:
Volume concentration aligns with regulatory mandate timing, where advanced safety system requirements intersect with consumer willingness to pay for enhanced visibility.
- Driver Assistance:HUD-based navigation, hazard alerts, and computer-vision monitoring systems. Margin pools concentrate here where NHTSA guidelines and EU safety mandates create compliance-driven procurement.
- Vehicle Design:Virtual prototyping and spatial computing for concept development. Germany's engineering corridor around Stuttgart and Munich drives adoption of interoperable content formats between game engines and CAD visualization.
- Maintenance Training:Immersive diagnostics and remote repair guidance for distributed technician workforces. Aftermarket providers reconfigure service revenue toward spatial troubleshooting capabilities.
- Customer Engagement:Virtual showrooms and configurators for retail environments. Retailers adopt these systems as digital transformation investments, though capital intensity limits deployment scale.
Driver Assistance holds the largest share; Maintenance Training is gaining share fastest as aftermarket service models reconfigure.
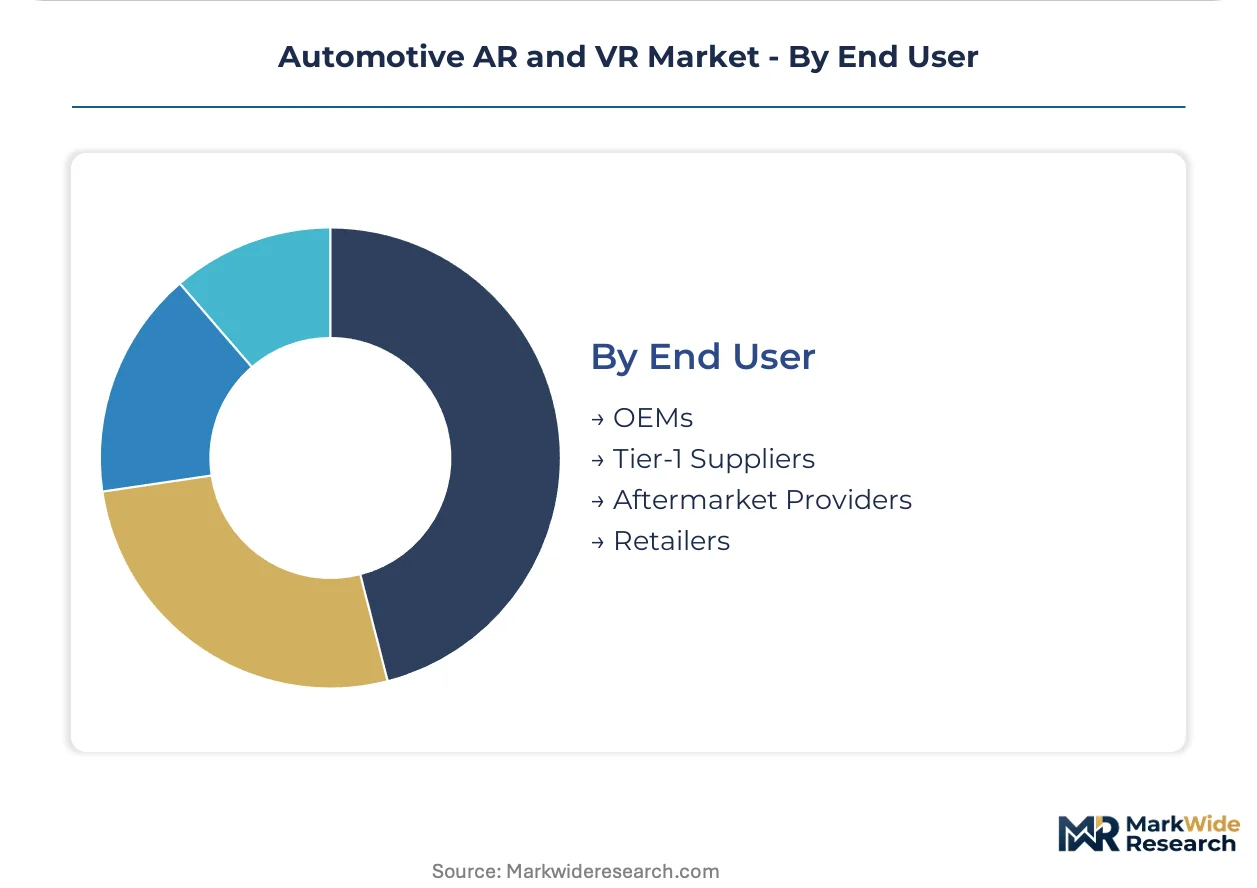
End User:
Customer type determines procurement rhythm, with OEMs driving specification standards that cascade through Tier-1 suppliers and into aftermarket channels.
- OEMs:Vehicle manufacturers integrating AR/VR systems into production platforms. These stakeholders accelerate headset deployment for safety certification while navigating multi-regulatory approval timelines across NHTSA, EU AI Act, and F-Gas frameworks.
- Tier-1 Suppliers:Component and system integrators supplying dashboard modules and HUD assemblies. German and Japanese suppliers adopt surface-relief grating waveguide architectures at accelerated qualification paces.
- Aftermarket Providers:Independent service networks and retrofit specialists. These players face legacy vehicle integration complexity requiring CAN bus protocol adaptation and power budget reallocation.
- Retailers:Dealership networks and consumer-facing sales channels. Capital constraints limit deployment velocity compared to industrial end users.
OEMs hold the largest share; momentum sits with Aftermarket Providers as subscription-based training models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with fleet operators in Germany accepting premium pricing for industrial-grade systems while aftermarket channels in India and Mexico prioritize cost-constrained TFT-LCD alternatives for training deployment.
United States
Fleet safety certification programs drive headset procurement across logistics corridors in Texas and the Midwest. NHTSA guidelines on driver distraction compress display interface development cycles for Detroit-based OEMs. The Southeast manufacturing belt around Georgia and Tennessee anchors VR training adoption for automotive assembly workforces.
Germany
Stuttgart and Munich engineering clusters sustain premium demand for waveguide-based HUD systems in luxury vehicle platforms. The EU F-Gas Regulation restricts thermal management options for high-brightness displays, forcing alternative heat dissipation engineering. Baden-Württemberg's Tier-1 suppliers accelerate qualification of surface-relief grating architectures.
Japan
Automotive design studios in Nagoya and Tokyo adopt real-time 3D pipelines for concept-to-clay compression. METI digital transformation incentives subsidize VR-based safety training platform deployment. The Kanto region concentrates optical engineering talent for micro-display calibration.
China
Domestic OEMs embed AR-based navigation into mass-market electric vehicle platforms at accelerated volumes. MIIT standards for in-vehicle electronics shape local display controller specifications. The Yangtze River Delta around Shanghai anchors HUD assembly capacity for regional supply chains.
South Korea
Hyundai Motor Group's integrated operations drive captive demand for mixed reality design tools in Seoul Capital Area studios. The country's national electronics regulator enforces electromagnetic compatibility standards for head-mounted displays. Busan-Ulsan automotive clusters pilot computer-vision-based driver monitoring systems.
Automotive AR and VR Market Vendor Landscape
Capability concentration sits with specialized optics developers; scale advantage sits with platform-technology conglomerates. The market structures around three tiers: industrial-grade specialists commanding premium positioning, real-time 3D engine providers anchoring content pipelines, and diversified technology groups leveraging consumer electronics scale. Dominant competitive moves include strategic partnerships between automotive OEMs and software platforms, plus technology licensing agreements that accelerate HUD qualification timelines.
Within the industrial-grade specialist tier, Varjo exemplifies premium positioning through precision optics for professional training environments. Among platform-technology providers, Unity Technologies anchors real-time 3D content pipelines that compress automotive design iteration cycles. PTC occupies a position within the industrial AR platform segment, competing against CAD-integrated visualization tools through its ThingWorx ecosystem.
| Leading Market Players |
|---|
| Autodesk |
| Varjo |
| Xreal |
| PTC |
| Meta |
| Unity Technologies |
| Hyundai Motor |
| Tecknotrove |
| Holoride |
| Others |
Supply Flow & Price Mechanics
EU F-Gas thermal management restrictions function as a dual chokepoint that widens pricing spreads between compliant and non-compliant display tiers while forcing supply chain reconfiguration toward alternative cooling component sources. This regulatory friction compresses margins on high-brightness HUD modules while creating premium capture opportunities for vendors with certified heat-dissipation architectures.
Pricing Analysis
Aftermarket service contracts and per-seat VR training subscriptions now drive lifetime value capture beyond initial hardware transactions. Three-tier pricing structure across premium waveguide HUDs, standard TFT-LCD alternatives, and economy sensor modules reflects certification grade differentiation and thermal compliance burden. Cost compression in economy tiers intensifies as Chinese micro-display suppliers expand capacity. Fleet operators in Germany's logistics corridors exhibit lowest price sensitivity due to regulatory re-certification requirements, while Indian aftermarket channels prioritize cost-constrained configurations.
Supply Chain Analysis
Extended payment terms from Tier-1 suppliers to waveguide component vendors now stretch 90-120 days as qualification timelines lengthen. Optical engineering talent concentrates in Germany, Japan, and Finland, with micro-display manufacturing anchored in South Korea and China. Rare-earth phosphor and precision glass substrate dependencies create single-source vulnerability for high-brightness projection engines. Distribution runs through Stuttgart-based system integrators for European OEM programs and Nagoya-Tokyo corridors for Japanese design studio procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive AR and VR market fragmentation creates entry niches as unbundled safety certification models displace perpetual hardware licenses and subscription economics reconfigure buyer-vendor relationships.
For Market Incumbents: Harden defensive positioning through backward integration into waveguide combiner manufacturing and captive optical calibration facilities. Consolidate procurement relationships with Stuttgart-based Tier-1 suppliers before surface-relief grating architectures commoditize. Regulatory compliance investments in EU AI Act algorithmic transparency create switching-cost barriers against emerging software entrants. For New Entrants and Emerging Players: India's aftermarket training channels offer underpenetrated white-space as domestic logistics fleets expand VR safety certification programs. Target maintenance training applications where legacy vehicle integration complexity deters incumbent platform providers. Pursue METI-subsidized deployment partnerships with Japanese manufacturing consortia as a credibility-building beachhead. For Investors and Strategic Acquirers: The market sits at a standards-convergence phase that favors industrial-grade optics specialists with certified thermal management IP. Long-term viability hinges on regulatory compliance moats rather than consumer electronics scale. Monitor NHTSA distraction guideline enforcement intensity as the signal for HUD mandate acceleration and premium pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Waveguide Combiner Qualification | Surface-relief grating certification with Stuttgart Tier-1 suppliers accelerates OEM program integration timelines. |
| Per-Seat Subscription Model | Fleet operator re-certification schedules align recurring revenue with regulatory compliance cycles. |
| EU AI Act Compliance Investment | Algorithmic transparency documentation creates compliant-first competitive positioning in European deployments. |
| Real-Time 3D Pipeline Integration | Unity Technologies content workflows compress concept-to-clay iteration for automotive design studios. |
| METI Subsidy Capture | Japanese government digital transformation incentives reduce customer acquisition costs for VR training platforms. |
Methodological Framework
The analysis maps head-mounted displays, windshield-projected HUDs, and spatial computing sensors, each validated through Tier-1 supplier procurement leads, OEM platform engineering directors, aftermarket service network managers, and optical component specialists. Primary interview findings triangulate against vehicle production databases, IHS Markit registration data, NHTSA regulatory filings, and EU F-Gas compliance registries. Bottom-up component demand modeling and top-down OEM technology adoption surveys converge on segment-level value estimates.
Forecast assumptions hold fixed NHTSA guideline enforcement trajectories and EU AI Act implementation timelines while varying HUD mandate adoption curves and VR training subscription penetration rates across the projection horizon. Segmentation dimensions include product type, technology tier, application use case, and end-user procurement archetype. CAGRs derive from regression analysis against historical safety system adoption patterns and real-time 3D content pipeline deployment rates in automotive design studios.
Practitioners should monitor regulatory divergence between U.S. permissive frameworks and European precautionary approaches for early signals of regional product variant proliferation. Forecast outputs rest on assumptions of sustained semiconductor availability and stable rare-earth phosphor supply; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market