
 China Digital Showers Market | 2026-2036
China Digital Showers Market Size, Share, and Industry Trends Forecast 2026-2036
China Digital Showers Market Insights
The gap between premium digital showers and basic thermostatic units is shifting from feature count to ecosystem integration. Jomoo leverages its domestic manufacturing scale to control costs across Guangdong production bases. Kohler China anchors its position through R&D intensity in touchscreen interface development. HEGII differentiates via channel control in tier-one city showrooms.
China digital showers encompass electronically controlled water delivery systems incorporating thermostatic valves, digital temperature displays, and connectivity modules that regulate flow rate, temperature precision within 0.5°C, and user profiles through embedded processors. These systems serve residential and commercial installations requiring consistent water performance, water conservation compliance, and smart home integration. Thermostatic showers dominate current volume due to established installation protocols and lower retrofit complexity. Smart shower panels represent the fastest-growing category as hospitality buyers in Beijing and Shenzhen specify integrated spa-function systems. Voice control technology commands premium positioning among luxury residential developers, while Bluetooth connectivity occupies the mass-market entry tier.
MIIT smart home standards and GB water-efficiency regulations shape product design requirements, forcing manufacturers to certify flow restrictors and electromagnetic compatibility before market access. SAMR consumer protection enforcement on digital appliance warranties influences after-sales service commitments across domestic brands. Stakeholders must monitor evolving interoperability mandates between property management platforms and shower control APIs.
Market Dynamics
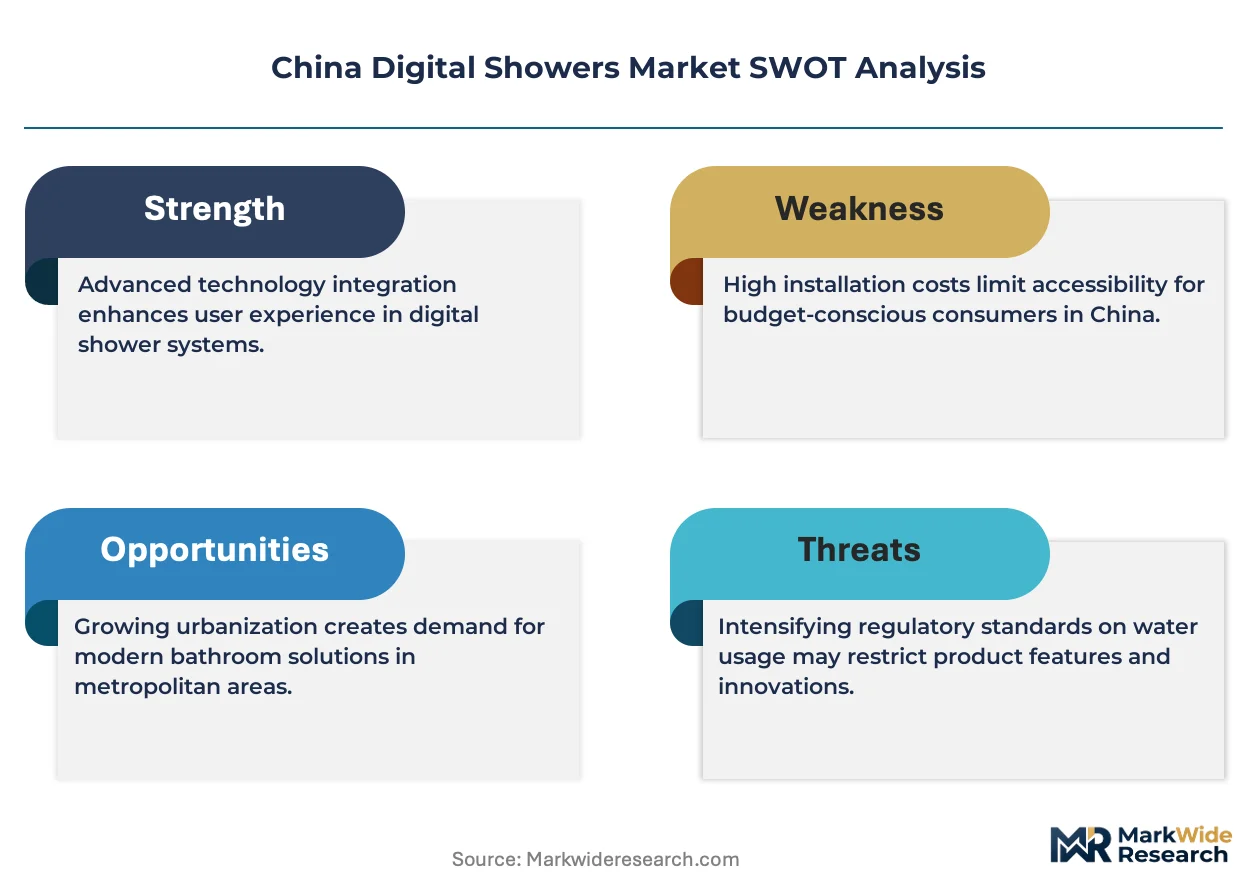
MIIT smart home interoperability mandates and GB water-efficiency standards are compressing product development cycles while elevating certification barriers for new entrants across Guangdong and Zhejiang manufacturing bases.
Growth Catalysts
- MIIT Smart Home Standards:Mandatory interoperability protocols are forcing ecosystem integration investments that lock in recurring firmware upgrade revenues for certified manufacturers.
- Luxury Hospitality Procurement:Shanghai and Shenzhen hotel developers specify voice-controlled thermostatic systems as standard amenities in premium tower construction.
- Guangzhou Premium Residential:New construction towers in first-tier city districts are embedding digital shower infrastructure during rough-in phases.
Market Restraints
- Semiconductor Import Dependency:Embedded processor and sensor module sourcing concentrates through Taiwan and South Korea foundries, exposing margin compression from currency volatility.
- Plumber Skill Scarcity:Installation complexity for digital valve systems exceeds capabilities of standard residential plumbing contractors in tier-two and tier-three cities.
- Retrofit Friction:Legacy bathroom infrastructure in Beijing and Shanghai pre-2010 housing stock lacks electrical rough-in capacity for smart panel systems.
Strategic Opportunities
- Chengdu-Chongqing Corridor:Underpenetrated luxury residential development in western China presents first-mover positioning before MIIT standards harden.
- Property Management Platform Integration:API partnerships with building automation vendors unlock recurring service revenue from commercial installations.
- Dual Carbon Compliance:MEE water conservation incentives reward flow-restrictor certification with preferential procurement in government-backed housing projects.
Industry Challenges
- Embedded Systems Talent Gap:Firmware engineering for thermostatic valve control requires specialized skill sets concentrated in Shenzhen and Hangzhou.
- SAMR Warranty Enforcement:Digital appliance consumer protection rules mandate extended service commitments that strain domestic brand balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Digital Showers Market |
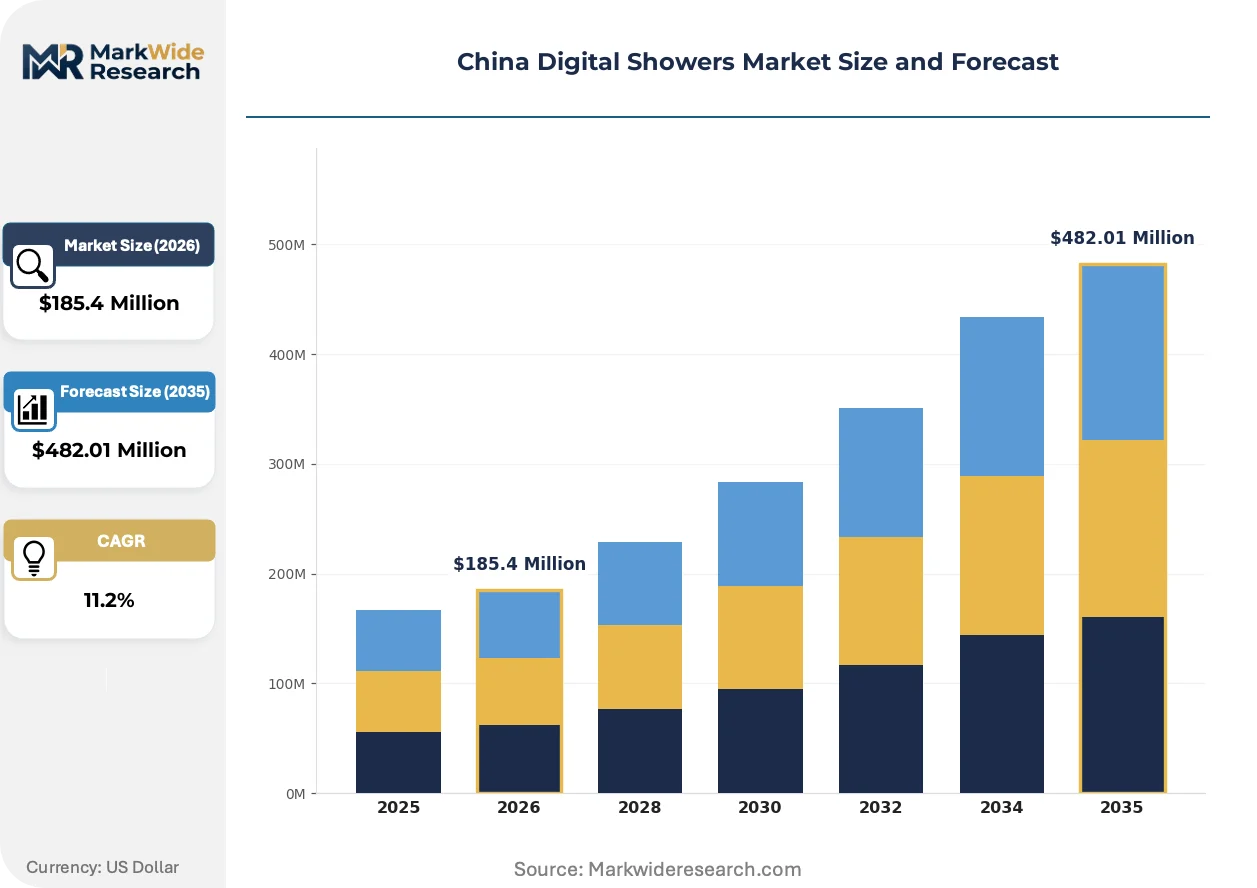
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $482.01 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostatic Showers, Smart Shower Panels, Digital Control Showers, Rain Showers Technology: Wi-Fi Enabled, Bluetooth Connectivity, Voice Control, Touchscreen Control End User: Residential, Commercial, Hospitality, Healthcare Installation: Wall-Mounted, Freestanding, Retrofit, New Construction |
| Companies Covered | Jomoo, FAAO, Kohler China, Purity, Xiamen Rainshower, Plumberstar, Gentory, HEGII, Zhejiang Qilong Sanitary Ware, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Digital Showers Market Trends and Innovations
Product architecture is migrating from standalone temperature control toward ecosystem-embedded nodes, with connectivity modules becoming the primary value determinant rather than mechanical valve precision.
Smart shower panels are expanding into hospitality specification channels as Beijing and Shenzhen luxury hotel developers bundle spa-function systems with room automation platforms. Procurement teams at international chain properties now require Bluetooth-to-building-automation gateway compatibility as a baseline qualification. This convergence is compressing standalone thermostatic unit margins while expanding software service attach rates.
GB water-efficiency regulations are mandating flow restrictor certification before market access, forcing manufacturers to redesign valve architectures around electromagnetic compatibility testing protocols. SAMR enforcement of digital appliance warranty terms is extending after-sales service commitments to seven-year coverage windows. Premium residential developers in Guangzhou are responding by specifying only MIIT-certified interoperability modules to limit liability exposure.
Buyer concentration among property management platforms is consolidating procurement authority away from individual contractors toward centralized specification teams. Tier-one city showroom channels are losing ground to direct developer relationships where digital shower systems are specified at rough-in stage. This shift is most visible in Shenzhen premium residential towers where building automation vendors now control shower system selection through bundled subsystem contracts.
China Digital Showers Market Segmentation
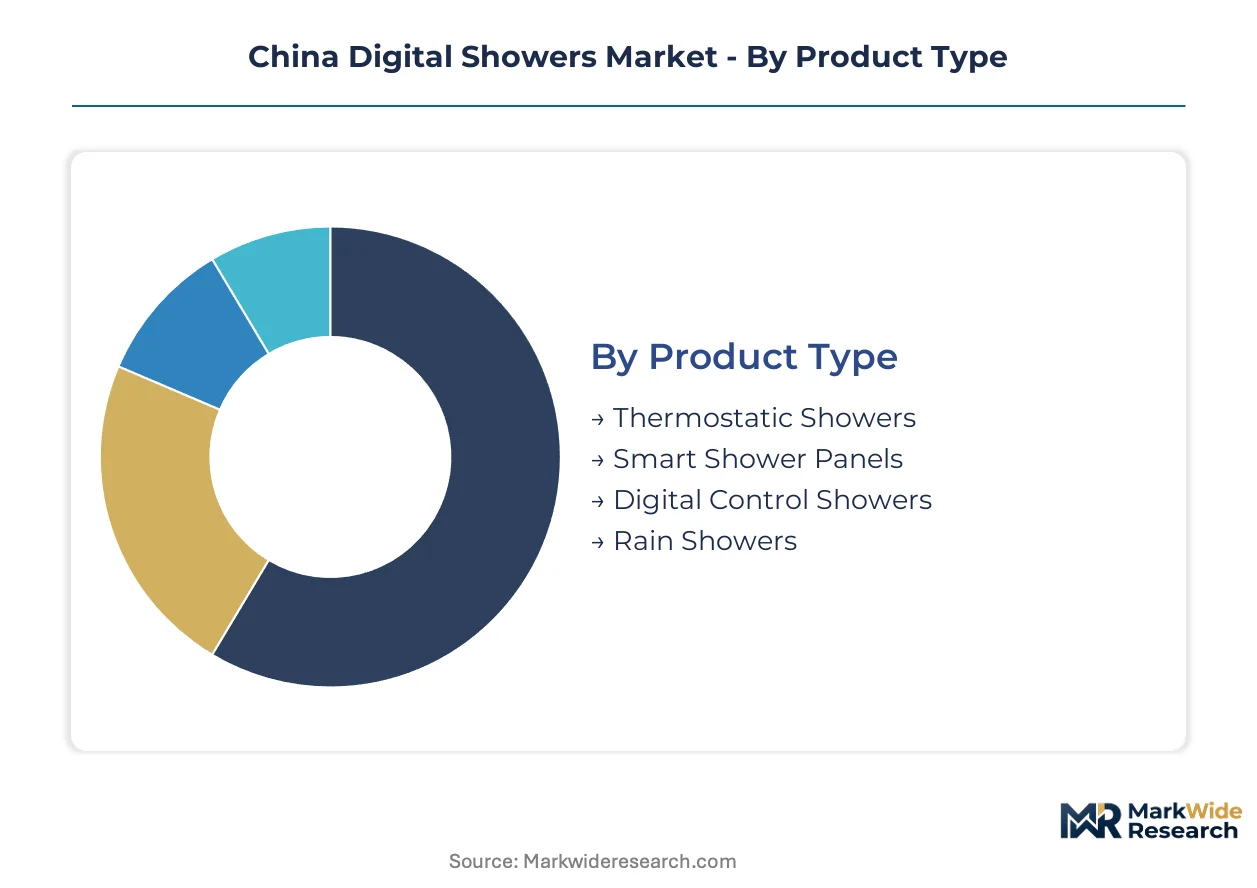
Digital shower procurement in China diverges sharply between new construction specifications and retrofit replacements, with rough-in timing determining which product architectures gain traction. MIIT certification requirements and GB water-efficiency standards apply unevenly across these segments, creating distinct compliance cost structures.
Product Type:
Buyer selection hinges on installation infrastructure readiness and ecosystem integration depth rather than price point alone.
- Thermostatic Showers:Electronically regulated valve systems maintain temperature precision within 0.5°C through embedded sensors and processor-controlled mixing. Demand concentrates in Guangzhou and Beijing premium residential towers where developers specify MIIT-certified units during rough-in phases to minimize liability exposure under SAMR warranty rules.
- Smart Shower Panels:Integrated spa-function systems bundle multiple water outlets, steam generation, and connectivity modules into single architectural units. Luxury hospitality procurement in Shanghai and Shenzhen accelerates specification of these systems as standard amenities, with building automation vendors controlling selection through bundled subsystem contracts.
- Digital Control Showers:Modular temperature and flow management systems with standalone processor units. Shenzhen manufacturing bases optimize component sourcing for these mid-tier configurations.
- Rain Showers:Overhead delivery systems with optional digital flow regulation. Guangdong production lines concentrate volume output for this established category.
Thermostatic showers lead on scale; smart shower panels lead on momentum.
Technology:
Connectivity protocol selection determines firmware upgrade revenue potential and property management platform compatibility.
- Wi-Fi Enabled:Full-stack internet connectivity supporting remote diagnostics, over-the-air updates, and building automation integration. New construction towers in Beijing embed these modules during electrical rough-in to satisfy MIIT interoperability mandates.
- Voice Control:Natural language processing interfaces requiring cloud connectivity and local microphone arrays. Luxury residential developers in Shenzhen specify these for premium positioning despite higher embedded systems engineering costs.
- Bluetooth Connectivity:Local device pairing without persistent internet dependency. Mass-market entry tier concentrates in tier-two city retrofit channels where plumber skill scarcity limits installation complexity.
- Touchscreen Control:Capacitive interface panels with programmable user profiles. Kohler China anchors R&D intensity in this segment through dedicated interface development teams.
Bluetooth connectivity dominates unit volume; voice control commands premium expansion.
End User:
Procurement authority concentration varies sharply across these segments, from individual homeowners to centralized specification teams.
- Residential:Individual household installations spanning new construction and replacement cycles. First-tier city demand concentrates in premium tower segments where rough-in timing enables full digital infrastructure.
- Hospitality:Hotel and serviced apartment specifications with centralized procurement through international chain property management platforms. Procurement teams now require Bluetooth-to-building-automation gateway compatibility as baseline qualification.
- Commercial:Office and mixed-use building installations. Property management platform integration unlocks recurring service revenue from these installations.
- Healthcare:Hospital and eldercare facility specifications with hygiene and accessibility requirements. MEE water conservation incentives reward flow-restrictor certification in government-backed healthcare construction.
Residential leads on absolute volume; hospitality leads on specification standardization.
Installation:
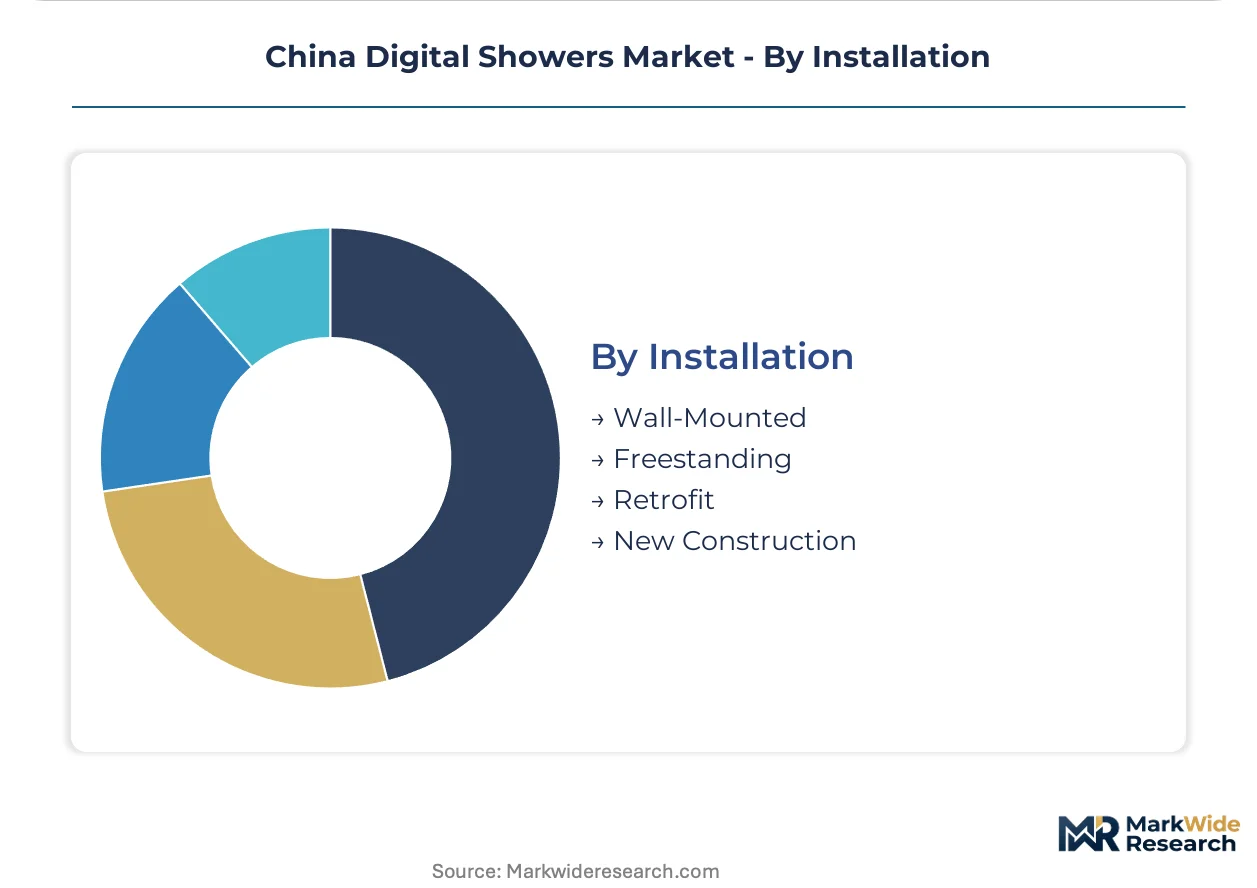
Electrical rough-in availability at construction phase determines which product tiers achieve viable economics.
- New Construction:Greenfield installations with coordinated mechanical and electrical infrastructure. Guangzhou premium residential towers embed digital shower infrastructure during rough-in phases, enabling full-featured system deployment.
- Wall-Mounted:Fixed architectural integration with concealed valve bodies. Dominates current volume due to established installation protocols and lower retrofit complexity relative to freestanding alternatives.
- Retrofit:Replacement installations in legacy housing stock. Beijing and Shanghai pre-2010 housing stock lacks electrical rough-in capacity for smart panel systems, compressing addressable market.
- Freestanding:Self-supporting units with exposed supply connections. Limited penetration outside luxury hospitality showpiece bathrooms.
New construction leads on system sophistication; retrofit constrains category expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China outpaces Japan in smart home fixture penetration, yet South Korea surpasses both in voice-control adoption rates for residential bathrooms. Germany and the United States anchor Western demand through luxury hospitality procurement channels.
China
Guangzhou and Beijing premium residential towers drive specification volume for MIIT-certified thermostatic systems. GB water-efficiency standards mandate flow restrictor certification before market access. Shenzhen manufacturing bases concentrate embedded processor sourcing for voice-control modules.
Japan
Tokyo luxury hotel chains specify spa-function shower panels with METI-compliant interoperability protocols. JIS standards govern electromagnetic compatibility testing for bathroom electronics. Osaka-based building automation vendors control subsystem selection through bundled procurement contracts.
South Korea
Seoul Capital Area developers embed voice-controlled showers in smart apartment complexes at rough-in stage. MFDS consumer protection rules extend warranty commitments for digital appliances. Busan-Ulsan corridor manufacturing clusters optimize touchscreen interface production for export markets.
Germany
Bavaria and North Rhine-Westphalia hospitality groups specify thermostatic systems with CE marking and REACH compliance for water-contact materials. EU Green Deal efficiency targets accelerate replacement cycles in Frankfurt and Munich commercial buildings. Baden-Württemberg engineering firms supply valve control firmware to Asian OEMs.
United States
California and New York Metro luxury residential towers specify Wi-Fi-enabled showers with EPA WaterSense certification. FCC electromagnetic compatibility rules shape connectivity module design for imported systems. Pacific Northwest hospitality developers require Bluetooth-to-building-automation gateway compatibility as baseline qualification.
China Digital Showers Market Competitive Landscape
Top-tier vendors anchor premium specification channels, while mid-scale domestic manufacturers compete on GB certification speed and Guangdong production scale. The vendor base stratifies across three tiers: multinational fixture brands with dedicated China R&D centers, domestic specialists with MIIT certification priority, and regional fabricators serving tier-two city retrofit demand. Two dominant competitive moves define current positioning: backward integration into embedded processor sourcing to reduce Taiwan foundry dependency, and direct developer relationships that bypass traditional showroom channels.
Within the domestic certification-priority tier, Jomoo and HEGII exemplify scale-driven positioning through Guangdong production base control. Kohler China occupies a position representing multinational R&D intensity in touchscreen interface development. These three anchors illustrate the strategic divergence between manufacturing scale, channel control, and technology specialization that characterizes competitive positioning in this market.
| Leading Market Players |
|---|
| Jomoo |
| FAAO |
| Kohler China |
| Purity |
| Xiamen Rainshower |
| Plumberstar |
| Gentory |
| HEGII |
| Zhejiang Qilong Sanitary Ware |
| Others |
Pricing and Supply Chain Analysis
MIIT certification tiering separates premium digital showers from commodity thermostatic units in both pricing power and Guangdong manufacturing configurations. SAMR-mandated warranty extensions compress margins on uncertified tiers while concentrating procurement authority among certified producers with Shenzhen embedded systems capabilities.
Pricing Analysis
Capacity additions in Guangdong are reshaping price floors for Bluetooth-enabled entry-tier units even as voice-control modules sustain premium positioning. Pricing stratifies across MIIT-certified interoperability, standard thermostatic, and basic retrofit tiers, with certification grade and after-sales bundling as primary differentiation drivers. Cost compression in the Bluetooth segment intensifies because of component standardization, while hospitality buyers show least price sensitivity. Residential retrofit channels exhibit highest price elasticity due to plumber skill scarcity limiting installation complexity tolerance.
Supply Chain Analysis
Firmware engineering talent scarcity in Shenzhen and Hangzhou constrains valve control module output despite Guangdong assembly scale. Embedded processor sourcing draws from Taiwan and South Korea foundries, with electromagnetic compatibility testing equipment and flow sensor arrays as critical inputs. Single-source vulnerability concentrates in Taiwan semiconductor foundries serving thermostatic control chip demand. Distribution runs through building automation vendors in tier-one cities and traditional showroom channels in tier-two retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in China digital showers rests on backward integration into embedded processor sourcing and premium-tier voice-control specification capture. Firmware upgrade revenue streams from MIIT-certified interoperability modules offset hardware margin compression.
For Market Incumbents: Lock in developer relationships at rough-in stage before building automation vendors consolidate procurement authority. Deepen upstream control over electromagnetic compatibility testing protocols to reduce certification cycle exposure. Threats concentrate in Taiwan foundry dependency and SAMR warranty liability expansion.
For New Entrants and Emerging Players: Voice-first interface specialization offers entry wedge against established touchscreen incumbents. White-space targets include Chengdu-Chongqing corridor luxury residential and healthcare facility flow-restrictor certification. Go-to-market through property management platform API partnerships bypasses showroom channel saturation.
For Investors and Strategic Acquirers: Consolidation pressure builds where firmware engineering talent scarcity intersects with MIIT certification backlog. Long-term viability favors vertically integrated specialists with captive embedded systems capabilities. Acquisition target archetype: mid-scale Guangdong manufacturers with GB water-efficiency certification priority. Monitor SAMR enforcement intensity on warranty term extension as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Fast-Track | Accelerates market access before interoperability mandates harden compliance windows. |
| Embedded Processor Backward Integration | Reduces Taiwan foundry exposure and stabilizes margin structure against currency volatility. |
| Property Management Platform API Partnership | Locks in recurring firmware revenue through building automation vendor channel control. |
| Chengdu-Chongqing Geographic Expansion | Captures first-mover positioning in underpenetrated western China luxury residential development. |
| Voice Control R&D Intensification | Commands premium positioning among Shenzhen luxury developers specifying spa-function systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged product managers at domestic fixture manufacturers, procurement leads at Shanghai and Shenzhen hotel developers, firmware engineers at Shenzhen embedded systems houses, and showroom channel heads in Guangzhou. Secondary validation drew from MIIT smart home standard filings, GB water-efficiency certification registries, SAMR consumer protection enforcement records, and customs trade data on semiconductor module imports. Bottom-up installation volume estimates triangulated against top-down construction pipeline data from tier-one city planning bureaus.
Historical reference periods anchored the projection horizon through verified shipment volumes and specification trends. The analytical framework modeled product type, connectivity protocol, end-user segment, installation timing, and regional city-tier dimensions. CAGRs derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated MIIT standard implementation timelines and hospitality construction pipeline visibility.
The model holds under steady MIIT enforcement and stable Taiwan semiconductor supply; deviation in trade restriction intensity or foundry allocation priorities would shift component cost assumptions. Practitioners should monitor SAMR warranty rule expansion and dual carbon incentive recalibration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Humidifier Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
Global Laptop Tables Market
Household Items
India Cookware Market
Household Items
Coffin and Cremation Urn Market
Household Items
Car Air Freshener Market
Household Items
Pocket Tissues Market
Household Items
North America Car Air Freshener Market
Household Items
Stainless Steel Water Bottles Market
Household Items
North America Glassware Market
Household Items
Plastic Bathtub Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Copper Water Bottle Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
Infrared Sauna Heaters Market
Household Items
Moving Supplies Market