
 Smart Spin Mop Market | 2026-2036
Smart Spin Mop Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Spin Mop Market Analytics
Premium-grade stainless steel centrifugal baskets is collapsing the gap between utility and durability in household cleaning tools. BISSELL leverages its established floor-care R&D infrastructure to sustain product refresh cycles across North American retail channels. Vileda anchors European demand through specialized microfiber pad formulations and tight supermarket distribution control. Shark competes aggressively on automated cleaning integration, positioning its spin mop variants within broader connected-home ecosystems.
A smart spin mop is a mechanized floor-cleaning device employing centrifugal force generated via foot-pedal or electric motor to wring excess water from a microfiber head, typically operating at drum speeds between 600 and 1,200 RPM to achieve controlled dampness for laminate, hardwood, and tile surfaces. Its primary commercial purpose is reducing physical strain and water consumption compared to conventional hand-wringing methods while improving debris capture through synthetic fiber density. Electric mop configurations currently lead unit value contribution as consumers prioritize powered wringing and battery-operated portability, while manual mop variants retain volume dominance in price-sensitive developing markets. Wi-Fi enabled technology remains nascent but captures disproportionate attention from manufacturers seeking recurring revenue through consumable subscription tie-ins.
EPA WaterSense specifications in the United States and REACH compliance requirements in Europe constrain chemical treatment options for mop heads while elevating material traceability burdens for exporters. China's GB standards for household electrical appliances and SAMR product safety certifications add parallel testing layers for motorized spin mop entrants targeting domestic distribution. Stakeholders must monitor whether automated cleaning convergence with robotic vacuum ecosystems creates platform lock-in risks or opens modular accessory opportunities for standalone spin mop specialists.
Market Dynamics
Centrifugal motor miniaturization is compressing price-performance thresholds across electric spin mop variants, forcing manual-pedal incumbents to reposition on durability claims rather than wringing efficiency.
Growth Catalysts
- EPA WaterSense mandates:Federal water-efficiency specifications in the United States are accelerating replacement cycles among drought-prone municipal water districts and their constituent households.
- Microfiber density advancements:Synthetic fiber engineering breakthroughs are extending pad lifespans and reducing consumable replenishment frequency for residential buyers.
- China's smart home penetration:Tier-1 city household automation adoption is creating pull-through demand for motorized cleaning tools compatible with connected appliance ecosystems.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack input expenses for cordless electric variants fluctuate with cobalt and nickel spot markets, compressing margin stability for motorized product lines.
- REACH chemical compliance:European ECHA restrictions on antimicrobial treatments for mop head materials are eliminating legacy preservative options and extending reformulation timelines.
- Manual mop substitution persistence:Low-cost string and flat mops retain volume dominance in price-sensitive developing markets, capping premium product addressable market expansion.
Strategic Opportunities
- India's urban household formation:Metropolitan apartment construction in Mumbai and Bangalore is generating first-time appliance purchaser cohorts with limited brand loyalty.
- Subscription consumable models:Wi-Fi enabled mop variants can anchor recurring revenue streams through automated microfiber pad replenishment programs.
- Robotic vacuum convergence:Modular docking interfaces between spin mops and autonomous floor-cleaning robots offer accessory positioning for standalone specialists.
Industry Challenges
- SAMR certification timelines:China's State Administration for Market Regulation testing protocols for motorized household appliances impose multi-month approval delays on new product introductions.
- Cross-border material traceability:GB standards compliance requires documented supply chain auditing for electrical components, complicating sourcing flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Spin Mop Market |
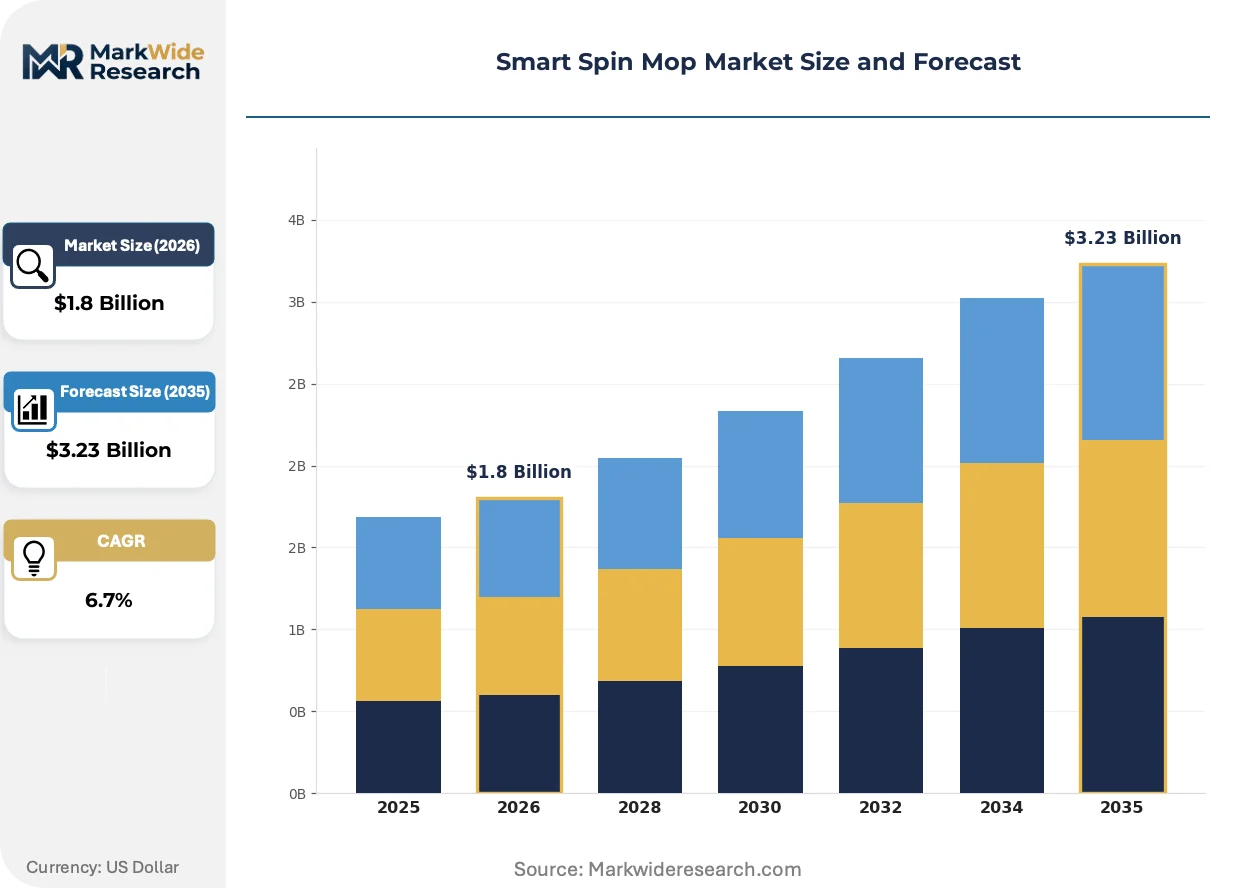
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Mop, Manual Mop, Spin Mop, Steam Mop End User: Residential, Commercial, Industrial, Hospitality Technology: Wi-Fi Enabled, Bluetooth Connectivity, Smart Sensors, Automated Cleaning Distribution Channel: Online Retail, Supermarkets, Home Improvement Stores, Direct Sales |
| Companies Covered | Blonex, iDOO, BISSELL, MOVA, AlfaBot, Shark, Vmai, Vileda, KACTOR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Spin Mop Market Evolving Landscape
Active reshaping of the smart spin mop landscape centers on component downsizing, regulatory chemistry constraints, and direct-to-consumer channel erosion of traditional retail gatekeepers.
Brushless DC motor assemblies are miniaturizing centrifugal wringing mechanisms into handheld form factors previously reserved for manual pedal systems. Apartment-dwelling millennials in urban Germany and Japan are adopting these compact electric variants at rates outpacing full-size canister replacements. The technology is miniaturizing price thresholds and enabling countertop storage solutions that expand addressable household penetration.
REACH authorization requirements for biocidal products are eliminating triclosan and silver-ion treatments from microfiber pad manufacturing processes. European manufacturers face reformulation costs and extended safety data sheet preparation timelines. Premium pad suppliers are responding with physical-mechanical antimicrobial alternatives using copper fiber weaving, though unit economics remain under pressure.
Direct-to-consumer video commerce is displacing supermarket and big-box retail as the primary discovery channel for first-time spin mop purchasers. TikTok Shop and Instagram Checkout conversion rates for cleaning appliance demonstrations exceed traditional e-commerce listings by substantial margins. This behavioral shift concentrates marketing spend on content production and influencer seeding rather than slotting fees, with visible concentration among United States and United Kingdom households aged 25-40.
Smart Spin Mop Market Segmentation
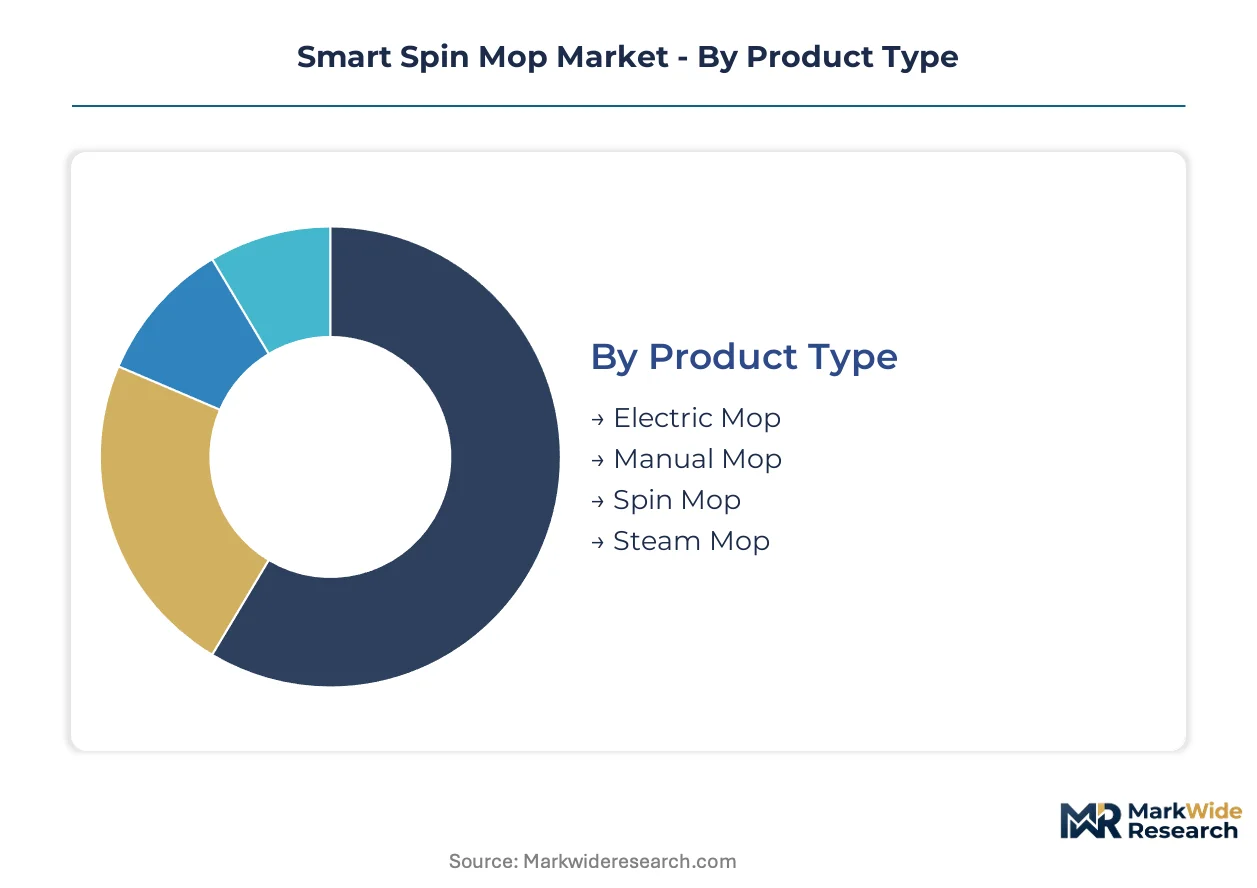
Smart spin mop manufacturers face divergent substitution pressures across product architectures, with motorized variants displacing manual systems in premium households while basic string mops retain cost-sensitive segments. Understanding these fracture lines reveals where R&D investment and channel strategy must concentrate to defend margin structure.
Product Type:
Manual pedal systems confront the steepest substitution threat as electric miniaturization collapses price barriers between powered and unpowered wringing mechanisms.
- Electric Mop:Battery-powered centrifugal motors operating at 600-1,200 RPM deliver consistent moisture control for hardwood and laminate preservation. Demand concentrates in United States and German urban apartments where countertop storage constraints favor compact form factors and consumers prioritize powered wringing over physical exertion.
- Manual Mop:Foot-pedal centrifugal baskets using mechanical leverage achieve comparable water extraction without electrical components. Volume dominance persists in India and Southeast Asian price-sensitive markets where first-time appliance purchasers prioritize acquisition cost over ergonomic convenience.
- Spin Mop:Hybrid systems combining manual wringing with motorized scrubbing heads occupy mid-tier positioning. These configurations appeal to transitional buyers upgrading from string mops but resisting premium electric pricing.
- Steam Mop:Pressurized vapor injection systems for sanitization-heavy applications in healthcare and childcare settings. Thermal componentry elevates unit economics and restricts penetration to specialty retail channels.
Manual mop configurations anchor the volume base while electric mop variants gain share at the steepest rate.
End User:
Cost tier stratification separates institutional procurement with lifecycle accounting from residential purchasing driven by immediate price visibility.
- Residential:Individual households upgrading from traditional cleaning tools represent the primary demand expansion vector. EPA WaterSense compliance and water bill reduction motivate replacement cycles in drought-affected United States municipalities.
- Commercial:Office complexes and retail facilities prioritize durability specifications and consumable standardization across multiple locations. Procurement teams negotiate volume contracts with pad replenishment provisions.
- Industrial:Manufacturing floor applications require chemical-resistant microfiber formulations and sealed motor housings for particulate-heavy environments. REACH compliance constrains antimicrobial treatment options for European facilities.
- Hospitality:Hotels and restaurants demand rapid-dry capabilities for turnaround efficiency and guest safety liability reduction. Brand standards from multinational chains drive specification consolidation.
Residential segments generate the highest absolute unit volumes while hospitality applications command the steepest premium pricing.
Technology:
Connectivity integration maturity separates experimental subscription-revenue models from proven functional improvements with immediate consumer willingness-to-pay.
- Wi-Fi Enabled:Cloud-connected mop variants supporting automated pad replenishment ordering and usage analytics. Adoption remains nascent outside early-adopter cohorts in United States and China Tier-1 cities.
- Bluetooth Connectivity:Local device pairing for mobile app control of motor speed and moisture settings. Limited functional differentiation from manual controls restricts value capture.
- Smart Sensors:Floor-type detection and automatic RPM adjustment for surface-specific cleaning. Sensor miniaturization costs compress margin structures at mid-tier price points.
- Automated Cleaning:Docking station integration with robotic vacuum ecosystems for sequential floor treatment. Shark and BISSELL positioning emphasizes ecosystem lock-in rather than standalone spin mop sales.
Sensor-based automation anchors current revenue contribution while Wi-Fi infrastructure builds subscription-recurrence optionality.
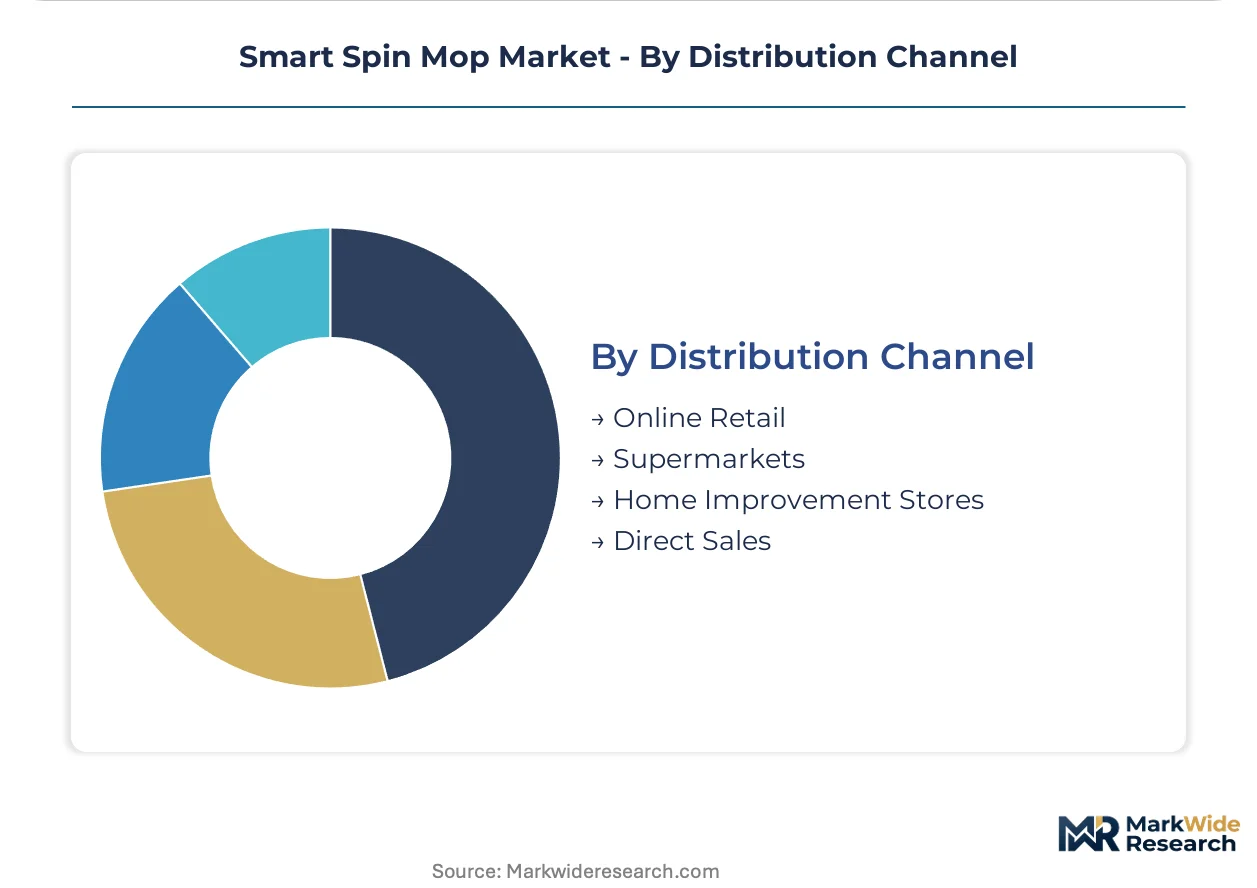
Distribution Channel:
Geographic concentration of digital commerce infrastructure determines where direct-to-consumer disintermediation outpaces traditional retail gatekeeper relationships.
- Online Retail:Amazon and domestic marketplace platforms dominate discovery and conversion for replacement purchases. TikTok Shop and Instagram Checkout demonstration content drives first-time buyer acquisition in United States and United Kingdom.
- Supermarkets:Vileda-controlled European retail networks and Walmart shelf placement sustain impulse purchases among less research-intensive shoppers. Slotting fee economics pressure standalone specialist margins.
- Home Improvement Stores:Lowe's and Home Depot professional contractor relationships channel commercial-grade specifications into residential renovation projects. In-store demonstration stations support premium electric variant trial.
- Direct Sales:Manufacturer-owned websites and televised infomercial formats retain viability for elderly demographics with established brand loyalties and limited digital commerce engagement.
Supermarket channels defend volume leadership in European markets while online retail climbs fastest in North American and Asia-Pacific penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export motorized spin mop assemblies to United States and German distribution networks, with containerized shipments routing through Ningbo and Shenzhen ports to Los Angeles and Hamburg terminals.
United States
EPA WaterSense specifications accelerate replacement cycles in California and Arizona municipal water districts. The Inflation Reduction Act's home appliance efficiency provisions subsidize electric mop purchases in drought-affected counties. Dallas-Fort Worth retail clusters concentrate inventory for Southwest distribution.
China
Tier-1 city smart home penetration drives motorized cleaning tool demand in Shanghai and Beijing apartments. SAMR certification timelines constrain new product introductions for domestic distribution. The Yangtze River Delta manufacturing belt hosts centrifugal motor assembly operations for export markets.
Germany
REACH chemical compliance eliminates legacy antimicrobial treatments from microfiber pad formulations. The EU Green Deal's circular economy requirements elevate material traceability burdens for electrical component sourcing. Bavarian engineering clusters specialize in brushless DC motor miniaturization for compact form factors.
India
Metropolitan apartment construction in Mumbai and Bangalore generates first-time appliance purchaser cohorts with limited brand loyalty. BIS certification requirements for household electrical appliances add parallel testing layers for motorized entrants. The Delhi-NCR corridor channels distribution to North Indian retail networks.
Japan
Kanto region urban density favors countertop storage solutions and compact electric variants. METI energy efficiency labeling programs differentiate premium products in Tokyo retail channels. Osaka-based trading houses coordinate Southeast Asian component sourcing for domestic assembly.
Smart Spin Mop Market Competitive Landscape
Listed leaders compete with private specialists across channel access and R&D amortization capacity. The vendor base stratifies into three tiers: multinational floor-care conglomerates with established retail infrastructure, mid-scale specialists concentrating on motorized configurations, and private-label assemblers serving price-sensitive developing markets. Dominant competitive moves include geographic expansion through distributor partnerships and portfolio diversification into adjacent cleaning appliance categories.
Among North American floor-care incumbents, BISSELL and Shark exemplify the ecosystem-integration archetype, positioning spin mop variants within broader connected-home strategies. Vileda occupies a position representing European supermarket-channel dominance through specialized distribution control. Chinese specialists including MOVA and AlfaBot represent the motorized-configuration tier, competing on component miniaturization and direct-to-consumer video commerce conversion.
| Leading Market Players |
|---|
| Blonex |
| iDOO |
| BISSELL |
| MOVA |
| AlfaBot |
| Shark |
| Vmai |
| Vileda |
| KACTOR |
| Others |
Value Network & Pricing Analysis
Centrifugal motor assembly scale in the Yangtze River Delta compresses unit economics for electric spin mop variants while simultaneously elevating price floors for manual-pedal alternatives lacking comparable volume amortization. This concentration of motorized manufacturing capacity grants Chinese specialists procurement leverage over lithium-ion cell suppliers that manual-only assemblers in Southeast Asia cannot replicate.
Pricing Analysis
Next-generation brushless DC motor configurations command 40-60% premiums over prior-generation brushed motor equivalents, while first-generation foot-pedal systems anchor economy positioning. Three-tier pricing structure across premium, standard, and economy levels segments on motor sophistication, with EPA WaterSense certification tier and stainless steel basket grade as secondary differentiation drivers. Pricing pressure stems from cobalt and nickel spot market volatility feeding battery pack input costs, compressing margin stability for cordless electric lines. Residential buyers in German and Japanese urban apartments demonstrate lowest price sensitivity, while first-time appliance purchasers in Indian metropolitan markets exhibit highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate microfiber pad sourcing as European manufacturers buffer against REACH reformulation delays, while just-in-time coordination governs centrifugal motor component flows from Ningbo and Shenzhen assembly nodes. Supply concentration rests on China for brushless DC motors and lithium-ion cells, Vietnam for injection-molded plastic housings, and Germany for precision bearing assemblies. Raw material dependencies center on cobalt and nickel for battery cathodes, copper fiber for antimicrobial pad alternatives, and ABS resin for structural components. Single-source vulnerability pervades advanced motor controller chipsets sourced from Taiwanese foundries. Distribution runs through Amazon and domestic marketplace platforms for replacement purchases, with TikTok Shop and Instagram Checkout capturing first-time buyer acquisition in United States and United Kingdom markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manual-pedal spin mop incumbents confront accelerating substitution from miniaturized electric variants, requiring defensive repositioning on durability claims and ecosystem integration to sustain relevance.
For Market Incumbents: Shield core supermarket channel relationships through exclusive microfiber pad formulation partnerships that lock in shelf placement against direct-to-consumer video commerce erosion. Vertical integration into brushless DC motor assembly, particularly through Bavarian engineering cluster partnerships, secures component supply stability amid lithium-ion cost volatility. Prioritize EPA WaterSense certification investment to capture Inflation Reduction Act subsidy flows in drought-affected United States counties.
For New Entrants and Emerging Players: Subscription consumable fulfillment gaps in Wi-Fi enabled mop variants present immediate white-space opportunity, as established manufacturers under-invest in automated pad replenishment infrastructure. Target hospitality procurement segments in Dubai and Singapore where rapid-dry specifications command premium pricing and brand loyalty remains unformed. Deploy direct-to-consumer video commerce with influencer-seeded demonstration content to bypass slotting fee barriers blocking supermarket entry.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors motorized-configuration specialists with SAMR certification capabilities and established Yangtze River Delta assembly relationships over manual-pedal legacy operators facing steepest substitution curves. Acquisition screening should prioritize targets with documented GB standards compliance and brushless DC motor miniaturization IP. Monitor lithium-ion cell cost stabilization as inflection indicator for margin expansion resumption in cordless electric segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Video Commerce Launch | TikTok Shop conversion rates exceed traditional e-commerce listings for cleaning appliance demonstrations among United States households aged 25-40. |
| Brushless DC Motor Miniaturization Investment | Bavarian engineering clusters specialize in compact form factors enabling countertop storage solutions for German and Japanese urban apartments. |
| Subscription Consumable Program Development | Wi-Fi enabled variants anchor recurring revenue through automated microfiber pad replenishment tied to usage analytics. |
| Robotic Vacuum Ecosystem Integration | Modular docking interfaces with autonomous floor-cleaning robots create accessory positioning for standalone spin mop specialists. |
| REACH-Compliant Antimicrobial Reformulation | Copper fiber weaving alternatives replace eliminated triclosan and silver-ion treatments for European microfiber pad manufacturing. |
Research Methodology
Operator-level perspectives from product development directors at floor-care conglomerates, procurement managers at European supermarket chains, and category buyers at Amazon and Walmart anchored the qualitative base. Primary fieldwork extended to plant managers at Yangtze River Delta motor assembly facilities, regulatory affairs specialists navigating SAMR and REACH compliance, and channel sales heads at home improvement retailers. Secondary validation drew from EPA WaterSense certification databases, ECHA biocidal product authorization registers, SEC 10-K filings from listed floor-care manufacturers, and customs records tracking containerized shipments through Ningbo and Shenzhen ports. Bottom-up unit shipment estimates triangulated against top-down household penetration modeling across the analysis window.
Sensitivity analysis tested forecast robustness against lithium-ion cell cost volatility scenarios and alternative smart home adoption trajectories in China Tier-1 cities. The analytical framework modeled segmentation dimensions spanning product architecture (manual, electric, hybrid, steam), end-use category (residential, commercial, industrial, hospitality), connectivity tier (Wi-Fi, Bluetooth, sensor-based, automated cleaning), and distribution channel (online retail, supermarkets, home improvement stores, direct sales). CAGRs were derived from replacement cycle frequency analysis, first-time purchaser cohort formation rates, and premium product share evolution. Industry-specific inputs included EPA WaterSense compliance penetration curves and REACH reformulation timeline assumptions.
Forecasts assume regulatory continuity in EPA WaterSense specifications, REACH chemical compliance requirements, and SAMR certification protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Drinkware Accessories Market
Household Items
Neck Pillows Market
Household Items
India Cookware Market
Household Items
Tiki Torch Market
Household Items
North America Glassware Market
Household Items
Smart Faucets Market
Household Items
Insulated Water Bottles Market
Household Items
Facial Tissue Paper Market
Household Items
Crash Mat Market
Household Items
Toilet Hygiene Products Market
Household Items
Smart Fork Market
Household Items
Alarm Clocks Market
Household Items
Japan Cookware Market
Household Items
Mexico Cookware Market
Household Items
Ironing Boards Market
Household Items
Stainless Steel Vacuum Flask Market