
 Permanent Marker Market | 2026-2036
Permanent Marker Market Size, Share, and Industry Trends Forecast 2026-2036
Permanent Marker Market Insights
Multi-pack bundling is recalibrating how educational institutions and office managers evaluate permanent marker procurement. Sharpie leverages its brand strength and retail shelf presence to dominate North American mass-market channels. Pentel anchors its position through R&D intensity in low-odor, non-toxic ink formulations for classroom environments. Sakura Color Products specializes in premium pigment systems that compete for art professional loyalty in Japan and export markets.
A permanent marker is a writing instrument containing quick-drying, solvent-based or water-based ink that bonds permanently to porous and non-porous surfaces through resin or dye fixation, typically rated for fade resistance and water impermeability. Its primary commercial purpose spans industrial labeling, artistic illustration, and everyday office documentation where legibility must endure handling and environmental exposure. Bullet tip configurations occupy the largest volume share due to universal utility across end users, while chisel tip formats generate disproportionate margin pools from art professionals and signage specialists. Alcohol-based inks lead industrial applications for substrate adhesion speed, though water-based formulations are gaining structural share where non-toxic certifications determine institutional purchasing eligibility.
EPA regulates volatile organic compound emissions from alcohol-based marker manufacturing facilities in the United States, while REACH governs chemical substance registration and restriction across European supply chains. ECHA substance evaluations are forcing reformulation of certain dye intermediates, reshaping raw material sourcing for manufacturers serving EU markets. Stakeholders must monitor evolving chemical compliance thresholds to preserve market access and anticipate which ink chemistry platforms will carry sustainable cost advantages.
Market Dynamics
REACH substance evaluations and ECHA dye intermediate restrictions are forcing wholesale reformulation of solvent-based ink chemistries, compressing margins for European-facing manufacturers while creating first-mover advantages for compliant water-based platforms.
Growth Catalysts
- Archival-grade pigment demand:Art professionals in Japan and export markets are specifying lightfast ratings above 100 years, pulling premium formulation R&D from industrial suppliers.
- China manufacturing cluster scale:Domestic production hubs in Zhejiang and Guangdong provinces are consolidating component supply, reducing lead times for export-oriented brands.
- RoHS chemical restrictions:European compliance mandates are accelerating substitution of legacy heavy-metal colorants with organic alternatives, opening specification windows for certified suppliers.
Market Restraints
- Resin feedstock volatility:Acrylic and alkyd resin prices fluctuate with petrochemical indices, squeezing gross margins on alcohol-based formulations.
- Tip assembly concentration:Precision-molded polyester fiber nib production clusters in Taiwan and South Korea, creating single-source vulnerability for mid-tier brands.
- Digital labeling substitution:Thermal transfer and laser etching systems are capturing industrial asset-tracking applications previously served by hand-marked labels.
Strategic Opportunities
- Indian educational procurement:State-level textbook distribution programs are creating institutional volume channels underserved by premium international brands.
- UV-curable ink convergence:Hybrid formulations combining instant polymerization with permanent adhesion are opening signage and packaging decoration applications.
- Refillable system design:Cartridge-based architectures are penetrating European office supply channels ahead of extended producer responsibility mandates.
Industry Challenges
- Colorant toxicology assessment capacity:REACH registration dossiers require mammalian study data that exceeds in-house capabilities of mid-sized compounders.
- Legacy equipment retrofit costs:Water-based ink transitions demand corrosion-resistant filling lines and modified drying tunnels, straining capital deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Permanent Marker Market |
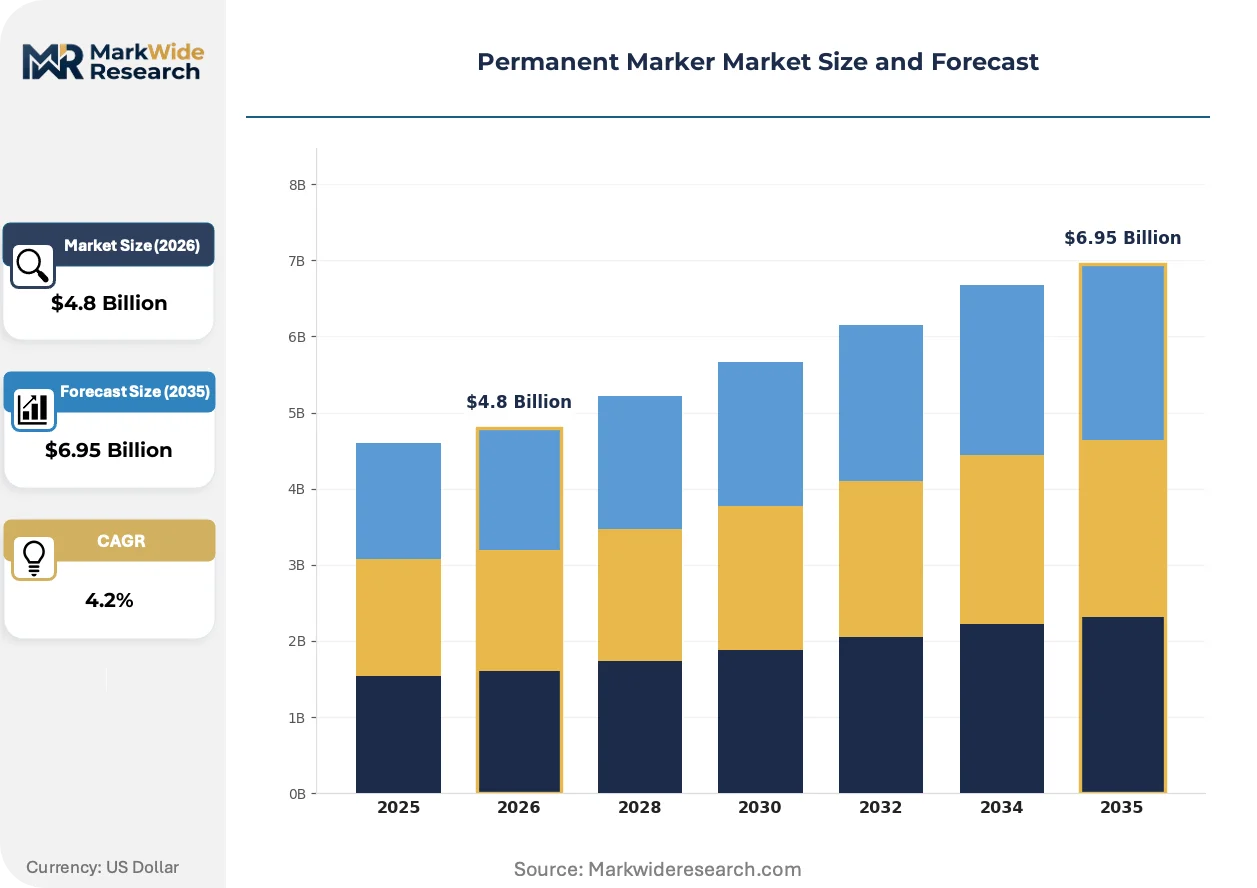
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bullet Tip, Chisel Tip, Fine Point, Broad Point Ink Type: Alcohol-Based, Water-Based, Oil-Based, Non-Toxic End User: Educational Institutions, Art Professionals, Office Supplies, Retailers Packaging Type: Single Pack, Multi-Pack, Refillable, Eco-Friendly |
| Companies Covered | Faber-Castell, Sakura Color Products, Sharpie, Pentel, Staedtler, Edding, Pilot Corporation, Artline, Zebra Pen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Permanent Marker Market Trends and Innovations
Formulation chemistry and procurement architecture are diverging simultaneously, with regulatory pressure on one axis and institutional buying consolidation on the other reshaping competitive advantage.
Water-based acrylic emulsion inks are overtaking solvent systems in classroom and healthcare environments where OSHA ventilation requirements and EPA VOC thresholds constrain alcohol-based product placement. School districts and hospital procurement offices are specifying low-odor, non-toxic certifications as mandatory bid criteria, compressing the addressable market for traditional permanent markers in these segments.
ECHA substance evaluation protocols are systematically restricting diarylide yellow and certain naphthol red dye intermediates, forcing reformulation cycles that extend 18-24 months. German and French ink compounders are accelerating partnerships with specialty chemical suppliers to secure compliant pigment alternatives ahead of sunset date enforcement.
Bundled multi-pack contracts are displacing single-unit retail purchasing in North American K-12 and higher education procurement, with district-level cooperative purchasing agreements aggregating demand across hundreds of individual schools. This concentration is compressing distributor margins while favoring manufacturers with direct institutional sales infrastructure and volume pricing flexibility.
Permanent Marker Market Segmentation
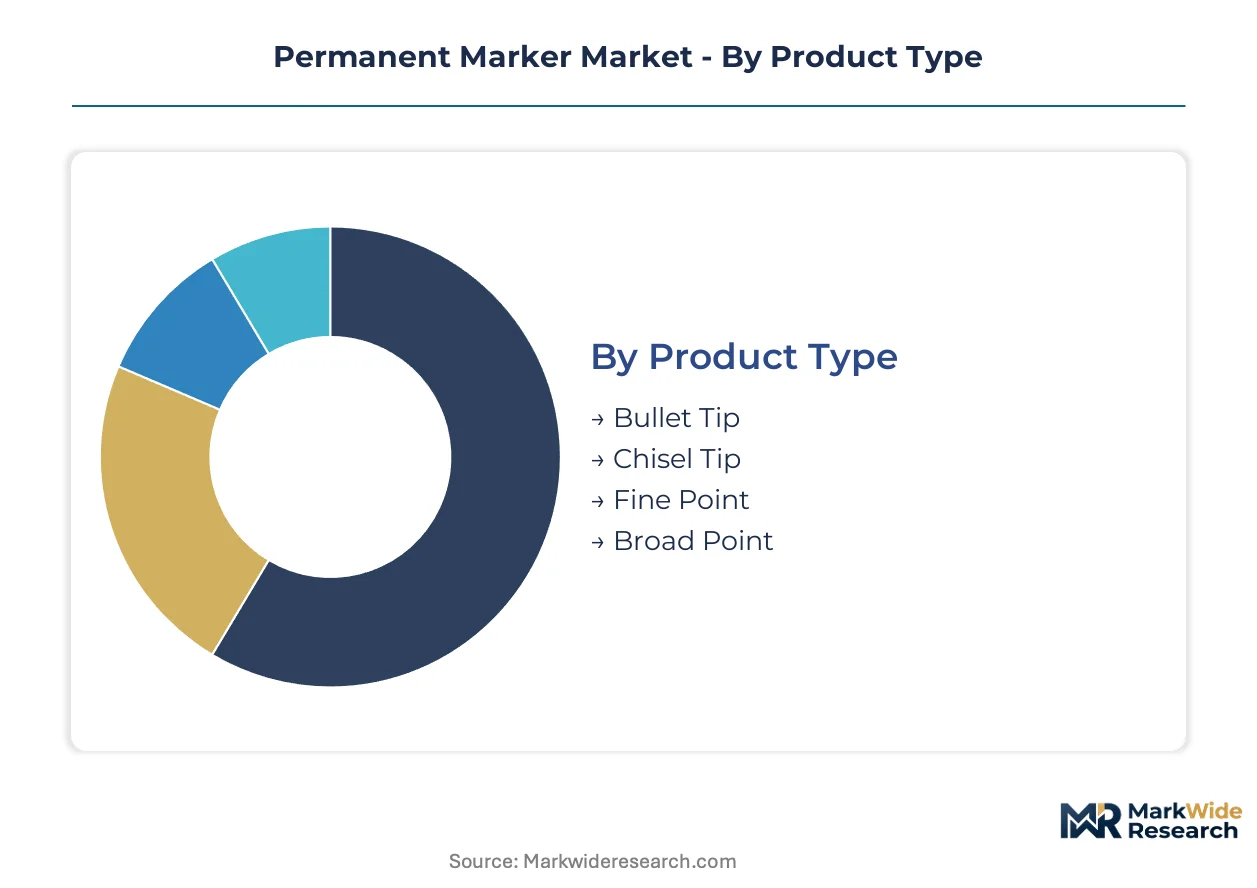
Permanent marker procurement decisions split sharply between high-volume commodity purchases and specification-driven premium selections. Understanding where volume concentrates versus where margins accumulate reveals which formulation platforms and tip geometries command sustainable competitive positions.
Product Type:
Bullet tip configurations anchor mass-market volume while chisel tip formats extract premium pricing from specialized applications.
- Bullet Tip:Cylindrical polyester fiber nibs deliver consistent line width across handwriting speeds and substrate textures. School districts in the United States specify bullet tip markers for standardized testing materials and classroom supply closets, prioritizing reliability over precision.
- Chisel Tip:Angled nib geometry enables variable stroke widths from fine lines to broad fills through rotation angle. Signage professionals in Japan and export markets specify chisel formats for hand-lettered displays, driving disproportionate margin capture despite lower unit volumes.
- Fine Point:Precision-molded tips target technical illustration and laboratory labeling where legibility at small scales determines utility.
- Broad Point:Maximum ink deposition rates serve industrial labeling and packaging decoration where visibility at distance matters.
Today's leader: Bullet Tip. Tomorrow's challenger: Chisel Tip.
Ink Type:
Regulatory pressure on volatile organic compounds is redistributing market share across solvent chemistry platforms.
- Alcohol-Based:Ethanol and isopropanol carriers enable rapid substrate penetration and permanent resin fixation on non-porous surfaces. EPA VOC emission thresholds constrain manufacturing facility locations and capacity expansions in the United States, compressing addressable growth in institutional channels.
- Water-Based:Acrylic emulsion systems achieve comparable permanence on porous substrates without OSHA ventilation requirements or EPA reporting obligations. Hospital procurement offices and school districts specify water-based formulations as mandatory bid criteria, accelerating share gains in North American and European institutional markets.
- Oil-Based:Hydrocarbon carriers serve extreme environment applications where freeze-thaw cycles or chemical exposure degrade aqueous systems.
- Non-Toxic:AP-certified formulations eliminate specific heavy metal colorants and aromatic solvents for early childhood and food-contact adjacent uses.
Alcohol-Based still commands industrial share. Water-Based climbs the fastest as compliance thresholds tighten.
End User:
Procurement consolidation patterns diverge sharply between institutional aggregators and fragmented individual purchasers.
- Educational Institutions:District-level cooperative purchasing agreements in North America aggregate demand across hundreds of individual schools, compressing distributor margins and favoring manufacturers with direct institutional sales infrastructure and volume pricing flexibility.
- Art Professionals:Individual practitioners and studio operations specify archival-grade pigment systems with lightfast ratings above 100 years, pulling premium formulation R&D from industrial suppliers and creating loyalty-based repeat purchase patterns.
- Office Supplies:Corporate procurement departments balance unit cost against storage consolidation, typically selecting multi-pack configurations over single-unit retail purchasing.
- Retailers:Private label programs and house-brand sourcing decisions concentrate manufacturing volume with suppliers capable of flexible packaging and rapid SKU rotation.
Educational Institutions drive volume concentration. Art Professionals sustain margin pools.
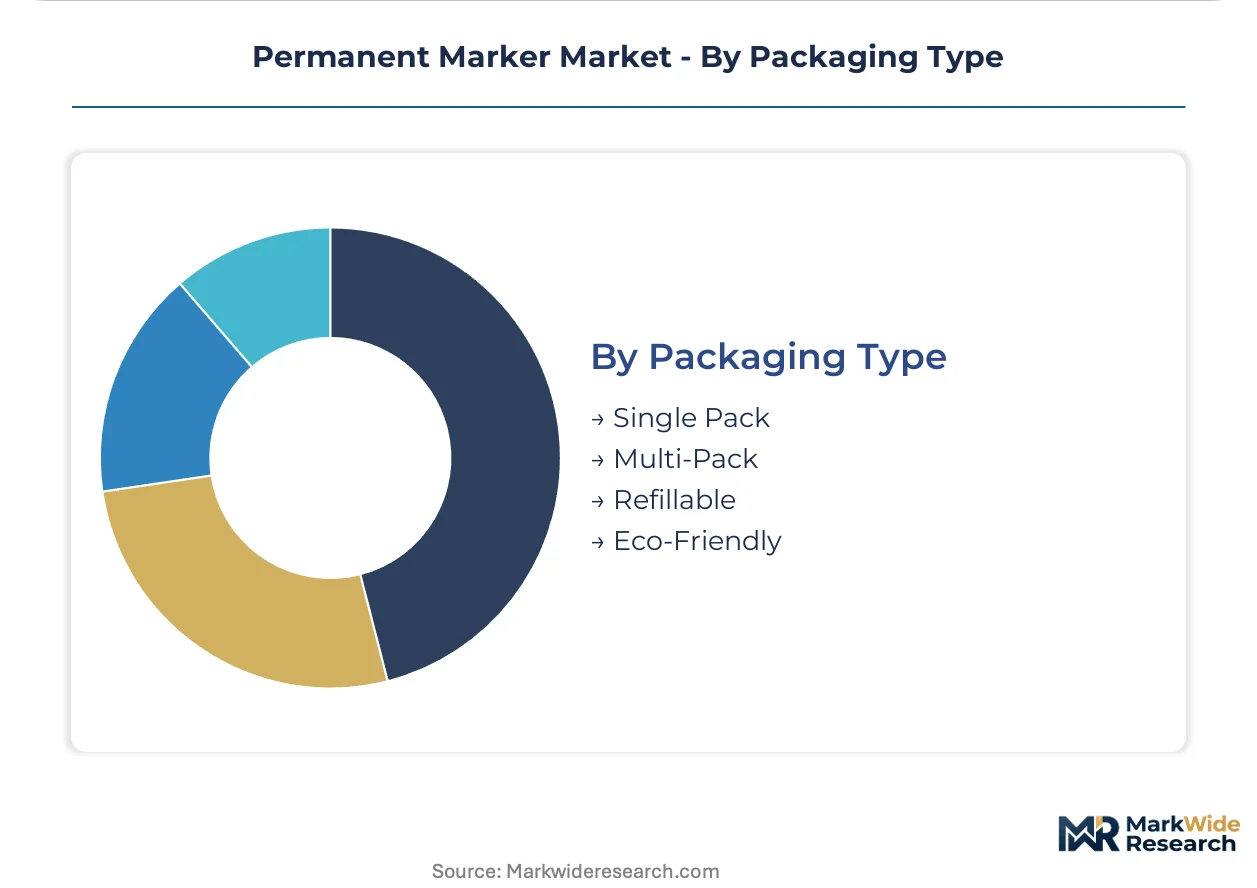
Packaging Type:
Extended producer responsibility mandates are accelerating architectural innovation in product delivery systems.
- Single Pack:Individual blister or hanging card configurations serve convenience retail and replacement purchasing where immediate need outweighs unit economics.
- Multi-Pack:Bundled configurations displace single-unit purchasing in North American K-12 and higher education procurement, with cooperative purchasing agreements aggregating demand across institutional networks.
- Refillable:Cartridge-based marker architectures penetrate European office supply channels ahead of regulatory mandates, reducing per-use material intensity while locking users into proprietary ink systems.
- Eco-Friendly:Post-consumer recycled content in barrels and caps, combined with reduced plastic packaging, addresses corporate sustainability procurement criteria without functional performance compromise.
Multi-Pack dominates current procurement. Refillable gains specification momentum in regulated markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The permanent marker industry traces its commercial origins to mid-20th century American innovation, with solvent-based formulations first achieving mass production scale in the United States before diffusing to German precision manufacturing and Japanese pigment specialization.
United States
School district cooperative purchasing agreements aggregate demand across thousands of individual institutions, favoring suppliers with direct institutional sales infrastructure. EPA VOC emission thresholds constrain alcohol-based manufacturing facility locations and capacity expansions. Manufacturing clusters in the Midwest and Southeast serve domestic distribution networks while maintaining compliance with OSHA ventilation requirements.
Germany
ECHA substance evaluation protocols systematically restrict diarylide yellow and naphthol red dye intermediates, forcing 18-24 month reformulation cycles among domestic ink compounders. REACH registration dossiers require mammalian study data that exceeds in-house capabilities of mid-sized manufacturers. Industrial chemical hubs in North Rhine-Westphalia and Baden-Württemberg accelerate partnerships with specialty pigment suppliers to secure compliant alternatives ahead of sunset date enforcement.
China
Domestic manufacturing clusters in Zhejiang and Guangdong provinces consolidate component supply and reduce lead times for export-oriented brands. The country's national environmental regulator enforces dual carbon goals that reshape chemical formulation priorities. Production hubs in the Yangtze River Delta and Pearl River Delta achieve scale economies in polyester fiber nib molding and barrel injection that underpin global cost structures.
Japan
Art professionals specify archival-grade pigment systems with lightfast ratings above 100 years, pulling premium formulation R&D from industrial suppliers. METI industrial standards govern chemical substance disclosure requirements for consumer products. Specialized manufacturing in the Kansai region around Osaka maintains precision pigment dispersion capabilities that serve domestic and export art supply channels.
India
State-level textbook distribution programs create institutional volume channels underserved by premium international brands. The Bureau of Indian Standards regulates toy and stationery safety specifications that determine import eligibility. Manufacturing corridors in Gujarat and Maharashtra develop domestic ink compounding capacity to serve educational procurement growth.
Permanent Marker Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation chemistry and tip precision dimensions, with archival-grade pigment specialists commanding pricing multiples over standard industrial labeling suppliers. The vendor base spans three strategic tiers: mass-market brands with retail shelf dominance, precision specialists with art professional loyalty, and private-label manufacturers serving distributor consolidation. Competitive moves concentrate on direct institutional sales infrastructure deployment and compliant water-based formulation transitions ahead of regulatory sunset dates.
Within the premium pigment specialist tier, Sakura Color Products and Faber-Castell occupy positions defined by archival-grade formulation credibility. Among mass-market brands with North American retail presence, Sharpie exemplifies the scale-driven archetype. Pentel sits within the institutional specification tier through low-odor, non-toxic formulation positioning. These three company structures—Japanese specialist, German heritage manufacturer, and American mass-market brand—represent the competitive archetypes reshaping procurement patterns across educational, artistic, and industrial end-use segments.
| Leading Market Players |
|---|
| Faber-Castell |
| Sakura Color Products |
| Sharpie |
| Pentel |
| Staedtler |
| Edding |
| Pilot Corporation |
| Artline |
| Zebra Pen |
| Others |
Pricing and Supply Chain Analysis
Petrochemical index volatility for acrylic and alkyd resins cascades through three distinct pricing tiers in permanent marker manufacturing, with art-grade pigment specialists capturing premium multiples while commodity producers absorb margin compression from feedstock swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement decisions, with lightfast certification grade and institutional volume scale serving as primary differentiation drivers. Pricing pressure stems from resin feedstock volatility squeezing gross margins on alcohol-based formulations. Educational procurement offices exhibit highest price sensitivity through cooperative purchasing aggregation, while art professionals demonstrate lowest sensitivity when archival-grade specifications are met.
Supply Chain Analysis
Workforce availability constraints in Zhejiang and Guangdong provinces are reshaping production economics for export-oriented manufacturers. Supply concentrates in China, Taiwan, and South Korea, with precision-molded polyester fiber nibs and acrylic resin systems as critical component dependencies. Single-source vulnerability in Taiwanese nib production clusters presents structural risk. Distribution runs through institutional procurement cooperatives and retail mass-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in water-based formulation transitions and direct institutional sales infrastructure deployment, with compliance-driven premium tier shifts offsetting commodity margin erosion.
For Market Incumbents: Extend compliant water-based platform coverage ahead of ECHA sunset dates, capturing specification windows in European educational procurement. Deepen backward integration into pigment dispersion capabilities to secure REACH-compliant colorant supply. Defend against digital labeling substitution in industrial asset-tracking by anchoring on substrate versatility and immediate application convenience. For New Entrants and Emerging Players: Begin with state-level textbook distribution programs in India, where institutional volume channels remain underserved by premium international brands. Target cartridge-based refillable architectures in European office supply ahead of extended producer responsibility mandates. Deploy direct institutional sales teams with volume pricing flexibility to penetrate cooperative purchasing agreements. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty pigment compounders possessing in-house toxicology assessment capacity for REACH registration dossiers. Long-term viability favors manufacturers bridging archival-grade art supply credibility with institutional non-toxic certification positioning. Watch ECHA substance evaluation enforcement velocity as inflection indicator for reformulation cycle intensity and first-mover advantage windows.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Formulation Transition | Captures institutional procurement share as EPA VOC thresholds and OSHA ventilation requirements constrain alcohol-based placement in schools and hospitals. |
| Direct Institutional Sales Infrastructure | Penetrates district-level cooperative purchasing agreements aggregating demand across hundreds of individual K-12 and higher education institutions. |
| Archival-Grade Pigment R&D Investment | Secures art professional loyalty through lightfast ratings above 100 years, extracting premium pricing multiples over industrial labeling suppliers. |
| Refillable System Architecture Development | Anticipates extended producer responsibility mandates in European markets while locking users into proprietary ink cartridge ecosystems. |
| REACH-Compliant Colorant Supply Partnerships | Accelerates reformulation cycles ahead of diarylide yellow and naphthol red dye intermediate sunset dates, preserving EU market access. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged ink formulation chemists, educational procurement directors, art supply retail buyers, and regulatory affairs specialists at chemical compounders. Secondary sources included ECHA substance evaluation databases, EPA VOC emission filings, customs trade records for marker exports, and institutional purchasing cooperative contract disclosures. Bottom-up volume modeling triangulated against top-down market sizing across tip geometry, ink chemistry, and end-use segments.
Rate-of-change decomposition anchored the analytical framework across the projection horizon, with segmentation dimensions spanning tip configuration, ink carrier chemistry, end-user procurement archetype, and regional regulatory cluster. CAGRs derived from regression analysis against petrochemical input indices, educational enrollment trajectories, and art supply consumption patterns. Industry-specific forecast inputs incorporated REACH substance evaluation timelines and cooperative purchasing agreement expansion rates.
Several conditions sit outside the modeled scope, including unannounced regulatory accelerations, abrupt petrochemical supply disruptions, and faster-than-anticipated digital labeling substitution in industrial applications. Forecasts reflect assumptions about reformulation cycle durations and institutional specification stickiness. Material deviation in ECHA enforcement velocity or resin feedstock volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Aluminum Cookware Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Oman Gas Hobs Market
Household Items
Toilet Brush Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
North America B2B Air Care Market
Household Items
Automatic Dishwashing Products Market
Household Items
Folded Tissues Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
Stainless Steel Vacuum Flask Market
Household Items
Porcelain Tableware Market
Household Items
Handheld Fans Market
Household Items
Silicone Soap Mold Market
Household Items
Chest Freezers Market
Household Items
Bristle Brush Market
Household Items
GCC Gas Hobs Market