
 Residential Air Purifiers Market | 2026-2036
Residential Air Purifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Air Purifiers Market Intelligence
Aftermarket filter replacement revenue is narrowing the profitability gap between initial unit sales and long-term customer value. Dyson Ltd. leverages its premium brand positioning and direct-to-consumer channels to capture this recurring revenue stream. In contrast, Coway Co. Ltd. dominates through its rental and subscription service models, particularly in the South Korean market. Honeywell International Inc. sustains its market presence through broad distribution networks in North America.
A residential air purifier is an appliance designed to remove airborne contaminants such as dust, pollen, smoke, and volatile organic compounds (VOCs) from indoor air. Its effectiveness is measured by its Clean Air Delivery Rate (CADR), which indicates the volume of filtered air delivered per minute. HEPA filters constitute the largest product type segment due to their proven efficacy against fine particulate matter. Within applications, allergy relief and smoke removal represent the primary use cases driving consumer purchasing decisions.
Product standards are shaped by a combination of voluntary and mandatory regulations, including the ENERGY STAR program managed by the US EPA and CE marking requirements in Europe. In China, GB standards dictate specific performance metrics for filtration efficiency and noise levels, influencing market access for all manufacturers. Future competitive differentiation will depend on balancing advanced filtration capabilities with energy efficiency and quiet operation to meet evolving consumer expectations.
Market Dynamics
The central force shaping the market is the business model shift from one-time hardware sales to recurring revenue streams derived from aftermarket filter replacements and service subscriptions. This redefines long-term customer value and alters competitive strategy away from unit price alone.
Growth Catalysts
- Health-Driven Household Demand:Heightened awareness of airborne allergens and pollutants, particularly in families with children or members with respiratory conditions like asthma, directly fuels unit sales for indoor air quality management.
- Stringent Indoor Air Quality Standards:Regulations like China's GB standards create specific performance benchmarks for filtration efficiency and noise, compelling manufacturers to innovate and raising the barrier to market entry.
- Smart Home Ecosystem Integration:The ability for purifiers to connect with smart home platforms and provide automated, responsive air treatment based on sensor data appeals to a growing segment of tech-forward consumers.
Market Restraints
- High Initial Unit Cost:The upfront expense for high-performance HEPA purifiers remains a significant barrier to adoption for many price-sensitive households, particularly in emerging economies.
- Operational Noise Levels:A persistent trade-off exists between a high Clean Air Delivery Rate (CADR) and quiet operation, limiting the appliance's usability in noise-sensitive environments like bedrooms or offices.
- HVAC System Substitution:Homes with advanced central HVAC systems incorporating high-MERV filtration can achieve whole-house air cleaning, reducing the perceived need for standalone room purifiers.
Strategic Opportunities
- Targeted Chemical Filtration:Developing specialized filters for volatile organic compounds (VOCs) and formaldehyde addresses growing consumer concerns that go beyond simple particulate matter removal.
- Rental and Subscription Model Expansion:Extending service-based models, proven successful in markets like South Korea, into North America and Europe offers a path to predictable, recurring revenue.
- Penetration in Underserved Regions:Markets in Southeast Asia and Latin America with rising urban pollution and growing middle-class populations represent significant untapped geographic potential.
Industry Challenges
- Navigating Regulatory Fragmentation:Manufacturers face complexity and cost in certifying products across disparate standards, including ENERGY STAR in the US, CE marking in Europe, and GB standards in China.
- Combating Counterfeit Consumables:The proliferation of unauthorized aftermarket filters erodes brand reputation, compromises device performance, and captures a significant portion of recurring revenue from legitimate suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Air Purifiers Market |
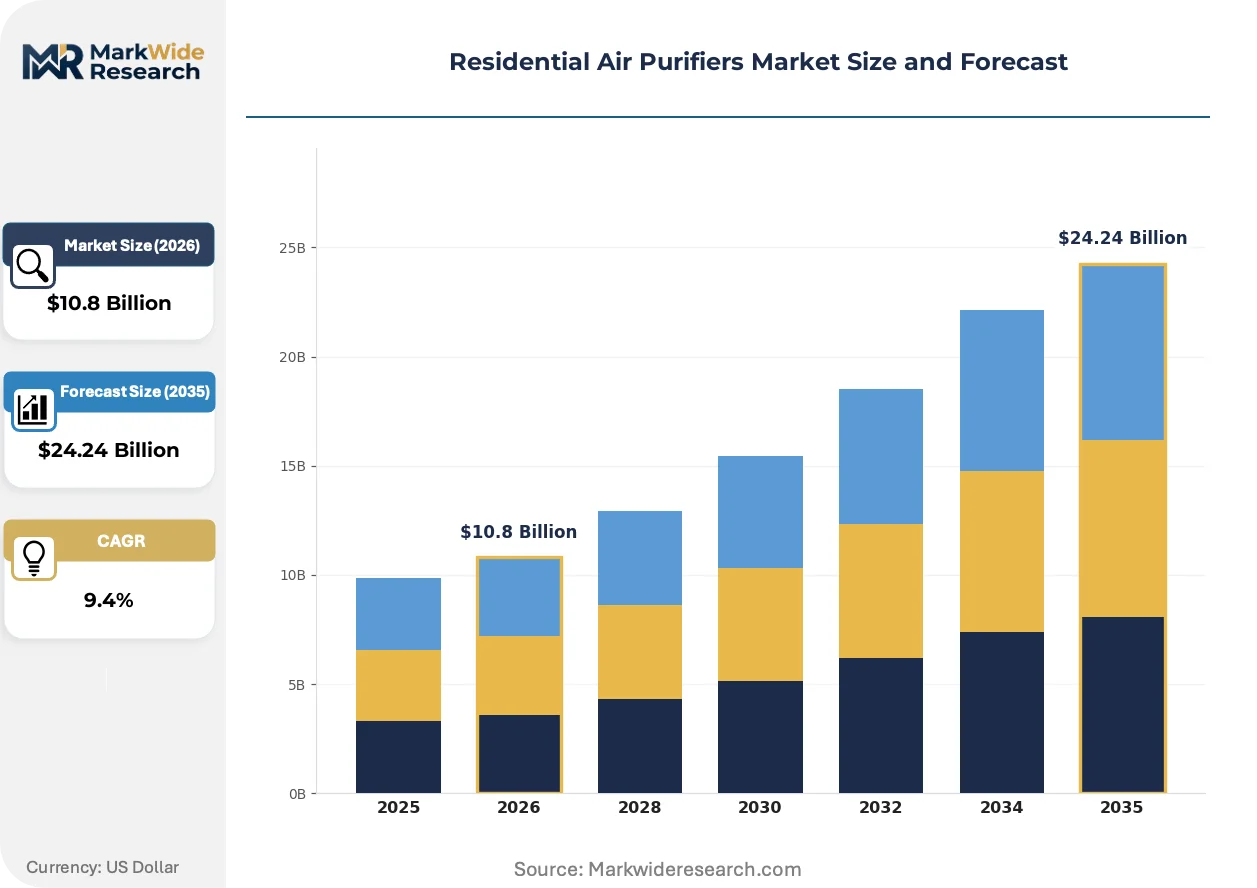
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $24.24 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Activated Carbon Filters, UV Purifiers, Ionizers, Electrostatic Precipitators Technology: Photocatalytic Oxidation, Ozone Generators, Negative Ionization, Plasma Wave, UV-C Light Application: Allergy Relief, Smoke Removal, Pet Dander Control, Mold Prevention, Odor Elimination End User: Homeowners, Renters, Senior Citizens, Children, Individuals with Respiratory Conditions |
| Companies Covered | Honeywell International Inc., Sharp Corporation, Dyson Ltd., Blueair AB, Coway Co. Ltd., LG Electronics Inc., Whirlpool Corporation, IQAir AG, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Air Purifiers Market Strategic Shifts & Innovations
An evolution from a standalone appliance into an integrated component of the connected, health-conscious home defines the market's trajectory. This shift is driven by advancements in sensor technology and data-centric features that provide users with greater control and insight into their indoor environment.
Advanced sensor arrays capable of detecting specific pollutants like PM2.5 and VOCs are becoming standard in new models. Health-conscious consumers are rapidly adopting these devices to gain real-time visibility into their indoor air quality. This integration is hybridizing the purifier from a simple filtration appliance into an active environmental data and management hub within the smart home.
The US EPA's ENERGY STAR program sets stringent criteria for energy consumption relative to performance. This regulation directly influences product design, compelling manufacturers to invest in more efficient DC motors and aerodynamic fan blades to achieve a high CADR without excessive power draw. The mid-range and premium market segments are most impacted, where certification is a key purchasing criterion.
A notable shift in consumer behavior is the preference for simplified, long-term ownership experiences over one-time transactions. This disrupts traditional retail channels reliant on single unit sales, favoring direct-to-consumer models offering automated filter replacement subscriptions. This trend is most pronounced in North America and parts of Asia, where convenience drives purchasing decisions.
Residential Air Purifiers Market Segmentation
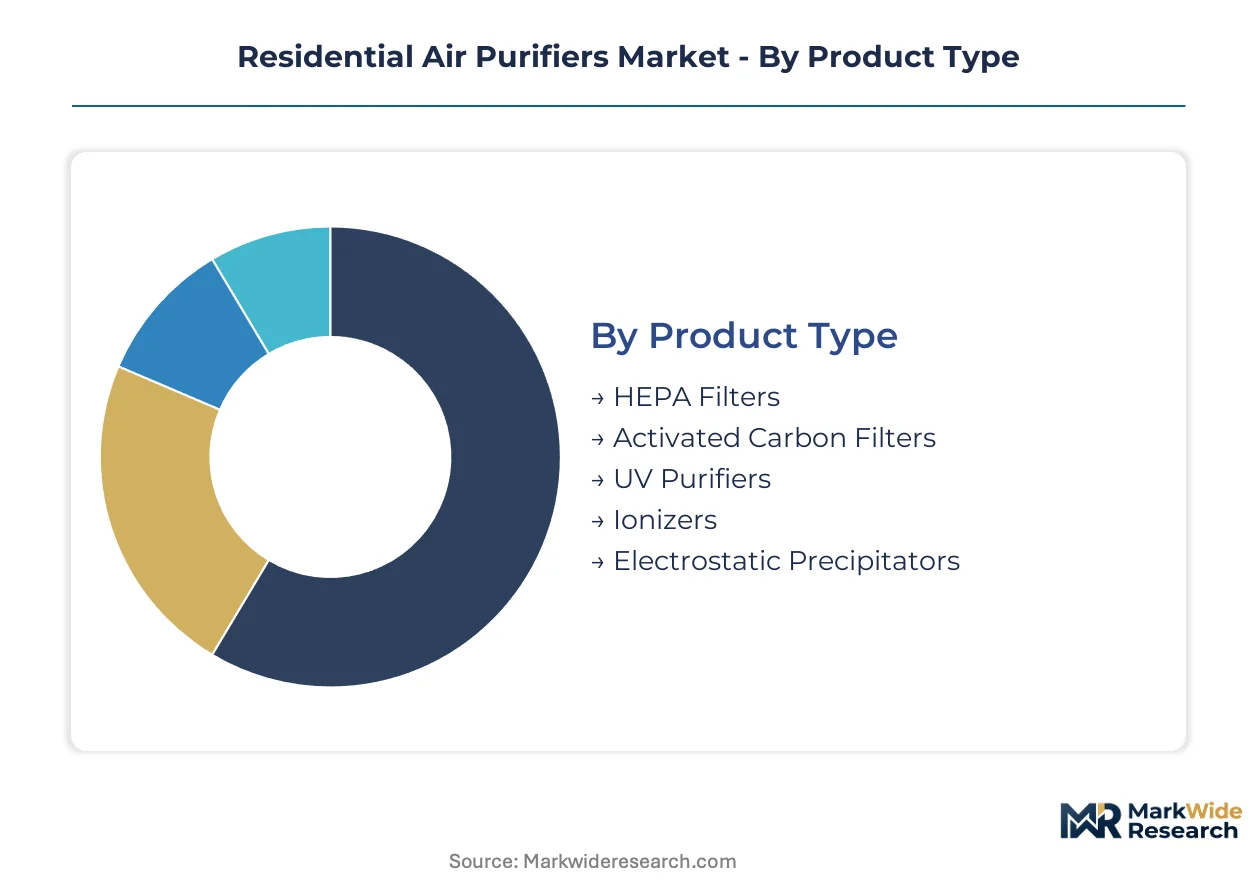
The segmentation analysis provides a granular view of the residential air purifiers market. Understanding these distinct categories helps identify specific demand drivers, technological preferences, and consumer behaviors. This detailed breakdown informs strategic product development and market penetration efforts across various consumer profiles.
Product Type:
The segmentation by product type reveals the foundational technologies employed in residential air purification.
- HEPA Filters:These filters capture 99.97% of airborne particles 0.3 microns or larger, including dust, pollen, and pet dander. Demand concentrates in households seeking comprehensive particulate matter removal, particularly in regions with high allergen counts.
- Activated Carbon Filters:Composed of highly porous carbon, these filters absorb volatile organic compounds (VOCs), odors, and gases. Urban households frequently adopt these for chemical filtration, addressing concerns beyond particulate matter.
- UV Purifiers:Ultraviolet (UV) light purifiers neutralize airborne microorganisms like viruses and bacteria through germicidal irradiation.
- Ionizers:Ionizers release negatively charged ions into the air, causing particulate matter to clump together and settle out.
- Electrostatic Precipitators:These systems use an electrostatic charge to attract and collect airborne particles on charged plates.
HEPA Filters command the established base. The steepest expansion runs through Activated Carbon Filters.
Technology:
Technological differentiation outlines the various mechanisms employed to neutralize airborne threats.
- UV-C Light:This technology utilizes short-wavelength ultraviolet light to inactivate airborne pathogens by damaging their DNA or RNA. Its application is critical in homes prioritizing germicidal air purification, especially for families with young children.
- Photocatalytic Oxidation:PCO technology uses UV light with a titanium dioxide catalyst to break down volatile organic compounds (VOCs) and odors into harmless substances. This advanced method attracts consumers concerned with chemical pollutants in sealed indoor environments.
- Ozone Generators:These devices produce ozone, a powerful oxidant that chemically reacts with pollutants to neutralize them.
- Negative Ionization:Negative ionization technology generates negative ions to bind with airborne particles, causing them to fall out of the air.
- Plasma Wave:Plasma Wave technology creates hydroxyl radicals to break down airborne contaminants at a molecular level.
UV-C Light technologies are gaining significant traction. Plasma Wave innovations are poised for future market penetration.
Application:
Consumer purchasing decisions are primarily influenced by the specific indoor air quality challenges they aim to address.
- Allergy Relief:This application targets the removal of common allergens such as pollen, dust mites, and pet dander from indoor air. Demand is particularly strong among families with children or individuals suffering from seasonal or perennial allergies.
- Smoke Removal:Purifiers designed for smoke removal effectively filter out particulate matter and gaseous pollutants from tobacco smoke, wildfires, or cooking fumes. High-pollution urban areas in countries like China and India represent significant demand for this specific application.
- Pet Dander Control:This segment focuses on filtering microscopic skin flakes and hair shed by animals, a common allergen for many pet owners.
- Mold Prevention:Air purifiers contribute to mold prevention by removing airborne mold spores, reducing their ability to colonize surfaces.
- Odor Elimination:This application targets the neutralization of unpleasant smells from cooking, pets, or household chemicals.
Allergy Relief remains a primary purchasing driver. Smoke Removal applications are seeing increased urgency in urban environments.
End User:
Demographic variations profoundly influence product features and marketing strategies.
- Individuals with Respiratory Conditions:This segment includes consumers with asthma, COPD, or other breathing difficulties who require consistently clean indoor air. Their demand fuels the market for high-CADR and medical-grade filtration systems, particularly in developed economies.
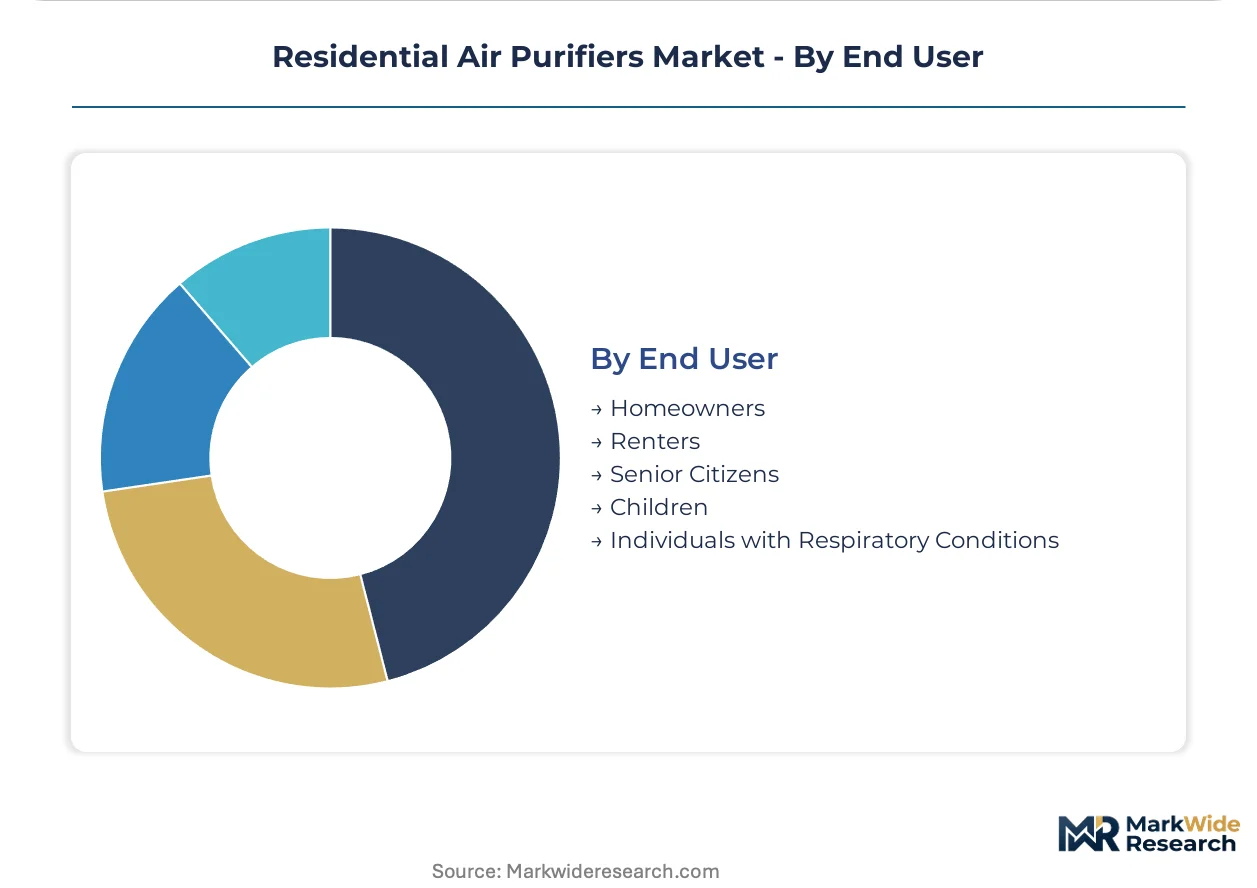
- Homeowners:Homeowners represent the largest segment, often investing in purifiers for overall household air quality improvement and long-term health benefits. This group prioritizes durability and integration with smart home ecosystems.
- Renters:Renters often seek portable and affordable air purification solutions that can be easily moved between residences.
- Senior Citizens:This demographic prioritizes ease of use, quiet operation, and reliable performance for health maintenance.
- Children:Air purifiers for children focus on protecting developing respiratory systems from pollutants and allergens in nurseries and play areas.
Homeowners constitute the largest installed base. Demand from Individuals with Respiratory Conditions represents the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for residential air purifiers vary significantly across different geographies, driven by distinct environmental concerns and market maturity levels. While some regions prioritize direct unit sales for particulate matter removal, others embrace service-based models for comprehensive indoor air quality management.
China
High levels of urban air pollution, particularly PM2.5, drive substantial demand for residential air purifiers in China. Stringent GB standards dictate specific performance metrics for filtration efficiency and noise levels, influencing product design. Major cities like Shanghai and Beijing demonstrate strong adoption of advanced HEPA and activated carbon filters for comprehensive indoor air cleaning.
India
Rising awareness of indoor air quality issues, especially in rapidly urbanizing areas, fuels demand for air purification solutions across India. National air quality initiatives encourage manufacturers to offer effective yet accessible products for household use. The Delhi-NCR region represents a significant market concentration, with consumers seeking relief from particulate pollution and allergens.
South Korea
The South Korean market exhibits a strong preference for rental and subscription models, reflecting a service-oriented consumer base. National product safety standards ensure device reliability and performance, building consumer trust. The Seoul Capital Area leads in adopting innovative purification technologies and integrated smart home solutions.
United States
Demand in the United States stems from a combination of allergy relief needs and an increasing focus on overall household wellness. The US EPA's ENERGY STAR program sets critical benchmarks for energy efficiency, influencing purchasing decisions for many consumers. Metropolitan areas across California and the Northeast corridor show high uptake of advanced HEPA purifiers and smart-enabled devices.
Germany
Health-conscious consumers in Germany prioritize energy-efficient and quiet-operating air purifiers for their homes. CE marking requirements ensure products meet rigorous European safety and environmental standards. Urban centers such as Munich and Hamburg demonstrate a preference for premium, high-performance models integrated with smart home ecosystems.
Residential Air Purifiers Market Key Industry Players
Capability concentration sits with one tier while scale advantage sits with another, creating a dynamic competitive environment within the residential air purifiers market. The market structure involves a blend of established appliance manufacturers, specialized air quality technology firms, and consumer electronics giants. Strategic archetypes include premium brand innovators, service-model specialists, and broad-market distributors. Competitive moves focus on recurring revenue streams through consumables and expanding smart home ecosystem integration.
Within the premium brand segment, Dyson Ltd. exemplifies leveraging direct-to-consumer channels and innovative design to capture high-value customers. Coway Co. Ltd. represents the successful expansion of service-based models, dominating markets with its rental and subscription offerings. Honeywell International Inc. occupies a position as a broad-market player, sustaining its presence through extensive distribution networks and established brand recognition.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Sharp Corporation |
| Dyson Ltd. |
| Blueair AB |
| Coway Co. Ltd. |
| LG Electronics Inc. |
| Whirlpool Corporation |
| IQAir AG |
| Panasonic Corporation |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes and their associated cost dynamics influence both the concentration of manufacturing supply and the subsequent price differentiation observed in the residential air purifiers market. This global freight corridor directly impacts the landed cost of finished goods and components, shaping pricing strategies across various market segments.
Pricing Analysis
Long-term contract-based arrangements for components and finished goods underpin the pricing structure for many established manufacturers. Price differentiation stems from advanced HEPA filter media quality and integrated smart home functionality. Pricing softness affects the mid-range segment due to intense competition from Asian-based manufacturers. Consumers seeking allergy relief or specific health benefits demonstrate lower price sensitivity compared to general homeowners in emerging markets.
Supply Chain Analysis
Logistics chokepoints in Southeast Asian ports present a structural risk to the residential air purifier supply chain. Geographic supply concentration for key components resides in China and Vietnam. Raw material dependencies include specialized HEPA filter media, activated carbon granules, and energy-efficient DC motors. Downstream distribution runs through broad retail networks, direct-to-consumer channels, and service-based rental models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as advanced central HVAC systems incorporating high-MERV filtration pose a significant threat to standalone purifiers.
For Market Incumbents:Harden proprietary filter media technology through continuous R&D investment, focusing on improved VOC capture and energy efficiency. Expand recurring revenue streams by offering automated filter replacement subscriptions and premium service packages to counter the threat from counterfeit consumables. Strengthen direct-to-consumer channels, leveraging brand reputation and smart home ecosystem integration to maintain competitive positioning against new entrants.
For New Entrants and Emerging Players:Specialized VOC filtration solutions for urban households represent a penetrable entry point, particularly in regions with high industrial pollution. Focus on subscription-based rental models in underserved European markets, replicating the success seen in South Korea. Differentiate through partnerships with health and wellness platforms, offering integrated indoor air quality monitoring services alongside purification hardware.
For Investors and Strategic Acquirers:Specialized filter media manufacturers with patented technologies present attractive acquisition targets for long-term viability in this market. Focus on firms with strong intellectual property in advanced filtration or sensor technology. The signal to watch is the increasing adoption rate of integrated smart home ecosystems, indicating a shift towards holistic environmental management solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Subscription Services | This initiative secures predictable, recurring revenue streams and fosters long-term customer loyalty in the residential air purifiers market. |
| Invest in VOC Filtration R&D | Developing specialized filters for volatile organic compounds addresses growing consumer health concerns beyond particulate matter removal. |
| Strengthen Direct-to-Consumer Channels | This move allows manufacturers to control brand messaging and capture higher margins from aftermarket filter sales. |
| Achieve ENERGY STAR Certification | Meeting stringent energy efficiency standards enhances product appeal for health-conscious consumers in developed economies. |
| Develop AI-Powered Sensor Arrays | Integrating advanced sensors provides real-time air quality data, transforming purifiers into smart home environmental hubs. |
Research Approach
A spread of perspectives from product development leads, procurement managers, regulatory affairs specialists, and smart home platform developers converged on the working assumptions for this analysis. Primary interviews with industry stakeholders were validated against secondary data from EPA reports, CE marking documentation, and China GB standards. This approach facilitated both bottom-up and top-down triangulation of market estimates.
Demand-supply-balance modeling formed the core of the analytical framework across the analysis window. The market was segmented by product type, technology, application, end-user, and regional pollution levels to derive granular insights. Compound annual growth rates were calculated based on historical data analysis and projected market dynamics, incorporating inputs like Clean Air Delivery Rate (CADR) standards and filter media costs.
Practitioners should monitor shifts in regulatory enforcement, raw material price volatility, or new competitive technologies for early signals that could revise forecasts. Forecasts reflect assumptions documented at the time of publication. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
Command Hooks Market
Household Items
Soap Dispenser Market
Household Items
LAMEA Robotic Pool Cleaner Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Ultrasonic Diffusers Market
Household Items
Hydralight Lanterns Market
Household Items
Global Aluminum Cookware Market
Household Items
Titanium Thermos Cup Market
Household Items
Portable Steamers Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Shoe Shine Machine Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Household Scales Market
Household Items
Drain Cleaners Market
Household Items
Global on-Premise-Laundry (OPL) Market