
 Portable Steamers Market | 2026-2036
Portable Steamers Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Steamers Market Analytics
Market Context
Appliance engineering talent shortages in Shenzhen and Dongguan is bifurcating production capacity between premium OEMs and mass-market assemblers. Philips leverages vertical integration across European distribution to sustain margin capture in the hospitality channel. Conair anchors North American retail placement through big-box partnerships, while Midea dominates domestic Chinese volume through cost-optimized manufacturing scale.
Technical Definition and Segment Structure
Portable steamers are electrically heated, pressurized water vapor devices typically operating between 800 and 1800 watts, designed for wrinkle removal, fabric sanitization, and light-duty cleaning without requiring an ironing board or fixed installation. The handheld segment leads consumer volume due to apartment-dwelling demographics and travel utility, though commercial standing units command the deepest margin pools in hospitality procurement. Online distribution channels are displacing traditional retail for residential buyers, while direct sales sustain industrial and hotel fleet contracts where specification consulting and service bundling add value.
Regulatory Environment and Outlook
UL 1008 electrical safety standards and EPA energy conservation programs in the United States, alongside CE marking and REACH substance restrictions in Europe, elevate compliance costs for cross-border suppliers while creating barriers for unqualified entrants. China's GB standards and CCC certification requirements similarly filter domestic market access, pressuring smaller assemblers toward export-only positioning. Stakeholders must monitor evolving efficiency mandates and material disclosure rules, as regulatory divergence between jurisdictions threatens to fragment product architectures and inflate SKU complexity.
Market Dynamics
Hospitality sector procurement of commercial-grade units is accelerating as hotels upgrade housekeeping equipment, while EPA energy-efficiency guidelines and UL safety certifications in the United States reshape product design requirements across the value chain.
Growth Catalysts
- EPA Energy Conservation Programs:United States federal efficiency mandates are forcing design upgrades that reduce power consumption in commercial standing units, expanding addressable market for certified OEMs.
- Apartment-Dwelling Demographics:Urban density trends in China and Western Europe are amplifying handheld segment volume as consumers prioritize space-efficient fabric care without ironing boards.
- Hotel Fleet Modernization:Post-pandemic housekeeping protocols in the hospitality sector are specifying steam sanitization capabilities, driving replacement cycles for legacy equipment.
Market Restraints
- Copper and Aluminum Input Volatility:Heating element raw material costs fluctuate with commodity markets, compressing assembler margins in mass-market handheld production.
- Shenzhen-Dongguan Talent Scarcity:Appliance engineering shortages in China's Pearl River Delta are bifurcating capacity between premium OEMs and cost-optimized assemblers.
- REACH Substance Restrictions:European chemical disclosure rules are elevating compliance costs for plastic housing and cord insulation materials, filtering smaller exporters.
Strategic Opportunities
- India BIS Certification Pathway:Formaldehyde emission standards for textile care appliances create first-mover advantage for compliant suppliers entering organized retail channels.
- Travel Retail Channel Expansion:Duty-free and airport retail placements are capturing impulse purchases from business travelers seeking compact garment care solutions.
- IoT-Enabled Fleet Management:Connected diagnostics for commercial standing units allow hospitality procurement teams to monitor utilization and schedule predictive maintenance.
Industry Challenges
- CCC Certification Timeline Compression:China's mandatory product safety approval process extends lead times for new model introductions, straining seasonal launch windows.
- Cross-Border SKU Fragmentation:Divergent voltage standards, plug configurations, and efficiency testing protocols between jurisdictions inflate inventory complexity for multi-region suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Steamers Market |
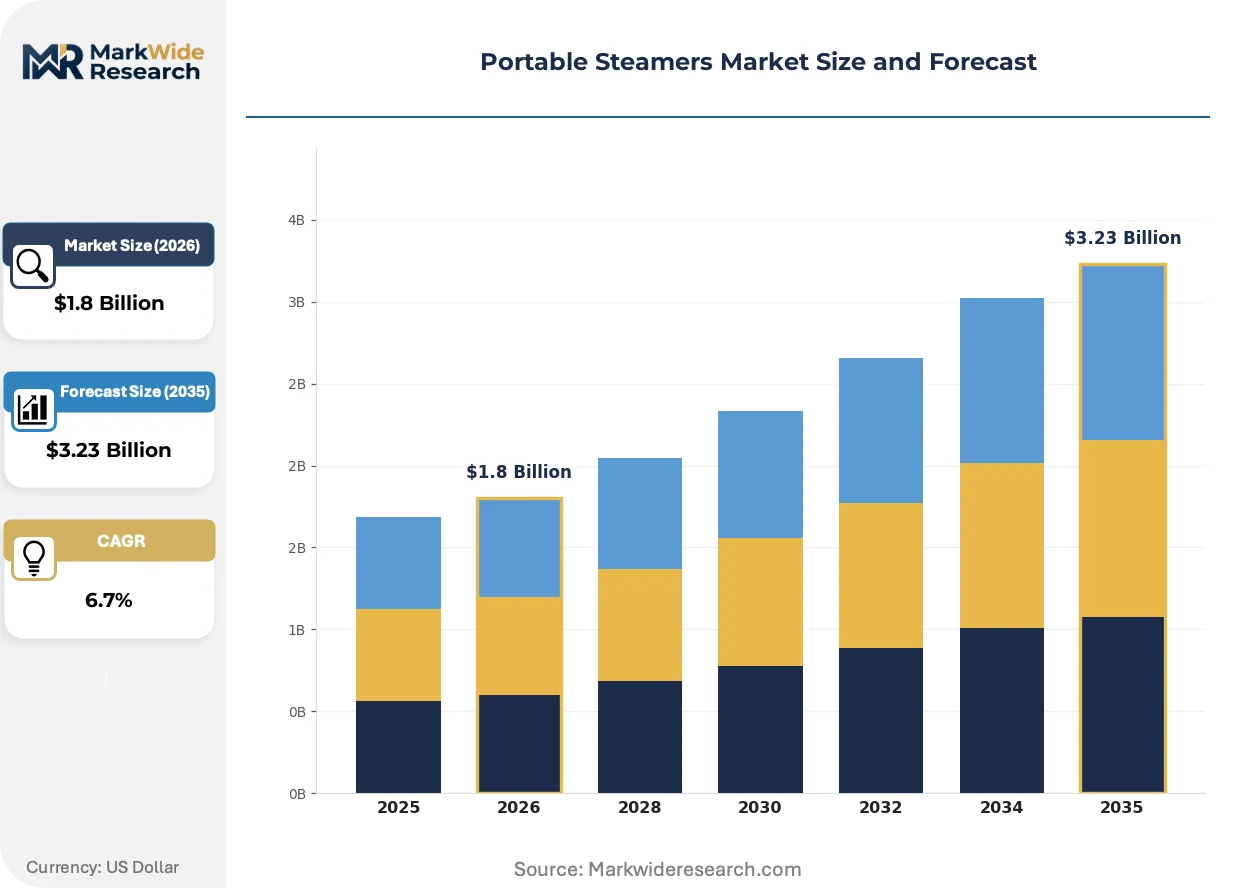
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Standing, Travel, Commercial End User: Residential, Hospitality, Retail, Industrial Power Rating: Low, Medium, High, Ultra Distribution Channel: Online, Retail Stores, Wholesalers, Direct Sales |
| Companies Covered | Philips, Rowenta, Conair, SharkNinja, BLACK+DECKER, SALAV, Midea, Panasonic, iSteam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Steamers Market Evolving Landscape
Product architecture is pivoting toward modularity and connected functionality as regulatory pressure intensifies and buyer expectations harden around service integration rather than standalone hardware.
Continuous-flow steam generation is supplanting traditional boiler-tank designs in premium handheld units. Hospitality procurement teams are specifying these systems for reduced heat-up latency during housekeeping rounds. The technology is supplanting capacity-as-a-differentiator, compressing competitive focus toward thermal efficiency metrics and warranty terms.
REACH substance restrictions and RoHS lead-free soldering mandates in Europe are accelerating material substitution in heating element assemblies. Manufacturers are reformulating circuit board compositions and cord insulation compounds to maintain CE marking eligibility. Commercial standing units face the steepest compliance burden due to higher power densities and longer duty cycles.
Direct-to-hotel sales contracts with embedded service bundling are eroding traditional distributor margins in the commercial channel. Procurement officers at mid-scale hotel chains are negotiating multi-year fleet agreements that specify uptime guarantees and rapid replacement protocols. This pattern is most visible in China's domestic hospitality market, where Midea and domestic competitors compete on service response time rather than unit price alone.
Portable Steamers Market Segmentation
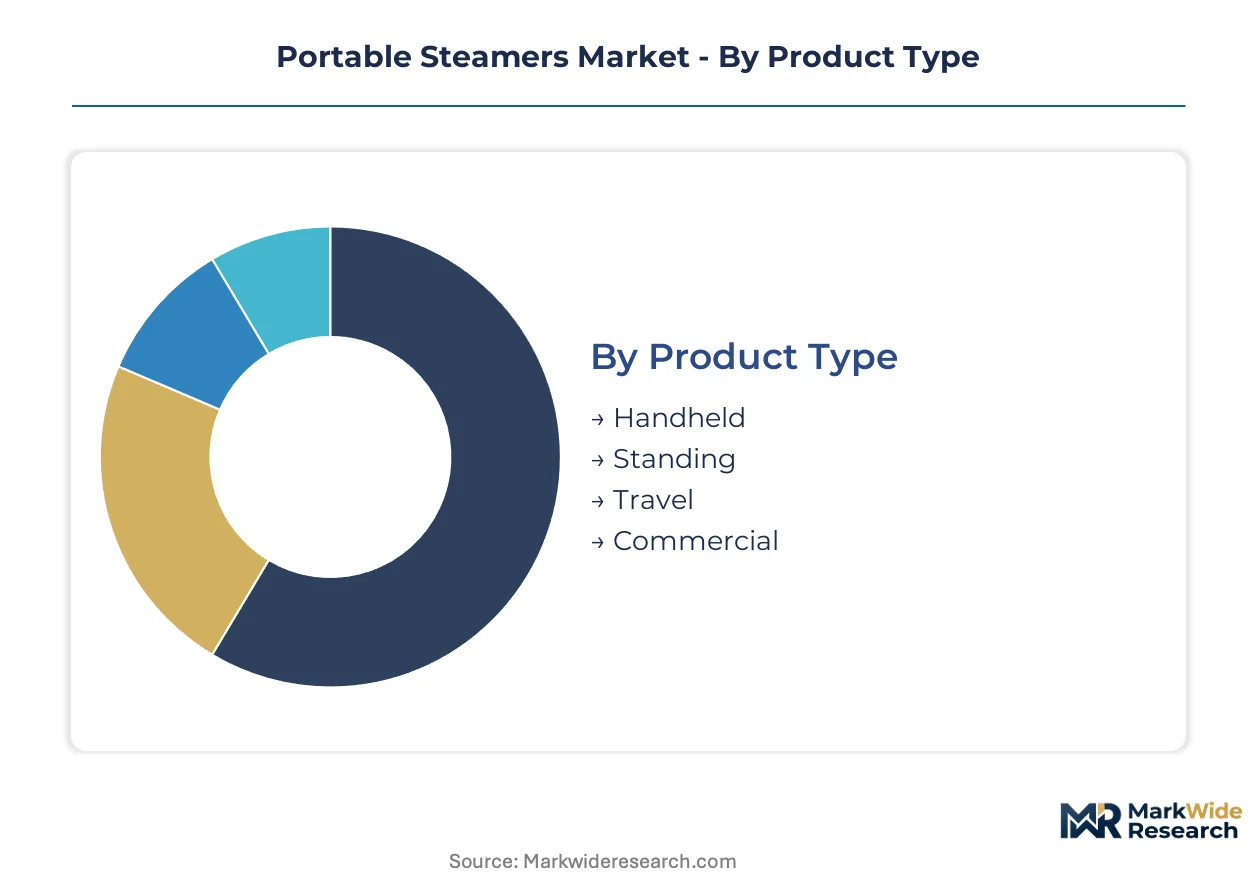
Segmentation in the portable steamers market reveals how regulatory pressure, procurement patterns, and power specifications fragment addressable demand across incompatible product architectures. Buyers in hospitality, residential, and industrial channels operate under divergent compliance regimes and performance requirements that resist unified product design.
Product Type:
UL 1008 electrical safety standards in the United States and CE marking requirements in Europe impose distinct testing protocols on each form factor, creating certification cost asymmetries between handheld and commercial formats.
- Handheld:Compact 800-1500 watt units with integrated water reservoirs target apartment dwellers in Shenzhen and Paris where storage constraints eliminate standing alternatives. EPA energy conservation programs are compressing allowable standby power consumption, forcing redesign of heating element controllers in units bound for United States retail.
- Standing:Commercial-grade systems with continuous-fill boilers and pressurized steam wands dominate hotel fleet procurement in China's domestic hospitality market. Midea and domestic OEMs compete on service response time for these installations, where uptime guarantees override unit price in contract negotiations.
- Travel:Dual-voltage 120/240V compact units with collapsible handles capture impulse purchases in airport duty-free channels.
- Commercial:High-capacity stainless-steel boiler systems with multi-wand configurations serve industrial textile finishing operations in Dongguan manufacturing clusters.
Established volume favors Handheld; emerging adoption favors Standing.
End User:
Cost tier differentiation separates specification-intensive hospitality procurement from price-sensitive residential purchasing, with margin capture varying by a factor of three across these channels.
- Residential:Individual consumers purchasing through Amazon and Tmall prioritize wattage-to-price ratios and reservoir capacity, with Chinese domestic brands capturing volume through cost-optimized manufacturing in the Pearl River Delta.
- Hospitality:Post-pandemic housekeeping protocols specifying steam sanitization capabilities are accelerating replacement cycles for legacy equipment at mid-scale hotel chains, where procurement officers negotiate multi-year fleet agreements with embedded service bundling.
- Retail:Garment care service providers in European urban centers specify commercial handheld units for on-demand wrinkle removal services.
- Industrial:Textile manufacturers in Bangladesh and Vietnam deploy high-capacity standing units for pre-shipment fabric finishing.
Margin concentration sits with Hospitality; volume scale accumulates in Residential.
Power Rating:
Application requirements and electrical infrastructure limitations in target geographies determine feasible power bands, with voltage standard divergence between 110V and 220V markets fragmenting SKU architectures.
- Low:Sub-1000 watt travel and entry-level handheld units designed for 110V North American circuits face compressed thermal output that extends garment treatment time.
- Medium:1000-1500 watt handheld systems represent the dominant residential configuration in 220V European and Chinese markets, balancing heat-up speed against circuit breaker compatibility.
- High:1500-1800 watt commercial standing units require dedicated 20-amp circuits standard in United States hotel infrastructure.
- Ultra:Above-1800 watt industrial systems with three-phase power connections serve textile finishing operations in manufacturing clusters.
Technology evolution favors Medium; infrastructure constraints limit Ultra expansion.
Distribution Channel:
Customer type and purchase urgency determine channel selection, with specification complexity driving hospitality buyers toward consultative sales while residential demand migrates online.
- Online:Amazon, Tmall, and JD.com capture residential volume through search-optimized listings and review aggregation, with return rates elevated for units failing to meet wattage claims.
- Retail Stores:Big-box partnerships with Walmart and Target sustain Conair's North American placement, where in-store demonstration drives conversion for first-time buyers.
- Wholesalers:Regional distributors in India and Southeast Asia aggregate demand from independent garment care service providers.
- Direct Sales:Manufacturer-to-hotel contracts with embedded maintenance protocols are eroding traditional distributor margins in China's domestic hospitality market.
Volume accumulation favors Online; margin protection favors Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA energy-efficiency guidelines and UL safety certifications in the United States are reshaping product design requirements, while China's GB standards and CCC certification requirements filter domestic market access. Shenzhen and Dongguan manufacturing clusters anchor production capacity for both handheld and standing formats.
United States
Hotel fleet modernization drives commercial standing unit procurement, with mid-scale chains negotiating multi-year service-bundled contracts. EPA energy conservation programs compress allowable standby power consumption in units bound for retail. Midwest distribution hubs consolidate inventory for big-box partnerships.
China
Domestic manufacturers scale capacity for export-oriented production clusters serving both handheld and standing formats. GB standards and CCC certification requirements pressure smaller assemblers toward export-only positioning. Pearl River Delta engineering talent shortages bifurcate capacity between premium OEMs and mass-market producers.
Germany
REACH substance restrictions and RoHS lead-free soldering mandates accelerate material substitution in heating element assemblies. CE marking requirements elevate compliance costs for plastic housing and cord insulation materials. Industrial textile finishing operations in Baden-Württemberg specify high-capacity standing units.
India
BIS certification pathways for formaldehyde emission standards create first-mover advantage for suppliers entering organized retail channels. Wholesalers in Maharashtra and Gujarat aggregate demand from independent garment care service providers. Organized retail expansion in Delhi-NCR and Bangalore accelerates branded unit penetration.
Japan
METI efficiency guidelines and JIS standards shape premium handheld specifications for space-constrained urban households. Kanto region electronics retailers emphasize wattage-to-price ratios and reservoir capacity in consumer purchasing decisions. Osaka-based hospitality procurement teams specify steam sanitization capabilities for post-pandemic housekeeping protocols.
Portable Steamers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the portable steamers market. Philips leverages vertical integration across European distribution to sustain margin capture in the hospitality channel. Conair anchors North American retail placement through big-box partnerships. Midea dominates domestic Chinese volume through cost-optimized manufacturing scale. Competitive moves center on service bundling for commercial contracts and direct-to-hotel sales erosion of traditional distributor margins.
Among the named participants, Philips and Conair occupy positions on the integrated leader vector, while Midea exemplifies the scale-driven domestic specialist archetype. Philips represents European-anchored premium positioning with backward integration into distribution infrastructure. Conair sits within North American retail-centric placement strategies. Midea anchors Chinese manufacturing scale with domestic hospitality market penetration. These three participants collectively illustrate the tripartite competitive structure spanning premium integration, retail dominance, and cost-optimized volume production.
| Leading Market Players |
|---|
| Philips |
| Rowenta |
| Conair |
| SharkNinja |
| BLACK+DECKER |
| SALAV |
| Midea |
| Panasonic |
| iSteam |
| Others |
Value Network & Pricing Analysis
EPA energy conservation programs and UL safety certifications in the United States simultaneously gate supplier qualification and stratify price tiers, forcing OEMs to absorb compliance costs in mass-market handheld production while capturing premiums through certified commercial standing units bound for hospitality procurement.
Pricing Analysis
Long-term fleet agreements with embedded service bundling dominate hospitality channel procurement, while spot purchasing through Amazon and Tmall characterizes residential transactions. Price differentiation separates UL-certified commercial units from uncertified mass-market alternatives, with copper and aluminum heating element volatility compressing margins in entry-tier handheld production. Pricing pressure stems from REACH substance restrictions elevating plastic housing compliance costs for European-bound exports. Residential buyers in China's Pearl River Delta exhibit highest price sensitivity, whereas hotel procurement officers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Inventory lead times extend from 12-16 weeks for CCC-certified models bound for China's domestic market, compressing seasonal launch windows for new handheld introductions. Manufacturing concentrates in China, Vietnam, and Malaysia, with Shenzhen and Dongguan clusters anchoring heating element and controller production. Raw material dependencies center on copper wire, aluminum heat exchangers, and RoHS-compliant circuit board substrates. Single-source vulnerability concentrates in precision temperature sensor supply from Japanese component houses. Distribution runs through direct-to-hotel contracts eroding traditional wholesaler margins in commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous-flow steam generation technology is disrupting capacity-as-differentiator logic, compressing competitive focus toward thermal efficiency metrics and compressing replacement cycles across hospitality fleets.
For Market Incumbents: Consolidate service response capabilities in China's domestic hospitality corridor where Midea and domestic OEMs compete on uptime guarantees rather than hardware pricing alone. Deepen backward integration into heating element production to offset copper and aluminum input volatility. Capture margin through embedded predictive maintenance protocols in IoT-enabled commercial standing units. For New Entrants and Emerging Players: BIS certification fast-track for formaldehyde emission standards creates first-mover positioning in India's organized retail expansion across Delhi-NCR and Bangalore. White-space concentrates in travel retail duty-free channels capturing impulse purchases from business travelers seeking dual-voltage compact solutions. Target garment care service providers in European urban centers through commercial handheld specifications with rapid heat-up architectures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed appliance assemblers in Shenzhen-Dongguan corridor facing engineering talent scarcity and export-only positioning pressure. Long-term viability favors OEMs with captive hospitality service contracts and vertical control over distribution infrastructure. Monitor EPA efficiency mandate tightening as inflection indicator for certified versus uncertified supplier bifurcation.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Fleet Management Integration | Connected diagnostics allow hospitality procurement teams to monitor utilization and schedule predictive maintenance across standing unit deployments. |
| REACH-Compliant Material Substitution | Reformulated circuit board compositions and cord insulation compounds maintain CE marking eligibility for European market access. |
| Direct-to-Hotel Sales Channel | Manufacturer contracts with embedded maintenance protocols erode traditional distributor margins in China's domestic hospitality market. |
| Continuous-Flow Steam Generation | Technology supplants boiler-tank designs in premium handheld units, reducing heat-up latency for housekeeping efficiency. |
| India BIS Certification Pathway | Formaldehyde emission standards compliance creates first-mover advantage for suppliers entering organized retail channels in Maharashtra and Gujarat. |
Research Methodology
The analysis maps handheld, standing, travel, and commercial product segments, each validated through procurement officers at mid-scale hotel chains, appliance engineering directors in Shenzhen-Dongguan corridor, category buyers at Amazon and Tmall, and aftermarket service heads. Primary interview data triangulates against customs records for copper and aluminum trade flows, EPA energy conservation program filings, and CCC certification registry databases. Bottom-up unit economics and top-down sector sizing converge through iterative stakeholder feedback loops.
Consistency checks validate volume and value outputs against hospitality fleet replacement cycle disclosures, residential retail audit patterns, and industrial textile finishing capacity expansion in Bangladesh and Vietnam. The analytical framework segments by product architecture, end-use channel, power rating band, and distribution pathway across the projection horizon. CAGRs derive from installed base depreciation curves, efficiency mandate adoption timelines, and urban density projections for apartment-dwelling demographics. Forecast inputs incorporate REACH substance restriction phase-in schedules and BIS certification penetration rates in Indian organized retail.
The analysis sits within stated boundaries; outcomes outside EPA efficiency mandate acceleration or CCC timeline compression would require recalibration. Forecasts reflect documented assumptions regarding copper price trajectories, hospitality sector capital expenditure continuity, and engineering talent availability in China's Pearl River Delta. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
United Kingdom Air Purifier Market
Household Items
Insulated Drinkware Market
Household Items
Gas Hobs Market
Household Items
North America Car Air Freshener Market
Household Items
Memory Foam Market
Household Items
Pet Safe Cleaners Market
Household Items
UV Sanitizer Travel Wand Market
Household Items
Desktop Air Purifier Market
Household Items
Japan Faucets Market
Household Items
Global Refrigerator Water Filters Market
Household Items
Facial Tissue Market
Household Items
Electric Tealight Candles Market
Household Items
Commercial Lawnmower Market
Household Items
Coin-Operated Laundries Market
Household Items
Soap Dispenser Market
Household Items
Electric Mop Market