
 Bristle Brush Market | 2026-2036
Bristle Brush Market Size, Share, and Industry Trends Forecast 2026-2036
Bristle Brush Market Outlook
Synthetic fiber formulation is fragmenting across performance tiers as manufacturers balance cost, durability, and regulatory compliance. Gordon Brush leverages captive nylon extrusion capabilities to control raw material quality from polymer to finished filament. Braun Brush sustains geographic dominance in North American industrial channels through dedicated distribution partnerships with automotive OEM suppliers.
A bristle brush consists of filaments secured to a handle or block, with filament diameter, density, and stiffness measured in grams per centimeter of deflection, engineered for material removal, surface finishing, or coating application. Round brushes lead professional cosmetic and dental segments where controlled product placement commands premium positioning, while flat brushes dominate architectural painting volumes where coverage efficiency drives procurement decisions. Synthetic fiber categories are displacing natural hair in food-contact cleaning applications due to allergen and shedding concerns.
EPA regulations on volatile organic compound emissions from paint application tools indirectly shape brush design standards for solvent-resistant filament bonding. FDA food contact substance notifications govern nylon and polyester bristles deployed in commercial kitchen and pharmaceutical cleaning protocols. REACH substance restrictions on certain polymer plasticizers are forcing European brush manufacturers to reformulate handle and ferrule materials. Stakeholders must monitor evolving biopolymer certifications as sustainability criteria migrate from packaging claims to filament composition requirements.
Market Dynamics
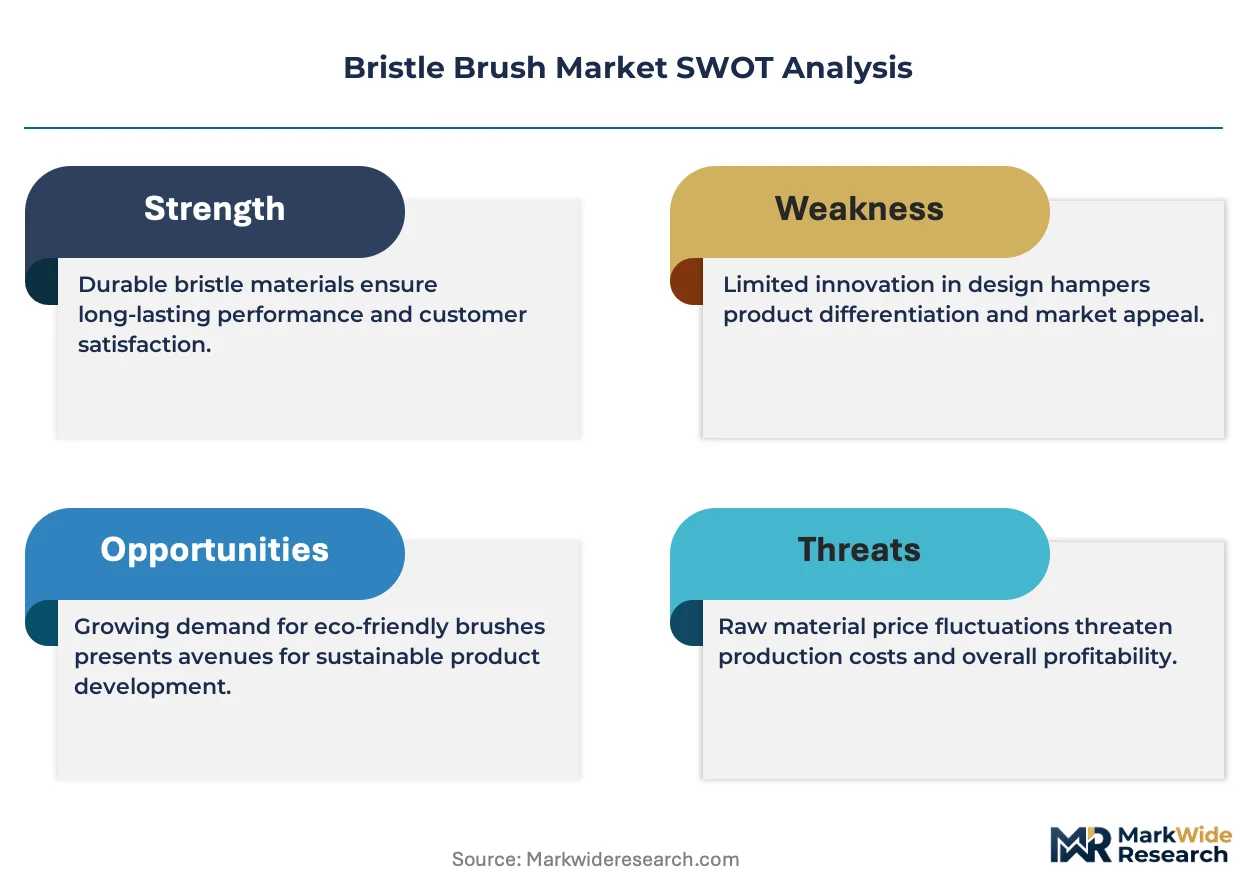
REACH substance restrictions on polymer plasticizers are forcing European brush manufacturers to reformulate handle and ferrule materials, creating a cascading quality control burden across synthetic fiber supply chains while simultaneously opening certification premiums for compliant producers.
Growth Catalysts
- Industrial hygiene protocol upgrades:Manufacturing facilities in Germany's automotive belt are mandating precision cleaning brushes for contamination-sensitive production lines, pulling demand for high-density synthetic filament brushes.
- EPA volatile organic compound regulations:Solvent-resistant filament bonding standards are reshaping brush design specifications for architectural painting contractors seeking compliance with emission controls.
- FDA food contact substance notifications:Commercial kitchen operators are replacing natural hair brushes with certified nylon and polyester alternatives to eliminate allergen and shedding risks in food-contact environments.
Market Restraints
- Petrochemical input volatility:Nylon and polyester filament producers face margin compression from polymer feedstock price swings tied to crude oil derivatives.
- Natural bristle supply concentration:Hog hair and horsehair sourcing clusters in China and Argentina create geographic vulnerability for specialty brush manufacturers serving artist and cosmetic segments.
- Biopolymer performance limitations:Plant-based filaments currently lack the stiffness durability and heat resistance required for industrial metal finishing applications.
Strategic Opportunities
- Pharmaceutical cleanroom expansion:Sterile brush demand is accelerating in South Korean and Irish drug manufacturing hubs as batch integrity standards tighten.
- EU Green Deal procurement mandates:Public sector brush purchasing in France and Italy is beginning to require verified recycled content in handle materials.
- Direct-to-facility digital channels:Industrial maintenance managers are bypassing traditional distribution to source brushes through specialized B2B platforms offering specification-matching algorithms.
Industry Challenges
- Polymer formulation expertise scarcity:Brush manufacturers struggle to hire chemists capable of balancing REACH compliance with filament performance specifications.
- Multi-certification timeline compression:Simultaneous FDA, EPA, and ISO 9001 audits are extending new product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bristle Brush Market |
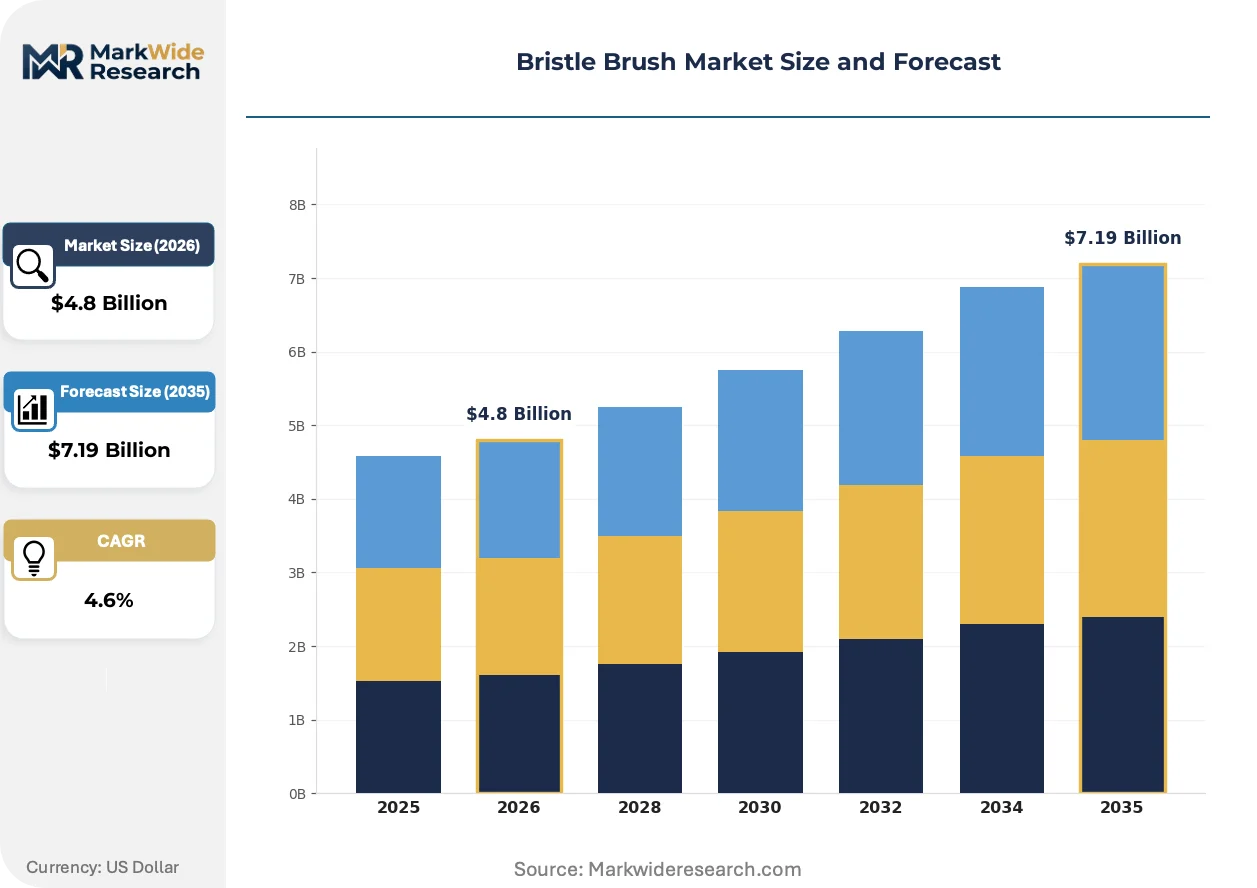
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Brush, Flat Brush, Angular Brush, Detail Brush Material: Nylon, Natural Hair, Synthetic Fiber, Boar Bristle Application: Cosmetic, Painting, Cleaning, Industrial Use End User: Professional Artists, Home Users, DIY Enthusiasts, Commercial Painters |
| Companies Covered | Brush Research Manufacturing, Braun Brush, Precision Brush, Felton Brushes, The Industrial Brush Company, Gordon Brush, Schaefer Brush, Kent Brushes, Cocker-Weber Brush Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bristle Brush Market Strategic Shifts
Captive polymer extrusion capabilities are becoming a decisive competitive moat as quality differentiation migrates from finished brush performance back to filament molecular structure and additive composition control.
Carbon fiber composite filaments are rendering obsolete traditional brass wire brushes in aerospace turbine maintenance applications. MRO facilities at Delta and Lufthansa Technik are transitioning to non-sparking, non-marring synthetic alternatives for precision component cleaning. The technology is rendering obsolete century-old metal filament dominance in high-value cleaning segments where surface integrity commands premium pricing.
REACH Annex XVII restrictions on phthalate plasticizers are compelling European handle manufacturers to validate alternative polymerizers through ECHA notification procedures. The regulatory friction is compressing supplier lists as smaller producers lack toxicology submission budgets. German brush exporters are absorbing compliance costs to maintain access to EU institutional procurement channels.
Specification-driven procurement is consolidating buyer power among industrial distributors offering digital brush configuration tools. Maintenance supervisors at Toyota and BMW Group plants now input filament diameter, density, and chemical resistance requirements into vendor platforms receiving automated compatibility scoring. This behavioral shift is most pronounced in Midwestern US manufacturing corridors where centralized MRO purchasing has eliminated spot-buying autonomy at facility level.
Bristle Brush Market Segmentation
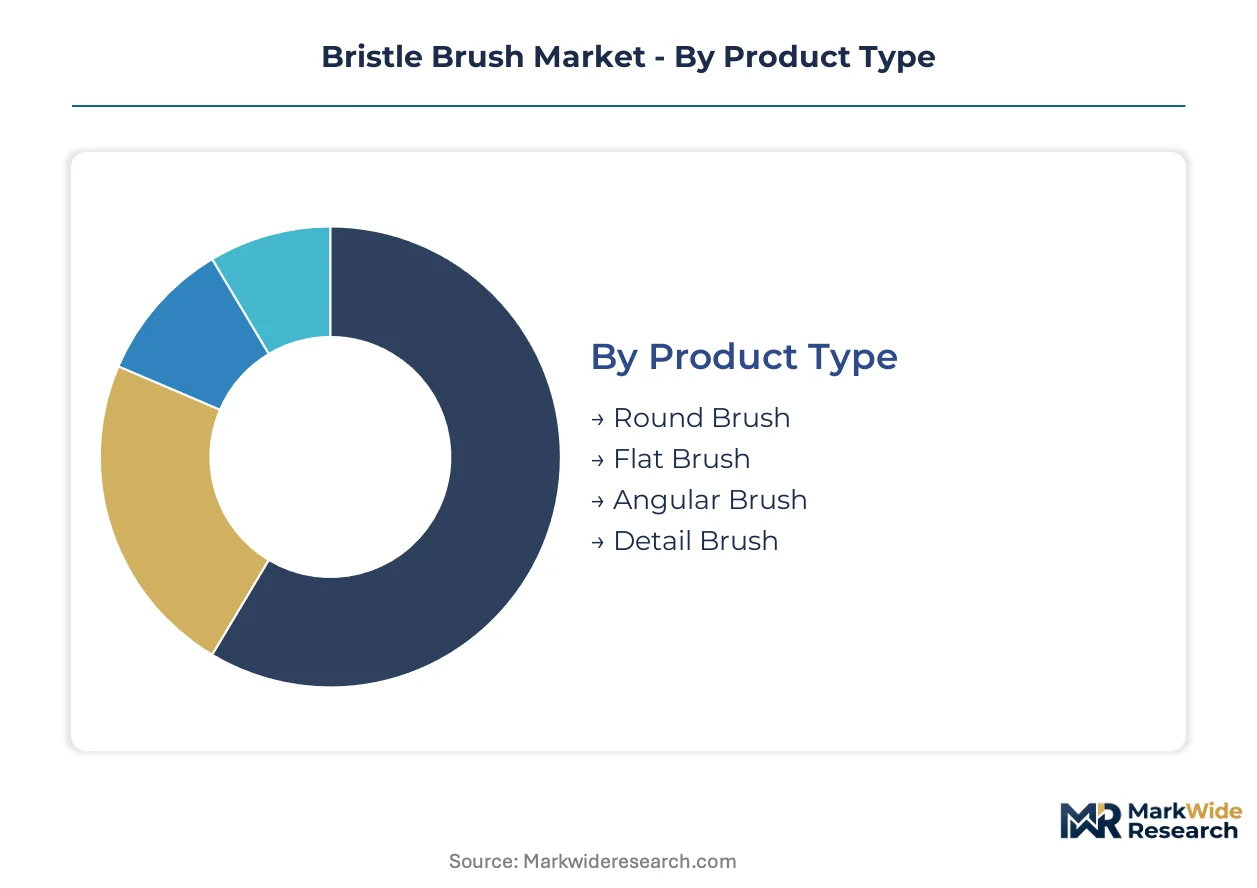
Bristle brush segmentation reveals distinct performance requirements across filament chemistry, geometry, and end-use intensity. Procurement patterns diverge sharply between specification-driven industrial buyers and price-sensitive consumer channels, creating tiered margin structures within each category.
Product Type:
Mature geometries dominate volume, while emerging form factors capture premium positioning in specialized applications.
- Round Brush:Cylindrical filament bundles taper to a domed tip, with diameter and density calibrated for controlled product deposition. Professional cosmetic and dental segments in Germany's manufacturing belt specify these for precision placement where surface integrity commands premium procurement decisions.
- Flat Brush:Rectangular filament arrays maximize coverage efficiency across broad surface areas. Architectural painting contractors in France and Italy source these in volume for solvent-based coating application where EPA emission compliance shapes bonding specification requirements.
- Angular Brush:Slanted filament edges enable corner access and trim cutting.
- Detail Brush:Ultra-fine diameters serve miniature and restoration work.
Flat brushes retain volume leadership; round brushes hold the steepest expansion curve.
Material:
Cost tiers stratify from commodity synthetics through certified natural fibers to performance-engineered polymers.
- Nylon:Polyamide filaments extruded with controlled molecular weight deliver abrasion resistance and chemical compatibility. FDA food contact notifications are accelerating replacement of natural alternatives in commercial kitchen protocols across US institutional foodservice operations.
- Synthetic Fiber:Polyester and proprietary polymer blends balance durability against REACH-compliant formulation constraints. European manufacturers are reformulating handle and ferrule materials as ECHA restrictions tighten on phthalate plasticizers in polymer systems.
- Natural Hair:Hog and horsehair retain dominance in artist and cosmetic segments despite allergen and shedding limitations.
- Boar Bristle:Keratin-based filaments serve premium cosmetic distribution through specialty retail channels.
Synthetic fiber commands volume leadership; nylon holds the steepest expansion curve.
Application:
Customer type determines specification rigor, from regulated industrial protocols to discretionary consumer selection.
- Industrial Use:High-density synthetic filament arrays engineered for contamination-sensitive production environments. Automotive OEM suppliers in Germany's precision manufacturing corridor mandate these for cleanroom maintenance where batch integrity standards eliminate tolerance variance.
- Cleaning:Chemical-resistant bonding systems withstand aggressive solvent exposure. Commercial kitchen operators in Ireland and South Korea are deploying certified nylon alternatives to eliminate natural hair allergen risks in pharmaceutical and food-contact environments.
- Cosmetic:Soft-tapered filaments prioritize skin contact comfort and product pickup efficiency.
- Painting:Architectural and fine art segments split between solvent-resistant synthetic and traditional natural fiber preferences.
Industrial use retains volume leadership; cleaning holds the steepest expansion curve.
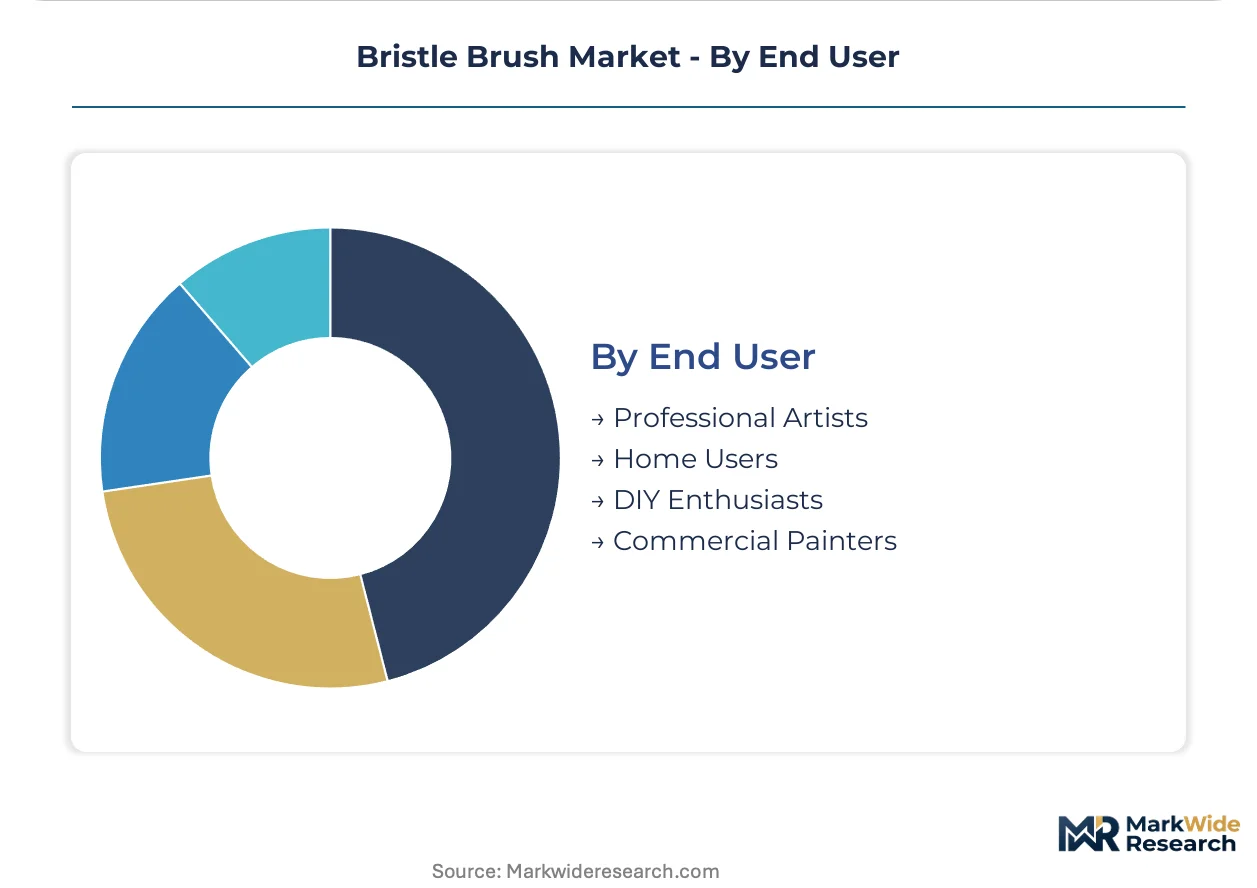
End User:
Procurement autonomy concentrates among centralized maintenance managers while fragmented DIY channels resist price discipline.
- Commercial Painters:Specification-driven buyers operate through distributor partnerships with automated compatibility scoring. Midwestern US manufacturing corridors have eliminated facility-level spot-buying autonomy through centralized MRO purchasing platforms.
- Professional Artists:Quality-sensitive segment sources through specialty retail with strong preference for natural hair performance characteristics. Supply concentration in China and Argentina creates geographic vulnerability for hog hair and horsehair procurement.
- Home Users:Price-elastic demand flows through mass retail and digital marketplaces.
- DIY Enthusiasts:Hobbyist segment balances cost sensitivity against project-specific performance requirements.
Commercial painters retain volume leadership; professional artists hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German brush manufacturers export precision industrial filament products to automotive production facilities across the US Midwest and South Korean pharmaceutical hubs, establishing a trans-Atlantic and trans-Pacific trade corridor anchored by REACH-compliant synthetic fiber formulations.
Germany
Automotive OEM suppliers in Bavaria and Baden-Württemberg mandate high-density synthetic filament brushes for contamination-sensitive production lines, pulling demand through centralized MRO procurement platforms. ECHA REACH Annex XVII restrictions on phthalate plasticizers are compelling handle manufacturers in Stuttgart's manufacturing belt to reformulate polymer systems and validate alternatives through notification procedures.
United States
Commercial painting contractors across the Midwest are sourcing solvent-resistant filament bonding systems to comply with EPA volatile organic compound emission controls on architectural coating application. FDA food contact substance notifications are accelerating nylon brush deployment in institutional foodservice operations from Chicago to Dallas, eliminating natural hair allergen risks in commercial kitchen protocols.
South Korea
Sterile brush demand is accelerating in Seoul Capital Area and Busan-Ulsan pharmaceutical manufacturing hubs as MFDS batch integrity standards tighten for cleanroom maintenance. Drug manufacturers in Songdo and Incheon are specifying certified synthetic filament arrays for precision component cleaning where surface integrity commands premium procurement decisions.
France
EU Green Deal procurement mandates are beginning to require verified recycled content in brush handle materials for public sector purchasing in Île-de-France and Auvergne-Rhône-Alpes. Architectural painting volumes in Lyon and Marseille drive flat brush procurement where coverage efficiency shapes distributor selection criteria for solvent-based coating application.
China
Industrial cleaning brush production concentrates in Yangtze River Delta manufacturing zones serving export markets with cost-optimized synthetic fiber formulations. MEE environmental compliance standards are tightening chemical safety protocols for polymer extrusion facilities in Jiangsu and Zhejiang provinces, compressing supplier lists as smaller producers lack toxicology submission budgets.
Bristle Brush Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions defined by filament formulation expertise and regulatory certification depth. The vendor base stratifies between scale-driven manufacturers with captive polymer extrusion capabilities and niche specialists serving specification-intensive industrial segments. Three strategic archetypes dominate: integrated filament-to-finished-brush producers, distribution-aligned contract manufacturers, and precision-application specialists. Competitive moves concentrate on backward integration into polymer supply chains and geographic expansion through distributor partnership networks.
Among North American fabricators, Braun Brush and Gordon Brush exemplify contrasting strategic positions within the industrial channel. Braun Brush occupies a distribution-aligned archetype through dedicated partnerships with automotive OEM suppliers. Gordon Brush represents the integrated manufacturing archetype with captive nylon extrusion capabilities controlling raw material quality from polymer to finished filament. Precision Brush and Kent Brushes anchor the precision-application specialist tier, serving cosmetic and dental segments where controlled product placement commands premium positioning. The Industrial Brush Company and Schaefer Brush sit within the contract manufacturing segment, supplying specification-matched products through centralized MRO procurement platforms.
| Leading Market Players |
|---|
| Brush Research Manufacturing |
| Braun Brush |
| Precision Brush |
| Felton Brushes |
| The Industrial Brush Company |
| Gordon Brush |
| Schaefer Brush |
| Kent Brushes |
| Cocker-Weber Brush Company |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta freight corridor's container cost dynamics compress margins for synthetic filament exporters while amplifying price differentiation between REACH-certified European producers and cost-optimized Asian manufacturers. This logistics tension concentrates procurement power among buyers capable of absorbing landed cost variance through volume scale or specification premiums.
Pricing Analysis
Current-generation carbon fiber composite filaments command three-to-five-fold premiums over prior-generation brass wire brushes in aerospace MRO channels, while next-generation biopolymer formulations remain priced at experimental tiers pending performance validation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth—FDA food-contact notifications and ECHA REACH compliance create measurable price ladders. Cost compression in commodity synthetic fiber tiers is intensifying because polymer feedstock volatility transfers directly to spot-market filament pricing. Commercial painters exhibit highest price sensitivity through centralized MRO platforms, whereas pharmaceutical cleanroom operators demonstrate lowest sensitivity where batch integrity failure costs dwarf brush expenditure.
Supply Chain Analysis
Contract manufacturing concentration clusters among Yangtze River Delta synthetic extrusion houses and Stuttgart-area precision brush fabricators serving automotive OEM specifications. Geographic supply concentration anchors in China for commodity polymer extrusion, Germany for REACH-compliant precision manufacturing, and South Korea for sterile pharmaceutical-grade production. Raw material dependencies rest on caprolactam for nylon polymerization, terephthalic acid for polyester formulations, and carbon fiber precursor from Japanese and US suppliers. Single-source vulnerability concentrates in pharmaceutical-grade filament certification where MFDS and FDA audit timelines extend supplier qualification cycles. Distribution runs through industrial distributor partnerships with automated specification-matching platforms displacing traditional spot-buying channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including filament reconditioning programs and predictive replacement scheduling expand faster than hardware sales as industrial maintenance managers prioritize uptime guarantees over unit procurement.
For Market Incumbents: Insulate market position through captive polymer extrusion capabilities that lock in REACH-compliant formulation control ahead of ECHA Annex XVII expansion. Defend against carbon fiber composite substitution in aerospace channels by accelerating FDA food-contact certification for nylon alternatives in pharmaceutical applications. Prioritize certification investment as the primary lever—simultaneous EPA, FDA, and ISO 9001 audit preparation compresses new entrant launch timelines by eight to fourteen months. For New Entrants and Emerging Players: South Korean pharmaceutical cleanroom brush demand offers underpenetrated white space as MFDS batch integrity standards tighten faster than domestic supplier capacity expansion. Target sterile synthetic filament arrays for precision component cleaning where surface integrity commands premium procurement decisions. Deploy direct-to-facility digital channels with specification-matching algorithms to bypass entrenched distributor relationships controlling Midwestern US manufacturing corridors. For Investors and Strategic Acquirers: REACH Annex XVII expansion reshapes the acquisition landscape by compressing compliant supplier lists and inflating toxicology submission budgets beyond mid-tier producer capacity. Long-term viability centers on integrated filament-to-finished-brush manufacturers with demonstrated ECHA notification capabilities and captive polymer extrusion infrastructure. Watch ECHA substance restriction proposal timelines as the signal indicating accelerated consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Polymer Extrusion Investment | Backward integration into nylon polymerization secures REACH-compliant formulation control against ECHA restriction expansion. |
| Pharmaceutical Cleanroom Certification | MFDS and FDA sterile brush qualifications open South Korean and Irish drug manufacturing hub procurement channels. |
| Carbon Fiber Composite Filament Scale-Up | Non-sparking synthetic alternatives capture aerospace MRO demand from Delta and Lufthansa Technik maintenance facilities. |
| Direct-to-Facility Digital Platform Launch | B2B specification-matching algorithms disintermediate traditional distribution controlling Toyota and BMW Group plant procurement. |
| Biopolymer Performance Engineering Partnership | Collaborative R&D with polymer institutes addresses plant-based filament stiffness limitations blocking industrial metal finishing adoption. |
Study Parameters
A spread of perspectives from brush manufacturing plant managers, automotive OEM procurement leads, pharmaceutical cleanroom maintenance directors, and industrial distribution channel partners converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with filament extrusion engineers and aftermarket service heads at centralized MRO platforms with secondary validation against ECHA REACH registration databases, FDA food contact substance notification filings, and customs trade data tracking synthetic fiber import flows. Bottom-up triangulation across filament chemistry segments and top-down cross-checks against end-use industry consumption patterns anchored volume estimates.
Demand-supply-balance framing shaped the analytical approach across the analysis window, with segmentation dimensions spanning filament material chemistry, brush geometry configuration, application intensity tier, and regional regulatory cluster. CAGRs derived from weighted regression across historical consumption trajectories and projected regulatory compliance cost absorption rates. Industry-specific forecast inputs incorporated EPA volatile organic compound enforcement timelines and MFDS pharmaceutical manufacturing capacity expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by commodity chemical producers or accelerated biopolymer breakthrough announcements would shift outcomes beyond modeled ranges. Quarterly review of ECHA substance restriction proposal dockets and pharmaceutical cleanroom construction permit filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Brazil Cookware Market
Household Items
Japan Cookware Market
Household Items
Smart Bathroom Products Market
Household Items
US Digital Showers Market
Household Items
Global Electric Scissors Market
Household Items
Asean Cookware Market
Household Items
Deodorizer Bag Market
Household Items
Tablet Tissue Paper Market
Household Items
Residential Air Purifiers Market
Household Items
Pet Fur Remover Market
Household Items
Sleeping Pillow Market
Household Items
Permanent Marker Market
Household Items
Latex Mattress Market
Household Items
Coffin and Cremation Urn Market
Household Items
Global Nap Pod Market
Household Items
Bladeless Neck Fan Market