
 Europe Hand Dryers Market | 2026-2036
Europe Hand Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hand Dryers Market Analysis
The EU Green Deal's waste-reduction targets for public facilities is broadening the addressable market for electric hand dryers across European institutional buyers. Dyson leverages its air-multiplier engineering to dominate premium restroom specifications in London and Paris commercial developments. Electrostar GmbH anchors its position through German manufacturing scale and direct channel control over facility management distributors. JVD SAS competes in Southern Europe through compact designs tailored for space-constrained washrooms in Spain and Italy.
A hand dryer is an electromechanical device that uses forced airflow, heating elements, or high-velocity jets to evaporate or strip water from hands after washing, typically operating at air speeds between 180 and 400 mph for high-speed units and incorporating HEPA filtration or antimicrobial coatings in healthcare-grade specifications. Its primary commercial purpose is to eliminate paper towel consumption while reducing restroom maintenance labor and waste disposal costs in high-traffic facilities. High-speed jet-air models command the strongest margin pools due to energy-efficiency certifications and premium pricing in airport and stadium contracts, while wall-mounted installations sustain the largest volume base across existing building retrofits where electrical infrastructure is already positioned. Touchless infrared technology leads new specification growth as hygiene protocols in healthcare and educational end users harden against cross-contamination risks.
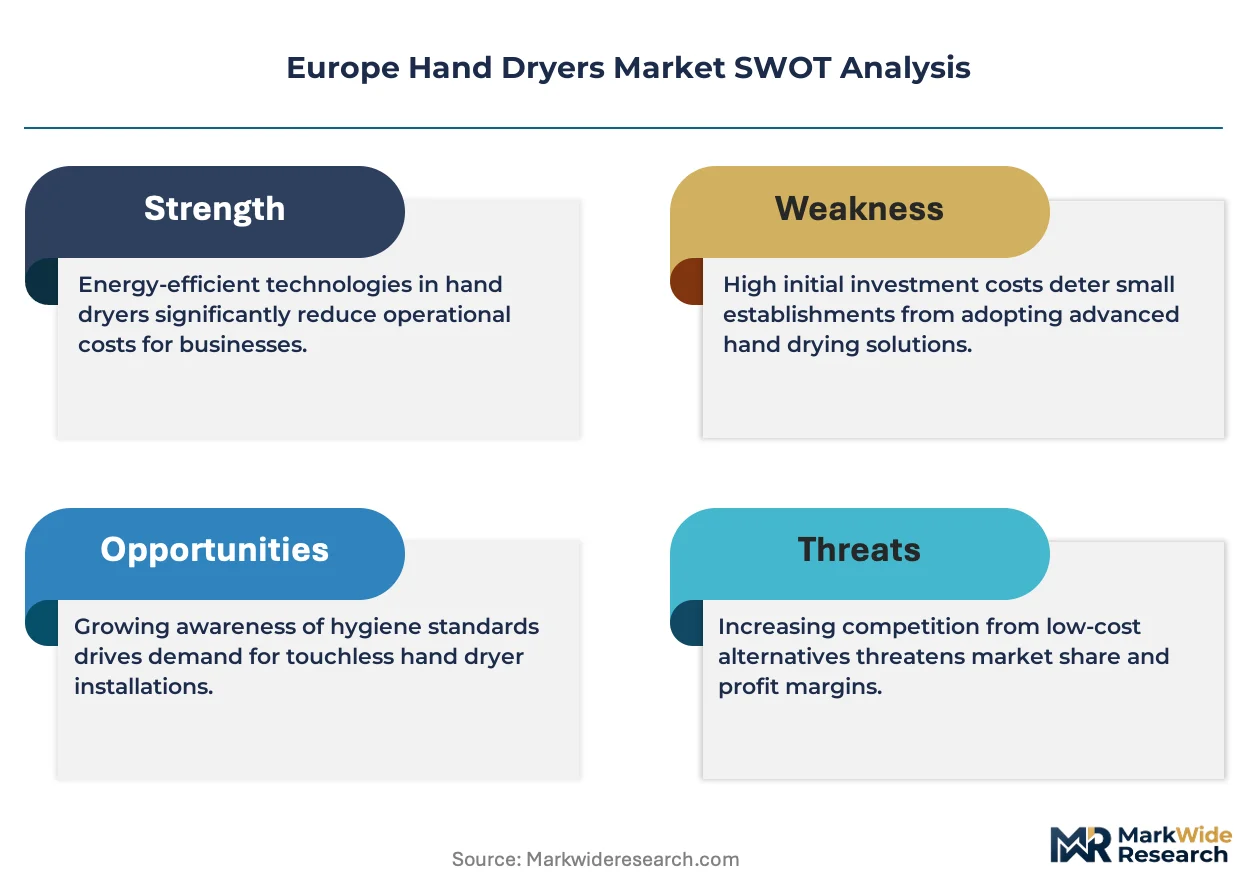
CE marking under the EU Machinery Directive and Ecodesign regulations govern minimum efficiency standards and electrical safety compliance for hand dryers sold across member states, while national building codes in Germany and France mandate accessibility dimensions that shape product form factors. The EU F-Gas Regulation restricts refrigerant-based heating systems, pushing manufacturers toward resistive and jet-air architectures. Stakeholders must monitor how the EU AI Act's emerging classification of sensor-driven building equipment affects firmware-enabled touchless units with data collection capabilities.
Market Dynamics
Touchless infrared activation systems are compressing specification cycles across European institutional procurement, as hygiene protocols in healthcare and education sectors harden against cross-contamination vectors. Facility managers now prioritize sensor-driven units that eliminate physical contact surfaces entirely.
Growth Catalysts
- EU Green Deal waste-reduction targets:Mandatory paper waste reduction in public facilities redirects municipal budgets toward electric drying infrastructure across member states.
- Airport restroom modernization programs:German aviation authorities are accelerating touchless unit procurement through terminal renovation contracts.
- Healthcare-grade HEPA filtration:Antimicrobial coating specifications in clinical settings expand the premium product addressable market.
Market Restraints
- Copper and aluminum input volatility:Heating element and motor housing materials face commodity price swings that compress manufacturing margins.
- Residual paper towel infrastructure:Existing dispenser installations and maintenance contracts in older facilities create switching friction.
- CE marking compliance timelines:EU Machinery Directive certification delays extend product launch windows by four to six months.
Strategic Opportunities
- France hospitality renovation wave:Boutique hotel chains in Paris and Lyon are retrofitting bathrooms with designer aesthetic units.
- EU AI Act sensor classification:Firmware-enabled touchless units with data collection capabilities face emerging regulatory clarity that rewards early compliance investment.
- Southern Europe space constraints:Compact wall-mounted designs for Spain and Italy's smaller washroom footprints represent underserved specification demand.
Industry Challenges
- Electrical infrastructure retrofit costs:Legacy buildings without positioned conduit require expensive installation labor that erodes project economics.
- Cross-border distributor coordination:Facility management procurement networks span multiple national standards, complicating inventory and service coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hand Dryers Market |
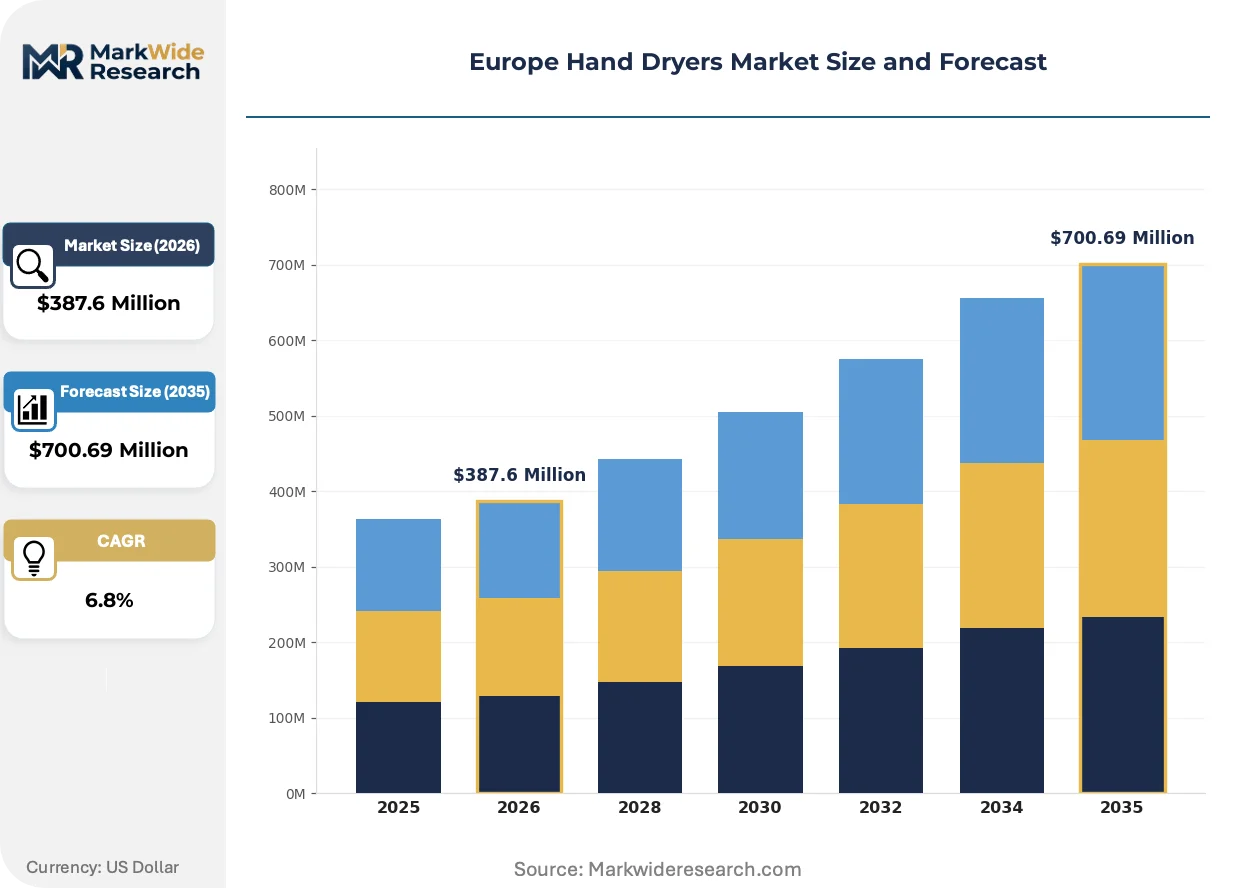
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed, Standard, Automatic, Manual Installation Type: Wall-Mounted, Countertop, Portable, Floor Stand End User: Commercial, Industrial, Educational, Healthcare Technology: Infrared, Touchless, Heating Element, Jet Air |
| Companies Covered | Dyson, Bobrick Washroom Equipment, Electrostar GmbH, Excel Dryer, JVD SAS, Mediclinics, Stiebel Eltron, Saniflow Hand Dryer Corporation, Veltia Hand Dryers, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hand Dryers Market Emerging Trajectories
Jet-air engineering architectures are compressing drying times while slashing energy consumption, forcing a specification pivot away from conventional heated-air models. Manufacturers now compete on air-multiplier physics rather than thermal output alone.
High-velocity blade-style airflow systems is consolidating competitive positioning in premium commercial developments. London and Paris specification teams specify these units for airport and stadium contracts where throughput density matters. The technology is consolidating margin pools around energy-efficiency certifications that command pricing premiums.
REACH chemical restrictions and the EU F-Gas Regulation are eliminating refrigerant-based heating architectures from new product pipelines. Manufacturers pivot toward resistive and jet-air designs exclusively. Healthcare and food-service end-use verticals respond fastest due to contamination-risk sensitivities.
Facility management procurement teams now bundle hand dryer specifications into broader restroom renovation contracts rather than standalone equipment purchases. Distributor relationships with construction contractors displace traditional direct-channel sales. Germany's airport modernization programs exhibit this pattern most visibly, with terminal-wide packages replacing piecemeal unit acquisition.
Europe Hand Dryers Market Segmentation
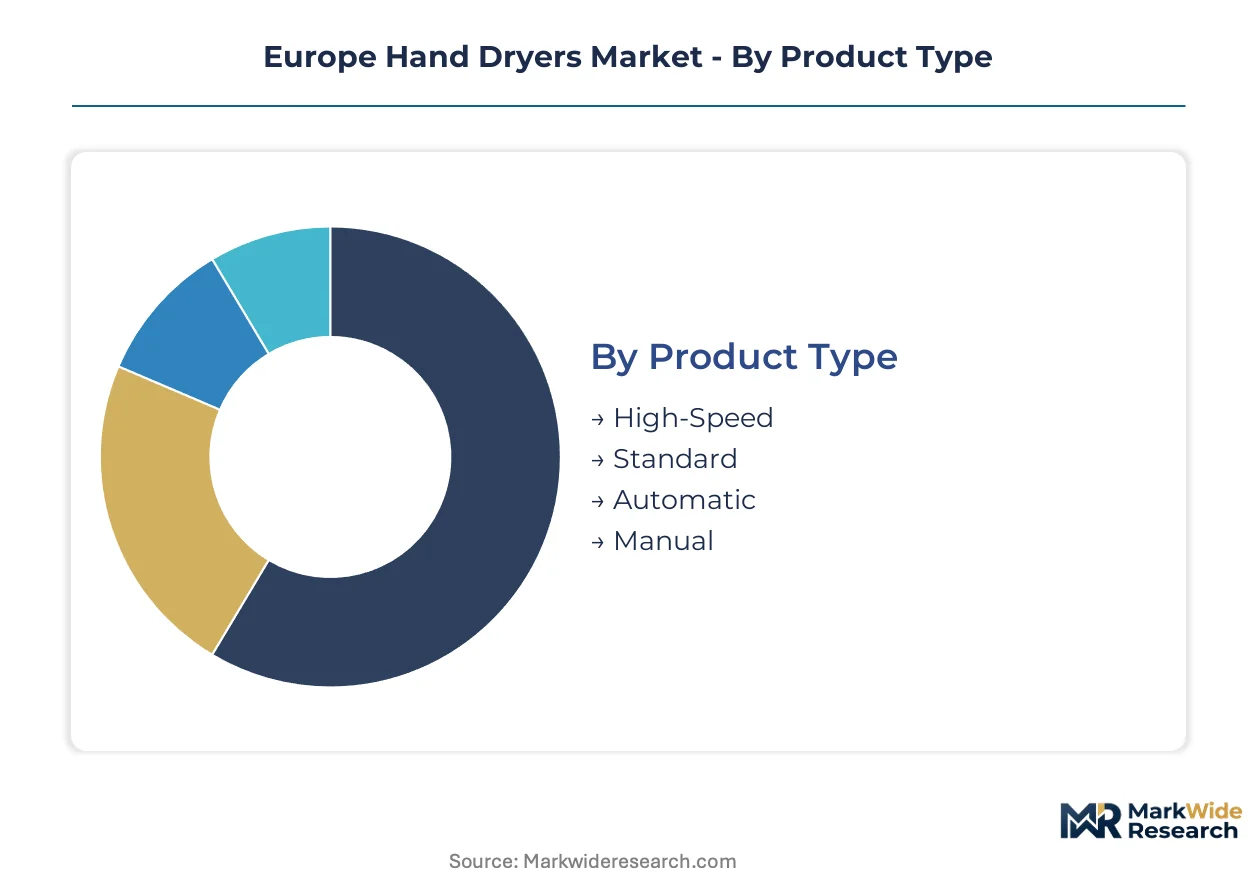
Hand dryer procurement patterns diverge sharply between standalone replacement purchases and integrated restroom renovation contracts. Facility managers specify products differently when buying discrete units versus embedding them within broader infrastructure upgrades. Segmentation clarity helps suppliers align R&D investment with where specification authority actually sits.
Product Type:
Integration depth varies substantially across product categories, with some segments designed for plug-and-play replacement while others require coordinated electrical and mechanical system planning.
- High-Speed:These units deploy air-multiplier physics to achieve drying cycles under 12 seconds at velocities between 300-400 mph. German airport terminals and French TGV stations prioritize this segment for throughput density where passenger flow continuity matters. The EU Ecodesign Directive's efficiency thresholds favor this architecture over heated alternatives.
- Automatic:Sensor-activated units eliminate physical contact through infrared detection circuits embedded in the housing. Healthcare procurement in the Netherlands and Belgium mandates this specification for infection control protocols in clinical washrooms. CE marking under the EU Machinery Directive governs sensor reliability standards.
- Standard:Conventional heated-air models with push-button or lever activation dominate existing building retrofits where electrical infrastructure cannot support high-amp jet systems. Italian municipal facilities favor this segment for budget-constrained renovations.
- Manual:Basic electromechanical units with mechanical switches persist in industrial settings across Poland and Czech Republic where hygiene protocols remain less stringent and capital budgets are constrained.
Volume placements concentrate in Standard units for budget-driven retrofits; the faster expansion belongs to High-Speed as energy-efficiency certifications harden procurement criteria.
Installation Type:
Mounting configuration dictates project economics and determines whether hand dryers enter facilities through equipment-only channels or bundled construction contracts.
- Wall-Mounted:The dominant volume configuration positions units at standardized heights above wash basins, leveraging existing electrical conduit in restroom walls. Spanish hospitality renovations favor compact wall-mounted designs for space-constrained bathrooms in historic building stock.
- Countertop:Integrated basin-level installations appear in premium commercial developments across London and Paris where architectural uniformity outweighs unit cost considerations. These specifications require coordinated plumbing and electrical trades during construction.
- Portable:Battery or corded mobile units serve temporary facilities and event infrastructure across European festival circuits and construction site welfare accommodations.
- Floor Stand:Freestanding pedestal mounts address accessibility requirements in German public facilities where DIN standards mandate reach ranges for wheelchair users.
Specification authority for Wall-Mounted units sits with facility management distributors; Countertop placements flow through construction contractor relationships.
End User:
End-use verticals impose distinct performance requirements that filter through to product specification, with hygiene sensitivity and traffic density as primary differentiators.
- Commercial:Office buildings, retail centers, and hospitality properties across France and the UK constitute the largest addressable volume. Boutique hotel chains in Lyon and Marseille drive designer aesthetic specifications that command pricing premiums.
- Healthcare:Hospitals and clinical settings mandate HEPA filtration and antimicrobial coatings under national infection control guidelines. This segment exhibits the strictest compliance requirements and longest procurement cycles.
- Educational:Schools and universities prioritize vandal-resistant housings and simplified maintenance access. Scandinavian public procurement frameworks govern this vertical through centralized municipal purchasing.
- Industrial:Manufacturing facilities and logistics warehouses emphasize durability and rapid cycle times over energy efficiency. Eastern European industrial zones favor basic specifications with minimal electronic complexity.
Margin concentration sits with Healthcare specifications; the steepest volume expansion trajectory belongs to Commercial as hospitality renovation activity accelerates.
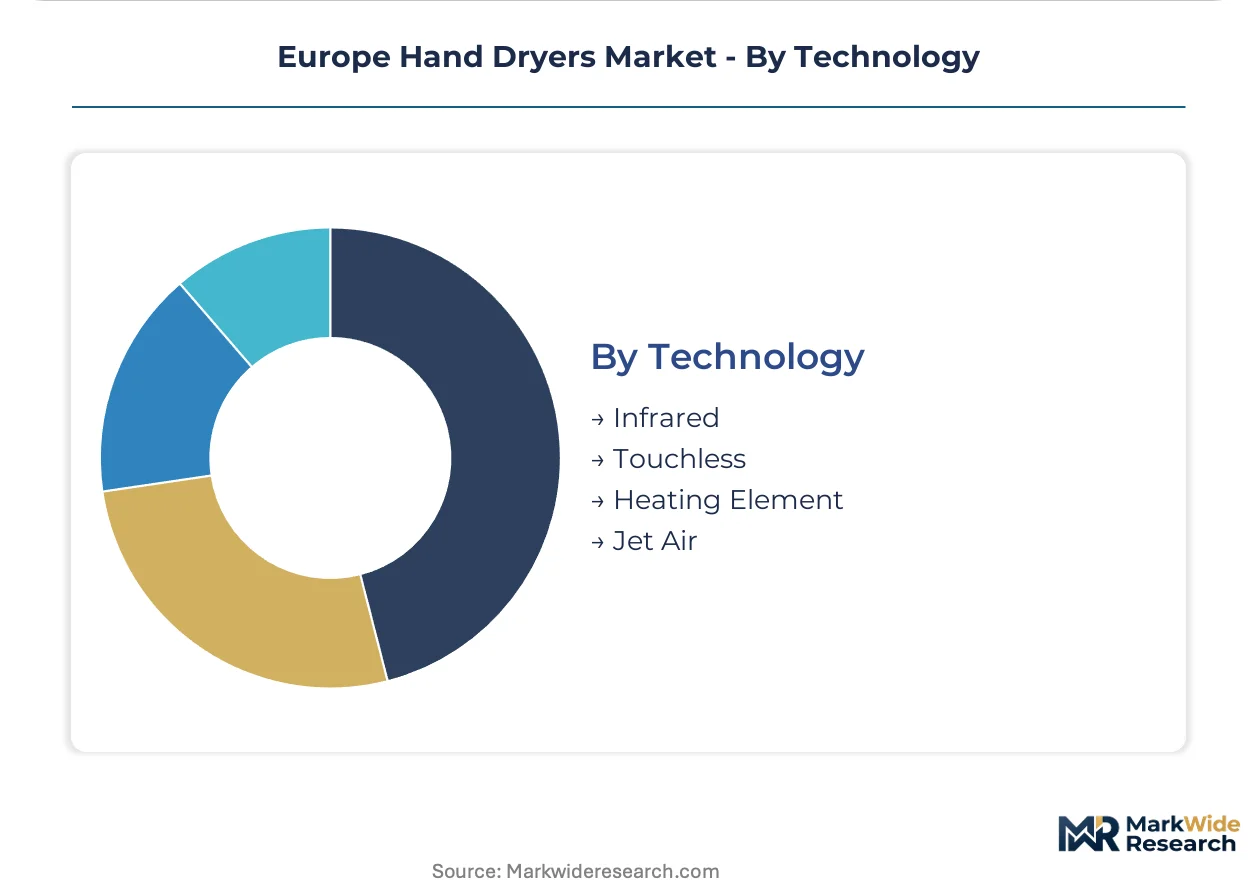
Technology:
Technology architecture determines regulatory compliance pathways and shapes supplier competitive positioning across European member states.
- Jet Air:Blade-style high-velocity systems strip water through aerodynamic force rather than thermal evaporation. Dyson dominates premium specifications in UK commercial developments through patented air-multiplier engineering. The EU F-Gas Regulation accelerates displacement of refrigerant-based alternatives toward this architecture.
- Touchless:Infrared sensor systems eliminate all physical contact surfaces. Healthcare procurement in Germany and Austria mandates this specification under hygiene protocols hardened by pandemic experience. The EU AI Act's emerging sensor classification creates compliance preparation requirements for firmware-enabled units.
- Heating Element:Resistive thermal architectures persist in budget-sensitive segments where capital cost outweighs operating efficiency. REACH chemical restrictions constrain coating formulations in this segment.
- Infrared:Sensor activation technology spans both jet-air and heated-air product architectures, with specification teams treating it as a cross-cutting feature rather than standalone category.
Technology sourcing for Heating Element units concentrates in Asian component suppliers; Jet Air engineering capabilities cluster with European manufacturers possessing aerodynamics expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt Airport's terminal modernization program is channeling specification authority toward German facility management distributors. The EU Green Deal's waste-reduction mandates are redirecting municipal procurement budgets across member states toward electric drying infrastructure.
Germany
Aviation authorities in Frankfurt and Munich are bundling touchless hand dryer specifications into terminal-wide renovation contracts. CE marking under the EU Machinery Directive governs sensor reliability standards for healthcare procurement in Berlin and Hamburg. Electrostar GmbH anchors manufacturing scale in North Rhine-Westphalia, supplying facility management distributors with direct channel control.
France
Boutique hotel chains in Paris and Lyon are retrofitting bathrooms with designer aesthetic units that command pricing premiums. The country's national building codes mandate accessibility dimensions that shape product form factors for public facilities. Île-de-France specification teams prioritize architectural uniformity in premium commercial developments across the capital region.
United Kingdom
London commercial developments specify blade-style high-velocity systems for airport and stadium contracts where throughput density matters. Ecodesign regulations enforce minimum efficiency standards that favor jet-air architectures over heated alternatives. Dyson leverages air-multiplier engineering to dominate premium restroom specifications across Greater London.
Spain
Compact wall-mounted designs address space-constrained washrooms in historic building stock across Madrid and Barcelona. Hospitality renovations in Catalonia favor units that fit within narrow bathroom footprints without electrical infrastructure expansion. Southern Europe's smaller washroom dimensions represent underserved specification demand for space-optimized products.
Italy
Municipal facilities in Milan and Rome favor standard heated-air models for budget-constrained renovations where existing electrical infrastructure limits upgrade options. REACH chemical restrictions constrain coating formulations in resistive thermal architectures. Northern industrial zones maintain demand for basic electromechanical units with minimal electronic complexity.
Europe Hand Dryers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and certification depth. The vendor base organizes into three tiers: aerodynamics-focused engineering houses, manufacturing-scale German specialists, and Southern European compact-design experts. Consolidation pressure operates through facility management distributor relationships rather than direct manufacturer rivalry. M&A activity targets sensor firmware capabilities, while capacity expansion concentrates in German industrial corridors.
Within the engineering-led tier, Dyson and Excel Dryer represent premium specification anchors in UK and US-derived positioning. Electrostar GmbH exemplifies manufacturing-scale specialization with German GmbH structure and direct channel control. JVD SAS occupies a position among compact-design specialists serving space-constrained Southern European markets.
| Leading Market Players |
|---|
| Dyson |
| Bobrick Washroom Equipment |
| Electrostar GmbH |
| Excel Dryer |
| JVD SAS |
| Mediclinics |
| Stiebel Eltron |
| Saniflow Hand Dryer Corporation |
| Veltia Hand Dryers |
| Others |
Supply Flow & Price Mechanics
Copper and aluminum price indices on the London Metal Exchange cascade through heating element and motor housing costs, compressing manufacturing margins and forcing tiered pricing stratification across premium jet-air, standard heated, and economy manual units. Facility management distributors absorb commodity volatility through project-based contract structures that bundle installation labor with equipment procurement.
Pricing Analysis
Throughput-based value anchors dominate procurement in German airport terminals and French TGV stations where passenger flow density justifies premium pricing for sub-12-second drying cycles. Pricing stratifies across energy-efficiency certification tiers, with EU Ecodesign Directive compliance commanding measurable premiums over uncertified alternatives. Cost compression in standard heated-air segments intensifies because Italian municipal buyers prioritize capital expenditure minimization over operating efficiency. Healthcare procurement in the Netherlands and Belgium exhibits the lowest price sensitivity due to infection control mandates, while Polish industrial facilities demonstrate acute budget constraints.
Supply Chain Analysis
Refurbishment flows for sensor modules and motor assemblies remain underdeveloped across European hand dryer networks, creating aftermarket service gaps that third-party maintenance providers are beginning to address. Manufacturing concentration clusters in Germany, China, and Taiwan, with German producers anchoring high-velocity jet-air engineering and Asian suppliers dominating resistive heating component production. Supply chains draw from copper winding wire, aluminum die-cast housings, and infrared sensor arrays, exposing assemblers to commodity price volatility. Single-source vulnerability concentrates in specialized aerodynamics engineering for blade-style airflow systems. Distribution runs through facility management distributors with direct channel control over construction contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European hand dryer supply faces capacity constraints in certified sensor firmware engineering, propping pricing power for compliant manufacturers against commodity competitors.
For Market Incumbents: Deepen backward integration into infrared sensor module production to defend margin position against Asian component suppliers encroaching on touchless specifications. Expand German manufacturing scale to capture Frankfurt and Munich airport terminal renovation contracts before specification authority consolidates around bundled construction packages. For New Entrants and Emerging Players: Boutique hotel procurement teams in Lyon and Marseille represent the most penetrable buyer archetype, as designer aesthetic specifications remain underserved by engineering-focused incumbents. Target compact wall-mounted configurations for Spanish historic building renovations where space constraints exclude standard-format competitors. Pursue direct architectural specification relationships rather than distributor channel dependence. For Investors and Strategic Acquirers: Distressed-cycle entries favor sensor firmware specialists in Southern Germany with EU AI Act compliance capabilities already embedded. Long-term viability over the medium-term projection horizon rests on regulatory preparation rather than manufacturing scale alone. Acquisition targets should demonstrate CE marking expertise under the EU Machinery Directive. Watch for Ecodesign Directive efficiency threshold tightening as the inflection signal that separates compliant from stranded asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Firmware Acquisition | EU AI Act compliance preparation rewards early sensor data capability investment. |
| Compact Design R&D Program | Spanish and Italian historic building stock demands space-optimized wall-mounted configurations. |
| Energy Efficiency Certification | Ecodesign Directive thresholds favor jet-air architectures over heated alternatives in procurement scoring. |
| Construction Contractor Partnership | Bundled restroom renovation contracts displace standalone equipment purchasing in German aviation. |
| HEPA Filtration Integration | Healthcare procurement in Belgium and the Netherlands mandates antimicrobial coating specifications. |
Methodological Framework
Trade publications, EU regulatory filings, and facility management procurement databases formed the secondary backbone, supplemented by primary interviews with product managers at German manufacturing specialists, specification directors at French architectural firms, and procurement leads at Benelux healthcare systems. Bottom-up and top-down triangulation validated volume estimates across product type, installation configuration, and end-use vertical segmentation.
Bottom-up modeling anchored projections, with top-down macro checks against EU Green Deal implementation timelines and airport modernization budget disclosures. Segmentation dimensions span drying technology architecture, mounting configuration, end-use hygiene sensitivity, and national regulatory cluster. CAGRs were derived from installed base replacement cycles and new construction penetration assumptions, incorporating copper price elasticity effects on manufacturing margins and REACH chemical restriction impacts on coating formulation costs.
Revisions become necessary when EU AI Act sensor classification guidance materializes, when Ecodesign Directive efficiency thresholds tighten, or when German aviation authority procurement bundling accelerates beyond current terminal renovation schedules. Forecasts reflect documented assumptions about commodity price stabilization and regulatory implementation pacing. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Fan Market
Household Items
Neck Pillows Market
Household Items
Washing Capsules Market
Household Items
Car Air Freshener Market
Household Items
Industrial Vacuum Cleaner Market
Household Items
Nebulizing Diffuser Market
Household Items
Qatar Gas Hobs Market
Household Items
Sleeping Pods Market
Household Items
Air Freshener Market
Household Items
Cutlery Steel Market
Household Items
Japan Digital Showers Market
Household Items
Industrial Floor Mats Market
Household Items
Bottle Openers Market
Household Items
Command Hooks Market
Household Items
Aromatherapy Diffuser Market
Household Items
Infrared Sauna Heaters Market