
 Copper Water Bottle Market | 2026-2036
Copper Water Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Water Bottle Market Insights
The gap between hand-hammered artisan copper bottles and machine-pressed commodity variants is expanding, with finish quality and purity certification now splitting price tiers by multiples rather than margins. Milton leverages its pan-Indian distribution network to sustain volume leadership in standardized formats. P-TAL anchors the premium segment through direct artisan partnerships and heritage craft positioning. Indian Art Villa competes aggressively on engraved customization and gifting-oriented SKUs.
Copper water bottles are vessels fabricated from electrolytic or food-grade copper sheet, typically 99.9% pure, formed through spinning or hand-beating processes and finished with food-safe lacquer or bare metal interiors; they function as antimicrobial hydration containers leveraging copper's oligodynamic properties for consumer wellness applications. Classic copper formats dominate unit volumes due to lower production complexity and broader retail penetration, while insulated copper variants command the fastest value growth as temperature retention becomes a decisive purchase criterion for office and travel segments. The material grade dimension concentrates margin pools at food-grade and electrolytic purity tiers where certification documentation supports premium positioning against unverified alloy alternatives.
India's BIS mandates food-grade copper standards under IS 15448 for direct food contact, while the US FDA regulates surface coatings and lacquers through indirect food additive provisions under 21 CFR 175.300; these frameworks compel manufacturers to maintain dual compliance documentation for cross-border sales. The EU REACH framework further restricts certain anti-tarnish chemical treatments, pushing suppliers toward mechanical finishing methods. Stakeholders must monitor evolving alloy disclosure requirements and purity verification protocols as wellness claims face intensifying scrutiny from consumer protection authorities.
Market Dynamics
The artisan-commodity bifurcation in copper water bottles is intensifying as purity certification becomes a non-negotiable purchase filter, compressing margins for uncertified suppliers while amplifying premiums for documented food-grade compliance.
Growth Catalysts
- IS 15448 Compliance Pull:India's BIS food-grade copper mandate creates a compliance floor that eliminates alloy-adulterated competitors, rewarding certified manufacturers with shelf access in organized retail and e-commerce marketplaces.
- Wellness Community Amplification:Fitness and yoga practitioners propagate antimicrobial claims through social channels, generating organic demand velocity that reduces customer acquisition costs for heritage-positioned brands.
- Electrolytic Purity Verification:Laboratory assay documentation now accompanies premium SKUs, enabling price multiples over unverified alternatives and shifting buyer preference toward traceable supply chains.
Market Restraints
- Raw Copper Price Volatility:LME copper futures fluctuations transmit directly to finished goods pricing, squeezing working capital for inventory-heavy distributors and forcing frequent retail price adjustments.
- Artisan Production Bottlenecks:Hand-beating capacity concentrates in Moradabad and Jaipur clusters, creating supply rigidities that prevent rapid volume scaling during demand surges.
- REACH Chemical Restrictions:The EU framework bans certain anti-tarnish surface treatments, compelling exporters to adopt costlier mechanical polishing methods or forfeit continental market access.
Strategic Opportunities
- Insulated Format Expansion:Double-wall vacuum construction addresses office and travel temperature-retention needs, opening price points above classic formats while differentiating against generic metal bottles.
- Direct Artisan Platforms:Brand-owned digital channels bypass wholesale markups, capturing full margin on heritage-positioned SKUs while building narrative control around craft provenance.
- Corporate Gifting Verticals:Engraved customization for wellness-oriented employers creates recurring B2B revenue streams with lower return rates than individual consumer purchases.
Industry Challenges
- Assay Documentation Burden:Third-party laboratory verification for every production batch extends lead times and adds fixed costs that burden smaller artisan workshops.
- Cross-Border Compliance Complexity:Simultaneous adherence to BIS, FDA indirect additive rules, and REACH mechanical finishing requirements demands dedicated regulatory staff that mid-tier exporters struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Water Bottle Market |
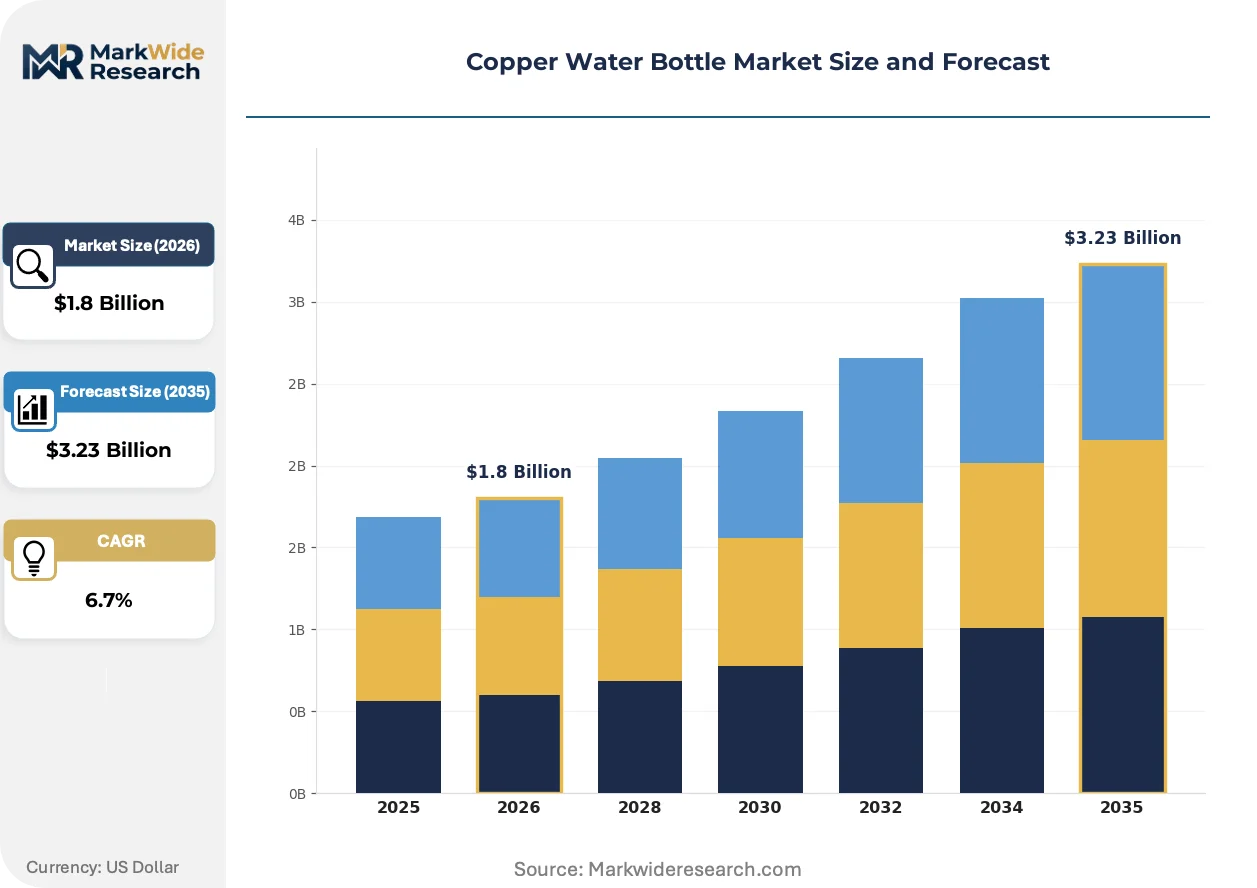
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Copper, Insulated Copper, Copper with Lid, Copper with Handle, Engraved Copper Material Grade: Pure Copper, Copper Alloy, Food Grade Copper, Recycled Copper, Electrolytic Copper End Use Application: Yoga & Meditation, Travel & Outdoors, Home & Kitchen, Office Use, Fitness & Sports Sales Channel: Online Retailers, Specialty Stores, Direct Sales, Department Stores, Wellness Centers |
| Companies Covered | Milton, P-TAL, Indian Art Villa, Signoraware, The Better Home, Kaarigar, Borosil, Purely Copper, Copper H2O, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Water Bottle Market Trends and Innovations
Product architecture and verification protocols are converging to reshape competitive positioning, with thermal performance and documentary proof displacing aesthetic differentiation as primary purchase determinants.
Electrolytic-grade copper sheet with certified 99.9% purity is absorbing market share from lower-grade alternatives as wellness buyers prioritize documented antimicrobial efficacy over decorative appeal. Urban professionals and fitness enthusiasts now demand batch-specific assay certificates, compressing demand for unverified alloy bottles. This purity verification infrastructure is absorbing margin from commodity suppliers while consolidating premium positioning around documented supply chains.
REACH chemical restrictions are eliminating solvent-based anti-tarnish coatings from EU-bound shipments, forcing suppliers toward mechanical buffing and food-safe lacquer alternatives. The regulation compresses production efficiency for exporters reliant on rapid chemical finishing. German and French distributors now prioritize mechanically finished inventory, reshaping procurement criteria across European wellness retail channels.
Wellness buyers increasingly substitute direct brand relationships for traditional retail discovery, with Instagram and dedicated wellness platforms displacing generalist e-commerce as primary research channels. This channel migration rewards narrative-rich heritage positioning over price comparison. The shift concentrates most visibly in North American metropolitan markets where yoga studio retail and influencer endorsement drive purchase decisions.
Copper Water Bottle Market Segmentation
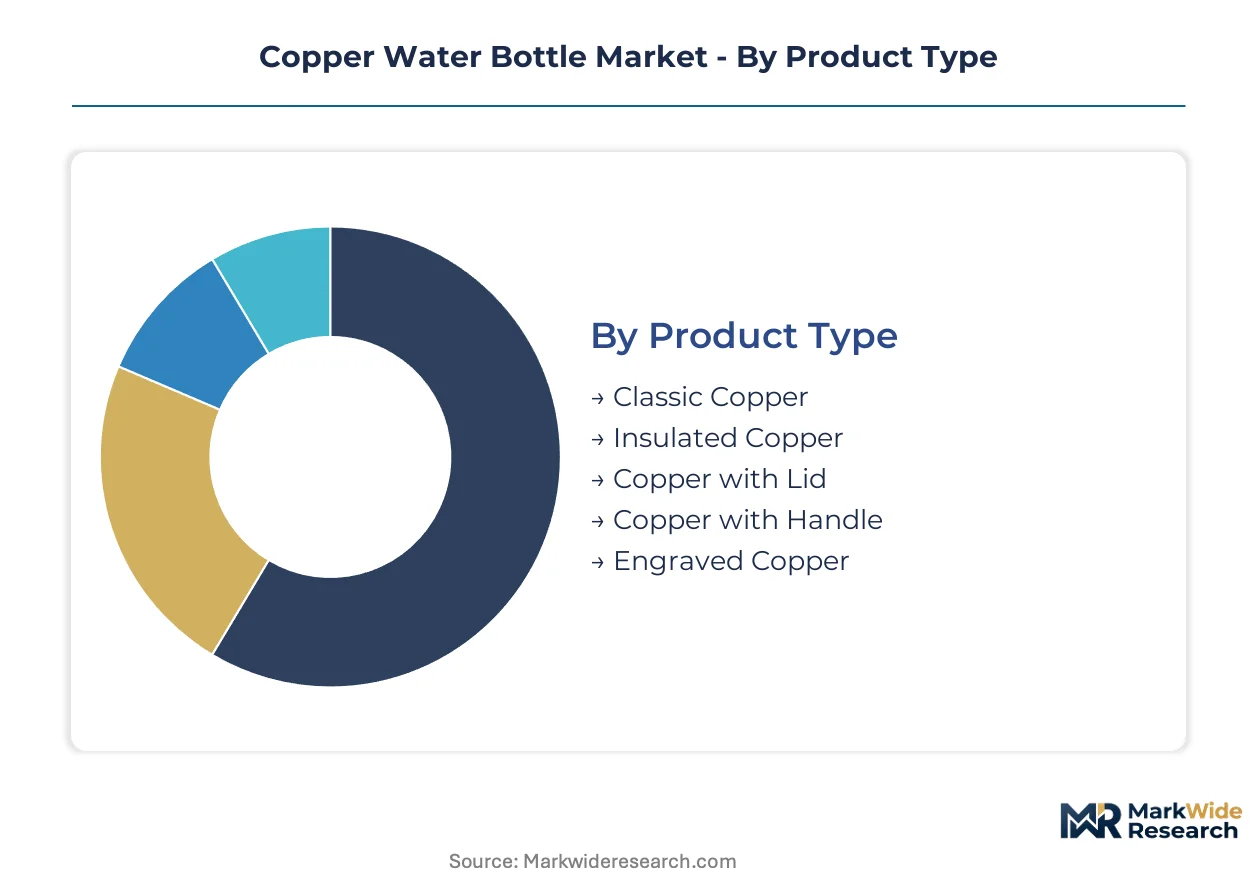
Product architecture in copper water bottles now splits sharply along certification requirements, with food-grade documentation filtering shelf access and thermal performance commanding premium positioning. Understanding how purity tiers, format variations, and channel structures intersect reveals where margin pools concentrate and which segments face commoditization pressure.
Product Type:
IS 15448 compliance applies uniformly across formats, yet insulated and engraved variants face additional BIS thermal performance and surface coating scrutiny that classic formats bypass.
- Classic Copper:Single-wall construction from 99.9% electrolytic sheet with food-safe interior lacquer. Demand concentrates in Indian tier-2 cities and North American yoga studios where price accessibility outweighs temperature retention needs.
- Insulated Copper:Double-wall vacuum construction with copper outer shell and stainless steel inner chamber, requiring dual-material certification under FDA indirect additive rules. Office professionals in New York, Toronto, and London drive fastest adoption as temperature retention becomes non-negotiable for workplace hydration.
- Copper with Lid:Screw-top or push-fit closures with silicone gaskets, subject to additional migration testing under EU REACH for rubber components.
- Copper with Handle:Riveted or welded loop attachments, common in travel-oriented SKUs where portability trumps minimalist aesthetics.
- Engraved Copper:Laser-etched or hand-tooled surface designs, dominating corporate gifting verticals with customization lead times of 7-14 days.
Leading the category by volume: Classic Copper. Growing fastest: Insulated Copper.
Material Grade:
Cost tiers stratify sharply around laboratory verification burden, with electrolytic and food-grade segments absorbing documentation costs that alloy and recycled variants avoid.
- Electrolytic Copper:99.9% purity with batch-specific assay certificates from NABL-accredited laboratories. Heritage-positioned brands in Jaipur and Moradabad command price multiples through documented antimicrobial efficacy, with North American wellness buyers paying premiums for traceable supply chains.
- Food Grade Copper:IS 15448-compliant sheet with mandatory lead and cadmium migration testing. Organized retail in India and FDA-registered importers in the United States require this documentation as a baseline for shelf access, compressing demand for unverified alternatives.
- Pure Copper:General purity claims without third-party verification, increasingly confined to unorganized retail and price-sensitive export markets.
- Copper Alloy:Brass or bronze mixtures with reduced copper content, facing exclusion from wellness-positioned channels due to antimicrobial claim dilution.
- Recycled Copper:Post-consumer scrap remelted to variable purity, concentrated in economy-tier gifting SKUs where sustainability messaging offsets certification gaps.
Highest margin capture: Electrolytic Copper. Fastest volume expansion: Food Grade Copper.
End Use Application:
Application segments diverge by performance requirements, with fitness and travel use cases demanding insulated formats while home and meditation applications tolerate classic construction.
- Fitness & Sports:Gym-goers and athletic trainers prioritize leak-proof insulated bottles with copper exteriors for antimicrobial surface contact, driving fastest value growth in premium sporting goods retail.
- Travel & Outdoors:Hikers and commuters require vacuum insulation and durable finishes, with German and French distributors prioritizing REACH-compliant mechanical polishing for this segment.
- Yoga & Meditation:Studio practitioners favor lightweight classic formats with engraved mantras or symbols, concentrated in Rishikesh, Bali, and California wellness clusters.
- Home & Kitchen:Domestic use tolerates wider format variation, with Indian households representing the largest absolute volume for untreated copper storage vessels.
- Office Use:White-collar professionals in Mumbai, Bangalore, and Chicago drive insulated format adoption where desk-side temperature retention replaces frequent refilling.
Largest volume base: Home & Kitchen. Steepest expansion trajectory: Fitness & Sports.
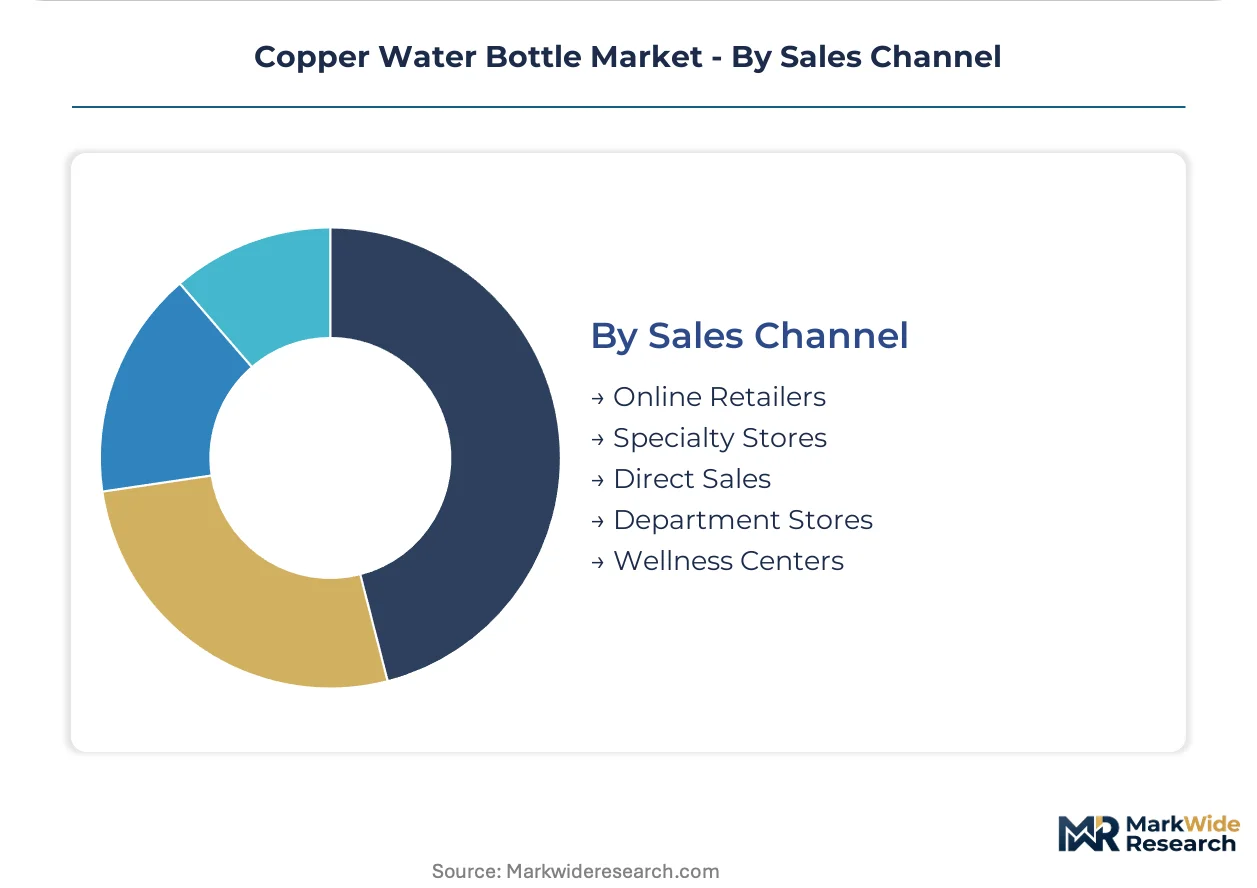
Sales Channel:
Channel economics split between margin capture and reach, with direct and specialty channels rewarding narrative control while online marketplaces prioritize price comparison.
- Online Retailers:Amazon, Flipkart, and dedicated wellness platforms dominate unit volumes, with algorithmic search favoring IS 15448 keyword compliance and verified purity claims in product titles.
- Specialty Stores:Yoga studio retail and ayurvedic pharmacies in Kerala, Rajasthan, and British Columbia capture full margin on heritage-positioned SKUs through tactile evaluation and staff education.
- Direct Sales:Brand-owned websites and Instagram commerce bypass platform fees, enabling artisan workshops in Moradabad to build narrative control around craft provenance.
- Department Stores:Marks & Spencer, Nordstrom, and Indian department chains curate gifting-oriented assortments with engraved customization services.
- Wellness Centers:Spa and retreat properties in Goa, Sedona, and Tulum bundle copper bottles into wellness packages, creating low-churn B2B revenue.
Highest transaction value: Specialty Stores. Widest geographic reach: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moradabad anchors artisan production capacity for copper water bottles, with the Uttar Pradesh cluster supplying hand-beaten heritage formats to wellness retailers across North America and Europe. India's BIS food-grade mandate under IS 15448 shapes compliance requirements for all export-bound manufacturers.
United States
FDA indirect food additive rules under 21 CFR 175.300 govern surface lacquer migration limits for copper bottles entering American wellness retail. California and New York metropolitan markets absorb the highest per-capita volumes of insulated copper formats as temperature retention becomes standard for office hydration. Los Angeles yoga studio retail channels drive premium positioning for heritage-positioned imports.
India
Domestic demand concentrates in tier-2 cities where untreated classic formats serve household storage needs, while organized retail in Mumbai and Bangalore enforces IS 15448 documentation as a baseline shelf requirement. Jaipur's hand-beating workshops supply engraved gifting SKUs with 7-14 day customization lead times. BIS laboratory assay verification now accompanies premium export batches to North American and European buyers.
Germany
ECHA REACH restrictions on solvent-based anti-tarnish coatings eliminate chemical finishing methods for EU-bound copper bottles, compelling exporters toward mechanical polishing alternatives. Berlin and Munich wellness retailers prioritize mechanically finished inventory with documented supply chains. The regulatory shift compresses production efficiency for Indian suppliers serving German distributors.
Canada
Health Canada antimicrobial claim scrutiny intensifies for copper wellness products marketed through Vancouver and Toronto specialty channels, pushing importers toward third-party purity verification. British Columbia yoga studio retail mirrors California demand patterns for heritage-positioned formats. Cross-border e-commerce from US platforms dominates unit volumes despite domestic distribution expansion.
United Kingdom
Marks & Spencer and department store curators in London enforce food-grade documentation requirements that parallel FDA and BIS standards for copper hydration vessels. The UK market absorbs significant volumes of engraved corporate gifting SKUs from Jaipur and Moradabad workshops. Brexit-related customs documentation has extended lead times for artisan exporters serving British wellness retailers.
Copper Water Bottle Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the copper water bottle market, with integrated foundry operations in Moradabad supplying raw material to specialized finishing workshops. The vendor base stratifies into three tiers: heritage artisan partnerships commanding premium multiples, organized retail brands scaling standardized formats, and unorganized alloy suppliers facing exclusion from certified channels. Dominant competitive moves include direct-to-consumer platform construction and purity verification infrastructure investment.
Within the heritage artisan tier, P-TAL and Kaarigar exemplify craft-provenance positioning through direct Moradabad workshop partnerships. Milton anchors the organized retail vector with pan-Indian distribution density for IS 15448-compliant standardized formats. Indian Art Villa occupies the customization-specialist position, competing on engraved gifting SKUs with extended production lead times.
| Leading Market Players |
|---|
| Milton |
| P-TAL |
| Indian Art Villa |
| Signoraware |
| The Better Home |
| Kaarigar |
| Borosil |
| Purely Copper |
| Copper H2O |
| Others |
Pricing and Supply Chain Analysis
Electrolytic-grade certification bifurcation splits the copper water bottle market into documented premium tiers and unverified commodity alternatives, with Moradabad's hand-beating workshops commanding price multiples through NABL assay certificates while machine-pressed formats compete on volume accessibility. This tier divergence concentrates margin capture in heritage-positioned brands with direct artisan partnerships, while raw copper LME volatility transmits cost pressure across both segments.
Pricing Analysis
Antimicrobial efficacy documentation anchors value-based pricing, with batch-specific assay certificates from NABL-accredited laboratories enabling heritage brands to capture premiums over unverified alternatives. Price differentiation rests on food-grade certification under IS 15448 and FDA indirect additive compliance, with thermal performance in insulated formats commanding additional positioning. Pricing pressure stems from LME copper futures volatility squeezing working capital for inventory-heavy distributors. Yoga studio retail channels show least price sensitivity, while unorganized tier-2 Indian markets exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Moradabad's artisan cluster concentration, where hand-beating capacity constraints prevent rapid volume scaling during demand surges. Raw material sourcing draws from Indian electrolytic copper sheet suppliers, Chinese lacquer component vendors, and German REACH-compliant mechanical finishing equipment. Supply chain risk centers on artisan production bottlenecks limiting surge capacity. Distribution runs through Amazon and Flipkart algorithms, yoga studio specialty retail, and brand-owned direct channels bypassing wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hand-beating capacity constraints in Moradabad and Jaipur clusters prop pricing power for certified heritage producers, creating supply-constrained conditions that favor documented purity positioning over commodity scale.
For Market Incumbents: Deepen direct artisan platform investments to capture full margin on heritage SKUs while building narrative control around craft provenance. Fortify IS 15448 and FDA compliance documentation infrastructure against intensifying regulatory scrutiny from consumer protection authorities. Anchor backward integration into electrolytic copper sheet sourcing to buffer LME price volatility transmission. For New Entrants and Emerging Players: Instagram commerce and wellness influencer partnerships offer lowest customer acquisition cost entry into North American metropolitan yoga communities. White-space concentration sits with corporate gifting verticals for wellness-oriented employers, where engraved customization creates recurring B2B revenue with lower return rates. Target direct-to-consumer positioning with batch-specific assay transparency as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with heritage-positioned brands with documented Moradabad workshop partnerships given REACH chemical restriction tailwinds favoring mechanical finishing methods. Long-term viability over a multi-year horizon rests on purity verification infrastructure and direct channel control rather than retail distribution scale. Watch BIS laboratory assay verification adoption rates across export batches as the inflection signal for premium tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Bypasses Amazon algorithm fees while building craft provenance narrative control for Moradabad workshops. |
| Insulated Format Capacity Expansion | Captures office professional demand in New York and Toronto where temperature retention is non-negotiable. |
| NABL Assay Verification Infrastructure | Enables price multiples over unverified competitors through documented antimicrobial efficacy claims. |
| REACH-Compliant Mechanical Finishing | Secures German and French market access as solvent-based anti-tarnish coatings face ECHA prohibition. |
| Corporate Gifting Customization Service | Creates recurring B2B revenue streams with 7-14 day engraved lead times from Jaipur workshops. |
Research Methodology
Multi-period observation of LME copper futures, BIS certification adoption rates, and REACH compliance transitions anchored the trend analysis, supplemented by interviews with Moradabad workshop owners, Indian organized retail category managers, North American yoga studio buyers, German wellness distributors, and FDA regulatory consultants. Secondary validation drew from BIS laboratory assay databases, ECHA restriction substance lists, Amazon search algorithm documentation, and customs trade records. Bottom-up artisan production estimates triangulated against top-down retail channel revenue assessments.
Input-output matrices mapped electrolytic copper sheet flows through hand-beating and machine-pressing processes to finished goods across classic, insulated, and engraved formats. Segmentation modeling incorporated product architecture, material grade tiers, end-use applications, and channel structures. CAGRs were derived from regression analysis of historical volume trajectories against purity verification adoption curves and wellness community amplification patterns.
Inputs from artisan workshop production logs and specialty retail inventory systems were available through the study window; gaps in real-time LME hedging positions and unorganized market volume estimates introduce uncertainty bands around working capital and commodity price transmission assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Remote Control Holder Market
Household Items
Desktop Air Purifier Market
Household Items
Moving Supplies Market
Household Items
Paper Towel Dispenser Market
Household Items
Massage Pillow Market
Household Items
Portable Iron Market
Household Items
Manual Bottle Opener Market
Household Items
Europe Heated Mattress Pads Market
Household Items
Towel Warmers Market
Household Items
Dry and Wet Wipes Market
Household Items
UK Digital Showers Market
Household Items
Netherlands Cookware Market
Household Items
Trash Can Market
Household Items
Mirror Holder Market
Household Items
Range Hood Cleaning Service Market
Household Items
US Handheld Vacuum Cleaners Market