
 Single Origin Tea Market | 2026-2036
Single Origin Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Single Origin Tea Market Analytics
Subscription-based direct-to-consumer curation is realigning how single origin teas reach buyers, shifting value from bulk wholesale to recurring, provenance-verified deliveries. Dilmah Ceylon Tea Company PLC anchors its competitive position through vertical integration from Sri Lankan estates to packaged goods. Rishi Tea & Botanicals differentiates via organic certification depth and direct trade relationships with specific gardens. Organic India leverages its Ayurvedic heritage to occupy a distinct wellness-positioned niche in North American and European channels.
Single origin tea denotes leaves harvested from one specific geographic location—often a single estate, garden, or defined microclimate—with no blending across regions, typically processed to preserve terroir-specific polyphenol profiles and aromatic compounds. The primary commercial purpose is to command premium pricing through traceability, flavor distinctiveness, and narrative value for discerning consumers and hospitality buyers. Loose leaf formats dominate margin pools due to lower packaging intensity and higher per-gram price realization, while handcrafted processing methods attract connoisseur segments willing to pay provenance premiums. Machine-processed black tea from established estates represents the volume base, though oolong and white tea categories are gaining traction among specialty retailers seeking differentiation.
FDA food facility registration and EU REACH-aligned agricultural residue standards shape import compliance burdens for origin-labeled teas entering the United States and European Union. China's SAMR enforces GB standards for domestic tea safety and labeling, while India's FSSAI mandates pesticide maximum residue limits that directly affect Assam and Darjeeling export viability. Stakeholders must monitor evolving geolocation traceability mandates and climate adaptation investments in heritage growing regions to secure long-term supply continuity.
Market Dynamics
Traceability mandates from the EU Green Deal are compressing sourcing timelines and forcing estate-level documentation investments across the value chain.
Growth Catalysts
- EU Green Deal traceability mandates:Agricultural import documentation requirements are accelerating blockchain adoption for provenance verification. Specialty retailers now require lot-level geolocation data.
- Specialty hospitality procurement:Premium hotel chains and Michelin-recognized restaurants are expanding single origin tea programs as signature beverage offerings. This channel commands 40-60% price premiums over conventional foodservice.
- Yunnan heritage cultivar demand:China's domestic connoisseur market is absorbing limited-production Pu-erh and Dianhong varieties. Estate-specific auctions now clear volumes at 3-5x commodity tea benchmarks.
Market Restraints
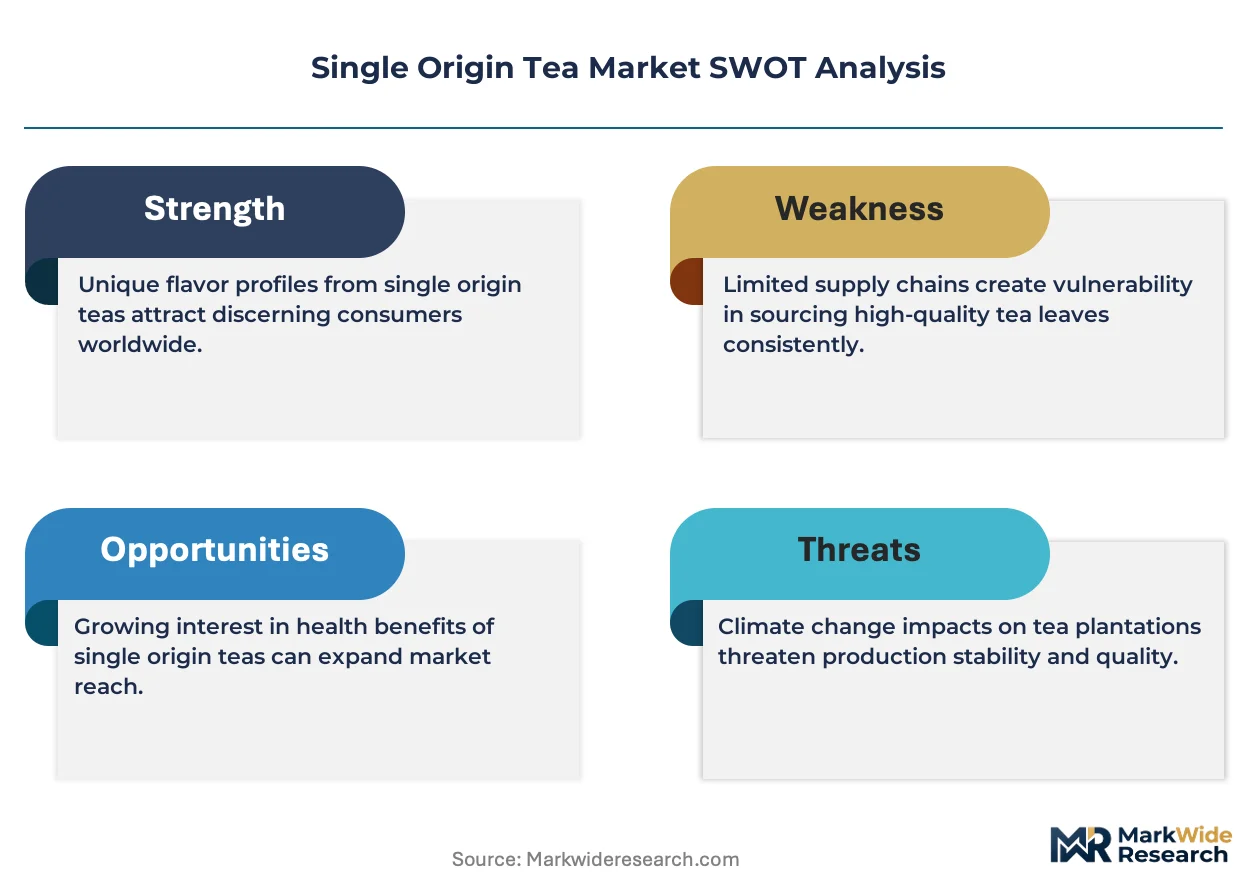
- Climate volatility in high-altitude gardens:Darjeeling and Nilgiri estates face erratic monsoon patterns and temperature shifts. Yields from heritage bushes are declining 8-15% in marginal years.
- Input cost concentration:Organic certification compliance and manual harvesting labor pool 70-80% of production costs. Wage inflation in Sri Lankan and Indian tea regions outpaces mechanization savings.
- REACH-aligned residue testing:EU pesticide maximum residue limits require pre-shipment laboratory verification. Rejected lots destroy margin on entire container shipments.
Strategic Opportunities
- Direct-to-consumer subscription channels:Curated monthly deliveries bypass traditional wholesale markups. Origin-labeled micro-lots reach enthusiasts at 2.5-4x estate gate prices.
- Ayurvedic wellness positioning:North American natural products retailers are creating dedicated single origin tea sets with functional health claims. Tulsi and ashwagandha blends command shelf space premiums.
- Carbon-neutral estate certification:EU CBAM alignment and voluntary carbon markets reward regenerative cultivation. Early adopters access green procurement tenders from Nordic hospitality groups.
Industry Challenges
- Heritage processing skill attrition:Traditional withering and oxidation expertise resides with aging master processors. Knowledge transfer to younger workers lacks formal apprenticeship structures.
- Multi-jurisdiction compliance synchronization:FDA facility registration, EU REACH residue protocols, and China's GB labeling standards create overlapping documentation burdens. Small estates lack dedicated regulatory staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Origin Tea Market |
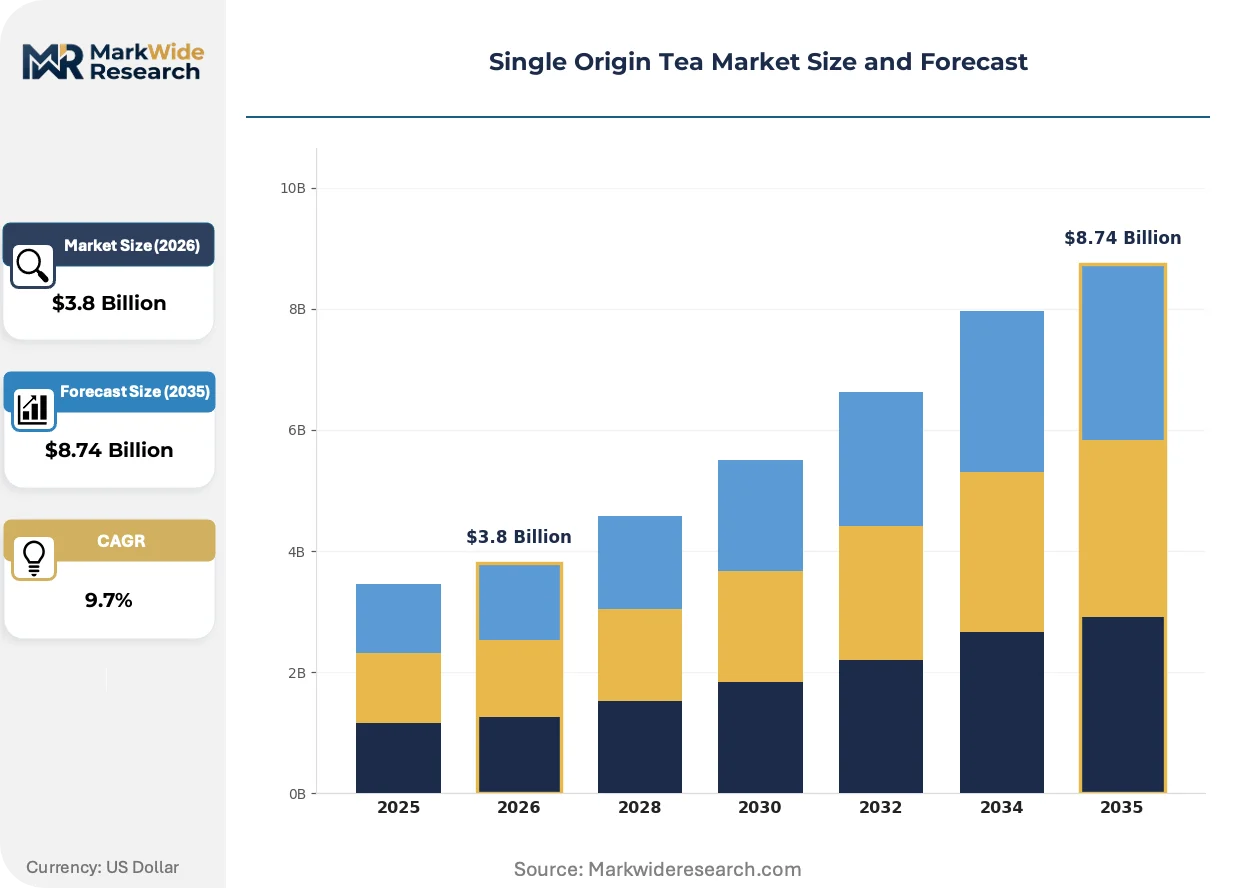
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, White Tea, Oolong Tea Processing Method: Handcrafted, Machine-Processed, Fermented, Sun-Dried Flavor Profile: Floral, Fruity, Earthy, Spicy Packing Type: Loose Leaf, Tea Bags, Canned, Bottled |
| Companies Covered | Origin Tea, Organic India, Dilmah Ceylon Tea Company PLC, Alveus GmbH, Premier's Tea Limited, Akbar Brothers Ltd, Debonair Tea Company, Rishi Tea & Botanicals, Art of Tea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Origin Tea Market Evolving Landscape
Digital traceability infrastructure and climate-adaptive cultivation are converging to reshape how provenance is verified and valued across origin-specific supply chains.
Blockchain-based lot tracking is automating documentation workflows for estate-to-retailer provenance chains. Japanese specialty importers and Nordic organic distributors are piloting QR-code-linked harvest records. This compression of verification labor is reducing third-party audit costs while tightening fraud detection.
EU Green Deal agricultural import standards are mandating geolocation verification and deforestation-free sourcing attestations. Estate operators in Assam and Uva must now submit polygon-mapped cultivation boundaries. Organic-certified gardens are accelerating compliance investments to maintain EU market access ahead of 2025 enforcement deadlines.
Certification-driven purchasing is displacing origin-loyalty as the primary buyer decision framework. North American specialty retailers now lead with organic, Fair Trade, or carbon-neutral claims rather than estate name recognition. This behavioral pivot is most visible in California and Pacific Northwest natural products channels where label transparency dominates shelf positioning.
Single Origin Tea Market Segmentation
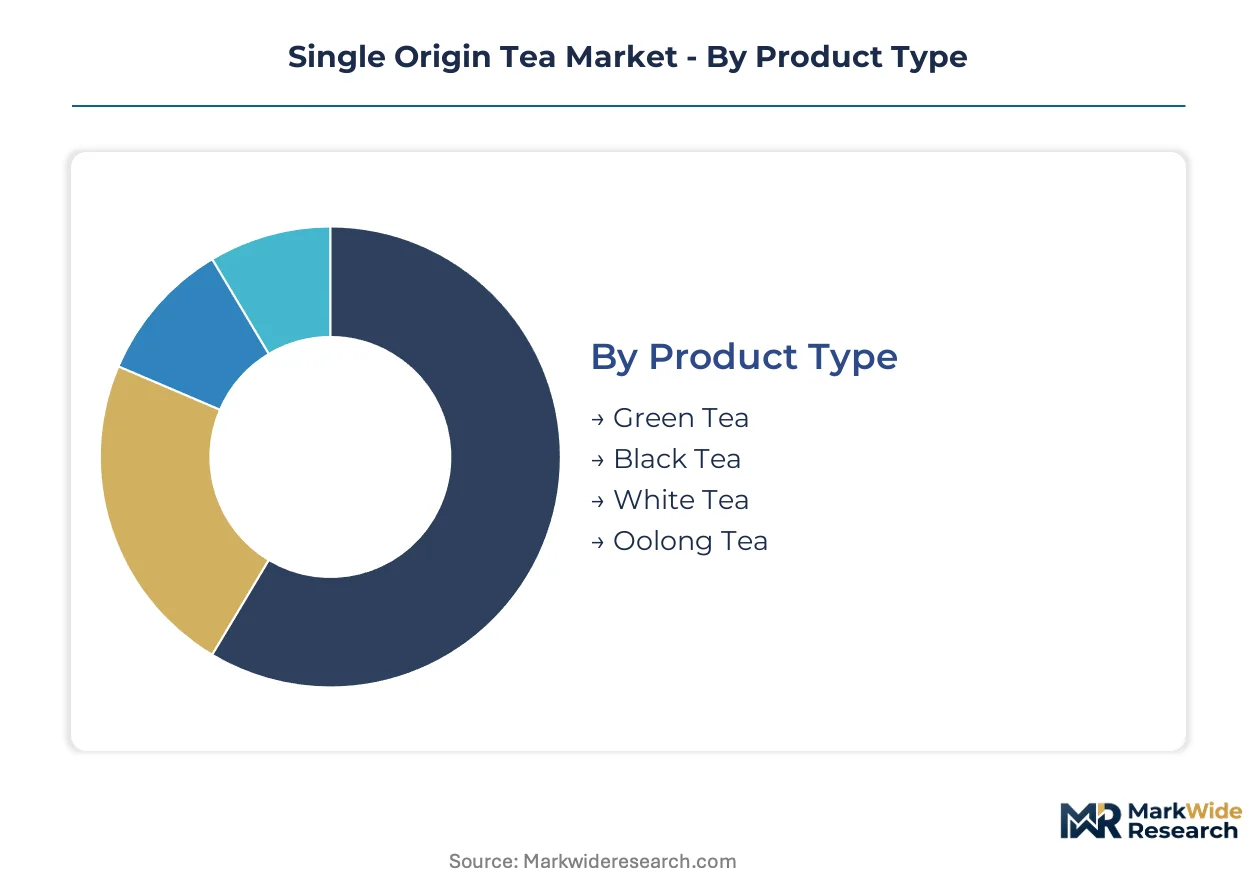
Single origin tea segmentation reflects divergent capital requirements across processing infrastructure, certification depth, and channel-specific packaging formats. Producers must align segment focus with estate capabilities and target market compliance burdens.
Product Type:
Capital intensity varies sharply by cultivar, with oxidized categories demanding longer curing infrastructure and climate-controlled storage.
- Green Tea:Minimal oxidation preserves fresh polyphenol profiles through rapid steaming or pan-firing. Japanese sencha and Chinese Longjing varieties command premiums in North American specialty retail channels where unoxidized wellness positioning drives placement.
- Black Tea:Full oxidation requires controlled withering and rolling equipment. Assam and Ceylon estates anchor volume supply for EU hospitality procurement programs with stringent origin documentation requirements.
- White Tea:Bud-only harvesting limits scale and concentrates labor costs. Fujian Silver Needle lots reach direct-to-consumer subscribers at steep premiums.
- Oolong Tea:Semi-oxidized processing demands master-level skill in kill-green timing. Taiwanese Alishan and Fujian Tieguanyin lots attract connoisseur segments in East Asian export markets.
Black tea absorbs the bulk of installed capacity; oolong tea is expanding most quickly.
Processing Method:
Method selection determines labor-to-capital ratios and margin structure across estate output.
- Handcrafted:Manual rolling and withering preserves terroir expression. Darjeeling first-flush and Uva seasonal lots target Michelin-tier restaurant programs with limited-batch provenance narratives.
- Machine-Processed:CTC and orthodox roller systems enable scale. Kenyan and Assam estates supply commodity-grade orthodox black tea to EU blenders meeting REACH residue protocols.
- Fermented:Microbial aging transforms Pu-erh and dark tea categories. Yunnan warehouses with decade-plus inventory cycles attract Chinese domestic investor-collectors.
- Sun-Dried:Minimal energy input suits off-grid estates. White tea and raw Pu-erh producers in remote Fujian and Yunnan microclimates leverage this method for organic certification compliance.
Machine-processed output dominates volume throughput; handcrafted methods claim the steepest price premiums.
Flavor Profile:
Profile-driven procurement is displacing origin-loyalty in North American and European retail channels.
- Floral:High-aromatic cultivars including Tieguanyin and high-mountain oolongs. Taiwanese estates supply Nordic specialty importers with EU organic certification.
- Fruity:Muscatel and stone-fruit notes typify Darjeeling second-flush and Nilgiri frost teas. Indian auction lots attract Japanese and German connoisseur buyers.
- Earthy:Aged Pu-erh and dark tea categories dominate. Chinese domestic collectors and US wellness retailers split demand for fermented inventory.
- Spicy:Clove and pepper notes characterize some Yunnan Dianhong and Nepali orthodox lots. Emerging category with limited estate-scale production.
Earthy profiles anchor aged-tea inventory value; floral categories are gaining share fastest in premium subscription channels.
Packing Type:
Format choice directly shapes margin realization and channel access for origin-labeled producers.
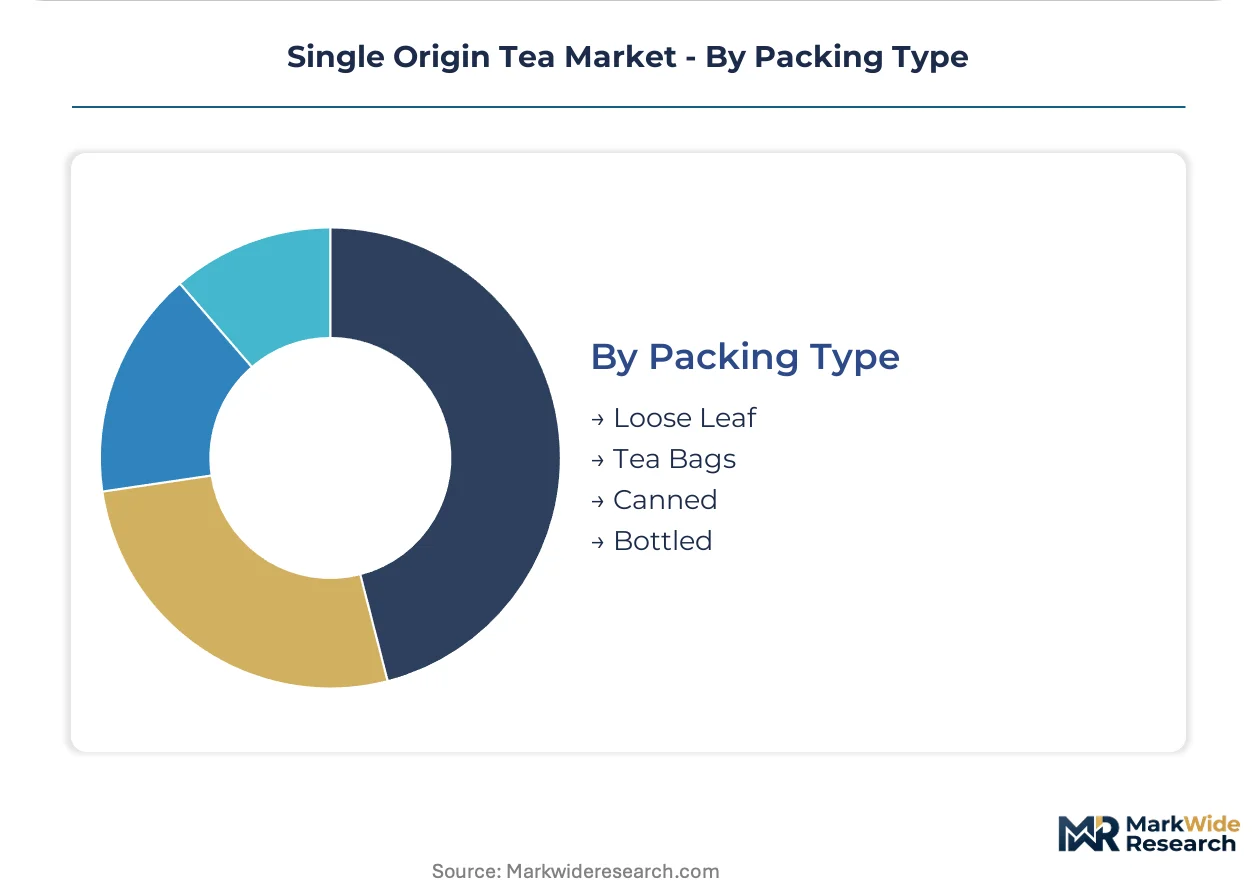
- Loose Leaf:Minimal packaging material and highest per-gram pricing. Specialty retailers and direct-to-consumer curators prefer this format for provenance storytelling.
- Tea Bags:Convenience positioning with higher packaging intensity. EU hospitality chains demand compostable or plastic-free sachets under Green Deal procurement guidelines.
- Canned:Airtight preservation for premium matcha and powdered formats. Japanese and South Korean export markets absorb most volume.
- Bottled:Ready-to-drink single origin cold brew. California and New York metro-area premium convenience channels test this format with limited estate partnerships.
Loose leaf commands the dominant share of origin-premium value capture; tea bags are expanding most quickly through sustainability-certified hospitality procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yunnan Province anchors the global single origin tea trade, with Kunming's auction houses clearing heritage Pu-erh lots at multiples of commodity benchmarks. Estate-level traceability investments now concentrate across four producer countries.
China
Fujian's Silver Needle white tea and Yunnan's aged Pu-erh categories absorb domestic connoisseur demand at 3-5x standard pricing. SAMR enforces GB standards for pesticide residues and geographic indication labeling. Xishuangbanna's ancient tree gardens supply limited-production lots to direct-to-consumer curators in Shanghai and Beijing.
India
Darjeeling's first-flush muscatel lots and Assam's orthodox black teas target EU hospitality procurement with origin-verified documentation. FSSAI mandates maximum residue limits that determine export lot viability. Nilgiri estates in Tamil Nadu face yield compression from erratic monsoon patterns while investing in organic certification for Nordic market access.
Sri Lanka
Uva and Nuwara Eliya high-grown districts supply Ceylon tea with provenance narratives for premium retail channels. EU REACH-aligned residue testing requires pre-shipment laboratory verification for container shipments. Colombo's auction system is integrating blockchain traceability to compress documentation timelines for European importers.
Japan
Shizuoka and Kagoshima prefectures cultivate shade-grown sencha and gyokuro for North American specialty retail. METI supports geographic indication protection for traditional processing methods. Kyoto's Uji district maintains heritage matcha stone-grinding operations for ceremonial-grade export.
Taiwan
Alishan and Sun Moon Lake high-mountain oolongs command connoisseur premiums in East Asian export markets. The island's tea research stations develop climate-adaptive cultivars as temperature shifts affect harvest timing. Nantou County's traditional kill-green processors supply floral-profile lots to Japanese and German importers.
Single Origin Tea Market Competitive Landscape
Capital-heavy estate operators compete with asset-light curators and subscription platforms for margin capture. The market structure fragments across vertically integrated garden-to-package producers, direct-trade sourcing specialists, and digital-native subscription brands. Three archetypes dominate: heritage estate owners with in-house processing, organic-certified direct-trade intermediaries, and wellness-positioned Ayurvedic brands. Competitive moves concentrate on blockchain traceability investments and carbon-neutral certification to secure EU hospitality tenders.
Within the estate-integrated tier, Dilmah Ceylon Tea Company PLC exemplifies vertical control from Sri Lankan gardens to packaged goods. Rishi Tea & Botanicals occupies the direct-trade specialist position with organic certification depth. Organic India anchors the wellness-positioned segment through Ayurvedic heritage positioning in North American natural products channels.
| Leading Market Players |
|---|
| Origin Tea |
| Organic India |
| Dilmah Ceylon Tea Company PLC |
| Alveus GmbH |
| Premier's Tea Limited |
| Akbar Brothers Ltd |
| Debonair Tea Company |
| Rishi Tea & Botanicals |
| Art of Tea |
| Others |
Value Network & Pricing Analysis
EU Green Deal traceability mandates are forcing estate-level documentation investments that compress margins for non-compliant producers while rewarding certified gardens with premium access. This regulatory pressure stratifies pricing power across origin-labeled supply chains.
Pricing Analysis
Margin tightening in machine-processed black tea reflects REACH-aligned residue testing costs and wage inflation across Sri Lankan and Indian estates. Pricing stratifies across estate-verified micro-lots, organic-certified origin tiers, and commodity-grade orthodox volumes. Certification depth and lot-level geolocation data command the steepest premiums. Direct-to-consumer subscription channels absorb the least price-sensitive buyers, while EU hospitality procurement programs negotiate volume-based origin premiums.
Supply Chain Analysis
Container freight volatility from South Asian ports to Rotterdam and Hamburg is compressing landed margins for origin-verified lots. Supply concentrates in China's Yunnan and Fujian provinces, India's Assam and Darjeeling districts, and Sri Lanka's Uva highlands. Cultivar stock, manual harvesting labor pools, and climate-controlled curing infrastructure constitute critical input dependencies. Single-source vulnerability from monsoon-dependent high-altitude gardens threatens yield continuity. Distribution runs through Colombo and Kolkata auction houses, with blockchain-integrated direct trade bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance is erecting a cost-of-entry barrier that favors estates with dedicated regulatory staff and pre-existing organic certification. FSSAI, SAMR, and REACH-aligned residue protocols collectively filter out undercapitalized competitors.
For Market Incumbents: Deepen backward integration into heritage processing capacity to secure aging master processor expertise before attrition accelerates. Invest in polygon-mapped geolocation infrastructure to preempt EU deforestation-free sourcing attestations. Carbon-neutral estate certification opens Nordic hospitality procurement channels that competitors cannot access without multi-year compliance lead times. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route around entrenched wholesale markups. Target North American wellness-positioned retail channels with Ayurvedic-functional blends that bypass origin-loyalty competition. Curated micro-lot curation with QR-linked harvest records requires minimal estate capital versus vertical garden ownership. For Investors and Strategic Acquirers: The window for entry favors organic-certified direct-trade intermediaries with established EU channel relationships. Long-term viability hinges on climate-adaptive cultivar development and blockchain traceability infrastructure. Watch for EU CBAM enforcement tightening as the inflection signal that accelerates compliant estate valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | EU Green Deal mandates compress documentation timelines for origin-verified shipments. |
| Carbon-Neutral Estate Certification | Nordic hospitality procurement tenders reward regenerative cultivation investments. |
| Direct-to-Consumer Subscription Launch | Curated monthly deliveries bypass traditional wholesale markups to enthusiasts. |
| Ayurvedic Wellness Positioning | North American natural products retailers create dedicated shelf space for functional blends. |
| Heritage Processing Apprenticeship Programs | Knowledge transfer structures address aging master processor attrition risks. |
Research Methodology
Document review covered customs trade databases, EU regulatory filings, and estate auction records, complemented by interviews with specialty tea importers, hospitality procurement directors, and organic certification auditors. Primary fieldwork engaged estate managers in Yunnan and Darjeeling, Nordic distributor sourcing leads, and North American subscription platform operators. Secondary validation drew from FSSAI residue limit notifications, SAMR GB standard updates, and Colombo auction price indices. Bottom-up estate capacity modeling and top-down channel revenue estimates were triangulated for cross-verification.
Segmentation outputs across product type, processing method, flavor profile, and packing format were projected over the analysis window. CAGRs were derived from trend extrapolation of heritage cultivar auction premiums, organic certification adoption curves, and direct-to-consumer channel penetration rates. Climate volatility scenarios and regulatory enforcement timelines were incorporated as sensitivity inputs.
The model holds under stable EU-Asia trade relations and gradual Green Deal phase-in; deviation in tariff escalation or abrupt deforestation enforcement would shift origin premium distributions. Stakeholders should weight assumptions against their own operating context and compliance investment capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Matcha Market
Tea
Butterfly Pea Flower Tea Market
Tea
Edible Tea Market
Tea
Tea Essence Market
Tea
Mate Tea Market
Tea
White Tea Market
Tea
Black Tea Market
Tea
Pyramid Tea Bags Market
Tea
Oolong Tea Market
Tea
Pu-Erh Tea Market
Tea
US RTD Organic Tea Market
Tea
Instant Tea Market
Tea
Herbal Tea Market
Tea
Matcha Products Market
Tea
Matcha Tea Market
Tea
Asia-Pacific Tea Market